The tax legal framework in Vietnam requires foreign-invested enterprises (FDI) to strictly fulfill compliance obligations for multiple mandatory taxes including Value-Added Tax (VAT), Corporate Income Tax (CIT), Personal Income Tax (PIT), and Foreign Contractor Tax (FCT). Each tax has its own separate declaration cycle and tax payment deadline; particularly from 01/07/2026, the new regulations under the Law on Tax Administration No. 108/2025/QH15, Decree 252/2026/ND-CP, and Circular 89/2026/TT-BTC officially take effect, applying a new standardized return form system.
The biggest barrier for FDI managers is that tax policy documents continuously change, the language mismatch in handling administrative dossiers, the complexity of cross-border transactions with the parent company, as well as the requirement for continuous data reconciliation between accounting books, the electronic invoice system, and bank statements. Standing firm on a foundation of more than 20 years of practical experience accompanying more than 500 corporate clients, Vina TPT brings a full-package tax preparation services for businesses solution, helping enterprises optimize costs and limit compliance risks.
1. Taxes FDI Companies Must File and Their Deadlines (tax preparation services for businesses)
For FDI enterprises, tax preparation services for businesses must cover the declaration and payment obligations associated with each applicable tax. The table below summarizes the main tax types, filing periods, deadlines, and corresponding services provided by Vina TPT.
|
Tax type |
Declaration period | Deadline for submitting dossiers & tax payment |
Scope of work performed by Vina TPT |
| Value-Added Tax (VAT) | Declaration by month or by quarter | The 20th of the following month (for monthly declaration); the last day of the first month of the following quarter (for quarterly declaration) | Collecting documents, checking invoice validity, preparing Form 01/GTGT returns, performing reconciliation, and supporting tax payment |
| Corporate Income Tax (CIT) | Quarterly provisional payment and Annual finalization | The last day of the first month of the following quarter (quarterly provisional payment); the last day of the 3rd month from the end date of the fiscal year (annual finalization) | Calculating the quarterly provisional tax amount, preparing the annual CIT finalization return together with Financial Statements and Related-Party Transaction Appendix |
| Personal Income Tax (PIT) | Withholding by month/quarter and Annual finalization | According to the monthly/quarterly withholding declaration period; the last day of the 3rd month from the end date of the fiscal year (for finalization of the income-paying organization) | Calculating the monthly/quarterly withholding tax amount, preparing the statement, and performing the annual PIT finalization return for employees |
| Foreign Contractor Tax (FCT) | Declaration upon each arising obligation | The 10th day from the date the obligation to pay the foreign party arises | Reviewing contractor contracts, determining tax rates, preparing FCT returns, and supporting tax payment procedures when paying service fees, royalties, loan interest |
For foreign-invested enterprises searching for VAT filing Vietnam requirements, understanding the applicable declaration cycle and submission deadlines is essential for maintaining tax compliance.
Under the regulations in Article 19 of Circular 89/2026/TT-BTC, the enterprise performs VAT declaration by quarter if the total revenue from selling goods and providing services of the immediately preceding year is 50 billion dong or less; enterprises newly starting production and business activities have the right to choose quarterly declaration. From Q3/2026, enterprises apply the newly issued VAT return Form 01/GTGT. For Corporate Income Tax, the total provisional CIT amount of the 04 quarters must not be lower than 80% of the CIT amount payable according to the annual finalization. The tax payment deadline is based on the regulations in Article 10 of Decree 252/2026/ND-CP; in the case of late tax payment, late payment interest will be calculated at the rate of 0.03%/day on the late tax amount. It should be noted that the business license tax has been officially abolished from 01/01/2026.
Tax preparation services for businesses
For foreign-invested enterprises, tax preparation services for businesses require particular attention to internal group transactions, Foreign Contractor Tax (FCT) withholding on applicable overseas payments, and consistency between tax finalization dossiers and audited Financial Statements. Financial Statements that have undergone mandatory independent audit. In addition, newly established small and medium-sized enterprises (SME) need to be carefully reviewed against the criteria in order to apply the 3-year initial Corporate Income Tax exemption incentive policy (Readers may see further details in the article CIT Exemption 2026: 3-Year Conditions for New FDI SMEs in Vietnam).
EXPLORE VINA TPT’S TAX FILING SERVICES
2. How Vina TPT Keeps Your Tax Filings Compliant and Worry-Free
Vina TPT provides tax preparation services for businesses that go beyond preparing tax returns. The service combines filing support, document review, regulatory guidance, and assistance when working with tax authorities.
A 3-Layer Review Before Every Filing
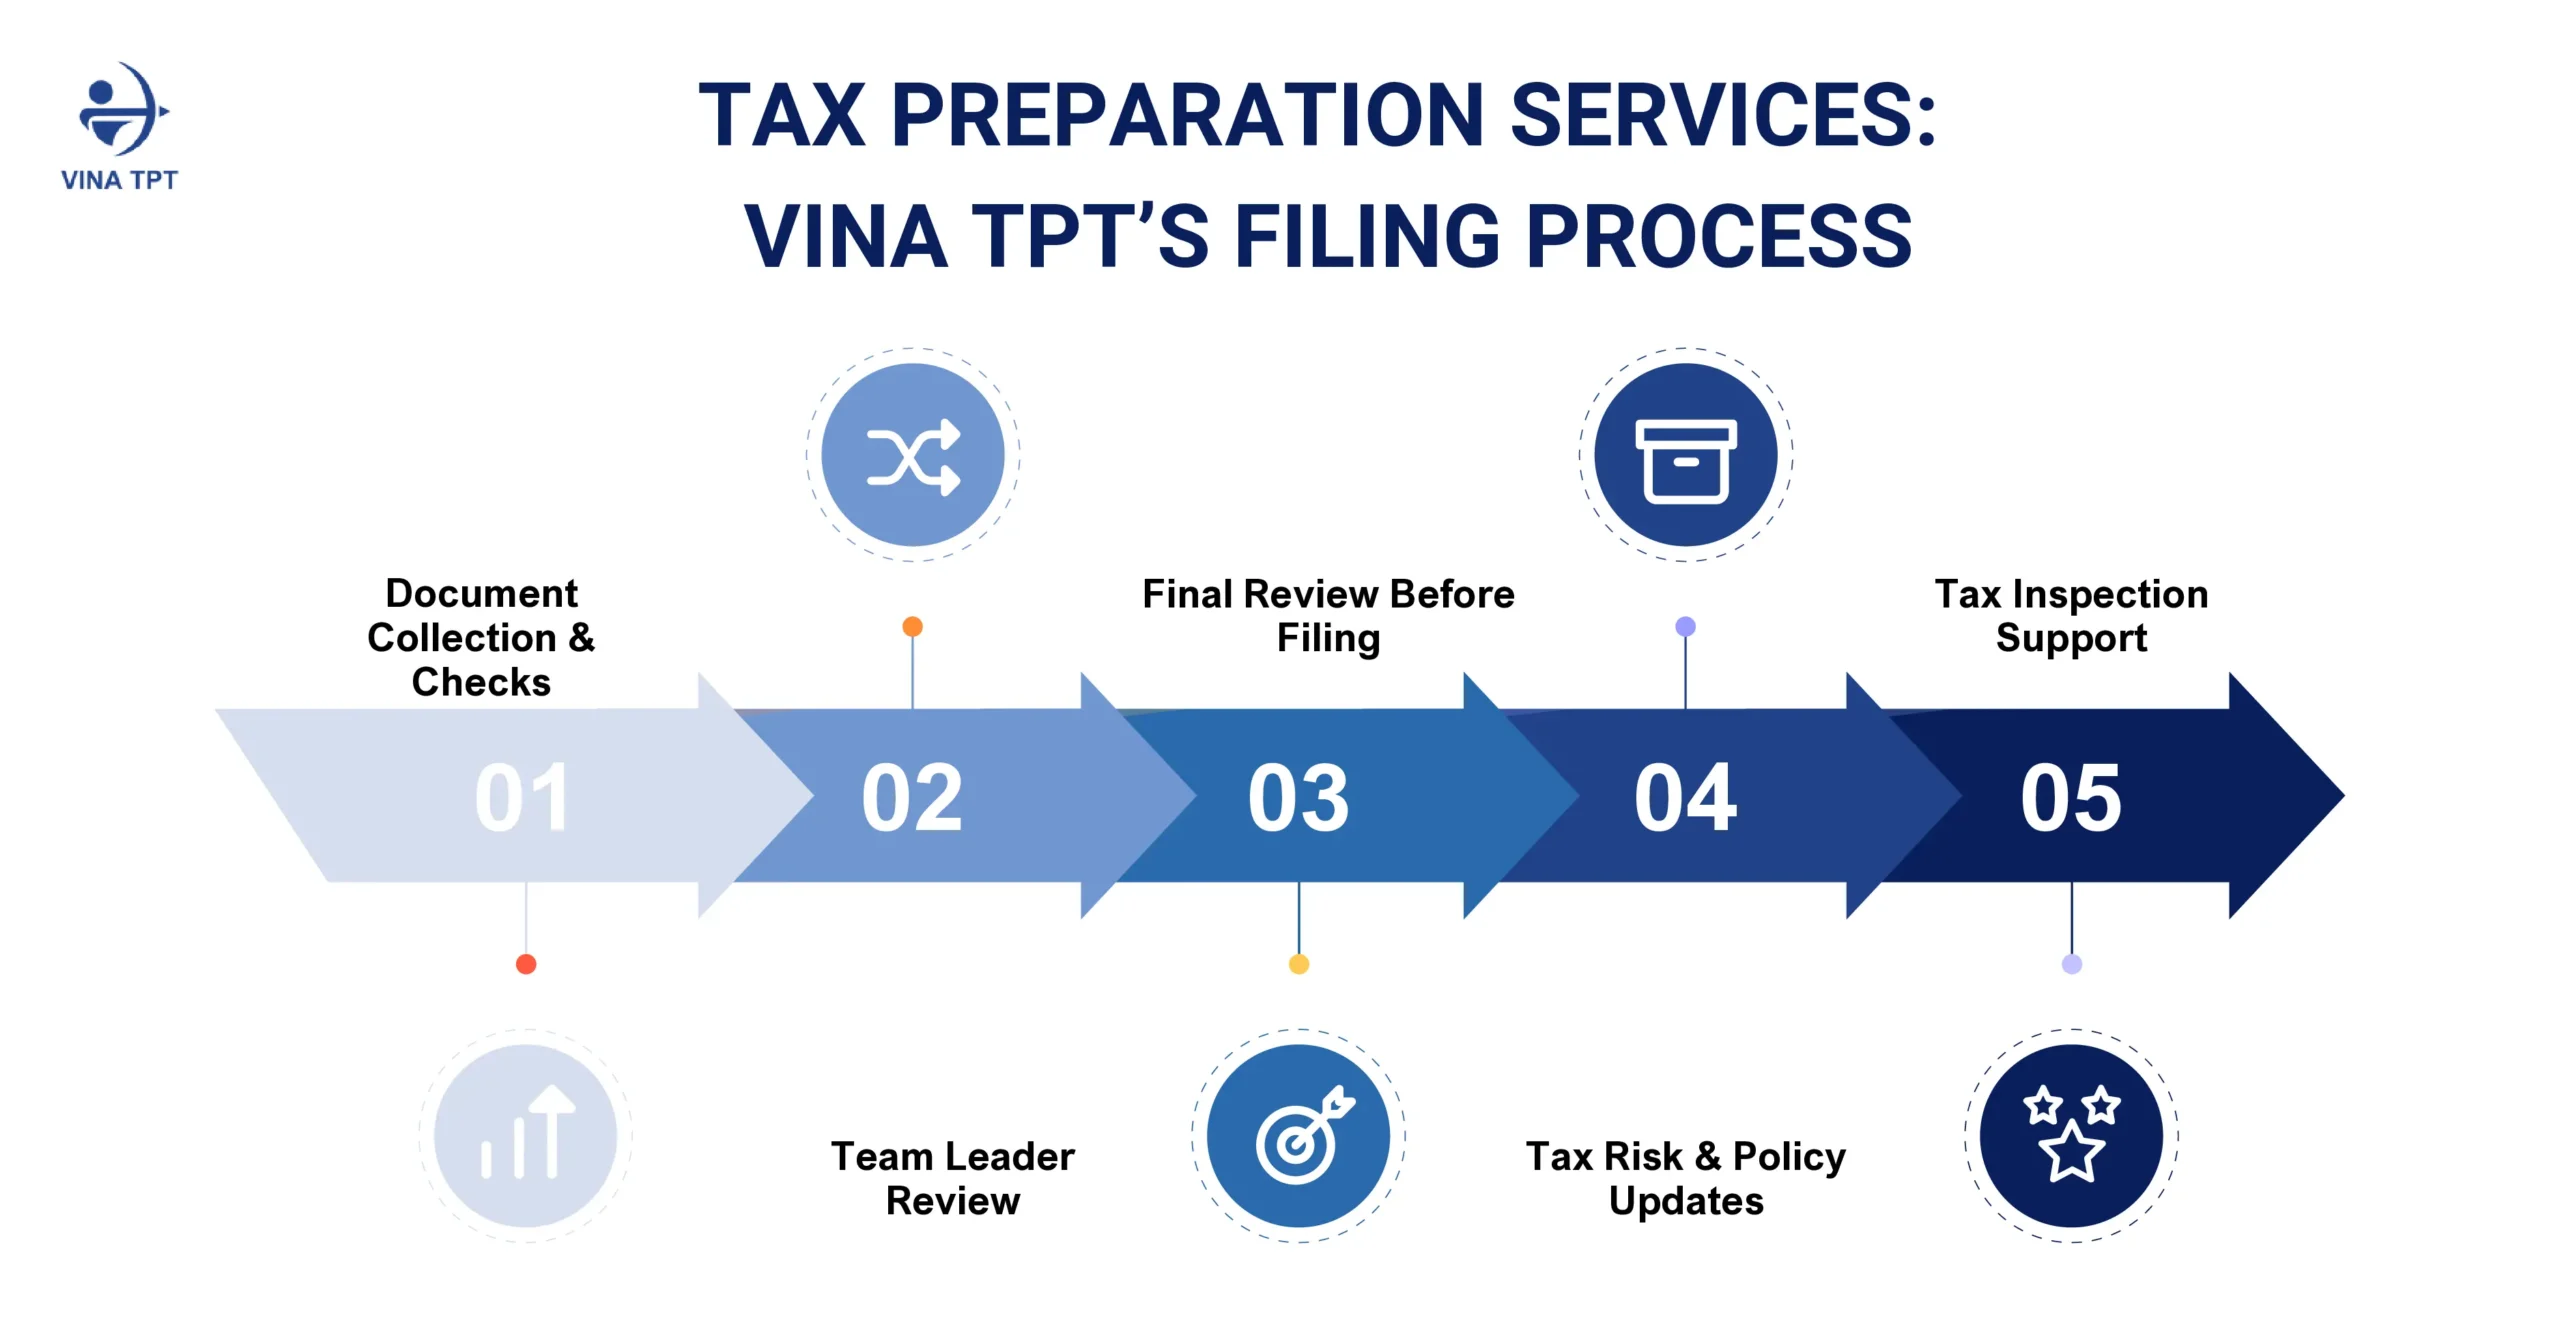
This three-layer review is a key part of Vina TPT’s tax preparation services for businesses, helping identify inconsistencies before returns are submitted to the tax authority: the accounting specialist in charge directly collects and checks documents; the professional team leader performs detailed reconciliation between invoice data, accounting books, and bank statements; the tax advisory expert conducts an independent final review before presenting to the investor for approval and digital signing.
For businesses managing VAT filing Vietnam obligations, this review process helps identify discrepancies between invoice data, accounting books, and bank statements before submission.
Advice Included, Not Just Filing
As part of our tax preparation services for businesses, Vina TPT provides proactive guidance on potential tax risks arising from document preparation, commercial contracts, and related-party transaction dossiers. This helps enterprises identify compliance issues before they affect subsequent tax filings.
Monthly Regulatory Updates
Monthly, Vina TPT updates clients on the latest changes in tax policies (such as the new regulations in the Law on Tax Administration 2025 or electronic invoice standardization under Decree 254/2026/ND-CP), accompanied by specific guidance on the tasks the enterprise needs to perform in order to adapt.
Support When Working With Tax Authorities
Vina TPT’s tax preparation services for businesses also include support during tax inspections and audits. The team accompanies enterprises, assists with explanations, and represents them when working with tax authorities within the agreed service scope.
3. Why Businesses Choose Vina TPT for Tax preparation services for businesses
- Owning a foundation of more than 20 years of practical experience, serving more than 500 FDI corporate clients, together with a specialist team holding CPA and ACCA practicing certificates.
- Synchronously integrating Accounting, Tax, and Payroll services in a single team, ensuring that tax declaration figures completely match the accounting books and social insurance data.
- A consulting team working fluently in English, Japanese, and Chinese; issuing bilingual reports and providing a transparent quotation policy with clear definition of the work scope before implementation.
Conclusion
Choosing a professional tax preparation services for businesses solution from Vina TPT ensures that the enterprise always submits returns on time, with accurate figures, reviewed through 3 layers of in-depth control, and accompanied by advisory experts throughout.
If your enterprise is looking for tax preparation services for businesses in Vietnam, please send your most recent tax returns and a list of taxes currently being declared. Vina TPT can review the required work scope and provide a detailed advisory quotation.