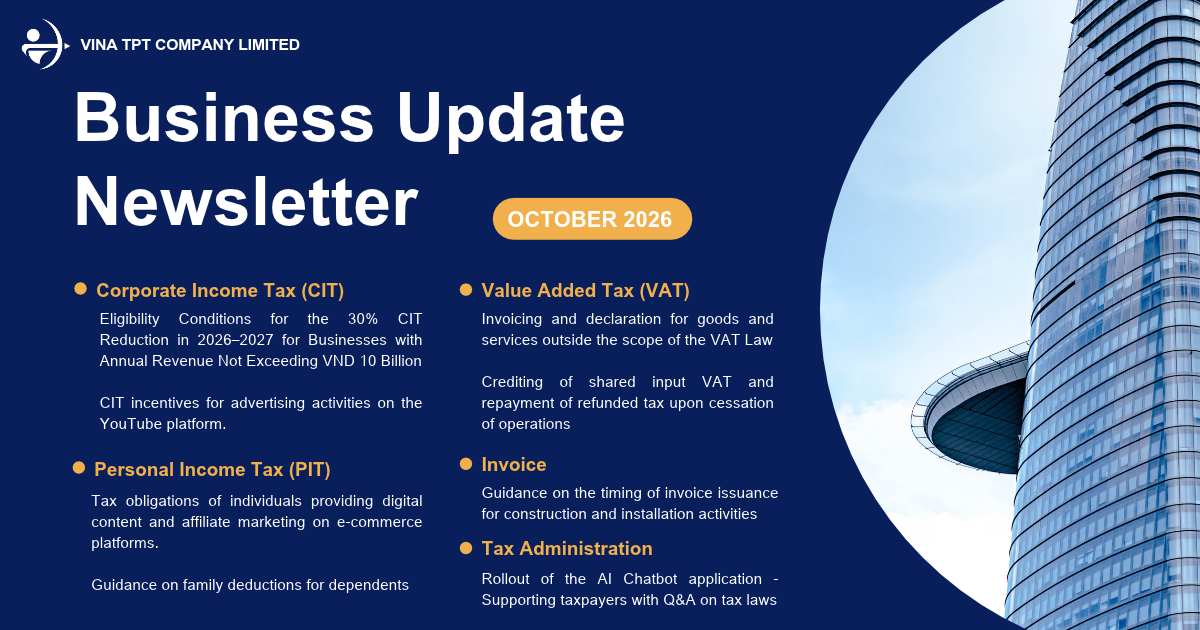
Keeping pace with Vietnam’s evolving regulatory framework is critical for avoiding tax compliance risks. In our Vietnam tax update October 2026, Vina TPT summarizes the latest decrees and official letters impacting Corporate Income Tax (CIT), Value-Added Tax (VAT), Personal Income Tax (PIT), e-invoicing, and tax administration. From the 30% CIT reduction for SMEs under Decree 398/2026/ND-CP to new VAT invoicing codes and digital creator tax rules, discover what your business needs to act on now.
CORPORATE INCOME TAX
Eligibility Conditions for the 30% CIT Reduction in 2026–2027 for Businesses with Annual Revenue Not Exceeding VND 10 Billion
- Enterprises, cooperatives, public service units and other organizations established under Vietnamese law with annual revenue not exceeding VND 10 billion are entitled to a 30% reduction in CIT payable.
- Annual revenue used to determine eligibility for the CIT reduction includes revenue from sales of goods and provision of services (excluding revenue deductions), revenue from financial activities and other income.
- For enterprises currently enjoying tax incentives under the CIT Law or other laws and resolutions of the National Assembly, the CIT reduction under this provision is calculated on the CIT payable after deducting tax incentives.
- Not applicable to enterprises established under the Law on Enterprises through division or separation after Resolution No. 43/2026/QH16 takes effect, where the total annual revenue in 2026 or 2027 of the enterprises after division or separation exceeds VND 10 billion.
CIT incentives for advertising activities on the YouTube platform.
VALUED-ADD TAX
Invoicing and declaration for goods and services outside the scope of the VAT Law
1. Official Letter 7813/CT-QLNT (issued to a freight forwarding and logistics company):
- When issuing invoices for goods and services outside the scope of the VAT Law, enter the code “KTPVDC” in the tax rate field (No. 9, Appendix V, Decision 1233/QD-CT dated 27/8/2026)
- This revenue is declared in indicator [34a] of VAT return form 01/GTGT (Circular 89/2026/TT-BTC). Input VAT is credited in accordance with Article 23 of Decree 181/2025/ND-CP
- International transport support services (cargo handling, customs clearance, loading/unloading, lifting, packing) that are not performed in Vietnam and not used for production, business or consumption in Vietnam are outside the scope of the VAT Law.
- Enterprises must still issue invoices to buyers in accordance with Clause 1, Article 4 of Decree 254/2026/ND-CP.
Crediting of shared input VAT and repayment of refunded tax upon cessation of operations
- Input VAT on goods and services used for both taxable and non-taxable activities is only creditable in proportion to the portion used for VAT-taxable activities.
- Enterprises that cease operations without generating output VAT from their main business activities must repay to the state budget the VAT previously refunded.
- Where an enterprise sells assets subject to VAT, it is not required to adjust the input VAT already declared and credited in relation to those assets.
PERSONAL INCOME TAX
Tax obligations of individuals providing digital content and affiliate marketing on e-commerce platforms.
- Income under a labor contract or collective labor agreement signed with the income-paying organization or individual in accordance with labor laws is classified as income from salaries and wages. The income-paying organization or individual shall withhold, declare and pay personal income tax as prescribed.
- Individuals engaged in digital content creation, product promotion or affiliate marketing on e-commerce or digital platforms who receive non-salary income from platforms or brands from business activities shall have such income classified as business income. Household businesses and individual businesses shall register, declare and pay tax as prescribed.
Guidance on family deductions for dependents
- Children studying at university, college, intermediate or vocational level qualify as dependents if there are documents proving the relationship and their enrollment (student card, declaration certified by the school or other documents) under Article 47 of Decree 253/2026/ND-CP and Article 4 of Circular 87/2026/TT-BTC.
- Family deductions are calculated in full months. The end date of the deduction is declared on Form 41/UQ-DKT (Appendix II, Circular 90/2026/TT-BTC).
- Official Letter No. 13757/TPHCM-QLDN3 dated 25/09/2026 of the Ho Chi Minh City Tax Department on registering family deductions for dependents with no one to rely on
- Taxpayers may only register family deductions for dependents with no one to rely on if they directly support them and have complete documents proving the support obligation as prescribed. The documents must show that the persons legally responsible for support are still alive but unable to fulfill this obligation.
- Where the dependent was registered and fully met the conditions before 01/07/2026, re-registration is not required.
TAX ADMINISTRATION
Rollout of the AI Chatbot application – Supporting taxpayers with Q&A on tax laws and policies on the eTax Mobile app and the Tax Sector Public Service Portal.
Pursuant to Official Letter 7364/CT-CDS of the Tax Department dated 05 October 2026.
– Target users: taxpayers that are enterprises, organizations, household businesses and individuals with accounts registered with the tax authority.
– Scope: integrated on the eTax Mobile app and the Tax Sector Public Service Portal (address: https://dichvucong.gdt.gov.vn).
– Content: Q&A function on tax laws and policies on the AI Chatbot – Taxpayer Support system, with key features:
+ Receiving and answering questions on taxes, fees, charges, invoices and legal documents in the tax field (Laws, Decrees, Circulars, etc.).
+ Answers are presented in a user-friendly, easy-to-understand manner, with specific references to the articles, clauses and points of the relevant legal documents (including original and amending/supplementing documents). Referenced articles and clauses are hyperlinked directly in the answer so taxpayers can view the details of each article, clause or the full text of the relevant document.
+ Supports Q&A in Vietnamese and English via text or voice input; automatically detects the user’s language and responds in the same language.
E-INVOICE
Guidance on the timing of invoice issuance for construction and installation activities
Pursuant to Official Letter No. 7391/CT-QLNT dated 06/10/2026, Point c, Clause 4, Article 9 of Decree No. 254/2026/ND-CP and Clause 6, Article 16 of Decree No. 181/2025/ND-CP.
The time of invoice issuance and VAT determination for construction and installation activities is the time of acceptance and handover of the completed works, work items, construction or installation volume, or completed portion of work handed over, regardless of whether payment has been received.
Have Questions About Your Tax or Compliance Obligations?
Every business faces unique tax, accounting, and compliance challenges in Vietnam. If you have questions about how recent regulatory shifts affect your company – or need reliable, end-to-end financial and corporate advisory.
Reach out to Vina TPT today to speak directly with our expert team.