

30% CIT Reduction: New Tax Policy in Vietnam for 2026–2027 Tax Period
Vietnam has introduced a new tax relief measure for the 2026 and 2027 tax periods under Resolution No. 43/2026/QH16. Eligible enterprises and organizations established under Vietnamese law with annual revenue of no more than VND 10 billion may receive a 30% reduction in corporate income tax (CIT) payable.
The policy is intended to provide additional tax support for eligible businesses. However, the 30% reduction should not be confused with a 30% reduction in the statutory CIT rate. In practice, businesses need to determine their eligible CIT payable first, then apply the reduction in accordance with the applicable rules.
What Does Resolution No. 43/2026/QH16 Say About the Tax Reduction?
Resolution No. 43/2026/QH16 was issued by the National Assembly on 24 August 2026. The Resolution introduces tax reductions for both personal income tax (PIT) and corporate income tax (CIT) for the 2026 and 2027 tax periods as follows:
“…
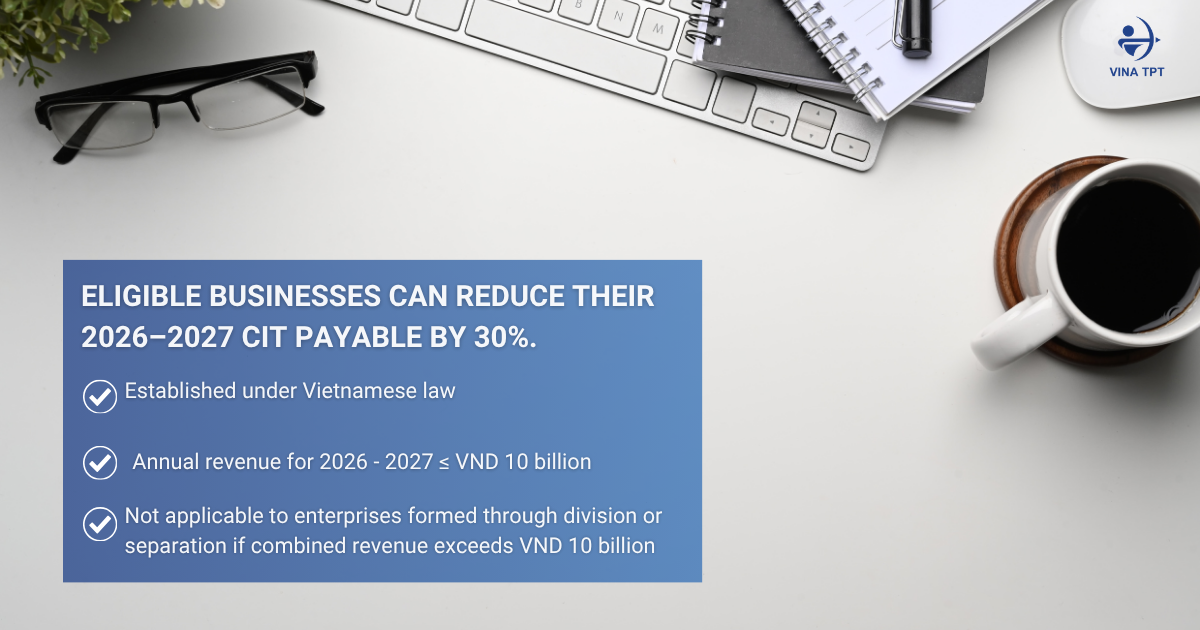
2. A 30% reduction in corporate income tax payable for the 2026 and 2027 tax periods shall apply to the income of enterprises and organizations established in accordance with Vietnamese law whose annual revenue in 2026 or 2027 does not exceed VND 10 billion.
This reduction does not apply to enterprises established through the division or separation of an enterprise after the effective date of this Resolution, where the combined annual revenue of the enterprises resulting from such division or separation exceeds VND 10 billion in 2026 or 2027.
In cases where an enterprise is already entitled to tax incentives under the Law on Corporate Income Tax or other laws or resolutions of the National Assembly, the corporate income tax reduction specified in this Clause shall be calculated based on the corporate income tax payable after deducting the applicable tax incentives.”
30% CIT Reduction for Enterprises
For CIT, eligible enterprises and organizations may receive a 30% reduction in CIT payable for the 2026 and 2027 tax periods if they are established under Vietnamese law and have annual revenue of no more than VND 10 billion in the relevant tax year.
The reduction does not apply to enterprises formed through the division or separation of an existing enterprise after the Resolution takes effect if the combined annual revenue of the enterprises resulting from such division or separation exceeds VND 10 billion in the relevant year.
For enterprises already benefiting from CIT incentives under the Law on Corporate Income Tax or other laws and resolutions of the National Assembly, the 30% reduction is calculated based on the CIT payable after the applicable tax incentives have been deducted.
30% PIT Reduction for Business Individuals and Households
Resolution 43 also provides a 30% reduction of PIT payable for the 2026 and 2027 tax periods for resident individuals earning business income whose annual revenue does not exceed VND 10 billion.
Although the CIT and PIT provisions use a similar 30% reduction concept and a VND 10 billion revenue threshold, they apply to different taxpayers.
Importantly, this 30% PIT reduction applies only to PIT arising from business income. It does not apply to PIT calculated on employment income, such as salary or wages received by individuals as employees.
What Is the Current CIT Rate in Vietnam?
The 30% CIT reduction needs to be considered alongside the CIT rates currently applicable in Vietnam.
Under the 2025 Law on Corporate Income Tax, the standard CIT rate is 20%, while 15% and 17% rates may apply to qualifying enterprises based on annual revenue and other statutory conditions.
This makes it important to distinguish between two separate concepts:
- CIT rate — the statutory rate used to calculate CIT liability.
- 30% CIT reduction — a tax relief mechanism that reduces the resulting CIT payable for qualifying businesses.
Reference: Updated 2025 | Corporate Income Tax Rates in Vietnam
Standard CIT Rate: 20%
The general CIT rate under the 2025 Law on Corporate Income Tax is 20%, unless a different rate or preferential tax rate applies.
For example:
If a company has VND 1 billion in taxable profit and the applicable CIT rate is 20%, its CIT payable before the reduction would be VND 200 million. And the company qualifies for the 30% CIT reduction under Resolution No. 43/2026/QH16, it would receive a reduction of VND 60 million (30% of VND 200 million) and would therefore pay VND 140 million in CIT.
=> In other words, the company effectively pays 70% of its applicable CIT liability. The statutory CIT rate, however, remains 20%; it is not reduced to 14%.
15% and 17% CIT Rates for Smaller Enterprises
The 2025 Law on Corporate Income Tax introduced additional CIT rates for qualifying enterprises:
| Annual revenue condition | CIT rate |
| No more than VND 3 billion | 15% |
| Over VND 3 billion to VND 50 billion | 17% |
| General rate | 20% |
The law specifies that the revenue used to determine eligibility for the 15% and 17% rates is based on the total revenue of the immediately preceding CIT tax period, subject to the applicable rules. Certain types of income and enterprises are excluded from these reduced rates.
Businesses should therefore avoid assuming that the VND 10 billion threshold under Resolution 43 and the thresholds for the 15% or 17% CIT rates operate in exactly the same way.
Vina TPT – Accounting & Tax Services
Vina TPT provides accounting, tax and business advisory support for companies operating in Vietnam, with experience supporting foreign-invested businesses and their ongoing compliance requirements.
Our services cover accounting records, periodic tax declarations, CIT, VAT, PIT, foreign contractor tax, payroll and other tax-related compliance matters.
For businesses reviewing their tax position for the 2026–2027 tax periods, our team can support the review of applicable CIT rules, tax incentives and compliance requirements based on the company’s specific circumstances.
Need support with accounting and tax compliance in Vietnam? Contact Vina TPT to discuss your requirements.