

Most international investors and FDI finance directors expanding business in Vietnam are already familiar with International Financial Reporting Standards (IFRS). However, in Vietnam, a company’s set of financial statements must be prepared under Vietnamese Accounting Standards (VAS) and must comply with the strict form system issued by the Ministry of Finance. Due to differences in accounting substance and recognition principles, the two sets of figures often show differences in both value and the timing of revenue and expense recognition.
Entering the 2026 accounting period, the preparation of financial statements Vietnam officially applies the new regulations under Circular 99/2025/TT-BTC (replacing Circular 200/2014/TT-BTC). This article analyzes in detail the structure of the four mandatory financial statements, the signing and filing rules for FDI companies, the list of documents that need to be prepared, and the standardized 8-step book-closing process for companies.
1. What Financial Statements in Vietnam Include
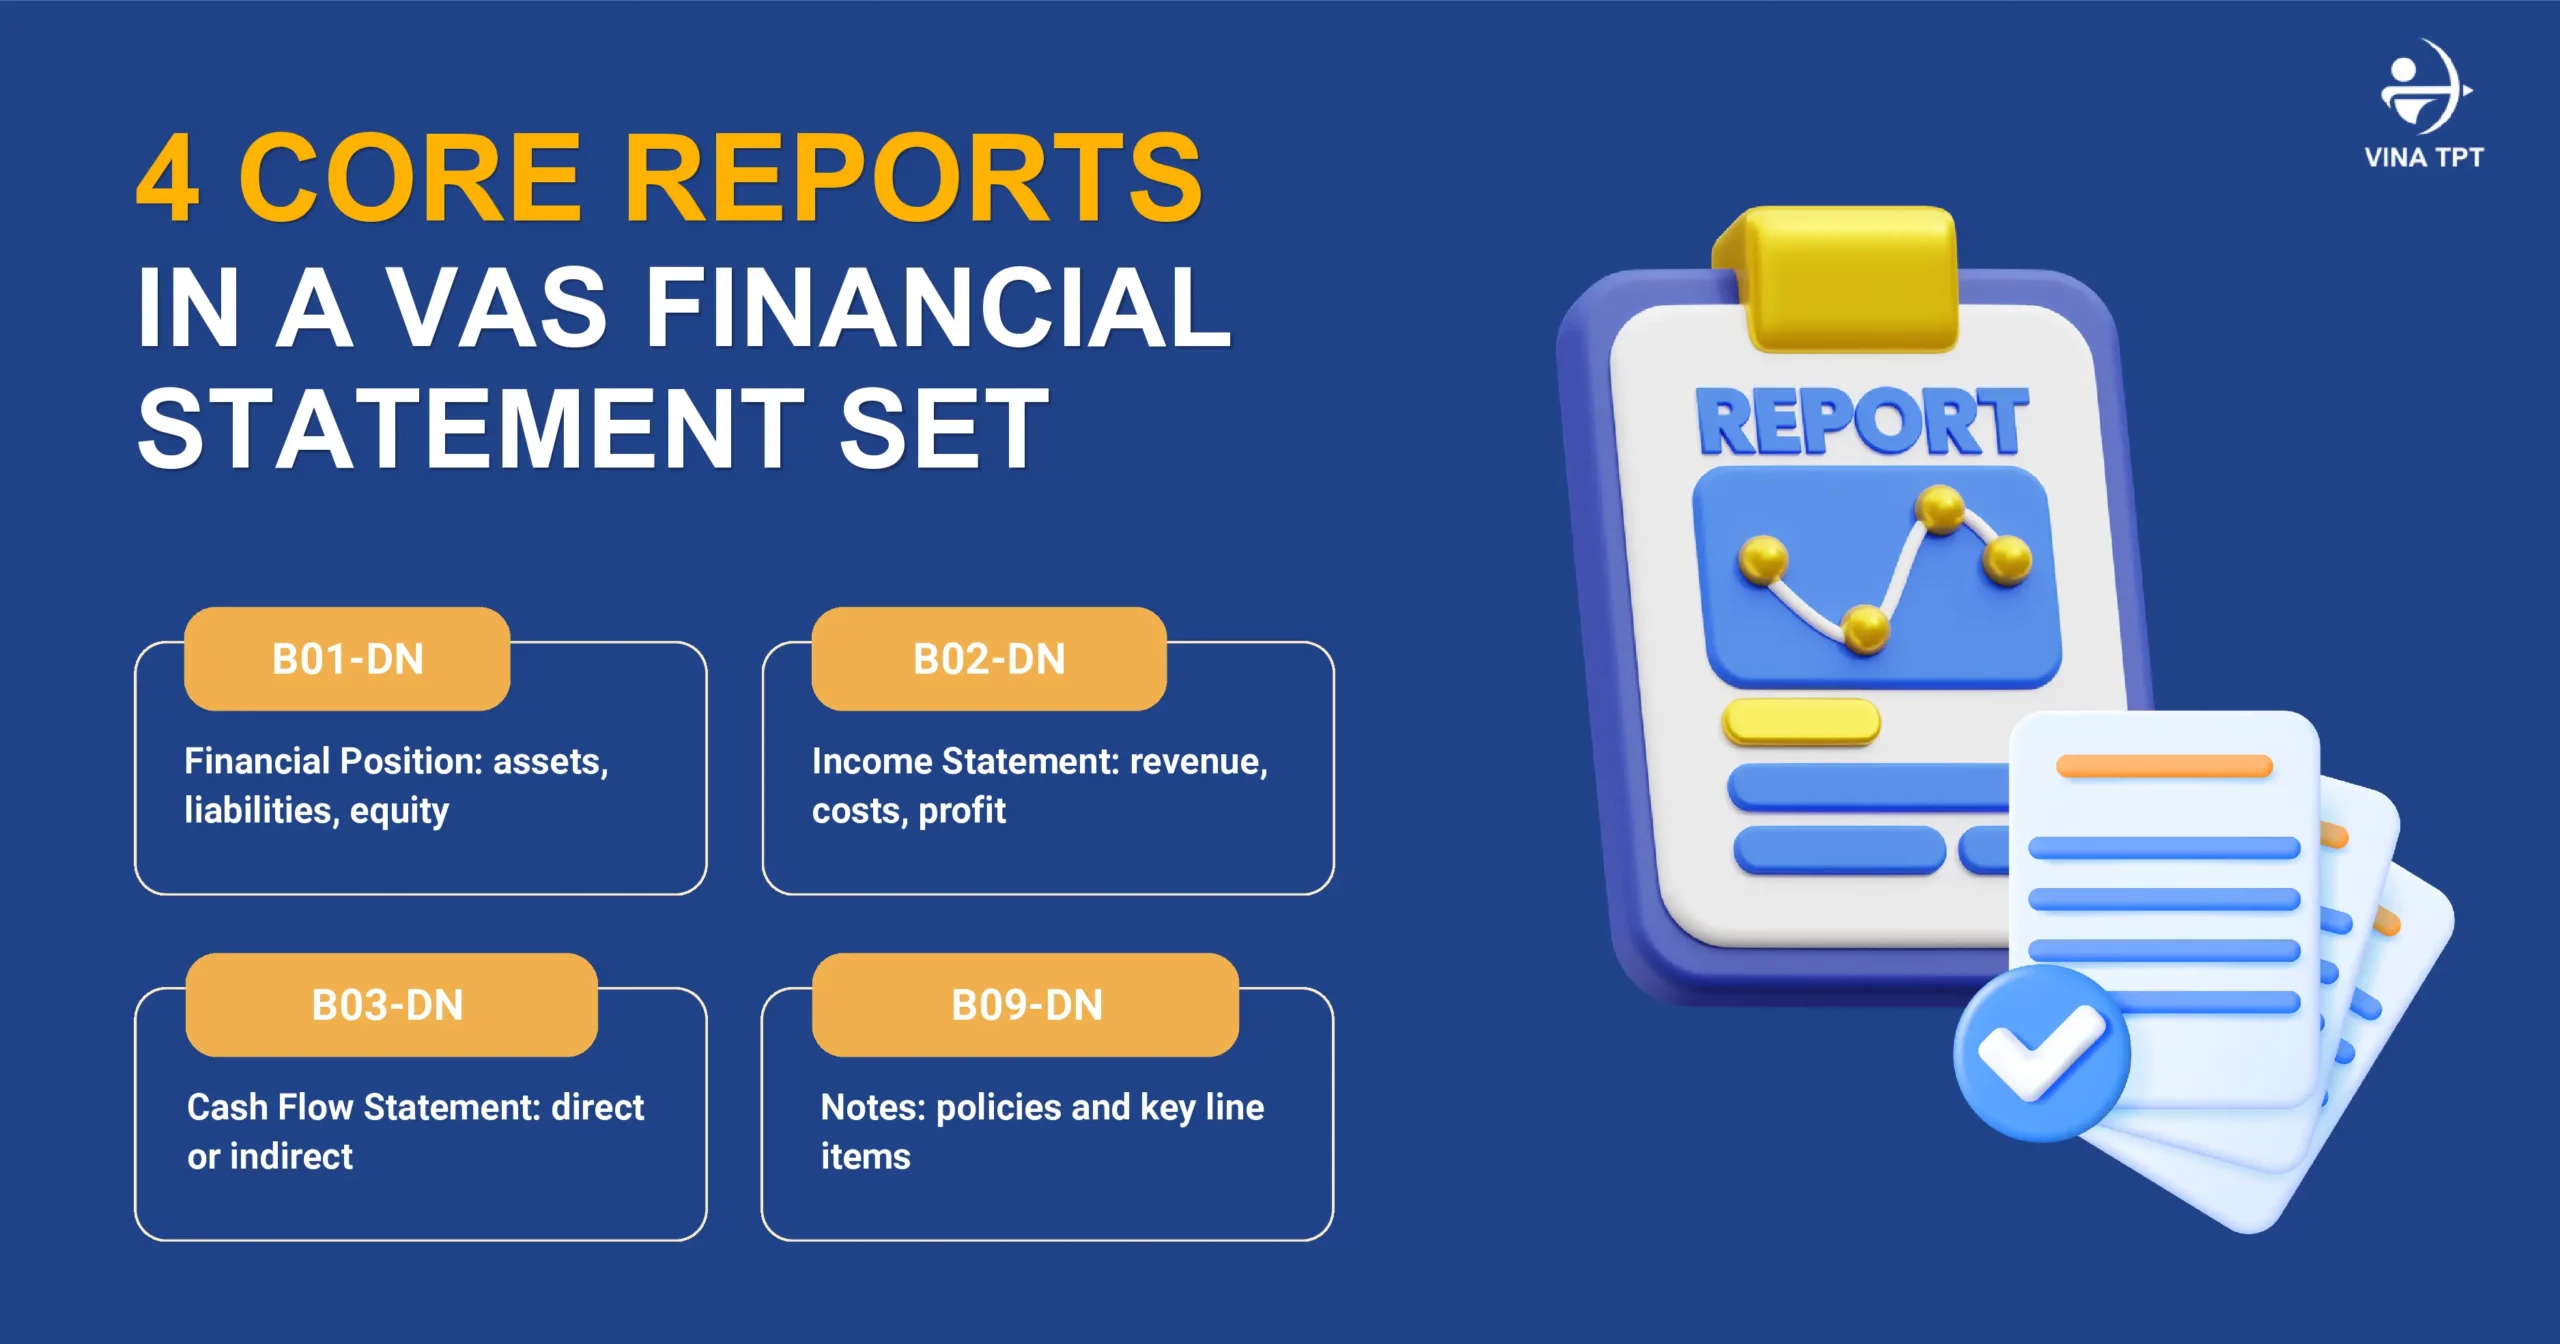
Under Article 17 of Circular 99/2025/TT-BTC, applicable to financial years beginning on or after 01 January 2026, a complete set of annual financial statements of a company includes the following four constituent reports:
- Statement of Financial Position (Form B01-DN): The new legal name replacing the concept of “Balance Sheet,” presenting in aggregate all Assets, Liabilities, and Equity of the company at the book-closing date.
- Income Statement (Form B02-DN): Presenting an overview of revenue, expenses, and net profit from business activities and other activities during the financial year.
- Cash Flow Statement (Form B03-DN): Presenting cash inflows and cash outflows during the period from operating activities, investing activities, and financing activities (prepared under the direct or indirect method).
- Notes to the Financial Statements (Form B09-DN): Providing detailed explanations of the accounting policies applied, movements of significant line items, and financial commitments not yet recognized in the numerical statements.
VAS Financial Statements under Circular 99/2025Circular 99/2025/TT-BTC officially takes effect from 01 January 2026, completely replacing Circular 200/2014/TT-BTC. The new points that directly affect VAS financial statements for 2026 include:
Technical recommendation: FDI companies need to proactively work with their accounting software provider to update the chart of accounts and forms under Circular 99/2025/TT-BTC before the 2026 book-closing period, in order to avoid non-compliance risks during independent audit. |
2. Audit, Signing and Filing Rules for FDI Companies
Foreign-invested companies (FDI) in Vietnam are subject to strict management regarding annual financial statement obligations:
- Mandatory audit obligation: All FDI companies are required to have their annual financial statements audited by an independent audit firm legally operating in Vietnam, regardless of capital size or profit/loss status (as prescribed in Article 37 of the Law on Independent Audit 2011 and Article 15 of Decree 17/2012/NĐ-CP).
- Signing responsibility: Financial statements must bear the signatures of the preparer, the Chief Accountant (or the person in charge of accounting), and the Legal Representative of the company (under Article 29 of the Law on Accounting 2015).
- Filing deadline: No later than 90 days from the end of the financial year, the company must complete submission of the financial statements together with the independent audit report (as prescribed in Articles 25–26 of Circular 99/2025/TT-BTC). For the 2026 financial year calculated on a calendar-year basis, the final filing deadline is 31 March 2027.
- Receiving authorities: The company submits the financial statements simultaneously to the directly managing Tax Authority, the Statistics Authority, the Business Registration Authority (Department of Planning and Investment), and the Management Board of the Industrial Park/Export Processing Zone (if the company is located in such a zone).
- Accounting currency conversion: In cases where the company is approved by the Ministry of Finance to use a foreign currency as its accounting currency, the financial statements submitted to state authorities must be converted into Vietnamese Dong (VND) at the prescribed exchange rate.
- Penalties for late filing: Under Decree 41/2018/NĐ-CP (as amended by Decree 102/2021/NĐ-CP and the latest updating documents), late filing of financial statements for less than 3 months is subject to a fine of 5–10 million VND; late filing of 3 months or more, or failure to attach the audit report, is subject to a fine of 10–20 million VND.
3. Documents to Prepare Before Closing the Books
To ensure the process of preparing financial statements and the audit proceeds on schedule, companies need to proactively prepare a complete set of source documents before 31 January 2027:
- Bank balances: Full 12-month statements of all VND and foreign-currency current accounts and the Direct Investment Capital Account (DICA).
- Invoices and documents: All input and output invoices that have been reconciled and matched with the tax authority’s invoice management system.
- Receivables/payables and contracts: Debt confirmation reconciliation minutes as of 31 December with customers and suppliers, and major economic contracts still in effect.
- Assets and inventories: Fixed asset register, depreciation schedule, together with cash count minutes and physical inventory count minutes as of 31 December 2026.
- Labor and tax: 12-month payroll, social insurance payment documents, and tax returns (VAT, PIT, FCT) filed during the year.
- Foreign currency and related-party transactions: Schedule of foreign-currency balances, year-end exchange rates, and list of transactions arising with related parties within the group.
4. How Financial Statements Are Prepared: Step by Step
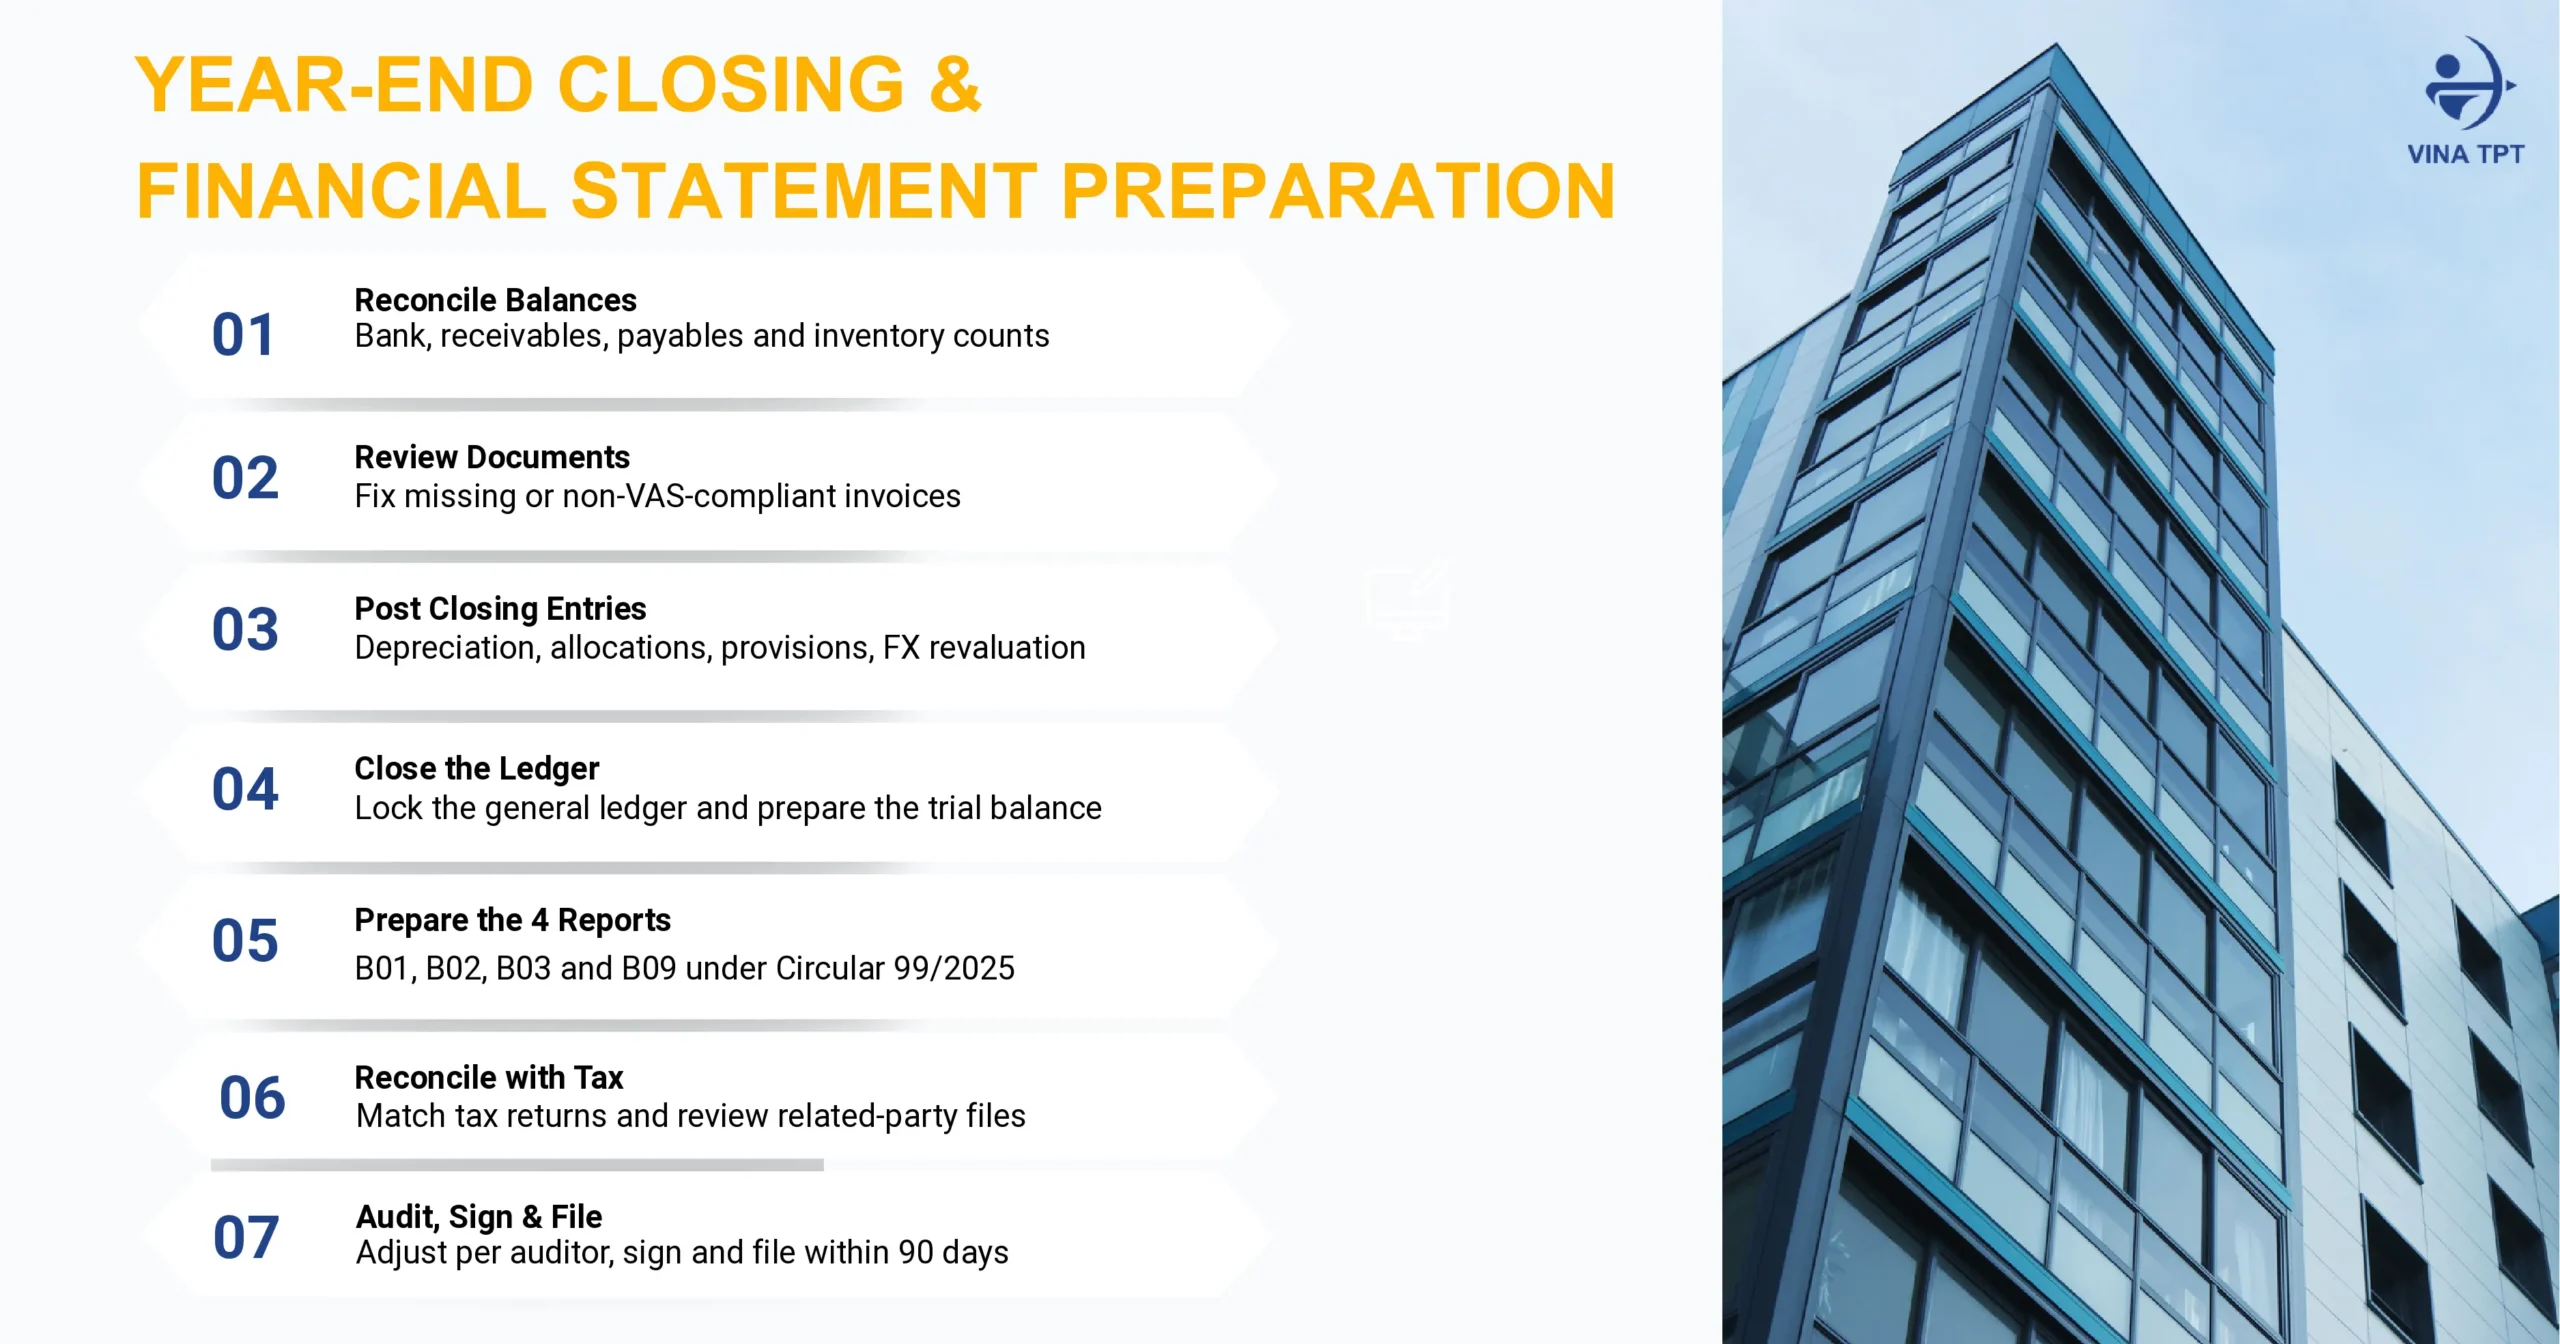
To complete a standard set of annual financial statements that fully meets audit requirements and does not generate risks during tax finalization, companies need to follow a rigorous book-closing process. Below are the 8 standard implementation steps that help the accounting department comprehensively control figures from source documents through to the issuance of the official report:
- Step 1: Reconcile bank deposit balances, receivable/payable balances, and perform physical inventory counts.
- Step 2: Review the set of accounting documents and process any missing invoices or documents that do not meet VAS validity requirements.
- Step 3: Record year-end closing entries: depreciation of fixed assets, allocation of prepaid expenses, recognition of provisions, and revaluation of foreign-currency monetary items.
- Step 4: Close the general ledger and prepare the Trial Balance.
- Step 5: Generate the four financial statements according to the form system of Circular 99/2025/TT-BTC.
- Step 6: Reconcile consistency between the financial statements and the periodic tax returns already filed, and review related-party transaction files.
- Step 7: Hand over the data to the independent audit firm and perform adjusting entries according to the auditor’s recommendations.
- Step 8: Complete legal signing and finalize submission of the reports to the competent authorities within the prescribed deadline.
5. How Financial Statements Link to Tax Finalization
Audited financial statements are the most important legal basis for determining Corporate Income Tax obligations for the year. The accounting profit before tax figure on the financial statements (Form B02-DN) is the starting point for adjusting increase/decrease differences under tax law, thereby determining taxable income for Corporate Income Tax.
The deadline for submitting the Corporate Income Tax finalization dossier coincides with the deadline for submitting financial statements (the last day of the third month from the end of the financial year, under Article 44 of the Law on Tax Administration 2019). Where the company has related-party transactions, the financial statements must be submitted together with the related-party transaction information appendices under Decree 132/2020/NĐ-CP.
(Note: To learn more about annual tax finalization regulations, please refer to the article Annual Tax Finalization in Vietnam 2026. In addition, the obligation to report FDI investment project implementation status on the fdi.gov.vn system is an independent reporting obligation, detailed in the article on FDI Investment Reporting Requirements.)
6. Year-End Financial Statement Support at Vina TPT
With its position as an advisory firm with more than 20 years of experience supporting FDI companies, Vina TPT provides a comprehensive solution for the 2026 annual financial statement period:
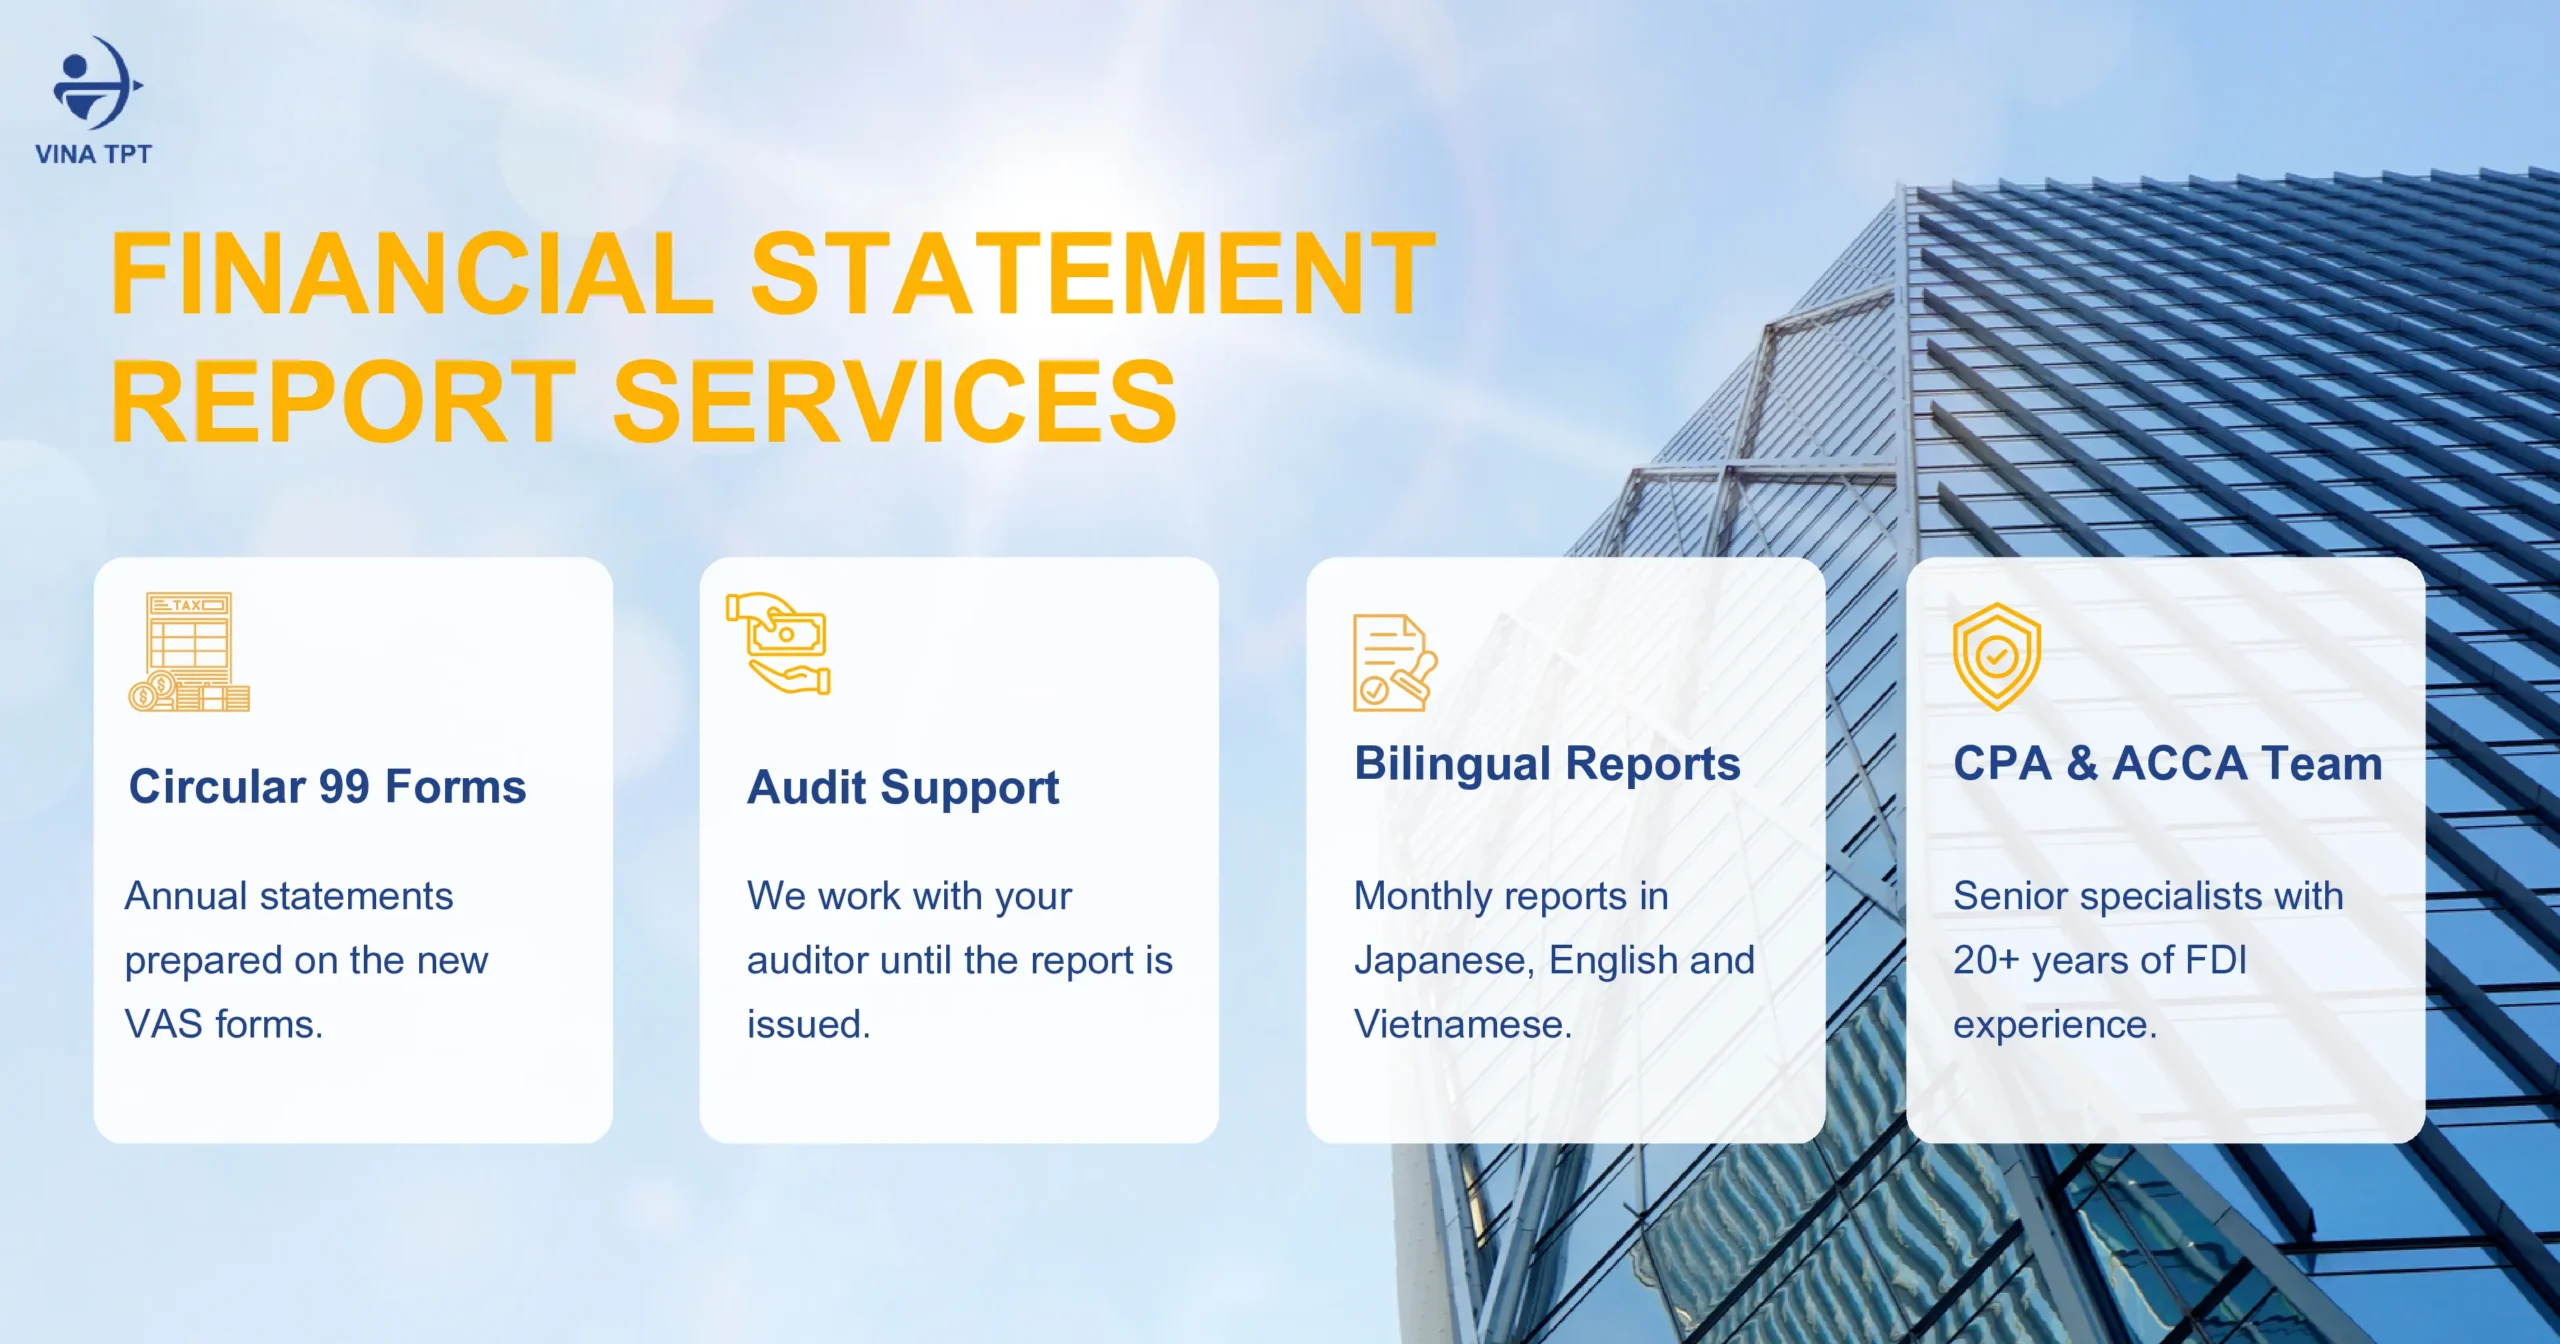
- Standardized financial statement preparation: Perform the full recording and preparation of financial statements in exact accordance with the forms prescribed in Circular 99/2025/TT-BTC.
- Audit representation: Work directly with independent audit firms and explain figures in depth until the official audit report is issued.
- Bilingual management reports: Provide a standardized periodic monthly/quarterly management reporting system in bilingual (Japanese – English – Vietnamese) format to help the Parent Company easily control finances.
- Senior specialist team: Directly performed by specialists holding CPA and ACCA certificates with more than 20 years of FDI advisory experience.
Conclusion
The set of financial statements in Vietnam consists of four standard reports under VAS, must be independently audited for FDI companies, and must be submitted to the competent authorities within 90 days. Early preparation of documents from January is the key factor that enables companies to proactively control figures and complete compliance obligations on time.
Please send information about your financial year and current book status to receive the document preparation checklist and a free book-closing roadmap.