In 2026, there are many changes to the accounting regime, particularly the official replacement of Circular 200 by Circular 99/2025/TT-BTC from 01 January 2026. Adjustments to the chart of accounts, the presentation of financial statements, and internal control requirements have caused difficulties for many company accountants – especially accountants of FDI companies – when closing the books and preparing the annual financial statements.
This article shares the points to note when preparing 2026 financial statements under VAS, from report components and documents that need to be prepared to the book-closing process, with the aim of helping FDI companies complete the report set on time and in line with audit requirements as well as Corporate Income Tax finalization.
1. What Year-End Financial Reporting Requires in 2026
Under Vietnamese Accounting Standards (VAS), a complete financial statement set must include four components: the Balance Sheet, the Income Statement, the Cash Flow Statement, and the Notes to the Financial Statements. For foreign-invested companies (FDI), the annual financial statements must be audited by an independent audit firm that is legally operating in Vietnam. The deadline for submitting audited financial statements is no later than 90 days from the end of the financial year (corresponding to 31 March 2027 for companies that apply a calendar financial year).
The 2026 financial statement period is the first year companies officially apply Circular 99/2025/TT-BTC in place of Circular 200/2014/TT-BTC. Two core changes that directly affect the annual financial statements are:
- Transition of the chart of accounts: Changes to the list and accounting methods of certain detailed accounts require that the conversion of opening balances be performed accurately and accompanied by a clear reconciliation with the old books.
- Transparency requirements on the financial statements: Restructuring of the presentation method for certain items on the Income Statement and the Notes to the Financial Statements, while raising standards for internal control and financial information disclosure.
The detailed components and the book standardization process will be analyzed in depth in the article on the accounting regime for FDI companies.
2. Documents to Prepare Before Closing the Books
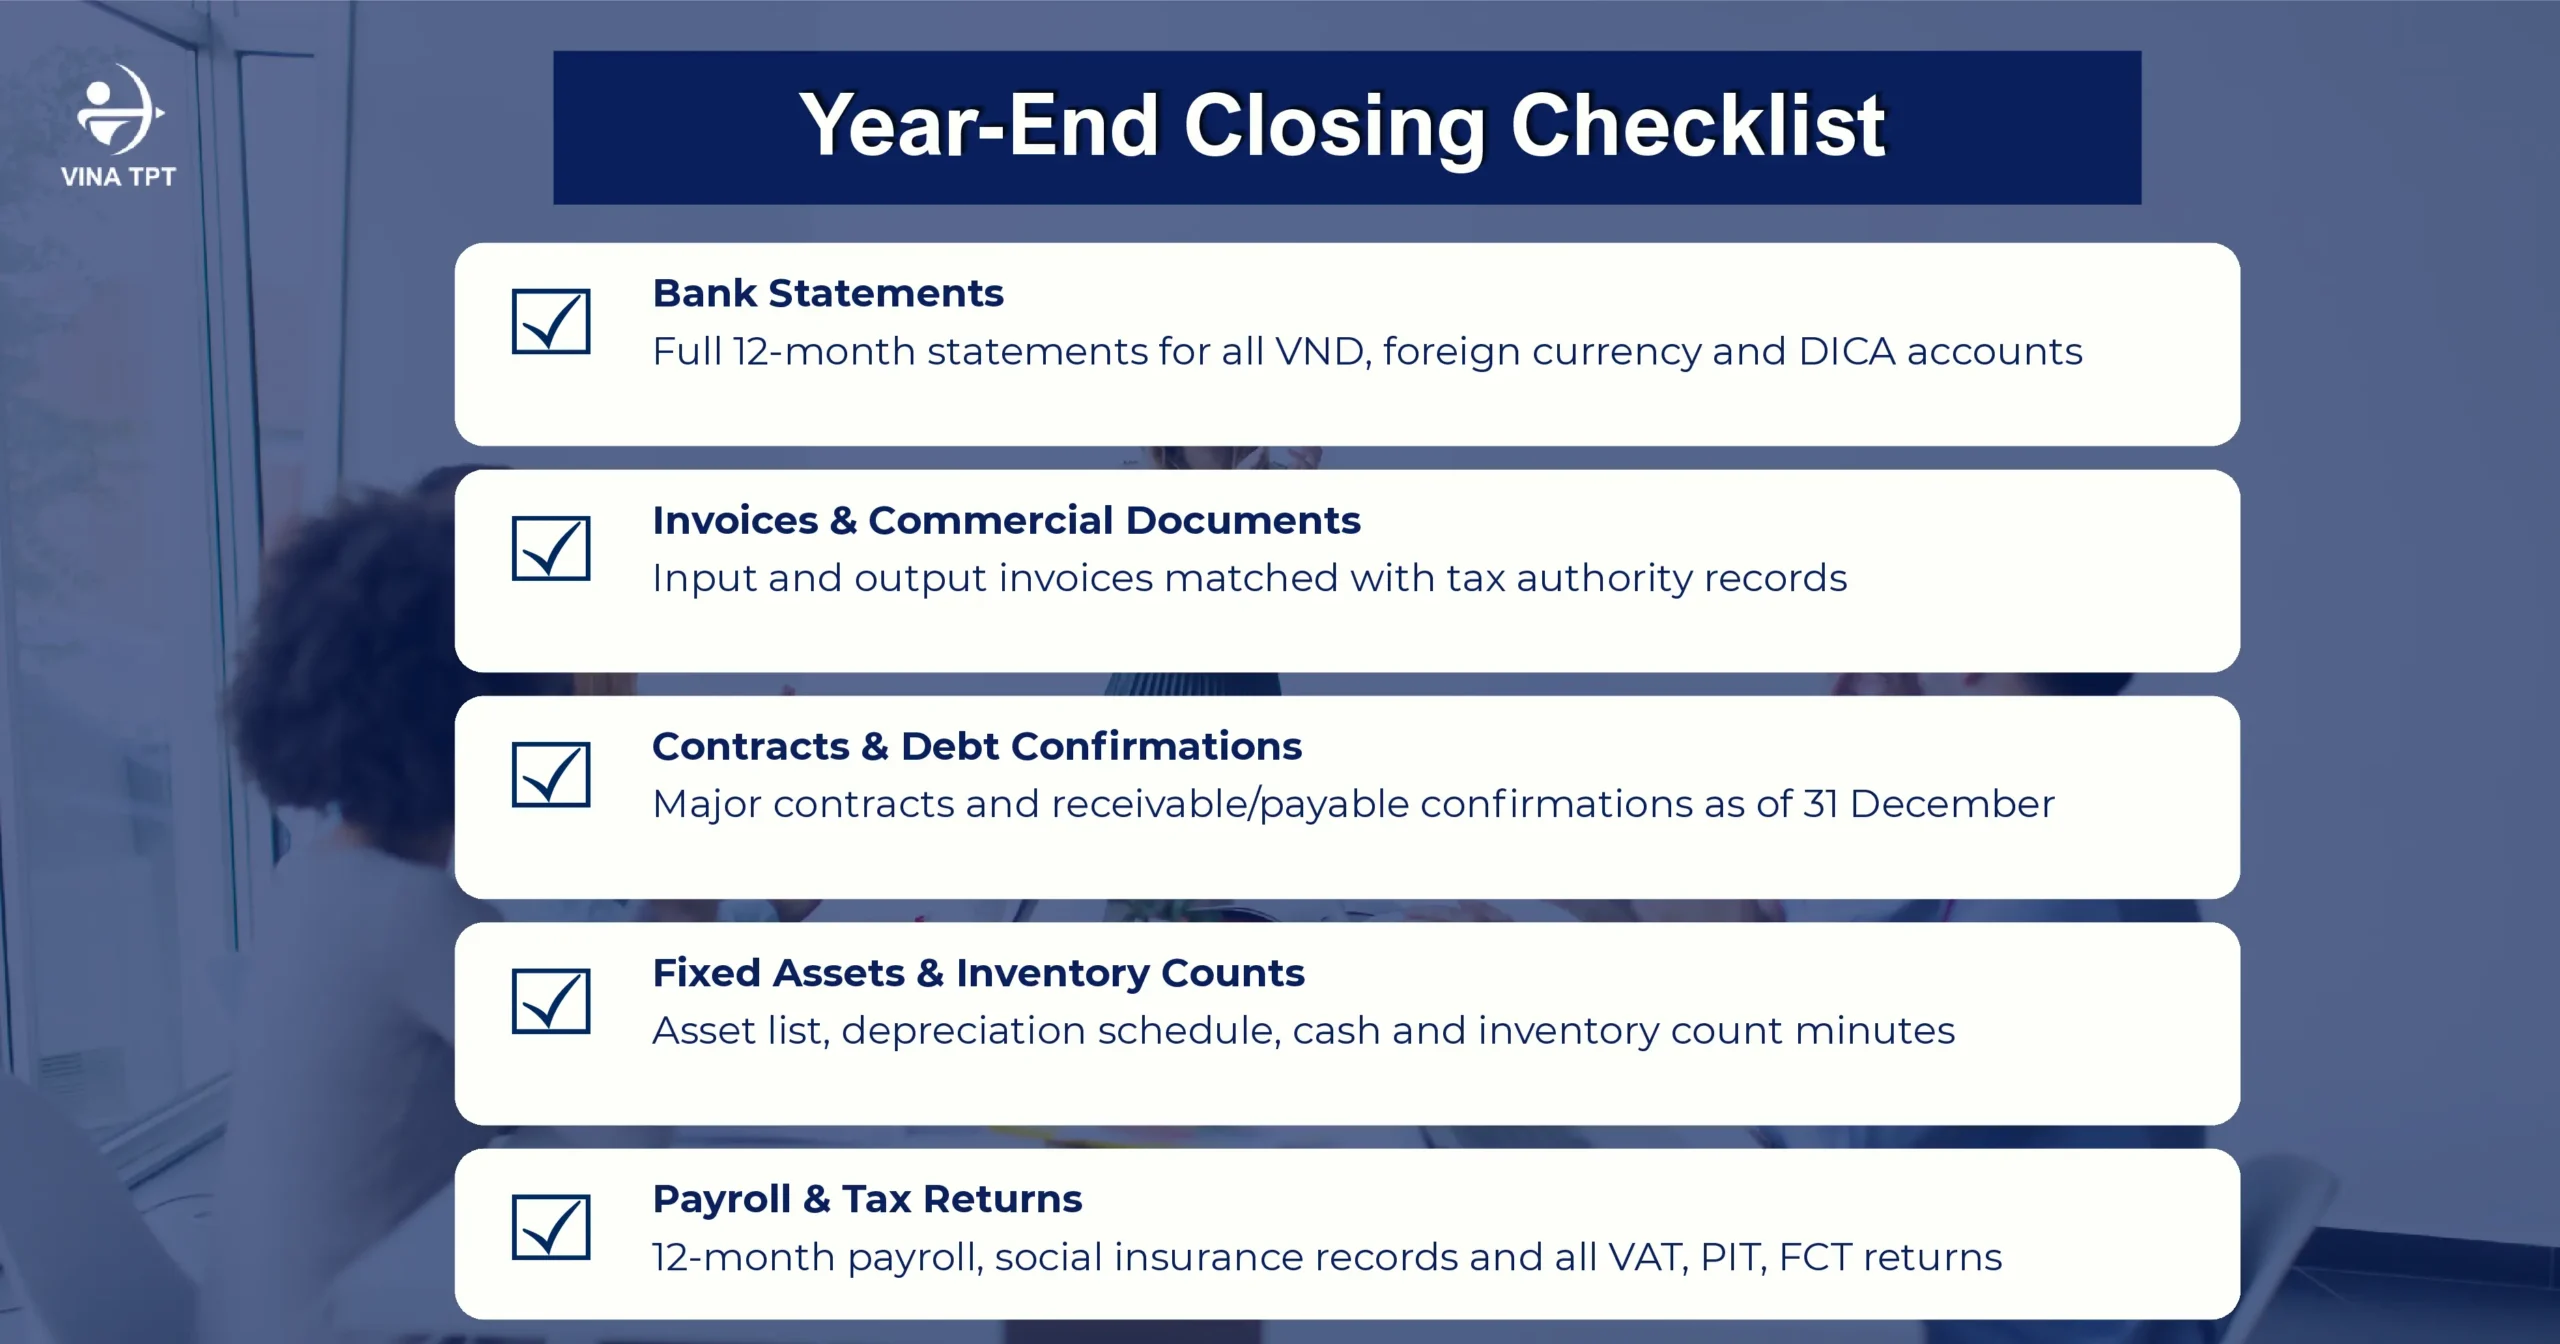
To ensure the 2026 annual financial statement closing proceeds accurately and without interruption, companies need to proactively collect and prepare a complete set of source documents, including:
- Bank account statements: Full 12-month statements for all current accounts (VND and foreign currency) and the Direct Investment Capital Account (DICA).
- Invoices and commercial documents: All input and output invoices that have been reconciled and matched with the tax authority’s invoice management system.
- Contracts and receivables/payables: Major economic contracts arising during the year, together with debt confirmation reconciliation minutes as of 31 December with customers and suppliers.
- Assets and inventory counts: Fixed asset list, depreciation schedule, together with cash count minutes and physical inventory count minutes as of 31 December 2026.
- Labor and tax: 12-month payroll, social insurance payment documents, and all tax returns (VAT, PIT, FCT) filed during the year.
Recommended timeline: Companies should complete the handover of all document data before 31 January 2027. This is the golden period for the specialist team to check validity, perform year-end adjusting entries, and work with the independent auditor before the legal deadline of 31 March 2027.
3. What Our Financial Reporting Services Include
Vina TPT’s financial reporting services package for the 2026 accounting period is designed as an end-to-end solution, representing the company in all specialized technical stages:
- Consultation and classification: Review and advise on the correct list of required documents under VAS regulations.
- Document examination: Check the legality, validity, and reasonableness of all accounting documents provided by the company.
- Specialized recording: Perform closing entries, allocations, provision recognition, and year-end foreign exchange revaluation.
- Balance review: Analyze, check the balance, and reconcile in detail the balances of all accounting accounts.
- Preparation and explanation of financial statements: Prepare the annual financial statement set in full compliance with VAS, submit it to the Board of Directors for approval, and answer all detailed questions about the figures.
- Audit accompaniment: Represent the company in working directly with the independent audit firm and provide explanatory documents until the official audit report is issued.
Superior value from Vina TPT: With more than 20 years of specialized experience in FDI advisory, and a team of specialists holding CPA and ACCA certificates, Vina TPT provides standardized bilingual (Japanese – English – Vietnamese) financial statements. We provide a Chief Accountant solution that signs off on the financial statements (when using the Chief Accountant service) and implement the entire operating process flexibly on a remote platform.
BOOK A FINANCIAL REPORTING SERVICES CONSULTATION
4. When Is the Right Time to Prepare the Financial Statements
Although the law allows a 90-day deadline for submitting financial statements from the end of the financial year, companies should absolutely not wait until the end of the year to begin collecting and processing data. In practice, accounting data needs to be reviewed and checked on a monthly basis to promptly detect errors and make adjustments arising during the year.
For small and medium-sized companies that are using in-house accounting staff to record the books and want an independent advisory firm to perform a cross-check, Q4 of each year is the most optimal period to begin signing the engagement. Delaying until after 31 December will expose the company to significant risk: most reputable accounting service providers are already fully booked, the workload becomes compressed, leading to the risk of delayed audit progress and late report submission.
5. How Financial Statements Link to Tax Finalization
Audited financial statements are the most important legal basis for preparing the Corporate Income Tax finalization return. Any difference between the financial statement figures and the tax finalization figures that lacks a reasonable explanatory reconciliation is the first warning signal that attracts a tax inspection.
Vina TPT’s financial reporting solution is integrated with the Corporate Income Tax finalization service, ensuring 100% consistency from the VAS book data to the company’s annual tax return.
(To learn more about the legal deadlines, filing process, and the regulation requiring provisional payment of at least 80% of the full-year Corporate Income Tax, please refer to the article: Annual Tax Finalization in Vietnam 2026)
Conclusion
From January onward, companies need to proactively complete document standardization, reconcile bank balances and receivables/payables, and authorize a professional financial reporting provider to prepare the financial statements and complete the audit before 31 March 2027.
Please send information about your financial year and current book status to receive a tailored book-closing roadmap and service quotation.