

“Does changing the accounting service provider mid-year delay the company’s next tax filing period?” The answer is definitely no, provided that the transition is managed tightly through a clear handover list (accounting handover checklist). In practice, delays or discrepancies in figures in the next filing period usually stem from handing over incomplete original records, failing to finalize opening balances, or failing to determine a specific cut-off date between the parties.
This article compiles a detailed accounting handover checklist by group of key records. The content focuses entirely on the technical handover of figures and documents, helping the company maintain continuity and on-time compliance in the following filing periods when it makes the decision to change accounting firm Vietnam.
1. When to Plan the accounting handover checklist
To ensure the transition runs smoothly and does not interrupt tax obligations, the company needs to proactively plan the timeline early:
- Determine the cut-off date: The ideal cut-off point is right after the tax obligations of a periodic filing period (end of month or end of quarter) have been completed and paid. This clearly allocates legal responsibility for the figures already filed between the former firm and the new firm.
- Handle the peak period (finalization season, January–March): If the accounting firm is changed right during the period of preparing Financial Statements and annual tax finalization, the company must agree in writing on which party will bear the main responsibility for completing the Financial Statements and finalizing Corporate Income Tax/Personal Income Tax for the previous financial year.
- Notice period and handover roadmap: The company sends the termination notice within the period committed to in the current service contract. The handover roadmap should run for 2 to 4 weeks before the official cut-off date so that the parties have enough time to count, reconcile and hand over the records.
- Official handover record: The entire list of documents and vouchers and the account balances at the cut-off date must be recorded in detail in a Handover Record confirmed by the parties.
2. Accounting Handover Checklist: Books and Records
The list of accounting books and figures to be handed over consists of two core parts: electronic data and the original legal vouchers.
a. Books and Financial Data
The former accounting firm is obliged to export and hand over all accounting data up to the cut-off date:
- The General Ledger, the Detail Ledgers of accounts and the Trial Balance up to the cut-off date.
- The complete set of Financial Statements of previous years (including the audited version where an independent audit is mandatory).
- Backup files of the data in the accounting software or a complete data export in Excel format.
- The fixed asset register and depreciation schedule, the prepaid expense allocation schedule (Account 242), and the inventory summary and detail schedule of receipts, issues and balances.
- A list of all of the company’s bank accounts together with the reconciliation of deposit balances at the cut-off date.
b. Source Documents and Contracts
Source documents are an important legal basis for explanations when the tax authority carries out an inspection or audit:
- The set of input source documents, output invoices, receipt vouchers, payment vouchers, and bank debit and credit advices.
- All economic contracts (sales and purchase, service provision, loan agreements and asset lease contracts) together with acceptance and liquidation minutes.
Legal note on storage: Under Article 12 of Decree 174/2016/NĐ-CP, the company’s Legal Representative is responsible for managing and storing accounting books, Financial Statements and accounting vouchers for a minimum of 10 years. Therefore, all original documents must be stored centrally at the company’s premises, and the service provider should not hold the originals long-term.
Explore Vina TPT’s Accounting Services
3. Tax Files and Filing History
The filing history and tax files are the foundation for the new accounting firm to continue performing tax obligations in accordance with regulations:
- Periodic tax returns: All VAT returns, Personal Income Tax returns, provisional Corporate Income Tax returns and Foreign Contractor Tax (FCT) returns filed over the periods.
- Annual finalization files: Corporate Income Tax finalization returns and Personal Income Tax finalization returns of past years, together with the related-party transaction information appendices (if any).
- Payment documents: Payment receipts to the state budget, and confirmation notices of outstanding or overpaid tax from the tax authority.
- In-depth files: Files proving Corporate Income Tax incentives, the schedule tracking loss carry-forwards over the years, and the most recent tax inspection/audit minutes of the tax authority (if any).
- Confirmation of period status: A document clearly confirming which accounting/tax periods have been closed and which are still open.
The new firm should reconcile the figures in the returns already filed with the books at the cut-off date. If differences are found, they need to be added to the list of open items for immediate handling, rather than being discovered only at the finalization period.
4. Access Rights to Transfer (accounting handover checklist)
The transfer of access rights to electronic management systems needs to be carried out in parallel to ensure the security and the company’s control:
- Electronic tax account: Receive the login information and change the password immediately after the handover is completed.
- Digital signature (USB Token / Digital Certificate): The digital signature is a legal asset owned by the company and must be kept directly at the company.
- E-invoice account: Hand over the administrator rights of the e-invoice system and the rights to issue/adjust/replace invoices, together with the list of invoices that are wrong or awaiting handling.
- E-banking view rights (Internet Banking): Hand over view-only access to look up balances and transaction history, if it was previously granted to the former accounting firm.
- Social insurance and investment reporting accounts: Receive the electronic social insurance filing account. For FDI companies, the accounts on the National Investment Information System and the statistical reporting system must also be recovered and received.
- Revoking access rights: Revoke all access rights, permissions and passwords of the former service provider immediately after the cut-off handover date.
5. Payroll, Social Insurance and Labor Records (accounting handover checklist)
Labor and payroll records are directly related to deductible expenses when calculating Corporate Income Tax and to employees’ Personal Income Tax obligations:
- Payroll sheets, labor contracts and decisions on salary adjustments/appointments.
- The social insurance unit code, the list of employee increases/decreases and the registration records of dependents.
- Written authorizations for employees’ Personal Income Tax finalization (if any).
- Valid Work Permits and Temporary Residence Cards (TRC) of foreign personnel.
- Periodic labor utilization reports (6-month and annual) already submitted to the labor management authority.
For foreign personnel, the validity of the Work Permit and the Temporary Residence Card should be checked at the time of handover so that the accountant knows the upcoming renewal dates. The payroll and social insurance records should also be reconciled with the number of employees actually working at the company.
6. Open Items and Handover Minutes
Outstanding items that have not been handled need to be listed transparently so that the new accounting firm can take them over and follow up on their resolution:
- A list of customer/supplier balances not yet reconciled, internal advances not yet settled, or invoices/documents still missing.
- Files, explanation documents or tax refund requests awaiting an official response from the tax authority.
- The schedule for tracking the filing and payment deadlines of the next filing period.
- Handover Minutes: The record must state in detail the list of records, the opening account balances handed over, and the lawful confirming signatures of the company’s Representative, the former service provider and the new service provider.
Each outstanding item should state the person in charge, the deadline for handling and the related documents. This list is attached to the handover record so that the parties can follow it together until completion.
7. How Vina TPT Takes Over Your Books
The process of taking over books at Vina TPT is standardized to protect the interests of the company:
- Reviewing the list before takeover: Vina TPT sends the company a detailed accounting handover checklist before the cut-off date, and proactively reconciles the opening balances taken over with the data in the tax returns already filed.
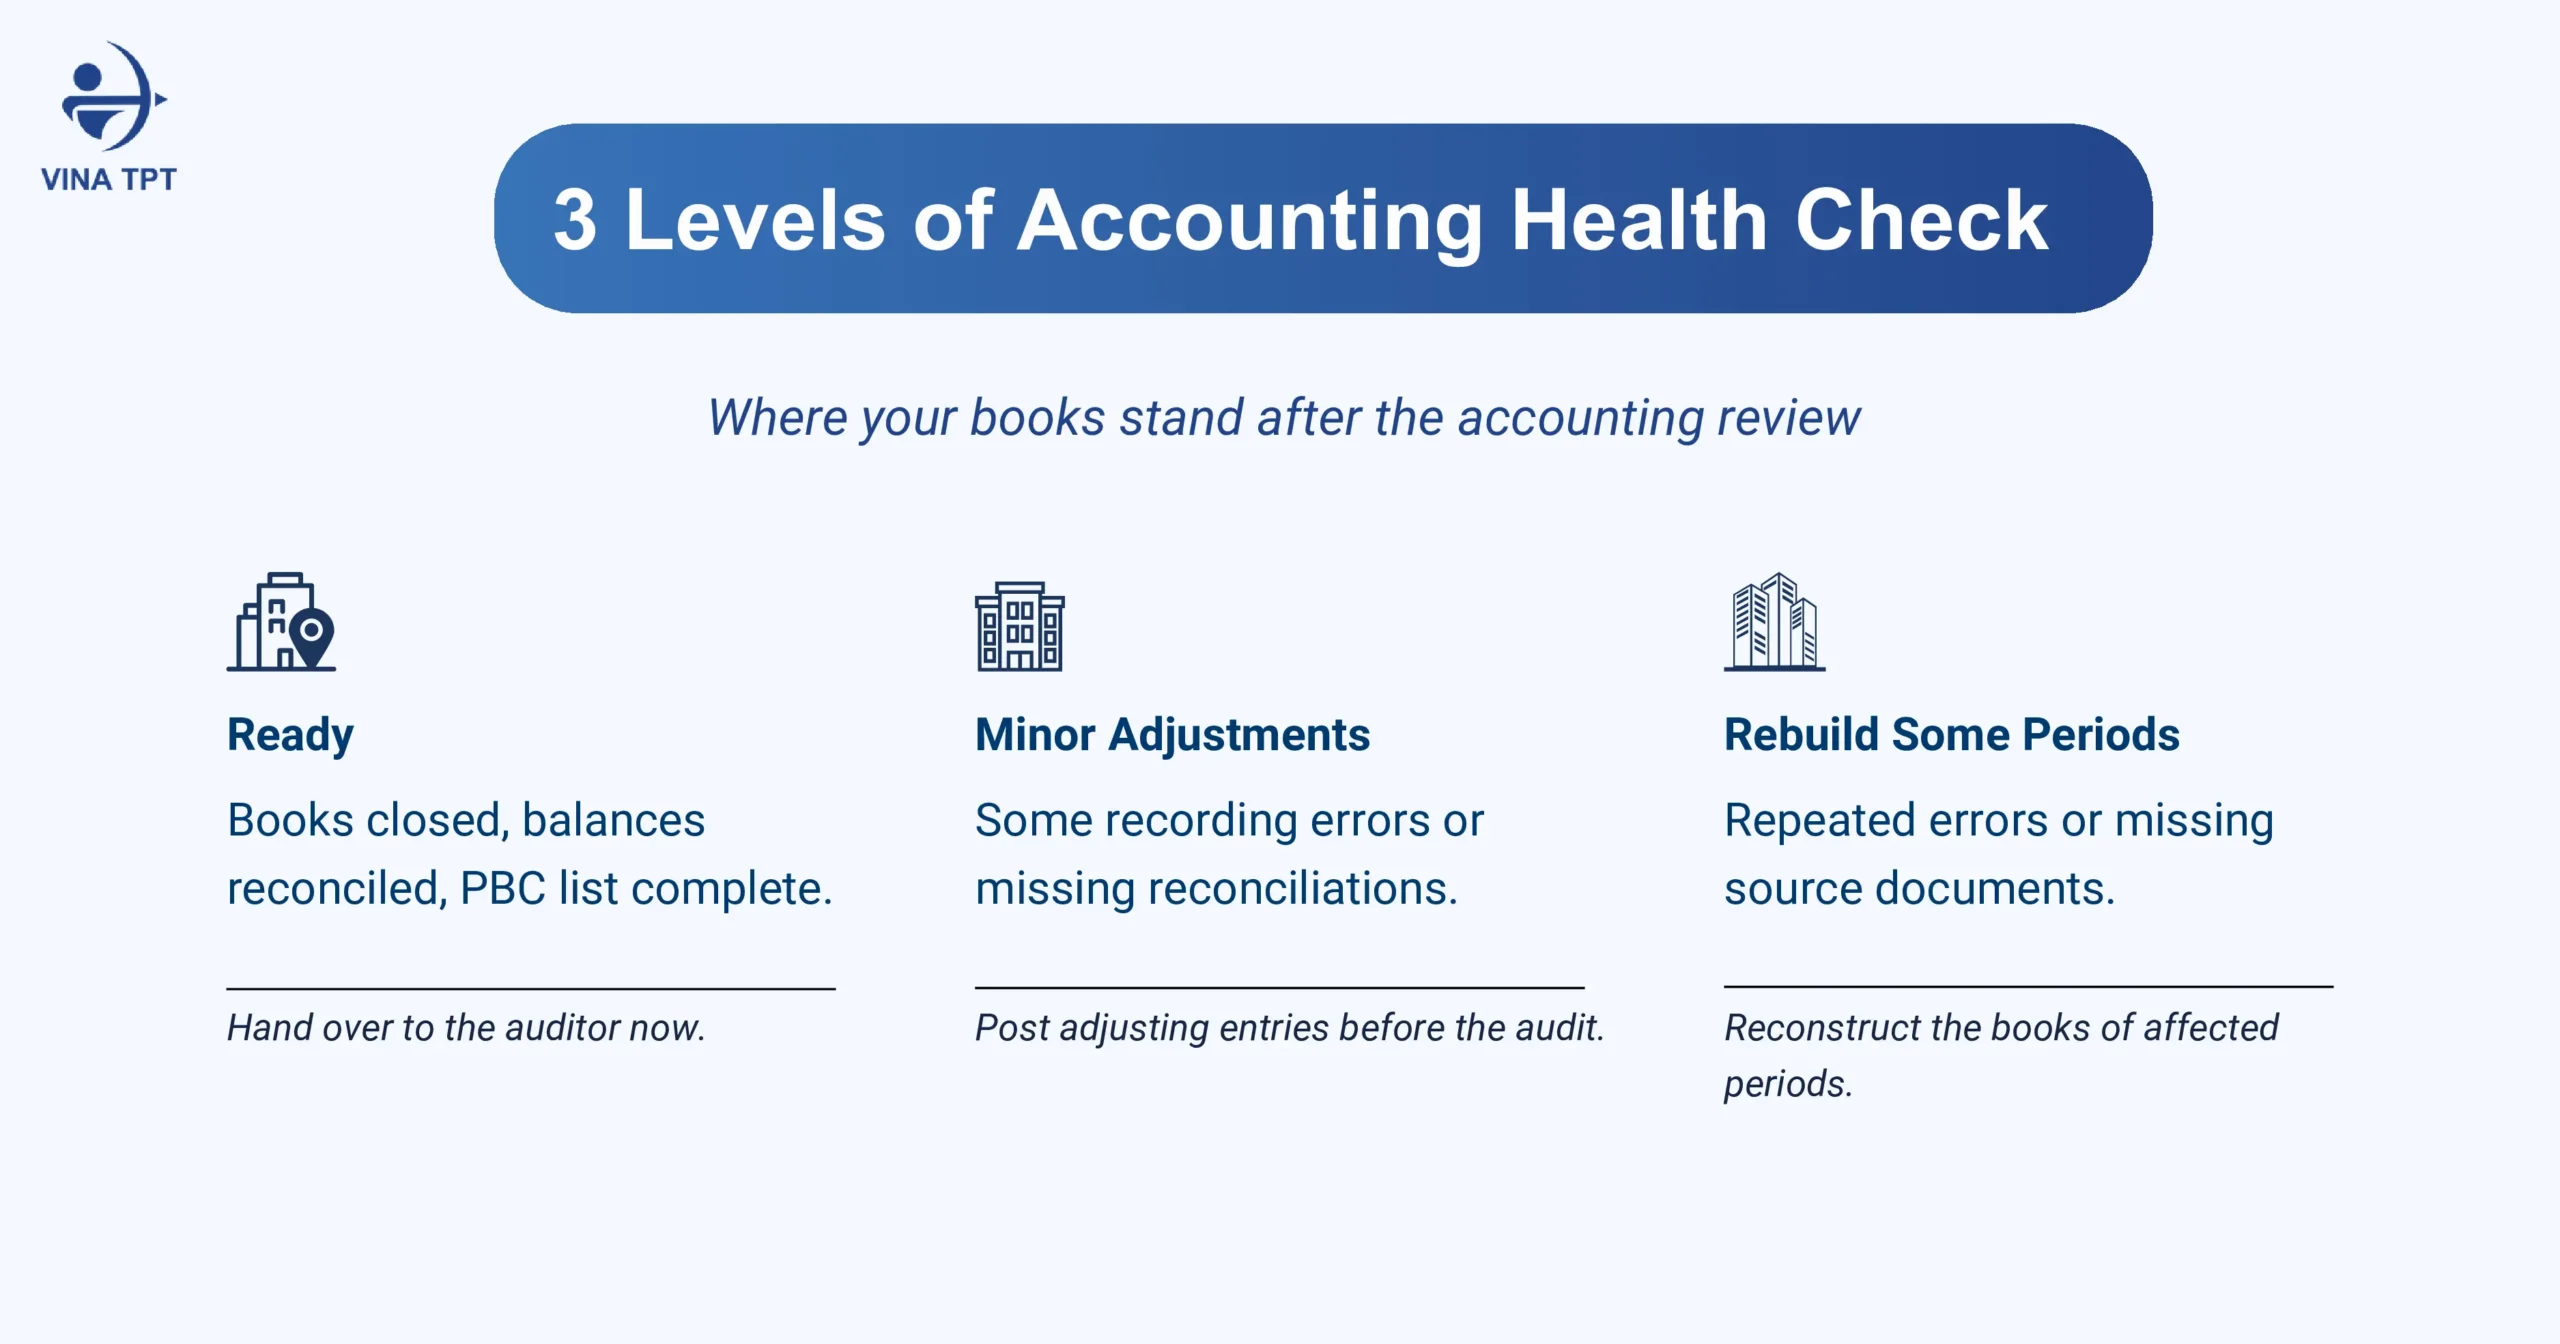
- Proposing an Accounting Review: If the former books are found to have many errors or inconsistent figures, we will propose an in-depth accounting review solution (please refer to the article Accounting Review in Vietnam for more details).
- Ensuring the schedule & bilingual reports: The first tax filing period right after the handover is submitted on time, and the company receives a bilingual reporting system so that the management can follow the situation.
Conclusion
Using a standardized accounting handover checklist helps the company control all financial books, tax files, electronic access rights, payroll – social insurance data and outstanding tasks when changing service providers. This careful preparation ensures that the company’s tax compliance runs continuously and with legal safety. When each group of records is counted and confirmed in the handover record, the new accounting firm can take over the work right from the first filing period.
Please send us the planned date for changing your accounting firm to receive a list of files to prepare under the accounting handover checklist and a free sample Handover Record, together with a takeover roadmap that fits your company’s filing schedule!