

Foreign direct investment (FDI) enterprises and multinational corporations operating in Vietnam operate under strict regulatory scrutiny regarding Transfer Pricing Vietnam compliance. The General Department of Taxation actively identifies profit shifting, scrutinizes cross-border transactions, and targets artificial margin compression.
At the center of this enforcement architecture stands Decree 132/2020/ND-CP, which establishes rigorous documentation standards aligned with the OECD’s Base Erosion and Profit Shifting (BEPS) Action 13 framework. Navigating these requirements demands meticulous preparation: failure to maintain compliant contemporaneous files exposes taxpayers to severe tax reassessments, aggressive expense disallowance, and statutory penalties.
Key Takeaways for Taxpayers:
- Decree 132 applies to all domestic and cross-border related-party transactions (RPTs).
- Net interest expense deductions are capped at 30% of EBITDA across all debt instruments once RPTs exist.
- Compliance mandates both annual disclosure forms and a contemporaneous three-tiered documentation package.
- Missing filing deadlines or presenting unverified benchmarks allows tax authorities to adjust profits directly to the median range.
1. Regulatory Framework & Key Triggers Under Decree 132
Vietnam’s transfer pricing regime operates strictly under the principle of substance-over-form. Decree 132/2020/ND-CP regulates how associated enterprises determine transaction prices, allocate operating costs, and establish taxable income for Corporate Income Tax (CIT) purposes. The framework hinges on identifying associated relationships and controlling allowable deductions.
1.1 How Related-Party Relationships Are Defined
Under Article 5 of Decree 132, two entities are classified as related parties when one party participates directly or indirectly in the management, control, capital contribution, or financing of the other. Critical legal triggers include:
- Equity Ownership Threshold: One enterprise directly or indirectly holds at least 25% of the owner’s equity in the second enterprise.
- Financing & Guarantee Exposure: One enterprise guarantees or extends loans to another, provided the loan capital represents at least 25% of the borrowing entity’s equity and constitutes more than 50% of its total medium- and long-term debts.
- Management & Control: An enterprise appoints more than 50% of the board of directors or controls key executive decisions of another.
- Commercial Dependency: One entity accounts for more than 50% of the total sales or purchase turnover of the other entity under exclusive commercial arrangements.
Common Audit Trap: Many independent foreign enterprises mistakenly trigger related-party status simply by securing a large commercial bank loan backed by a parent company guarantee, unaware that passing the 25% equity and 50% debt threshold subjects their entire cost structure to Decree 132.
1.2 The 30% EBITDA Cap on Net Interest Expense
Under Clause 3, Article 16 of Decree 132/2020/ND-CP, the cap on deductible loan interest expenses is stipulated as follows:
- Interest Cap: Total net interest expense (interest expense incurred during the period minus interest income from deposits and loans) deductible for Corporate Income Tax (CIT) purposes shall not exceed 30% of the total net operating profit plus net interest expense and depreciation/amortization expenses (EBITDA).
- Negative EBITDA: If the taxpayer’s EBITDA is negative or zero, the entire net interest expense incurred in the period is non-deductible.
- Carry-Forward of Disallowed Interest: Any net interest expense exceeding the 30% cap can be carried forward to subsequent tax periods when determining total deductible interest expense. The continuous carry-forward period must not exceed 05 consecutive years, starting from the year following the incurred year.
- Excluded Entities: This cap does not apply to credit institutions, insurance enterprises, securities companies, and certain ODA-funded projects or concessional government loans as prescribed by law.
2. Who Must Prepare Documentation? Exemptions and Safe Harbors
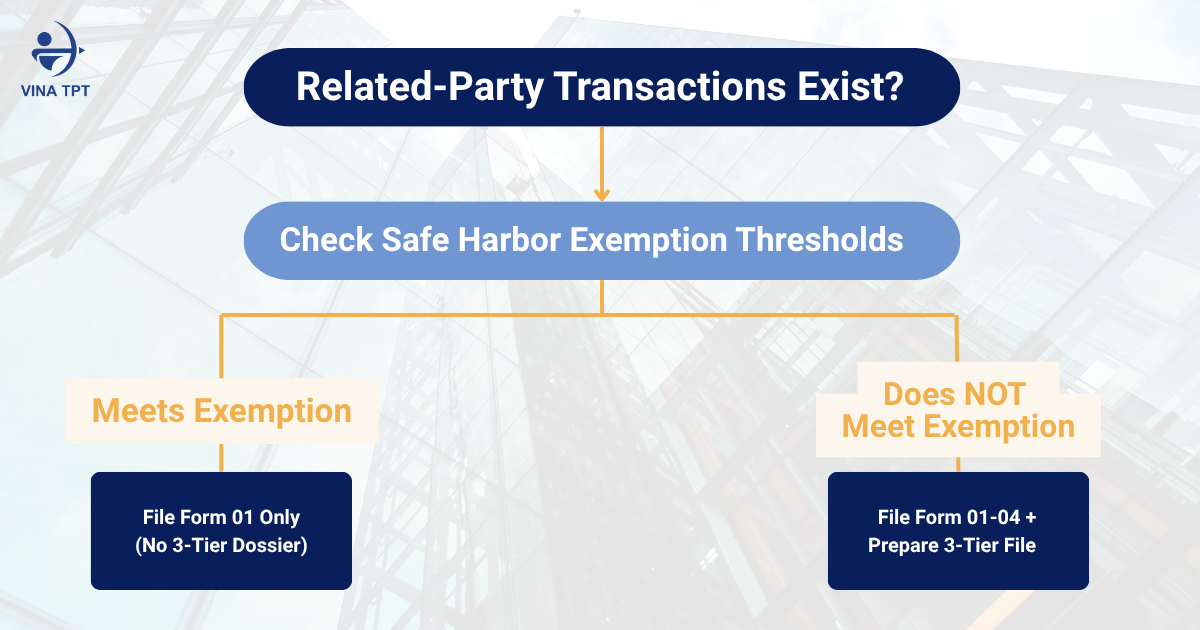
Enterprises engaging in related-party transactions must assess their eligibility under the safe harbor provisions of Decree 132 before committing resources to full documentation packages
2.1 Full Exemption Thresholds
Under Clause 2, Article 19 of Decree 132/2020/ND-CP, taxpayers are exempt from preparing Transfer Pricing Documentation (Local File, Master File, and CbCR) if they qualify under any of the following cases:
- Revenue and Transaction Threshold: Total revenue in the tax period is under VND 50 billion and the total value of related-party transactions is under VND 30 billion.
- Advance Pricing Agreement (APA): The taxpayer has entered into an APA and submits the required annual APA reports in compliance with applicable regulations.
- Simple Business Operations Meeting Margin Thresholds: The taxpayer performs routine functions, incurs no revenue or expenses from intangibles, generates revenue under VND 200 billion, and achieves an operating margin (EBIT to net revenue) of at least:
» 5% for distribution.
» 10% for manufacturing.
» 15% for toll processing/contract manufacturing.
Note: Taxpayers exempt from TP documentation are still required to submit the prescribed TP disclosure forms with their annual CIT return.
2.2 Form Disclosure vs. Contemporary Documentation
Taxpayers frequently confuse filing exemptions with complete reporting waivers:
- Exempt Taxpayers (Form-Only): Qualifying for a documentation safe harbor waives only the burden of drafting the Local File, Master File, and CbCR. The taxpayer remains legally obligated to declare its related parties and transactions on Form 01 attached to the annual CIT finalization dossier.
- Non-Exempt Taxpayers (Full Dossier): Must file the required statutory appendices (Forms 01, 02, 03, and 04) and compile contemporaneous three-tier files prior to the CIT filing date, storing them locally for immediate tax authority audit requests.
3. The Three-Tier Documentation Structure Explained
Decree 132 aligns Vietnam’s compliance rules directly with the OECD BEPS Action 13 three-tiered documentation standard. This integrated structure provides tax authorities with a clear overview from local operations up to global value chains.
3.1 Local File vs. Master File Requirements
The Local File and Master File address different operational dimensions of an enterprise:
| Criterion | Local File (Hồ sơ quốc gia) | Master File (Hồ sơ tập đoàn toàn cầu) |
| Primary Scope | Entity-level activities within Vietnam. | Global operations of the multinational group (MNE). |
| Core Content | • Detailed Functional, Asset, and Risk (FAR) analysis.
• Local management structure and business strategy.
• Intercompany pricing agreements and material transaction values.
• Financial reconciliations and local economic benchmarking studies.
|
• Global organizational structure and geographical presence.
• Five primary drivers of group profitability.
• Intangible asset (IP) development and ownership strategies.
• Intercompany financial arrangements and treasury policies.
• Consolidated financial statements.
|
| Source of Preparation | Formulated directly by the Vietnamese subsidiary and local tax advisors. | Drafted by the global ultimate parent entity and localized for submission in Vietnam. |
3.2 Country-by-Country Reporting (CbCR)
Country-by-Country Reporting (Báo cáo lợi nhuận liên quốc gia) maps where value, employees, assets, and tax liabilities sit across worldwide tax jurisdictions.
- Reporting Threshold: Mandated for multinational groups with consolidated global revenue of at least VND 18,000 billion (approx. EUR 750 million) in the preceding tax period.
- Filing Obligations for Vietnamese Subsidiaries: If the Ultimate Parent Entity (UPE) is located in a foreign jurisdiction that has an effective Automatic Exchange of Information (AEOI) treaty with Vietnam, the local subsidiary only needs to file a formal notification letter. If no functional exchange agreement exists, or if the UPE fails to file, the Vietnamese entity must submit the CbCR copy directly to the local tax department.
4. Benchmarking Methodology: Establishing the Arm’s Length Range
A transfer pricing study relies on an Economic Analysis that proves all intercompany pricing reflects independent market outcomes (the Arm’s Length Principle).
4.1 Common Transfer Pricing Methods in Vietnam
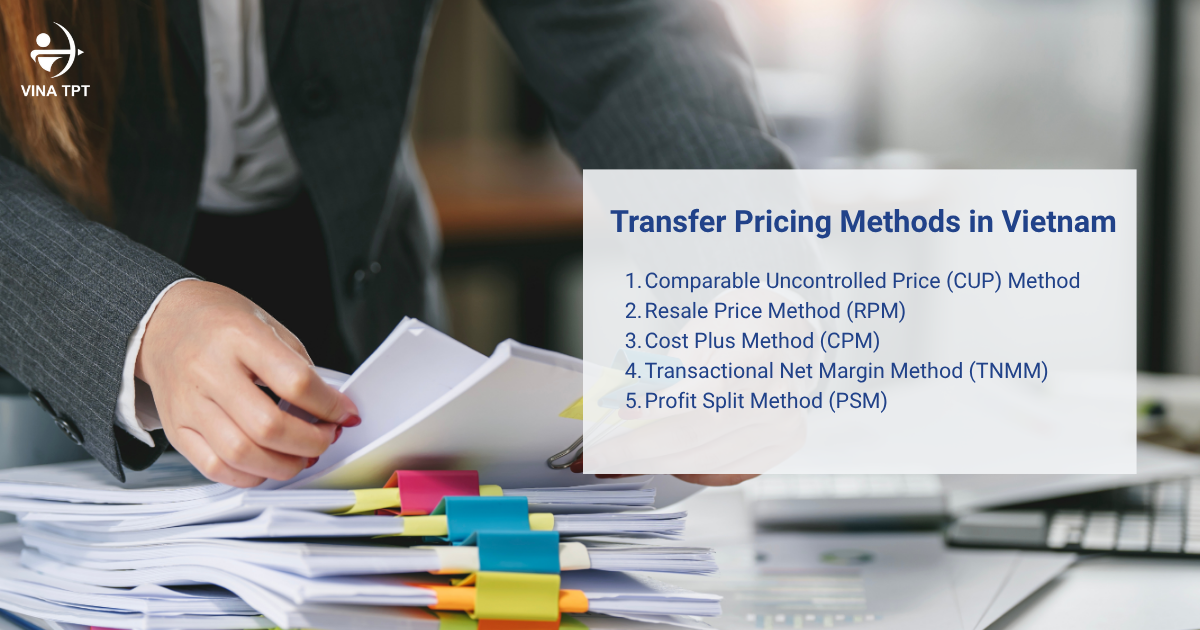
Decree 132 outlines five formal pricing methods:
- Comparable Uncontrolled Price (CUP) Method: Directly compares transaction prices to external or internal market prices; standard for commodities and plain vanilla financing.
- Resale Price Method (RPM): Evaluates gross margins earned in related purchases against resale to independent parties; best for routine distributors.
- Cost Plus Method (CPM): Adds an appropriate gross markup to direct and indirect production costs; ideal for contract manufacturers and routine service providers.
- Transactional Net Margin Method (TNMM): Examines operating profit relative to an appropriate base (costs, sales, or assets). TNMM is the most common method in Vietnam because local contract manufacturers and toll processors rarely possess reliable public gross-margin data or exact product-level comparables.
- Profit Split Method (PSM): Allocates combined operating profit from complex, integrated transactions where both parties contribute unique intangibles.
4.2 Database Screening & Interquartile Range
In accordance with Articles 17 and 18 of Decree 132/2020/ND-CP, the three-step screening and calculation process to determine the arm’s length range is conducted as follows:
- Quantitative Screening: Automatic filtering via commercial databases based on industry classification codes (SIC/NACE), comparable geographic markets, active operational status (at least 3 consecutive operating years), minimum revenue thresholds, availability of sufficient financial data, and verified independence (related-party ownership below 25%).
- Qualitative Screening: Manual review of annual reports, financial statements, company websites, and business descriptions to assess comparability in Functions, Assets, and Risks (FAR analysis). Companies engaged in diversified operations without segmented data or possessing unique, valuable intangibles are rejected.
- Calculation of the Arm’s Length Range: Profit Level Indicators (such as OP/OR, Berry Ratio, or OP/TC) of the accepted comparable companies are compiled, excluding entities with extreme or persistent losses. Under Decree 132, the standard arm’s length range is determined using the interquartile method, spanning from the 25th percentile ($Q_1$) to the 75th percentile ($Q_3$), with the median value serving as the primary benchmark.
5. Compliance Timelines, Penalties, and Audit Red Flags
Transfer pricing compliance requires strict adherence to statutory deadlines and proactive risk management to avoid audits.
5.1 Submission Deadlines and Inspection Timelines
- Statutory Filing Deadline: Transfer pricing disclosure forms (Forms 01 to 04) must be submitted along with the annual Corporate Income Tax finalization return no later than the last day of the 3rd month following the close of the calendar/financial year (typically March 31).
- Documentation Availability: Three-tier transfer pricing files must be completed and stored contemporaneously prior to the tax filing date.
- Inspection Response Window: Upon receiving a formal written demand from tax authorities:
- Taxpayers have 30 business days to deliver the complete transfer pricing documentation during standard audits.
- The timeline drops to 15 business days during pre-audit consultation proceedings.
- Language Requirement: Documentation must be provided in Vietnamese. Master files or transaction agreements drawn up in foreign languages must include verified Vietnamese translations when requested.
5.2 Audit Triggers and Consequences of Non-Compliance
Tax bureaus use data-driven algorithms to flag high-risk taxpayers. Common audit triggers include:
- Reporting consecutive multi-year operating losses while continuing to expand local production footprints or report surging revenues.
- Maintaining profit margins significantly lower than the benchmarked industry average in the same province.
- Making substantial royalty, software license, or management fee payments to offshore affiliates in low-tax jurisdictions.
- Unbalanced functional and asset profiles (e.g., operating as an asset-heavy toll manufacturer while absorbing all inventory risks).
6. Comprehensive Transfer Pricing Advisory Services by Vina TPT
Navigating Decree 132 requires local tax insight, economic modeling expertise, and defendable empirical benchmarks. Vina TPT provides specialized transfer pricing solutions that protect multinational enterprises from tax adjustments while ensuring operational compliance across Vietnam.
End-to-End Transfer Pricing Compliance Solutions by Vina TPT
- Diagnostic TP Risk Reviews (Health Check): Auditing existing related-party structures, intercompany contracts, and commercial terms to highlight adjustment exposures before authorities launch an audit.
- Three-Tier Dossier Preparation: Drafting compliant, localized Local Files, Master Files, and statutory disclosures (Forms 01 through 04) tailored to your operational realities in Vietnam.
- Defensible Economic Benchmarking: Accessing certified global financial databases to develop verifiable, robust peer groups that withstand rigorous scrutiny from local tax offices.
- Supply Chain Restructuring & APAs: Structuring intercompany transaction flows, intangibles licensing, and negotiating Advance Pricing Agreements (APAs) with the General Department of Taxation.
Audit Defense Support & Consultation Process
When tax authorities challenge your documentation, having the right team beside you makes all the difference. Vina TPT works alongside your internal finance teams during transfer pricing audits by:
- Reconciling technical differences directly with tax audit teams.
- Defending functional characterizations and screening criteria.
- Preventing arbitrary adjustments to the median range.
Mitigating tax exposure through early transfer pricing compliance is vastly superior to managing retrospective tax adjustments. Partner with Vina TPT today to evaluate your risk profile and secure a customized compliance roadmap for your enterprise.