In practice, mistakes involving invoices issued with the wrong date are a constant, quiet source of anxiety for accountants and business owners alike. A single oversight regarding the date can lead to unnecessary legal risks, particularly as regulations governing electronic invoices become increasingly stringent. Are you struggling to figure out whether an invoice with an incorrect date can be adjusted? Will your enterprise face administrative penalties or be denied input VAT deductions?
Rest assured, the answer is YES, it can certainly be adjusted. However, enterprises must strictly comply with official invoice adjustment guidelines.
Specifically, under Decree No. 123/2020/ND-CP (along with amendments and supplements in Decree No. 70/2025/ND-CP applicable from June 2025), the resolution process has shifted toward issuing either an adjustment invoice or a replacement invoice.
Important Note: Canceling an invoice to reissue it from scratch is virtually no longer accepted for incorrect date errors, except in a few special technical scenarios. Executing a written agreement between both parties remains a mandatory legal step to protect your enterprise during tax audits.
This article synthesizes detailed instructions, step-by-step procedures, updated penalty rates, tax deduction guidelines, and key compliance notes to help you handle errors correctly, avoid fines, and ensure valid documentation according to the latest 2026 regulations.
1. What Is an Invoice Issued with the Wrong Date? Common Errors & Consequences
An invoice issued with the wrong date (issued at an improper time) occurs when an invoice is generated outside the timeframes specified under Article 9 of Decree No. 123/2020/ND-CP (as amended by Decree No. 70/2025/ND-CP). The proper time to issue an invoice is generally upon delivery of goods, completion of service provision, or final sign-off and handover.
Common Error Scenarios:
- Generating an invoice prior to the actual date of goods delivery or service handover.
- Generating an invoice many days or months after the delivery date (backdating or delayed issuance).
- Recording an incorrect day, month, or year on the invoice compared to actual transaction facts.
- Mismatched VAT tax declaration periods caused by improper timing.
Severe Consequences of Improper Handling:
- Administrative tax fines concerning invoices (ranging from formal warnings to tens of millions of VND).
- Disallowance of input VAT deductions (for the buyer) or rejection of legitimate business expenses (for the seller).
- Elevated exposure to tax inspection and audit risks.
- Adverse impacts on financial statements and corporate reputation.
Understanding these errors allows you to resolve issues proactively, swiftly, and in full compliance with the law.
2. Can an Invoice Issued with the Wrong Date Be Adjusted?
An invoice issued with the wrong date can be adjusted. Starting June 1, 2025, pursuant to Clause 13, Article 1 of Decree No. 70/2025/ND-CP amending Article 19 of Decree No. 123/2020/ND-CP, any errors on electronic invoices (including incorrect dates) cannot be canceled; instead, they must be addressed via an adjustment invoice or a replacement invoice.
Case 1: The Invoice Has Not Been Delivered to the Buyer
This is the easiest scenario to resolve because the invoice has not yet impacted the buyer, nor has it completed final data submission cycles.
Resolution Steps:
- The seller issues a replacement invoice for the erroneous invoice (replacement is preferred since the timing is completely wrong).
- The replacement invoice must feature the mandatory text: “Replacing invoice Form No…., Symbol…., No…., dated [Day]/[Month]/[Year]…”
- A written agreement is not required if the invoice has not been sent to the buyer.
- Once the replacement in voice is generated, the system automatically invalidates the original invoice within the tax authority database (under updated mechanisms).
Important Notes:
- Take action immediately upon detecting the error to avoid disrupting VAT declaration cycles.
- If the invoice was already granted a tax authority code but not yet delivered, follow the same replacement procedure.
- Benefit: Involves no additional procedures with the buyer, minimizing dispute risks.
Case 2: The Invoice Has Been Delivered to the Buyer but Not Yet Declared for Tax
This situation commonly arises when an error is caught within the same reporting period.
Resolution Steps:
- Both parties (seller and buyer) execute a written agreement explicitly stating the error (wrong date), the adjustment content, and the original invoice information.
- The seller issues an adjustment invoice (most suitable when only the date is incorrect while all other details remain accurate) or a replacement invoice.
- Mandatory text required on the adjustment invoice: “Adjusting invoice Form No…., Symbol…., No…., dated [Day]/[Month]/[Year]…”
- Declare the adjustment or replacement invoice in the same reporting period as the original invoice to avoid supplementary returns.
- Send the written agreement along with the new invoice to the buyer and transmit data to the tax authority.
This method preserves document continuity, allowing the buyer to claim input VAT deductions normally without affecting tax reports.
Note: Executing a written agreement is mandatory when the buyer is a business enterprise, an organization, or a business household starting from June 1, 2025.
Case 3: The Invoice Has Been Delivered to the Buyer and Already Declared for Tax
This is the most complex scenario because it affects the tax declaration obligations of both parties.
Resolution Steps:
- Execute a written agreement between both parties detailing the mistake and corrective adjustments.
- Issue an adjustment invoice (preferred) or a replacement invoice featuring clear notation as outlined above.
- File supplementary VAT returns for the period in which the original invoice arose (if the incorrect date caused the invoice to fall into a different tax period) pursuant to supplementary declaration rules.
- Both the seller and the buyer must adjust their respective VAT returns.
Risks of Inaction: The seller faces administrative fines for improper invoice timing. The buyer risks having input VAT deductions disallowed if tax inspectors determine the documentation is invalid.
3. Step-by-Step Procedure for Handling Invoices Issued with the Wrong Date (E-Invoices)
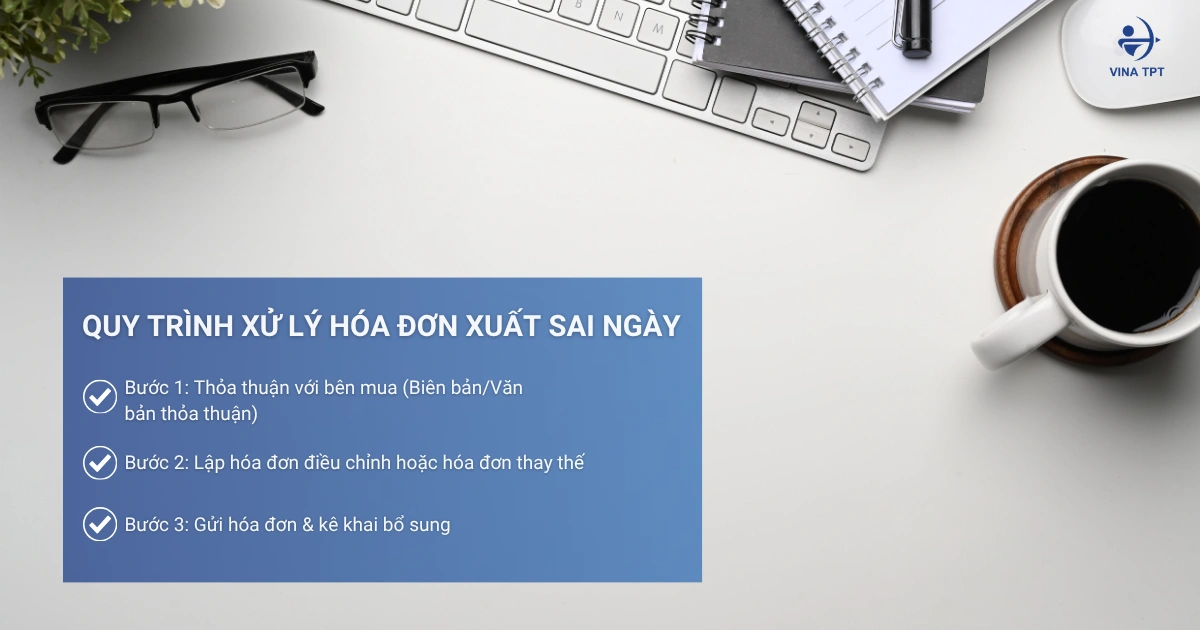
Step 1: Agreement with the Buyer (Written Agreement / Minutes)
Prior to issuing a new invoice, the seller and buyer must draft a written agreement acknowledging the error (incorrect content and correction details). The document must state:
- Original invoice information (Form number, Symbol, Invoice number, Date of issuance).
- Nature of the error (incorrect date).
- Adjustment content.
- Digital signatures of both parties (if enterprises).
Step 2: Issue an adjustment invoice or replacement invoice
- Adjustment invoice (most suitable when only the date is incorrect and values remain unchanged): Must state the mandatory text: “Adjustment for invoice form number… symbol… number… dated… month… year…”.
- Replacement invoice: Used when errors are numerous or the entire invoice needs replacement. Must state: “Replacement for invoice form number… symbol… number… dated… month… year…”.
Step 3: Send the invoice & file supplementary tax declaration
- Digitally sign and deliver to the buyer.
- File a supplementary VAT tax declaration (if in a different period).
4. Are incorrectly timed invoices penalized? Latest penalty rates
According to Article 24 of Decree 125/2020/ND-CP (as amended by Decree 310/2025/ND-CP effective January 16, 2026):
- Warning penalty (if minor, with mitigating circumstances).
- Monetary fine from VND 500,000 to VND 70 million depending on the number of invoices and the degree of impact on tax obligations (penalties increase progressively based on the number of violations).
Note: Penalties for organizations are double those for individuals. Mitigating circumstances apply if voluntarily remedied.
See also: Full-service accounting services
5. Can an incorrectly dated invoice be eligible for VAT deduction and expense accounting?
This is the primary concern for buyers: “Is this expense considered valid and eligible for VAT deduction?” In principle, an incorrectly timed invoice (an invoice issued after the transaction period) can still be accepted, provided it satisfies the following “three-legged stool”:
Authenticity of the transaction: This is a prerequisite. You must prove that goods/services were delivered and utilized for business operations prior to the invoice date.
Complete supporting dossier: Besides the incorrectly dated invoice, the documentation set must display temporal logic among records:
- Economic contract (clearly specifying payment and handover terms).
- Delivery note (seller) and Goods receipt note (buyer).
- Handover record / Service acceptance record (matching the actual timing).
- Non-cash payment vouchers via bank transfer (for invoices of VND 5 million or higher).
- Seller compliance status: The seller must fully declare output tax and pay taxes for that invoice. If the seller absconds or fails to declare, the buyer faces a very high risk of VAT deduction disallowance.
Tax authorities generally evaluate substance over form. If the date error is merely an administrative oversight and the supporting documentation is complete, the buyer’s tax benefits will usually be protected.
6. Comparison between adjustment invoices and replacement invoices
| Criteria | Adjustment Invoice | Replacement Invoice |
| When to use | Partial error (only date, tax rate, or amount is wrong) | Entirely incorrect or multiple errors |
| Mandatory text | “Adjustment for invoice…” | “Replacement for invoice…” |
| Impact on tax declaration | Increase/decrease adjustment. Declared in the period the adjustment arises. | Replacement declaration filed in the original period or discovery period (depending on the situation). |
| Advantages | Preserves invoice numbering sequence, simpler | Thoroughly resolves errors |
| Disadvantages | Complex if there are multiple errors | May affect invoice sequence numbering |
An adjustment invoice can be issued multiple times for the same original invoice, whereas a replacement invoice can only be issued once for an erroneous invoice.
Conclusion
Therefore, the question “Can e-invoices issued with incorrect dates be adjusted?” has been answered along with step-by-step instructions following Decree 70/2025/ND-CP. Timely resolution not only helps avoid penalties but also protects tax deduction rights for both parties.
Advice: Establish a strict invoice issuance process and utilize reputable e-invoicing software equipped with effective error-correction features. When encountering complex situations, contact your managing tax office or tax experts at Vina TPT immediately for precise support.
Schedule a consultation with an expert