[Newsletter] September 2026 Tax Update: VAT Refund, PIT withholding, CIT & Invoice issuance 

Vietnam tax update september 2026

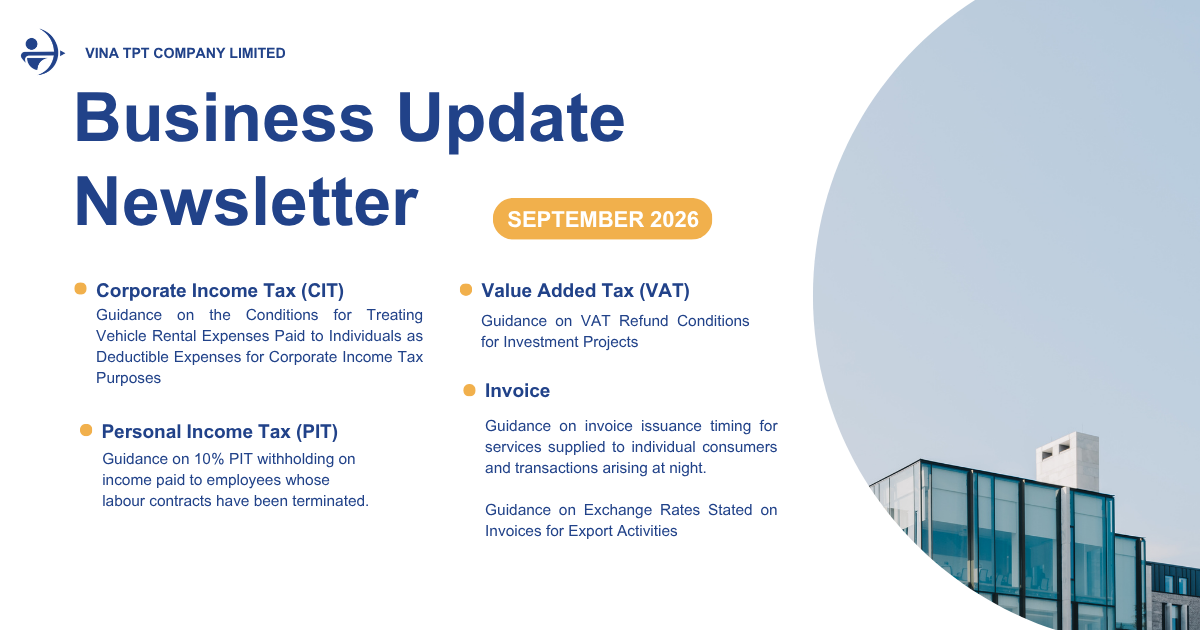
This September 2026 Vietnam tax update summarises recent guidance on VAT refunds for investment projects, deductible vehicle rental expenses, PIT withholding after employment termination, invoice issuance timing and exchange rates on export invoices. Each section highlights the relevant conditions and practical considerations to help businesses review their tax procedures and supporting documents. 

1. INVOICE

Guidance on invoice issuance timing for services supplied to individual consumers and transactions arising at night. 

Pursuant to Official Letter No. 6325/CT-QLNT dated August 26, 2026 of the Tax Department, guiding Article 9 of Decree No. 254/2026/NĐ-CP (effective July 1, 2026). 

Services supplied to individual consumers

For enterprises providing services to individual consumers, including banking; payment intermediary services; credit information services; securities business; crypto-asset transactions; support services for transactions on carbon exchanges; insurance business; money transfers via e-wallets; suspension and resumption of electricity supply; e-commerce; postal and transportation services supporting e-commerce; public passenger transport by metro and bus; passenger transport by taxi, contract vehicle, and two-wheeled motorcycle; parking services; cinema services; and other services, where such enterprises satisfy the conditions of having a software system capable of managing each transaction in detail and maintaining payment collection data in the system on a transaction-by-transaction basis: 

–  The seller shall prepare a Summary of E-Invoice Data for Sales of Goods and Provision of Services and a Detailed Statement of Transactions Arising During the Month or Quarter (covering the period from the first day to the last day of the relevant month or quarter), using the forms prescribed by the Minister of Finance, and submit them to the tax authority no later than the statutory deadline for submission of the Value Added Tax (“VAT”) return in accordance with the laws on tax administration. 

– Where a large volume of invoices is generated, the Summary of E-Invoice Data and the Detailed Statement of Transactions shall be divided into separate data files in accordance with the standard data format prescribed by the tax authority to ensure compliance with the technical requirements for data transmission and receipt. 

The seller is responsible for the accuracy of transaction information, must retain full detailed data for each transaction, and must ensure the data can be retrieved, reconciled and provided, together with related documents, on request of the tax authority or competent state agency. 

Transactions arising during night working hours

Where the seller has no automatic invoicing software and sells goods or supplies services during night working hours as defined by the Labor Code, the invoice must be issued no later than the next working day.ogether with the Appendix on VAT Refund Claim Information (Form No. 01-8/GTGT) as the basis for the tax authority to review and process the refund request. 

Guidance on Exchange Rates Stated on Invoices for Export Activities 

Pursuant to Official Letter No. 6810/CT-QLNT dated 14 September 2026 

In cases where economic or financial transactions are denominated in foreign currencies in accordance with foreign exchange regulations, the seller shall indicate on the invoice the exchange rate between the foreign currency and the Vietnamese Dong as prescribed in Point c.1, Clause 8 of the Appendix attached to Decree No. 254/2026/NĐ-CP. 

Pursuant to Clauses 1 and 5, Article 26 of the Law on Tax Administration No. 108/2025/QH15 and the accounting regulations, the exchange rate shown on the invoice shall be the actual transaction exchange rate determined in accordance with accounting laws and regulations.

2. PERSONAL INCOME TAX 

Guidance on 10% PIT withholding on income paid to employees whose labour contracts have been terminated. 

Pursuant to Official Letter No. 10049/NBI-QLDN1 dated August 3, 2026 of the Ninh Binh Provincial Tax Office, guiding Clauses 1 and 3, Article 26 and Clause 2, Article 50 of Decree No. 253/2026/NĐ-CP dated June 30, 2026 

– Where an employee is a resident individual whose labor contract was terminated on 30 June 2026, and the Company pays the employee’s salary for June 2026 on 10 July 2026, such payment shall be treated as a salary payment made to an individual whose labor contract has already been terminated. If the payment to each individual on each occasion is VND 5 million or more, the Company shall withhold personal income tax (“PIT”) at the rate of 10% before making the payment. If the payment is less than VND 5 million per payment, the Company shall withhold PIT at the rate of 10% only at the individual’s request. 

– The Company shall withhold PIT at the rate of 10% on taxable income from salaries and wages before making payment to the individual. Tax-exempt income prescribed by law, including remuneration for night work and overtime work, and salaries and wages paid for unused annual leave within the conditions, duration and limits prescribed by labor laws, shall not be included in the income subject to withholding. Any amount exceeding the statutory limits shall be included in taxable income. 

Compulsory insurance contributions, personal and dependent deductions, and other allowable deductions are taken into account in determining taxable income when applying the partially progressive tax tariff or upon annual PIT finalization, and shall not be deducted when applying the provisional 10% withholding rate prescribed in Clause 2, Article 50 of Decree No. 253/2026/ND-CP. 

3. VALUE ADDED TAX

Guidance on VAT Refund Conditions for Investment Projects 

Pursuant to Official Letter No. 7019/CT-QLNT dated 22 September 2026 issued by the Tax Department: 

Where, at the time of submitting the VAT refund application, a business establishment falls within the scope of cases eligible for a VAT refund in respect of an investment project, has input VAT that fully satisfies the conditions for VAT credit and refund in accordance with the VAT regulations, and has submitted a VAT refund application dossier in compliance with the tax administration regulations, the business establishment shall be considered for a VAT refund in respect of the investment project. 

Pursuant to Clause 4, Article 3 of Law on Investment No. 61/2020/QH14, Clause 2, Article 15 of Law on Value Added Tax No. 48/2024/QH15, and Article 30 of Decree No. 181/2025/ND-CP, there is no provision stipulating that the date of issuance of the Investment Registration Certificate (“IRC”) shall serve as the basis for determining the input VAT attributable to an investment project 

Where the Company has VAT invoices for purchased goods and services arising prior to the issuance of the IRC, if the Company is able to provide sufficient supporting documents and evidence demonstrating that such goods and services were actually purchased for the preparation and implementation of the investment project in accordance with the laws on investment, and the related input VAT satisfies the conditions for VAT credit and refund under the VAT regulations, such input VAT may be considered for credit and refund in respect of the investment project in accordance with the applicable regulations. 

4. CORPORATE INCOME TAX

Guidance on the Conditions for Treating Vehicle Rental Expenses Paid to Individuals as Deductible Expenses for Corporate Income Tax Purposes 

Pursuant to Official Letter No. 15944/DON-QLDN3 dated 18 August 2026 issued by the Dong Nai Tax Authority: 

  • Where an enterprise rents assets from an individual, the supporting documents required to substantiate the deductible expense include the asset lease agreement and documents evidencing payment of the rental fee. 
  • Where an enterprise rents assets from an individual and the lease agreement stipulates that the rental fee is exclusive of taxes (including value added tax and personal income tax), and the enterprise is required to declare and pay such taxes on behalf of the individual in accordance with the laws on tax administration, the taxes paid on behalf of the individual may also be treated as deductible expenses for corporate income tax purposes, provided that valid tax payment documents are available. 

5. Review Your Business’s Tax Compliance 

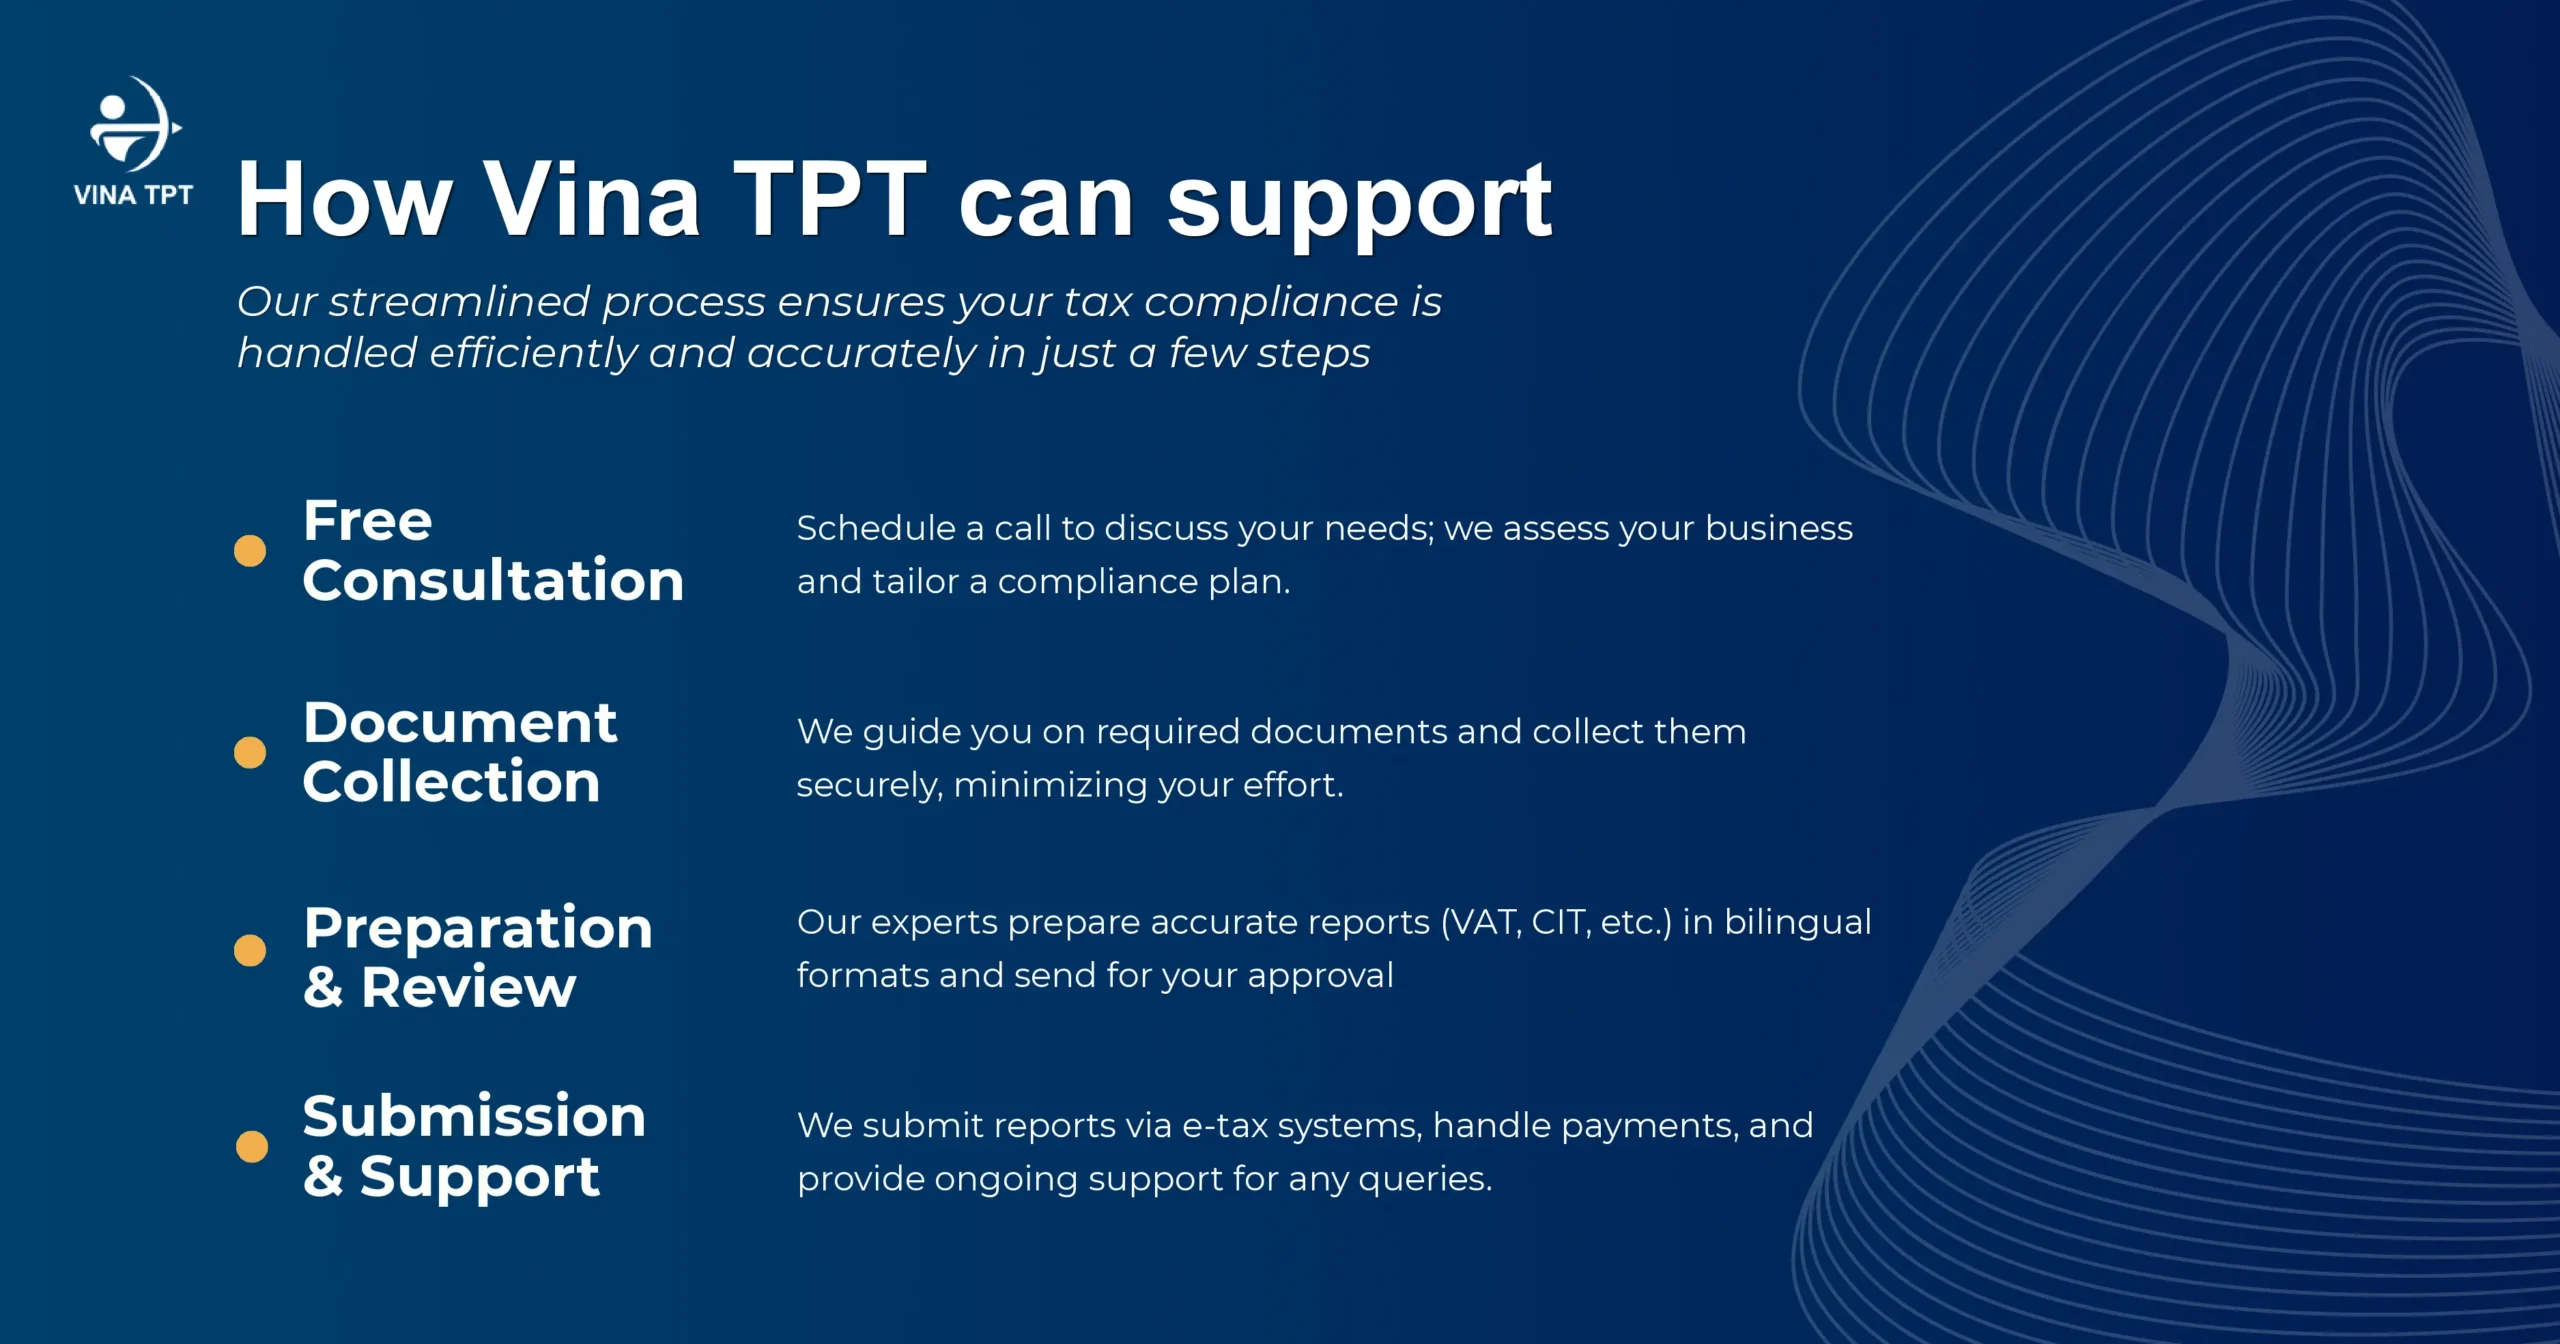
Vina TPT provides integrated accounting, tax, HR and payroll, legal and business advisory services for domestic and foreign-invested enterprises in Vietnam. From company establishment and post-licensing procedures to bookkeeping, financial reporting and ongoing compliance, we help businesses manage their obligations at each stage of their operations. 

Our tax services include tax filing and annual finalization, VAT refund assistance, tax health checks, transfer pricing and global minimum tax compliance. We also review supporting records, identify potential compliance gaps, and assist with documentation and explanations requested by tax authorities during tax reviews and inspections. 

If these updates affect your business, our team can help assess the implications, review your current procedures and recommend practical actions suited to your operations. 

Contact Vina TPT to Review Your Tax Compliance 
BOOK A FREE CONSULTATION

what-is-included-in-business-accounting-services-in-vietnam

Vietnam Tax Compliance for FDI Business: Key Taxes & CPA Support

Vietnam-Tax-Compliance-for-FDI-Key-Taxes-CPA-Services-scaled.webp

Vietnam Tax Compliance for FDI Key Taxes & CPA Services

For foreign investors entering the Vietnamese market, tax compliance is not simply an obligation to pay taxes to the state budget, but a critical factor that directly impacts the financial safety and long-term sustainability of the investment project. Language barriers, the complexity of the local legal system, and the frequent updates to sub-law documents often turn tax management into the biggest “bottleneck” for FDI company management.

Even a small mistake in identifying invalid invoices, incorrectly posting non-deductible expenses, or late declaration of contractor taxes can result in heavy administrative fines, additional tax assessments with 0.03% daily late payment interest, or prolonged tax inspections that disrupt the entire supply chain.

This article provides a comprehensive overview of tax compliance Vietnam FDI, an in-depth analysis of the four core taxes (VAT, CIT, PIT, FCT) with the latest legal obligations, and reveals Vina TPT’s specialized Vietnam tax obligations for foreign companies solutions to help investors take full control of their financial game in Vietnam.

Vietnam Tax Compliance for FDI Key Taxes & CPA Services

1. Value-Added Tax (VAT) – The Most Important Tax Obligation for all Businesses

Value-Added Tax (VAT) is an indirect tax with the highest transaction frequency and the strictest supervision from local tax authorities. It is a mandatory obligation applicable to all business sectors of FDI companies in Vietnam, including trading, manufacturing, services, import-export, and other fields.

1.1. Legal Basis & Declaration Cycle

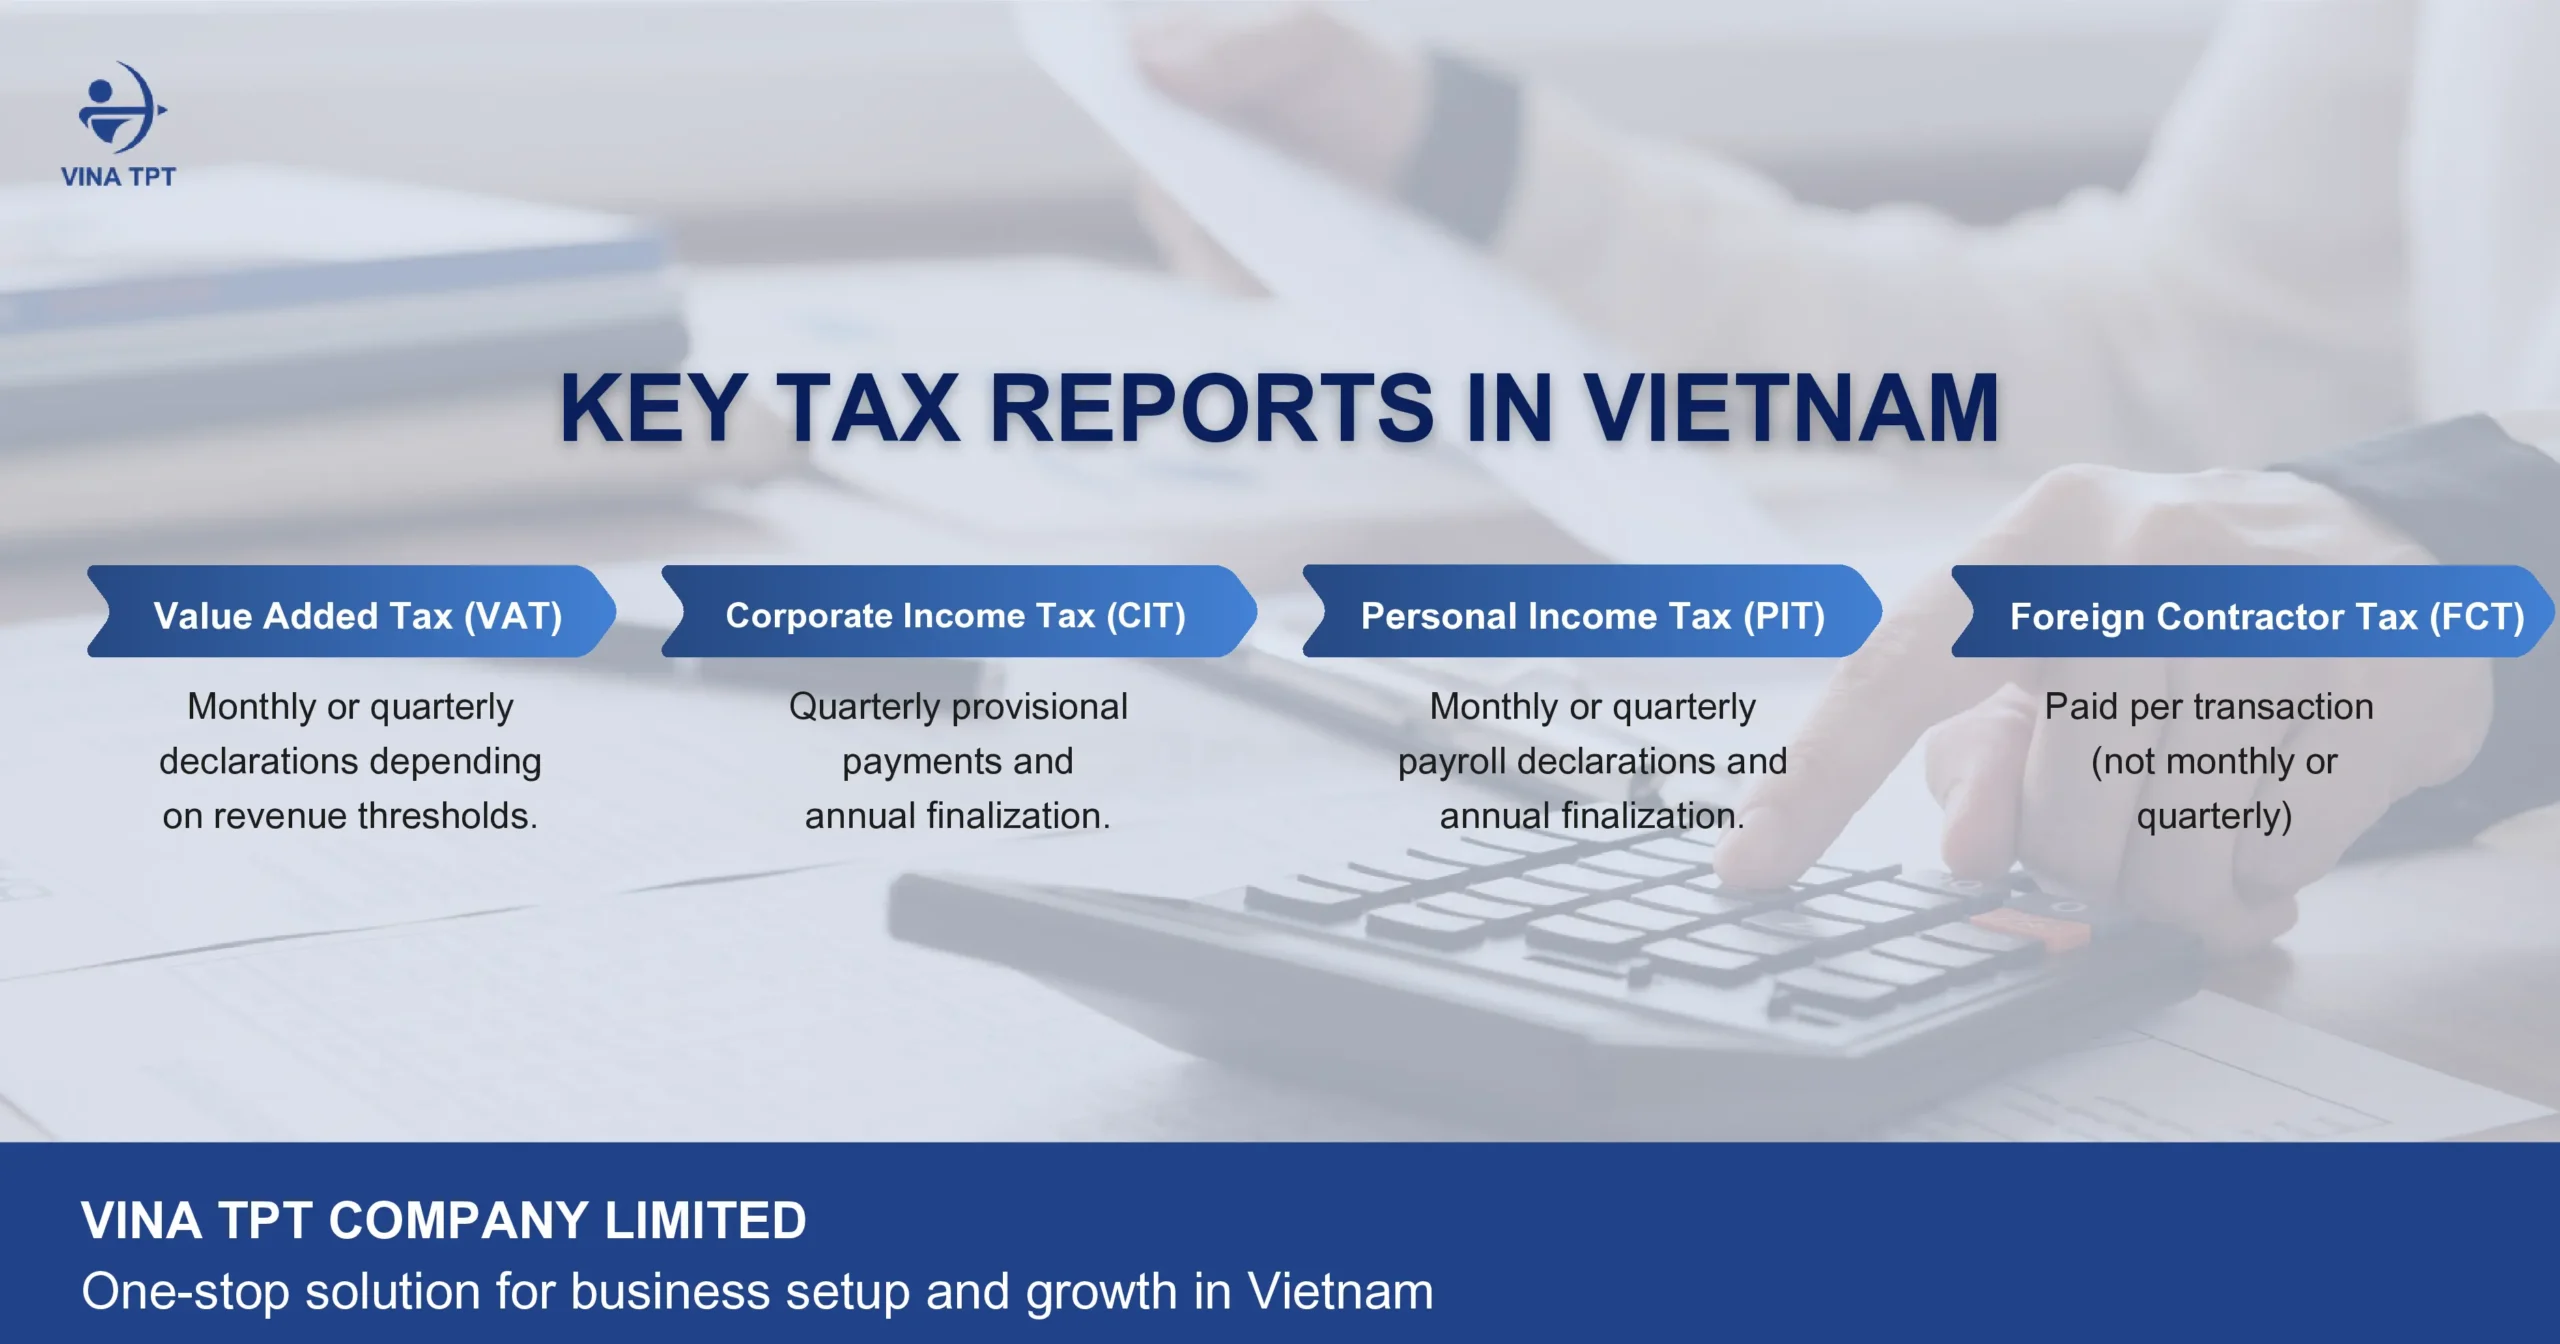
According to the Law on Value-Added Tax 2008 (as amended and supplemented) and the latest guidance in Decree 181/2025/ND-CP, newly established FDI enterprises or those with annual revenue of VND 50 billion or less in the previous year must declare VAT on a quarterly basis. Enterprises with previous year revenue exceeding VND 50 billion are required to declare VAT on a monthly basis.

1.2. Strict Conditions for Input VAT Deduction

To be eligible for input VAT deduction, the accounting department of an FDI company must simultaneously meet the following conditions:

  • Have a valid VAT invoice (issued with a tax authority code under Decree 123/2020/ND-CP).
  • Have non-cash payment documents (bank transfer from the buyer’s account to the seller’s account) for invoices valued at VND 5 million or more (including VAT).
  • The purchased goods or services must be directly used for the production or business of goods and services subject to VAT.

2. Corporate Income Tax (CIT) – Profit-Based Tax & the Provisional Payment Calculation

Corporate Income Tax (CIT) directly affects the net profit of foreign investors. Understanding the provisional payment rules and tax incentive mechanisms is the key to optimizing capital efficiency.

2.1. Standard Tax Rate & Quarterly Provisional Payment Rule (80% Rule)

The standard Corporate Income Tax (CIT) rate in Vietnam is currently 20% on taxable income. However, according to the new regulations in 2025, certain enterprises that meet the preferential conditions may enjoy lower tax rates:

  • 15%: Applied to enterprises with annual total revenue not exceeding VND 3 billion.
  • 17%: Applied to enterprises with annual total revenue from over VND 3 billion up to VND 50 billion.

Special Note on the 80% Rule:

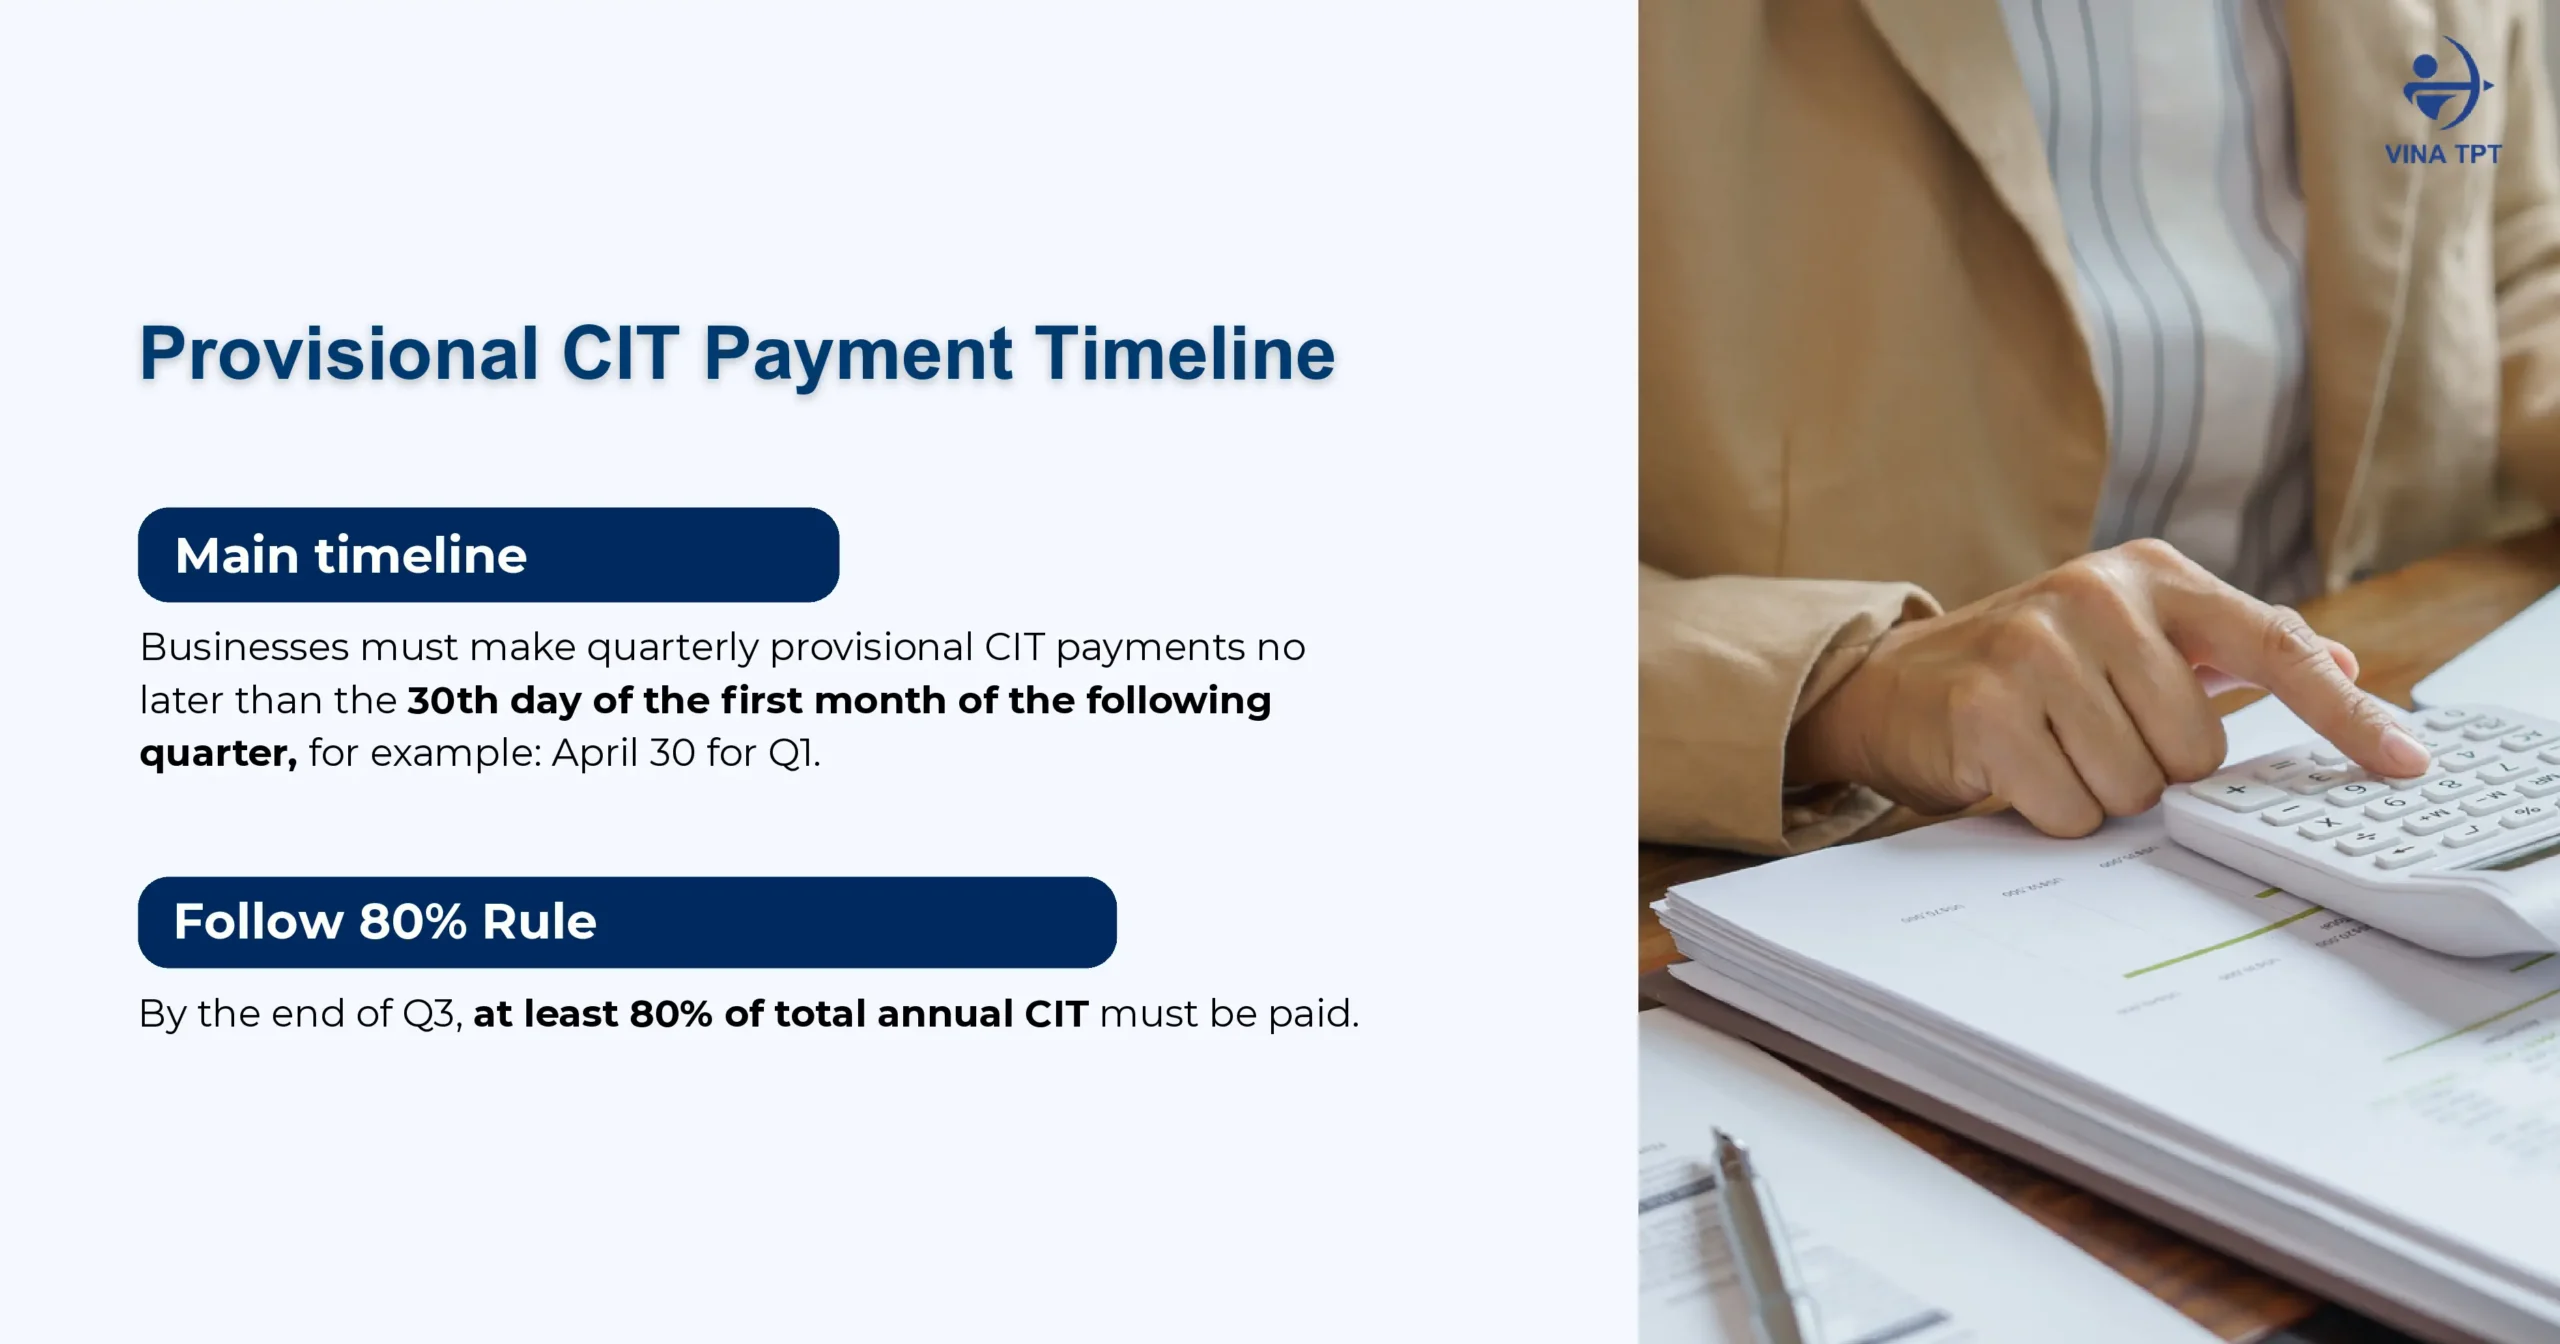
Special Note on the 80% Rule: According to current regulations, the total CIT amount provisionally paid for the four quarters of the tax year must not be less than 80% of the final CIT amount payable upon annual finalization. If the payment falls short of this 80% threshold, the company will be charged late payment interest (0.03% per day) on the shortfall, starting from the day after the deadline for the fourth-quarter tax payment.

2.2. Tax Incentive Mechanism (Tax Incentives) under the Law on Investment 2020

FDI companies can take advantage of attractive tax incentive packages if they meet the conditions regarding location or investment priority sectors according to Decree 31/2021/ND-CP:

Type of Incentive

Incentive Level

Conditions & Applicable Sectors

Preferential tax rate of 10% For 15 years (extendable to 30 years) High-tech projects, high-tech applications, R&D, renewable energy.
100% Exemption & 50% Reduction Exemption for 4 years, 50% reduction for the next 9 years Newly established projects in industrial parks, economic zones, or areas with particularly difficult socio-economic conditions.
Preferential tax rate of 15%–17% Applied throughout the project duration Enterprises meeting capital scale or large labor usage criteria as prescribed.

Key updates in 2025:

  • Enterprises are allowed to expand deductible expenses related to scientific research, digital transformation, new technology testing, emission reduction, and community activities.
  • If eligible for multiple incentive groups, the enterprise has the right to choose the most favorable incentive level.
  • Losses can be carried forward continuously for a maximum of 5 years, and up to 20% of taxable income may be set aside to establish a Science & Technology Development Fund (if used for the correct purposes).

Real-life example: A Korean technology corporation established a software factory in Ho Chi Minh City High-Tech Park. By correctly applying for CIT incentives, the company enjoys a 10% tax rate for 15 years, 100% CIT exemption for the first 4 years (from the year it has taxable income), and a 50% reduction for the next 9 years – saving millions of USD in taxes.

>>> For a more detailed and complete update on all Corporate Income Tax incentive policies in 2025, read the article: Tax Incentive in Vietnam 2025: Comprehensive Guide to Optimize Profits under New CIT Law

Vietnam Tax Compliance for FDI Key Taxes & CPA Services

Get Expert Advice on Tax Incentive Policies

3. Personal Income Tax (PIT) and Social Insurance Responsibilities for Personnel

Compliance with Personal Income Tax (PIT) and Social Insurance (BHXH) for the workforce – especially for foreign experts and managers (Expats) – always carries significant risks of additional tax assessments if residency status is not correctly classified.

3.1. PIT Withholding & Residency Classification Rules

FDI companies are obligated to withhold, declare, and pay Personal Income Tax (PIT) on a monthly or quarterly basis before paying income to employees:

  • Resident Individuals: Present in Vietnam for 183 days or more in a calendar year (or 12 consecutive months). Progressive tax rates from 5% to 35% apply on worldwide income (Global Income).
  • Non-Resident Individuals: A non-resident individual is a person who does not meet the conditions of a resident individual, specifically someone who is present in Vietnam for fewer than 183 days in the tax year and does not have a permanent residence in Vietnam.

3.2. Mandatory Social Insurance (BHXH) Responsibilities

According to the Law on Social Insurance and related regulations, FDI companies must contribute the following for employees:

  • Vietnamese Employees: Contributions to Social Insurance, Health Insurance, and Unemployment Insurance at a total rate of 32% (Employer: 21.5%, Employee: 10.5%).
  • Foreign Employees (Expats): Mandatory participation in Social Insurance and Health Insurance if they hold a Work Permit and have an employment contract that is indefinite or has a term of 1 year or longer.

>>> For more details: 

4. Foreign Contractor Tax (FCT) and Related Legal Obligations

Foreign Contractor Tax (FCT) is a special tax that many newly operating FDI companies often overlook, leading to declaration violations and penalties.

4.1. Nature & Mechanism of FCT Collection

FCT applies to foreign organizations and individuals who do not operate under Vietnamese law but generate income from providing services or goods associated with services in Vietnam (such as software royalties, parent company management consulting fees, cross-border digital marketing services, etc.).

FCT consists of two main components: VAT and Corporate Income Tax (or Personal Income Tax). The FDI company in Vietnam is responsible for withholding, declaring, and paying FCT on behalf of the foreign contractor before remitting payment.

Example: An FDI company pays USD 100,000 in software royalty fees to its parent company in Singapore. The company must determine the applicable FCT rate (typically 5% CIT on royalties), register a contractor tax code, and declare and pay FCT within 10 days from the payment date.

4.2. 2. Other Mandatory Fees & Periodic Reporting Obligations

In addition to the four main taxes, Vietnam tax obligations for foreign companies also include the Investment Activity Report (IAR): Periodic declaration and reporting of project implementation status on the National Investment Information System.

5. Benefits of Using Vina TPT’s Tax Compliance Services

When choosing to partner with Vina TPT, FDI companies are not simply using an external tax filing service – they are proactively equipping themselves with a solid “financial shield” for the entire operational process in Vietnam.

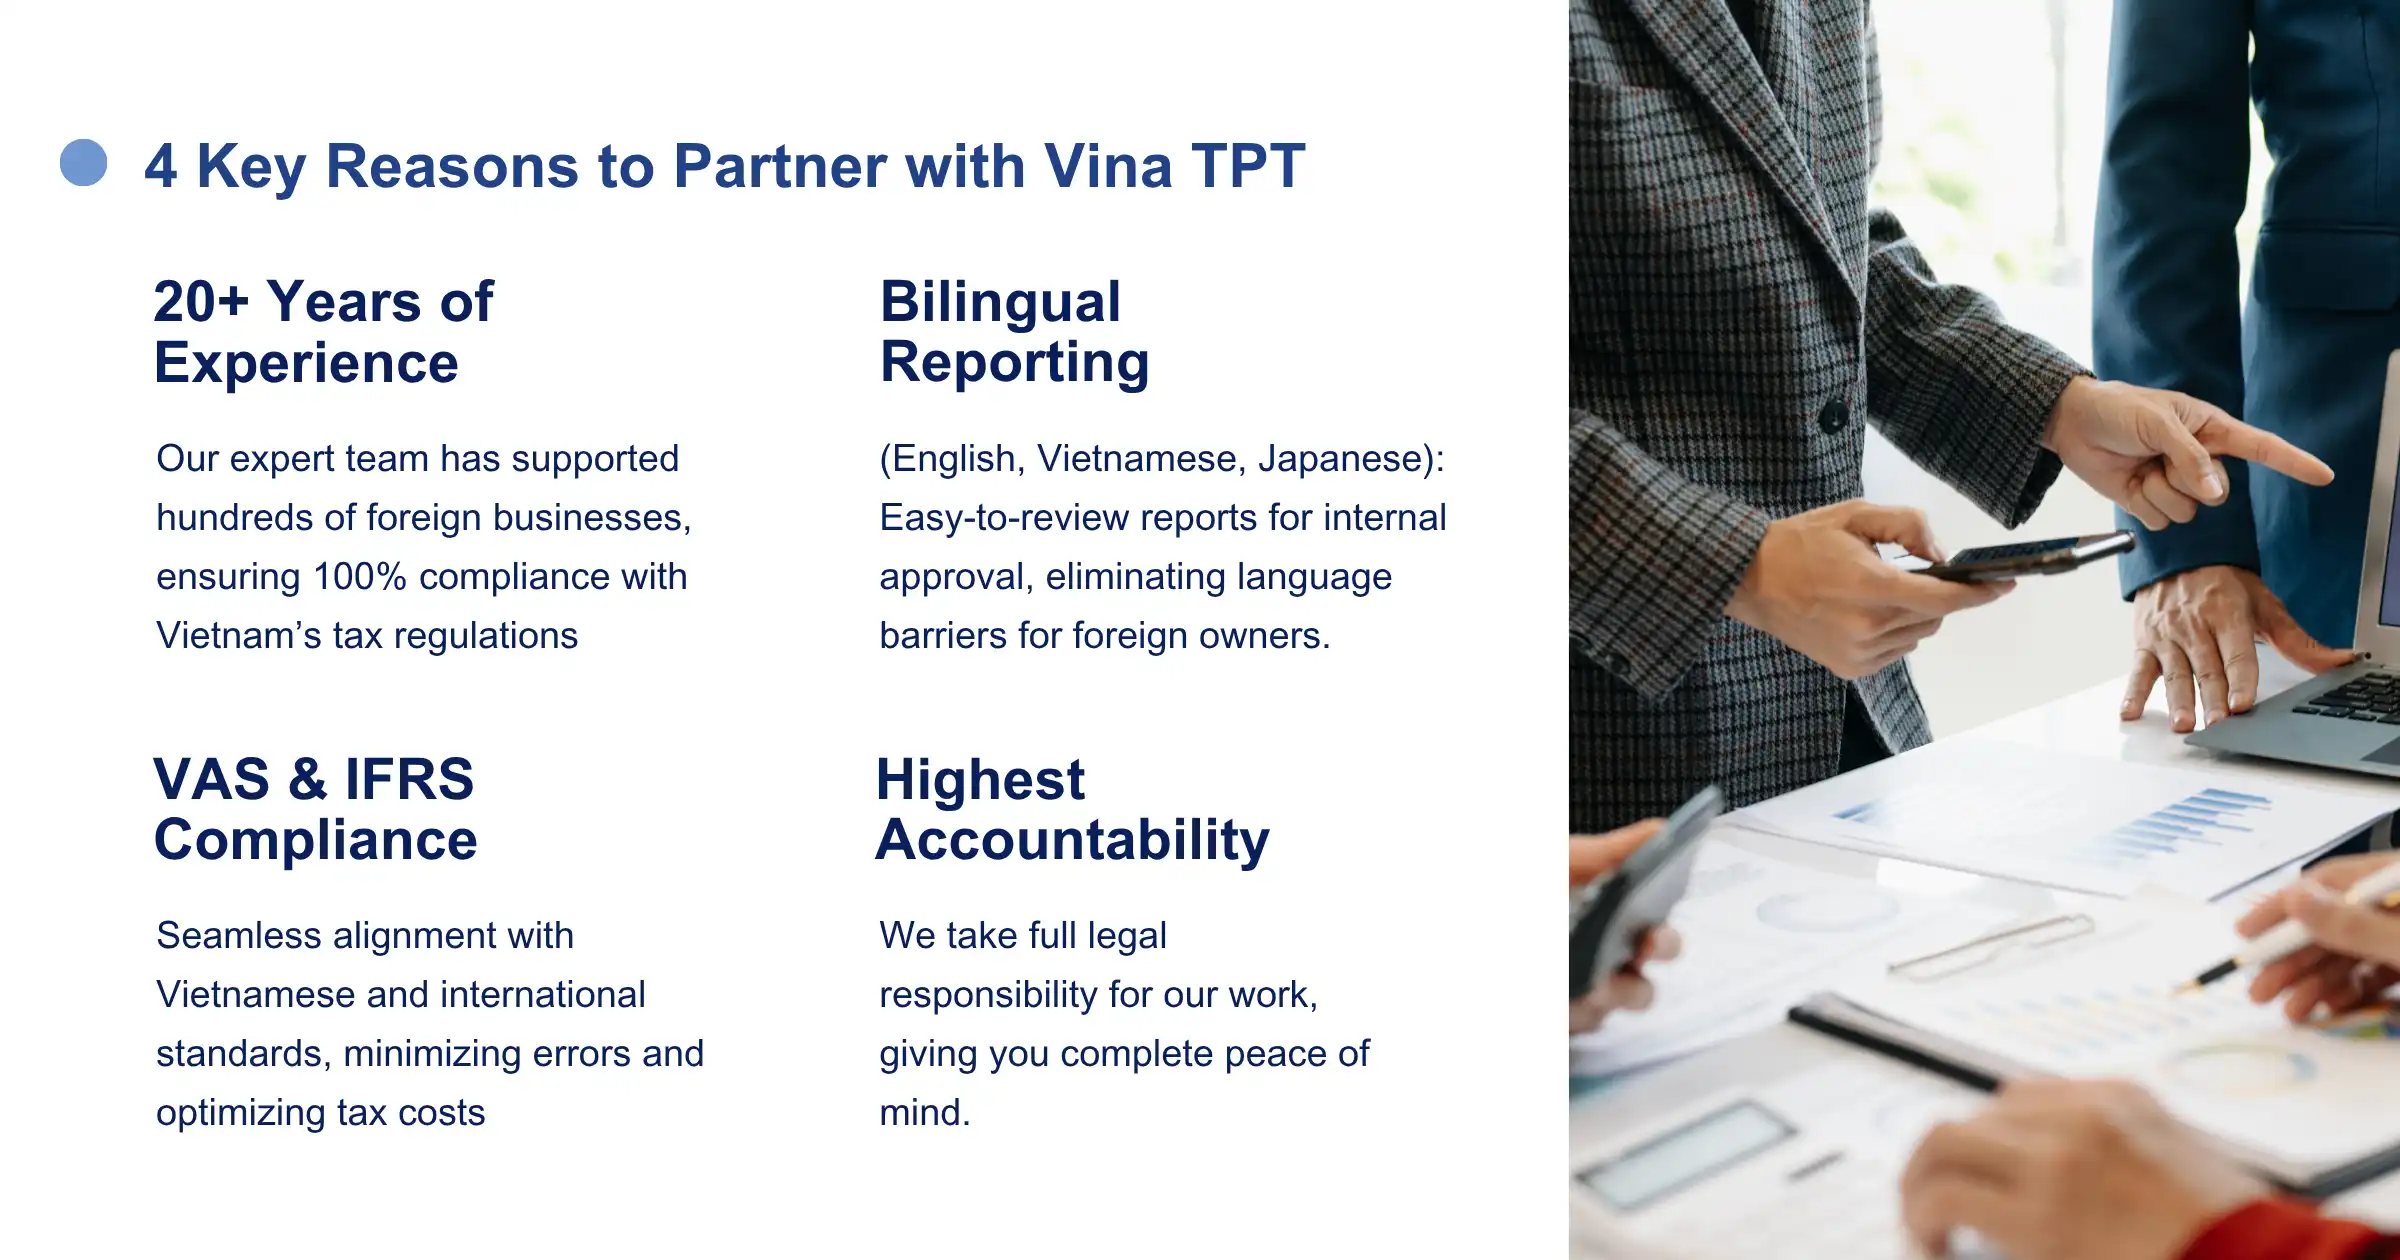
Instead of maintaining a bulky in-house accounting and tax team with high costs while still facing risks of staff turnover or lack of legal update capabilities, partnering with Vina TPT helps businesses optimize operating costs by up to 40%. More importantly, thanks to a 3-level independent quality control model operated by experienced CPA and Chief Accountant experts, all risks of additional tax assessments, administrative penalties, or errors during finalization are eliminated at the root.

In addition to legal safety, Vina TPT acts as a strategic advisor, helping businesses legally maximize tax incentives and optimize deductible expense structures in line with the spirit of the Corporate Income Tax Law. At the same time, all financial data is standardized into bilingual management reports (English & Vietnamese), creating a transparent information bridge that allows the Board of Directors and overseas Headquarters to easily grasp the accurate financial picture in real time. All of this brings complete peace of mind, allowing foreign investors to focus entirely on market expansion goals.

Are you concerned about tax compliance? Contact Vina TPT today to receive a free consultation and specialized tax compliance services.

BOOK A FREE CONSULTATION

Vietnam Tax Compliance for FDI Key Taxes & CPA Services


Financial statement preparation and compliance in 2025 for Japanese firms

Financial statement preparation and compliance in 2025 for Japanese firms

Financial statement preparation and compliance in 2025 for Japanese firms

1. Why 2025 Brings New Financial Reporting Challenges for Japanese Companies in Vietnam

2025 is considered an important milestone for Japanese enterprises operating in Vietnam. The constant change in tax and accounting policies, especially the regulations on Value Added Tax (VAT) and Corporate Income Tax (CIT), makes the preparation of financial statements more complicated and requires higher accuracy than ever.

For foreign-invested enterprises (FDI), especially Japanese enterprises, annual financial statements must be independently audited before being submitted to the tax authorities. This process requires early preparation, data must be complete, clear and can be easily compared with the accounting system at the headquarters in Japan. Compared to domestic enterprises, Japanese companies often spend more time on the comparison, consolidation and review stages, especially when there are differences between Vietnamese and Japanese accounting standards.

2. Key Financial Reports Every Japanese Firm Must Prepare

In Vietnam, all enterprises, especially foreign-invested enterprises (FDI), must prepare a complete set of financial statements according to Vietnamese Accounting Standards (VAS). This set of reports is not only a legal requirement to submit to tax authorities and independent auditors, but also a basis for Japanese enterprises to consolidate financial data with their headquarters in Japan.

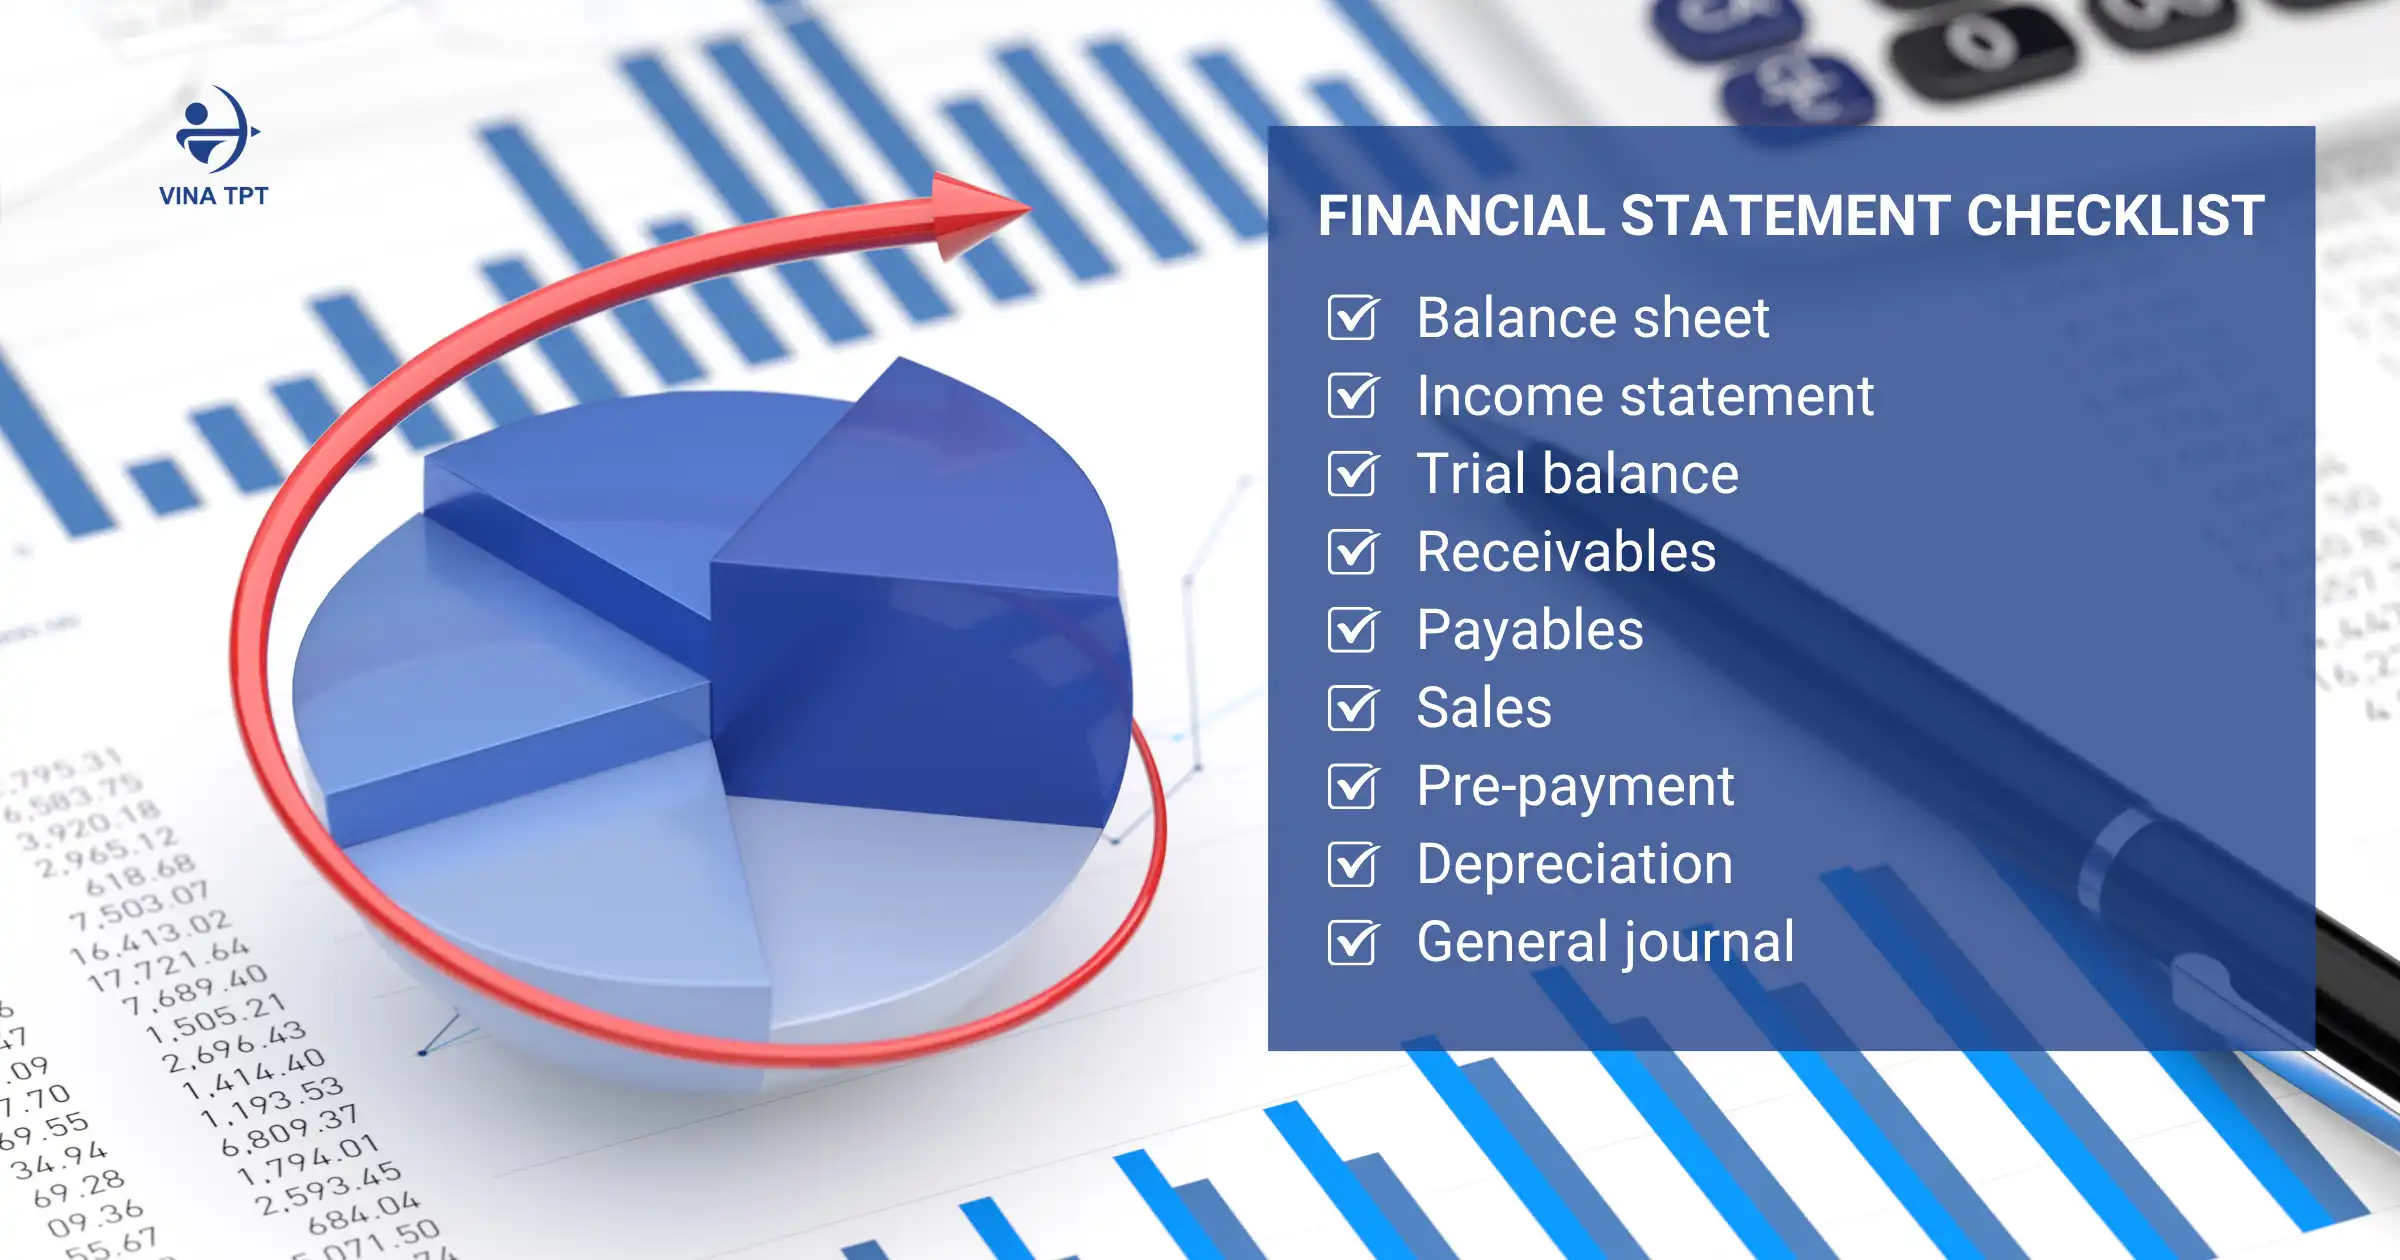
The three core reports include: Balance Sheet, Income Statement, and Cash Flow Statement.

Compared to J-GAAP (Japanese Generally Accepted Accounting Principles), VAS has some important differences that Japanese enterprises should note. For example, VAS requires depreciation of fixed assets according to the fixed time frame of the Ministry of Finance of Vietnam, while J-GAAP allows more flexibility based on the actual economic life of the asset. In addition, VAS recognizes revenue when ownership is transferred, not when invoices are issued as in some cases in Japan. Regarding consolidated reporting, VAS applies a different calculation method for minority interests and exchange rate differences than the Japanese standard, so if not adjusted in time, the data when consolidated to the parent company can be significantly different.

Therefore, during the financial statement preparation stage, Japanese companies often have to maintain two sets of data in parallel, one according to VAS standards to serve legal obligations in Vietnam, and one according to J-GAAP to serve the consolidated reporting to the head office. Handling this dual standard requires great care, in-depth understanding of both accounting systems, and close coordination between the internal accounting team, auditors, and consulting units such as Vina TPT Accounting service.

Financial statement preparation and compliance in 2025 for Japanese firms

3. Common Pitfalls in Year-End Financial Reporting

When it comes to preparing and submitting financial statements, many Japanese companies in Vietnam often encounter systematic errors that affect the auditing and tax compliance process.

3.1. Consolidation Differences Between Vietnam and Japan

One of the most common issues is the difference in financial statement consolidation between the branch in Vietnam and the headquarters in Japan. Vietnamese Accounting Standards (VAS) have many differences compared to J-GAAP, especially in handling exchange rate differences, classifying fixed assets and recording prepaid expenses.

According to i-Glocal’s analysis (2024), many Japanese FDI enterprises often have to prepare separate financial statements and consolidated reports in parallel, making the data reconciliation process complicated and prone to errors.

3.2. Lack of Valid Expense Documentation

Another common error is the lack of valid documents for deductible expenses. The 2023 report of the General Department of Taxation of Vietnam shows that more than 30% of tax inspection reports of FDI enterprises are related to invalid invoices, documents or incorrect accounting of deductible expenses.

These errors often lead to adjustments to taxable profits, collection of corporate income tax (CIT) and late payment penalties, directly affecting the reputation and financial planning of the parent company.

3.3. Exchange Rate Handling Issues

The handling of exchange rates is also a cause of discrepancies in financial statements. According to Circular 200/2014/TT-BTC, enterprises must use the actual exchange rate at the time of the transaction and prepare financial statements in Vietnamese Dong (VND).

However, many Japanese companies still use internal exchange rates according to Japanese accounting standards, leading to discrepancies when preparing reports to send to Vietnamese tax authorities, especially in the handling of foreign currency revenue and expenses.

3.4. Late Audit Submission and Transparency Requirements

Some Japanese enterprises in Vietnam also have problems submitting audit reports on time or not meeting financial transparency requirements. According to Vietnam Briefing (2024), all FDI enterprises must complete independent audits and submit financial reports within 90 days of the end of the fiscal year.

If the report is submitted late or does not meet standards, the enterprise may be subject to administrative fines, restricted from repatriating profits and face difficulties in renewing its investment license.

These risks not only increase compliance costs, but also directly affect the reputation and progress of consolidated reporting in Japan. Therefore, Japanese enterprises need to focus on controlling documents, complying with VAS and preparing financial records from the beginning to avoid being passive during the audit period.

In summary, full compliance with Vietnamese Accounting Standards (VAS) and financial statement regulations not only helps Japanese enterprises ensure financial transparency and accuracy, but also minimizes tax and audit risks. Proactively reviewing periodically and coordinating with professional accounting units in Vietnam is an important step to maintain stability in financial management and strengthen trust with Japanese management agencies and partners.

EXPERT YEAR-END FINANCIAL REPORTING SUPPORT

4. Outsourced Bookkeeping: The Smart Way to Stay Compliant

Faced with a large volume of accounting work and strict compliance requirements, more and more Japanese enterprises in Vietnam choose outsourced bookkeeping instead of maintaining an in-house accounting team. This solution helps save on personnel costs, ensures accuracy in reporting, and easily coordinates with auditors and tax authorities. Vina TPT Accounting service provides a complete outsourced bookkeeping service exclusively for Japanese enterprises, including: bookkeeping, preparing bilingual financial statements (English – Japanese – Vietnamese), and reviewing data before auditing. Vina TPT’s outstanding strength is its team of experts who can communicate fluently in Japanese, understand Japanese accounting standards (J-GAAP) and Vietnamese regulations (VAS), helping customers easily exchange, compare and consolidate financial data.

5. How Vina TPT Supports Japanese Firms for 2025 Compliance

Entering 2025, when the demand for financial transparency is increasing, Japanese enterprises need a partner who not only does accounting but also accompanies them throughout the entire compliance process.

Financial statement preparation and compliance in 2025 for Japanese firms

Vina TPT Accounting service provides comprehensive solutions including:

  • Preparing and reviewing bilingual financial statements (Japanese – Vietnamese): ensuring easy to understand, accurate and ready for audit.
  • Consulting on consolidated reports for Japanese corporations: supporting data conversion from VAS to J-GAAP or IFRS.
  • Consulting and coordinating audits: working directly with independent auditors, helping to reduce review time and limit post-audit adjustment risks.
  • Monitoring and updating the latest tax – accounting policies: ensuring reports are always in compliance with the regulations of the Ministry of Finance of Vietnam.

With a team of experienced accountants and auditors fluent in three languages ​​(Japanese, English, Vietnamese), Vina TPT helps Japanese enterprises in Vietnam maintain a transparent accounting system, comply with and optimize operating costs in accordance with international standards and Vietnamese law.

For comprehensive advice on financial statement preparation, auditing and tax compliance solutions in 2025, contact VinaTPT.

BOOK A FREE CONSULTATION

Vina TPT Accounting services