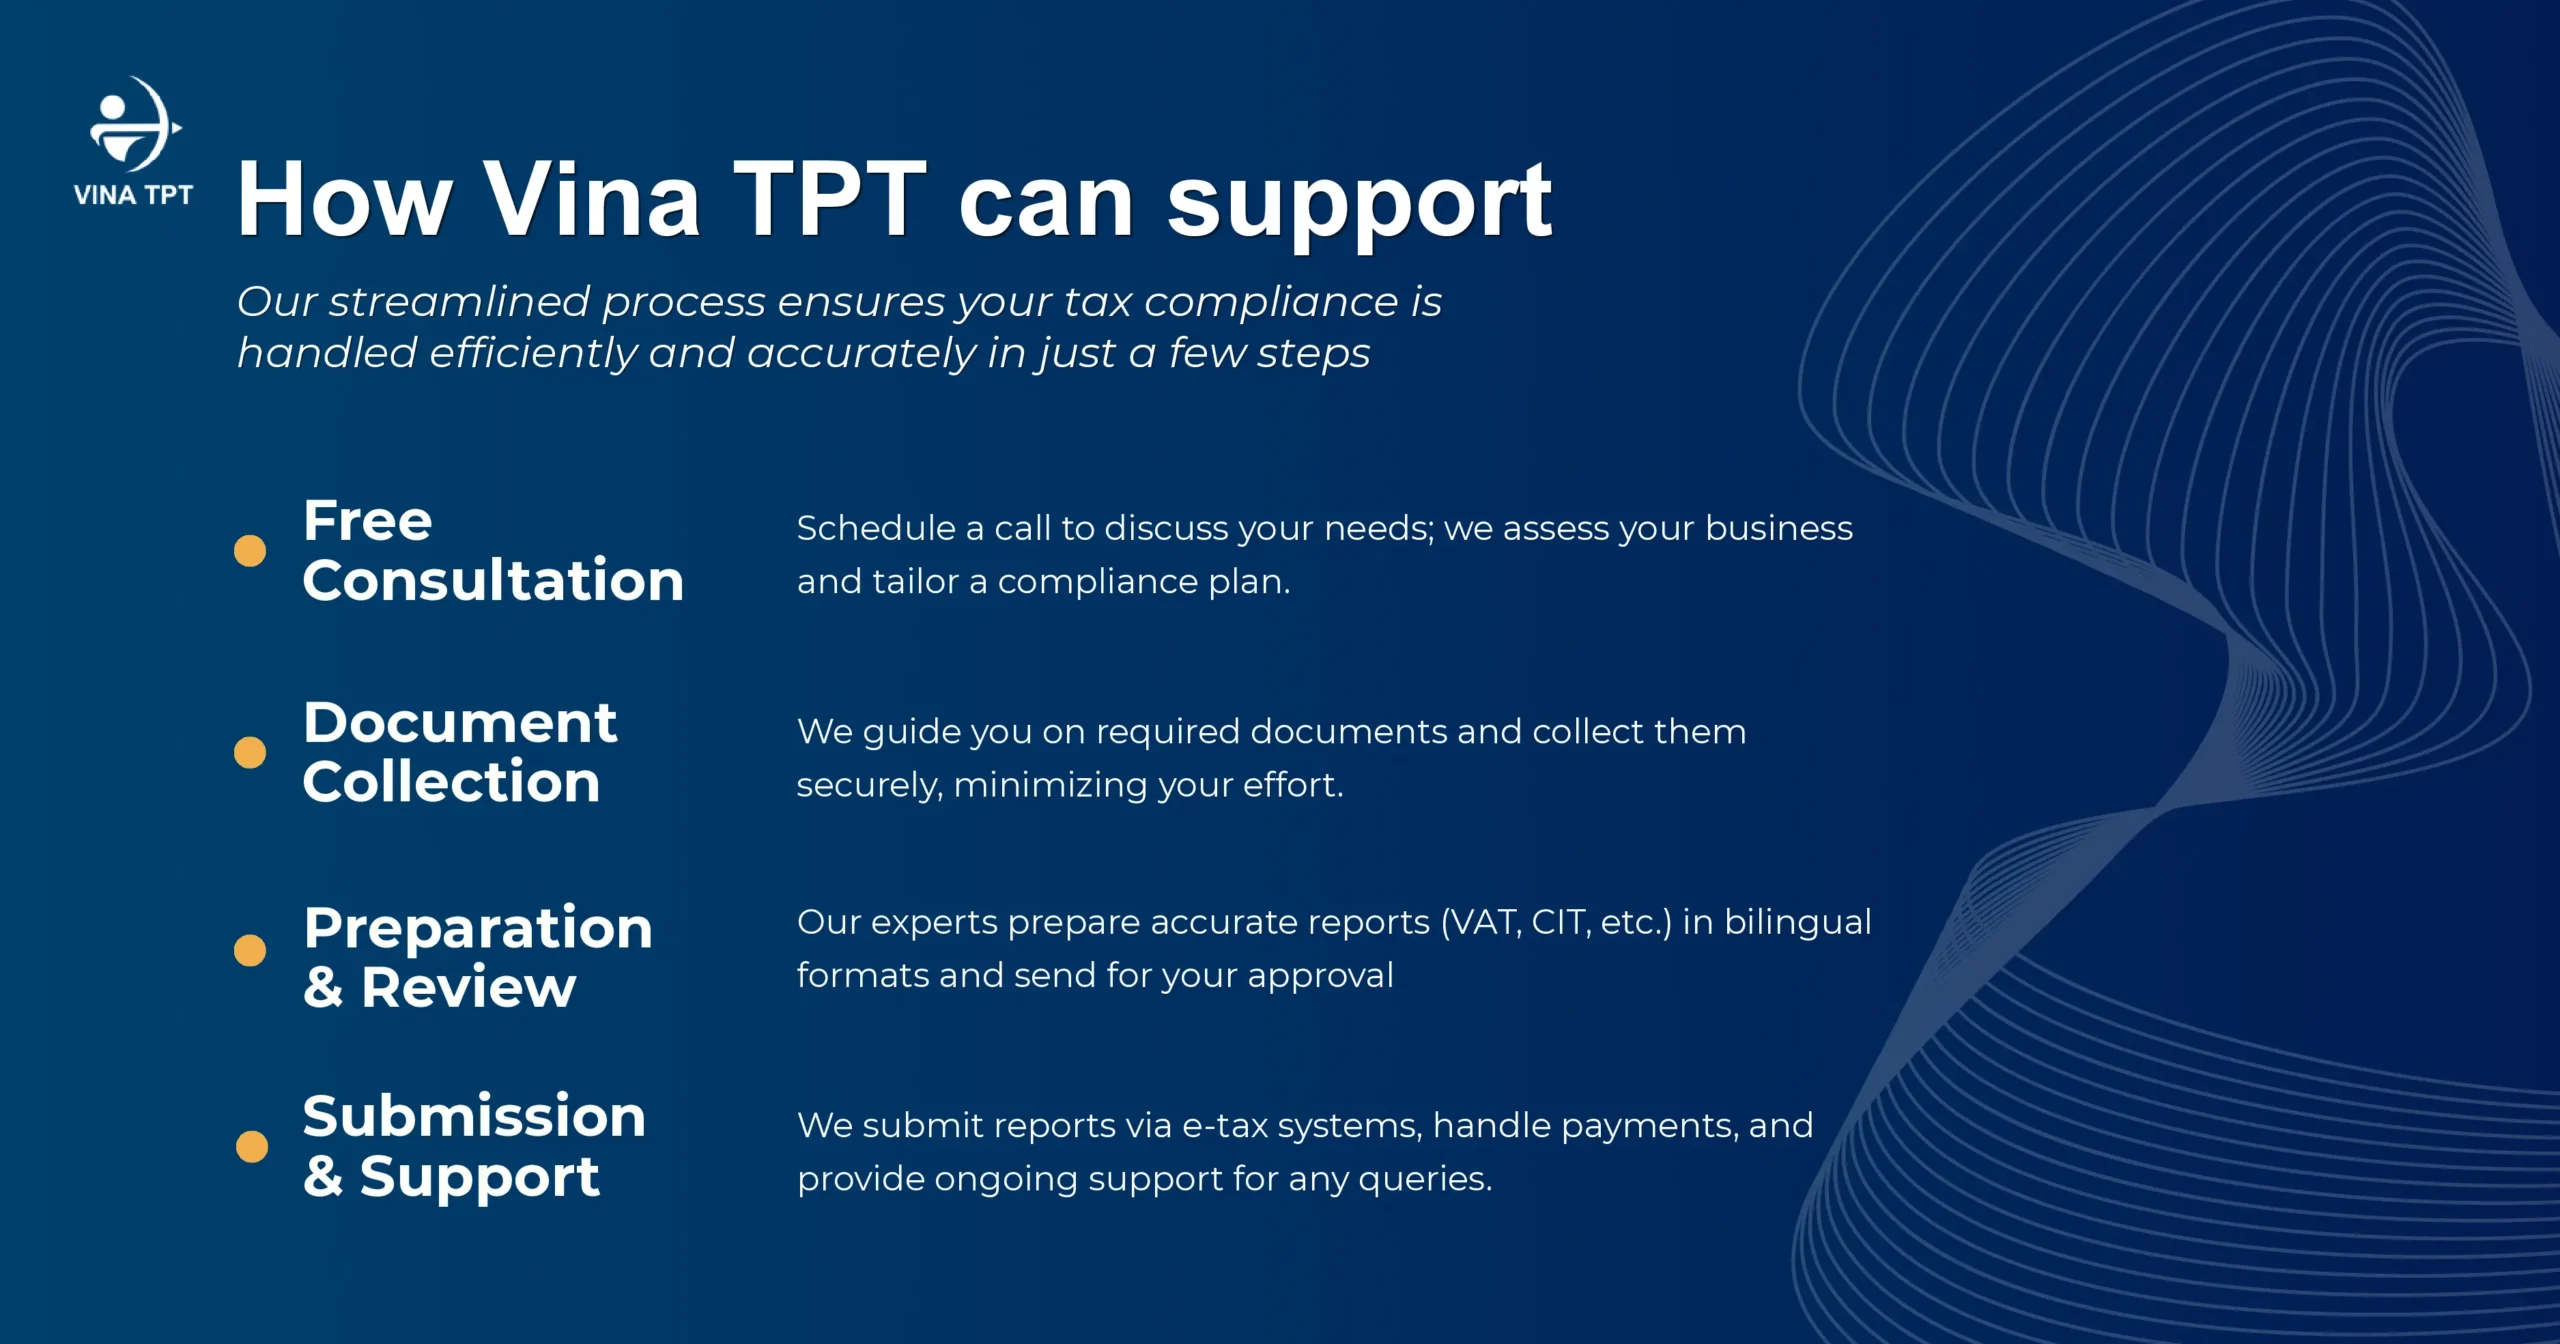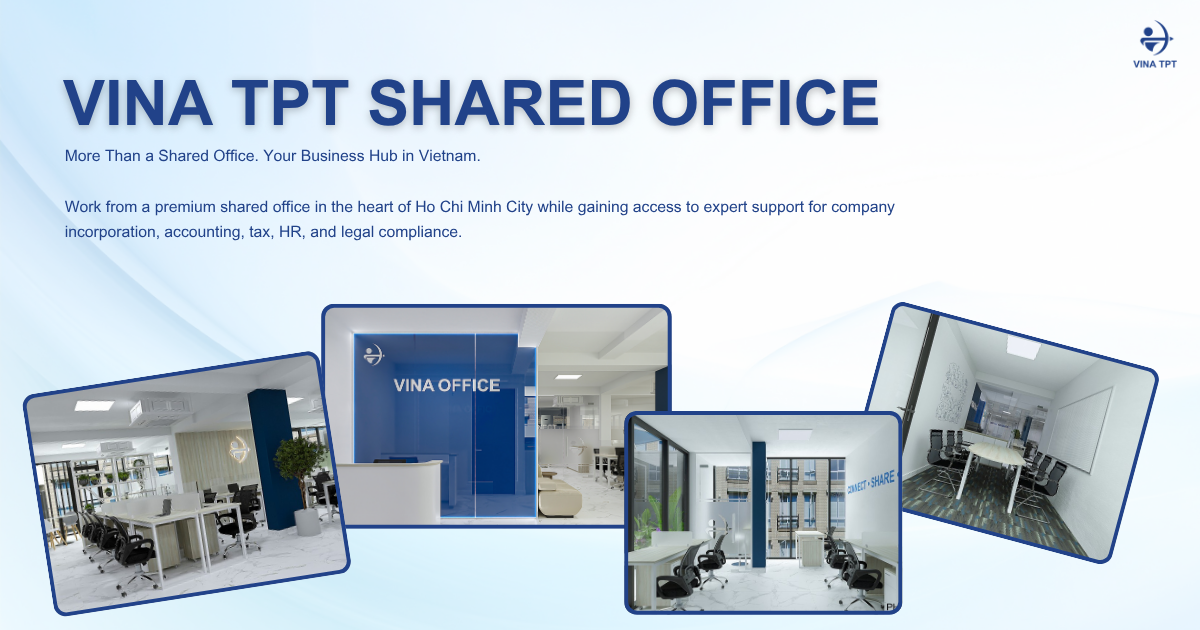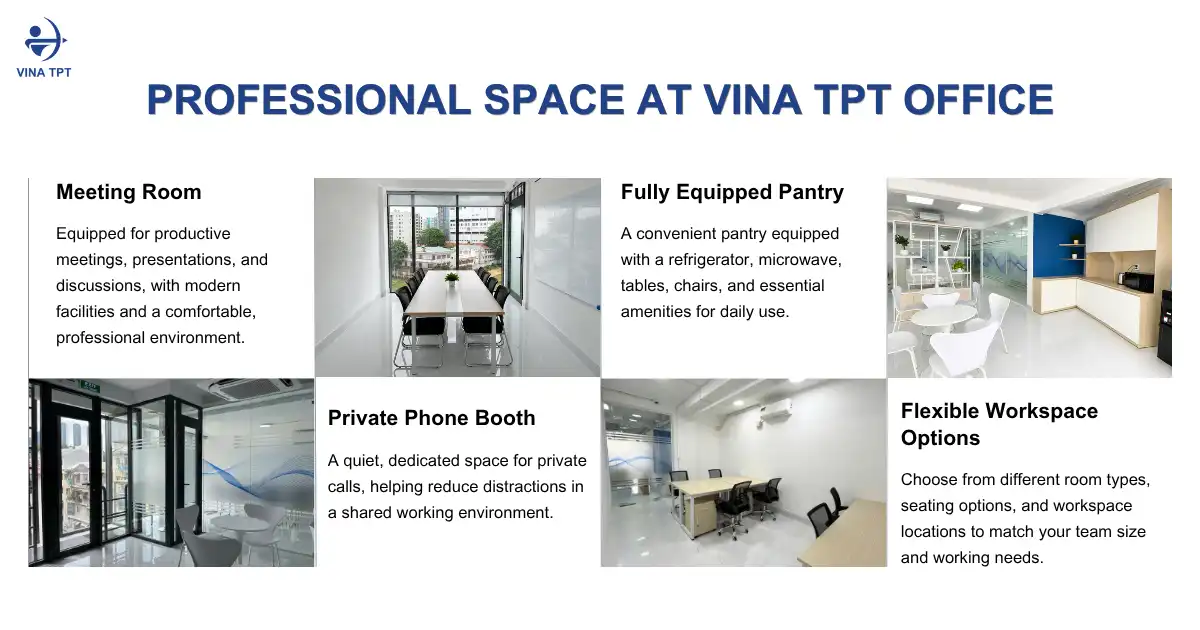
What Does a Tax Consultant in Vietnam Actually Do?

what-does-a-tax-consultant-in-vietnam-actually-do

what-does-a-tax-consultant-in-vietnam-actually-do

If you are already doing business in Vietnam and looking for tax advisory support, the harder question is often not whether to hire someone, but which services a tax consultant Vietnam actually offers. Some firms only handle monthly filings. Others also cover VAT refunds, tax health checks, inspection support, and transfer pricing. The scope is not the same, and the right package depends on where your company is in its operating cycle.

This article maps the tax advisory Vietnam services most commonly provided in the market: the routine accounting – tax work that keeps filings on time, the specialized work that protects cash flow and inspection risk, and the point at which an FDI company should bring in a professional partner. The goal is to give you a clear picture of tax compliance Vietnam support before you choose a consultant.

1. What Accounting & Tax Consultant Services Cover Each Month

For FDI companies, the role of a tax consultant Vietnam never stands alone as “someone who just files returns.” It must be tied to the internal accounting system. Periodic tax compliance Vietnam requires absolute accuracy from incoming source documents through to the data submitted on the Tax Authority’s system.

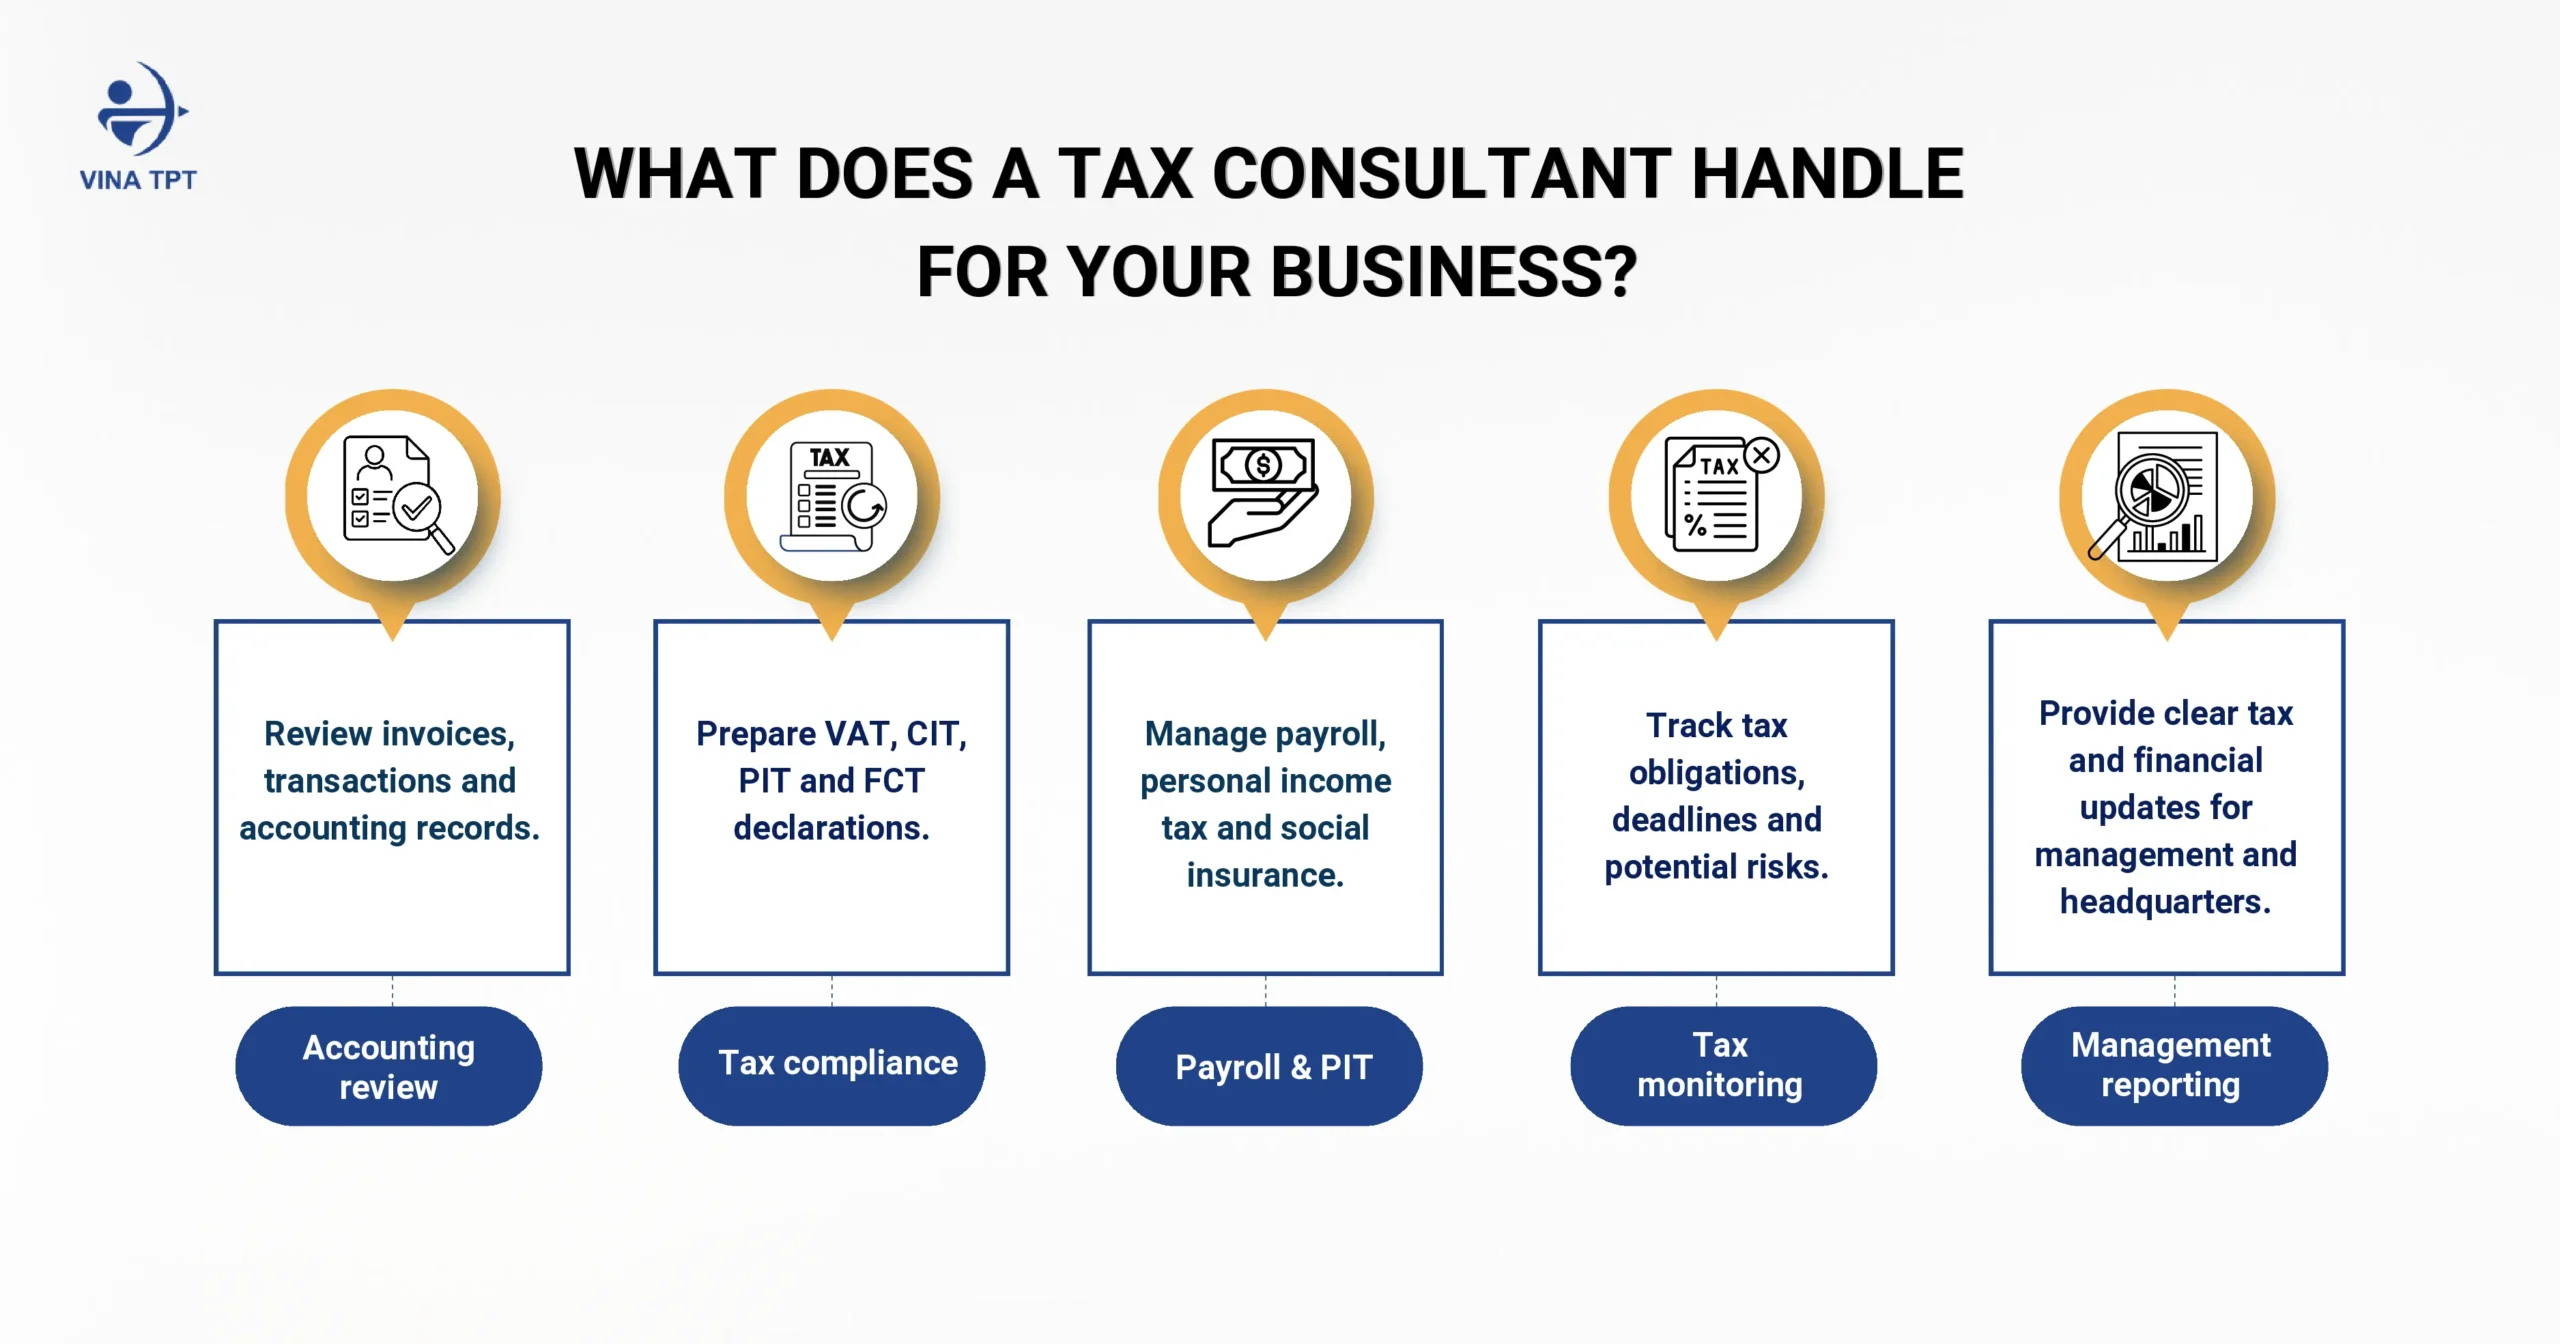
Below are the monthly and quarterly tasks that a professional tax advisory firm performs for FDI companies:

  • Document recording and e-invoice review: Receive all incoming and outgoing invoices and bank documents; review the legality, validity, and reasonableness of e-invoices on the General Department of Taxation portal to prevent risks from invoices issued by absconding or inactive companies.
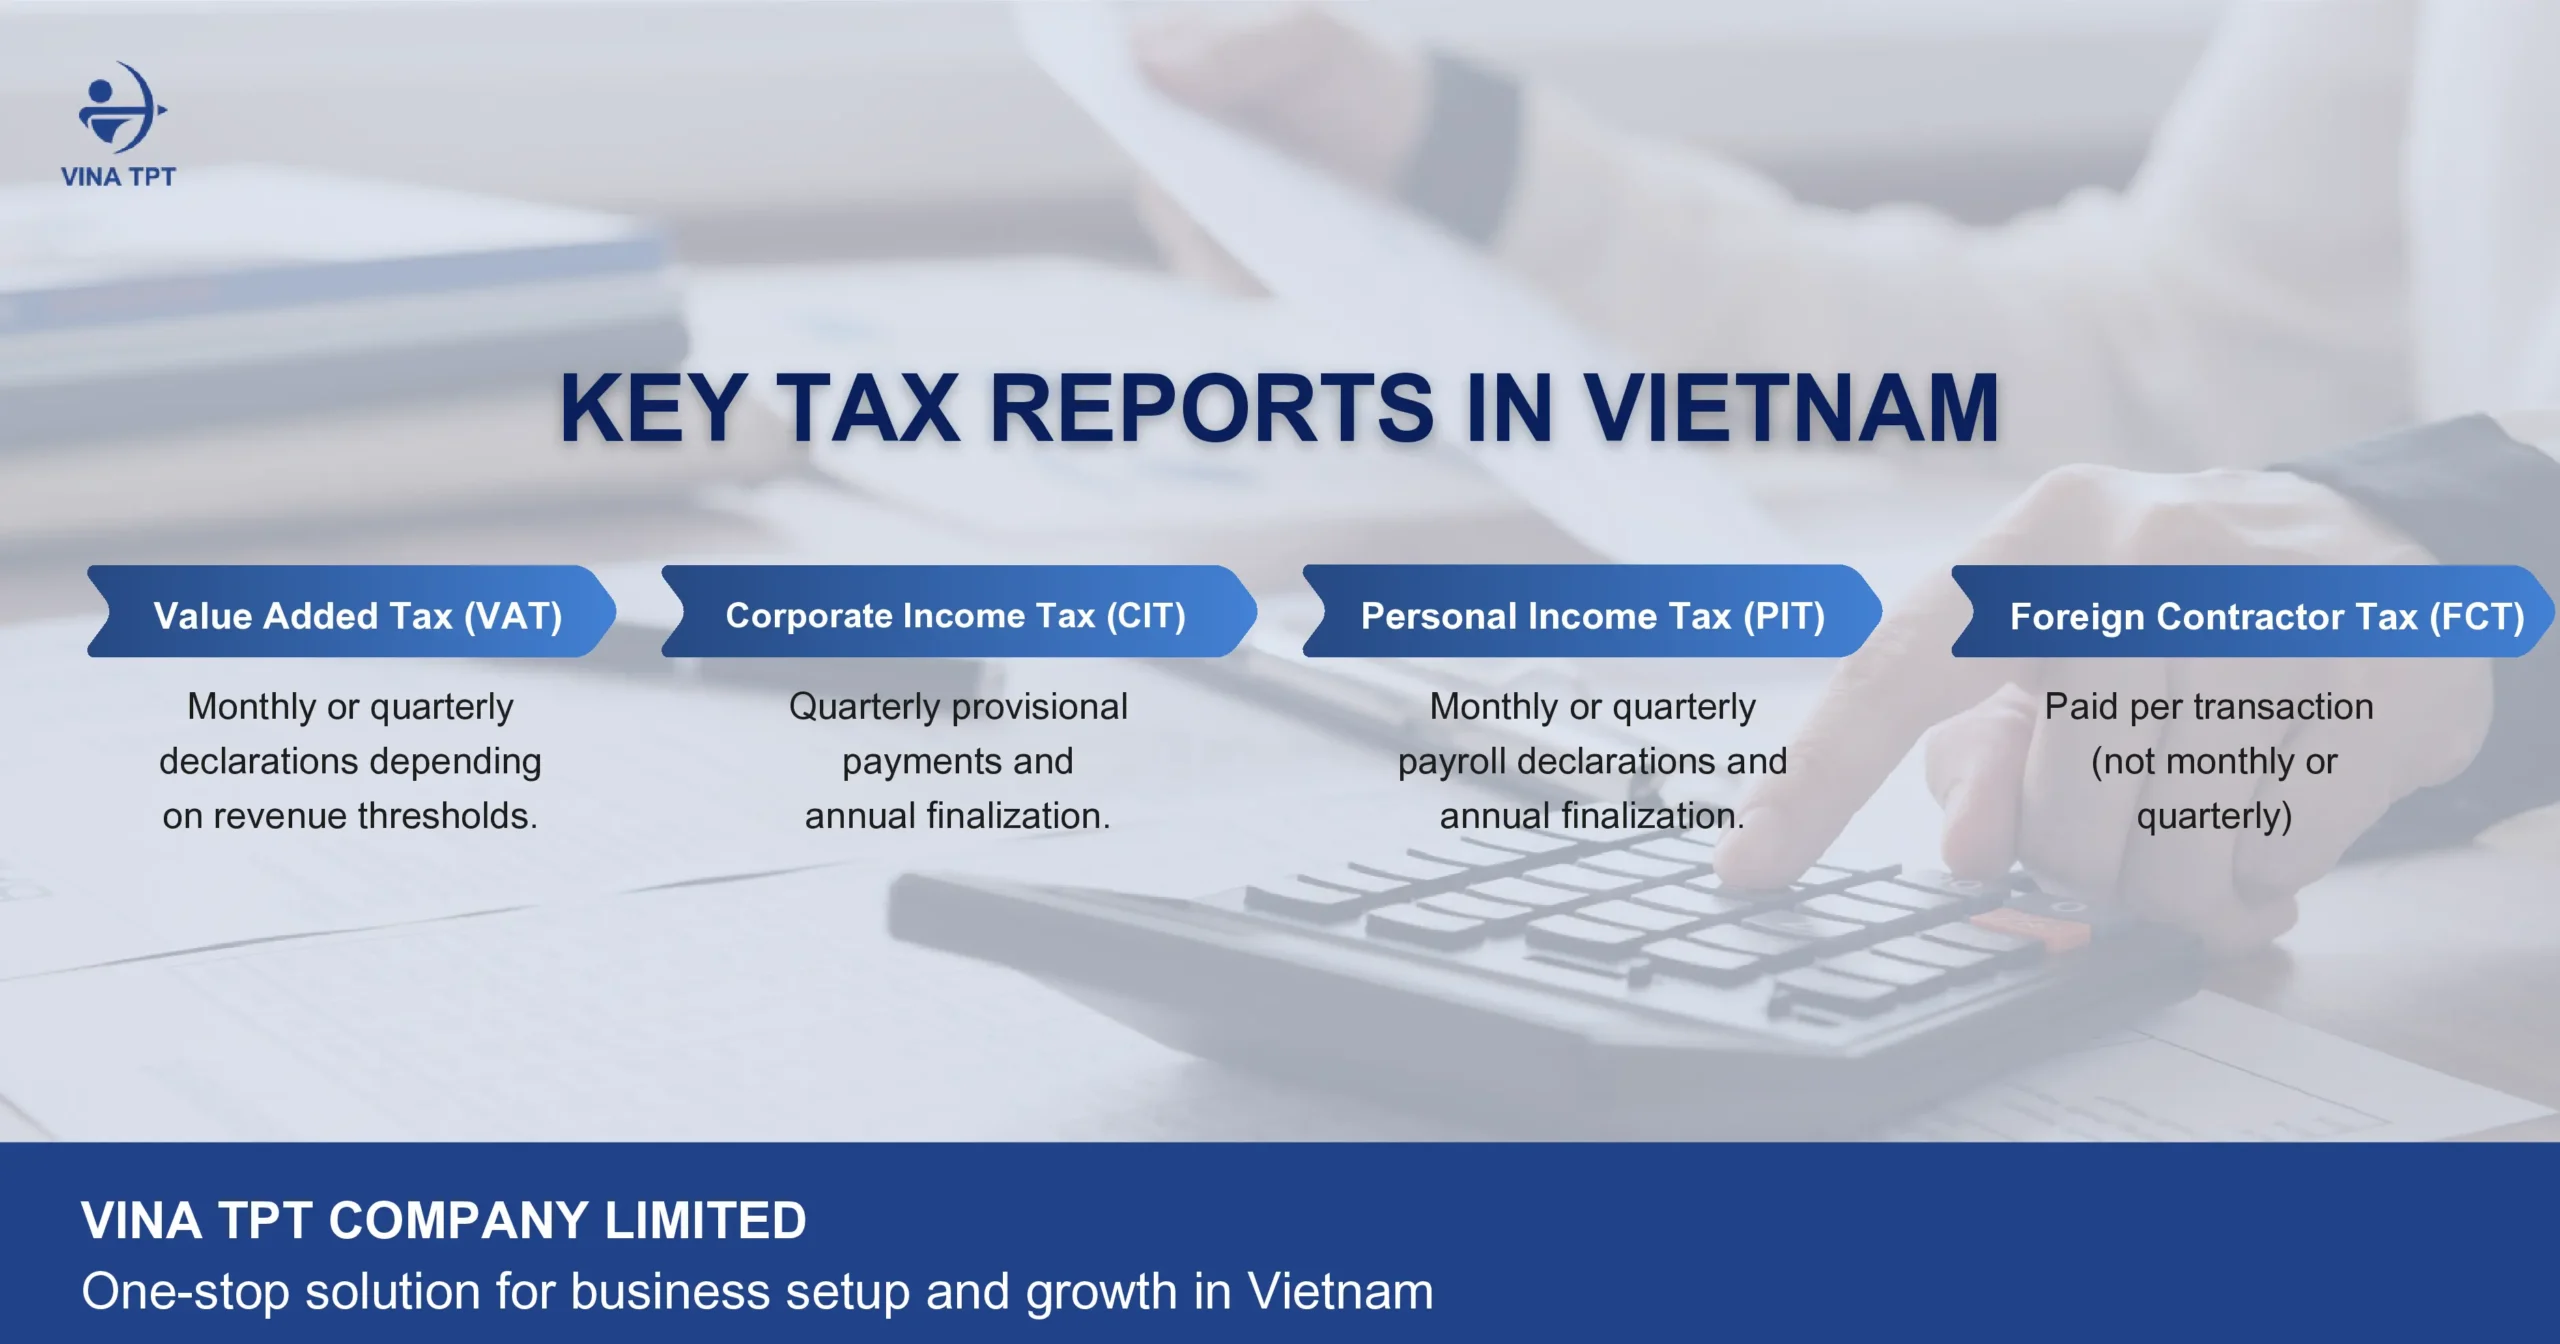
  • Full identification of tax obligations arising in the period: Accurately assess the taxes the company must pay, including Value-Added Tax (VAT), Corporate Income Tax (CIT), Personal Income Tax (PIT), Foreign Contractor Tax (FCT), and the business license fee.
  • Preparation and on-time filing of tax returns: Build tax computation worksheets, prepare VAT and PIT returns on a monthly or quarterly basis, and file them through the e-tax portal before the statutory deadlines (the 20th of the following month or the last day of the first month of the following quarter), completely eliminating the risk of late-filing penalties.
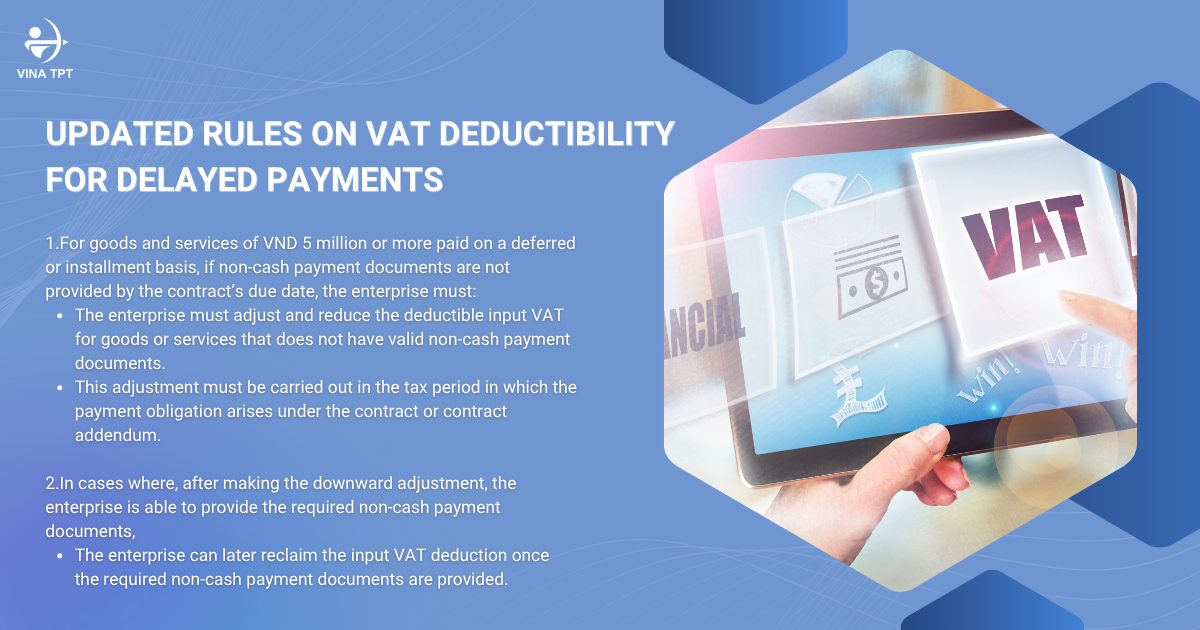
  • Review of VAT deduction conditions and non-cash payment rules: Strictly check input VAT deduction conditions, especially the mandatory bank-transfer requirement for invoices of VND 5 million or more, and verify valid bank payment evidence.
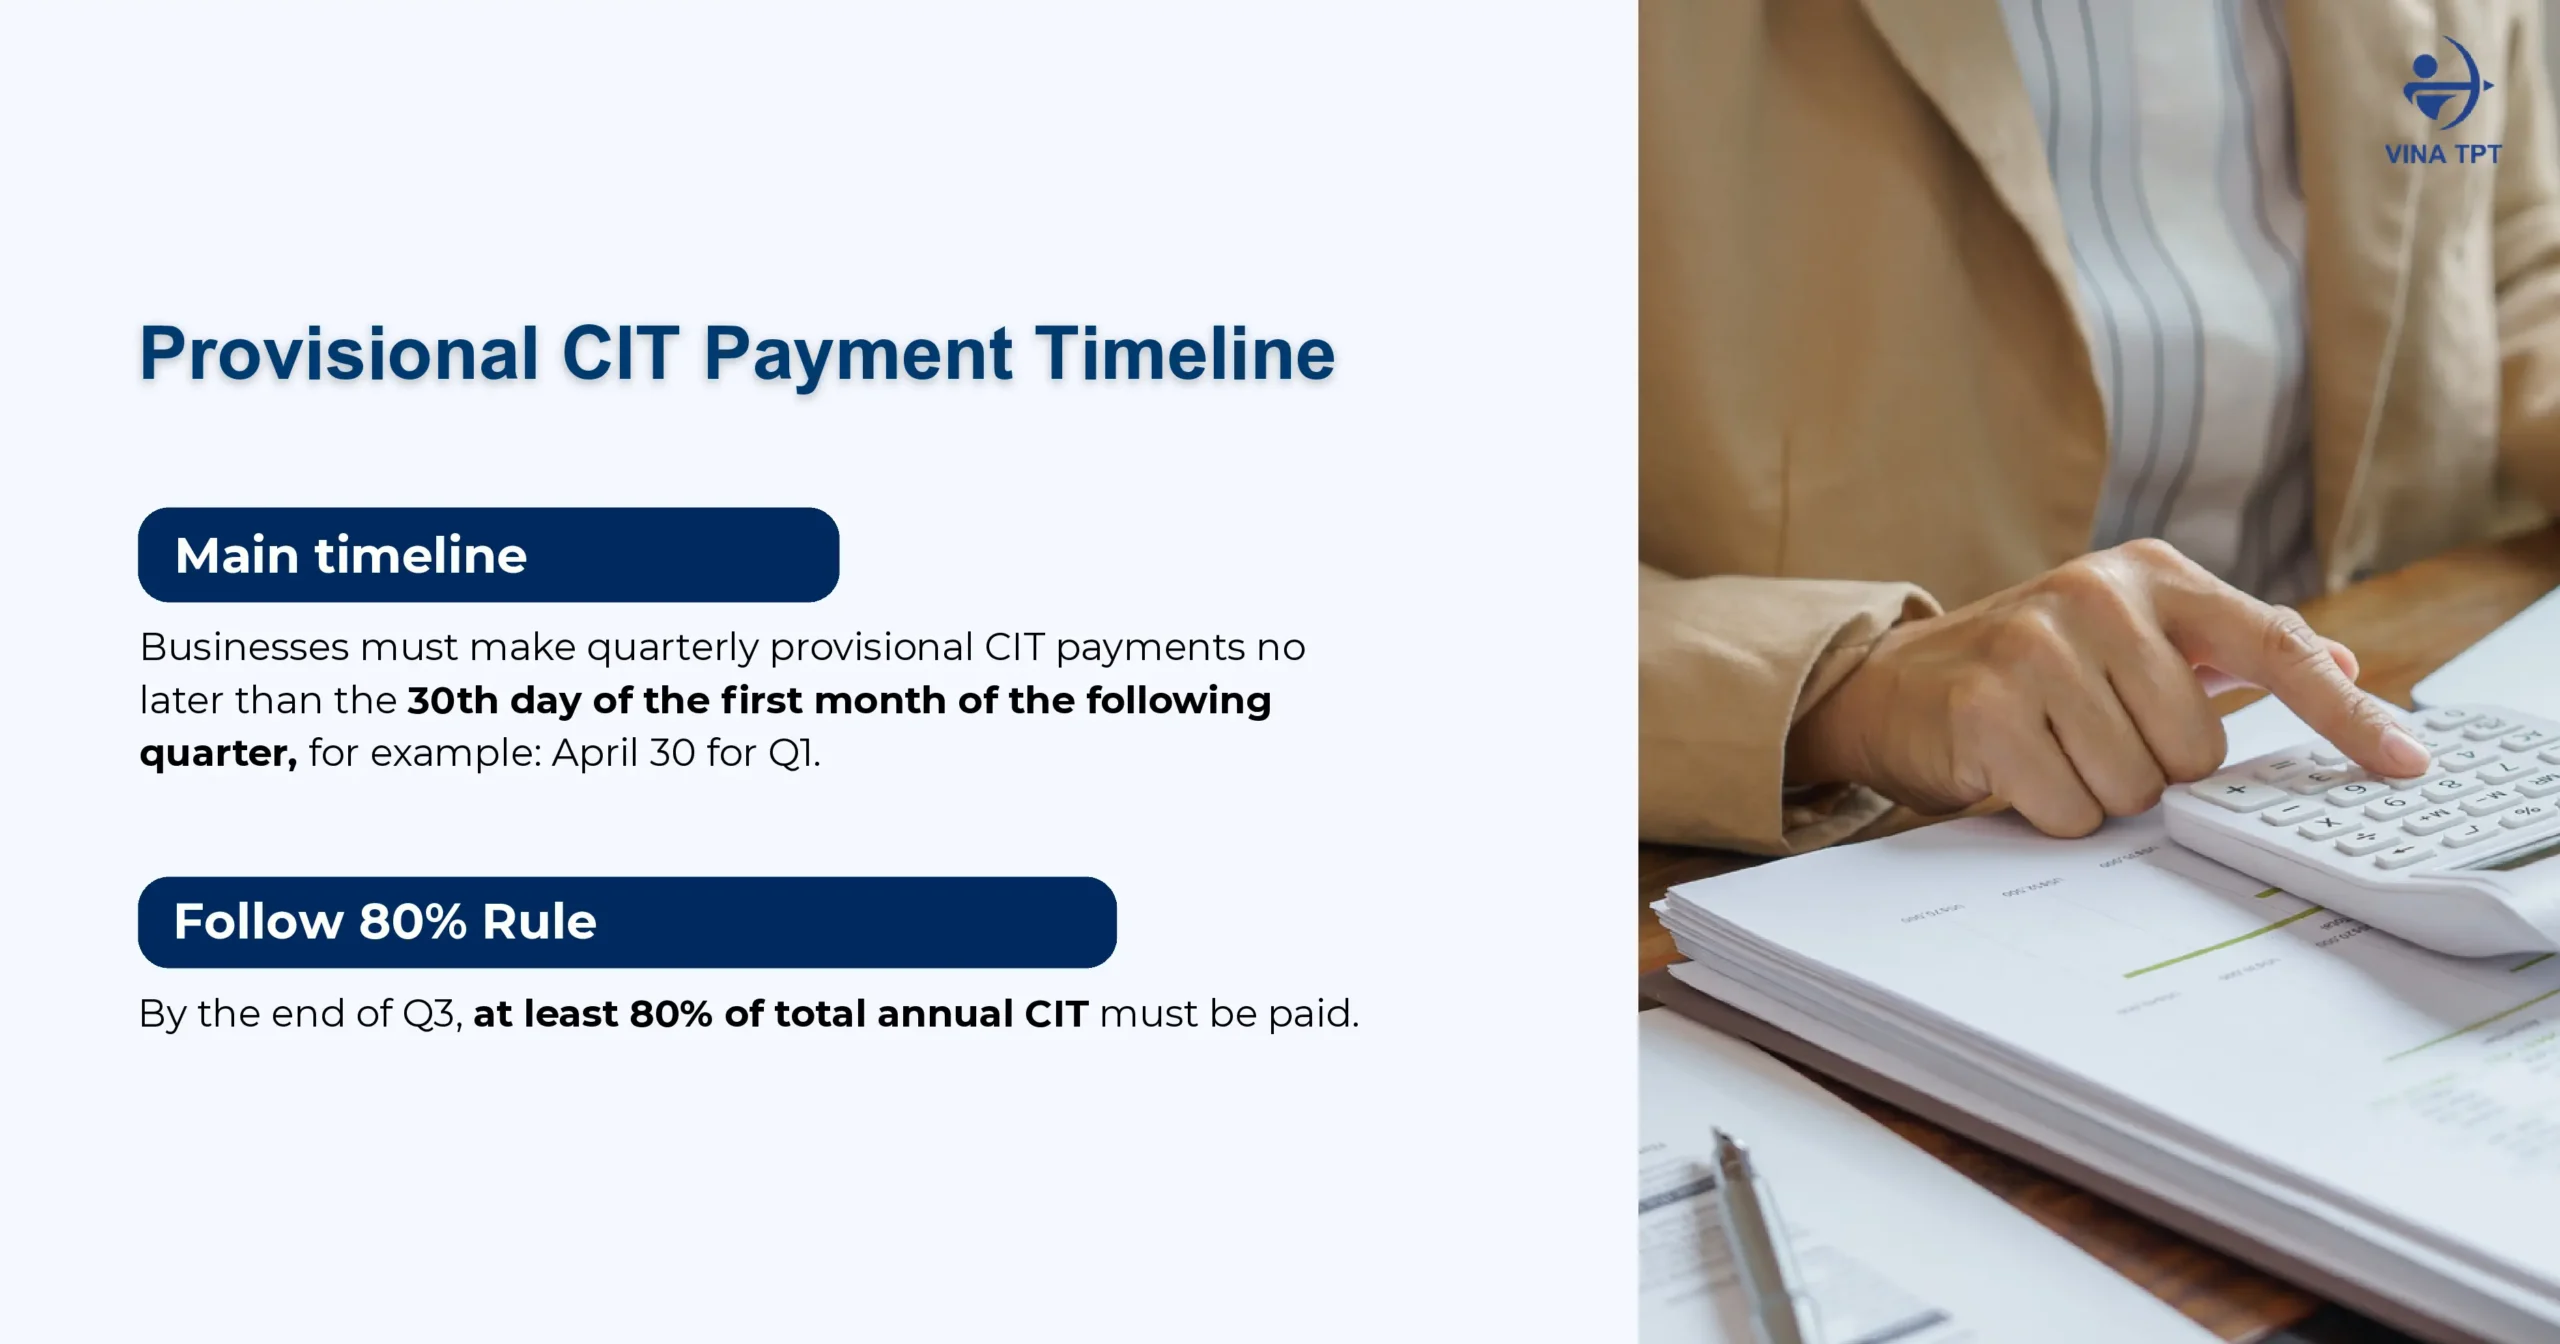
  • Monitoring and balancing CIT provisional payments: Provisionally calculate actual quarterly profit to determine the CIT amount payable in advance, ensuring that the total provisional CIT paid over four quarters is not lower than 80% of the CIT payable on the annual finalization, thereby avoiding late-payment interest.
  • Monitoring of Foreign Contractor Tax (FCT): Declare and pay FCT promptly whenever outbound payments arise to international suppliers (software royalties, consulting fees, commercial commissions, foreign loan interest, etc.), preventing reassessment risk from omitted transactions.
  • Consolidated reporting for the Board of Directors and Headquarters: Prepare tax-obligation summaries and management reports in English and Vietnamese so that management in Vietnam and the overseas parent company can easily track cash flow and compliance status.

Vina TPT’s professional view: A full-package tax compliance service must deliver three core elements: clean accounting books + accurate tax returns + figures that reconcile between accounting and tax. If any one of these is missing, the tax position will be off even if the company still “files on time.”

2. When You Need Deeper Tax Consultant Support

Monthly filing work only keeps the company on the correct administrative rhythm. The actual operations of FDI companies regularly give rise to complex matters that require in-depth tax advisory Vietnam capability:

  • VAT refund consulting and implementation: For FDI companies with new investment projects or export businesses, the amount of undeducted input VAT is often substantial. A tax consultant Vietnam will review the entire legal dossier, the validity of invoices, export contracts, and bank payment evidence, then file the application and explain it directly to the Tax Authority in order to recover the refund into the company’s account.
  • Tax Health Check: A full review of the accounting books, tax returns, and supporting documents of prior financial years. This work helps the company proactively detect errors, non-deductible expenses, or potential violations before a tax inspection, fundraising, M&A, or share transfer takes place.
  • Inspection dossier preparation and representation before the Tax Authority: When a tax inspection or audit decision is issued, the advisor helps collect documents and prepare detailed explanations of sensitive expense items (entertainment, expatriate costs, foreign-exchange differences, etc.) in order to protect reasonable expenses as far as possible and minimize reassessment risk.
  • Related-party transaction management and Transfer Pricing (TP) documentation: Most FDI companies have transactions with the parent company or other related parties. The tax advisor is responsible for identifying the scope of related-party transactions, preparing the related-party transaction appendix attached to the CIT finalization return, and building the Transfer Pricing documentation set (Local File and Master File) in strict compliance with Decree 132/2020/NĐ-CP.
what-does-a-tax-consultant-in-vietnam-actually-do

3. When Does an FDI Company Need a Tax Consultant?

An FDI company should proactively look for a professional tax advisory partner when it falls into one of the following situations:

  • Newly established FDI company: It does not yet have a dedicated accounting and tax team that fully understands the Vietnamese legal system and needs to set up the initial books and compliance processes correctly.
  • Need for a VAT refund: It wants to shorten the refund timeline and ensure that the input dossier meets the Tax Authority’s inspection standards so that cash can be released sooner.
  • Related-party transactions: It needs advice on preparing Transfer Pricing documentation to the required standard in order to avoid the risk of the Tax Authority imposing prices and assessing additional CIT.
  • Change in capital structure or business model: It needs advice on the tax obligations arising from a capital transfer, asset transfer, or corporate restructuring.
  • Several years of operation without a proper tax finalization review: It is not certain that prior periods were fully compliant and needs a Tax Health Check to address risks proactively before an inspection decision is issued.

Explore Vina TPT’s Tax Consultant Support Services

4. What to Look for When Choosing a Tax Consultant in Vietnam

When selecting a tax compliance Vietnam partner, the Board of Directors should assess the following practical capability criteria:

  • Hands-on experience with FDI clients: A deep understanding of the relationship between VAS and IFRS, a firm grasp of Vietnamese tax regulations, and familiarity with the reporting culture of multinational groups.
  • Valid practicing certificates: Both the firm and its staff must hold the Certificate of Practice in Tax Procedure Services and the Accountant / Chief Accountant certificate as required by law.
  • Multi-level quality control (QC): Accounting data and tax returns must pass through at least two to three review layers (Specialist → Team Leader → Chief Accountant / Tax Director) before official filing.
  • Multilingual communication and reporting: The ability to advise and prepare management reports clearly in English and Vietnamese, enabling Headquarters to monitor compliance with ease.
  • Transparent service contract: A clear scope among monthly filing work, in-depth advisory, inspection support, and Transfer Pricing documentation.
  • Integrated payroll and accounting: Seamless connection between payroll processing and tax filing so that financial data remains consistent and no discrepancies arise at year-end finalization.

5. How Vina TPT Works as a Tax Consultant for FDI Companies

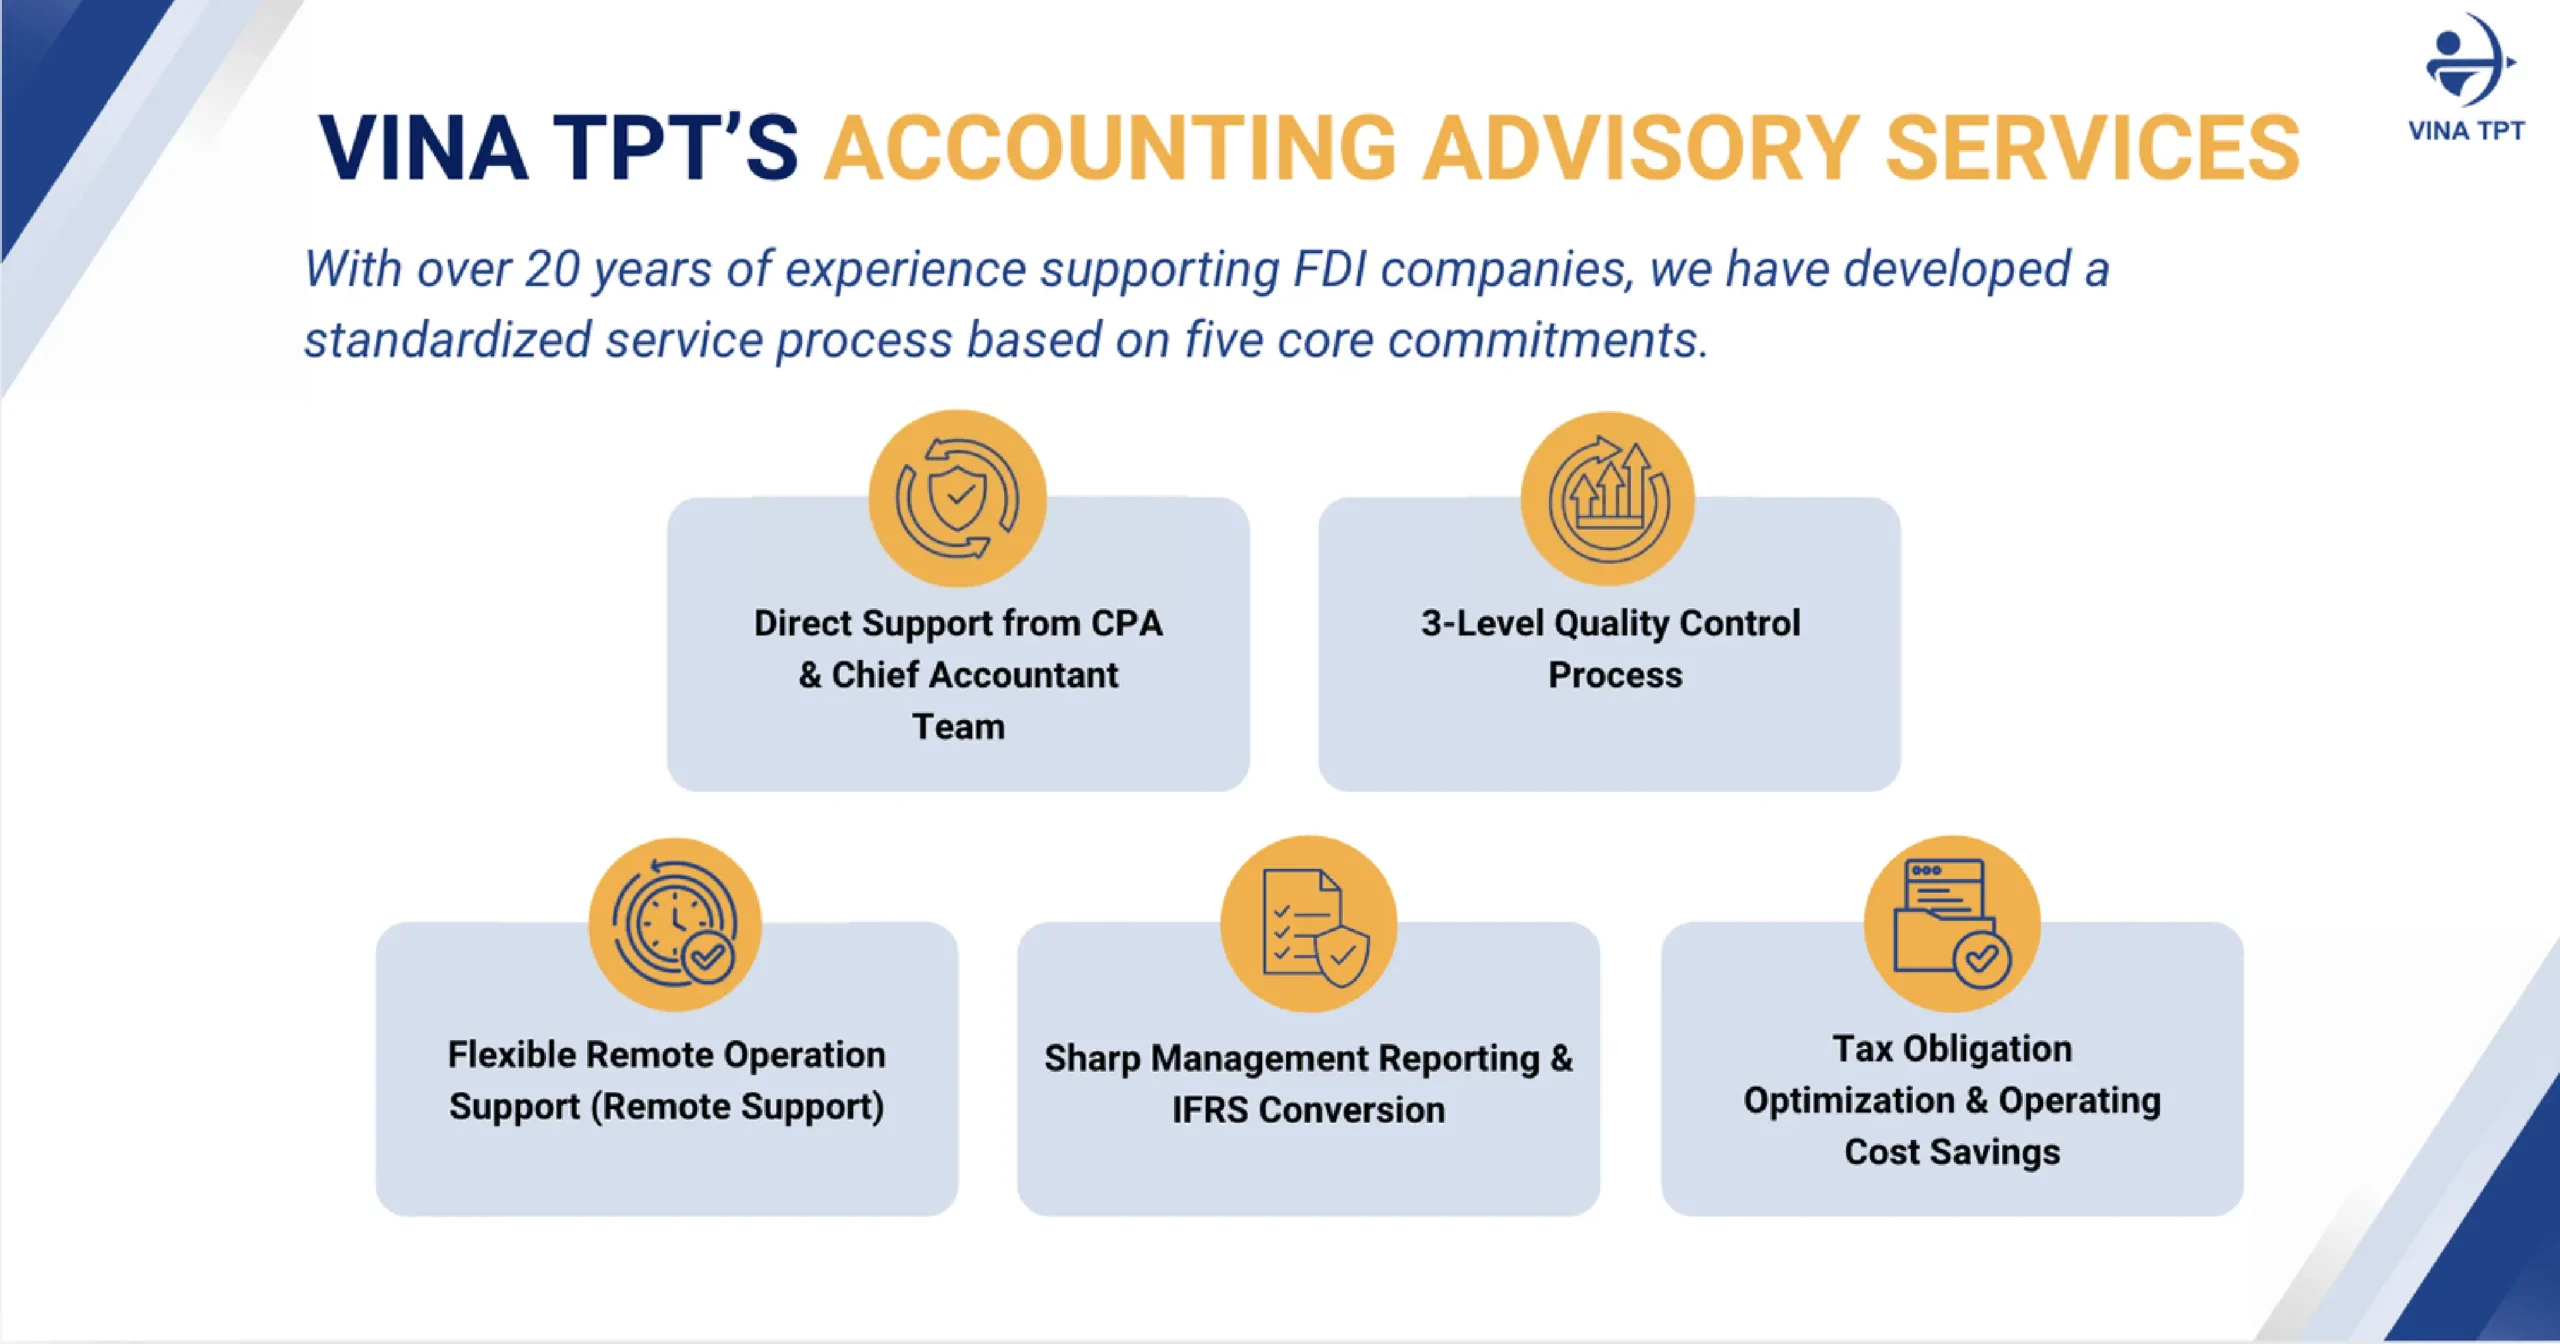
As a specialist advisory firm in finance, accounting, and tax for foreign-invested enterprises in Vietnam, Vina TPT delivers a two-layer tax advisory solution that helps companies optimize costs and control risk comprehensively.

The service areas Vina TPT implements for FDI companies include:

  • Recurring work: Full-package filing of VAT, CIT, PIT, and FCT; review of the legality of incoming documents; bookkeeping under VAS; payroll administration; and provision of a Chief Accountant.
  • Specialized work: Preparation of VAT refund dossiers; Tax Health Checks of prior-year books; preparation of inspection files and direct liaison during a tax inspection; and related-party transaction advisory and documentation.

Is your FDI company looking to review its current tax obligations in full, or do you need a reputable tax advisory partner for the long term? Contact Vina TPT today for a consultation on the most suitable service package – accurate, optimized, and free of unnecessary extra costs.
what-does-a-tax-consultant-in-vietnam-actually-do

BOOK A FREE CONSULTATION

30% CIT Reduction: New Tax Policy in Vietnam for 2026–2027 Tax Period

30% CIT Reduction for 2026 - 2027

30% CIT Reduction: New Tax Policy in Vietnam for 2026–2027 Tax Period 

Vietnam has introduced a new tax relief measure for the 2026 and 2027 tax periods under Resolution No. 43/2026/QH16. Eligible enterprises and organizations established under Vietnamese law with annual revenue of no more than VND 10 billion may receive a 30% reduction in corporate income tax (CIT) payable. 

The policy is intended to provide additional tax support for eligible businesses. However, the 30% reduction should not be confused with a 30% reduction in the statutory CIT rate. In practice, businesses need to determine their eligible CIT payable first, then apply the reduction in accordance with the applicable rules. 

What Does Resolution No. 43/2026/QH16 Say About the Tax Reduction? 

Resolution No. 43/2026/QH16 was issued by the National Assembly on 24 August 2026. The Resolution introduces tax reductions for both personal income tax (PIT) and corporate income tax (CIT) for the 2026 and 2027 tax periods as follows: 

“…

2. A 30% reduction in corporate income tax payable for the 2026 and 2027 tax periods shall apply to the income of enterprises and organizations established in accordance with Vietnamese law whose annual revenue in 2026 or 2027 does not exceed VND 10 billion. 

This reduction does not apply to enterprises established through the division or separation of an enterprise after the effective date of this Resolution, where the combined annual revenue of the enterprises resulting from such division or separation exceeds VND 10 billion in 2026 or 2027. 

In cases where an enterprise is already entitled to tax incentives under the Law on Corporate Income Tax or other laws or resolutions of the National Assembly, the corporate income tax reduction specified in this Clause shall be calculated based on the corporate income tax payable after deducting the applicable tax incentives.” 

30% CIT Reduction for Enterprises 

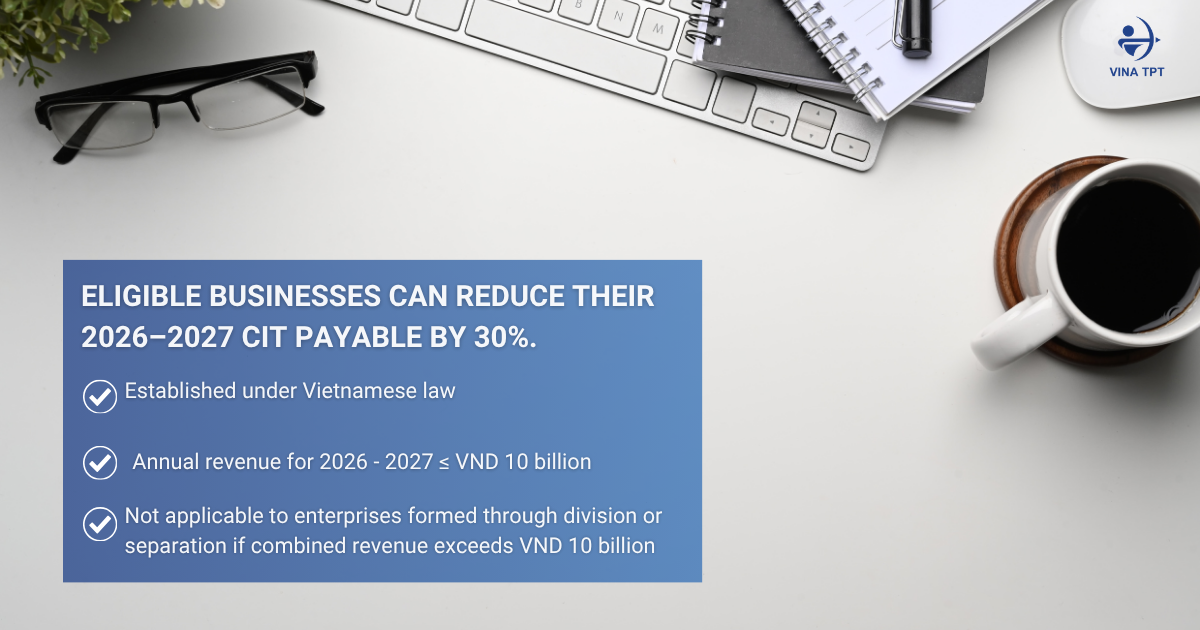
For CIT, eligible enterprises and organizations may receive a 30% reduction in CIT payable for the 2026 and 2027 tax periods if they are established under Vietnamese law and have annual revenue of no more than VND 10 billion in the relevant tax year. 

The reduction does not apply to enterprises formed through the division or separation of an existing enterprise after the Resolution takes effect if the combined annual revenue of the enterprises resulting from such division or separation exceeds VND 10 billion in the relevant year. 

For enterprises already benefiting from CIT incentives under the Law on Corporate Income Tax or other laws and resolutions of the National Assembly, the 30% reduction is calculated based on the CIT payable after the applicable tax incentives have been deducted. 

30% PIT Reduction for Business Individuals and Households 

Resolution 43 also provides a 30% reduction of PIT payable for the 2026 and 2027 tax periods for resident individuals earning business income whose annual revenue does not exceed VND 10 billion. 

Although the CIT and PIT provisions use a similar 30% reduction concept and a VND 10 billion revenue threshold, they apply to different taxpayers. 

Importantly, this 30% PIT reduction applies only to PIT arising from business income. It does not apply to PIT calculated on employment income, such as salary or wages received by individuals as employees. 

Eligible businesses can reduce their 2026–2027 CIT payable by 30%

What Is the Current CIT Rate in Vietnam? 

The 30% CIT reduction needs to be considered alongside the CIT rates currently applicable in Vietnam. 

Under the 2025 Law on Corporate Income Tax, the standard CIT rate is 20%, while 15% and 17% rates may apply to qualifying enterprises based on annual revenue and other statutory conditions. 

This makes it important to distinguish between two separate concepts: 

  1. CIT rate — the statutory rate used to calculate CIT liability. 
  2. 30% CIT reduction — a tax relief mechanism that reduces the resulting CIT payable for qualifying businesses. 

Reference: Updated 2025 | Corporate Income Tax Rates in Vietnam

Standard CIT Rate: 20% 

The general CIT rate under the 2025 Law on Corporate Income Tax is 20%, unless a different rate or preferential tax rate applies. 

For example:

If a company has VND 1 billion in taxable profit and the applicable CIT rate is 20%, its CIT payable before the reduction would be VND 200 million. And the company qualifies for the 30% CIT reduction under Resolution No. 43/2026/QH16, it would receive a reduction of VND 60 million (30% of VND 200 million) and would therefore pay VND 140 million in CIT.

=> In other words, the company effectively pays 70% of its applicable CIT liability. The statutory CIT rate, however, remains 20%; it is not reduced to 14%.

15% and 17% CIT Rates for Smaller Enterprises 

The 2025 Law on Corporate Income Tax introduced additional CIT rates for qualifying enterprises: 

Annual revenue condition  CIT rate 
No more than VND 3 billion  15% 
Over VND 3 billion to VND 50 billion  17% 
General rate  20% 

The law specifies that the revenue used to determine eligibility for the 15% and 17% rates is based on the total revenue of the immediately preceding CIT tax period, subject to the applicable rules. Certain types of income and enterprises are excluded from these reduced rates. 

Businesses should therefore avoid assuming that the VND 10 billion threshold under Resolution 43 and the thresholds for the 15% or 17% CIT rates operate in exactly the same way. 

Vina TPT – Accounting & Tax Services 

Vina TPT provides accounting, tax and business advisory support for companies operating in Vietnam, with experience supporting foreign-invested businesses and their ongoing compliance requirements. 

Our services cover accounting records, periodic tax declarations, CIT, VAT, PIT, foreign contractor tax, payroll and other tax-related compliance matters. 

For businesses reviewing their tax position for the 2026–2027 tax periods, our team can support the review of applicable CIT rules, tax incentives and compliance requirements based on the company’s specific circumstances. 

Need support with accounting and tax compliance in Vietnam? Contact Vina TPT to discuss your requirements. 

BOOK A FREE CONSULTATION


Vietnam Tax Updates August 2026: Key VAT, CIT, PIT, Foreign Contractor Tax, Tax Administration Changes

 vietnam-tax-updates-august-2026-cit-vat

Vietnam Tax Updates August 2026: Key VAT, CIT, PIT, Foreign Contractor Tax, Tax Administration Changes

Vietnam’s tax landscape continues to evolve, with several important changes and clarifications taking effect or being introduced in August 2026. This month’s updates cover key developments in Value Added Tax (VAT), Corporate Income Tax (CIT), Personal Income Tax (PIT), Foreign Contractor Tax (FCT), and tax administration.

Businesses and foreign-invested enterprises operating in Vietnam should pay close attention to these changes to stay compliant, avoid potential tax risks, and ensure timely adjustments to their tax and accounting practices.

New provisions regarding the tax period for newly established taxpayers and VAT refund applications for goods and services subject to the 5% VAT rate.

1. Tax calculation period for newly operating taxpayers

– According to Circular 89/2026/TT-BTC, updated and amended in Official Letter No. 5746/CT-CS dated August 10, 2026, newly established enterprises are allowed to default to quarterly VAT declarations. However, if the enterprise’s revenue in its first calendar year exceeds VND 50 billion (even if the enterprise has operated for less than 12 months in that financial year), it must mandatorily switch to monthly VAT declarations starting from the immediate next calendar year.

2. VAT Refund Dossier for Goods and Services subject to the 5% VAT rate

– New regulations govern the components of the input VAT refund application dossier for manufacturing goods and supplying services subject to the preferential 5% VAT rate. Accordingly, starting from the July 2026 tax period, taxpayers are required to declare the VAT refund claim directly on the VAT Return (Form No. 01/GTGT) and submit together with the Appendix on VAT Refund Claim Information (Form No. 01-8/GTGT) as the basis for the tax authority to review and process the refund request.

30% CIT Reduction for Tax Periods 2026 and 2027

According to the Resolution of the National Assembly on CIT reductions voted and approved on the afternoon of August 24, 2026, at the First Extraordinary Session of the 16th National Assembly

– A 30% reduction of CIT payable is granted to enterprises and organizations legally established under Vietnamese law with an annual total revenue of no more than VND 10 billion for the 2026 and 2027 tax periods. For enterprises currently enjoying other CIT incentives, the reduced tax amount will be calculated based on the actual CIT payable after deducting those existing tax incentives. For enterprises currently enjoying other CIT incentives, the reduced tax amount will be calculated based on the actual CIT payable after deducting those existing tax incentives. This Resolution takes effect from August 24, 2026, and applies directly to the tax periods of 2026 and 2027.

30% reduction of PIT payable for the tax periods of 2026 and 2027 for business individuals

Pursuant to Official Letter No. 7299/CTH-QLDN1 dated August 17, 2026 guiding the implementation of Decree No. 253/2026/NĐ-CP and the new PIT Law

30% reduction of PIT payable for the tax periods of 2026 and 2027 for business individuals

– Implementing a 30% reduction of PIT payable on income arising from production and business activities of resident individuals (including business households and individual businesses) with an annual revenue of no more than VND 10 billion.

Some Key Updates to Tax Administration Regulations

According to Circular 89/2026/TT-BTC updated in Official Letter 5746/CT-CS (August 10, 2026) and several new points in Circular 94/2026/TT-BTC

1. Shortening the time limit for tax payment extensions and late payment interest waivers

– The maximum time limit for tax authorities to assess and resolve dossiers requesting tax payment extensions, penalty waivers, or late payment interest waivers for enterprises is shortened from 10 working days to 07 working days.

2. Prioritizing tax refunds for highly compliant enterprises

According to the guidance in Circular No. 94/2026/TT-BTC on tax risk management, applying 3 risk levels: High risk, Medium risk, and Low risk

– High Risk: For taxpayers with high-risk tax refund dossiers, physical inspection at headquarters will be increased, with a mandatory “inspect first, refund later” approach applied to VAT, and post-refund audits conducted within 1 year.

– Medium Risk: For taxpayers with medium-risk tax refund dossiers: Within 03 years from the date of issuance of the refund decision, tax authorities will apply the “refund first, inspect later” method.

– Low Risk: For taxpayers with low-risk tax refund dossiers: Within 05 years from the date of issuance of the refund decision, tax authorities will apply the “refund first, inspect later” method.

3. General regulations on tax filing, calculation, and allocation

– Pending address changes: In case the tax filing deadline is due but the taxpayer has not completed procedures to change the headquarters address with the business registration authority or the tax office of the destination, the taxpayer must submit tax filing to the tax office of the departure location.

– Incorrect allocation: In case audits find that the taxpayer declared or allocated incorrectly, the directly managing tax authority will re-determine the amount to be allocated to the recipient provinces and handle administrative violations as prescribed (if any).

– No late payment interest on incorrect allocation: In case the taxpayer pays fully and on time but to the incorrect allocation area, the taxpayer will not have to pay late payment interest for the underpaid tax amount in the receiving allocation area. The directly managing tax authority will guide the taxpayer on performing a tax review or a refund-cum-offset procedure to adjust the revenue to the correct jurisdiction.

Amendment to the Tax Finalization Requirements upon Completion of a Foreign Contractor Agreement

Pursuant to Official Letter No. 5746/CT-CS dated August 10, 2026

VAT and CIT Tax Filing for Foreign Contractors and Foreign Subcontractors

– Amendments to the tax filing regulations for cases where Corporate Income Tax is calculated as a percentage of taxable revenue. Under the revised regulations, taxpayers are only required to submit a final tax declaration upon completion of a foreign contractor contract if there is a change (increase or decrease) in the amount of tax previously declared and paid.

– This completely abolishes the mandatory finalization obligation in all cases as previously required, and eliminates a series of accompanying documents such as Copies of the business registration certificate or professional practice license, a schedule of tax payment vouchers, the contract liquidation report, and appendices detailing the allocation of VAT payable by the foreign contractor to the localities entitled to receive the tax revenue.

Conclusion

The Vietnam Tax Updates August 2026 bring important changes and clarifications across VAT, CIT, PIT, Foreign Contractor Tax, and tax administration, including updates that may affect tax declarations, reporting obligations, and compliance procedures.

Businesses should review these changes carefully to understand how they may affect their tax compliance and reporting obligations, and make timely adjustments where necessary.

If you need assistance in interpreting these regulations or assessing their impact on your business, contact Vina TPT. Our accounting and tax professionals can provide practical guidance and support your business in maintaining compliance with Vietnam’s latest tax requirements.

BOOK A FREE CONSULTATION

How-to-Register-a-Company-in-Vietnam-Complete-Guide-to-IRC-and-ERC-for-Foreign-Investors

VAT Rate in Vietnam: Complete Guide to Value Added Tax Regulations

VAT Rate in Vietnam: Complete Guide to Value Added Tax Regulations

VAT Rate in Vietnam: Complete Guide to Value Added Tax Regulations

In corporate governance and financial compliance activities in Vietnam, accurately determining the VAT rate is not only a mandatory legal requirement but also a factor that directly influences pricing strategy, tax declaration efficiency, and cash flow circulation. Especially for foreign direct investment (FDI) enterprises, this tax requires the highest level of caution to minimize the risk of tax recovery or administrative penalties during operations.

Value Added Tax (VAT), or value added tax, is an important indirect tax that makes a major contribution to the state budget. It is calculated on the added value of goods and services arising throughout the entire process from production and distribution to consumption. To help enterprises gain a comprehensive understanding, this article compiles the latest regulations on the VAT rate Vietnam, provides a detailed analysis of the applicable tax rates in 2026, policy exemption and reduction cases, as well as core notes to help foreign investors ensure absolute legal compliance.

1. What is Value Added Tax (VAT) in Vietnam?

According to the Law on Value Added Tax of Vietnam, value added tax Vietnam is a tax applied to most types of goods and services used for production, business, and consumption purposes within the territory of Vietnam. The taxable objects cover a wide range, from domestic consumer goods to commercial services, excluding those items listed as non-taxable under specific provisions of the law.

Taxable subjects are defined as all organizations and individuals engaged in the production or trading of goods and services subject to VAT, or entities that import goods from abroad into Vietnam. From an economic management perspective, VAT not only ensures a stable and sustainable source of revenue for the national budget but also creates a transparent financial management mechanism through the invoice and supporting document system. A clear understanding of the nature of VAT will help foreign managers become more proactive in optimizing input costs and establishing standard compliance processes.

2. Current VAT Rates in Vietnam

The legal framework on the VAT rate Vietnam in 2026 categorizes goods and services into specialized tax rate groups in order to regulate the economy and support social welfare. The current system consists of three main tax rates along with a non-taxable group.

2.1. Standard Tax Rate of 10% and the Temporary Reduction Policy to 8% until the End of 2026

The 10% tax rate applies to most ordinary goods and services that fall outside preferential or export categories. However, to continue stimulating domestic consumption and supporting enterprises in production recovery, the Government has approved a temporary reduction of the VAT rate from 10% to 8%, which remains effective until 31 December 2026.

Enterprises should note that this 8% reduction policy does not apply universally across all sectors. Certain groups of goods and services are still required to apply the standard 10% rate, including:

  • Telecommunications services, financial activities, banking, securities, and insurance.
  • Real estate business and products from metals or mining products (excluding coal).
  • Goods subject to Special Consumption Tax (SCT) such as alcohol, beer, tobacco, and automobiles with fewer than 24 seats.

VAT Rate

Main Scope of Application

Practical Examples

8% (Until 31/12/2026) Ordinary consumer goods and services normally subject to 10% that are eligible for reduction. Consumer goods, food & beverage services, domestic logistics, processing manufacturing.
10% (Standard) Specific sectors not eligible for the VAT reduction. Telecommunications, banking, real estate, goods subject to Special Consumption Tax.
5% Essential goods and services, agriculture, healthcare, and education. Clean water, medical equipment, medicines, fertilizers, social housing.
0% Goods and services exported abroad or to non-tariff zones. Exported goods, international transportation, services provided to foreign partners.

2.2. Goods and Services Subject to 5% VAT Rate

The 5% tax rate is a preferential policy of the State applicable to groups of essential goods and services that serve people’s livelihoods, agricultural development, and social infrastructure. Common groups include:

Clean water used for production and daily living purposes (excluding bottled or containerized drinking water). Fertilizers, plant protection products, plant and animal growth stimulants. Medicines, vaccines, medical biological products, and specialized medical equipment and instruments. Teaching aids, educational materials, and specialized books. Certain agricultural, forestry, and aquatic products that have not been processed or have only undergone ordinary preliminary processing at the commercial trading stage, as well as social housing sale and lease projects as prescribed.

VAT Rate in Vietnam: Complete Guide to Value Added Tax Regulations

2.3. 0% VAT Rate and Exempt Cases

The 0% tax rate is designed to encourage export activities and enhance the competitiveness of Vietnamese products in the international market. The scope of application of the 0% rate includes goods exported abroad, goods sold into non-tariff zones for export production, international transportation services, and services provided directly to organizations and individuals overseas.

In addition, the law also specifies a list of VAT-exempt objects, such as self-produced agricultural products sold by the producers themselves, transfer of land use rights, credit services, securities, life insurance, and public healthcare and education services.

Core distinction between “0% Tax Rate” and “VAT-Exempt”:

  • 0% Tax Rate: The enterprise remains within the scope of VAT, and is therefore entitled to deduct and fully refund all input VAT paid on related production and business costs.
  • VAT-Exempt: The enterprise does not charge output VAT, but at the same time is not entitled to deduct or refund input VAT. This input tax must be included in production and business costs or the original cost of assets.

3. Key Compliance Requirements Related to VAT Rate

To maintain legal compliance and optimize the amount of deductible tax, enterprises must strictly comply with the current tax administration regulations:

Enterprises must fulfill their VAT declaration and payment obligations on a monthly or quarterly basis, depending on the total revenue of the immediately preceding year (enterprises with annual revenue of VND 50 billion or more are required to declare monthly). To be eligible for input VAT deduction, the enterprise must fully meet three mandatory conditions: possession of a valid VAT invoice; non-cash payment documents for invoices valued at VND 5 million or more (including tax); and the purchased goods or services must be used directly for the production or trading of goods and services subject to VAT.

In addition, the use of electronic invoices (with or without the tax authority’s code) is 100% mandatory. If an enterprise applies an incorrect VAT rate (for example, issuing an invoice at 8% for goods subject to the 10% rate), the enterprise will not only have to pay the underpaid tax and late payment interest but will also face serious administrative tax penalties.

EXPLORE TAX FILLING SERVICES

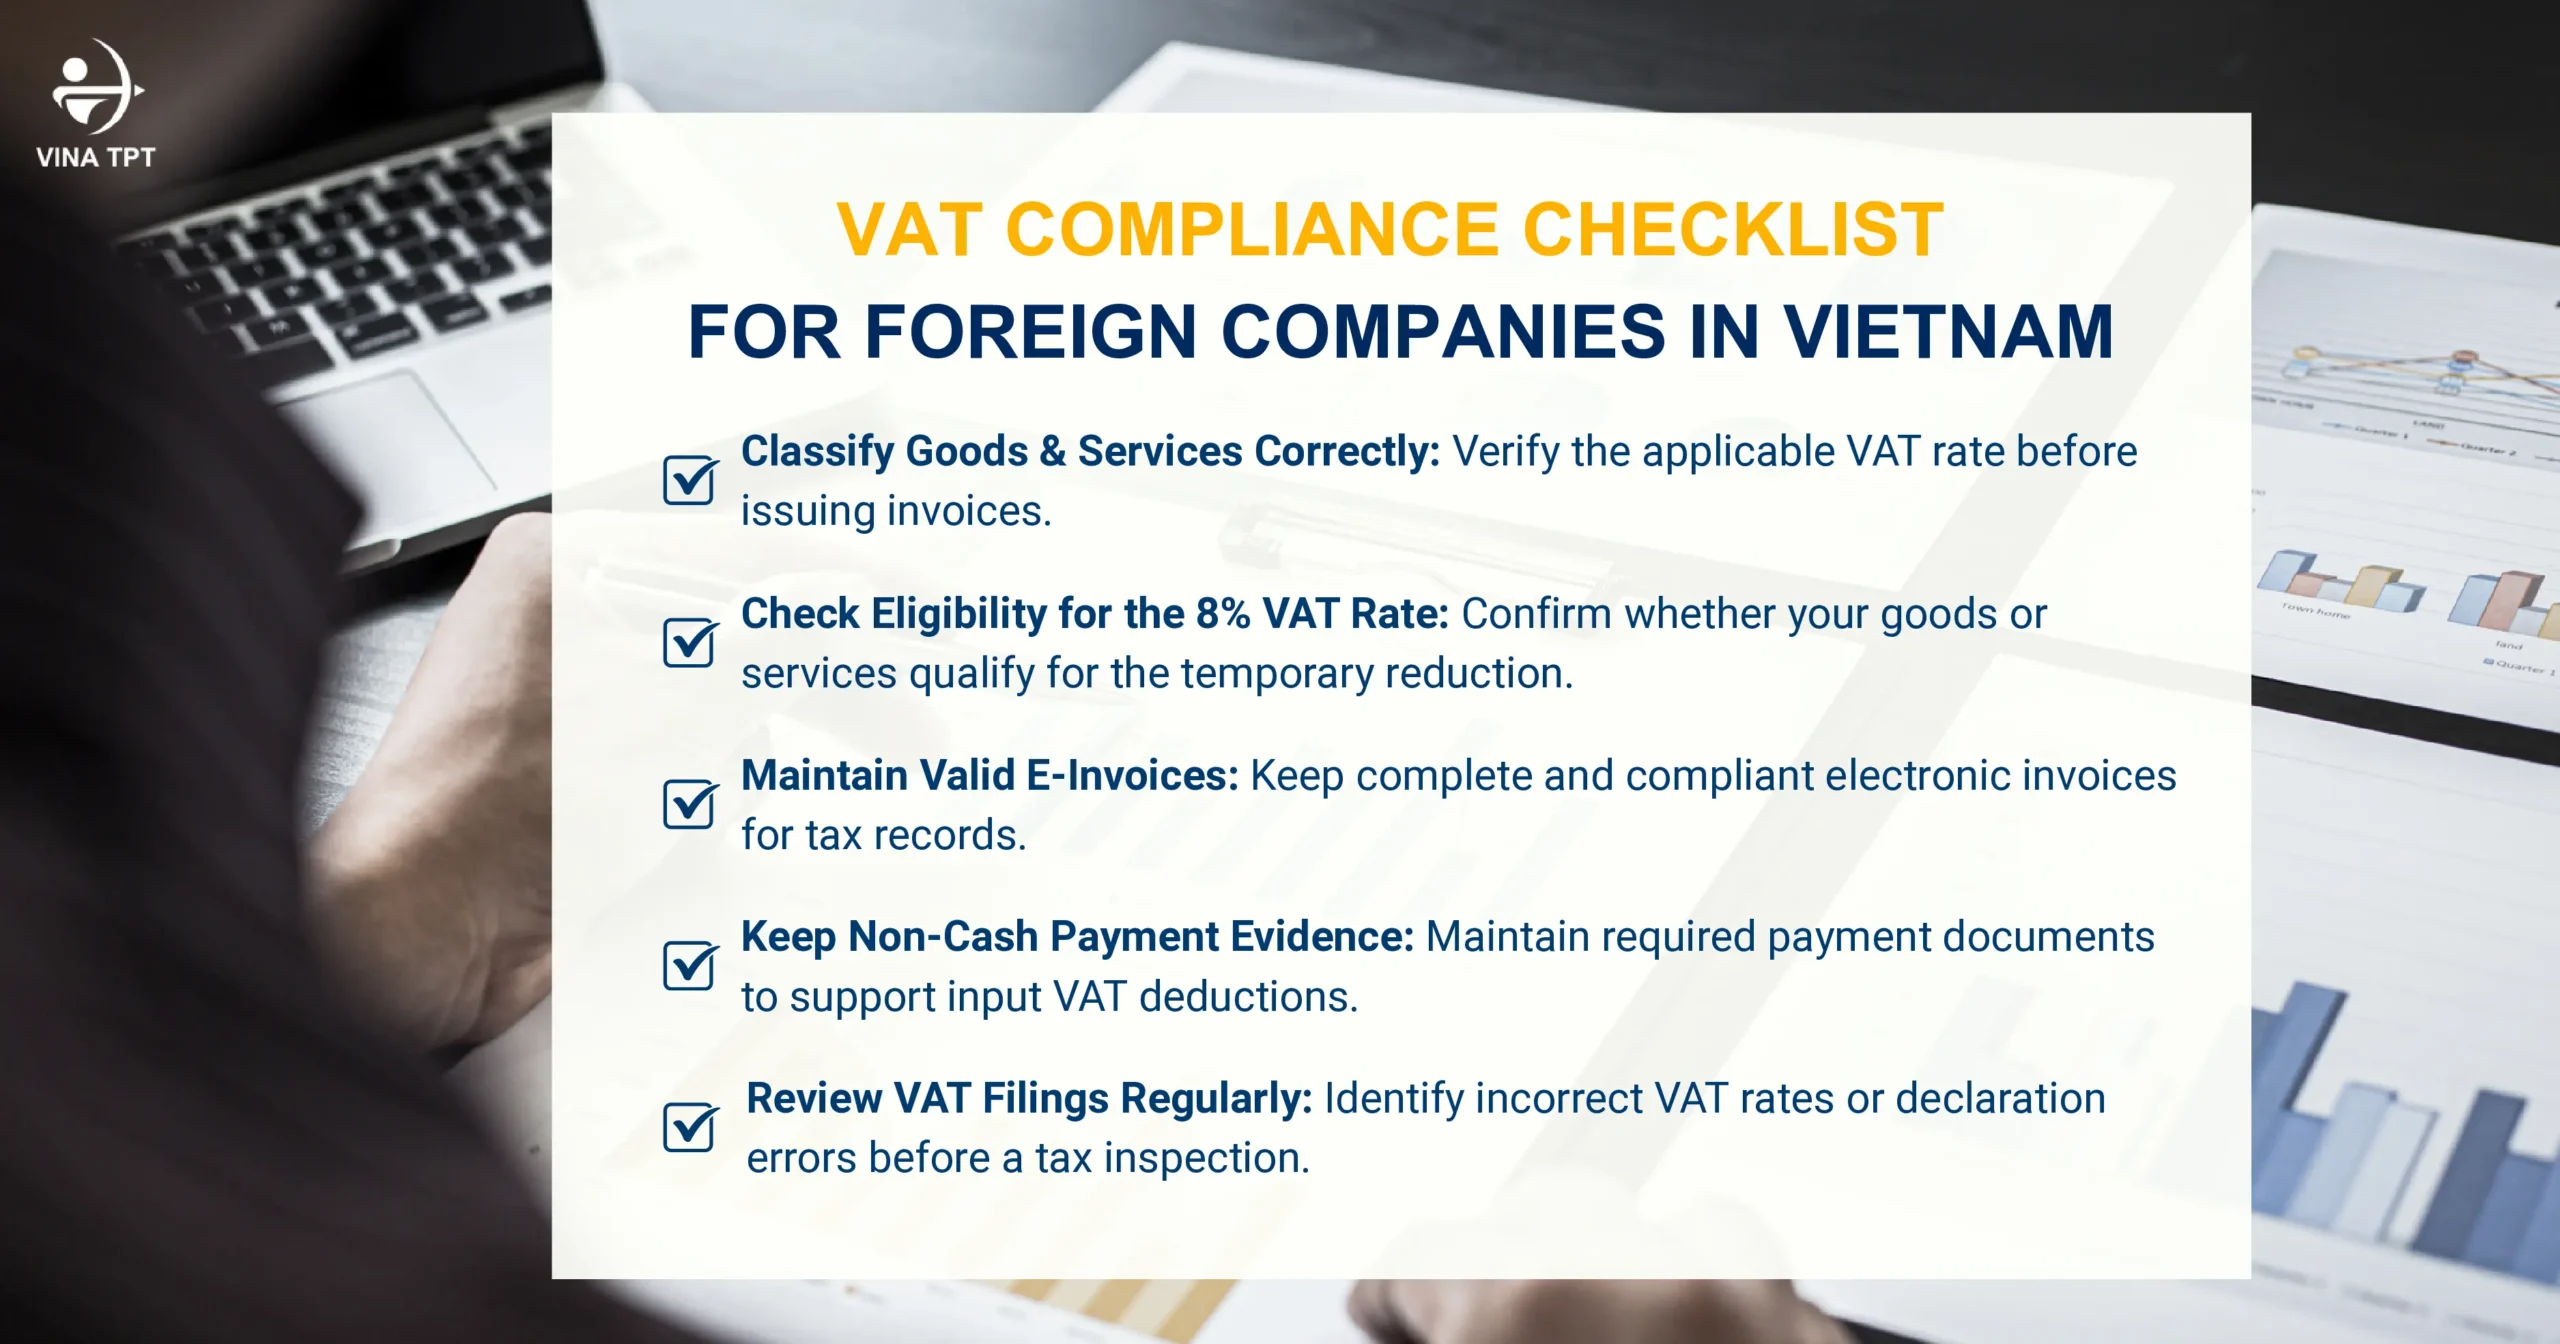
4. Practical Tips for Foreign Companies

To minimize financial errors when operating a business in Vietnam, foreign managers should keep the following practical experiences in mind:

Establish a process to accurately check and classify the enterprise’s goods and service categories right from the input stage. Because the 8% tax reduction policy contains many complex exceptions, the accounting department must carefully cross-check the economic industry codes and HS codes of the products to apply the correct tax rate.

Systematically store and organize all electronic invoices together with bank payment documents. This is the only legal basis that enables the enterprise to protect its rights to input VAT deduction and refund when the competent authorities conduct tax inspections or audits.

Proactively carry out periodic internal tax reviews (tax audits) of the tax declaration process to detect and correct errors in a timely manner before the Tax Authorities issue an inspection decision. In cases where the internal team does not have a deep understanding of the local tax legal system, the enterprise should consider cooperating with professional tax agency firms to ensure operational safety.

VAT Rate in Vietnam: Complete Guide to Value Added Tax Regulations

5. How Vina TPT Supports VAT Compliance

As a reputable firm specializing in financial consulting and tax compliance for FDI enterprises, Vina TPT provides comprehensive support solutions that help businesses optimize their VAT processes:

  • Tax Rate Consulting & Classification: Accurate assessment of product categories and advice on applying the correct VAT rate (clearly distinguishing between the 8%, 10%, 5%, and 0% groups).
  • Periodic Tax Declaration & Reporting: Preparation and submission of accurate monthly/quarterly VAT declarations in full compliance with statutory deadlines.
  • Input Deduction Review & Tax Refund Services: Appraisal of input invoice dossiers and representation of the enterprise in carrying out VAT refund procedures for investment projects and export activities.
  • Support During Tax Inspections: Direct explanation, protection of data, and safeguarding of the enterprise’s legitimate rights before the tax management authorities.

Conclusion

In summary, mastering the regulations on the VAT rate and accurately complying with the VAT declaration process is the golden key that enables FDI enterprises to operate safely, transparently, and sustainably in Vietnam.

Is your enterprise facing difficulties in determining the correct VAT rate or in need of professional tax declaration support? Contact Vina TPT today for a free consultation and experience our standard full-package accounting and tax services.

BOOK A FREE CONSULTATION

How Recent Vietnam Tax Reforms Impact FDI Business Accounting Requirements

vietnam-tax-reforms-impact-fdi-business-accounting

Vietnam business accounting and tax landscape is undergoing sweeping structural reforms between 2025 and 2026. Foreign Direct Investment (FDI) enterprises must align with five critical regulatory shifts: Decree 70/2025/ND-CP (e-invoicing rules), Circular 99/2025/TT-BTC (new accounting framework replacing Circular 200), the 2024 Value Added Tax (VAT) Law (effective July 1, 2025), the 2025 Corporate Income Tax (CIT) Law No. 67/2025/QH15, and the 2025 Personal Income Tax (PIT) Law. 

This guide examines the business impacts of Vietnam’s 2025–2026 tax and accounting reforms on foreign-invested firms under Vietnamese Accounting Standards (VAS).  

  • Key Overview: Recent Tax & Accounting Regulatory Reforms in Vietnam   
  • 5 Major Ways Tax Reforms Directly Affect FDI Business Accounting Requirements   
  • Comprehensive Business Accounting Services Tailored for FDI Enterprises 
  • Frequently Asked Questions 

Key Overview: Recent Accounting and Tax Regulatory Reforms in Vietnam 

The General Department of Taxation (GDT) and the Ministry of Finance (MOF) in Vietnam are rapidly accelerating digital tax administration, big-data cross-reconciliation, and international compliance integration. The modern regulatory environment leaves zero margin for record-keeping delays or bookkeeping discrepancies. 

For foreign-invested enterprises operating across Ho Chi Minh City (TPHCM), Hanoi, and key industrial zones, tax and accounting compliance is no longer a passive administrative routine. Regulatory compliance directly influences cash flow timing, profit repatriation, transfer pricing audit exposure, and corporate reputation. Understanding the full scope of informational and navigational requirements across legislative mandates is essential for maintaining tax health and operational continuity in Vietnam. 

Timeline of Critical Accounting and Tax Changes (2025–2026) 

  • 01/06/2025 — Decree 70/2025/ND-CP: Amends e-invoice regulations, enforcement mechanisms, data submission timing, and mandatory invoice contents. Introduces strict cut-offs for customs-linked transaction recording. 
  • 01/07/2025 — Law on VAT 2024 (Law No. 48/2024/QH15): Officially comes into force, tightening input VAT deduction criteria, mandating non-cash payment verification, and restricting VAT refund eligibility for export-import and investment projects. 
  • 01/10/2025 — Law on CIT 2025 (Law No. 67/2025/QH15): Takes effect for the 2025 tax year onwards, overhauling deductible expense conditions, related-party transaction controls, and foreign enterprise taxation rules. 
  • 01/01/2026 — Circular 99/2025/TT-BTC: Enforces a modernized accounting system replacing the decades-old Circular 200/2014/TT-BTC framework, altering chart of accounts, foreign exchange treatments, and financial statement presentations. 
  • 01/07/2026 — Law on Personal Income Tax 2025: Officially applies to individual income tax calculations, streamlining tax brackets and adjusting personal and dependent relief thresholds. 

5 Ways Accounting & Tax Reforms Impact FDI Business Accounting Requirements 

The convergence of these regulatory updates shifts tax compliance from periodic reporting to real-time verification. For FDI enterprises operating in Vietnam, structural mismatches between accounting entries, bank settlement records, customs declarations, and tax filings will automatically trigger tax authority risk alerts.

Decree 70/2025/ND-CP: Stricter E-Invoice and Transaction Recording Requirements

Decree 70/2025/ND-CP fundamentally alters the operational rules governing e-invoice generation, content accuracy, and timing. One of the most vital changes for export-oriented FDI companies is the strict requirement that e-invoices for exported goods must be issued no later than the next working day after customs clearance completion. 

Furthermore, Decree 70/2025 clarifies e-invoice requirements for cross-border digital services, software licenses, and complex intercompany transactions requiring multi-system data reconciliation. Accounting teams can no longer delay issuing invoices until month-end or quarter-end closing. Sales recognition, invoice logs, customs clearance timestamps, and tax declaration periods must be tightly aligned to avoid severe timing mismatch penalties. 

Expert Insight (Decree 70/2025): 

This is far more than an administrative “e-invoice compliance” task. For FDI enterprises engaged in import/export or cross-border intercompany service charges, an incorrect invoice issuance date directly disrupts revenue recognition timing under VAS/IFRS and invalidates 0% export VAT treatment during tax audits. 

Circular 99/2025/TT-BTC: New Accounting and Financial Reporting Requirements

Effective from January 1, 2026, Circular 99/2025/TT-BTC officially replaces the long-standing Circular 200 accounting regime. This represents the most comprehensive accounting overhaul in Vietnam over the past decade, introducing updated rules for accounting vouchers, the statutory chart of accounts, general ledger posting routines, foreign-exchange difference treatments, and year-end financial statement disclosures. 

Foreign-invested companies operating in Vietnam must systematically update their ERP systems (e.g., SAP, Oracle, Microsoft Dynamics) and local chart-of-accounts mapping. Simply rolling forward previous bookkeeping setups will result in non-compliant statutory financial statements, blocking profit remittance approvals from the State Bank of Vietnam (SBV) and tax authorities. 

Expert Insight (Circular 99/2025): 

Circular 99 is the cornerstone change for business accounting services. It directly dictates how transactions are recorded, books are closed, and statutory financial statements are compiled. FDI management must conduct an immediate ERP chart-of-accounts gap analysis prior to the 2026 fiscal year. 

EXPLORE ACCOUNTING SERVICES FOR FDI BUSINESS

2025 Personal Income Tax Law: Major Changes to Payroll Tax Calculations

Beginning in the 2026 tax assessment year, Vietnam’s Personal Income Tax system transitions from seven progressive tax brackets down to five streamlined tax brackets. Simultaneously, the personal deduction allowance increases to VND 15.5 million per month (VND 186 million annually), and the dependent allowance increases to VND 6.2 million per month per dependent. 

FDI employers employing expatriates, key foreign executives, and high-earning local personnel must reconfigure their HR payroll engine, employee tax profiles, dependent documentation archives, and monthly tax withholding logic. Given that expatriate compensation often involves gross-up packages, housing allowances, and school fee benefits, accurate PIT withholding calculations are vital to control corporate payroll costs. 
Expert Insight (2025 PIT Law): 

With foreign experts and senior management earning high income packages, the shift in progressive tax brackets directly recalibrates net compensation, tax gross-up expenses, and monthly corporate cash flow projections. Payroll accounting must be seamlessly integrated with corporate tax compliance. 

2025 Corporate Income Tax Law: Greater Focus on Taxable Income and Deductible Expenses

The 2025 Corporate Income Tax Law (No. 67/2025/QH15), effective October 1, 2025 and applicable to the 2025 tax year, establishes stringent conditions for deductible expenses, taxable income determination, tax incentive eligibility criteria, and foreign contractor income taxation. Foreign-invested businesses face heightened documentation standards for intercompany management fees, technical consulting services, trademark royalties, and interest deductions under transfer pricing rules (Decree 132/2020/ND-CP framework). 

Accounting teams must establish robust internal controls to substantiate economic substance, benefit tests, and direct transfer pricing documentation for all related-party transactions prior to year-end tax finalization. 

Expert Insight (2025 CIT Law): 

For FDI companies, CIT compliance extends far beyond multiplying accounting profit by 20%. The core challenge lies in proving that overseas parent company charges—such as regional management fees, IT allocations, and royalty fees—are fully deductible under Vietnamese tax rules with adequate supporting dossier proof. 

2025 Value Added Tax Law: Stricter Input VAT Deduction and Payment Controls

Enforced from July 1, 2025, the 2024 VAT Law drastically tightens input VAT deduction rules. Most notably, the statutory threshold for mandatory non-cash payment documentation is reduced from VND 20 million down to VND 5 million (VAT-inclusive) for any purchase transaction. Furthermore, transaction aggregation rules prevent split-invoicing tactics designed to bypass bank transfer requirements. 

Under these stricter rules, tax officers will automatically disallow input VAT deductions and corresponding CIT expense deductions if payment records fail to match the official corporate bank account of the issuing vendor. 

Expert Insight (2025 VAT Law): 

In daily accounting practice, accountants cannot merely verify whether an e-invoice is authentic on the GDT portal. They must perform a 3-way match: valid e-invoice + compliant non-cash payment proof + transaction contract/delivery note. Any flaw in payment evidence will trigger input VAT clawbacks and tax interest penalties. 

Vina TPT: Comprehensive Business Accounting Services Tailored for FDI Enterprises 

Vina TPT is a premier business consultancy and accounting firm operating in Ho Chi Minh City (TPHCM) and key economic hubs across Vietnam. We specialize in empowering Foreign Direct Investment (FDI) companies, foreign contractors, and multinational branches to navigate Vietnam’s complex regulatory environment with absolute financial clarity and 100% legal compliance.

Our tailored business accounting services bridge the critical gap between international financial management standards (IFRS/US GAAP) and mandatory Vietnamese statutory requirements (VAS, Circular 99/2025, GDT tax laws). 

Why Leading FDI Enterprises Choose Vina TPT: 

  • Full-Scope VAS & IFRS-Compliant Bookkeeping: Accurate monthly bookkeeping and statutory financial reporting under Vietnamese Accounting Standards (VAS) and IFRS upon request, delivered with comprehensive monthly management reports and dedicated bilingual accounting professionals. 
  • Periodic VAT Compliance & Filing: Complete preparation and timely filing of monthly or quarterly Value Added Tax (VAT) returns. 
  • Payroll Processing & Social Insurance Management: End-to-end payroll administration, precise salary calculations, gross-up tax modeling, and seamless handling of mandatory Social Insurance (SI/HI/UI) compliance and employee profiles. 
  • PIT Calculation & Periodic Tax Filing: Compliant Personal Income Tax (PIT) computation for both local and expatriate employees, dependent registrations, and preparation of periodic PIT declarations and annual tax finalizations. 
  • FDI Investment & Statutory Reporting: Timely preparation and submission of mandatory periodic investment activity reports to foreign investment authorities (MPI/DOIT), ensuring strict regulatory compliance for FDI projects. 
  • Back-Office & Document Administration: Comprehensive operational support including e-invoice issuance, systematic archiving of physical and digital accounting vouchers, and management of statutory business records. 
  • Proactive Tax Advisory & Regulatory Updates: Continuous monitoring and real-time updates on new tax and accounting regulations, backed by proactive advisory support to resolve operational queries and shield your business from compliance risks. 

Frequently Asked Questions (FAQ)

The 2025 CIT Law maintains tax incentives (e.g., 10-17% preferential tax rates, tax holidays, and 50% reduction periods) for targeted sectors like high-tech, green energy, and encouraged industrial zones. However, FDI firms must meet strict substance rules, investment capital disbursements, and accurate VAS accounting tracking under Circular 99 to retain these tax incentive benefits. 

FDI companies must submit monthly VAT and PIT returns by the 20th of the following month (or quarterly by the last day of the month following the quarter). Annual CIT finalization, PIT finalization, and audited financial statements prepared under VAS must be submitted within 90 days from the end of the fiscal year. 

No. All companies legally incorporated in Vietnam are strictly required to maintain statutory accounting records and submit tax returns in accordance with Vietnamese Accounting Standards (VAS) and Circular 99/2025/TT-BTC. While parent companies may request IFRS management reports, VAS remains the sole legal basis for local tax compliance and profit remittance. 

Need Professional Accounting & Tax Support for Your FDI Business? 

Contact Vina TPT today for a free consultation and customized solution tailored to your compliance needs! 

BOOK A FREE CONSULTATION

business-accounting-services


New Accounting and Tax Rules from July 2026: Important Notes for Compliance

new-accounting-and-tax-rules-from-july-2026-important-notes-for-compliance

new-accounting-and-tax-rules-from-july-2026-important-notes-for-compliance

1. From July 1, 2026, a series of important legal changes in the fields of accounting and tax officially take effect. The key focuses of this reform package include Decree 253/2026/ND-CP (guiding personal income tax), Circular 58/2026/TT-BTC (the new accounting regime), and the Tax Administration Law 2025 (Law on Tax Administration No. 108/2025/QH15).

For FDI enterprises, Accounting Departments, and Human Resources (HR) teams, these adjustments are not merely changes in administrative procedures. They directly impact payroll calculation processes, social insurance contributions, tax withholding, and the preparation of financial statements. Delays or inaccurate application of the new regulations can lead to declaration errors, administrative penalties, and strict inspections from the tax authorities.

This article summarizes the core new points together with practical notes to help businesses ensure tax compliance, proactively eliminate legal risks, and operate cash flow safely from the July 1, 2026 milestone.

5 Important Changes to Personal Income Tax under Decree 253/2026/ND-CP

Decree 253/2026/ND-CP introduces fundamental adjustments that directly affect personal income tax (PIT) obligations, which Accounting and Payroll departments must implement immediately:

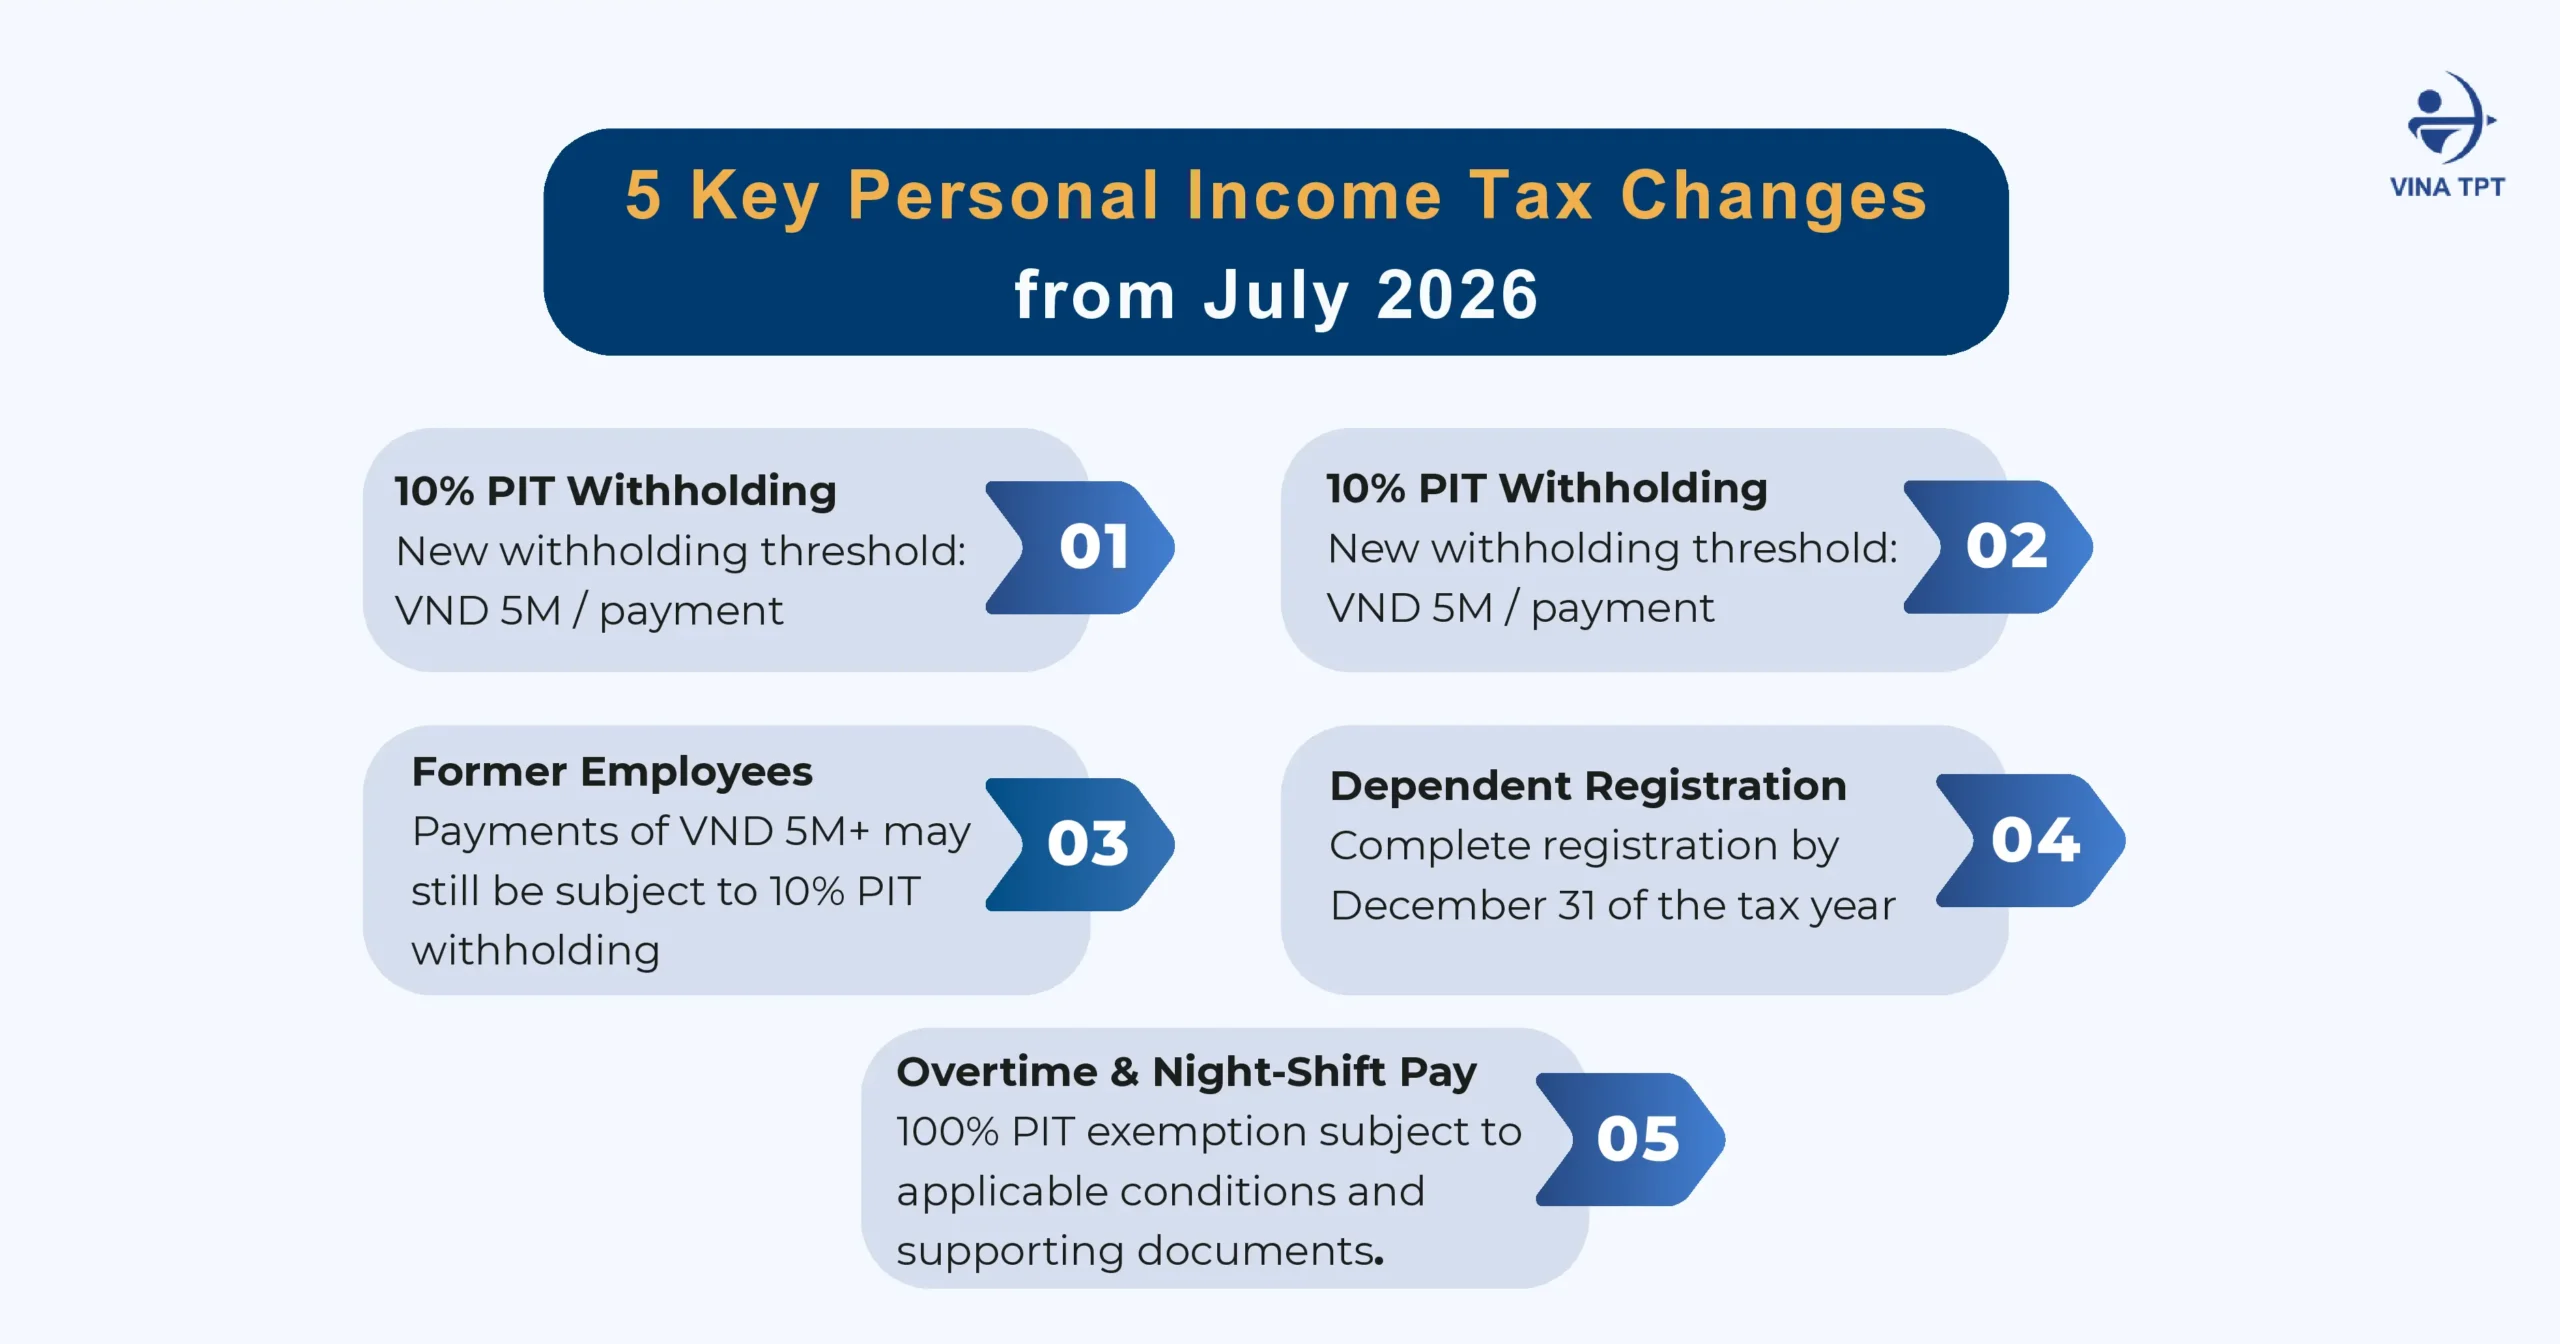
1. Mid-shift / lunch meal allowance – tax-exempt up to VND 1.2 million per person per month

Pursuant to Point g, Clause 2, Article 8 of Decree 253/2026/ND-CP, from July 1, 2026, the tax exemption for mid-shift meal allowances is tightened under a fixed limit:

  • Cash payment: The mid-shift or lunch meal allowance paid in cash by the enterprise to employees is exempt from PIT up to a maximum of VND 1.2 million per person per month. Any amount exceeding this limit must be included in taxable income subject to PIT.
  • In-kind payment / meal vouchers: If the enterprise directly organizes a canteen, purchases industrial meal portions, or issues meal vouchers, the entire value of the meals is exempt from PIT, regardless of the form of payment.

Important note: The new regulation abolishes the previous principle that “whatever amount the enterprise stipulates in its internal regulations is exempt.” Accountants must review the company’s Financial Regulations and Labor Contracts to adjust payment norms to ensure compliance.

2. Increase in the 10% PIT withholding threshold to VND 5 million per payment

According to Clause 2, Article 50 of Decree 253/2026/ND-CP:

  • Organizations paying income are required to withhold 10% personal income tax (PIT) only when the payment reaches VND 5 million or more per time for individuals who have not signed a labor contract or have signed a labor contract of less than 3 months (replacing the previous threshold of VND 2 million per payment).
  • For payments below VND 5 million per time, the enterprise is not required to withhold the 10% tax, unless the individual specifically requests it.
  • Individuals who estimate that their total income after family deductions has not yet reached the taxable threshold may still submit a Commitment Letter to the enterprise to temporarily avoid the 10% withholding.

3. Salary and bonus payments to former employees still require 10% withholding

Decree 253/2026/ND-CP clarifies the withholding obligation for payments arising after the termination of the employment relationship. When an enterprise pays salary, bonuses, commissions, or other support amounts of VND 5 million or more per payment to former employees, the enterprise is required to withhold personal income tax (PIT) at the rate of 10%. Omitting this obligation will result in the enterprise being subject to additional tax assessments and late-payment penalties during the annual tax finalization.

4. Stricter deadline for registering dependents – before 31 December

Pursuant to Clause 2, Article 48 of Decree 253/2026/ND-CP, registration for family circumstance deductions for dependents must be completed before 31 December of the tax year. If the registration dossier is submitted after this deadline, the employee will not be entitled to the family circumstance deduction for that tax year, directly affecting the individual’s tax finalization benefits.

5. 100% tax exemption on overtime and night-shift pay

According to Article 26 of Decree 253/2026/ND-CP:

  • Enterprises are exempt from personal income tax (PIT) on the entire amount of overtime pay and night-shift pay, provided the conditions under the Labor Code are fully met (replacing the previous rule that only exempted the differential portion compared with normal working-day pay).
  • Conditions for application: The enterprise must maintain complete supporting documentation (night-shift/overtime timesheets, payroll calculations, and overtime assignment documents).
  • Effective date: Applicable from 1 January 2026 for resident individuals and from 1 July 2026 for non-resident individuals.

new-accounting-and-tax-rules-from-july-2026-important-notes-for-compliance

Circular 58/2026/TT-BTC: New Accounting Regime for Micro-Enterprises

In addition to tax regulations, the accounting and tax regime from July 1, 2026, marks an important change with the Ministry of Finance’s issuance of Circular 58/2026/TT-BTC (completely replacing Circular 132/2018/TT-BTC).

Circular 58/2026/TT-BTC provides detailed guidance on accounting documents, accounting books, and the preparation and presentation of financial statements for micro-enterprises, helping to simplify the accounting apparatus while still ensuring legal transparency.

Criteria for identifying a Micro-Enterprise (under Decree 80/2021/ND-CP):

  • Agriculture – Forestry – Fishery, Industry & Construction sectors: Average number of employees participating in social insurance per year does not exceed 10 people AND total annual revenue does not exceed VND 3 billion (or total capital does not exceed VND 3 billion).
  • Trade & Services sectors: Average number of employees participating in social insurance per year does not exceed 10 people AND total annual revenue does not exceed VND 10 billion (or total capital does not exceed VND 3 billion).
  • Flexible choice of accounting regime:

Micro-enterprises have the right to choose to apply the Accounting Regime for Small and Medium-sized Enterprises (Circular 133/2016/TT-BTC) if it better suits their management needs. However, the chosen accounting regime must be applied consistently throughout an entire financial year; any change of regime may only be made at the beginning of the following accounting year.

  • Financial Statement System for Micro-Enterprises:

Micro-enterprises that pay corporate income tax using the method based on taxable income must prepare annual financial statements in accordance with the guidance in Circular 58/2026/TT-BTC, including:

  • Statement of Financial Position (Form B01 – DNSN).
  • Income Statement (Form B02 – DNSN).

Key Points to Note under the Tax Administration Law 2025

The Tax Administration Law 2025 (Law on Tax Administration No. 108/2025/QH15, promulgated on 10 December 2025) takes effect from 1 July 2026. It introduces stricter sanctions to strengthen declaration discipline and enhance the transparency of electronic invoice data.

Shortening of the time limit for supplementary tax declaration dossiers to 5 years

One of the core changes that Accounting teams must particularly note under Clause 5, Article 12 of the Tax Administration Law 2025 is: The time limit allowing taxpayers to self-detect errors and submit supplementary declaration dossiers has been shortened from 10 years to 5 years, counted from the deadline for submitting the tax declaration dossier of the tax period containing the error.

Taxpayers may perform supplementary declarations within the 5-year period in the following cases:

  1. The supplementary declaration is made before the tax authority or competent authority issues a Decision on tax inspection or examination at the taxpayer’s premises.
  2. The supplementary tax declaration dossier does not fall within the scope and period of the inspection stated in the Inspection Decision.
  3. The dossier is not related to a case in which the investigating authority has requested that the status quo be maintained to serve a criminal investigation.

Risk warning: Shortening the adjustment period to 5 years requires enterprises to strengthen annual internal audits of accounting books, rather than allowing errors to accumulate over a longer period as in the past.

new-accounting-and-tax-rules-from-july-2026-important-notes-for-compliance

Immediate Actions FDI Enterprises Need to Take for Compliance

To maintain absolute tax compliance and optimize operating costs under the new regulations effective from 1 July 2026, FDI enterprises should immediately implement the following actions:

  • Review Salary & Benefit Policies: Adjust the mid-shift meal allowance (cap at VND 1.2 million per month if paid in cash) and the regulations on overtime and night-shift pay within the payroll software system.
  • Update the 10% Tax Withholding Process: Configure the accounting system to apply the new 10% withholding threshold for payments of VND 5 million or more per time to casual workers and former employees.
  • Accelerate Standardization of Dependents: Urge employees to complete supporting documents and submit family circumstance deduction registrations before 31 December.
  • Check the Synchronization of Accounting & Tax Data: Review the consistency between sales software, the electronic invoice system, and VAT/CIT tax declarations.
  • Update Enterprise Information: Review the head office address, lease agreements, and legal representative information on the enterprise registration portal to avoid being classified by the tax authorities as a “high-risk taxpayer.”

Conclusion

The legal changes in accounting and tax effective from 1 July 2026 present a challenge of rapid adaptation for Accounting and HR teams. Proactively reviewing accounting processes, updating new tax policies, and controlling electronic invoice data are the keys that help FDI enterprises operate safely, transparently, and sustainably in Vietnam.

The entire adjustment process must be carried out rigorously to maximize benefits for employees and protect the enterprise against tax inspections.

Follow the News & Insight & News section of Vina TPT for continuous updates on the latest in-depth analyses of Accounting and Tax policies in Vietnam.

BOOK A FREE CONSULTATION

Vietnam Tax Updates July 2026: Key VAT, PIT, Transfer Pricing and E-Invoice Changes

vietnam-tax-updates-july-2026

Vietnam Tax Updates July 2026: Key VAT, PIT, Transfer Pricing and E-Invoice Changes

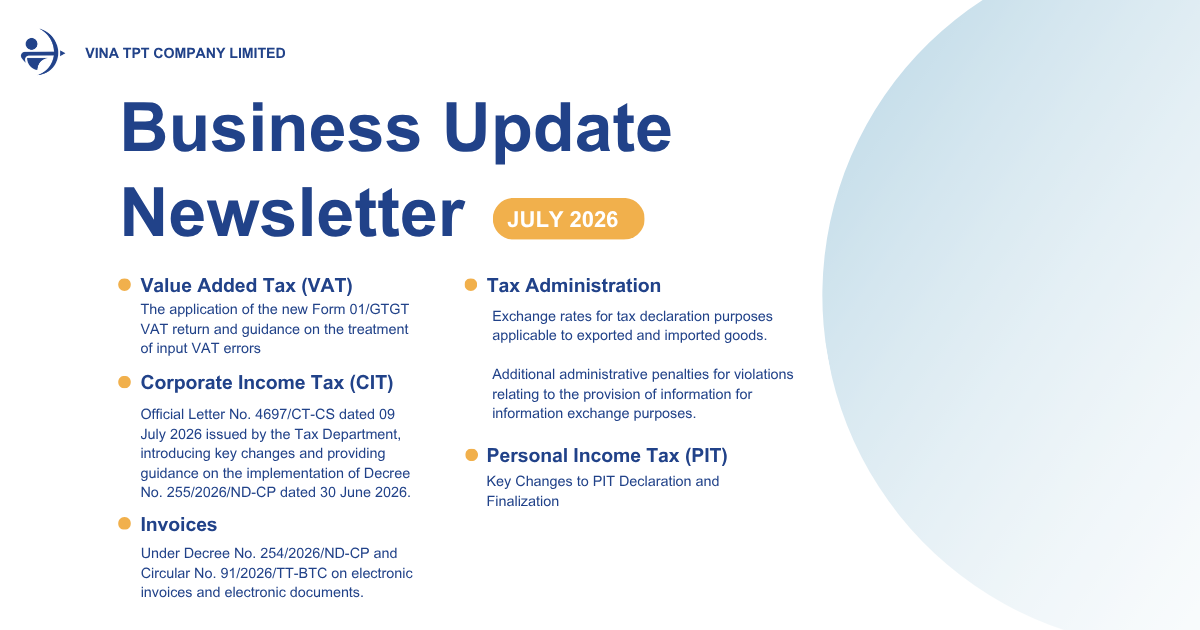
The Vietnam Tax Updates July 2026 introduce several important changes and clarifications affecting VAT declaration, input VAT adjustments, related-party transactions, transfer pricing documentation, Personal Income Tax (PIT), tax exchange rates, tax information disclosure penalties, and electronic invoices.

Businesses should pay close attention to these updates to ensure accurate tax declarations, comply with applicable reporting requirements, and manage their tax obligations effectively.

1. Regarding the application of the new Form 01/GTGT VAT return and guidance on the treatment of input VAT errors under items [37] and [38]: 

Circular No. 89/2026/TT-BTC dated 30 June 2026, applicable from the July 2026 tax period or Q3/2026.

1.1 Form 01/GTGT VAT return:

– Addition of item [32b]: Goods and services sold that are not included in the value-added tax taxable price 

– Addition of item [34a]: Goods and services sold that are outside the scope of the value-added tax regulations.

1.2 Guidance on the treatment of input VAT errors through items [37] and [38]:

– For goods and services purchased on deferred payment or installment terms with a purchase value of VND 5 million or more, the business shall declare and reduce the deductible input VAT corresponding to the portion of the purchase value for which no non-cash payment supporting document is available in item [37] of the tax period in which the payment obligation arises under the contract or contract appendix, without filing a supplementary tax return. If, after such adjustment, the business obtains a non-cash payment supporting document, it may declare and deduct the input VAT corresponding to the portion of the purchase value supported by the non-cash payment document in item [38] of the tax period in which such document is obtained. 

– Where a taxpayer discovers an error or omission in the input VAT previously declared and deducted, the adjustment shall be declared in item [37] or [38] of the month or quarter in which the error or omission is discovered if declaring the adjustment in the month or quarter in which the erroneous input VAT arose would reduce the tax payable or would only increase or decrease the input VAT credit carried forward to the following period, without filing a supplementary tax return. 

– Where the buyer receives an adjusted invoice or replacement invoice in the cases prescribed in Clause 5, Article 10 of Circular No. 91/2026/TT-BTC dated 30 June 2026 of the Ministry of Finance, the adjustment shall be declared in item [37] or [38] of the tax period in which the adjusted invoice or replacement invoice is received, without filing a supplementary tax return. 

– Where a taxpayer changes its VAT calculation method from the credit method to the direct method based on revenue, the taxpayer shall declare a reduction of any remaining uncredited input VAT in item [37] of the final tax period before changing the VAT calculation method, without filing a supplementary tax return.

2. Regarding related-party transactions 

Another important area covered by the Vietnam Tax Updates July 2026 is related-party transactions and transfer pricing.

Official Letter No. 4697/CT-CS dated July 9, 2026, issued by the Tax Department, introduces key changes and provides guidance on the implementation of Decree No. 255/2026/ND-CP dated June 30, 2026.

2.1 Related Party Relationship (Article 5)

A related-party relationship has been expanded to include borrowing and lending arrangements in a manner similar to loan transactions under Point l, Clause 2, Article 5 of the Decree, as follows: 

“An enterprise that engages in transactions involving the transfer or receipt of capital contributions representing at least 25% of the owner’s contributed capital during the tax period; or that borrows, lends, receives on loan, or provides on loan an amount equivalent to at least 10% of the owner’s contributed capital at the time the transaction arises during the tax period with an individual who manages or controls the enterprise, or with an individual having a relationship specified in Point g of this Clause.”

2.2 Exemption from preparing Transfer Pricing Documentation (Point c, Clause 2, Article 20)

– The Decree increases the revenue threshold for taxpayers eligible for exemption from preparing Transfer Pricing Documentation to less than VND 500 billion, while removing the requirement that the taxpayer must operate under a “simple functional profile.” 

Previously, taxpayers were required to satisfy all four of the following conditions to qualify for the exemption: (i)Conducting business with a simple functional profile; (ii)Not generating revenue from, incurring expenses related to, or utilizing intangible assets; (iii) Having annual revenue below VND 200 billion; (iv) Achieving the prescribed net profit margin applicable to the relevant business sector. 

– The increase in the revenue threshold and the removal of the “simple functional profile” criterion are intended to broaden the scope of low tax-risk taxpayers eligible for the exemption, simplify the application requirements, and reduce compliance costs and administrative burdens for taxpayers. 

3. Key Changes to PIT Declaration and Finalization. 

Circular No. 89/2026/TT-BTC dated June 30, 2026, also introduces changes to Personal Income Tax declaration and finalization.

3.1 Changes to tax declaration forms, notably Form 05/KK-TNCN

– Additional categories of tax-exempt income: 

[26] Income from performing scientific, technological, and innovation-related tasks. 

[27] Income of experts supporting innovative start-ups in accordance with regulations. 

[28] Other tax-exempt income. 

– Addition of item [32] Taxable income = [33] + [34]. 

– Addition of item [35] Personal income tax required to be withheld during the period. 

– Addition of item [36] Tax amount exempted during the period.

3.2 Tax finalization when employees are transferred from the former organization to a new organization.

– Where an employee is transferred from the former organization to a new organization as a result of a merger, consolidation, division, separation, or conversion of the enterprise type of the former organization, or where the former and new organizations belong to the same system, the new organization shall be responsible for conducting the tax finalization on behalf of the individual, subject to the individual’s authorization, for income paid by both the former and new organizations. The new organization shall also collect the personal income tax withholding certificate previously issued to the employee by the former organization, if any. 

pit-vietnam-kuly-2026

4. Exchange rates for tax declaration purposes applicable to exported and imported goods. 

Pursuant to Article 14 of Decree No. 252/2026/ND-CP dated June 30, 2026, the exchange rate used for tax calculation for imported and exported goods shall be determined in accordance with customs regulations.

Under the regulations on exchange rates for tax calculation in the customs sector, the applicable exchange rate is the foreign currency buying rate for bank transfers quoted by the Joint Stock Commercial Bank for Foreign Trade of Vietnam (Vietcombank) at the end of Thursday of the immediately preceding week.

If Thursday falls on a public holiday or non-working day, the end-of-day exchange rate of the immediately preceding working day shall be used.

This exchange rate applies to all customs declarations registered during that week.

EXPLORE VINA TPT BUSINESS ADVISORY

5. Additional administrative penalties for violations relating to the provision of information for information exchange purposes. 

Decree No. 291/2026/ND-CP dated July 21, 2026, introduces additional administrative penalties for violations relating to the provision of information for information exchange purposes.

  1. A fine ranging from VND 10,000,000 to VND 30,000,000 shall be imposed for providing information requested by the tax authority for information exchange purposes under Vietnamese law, international treaties, or international tax agreements to which the Socialist Republic of Vietnam is a member or signatory at least 5 days after the prescribed deadline.
  1. A fine ranging from VND 30,000,000 to VND 50,000,000 shall be imposed for providing inaccurate or incomplete information requested by the tax authority for information exchange purposes under Vietnamese law, international treaties, or international tax agreements to which the Socialist Republic of Vietnam is a member or signatory.
  1. A fine ranging from VND 50,000,000 to VND 100,000,000 shall be imposed for either of the following violations:

a) Failure to provide information within15 daysafter the expiry of the information provision deadline or the extended information provision deadline, as requested by the tax authority for information exchange purposes under Vietnamese law, international treaties, or international tax agreements to which the Socialist Republic of Vietnam is a member or signatory. 

b) Colluding with or shielding taxpayersin order toobstruct the tax authority from collecting or verifying information for information exchange purposes under Vietnamese law, international treaties, or international tax agreements to which the Socialist Republic of Vietnam is a member or signatory. 

  1. Remedial measure: The violating party shall be required to provide complete andaccurateinformation in respect of the violations specified in Clause 2 and Point a, Clause 3 of this Article. 

6. Regarding the introduction of new provisions under Decree No. 254/2026/ND-CP and Circular No. 91/2026/TT-BTC on electronic invoices and electronic documents. 

The Vietnam Tax Updates July 2026 also include new provisions concerning electronic invoices and electronic documents under Decree No. 254/2026/ND-CP and Circular No. 91/2026/TT-BTC.

Official Letter No. 4831/CT-CS dated July 15, 2026, provides further guidance on the implementation of these regulations.

– An additional case is introduced for handling incorrectly issued electronic invoices: where the incorrect invoice is an electronic invoice generated from a cash register or an electronic invoice for the sale of goods that are assets subject to registration of ownership or usage rights, the seller shall issue a replacement invoice for the incorrect invoice. 

– The regulations are amended for cases where an invoice contains errors in information such as the name, address, amount in words, or other details, but there are no errors in the tax identification number, amount stated on the invoice, tax rate, tax amount, or goods stated on the invoice. In such cases, the seller shall notify the buyer of the error in the issued invoice and is not required to reissue the invoice. 

Conclusion

The Vietnam Tax Updates July 2026 bring important changes to VAT declarations, input VAT adjustments, related-party transactions, transfer pricing documentation, PIT declaration and finalization, tax exchange rates, information exchange penalties, and electronic invoices.

Businesses should review these changes carefully to determine how they may affect their tax compliance and reporting obligations.

If you need assistance in interpreting these regulations or assessing their impact on your business, contact Vina TPT. Our accounting and tax professionals can provide practical guidance and support your business in maintaining compliance with Vietnam’s latest tax requirements.

BOOK A FREE CONSULTATION

Vietnam Tax Compliance for FDI Key Taxes & CPA Services


Shared Office Vietnam: A Smart Workspace Solution for Startups and FDI Companies 

Vina-tpt-shared-office-in-vietnam-1

Shared Office Vietnam: A Smart Workspace Solution for Startups and FDI Companies 

Entering Vietnam’s dynamic market opens up tremendous growth opportunities for foreign investors, global startups, and multinational corporations. However, establishing an operational presence often comes with a major challenge: leasing a traditional office. High upfront capital expenditure (CapEx), long-term lease commitments, and complex administrative procedures can quickly drain valuable resources before a business even launches. 

For companies with a long-term strategic vision, choosing a shared office in Vietnam offers a flexible and cost-effective alternative. It provides a ready-to-use workspace while ensuring full compliance with local legal requirements from day one. 

Shared Office vs. Traditional Office vs. Coworking Space 

Choosing the right office in Vietnam is about more than finding a place to work—it directly impacts your operating costs, business image, and day-to-day efficiency. Whether you’re setting up a new company or expanding your presence, understanding the differences between a Shared Office, Traditional Office, and Coworking Space will help you make the right decision.

Criteria Shared Office Traditional Office Coworking Space
Primary Purpose A fully serviced office with dedicated workstations for small teams, combined with a registered business address. A private office leased exclusively by one company with full control over the premises. A flexible, shared workspace designed for individuals and teams in a collaborative environment.
Workspace Dedicated desks or private offices with shared facilities. Entire private office customized to your business needs. Hot desks, dedicated desks, or shared seating areas.
Business Registration Yes. Provides legally compliant office lease documents for company registration. Yes. Suitable for business registration with a standard office lease. Depends on the provider. Some locations support company registration, while others do not.
Flexibility High. Flexible terms with minimal upfront investment. Low. Long-term lease commitments and office setup are typically required. Very high. Daily, weekly, or monthly memberships are common.
Setup Cost Low. Ready-to-use office with furniture and utilities included. High. Requires office fit-out, furniture, equipment, and ongoing facility management. Low. Membership fees generally include shared amenities.
Best For SMEs, foreign investors, and growing businesses with 1–20 employees. Established companies requiring complete privacy and branding control. Freelancers, startups, remote teams, and digital nomads seeking networking opportunities.

Each office solution serves a different stage of business growth.

A Traditional Office offers the highest level of privacy and customization, making it ideal for larger organizations with stable operations and long-term office requirements. However, it also requires significant upfront investment, longer lease commitments, and additional costs for office setup and management.

A Coworking Space is best suited for freelancers, startups, and remote professionals who value flexibility and community. It provides a dynamic working environment with networking opportunities but may offer limited privacy and, depending on the provider, may not always support business registration.

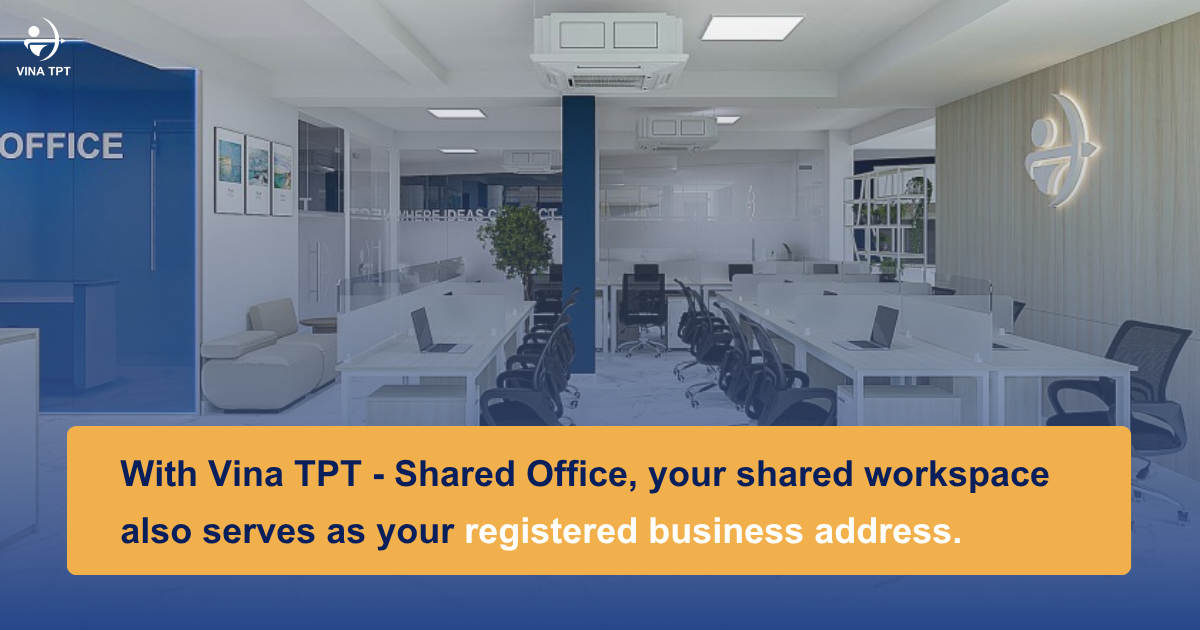
For many foreign investors and SMEs entering Vietnam, a Shared Office provides the ideal balance between professionalism, flexibility, and cost efficiency. It combines a legally registered business address with fully equipped workstations, meeting rooms, reception services, and essential office facilities—all without the financial burden of leasing and managing a traditional office. This allows businesses to establish a professional presence, operate efficiently from day one, and scale their workspace as the team grows.

serviced-office-ho-chi-minh-city

Legal Compliance: Can You Use a Shared Office for Business Registration in Vietnam? 

One of the biggest concerns for foreign investors establishing a legal presence in Vietnam is meeting local regulatory requirements. 

Under Vietnamese business regulations, every company must register a legitimate commercial business address that satisfies the legal requirements for obtaining both the Investment Registration Certificate (IRC) and the Enterprise Registration Certificate (ERC). 

To ensure full legal compliance, your workspace provider should meet the following requirements: 

  • Legally valid sublease agreement: The provider should issue a lease agreement that is legally acceptable for business registration. 
  • Proper zoning and building approval: The building must be officially licensed for commercial business activities. 
  • Fire safety compliance: The property should comply with Vietnam’s fire prevention and firefighting regulations and, where applicable, have been inspected and approved by the relevant authorities. 

At Vina TPT Office, every workspace solution is designed to meet strict legal compliance standards, helping your business registration application proceed smoothly through the approval process. 

Shared-Office-for-Business-Registration-1

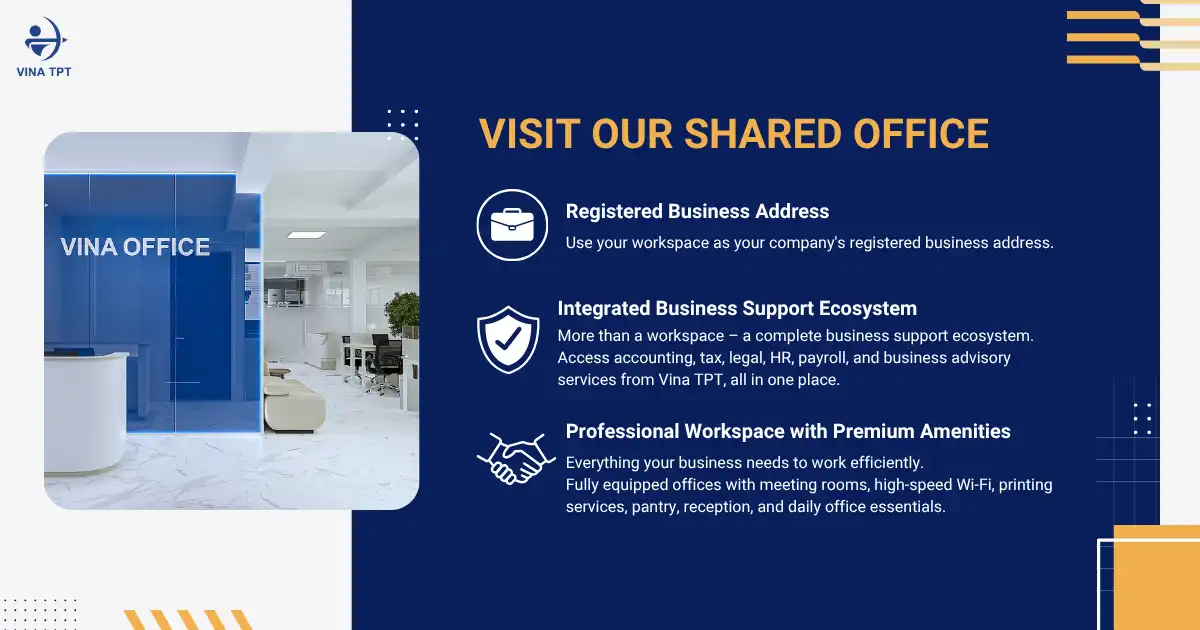
Vina TPT Shared Office: A Complete Business Support Ecosystem 

At Vina TPT, we understand that international investors need more than just office space when starting a business in a new country. Expanding into Vietnam involves navigating complex accounting, taxation, corporate legal matters, and human resources. 

That’s why our shared office is more than simply a workspace rental service—it serves as the physical foundation of a comprehensive business support ecosystem. By combining flexible office solutions with professional advisory services, Vina TPT removes many of the challenges associated with market entry, enabling foreign businesses to operate safely and efficiently from their very first day in Vietnam. 

Premium Amenities at Vina TPT Shared Office 

  • Located at 5th Floor, 75/18-20-22 Hoang Sa Street, Sai Gon Ward, Ho Chi Minh City, Vietnam
  • Vina TPT Office offers a modern and flexible workspace for startups, SMEs, and foreign companies entering the Vietnamese market. 
  • Situated along the scenic Hoang Sa canal, our office combines a peaceful working environment with excellent connectivity to Ho Chi Minh City’s major business districts. 
  • Whether you’re meeting clients, collaborating with your team, or managing day-to-day operations, you’ll enjoy a productive workplace in a highly accessible location. 

To help your team get started immediately, our shared office is equipped with modern infrastructure and professional administrative support, including: 

  • High-Speed Business Internet: Secure, enterprise-grade fiber-optic internet that ensures stable connectivity for uninterrupted global operations. 
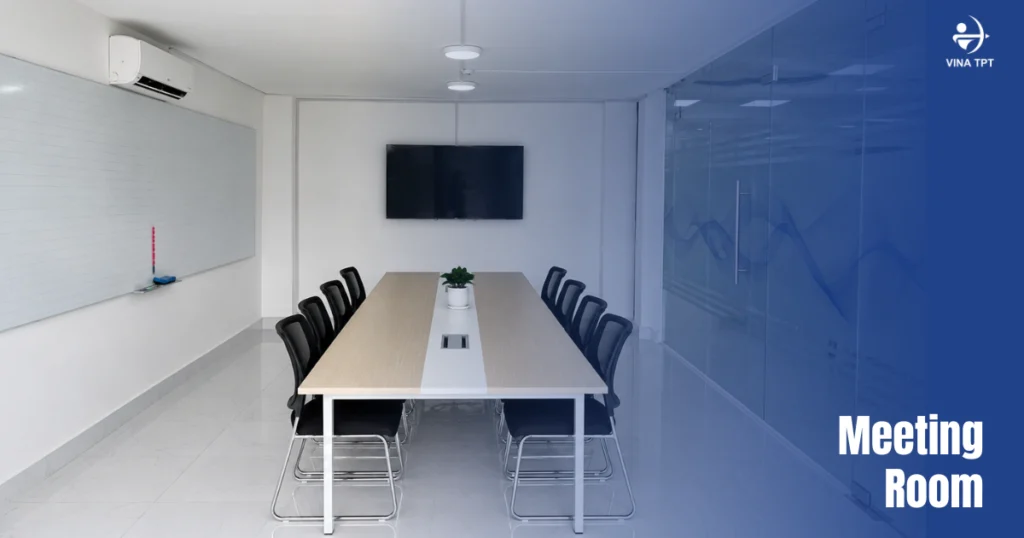
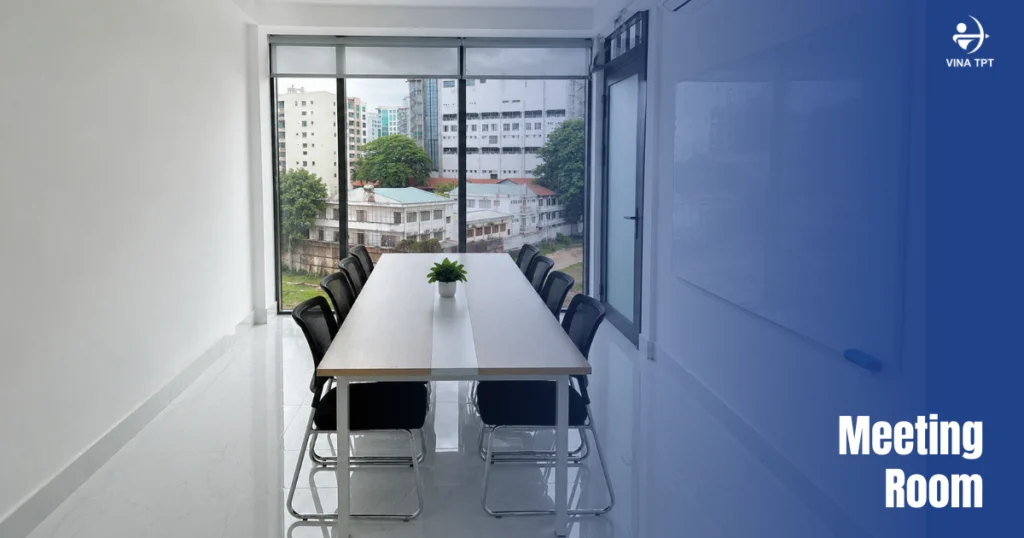
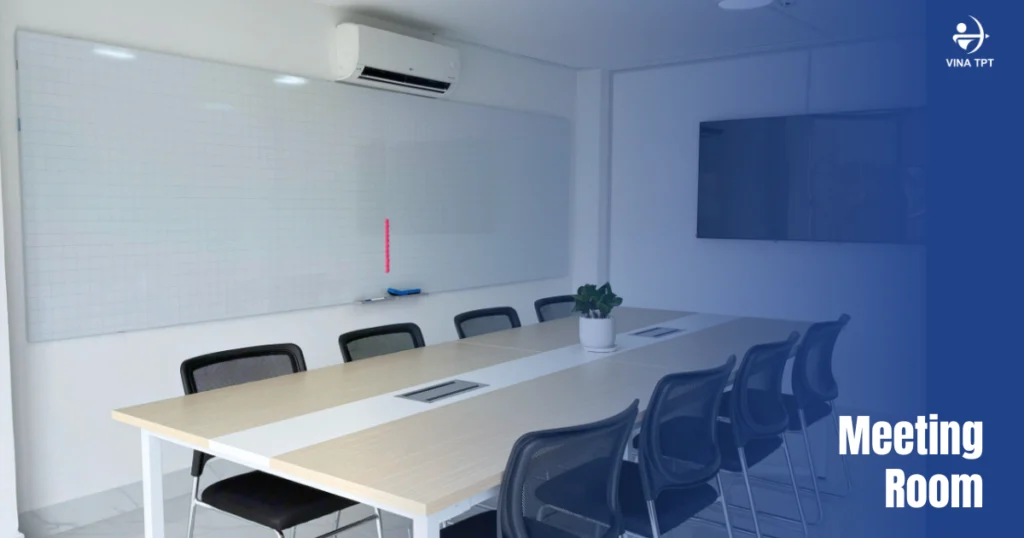
  • Modern Meeting Rooms: Fully equipped meeting rooms featuring whiteboards and large display screens (LED TVs), ideal for client presentations, team meetings, and online conferences. Each meeting room accommodates up to 15 people. 
  • Bilingual Reception Services: Our professional reception team communicates fluently in both English and Vietnamese, welcoming your guests and handling business mail and parcels. 
  • Comfortable Pantry Area: A relaxing shared pantry with complimentary tea and coffee, as well as a refrigerator and microwave, creating a welcoming space for networking and informal discussions. 

Why Choose Vina TPT Shared Office? 

Choosing Vina TPT Office as your workspace partner gives your business more than just a place to work. It provides an integrated business ecosystem that helps you establish, operate, and grow your company in Vietnam with confidence.

Comprehensive Business Ecosystem

More than a shared office, Vina TPT Office connects your workspace with a full range of professional business services. Whether you need accounting, tax compliance, legal advisory, payroll, HR support, or company incorporation, our in-house experts are ready to assist. This integrated approach allows you to focus on growing your business while we take care of the operational and compliance requirements.

Full Legal Compliance

Doing business in Vietnam requires ongoing compliance with corporate, tax, and labor regulations. Backed by Vina TPT’s experienced accounting, tax, and legal professionals, our office solutions are designed to support your business from incorporation through daily operations. We help reduce compliance risks, avoid unnecessary penalties, and ensure your company stays on the right track as regulations evolve.

Save Time and Reduce Costs

Managing separate providers for office rental, accounting, tax, payroll, and legal support can be time-consuming and costly. With Vina TPT Office, everything is coordinated under one trusted partner. This streamlined approach reduces administrative workload, improves communication, and helps your business save both time and operational expenses.

Move In and Start Working Immediately

Our fully furnished shared office is ready for your team from day one. There’s no need to invest in office fit-outs, furniture, internet installation, or administrative setup. Simply move in and start working in a professional environment with meeting rooms, reception services, high-speed Wi-Fi, printing facilities, and other essential amenities already in place – allowing you to accelerate your market entry and preserve valuable startup capital.

services-vina-tpt-business-ecosystem-1

How Much Does a Shared Office Cost in Vietnam? 

Understanding the local market helps foreign investors estimate operating costs more accurately. Shared office rental rates in Vietnam vary depending on the location and level of service provided. 

  • Hot Desks / Flexible Desks: USD 80–150 per month: Ideal for freelancers, independent professionals, and business travelers who need occasional access to a professional workspace. 
  • Dedicated Desks: USD 150–250 per month: A personal workstation with a lockable storage cabinet, making it an excellent choice for growing teams that require a permanent workspace. 
  • Private Serviced Offices: Starting from USD 500–700+ per month: Fully enclosed, secure private offices designed for branch offices or businesses that require dedicated operational space. 

Vina TPT offers competitive and transparent pricing with no hidden fees, along with flexible quarterly and annual payment options to accommodate different business needs. 

As an exclusive benefit, clients who use Vina TPT’s company incorporation services can enjoy complimentary access to our Shared Office while waiting for their business registration procedures to be completed. This allows businesses to reduce startup costs and begin preparing for operations even before receiving their Enterprise Registration Certificate (ERC). 

Frequently Asked Questions (FAQs) About Shared Offices in Vietnam 

Q: Can a 100% foreign-owned enterprise (FIE) use a shared office address to register a company in Vietnam? 

A: Yes. A foreign-invested enterprise (FIE) can use a shared office as its registered business address, provided that the workspace provider offers all required legal documentation, including a valid sublease agreement, and the property is officially approved for commercial business activities by the relevant authorities. 

Q: Does the Shared Office rental fee include management fees, electricity, and other operating costs? 

A: Yes. The Shared Office rental fee at Vina Office is all-inclusive, covering management fees, electricity, internet, cleaning, and other standard operating costs. There are no hidden charges, so you can move in and start working immediately without worrying about additional monthly facility fees. 
Q: Can I rent a Shared Office from Vina TPT without using any of its other services? 

A: Currently, our Shared Office service is available exclusively to clients who are already using other services within the Vina TPT ecosystem, such as: 

  • Company incorporation 
  • Accounting services 
  • Tax services 
  • Payroll services 
  • Corporate legal services 
  • Other related business advisory services 

This policy is designed to ensure legal compliance, operational security, and consistent service quality for all of our clients. 
By supporting businesses throughout their entire journey—from company formation to daily operations—we gain a thorough understanding of each client’s legal status. This enables us to provide more effective support in managing registered business addresses, receiving official correspondence, communicating with government authorities, and handling ongoing compliance matters. 
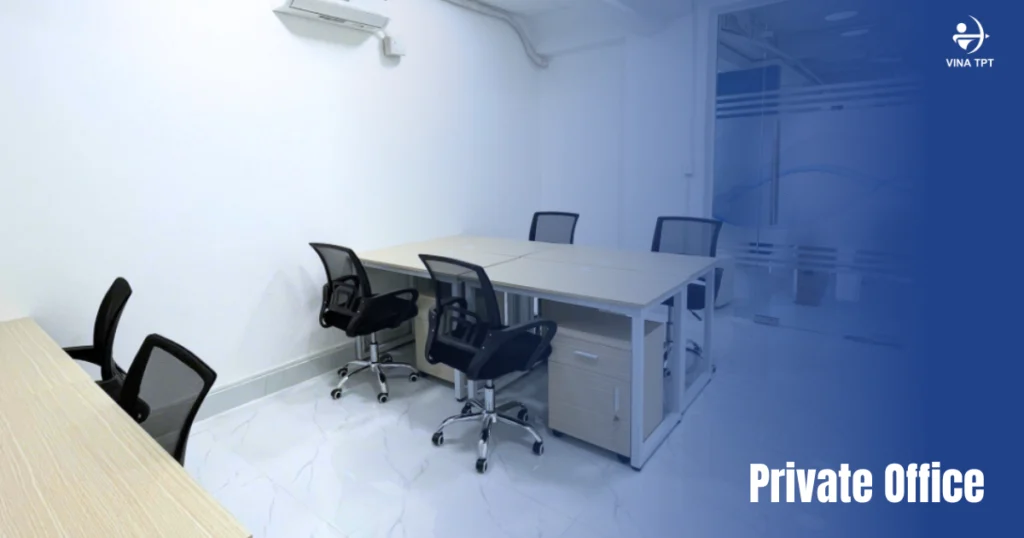
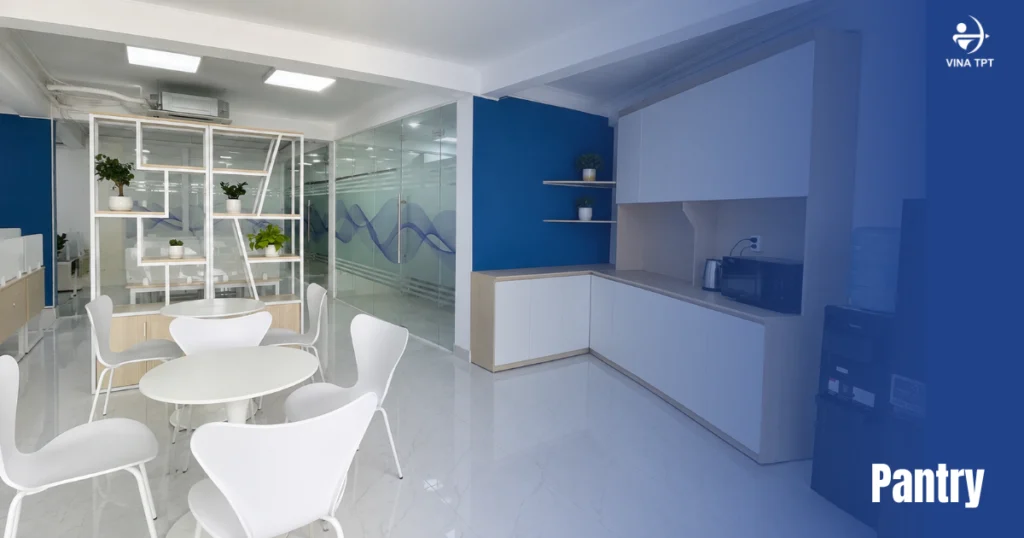
BOOK A FREE OFFICE TOUR AND GET QUOTE


Vietnam Tax Compliance for FDI Business: Key Taxes & CPA Support

Vietnam-Tax-Compliance-for-FDI-Key-Taxes-CPA-Services-scaled.webp

Vietnam Tax Compliance for FDI Key Taxes & CPA Services

For foreign investors entering the Vietnamese market, tax compliance is not simply an obligation to pay taxes to the state budget, but a critical factor that directly impacts the financial safety and long-term sustainability of the investment project. Language barriers, the complexity of the local legal system, and the frequent updates to sub-law documents often turn tax management into the biggest “bottleneck” for FDI company management.

Even a small mistake in identifying invalid invoices, incorrectly posting non-deductible expenses, or late declaration of contractor taxes can result in heavy administrative fines, additional tax assessments with 0.03% daily late payment interest, or prolonged tax inspections that disrupt the entire supply chain.

This article provides a comprehensive overview of tax compliance Vietnam FDI, an in-depth analysis of the four core taxes (VAT, CIT, PIT, FCT) with the latest legal obligations, and reveals Vina TPT’s specialized Vietnam tax obligations for foreign companies solutions to help investors take full control of their financial game in Vietnam.

Vietnam Tax Compliance for FDI Key Taxes & CPA Services

1. Value-Added Tax (VAT) – The Most Important Tax Obligation for all Businesses

Value-Added Tax (VAT) is an indirect tax with the highest transaction frequency and the strictest supervision from local tax authorities. It is a mandatory obligation applicable to all business sectors of FDI companies in Vietnam, including trading, manufacturing, services, import-export, and other fields.

1.1. Legal Basis & Declaration Cycle

According to the Law on Value-Added Tax 2008 (as amended and supplemented) and the latest guidance in Decree 181/2025/ND-CP, newly established FDI enterprises or those with annual revenue of VND 50 billion or less in the previous year must declare VAT on a quarterly basis. Enterprises with previous year revenue exceeding VND 50 billion are required to declare VAT on a monthly basis.

1.2. Strict Conditions for Input VAT Deduction

To be eligible for input VAT deduction, the accounting department of an FDI company must simultaneously meet the following conditions:

  • Have a valid VAT invoice (issued with a tax authority code under Decree 123/2020/ND-CP).
  • Have non-cash payment documents (bank transfer from the buyer’s account to the seller’s account) for invoices valued at VND 5 million or more (including VAT).
  • The purchased goods or services must be directly used for the production or business of goods and services subject to VAT.

2. Corporate Income Tax (CIT) – Profit-Based Tax & the Provisional Payment Calculation

Corporate Income Tax (CIT) directly affects the net profit of foreign investors. Understanding the provisional payment rules and tax incentive mechanisms is the key to optimizing capital efficiency.

2.1. Standard Tax Rate & Quarterly Provisional Payment Rule (80% Rule)

The standard Corporate Income Tax (CIT) rate in Vietnam is currently 20% on taxable income. However, according to the new regulations in 2025, certain enterprises that meet the preferential conditions may enjoy lower tax rates:

  • 15%: Applied to enterprises with annual total revenue not exceeding VND 3 billion.
  • 17%: Applied to enterprises with annual total revenue from over VND 3 billion up to VND 50 billion.

Special Note on the 80% Rule:

Special Note on the 80% Rule: According to current regulations, the total CIT amount provisionally paid for the four quarters of the tax year must not be less than 80% of the final CIT amount payable upon annual finalization. If the payment falls short of this 80% threshold, the company will be charged late payment interest (0.03% per day) on the shortfall, starting from the day after the deadline for the fourth-quarter tax payment.

2.2. Tax Incentive Mechanism (Tax Incentives) under the Law on Investment 2020

FDI companies can take advantage of attractive tax incentive packages if they meet the conditions regarding location or investment priority sectors according to Decree 31/2021/ND-CP:

Type of Incentive

Incentive Level

Conditions & Applicable Sectors

Preferential tax rate of 10% For 15 years (extendable to 30 years) High-tech projects, high-tech applications, R&D, renewable energy.
100% Exemption & 50% Reduction Exemption for 4 years, 50% reduction for the next 9 years Newly established projects in industrial parks, economic zones, or areas with particularly difficult socio-economic conditions.
Preferential tax rate of 15%–17% Applied throughout the project duration Enterprises meeting capital scale or large labor usage criteria as prescribed.

Key updates in 2025:

  • Enterprises are allowed to expand deductible expenses related to scientific research, digital transformation, new technology testing, emission reduction, and community activities.
  • If eligible for multiple incentive groups, the enterprise has the right to choose the most favorable incentive level.
  • Losses can be carried forward continuously for a maximum of 5 years, and up to 20% of taxable income may be set aside to establish a Science & Technology Development Fund (if used for the correct purposes).

Real-life example: A Korean technology corporation established a software factory in Ho Chi Minh City High-Tech Park. By correctly applying for CIT incentives, the company enjoys a 10% tax rate for 15 years, 100% CIT exemption for the first 4 years (from the year it has taxable income), and a 50% reduction for the next 9 years – saving millions of USD in taxes.

>>> For a more detailed and complete update on all Corporate Income Tax incentive policies in 2025, read the article: Tax Incentive in Vietnam 2025: Comprehensive Guide to Optimize Profits under New CIT Law

Vietnam Tax Compliance for FDI Key Taxes & CPA Services

Get Expert Advice on Tax Incentive Policies

3. Personal Income Tax (PIT) and Social Insurance Responsibilities for Personnel

Compliance with Personal Income Tax (PIT) and Social Insurance (BHXH) for the workforce – especially for foreign experts and managers (Expats) – always carries significant risks of additional tax assessments if residency status is not correctly classified.

3.1. PIT Withholding & Residency Classification Rules

FDI companies are obligated to withhold, declare, and pay Personal Income Tax (PIT) on a monthly or quarterly basis before paying income to employees:

  • Resident Individuals: Present in Vietnam for 183 days or more in a calendar year (or 12 consecutive months). Progressive tax rates from 5% to 35% apply on worldwide income (Global Income).
  • Non-Resident Individuals: A non-resident individual is a person who does not meet the conditions of a resident individual, specifically someone who is present in Vietnam for fewer than 183 days in the tax year and does not have a permanent residence in Vietnam.

3.2. Mandatory Social Insurance (BHXH) Responsibilities

According to the Law on Social Insurance and related regulations, FDI companies must contribute the following for employees:

  • Vietnamese Employees: Contributions to Social Insurance, Health Insurance, and Unemployment Insurance at a total rate of 32% (Employer: 21.5%, Employee: 10.5%).
  • Foreign Employees (Expats): Mandatory participation in Social Insurance and Health Insurance if they hold a Work Permit and have an employment contract that is indefinite or has a term of 1 year or longer.

>>> For more details: 

4. Foreign Contractor Tax (FCT) and Related Legal Obligations

Foreign Contractor Tax (FCT) is a special tax that many newly operating FDI companies often overlook, leading to declaration violations and penalties.

4.1. Nature & Mechanism of FCT Collection

FCT applies to foreign organizations and individuals who do not operate under Vietnamese law but generate income from providing services or goods associated with services in Vietnam (such as software royalties, parent company management consulting fees, cross-border digital marketing services, etc.).

FCT consists of two main components: VAT and Corporate Income Tax (or Personal Income Tax). The FDI company in Vietnam is responsible for withholding, declaring, and paying FCT on behalf of the foreign contractor before remitting payment.

Example: An FDI company pays USD 100,000 in software royalty fees to its parent company in Singapore. The company must determine the applicable FCT rate (typically 5% CIT on royalties), register a contractor tax code, and declare and pay FCT within 10 days from the payment date.

4.2. 2. Other Mandatory Fees & Periodic Reporting Obligations

In addition to the four main taxes, Vietnam tax obligations for foreign companies also include the Investment Activity Report (IAR): Periodic declaration and reporting of project implementation status on the National Investment Information System.

5. Benefits of Using Vina TPT’s Tax Compliance Services

When choosing to partner with Vina TPT, FDI companies are not simply using an external tax filing service – they are proactively equipping themselves with a solid “financial shield” for the entire operational process in Vietnam.

Instead of maintaining a bulky in-house accounting and tax team with high costs while still facing risks of staff turnover or lack of legal update capabilities, partnering with Vina TPT helps businesses optimize operating costs by up to 40%. More importantly, thanks to a 3-level independent quality control model operated by experienced CPA and Chief Accountant experts, all risks of additional tax assessments, administrative penalties, or errors during finalization are eliminated at the root.

In addition to legal safety, Vina TPT acts as a strategic advisor, helping businesses legally maximize tax incentives and optimize deductible expense structures in line with the spirit of the Corporate Income Tax Law. At the same time, all financial data is standardized into bilingual management reports (English & Vietnamese), creating a transparent information bridge that allows the Board of Directors and overseas Headquarters to easily grasp the accurate financial picture in real time. All of this brings complete peace of mind, allowing foreign investors to focus entirely on market expansion goals.

Are you concerned about tax compliance? Contact Vina TPT today to receive a free consultation and specialized tax compliance services.

BOOK A FREE CONSULTATION

Vietnam Tax Compliance for FDI Key Taxes & CPA Services


Accounting Advisory Services in Vietnam: Trusted CPA Expertise

Accounting Advisory Services in Vietnam Trusted CPA Expertise

Accounting Advisory Services in Vietnam Trusted CPA Expertise

When operating a foreign-invested enterprise (FDI) in Vietnam, the difference between “compliance accounting” and “strategic accounting advisory” is significant. The complexity of the tax policy system, Transfer Pricing regulations, and the differences between Vietnamese Accounting Standards (VAS) and International Financial Reporting Standards (IFRS) often expose management to hidden financial risks that standard data-entry services cannot detect.

This is why successful FDI companies always seek the support of accounting advisory services. Going far beyond simply cleaning the books or submitting reports on time, in-depth advisory services provide a comprehensive view of the financial landscape, helping investors legally optimize tax obligations, control audit risks, and confidently make strategic business decisions.

This article analyzes in detail the real value that a professional accounting advisory Vietnam service brings to your business, and how our team of CPA experts accompanies you to protect your invested capital in Vietnam.

1. What Challenges Does Accounting Advisory Solve for FDI Companies?

Rather than simply recording transactions that have already occurred, an in-depth accounting advisory services system is designed to proactively resolve the core issues throughout the entire operational cycle of FDI companies in Vietnam:

  • Standardization of Accounting Books & Document Management according to VAS: Ensures all transactions are supported by legal and valid documents as required by the Vietnamese Ministry of Finance. Electronic invoices and supporting documents are thoroughly reviewed and securely digitized, keeping the business always prepared for audits.
  • Financial Statement Reconciliation & Management Reporting: Converts data from VAS to IFRS or US GAAP for transparent reporting to overseas headquarters. At the same time, it builds a management reporting system (P&L, cash flow, cost by center) that helps leadership understand the real financial health for timely decision-making.
  • Tax Structure Optimization & VAT Refund Support: Develops legitimate deductible expense structures under the Corporate Income Tax Law and maximizes tax incentives by location and industry. Prepares and represents the company in VAT refund procedures for new investment projects or export activities quickly and legally.
  • Tax Health Check Program (Tax Review & Health Check): Conducts a comprehensive review of past accounting records and tax declarations to detect early risk points, eliminate illegitimate expenses, and propose corrective measures before the tax authorities issue an inspection decision.
  • Transfer Pricing Compliance Advisory: Assists in preparing transfer pricing documentation, advises on optimal debt-to-equity structures, helping the company achieve 100% legal compliance and avoid the risk of tax assessment.
  • Protection During Audits & Tax Inspections: Acts as the main point of contact when working directly with independent audit firms. Represents the company in providing in-depth explanations and maximally protects legitimate rights and interests before tax inspection teams.

2. How to Evaluate a Reputable and Suitable CPA Team for Your FDI Company

The quality of CPA advisory services Vietnam is not determined by beautiful promises, but directly by the practical capability and legal qualifications of the personnel who directly handle your company’s files. To avoid the risk of misplaced trust in inexperienced providers, foreign investors can evaluate a CPA team’s capability based on the following 3 golden criteria:

  1. Official Professional Credentials: The responsible experts must hold official CPA Vietnam certificates issued by the Ministry of Finance or reputable international certifications (CPA Australia, ACCA, CA). These serve as legal proof of their ability to sign reports, understand tax laws, and take professional responsibility before the law.
  2. Ability to “Translate” Between VAS and IFRS: For FDI companies, a good CPA must not only understand Vietnamese Accounting Standards (VAS) to work with tax authorities, but also master International Financial Reporting Standards (IFRS) to clearly explain financial data to overseas headquarters.
  3. Real-World Explanation Experience (Battle-tested Experience): Credentials are necessary, but hands-on experience representing companies during actual tax inspections and finalizations is what truly protects the investor’s capital.

Meeting these strict criteria, the core expert team at Vina TPT serves as a solid professional foundation for international investors:

  • Mrs. Chau Kim Hien – Executive Director: With over 10 years of specialized experience in FDI finance and tax, Ms. Hiền directly advises on strategic matters for complex business models. She has particular strengths in bridging international IFRS management needs with local VAS implementation in Manufacturing, IT, Trading Services, and Construction sectors.
  • Ms. Pham Thi Thu Van – Assistant Manager – Accounting & Tax: A Certified Public Accountant (CPA) with over 7 years of hands-on experience. Ms. Vân specializes in establishing internal control systems, building transparent financial reporting structures, and optimizing tax risks for multinational corporations.
  • Mr. Huynh Quoc Khanh – Senior Accounting & Tax: Holds the Chief Accountant Certificate issued by the Ministry of Finance and has over 7 years of experience supporting Korean-invested enterprises. He is known for his ability to identify tax risks early and successfully represent clients during tax inspections.
  • Ms. Nguyen Thi Ngoc Bich – Senior Accounting & Tax: Holds the Chief Accountant Certificate issued by the Ministry of Finance and has over 7 years of experience in accounting and taxation, specializing in supporting Japanese enterprises across various industries. She is recognized for ensuring regulatory compliance while helping clients improve operational efficiency.

Notably, the entire team operates in a bilingual (English & Vietnamese) working model, helping investors fully understand every legal and financial issue without any language barriers.

Accounting Advisory Services in Vietnam Trusted CPA Expertise

3. 5 Core Questions When Choosing an Accounting Advisory Services Provider

To find a truly high-quality financial and accounting consulting partner and avoid the risk of choosing low-cost, low-capability providers, the Board of Directors of FDI companies should ask the following 5 direct questions during the partner evaluation process:

1. “What professional credentials do the team members directly handling our files hold, and how is the language coordination process handled?”

A common reality in the market is that many accounting firms use the reputation of senior experts to sign contracts, but later assign all bookkeeping work to staff with insufficient experience. FDI companies should request clear confirmation of the identity of the person directly responsible for their files. This person must hold reputable professional credentials (CPA, Chief Accountant Certificate, Tax Agent Certificate).

In addition, the language factor should be viewed realistically: a highly skilled technical expert does not necessarily need to be fluent in every local foreign language. A professional consulting firm will have a flexible coordination mechanism – if the responsible expert does not communicate directly in the investor’s language (such as Japanese or Chinese), the firm must have a dedicated financial interpreter team to ensure that all technical information is conveyed with 100% accuracy and is not distorted by language barriers.

2. “Is your service structure based on standard pre-packaged packages or do you offer tailored solutions designed for each industry?”

Every FDI company entering Vietnam has a different scale and budget orientation. A reputable consulting firm will offer standard accounting service packages – an optimized solution that helps the majority of small and medium-sized FDI companies quickly fulfill their legal compliance obligations at a highly reasonable cost.

However, for industries with complex financial structures and cash flows such as Real Estate, large-scale Manufacturing, F&B chains, or IT Technology, a high-end consulting firm will flexibly design (tailor) in-depth solutions based on an actual operational survey. The combination of cost-effective standard packages and flexible customized solutions is the key to fully meeting every investor’s needs.

3. “Does the firm have the capability to convert financial statements from VAS to international standards such as IFRS?” Compliance with Vietnamese Accounting Standards (VAS) is mandatory for working with local tax authorities. However, the Board of Directors and foreign shareholders need reports prepared under international standards IFRS for consolidated group reporting and accurate investment performance evaluation. A reputable accounting advisory services provider must act as a “standards bridge”, helping to convert accounting data transparently and accurately between the two systems.

4. “What is your quality control process for accounting books and tax reporting?” Errors in accounting and tax declarations often stem from individual oversight. To eliminate this risk, a professional consulting partner must operate a multi-layer quality control mechanism (Double-check or Triple-check). All data prepared by accountants must undergo independent review by a Chief Accountant or CPA before being officially submitted to state authorities or sent to clients.

5. “Does your firm commit to accompanying the company and directly representing it during tax inspections?” This is considered the highest “responsibility benchmark” of a consulting firm. The true capability of a partner is demonstrated by their willingness to stand up and defend the legality of the figures, invoices, and tax arguments they themselves prepared.

Asking these direct questions not only helps investors clearly see the real capability of the consulting firm but also serves as an important screening step to protect the company’s capital and reputation in the Vietnamese market. If you are looking for a partner that fully meets these strict standards, Vina TPT is the most comprehensive answer.

Explore Vina TPT's Accounting Advisory Services

4. Why International FDI Companies Choose Vina TPT’s Accounting Advisory Services

Meeting the strictest criteria of foreign investors, Vina TPT has established itself as a leading strategic financial and tax advisory partner in Vietnam thanks to the following outstanding competitive advantages:

  • Over 20 years of hands-on experience supporting FDI: We have a deep understanding of management mindsets, risk appetites, and cultural nuances of different investor groups (Japan, Korea, Singapore, Europe, US…).
  • 3-Level Quality Control Process: Every accounting and tax file undergoes rigorous review through three layers: Assistant -> Senior Accountant -> Manager. This “triple-check” mechanism ensures the highest accuracy and minimizes the risk of errors.
  • Direct Support from CPA & Chief Accountant Team: 100% of our clients’ accounting and tax files are handled by experts holding CPA qualifications and Chief Accountant certificates issued by the Ministry of Finance.
  • Tax Obligation Optimization & Operating Cost Savings: We help businesses proactively maximize legal tax incentives, build transparent cash flow structures, and completely eliminate risks of late-payment fines or additional tax assessments.
  • Sharp Management Reporting & IFRS Conversion: We provide leadership with accurate, detailed financial pictures in English/Vietnamese, strongly supporting the parent company in consolidated reporting and investment decision-making.
  • Flexible Remote Operation Support (Remote Support): Integrated with high-security cloud storage technology, allowing investors to easily monitor, control, and approve financial data in Vietnam in real time, even from abroad.

Are you looking for a reputable, high-standard accounting advisory services solution to standardize your financial system and optimize tax risks for your business? Contact Vina TPT today to receive a free consultation from our expert team.

BOOK A FREE CONSULTATION

 Accounting-Advisory-Services-in-Vietnam-Trusted-CPA-Expertise