Vietnam Tax Updates July 2026: Key VAT, PIT, Transfer Pricing and E-Invoice Changes

vietnam-tax-updates-july-2026

Vietnam Tax Updates July 2026: Key VAT, PIT, Transfer Pricing and E-Invoice Changes

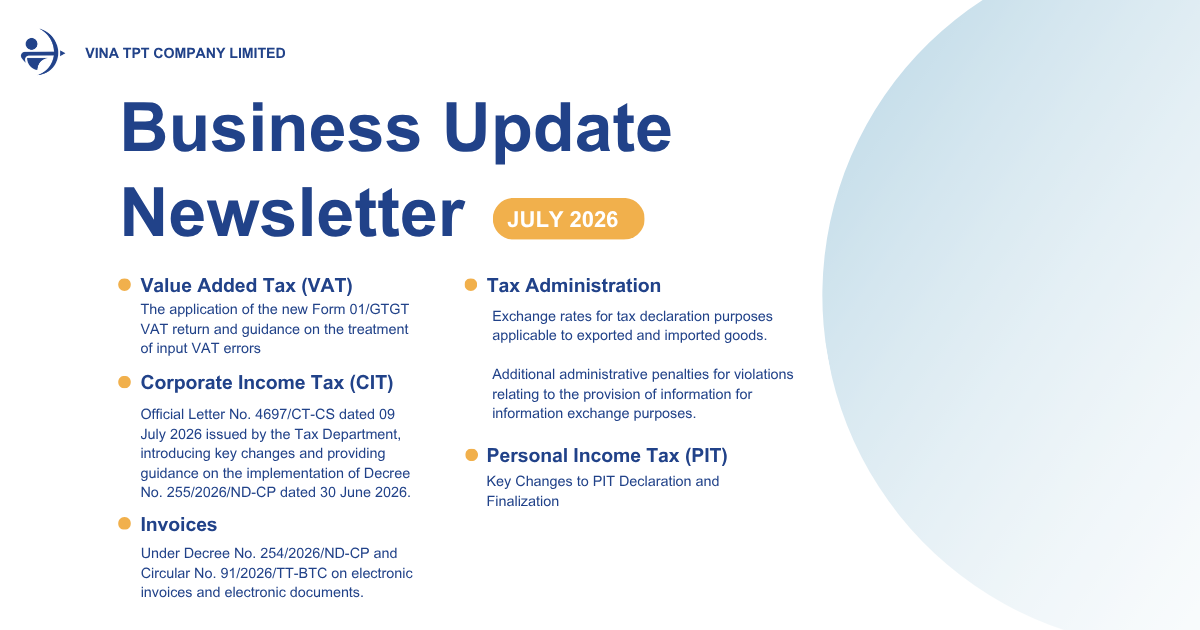
The Vietnam Tax Updates July 2026 introduce several important changes and clarifications affecting VAT declaration, input VAT adjustments, related-party transactions, transfer pricing documentation, Personal Income Tax (PIT), tax exchange rates, tax information disclosure penalties, and electronic invoices.

Businesses should pay close attention to these updates to ensure accurate tax declarations, comply with applicable reporting requirements, and manage their tax obligations effectively.

1. Regarding the application of the new Form 01/GTGT VAT return and guidance on the treatment of input VAT errors under items [37] and [38]: 

Circular No. 89/2026/TT-BTC dated 30 June 2026, applicable from the July 2026 tax period or Q3/2026.

1.1 Form 01/GTGT VAT return:

– Addition of item [32b]: Goods and services sold that are not included in the value-added tax taxable price 

– Addition of item [34a]: Goods and services sold that are outside the scope of the value-added tax regulations.

1.2 Guidance on the treatment of input VAT errors through items [37] and [38]:

– For goods and services purchased on deferred payment or installment terms with a purchase value of VND 5 million or more, the business shall declare and reduce the deductible input VAT corresponding to the portion of the purchase value for which no non-cash payment supporting document is available in item [37] of the tax period in which the payment obligation arises under the contract or contract appendix, without filing a supplementary tax return. If, after such adjustment, the business obtains a non-cash payment supporting document, it may declare and deduct the input VAT corresponding to the portion of the purchase value supported by the non-cash payment document in item [38] of the tax period in which such document is obtained. 

– Where a taxpayer discovers an error or omission in the input VAT previously declared and deducted, the adjustment shall be declared in item [37] or [38] of the month or quarter in which the error or omission is discovered if declaring the adjustment in the month or quarter in which the erroneous input VAT arose would reduce the tax payable or would only increase or decrease the input VAT credit carried forward to the following period, without filing a supplementary tax return. 

– Where the buyer receives an adjusted invoice or replacement invoice in the cases prescribed in Clause 5, Article 10 of Circular No. 91/2026/TT-BTC dated 30 June 2026 of the Ministry of Finance, the adjustment shall be declared in item [37] or [38] of the tax period in which the adjusted invoice or replacement invoice is received, without filing a supplementary tax return. 

– Where a taxpayer changes its VAT calculation method from the credit method to the direct method based on revenue, the taxpayer shall declare a reduction of any remaining uncredited input VAT in item [37] of the final tax period before changing the VAT calculation method, without filing a supplementary tax return.

2. Regarding related-party transactions 

Another important area covered by the Vietnam Tax Updates July 2026 is related-party transactions and transfer pricing.

Official Letter No. 4697/CT-CS dated July 9, 2026, issued by the Tax Department, introduces key changes and provides guidance on the implementation of Decree No. 255/2026/ND-CP dated June 30, 2026.

2.1 Related Party Relationship (Article 5)

A related-party relationship has been expanded to include borrowing and lending arrangements in a manner similar to loan transactions under Point l, Clause 2, Article 5 of the Decree, as follows: 

“An enterprise that engages in transactions involving the transfer or receipt of capital contributions representing at least 25% of the owner’s contributed capital during the tax period; or that borrows, lends, receives on loan, or provides on loan an amount equivalent to at least 10% of the owner’s contributed capital at the time the transaction arises during the tax period with an individual who manages or controls the enterprise, or with an individual having a relationship specified in Point g of this Clause.”

2.2 Exemption from preparing Transfer Pricing Documentation (Point c, Clause 2, Article 20)

– The Decree increases the revenue threshold for taxpayers eligible for exemption from preparing Transfer Pricing Documentation to less than VND 500 billion, while removing the requirement that the taxpayer must operate under a “simple functional profile.” 

Previously, taxpayers were required to satisfy all four of the following conditions to qualify for the exemption: (i)Conducting business with a simple functional profile; (ii)Not generating revenue from, incurring expenses related to, or utilizing intangible assets; (iii) Having annual revenue below VND 200 billion; (iv) Achieving the prescribed net profit margin applicable to the relevant business sector. 

– The increase in the revenue threshold and the removal of the “simple functional profile” criterion are intended to broaden the scope of low tax-risk taxpayers eligible for the exemption, simplify the application requirements, and reduce compliance costs and administrative burdens for taxpayers. 

3. Key Changes to PIT Declaration and Finalization. 

Circular No. 89/2026/TT-BTC dated June 30, 2026, also introduces changes to Personal Income Tax declaration and finalization.

3.1 Changes to tax declaration forms, notably Form 05/KK-TNCN

– Additional categories of tax-exempt income: 

[26] Income from performing scientific, technological, and innovation-related tasks. 

[27] Income of experts supporting innovative start-ups in accordance with regulations. 

[28] Other tax-exempt income. 

– Addition of item [32] Taxable income = [33] + [34]. 

– Addition of item [35] Personal income tax required to be withheld during the period. 

– Addition of item [36] Tax amount exempted during the period.

3.2 Tax finalization when employees are transferred from the former organization to a new organization.

– Where an employee is transferred from the former organization to a new organization as a result of a merger, consolidation, division, separation, or conversion of the enterprise type of the former organization, or where the former and new organizations belong to the same system, the new organization shall be responsible for conducting the tax finalization on behalf of the individual, subject to the individual’s authorization, for income paid by both the former and new organizations. The new organization shall also collect the personal income tax withholding certificate previously issued to the employee by the former organization, if any. 
pit-vietnam-kuly-2026

4. Exchange rates for tax declaration purposes applicable to exported and imported goods. 

Pursuant to Article 14 of Decree No. 252/2026/ND-CP dated June 30, 2026, the exchange rate used for tax calculation for imported and exported goods shall be determined in accordance with customs regulations.

Under the regulations on exchange rates for tax calculation in the customs sector, the applicable exchange rate is the foreign currency buying rate for bank transfers quoted by the Joint Stock Commercial Bank for Foreign Trade of Vietnam (Vietcombank) at the end of Thursday of the immediately preceding week.

If Thursday falls on a public holiday or non-working day, the end-of-day exchange rate of the immediately preceding working day shall be used.

This exchange rate applies to all customs declarations registered during that week.

EXPLORE VINA TPT BUSINESS ADVISORY

5. Additional administrative penalties for violations relating to the provision of information for information exchange purposes. 

Decree No. 291/2026/ND-CP dated July 21, 2026, introduces additional administrative penalties for violations relating to the provision of information for information exchange purposes.

  1. A fine ranging from VND 10,000,000 to VND 30,000,000 shall be imposed for providing information requested by the tax authority for information exchange purposes under Vietnamese law, international treaties, or international tax agreements to which the Socialist Republic of Vietnam is a member or signatory at least 5 days after the prescribed deadline.
  1. A fine ranging from VND 30,000,000 to VND 50,000,000 shall be imposed for providing inaccurate or incomplete information requested by the tax authority for information exchange purposes under Vietnamese law, international treaties, or international tax agreements to which the Socialist Republic of Vietnam is a member or signatory.
  1. A fine ranging from VND 50,000,000 to VND 100,000,000 shall be imposed for either of the following violations:

a) Failure to provide information within15 daysafter the expiry of the information provision deadline or the extended information provision deadline, as requested by the tax authority for information exchange purposes under Vietnamese law, international treaties, or international tax agreements to which the Socialist Republic of Vietnam is a member or signatory. 

b) Colluding with or shielding taxpayersin order toobstruct the tax authority from collecting or verifying information for information exchange purposes under Vietnamese law, international treaties, or international tax agreements to which the Socialist Republic of Vietnam is a member or signatory. 

  1. Remedial measure: The violating party shall be required to provide complete andaccurateinformation in respect of the violations specified in Clause 2 and Point a, Clause 3 of this Article. 

6. Regarding the introduction of new provisions under Decree No. 254/2026/ND-CP and Circular No. 91/2026/TT-BTC on electronic invoices and electronic documents. 

The Vietnam Tax Updates July 2026 also include new provisions concerning electronic invoices and electronic documents under Decree No. 254/2026/ND-CP and Circular No. 91/2026/TT-BTC.

Official Letter No. 4831/CT-CS dated July 15, 2026, provides further guidance on the implementation of these regulations.

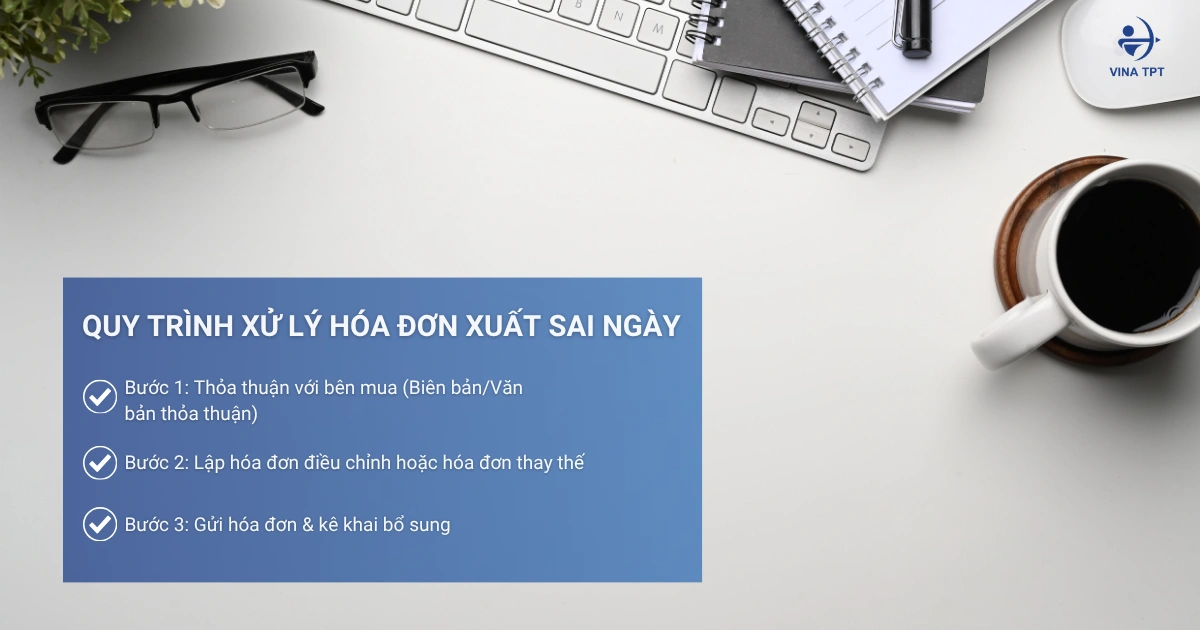
– An additional case is introduced for handling incorrectly issued electronic invoices: where the incorrect invoice is an electronic invoice generated from a cash register or an electronic invoice for the sale of goods that are assets subject to registration of ownership or usage rights, the seller shall issue a replacement invoice for the incorrect invoice. 

– The regulations are amended for cases where an invoice contains errors in information such as the name, address, amount in words, or other details, but there are no errors in the tax identification number, amount stated on the invoice, tax rate, tax amount, or goods stated on the invoice. In such cases, the seller shall notify the buyer of the error in the issued invoice and is not required to reissue the invoice. 

Conclusion

The Vietnam Tax Updates July 2026 bring important changes to VAT declarations, input VAT adjustments, related-party transactions, transfer pricing documentation, PIT declaration and finalization, tax exchange rates, information exchange penalties, and electronic invoices.

Businesses should review these changes carefully to determine how they may affect their tax compliance and reporting obligations.

If you need assistance in interpreting these regulations or assessing their impact on your business, contact Vina TPT. Our accounting and tax professionals can provide practical guidance and support your business in maintaining compliance with Vietnam’s latest tax requirements.
BOOK A FREE CONSULTATION

Vietnam Tax Compliance for FDI Key Taxes & CPA Services


Shared Office Vietnam: A Smart Workspace Solution for Startups and FDI Companies 

Vina-tpt-shared-office-in-vietnam-1

Shared Office Vietnam: A Smart Workspace Solution for Startups and FDI Companies 

Entering Vietnam’s dynamic market opens up tremendous growth opportunities for foreign investors, global startups, and multinational corporations. However, establishing an operational presence often comes with a major challenge: leasing a traditional office. High upfront capital expenditure (CapEx), long-term lease commitments, and complex administrative procedures can quickly drain valuable resources before a business even launches. 

For companies with a long-term strategic vision, choosing a shared office in Vietnam offers a flexible and cost-effective alternative. It provides a ready-to-use workspace while ensuring full compliance with local legal requirements from day one. 

Shared Office vs. Traditional Office vs. Coworking Space 

Choosing the right office in Vietnam is about more than finding a place to work—it directly impacts your operating costs, business image, and day-to-day efficiency. Whether you’re setting up a new company or expanding your presence, understanding the differences between a Shared Office, Traditional Office, and Coworking Space will help you make the right decision.

Criteria Shared Office Traditional Office Coworking Space
Primary Purpose A fully serviced office with dedicated workstations for small teams, combined with a registered business address. A private office leased exclusively by one company with full control over the premises. A flexible, shared workspace designed for individuals and teams in a collaborative environment.
Workspace Dedicated desks or private offices with shared facilities. Entire private office customized to your business needs. Hot desks, dedicated desks, or shared seating areas.
Business Registration Yes. Provides legally compliant office lease documents for company registration. Yes. Suitable for business registration with a standard office lease. Depends on the provider. Some locations support company registration, while others do not.
Flexibility High. Flexible terms with minimal upfront investment. Low. Long-term lease commitments and office setup are typically required. Very high. Daily, weekly, or monthly memberships are common.
Setup Cost Low. Ready-to-use office with furniture and utilities included. High. Requires office fit-out, furniture, equipment, and ongoing facility management. Low. Membership fees generally include shared amenities.
Best For SMEs, foreign investors, and growing businesses with 1–20 employees. Established companies requiring complete privacy and branding control. Freelancers, startups, remote teams, and digital nomads seeking networking opportunities.

Each office solution serves a different stage of business growth.

A Traditional Office offers the highest level of privacy and customization, making it ideal for larger organizations with stable operations and long-term office requirements. However, it also requires significant upfront investment, longer lease commitments, and additional costs for office setup and management.
A Coworking Space is best suited for freelancers, startups, and remote professionals who value flexibility and community. It provides a dynamic working environment with networking opportunities but may offer limited privacy and, depending on the provider, may not always support business registration.

For many foreign investors and SMEs entering Vietnam, a Shared Office provides the ideal balance between professionalism, flexibility, and cost efficiency. It combines a legally registered business address with fully equipped workstations, meeting rooms, reception services, and essential office facilities—all without the financial burden of leasing and managing a traditional office. This allows businesses to establish a professional presence, operate efficiently from day one, and scale their workspace as the team grows.

serviced-office-ho-chi-minh-city

Legal Compliance: Can You Use a Shared Office for Business Registration in Vietnam? 

One of the biggest concerns for foreign investors establishing a legal presence in Vietnam is meeting local regulatory requirements. 
Under Vietnamese business regulations, every company must register a legitimate commercial business address that satisfies the legal requirements for obtaining both the Investment Registration Certificate (IRC) and the Enterprise Registration Certificate (ERC). 

To ensure full legal compliance, your workspace provider should meet the following requirements: 

  • Legally valid sublease agreement: The provider should issue a lease agreement that is legally acceptable for business registration. 
  • Proper zoning and building approval: The building must be officially licensed for commercial business activities. 
  • Fire safety compliance: The property should comply with Vietnam’s fire prevention and firefighting regulations and, where applicable, have been inspected and approved by the relevant authorities. 

At Vina TPT Office, every workspace solution is designed to meet strict legal compliance standards, helping your business registration application proceed smoothly through the approval process. 

Shared-Office-for-Business-Registration-1

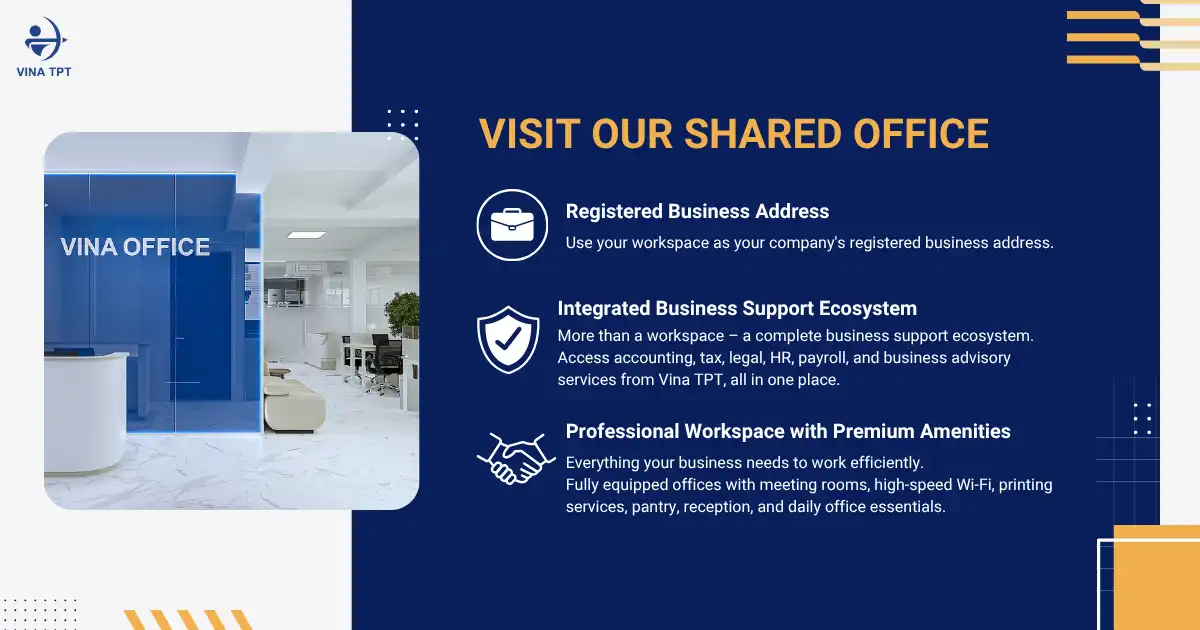
Vina TPT Shared Office: A Complete Business Support Ecosystem 

At Vina TPT, we understand that international investors need more than just office space when starting a business in a new country. Expanding into Vietnam involves navigating complex accounting, taxation, corporate legal matters, and human resources. 

That’s why our shared office is more than simply a workspace rental service—it serves as the physical foundation of a comprehensive business support ecosystem. By combining flexible office solutions with professional advisory services, Vina TPT removes many of the challenges associated with market entry, enabling foreign businesses to operate safely and efficiently from their very first day in Vietnam. 

Premium Amenities at Vina TPT Shared Office 

  • Located at 5th Floor, 75/18-20-22 Hoang Sa Street, Sai Gon Ward, Ho Chi Minh City, Vietnam
  • Vina TPT Office offers a modern and flexible workspace for startups, SMEs, and foreign companies entering the Vietnamese market. 
  • Situated along the scenic Hoang Sa canal, our office combines a peaceful working environment with excellent connectivity to Ho Chi Minh City’s major business districts. 
  • Whether you’re meeting clients, collaborating with your team, or managing day-to-day operations, you’ll enjoy a productive workplace in a highly accessible location. 

To help your team get started immediately, our shared office is equipped with modern infrastructure and professional administrative support, including: 

  • High-Speed Business Internet: Secure, enterprise-grade fiber-optic internet that ensures stable connectivity for uninterrupted global operations. 
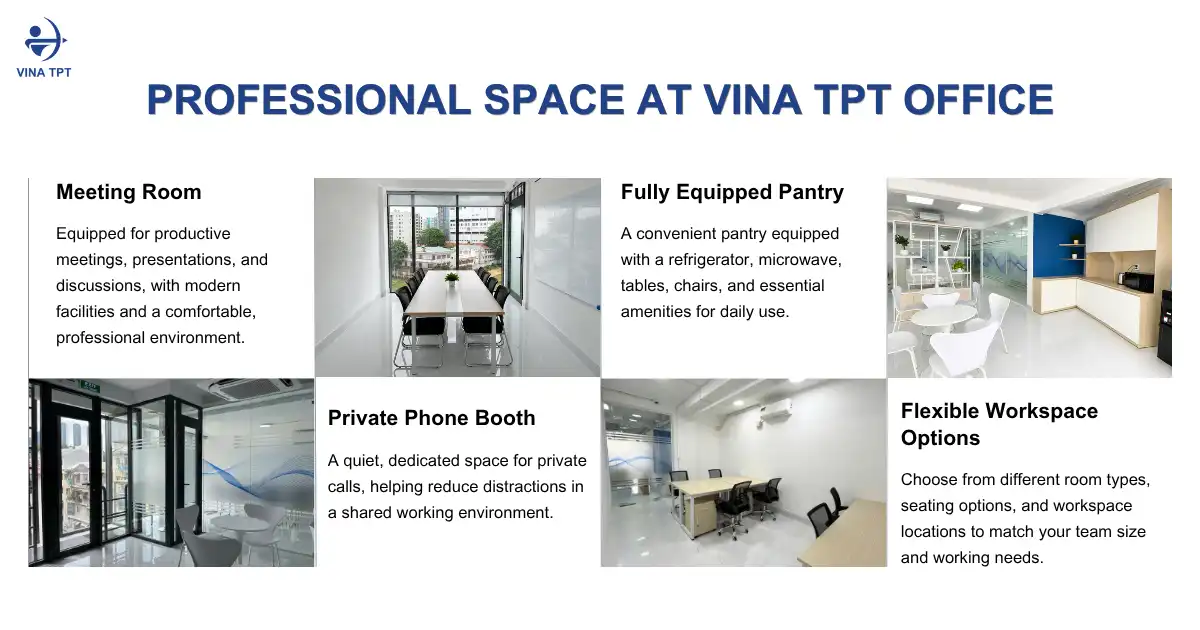
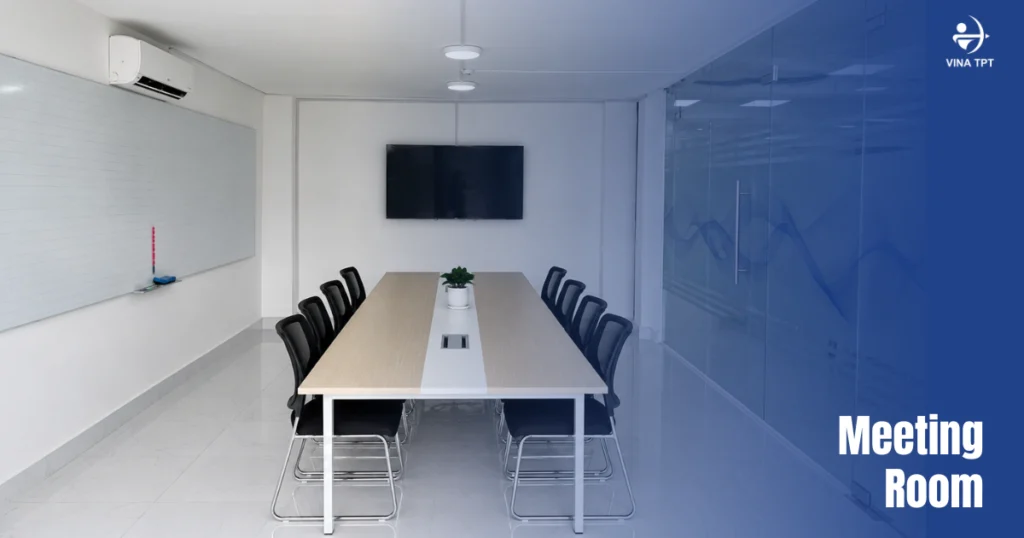
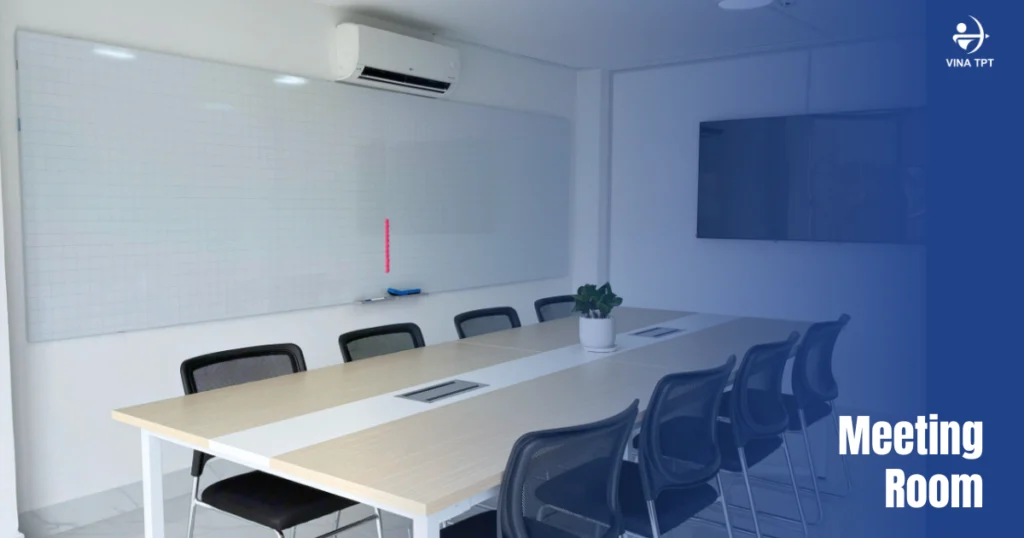
  • Modern Meeting Rooms: Fully equipped meeting rooms featuring whiteboards and large display screens (LED TVs), ideal for client presentations, team meetings, and online conferences. Each meeting room accommodates up to 15 people. 
  • Bilingual Reception Services: Our professional reception team communicates fluently in both English and Vietnamese, welcoming your guests and handling business mail and parcels. 
  • Comfortable Pantry Area: A relaxing shared pantry with complimentary tea and coffee, as well as a refrigerator and microwave, creating a welcoming space for networking and informal discussions. 

Why Choose Vina TPT Shared Office? 

Choosing Vina TPT Office as your workspace partner gives your business more than just a place to work. It provides an integrated business ecosystem that helps you establish, operate, and grow your company in Vietnam with confidence.

Comprehensive Business Ecosystem

More than a shared office, Vina TPT Office connects your workspace with a full range of professional business services. Whether you need accounting, tax compliance, legal advisory, payroll, HR support, or company incorporation, our in-house experts are ready to assist. This integrated approach allows you to focus on growing your business while we take care of the operational and compliance requirements.
Full Legal Compliance

Doing business in Vietnam requires ongoing compliance with corporate, tax, and labor regulations. Backed by Vina TPT’s experienced accounting, tax, and legal professionals, our office solutions are designed to support your business from incorporation through daily operations. We help reduce compliance risks, avoid unnecessary penalties, and ensure your company stays on the right track as regulations evolve.

Save Time and Reduce Costs

Managing separate providers for office rental, accounting, tax, payroll, and legal support can be time-consuming and costly. With Vina TPT Office, everything is coordinated under one trusted partner. This streamlined approach reduces administrative workload, improves communication, and helps your business save both time and operational expenses.

Move In and Start Working Immediately

Our fully furnished shared office is ready for your team from day one. There’s no need to invest in office fit-outs, furniture, internet installation, or administrative setup. Simply move in and start working in a professional environment with meeting rooms, reception services, high-speed Wi-Fi, printing facilities, and other essential amenities already in place – allowing you to accelerate your market entry and preserve valuable startup capital.

services-vina-tpt-business-ecosystem-1

How Much Does a Shared Office Cost in Vietnam? 

Understanding the local market helps foreign investors estimate operating costs more accurately. Shared office rental rates in Vietnam vary depending on the location and level of service provided. 

  • Hot Desks / Flexible Desks: USD 80–150 per month: Ideal for freelancers, independent professionals, and business travelers who need occasional access to a professional workspace. 
  • Dedicated Desks: USD 150–250 per month: A personal workstation with a lockable storage cabinet, making it an excellent choice for growing teams that require a permanent workspace. 
  • Private Serviced Offices: Starting from USD 500–700+ per month: Fully enclosed, secure private offices designed for branch offices or businesses that require dedicated operational space. 

Vina TPT offers competitive and transparent pricing with no hidden fees, along with flexible quarterly and annual payment options to accommodate different business needs. 

As an exclusive benefit, clients who use Vina TPT’s company incorporation services can enjoy complimentary access to our Shared Office while waiting for their business registration procedures to be completed. This allows businesses to reduce startup costs and begin preparing for operations even before receiving their Enterprise Registration Certificate (ERC). 

Frequently Asked Questions (FAQs) About Shared Offices in Vietnam 

Q: Can a 100% foreign-owned enterprise (FIE) use a shared office address to register a company in Vietnam? 

A: Yes. A foreign-invested enterprise (FIE) can use a shared office as its registered business address, provided that the workspace provider offers all required legal documentation, including a valid sublease agreement, and the property is officially approved for commercial business activities by the relevant authorities. 

Q: Does the Shared Office rental fee include management fees, electricity, and other operating costs? 

A: Yes. The Shared Office rental fee at Vina Office is all-inclusive, covering management fees, electricity, internet, cleaning, and other standard operating costs. There are no hidden charges, so you can move in and start working immediately without worrying about additional monthly facility fees. 

Q: Can I rent a Shared Office from Vina TPT without using any of its other services? 

A: Currently, our Shared Office service is available exclusively to clients who are already using other services within the Vina TPT ecosystem, such as: 

  • Company incorporation 
  • Accounting services 
  • Tax services 
  • Payroll services 
  • Corporate legal services 
  • Other related business advisory services 

This policy is designed to ensure legal compliance, operational security, and consistent service quality for all of our clients. 

By supporting businesses throughout their entire journey—from company formation to daily operations—we gain a thorough understanding of each client’s legal status. This enables us to provide more effective support in managing registered business addresses, receiving official correspondence, communicating with government authorities, and handling ongoing compliance matters. 

BOOK A FREE OFFICE TOUR AND GET QUOTE


Vietnam Tax Compliance for FDI Business: Key Taxes & CPA Support

Vietnam-Tax-Compliance-for-FDI-Key-Taxes-CPA-Services-scaled.webp

Vietnam Tax Compliance for FDI Key Taxes & CPA Services

For foreign investors entering the Vietnamese market, tax compliance is not simply an obligation to pay taxes to the state budget, but a critical factor that directly impacts the financial safety and long-term sustainability of the investment project. Language barriers, the complexity of the local legal system, and the frequent updates to sub-law documents often turn tax management into the biggest “bottleneck” for FDI company management.

Even a small mistake in identifying invalid invoices, incorrectly posting non-deductible expenses, or late declaration of contractor taxes can result in heavy administrative fines, additional tax assessments with 0.03% daily late payment interest, or prolonged tax inspections that disrupt the entire supply chain.

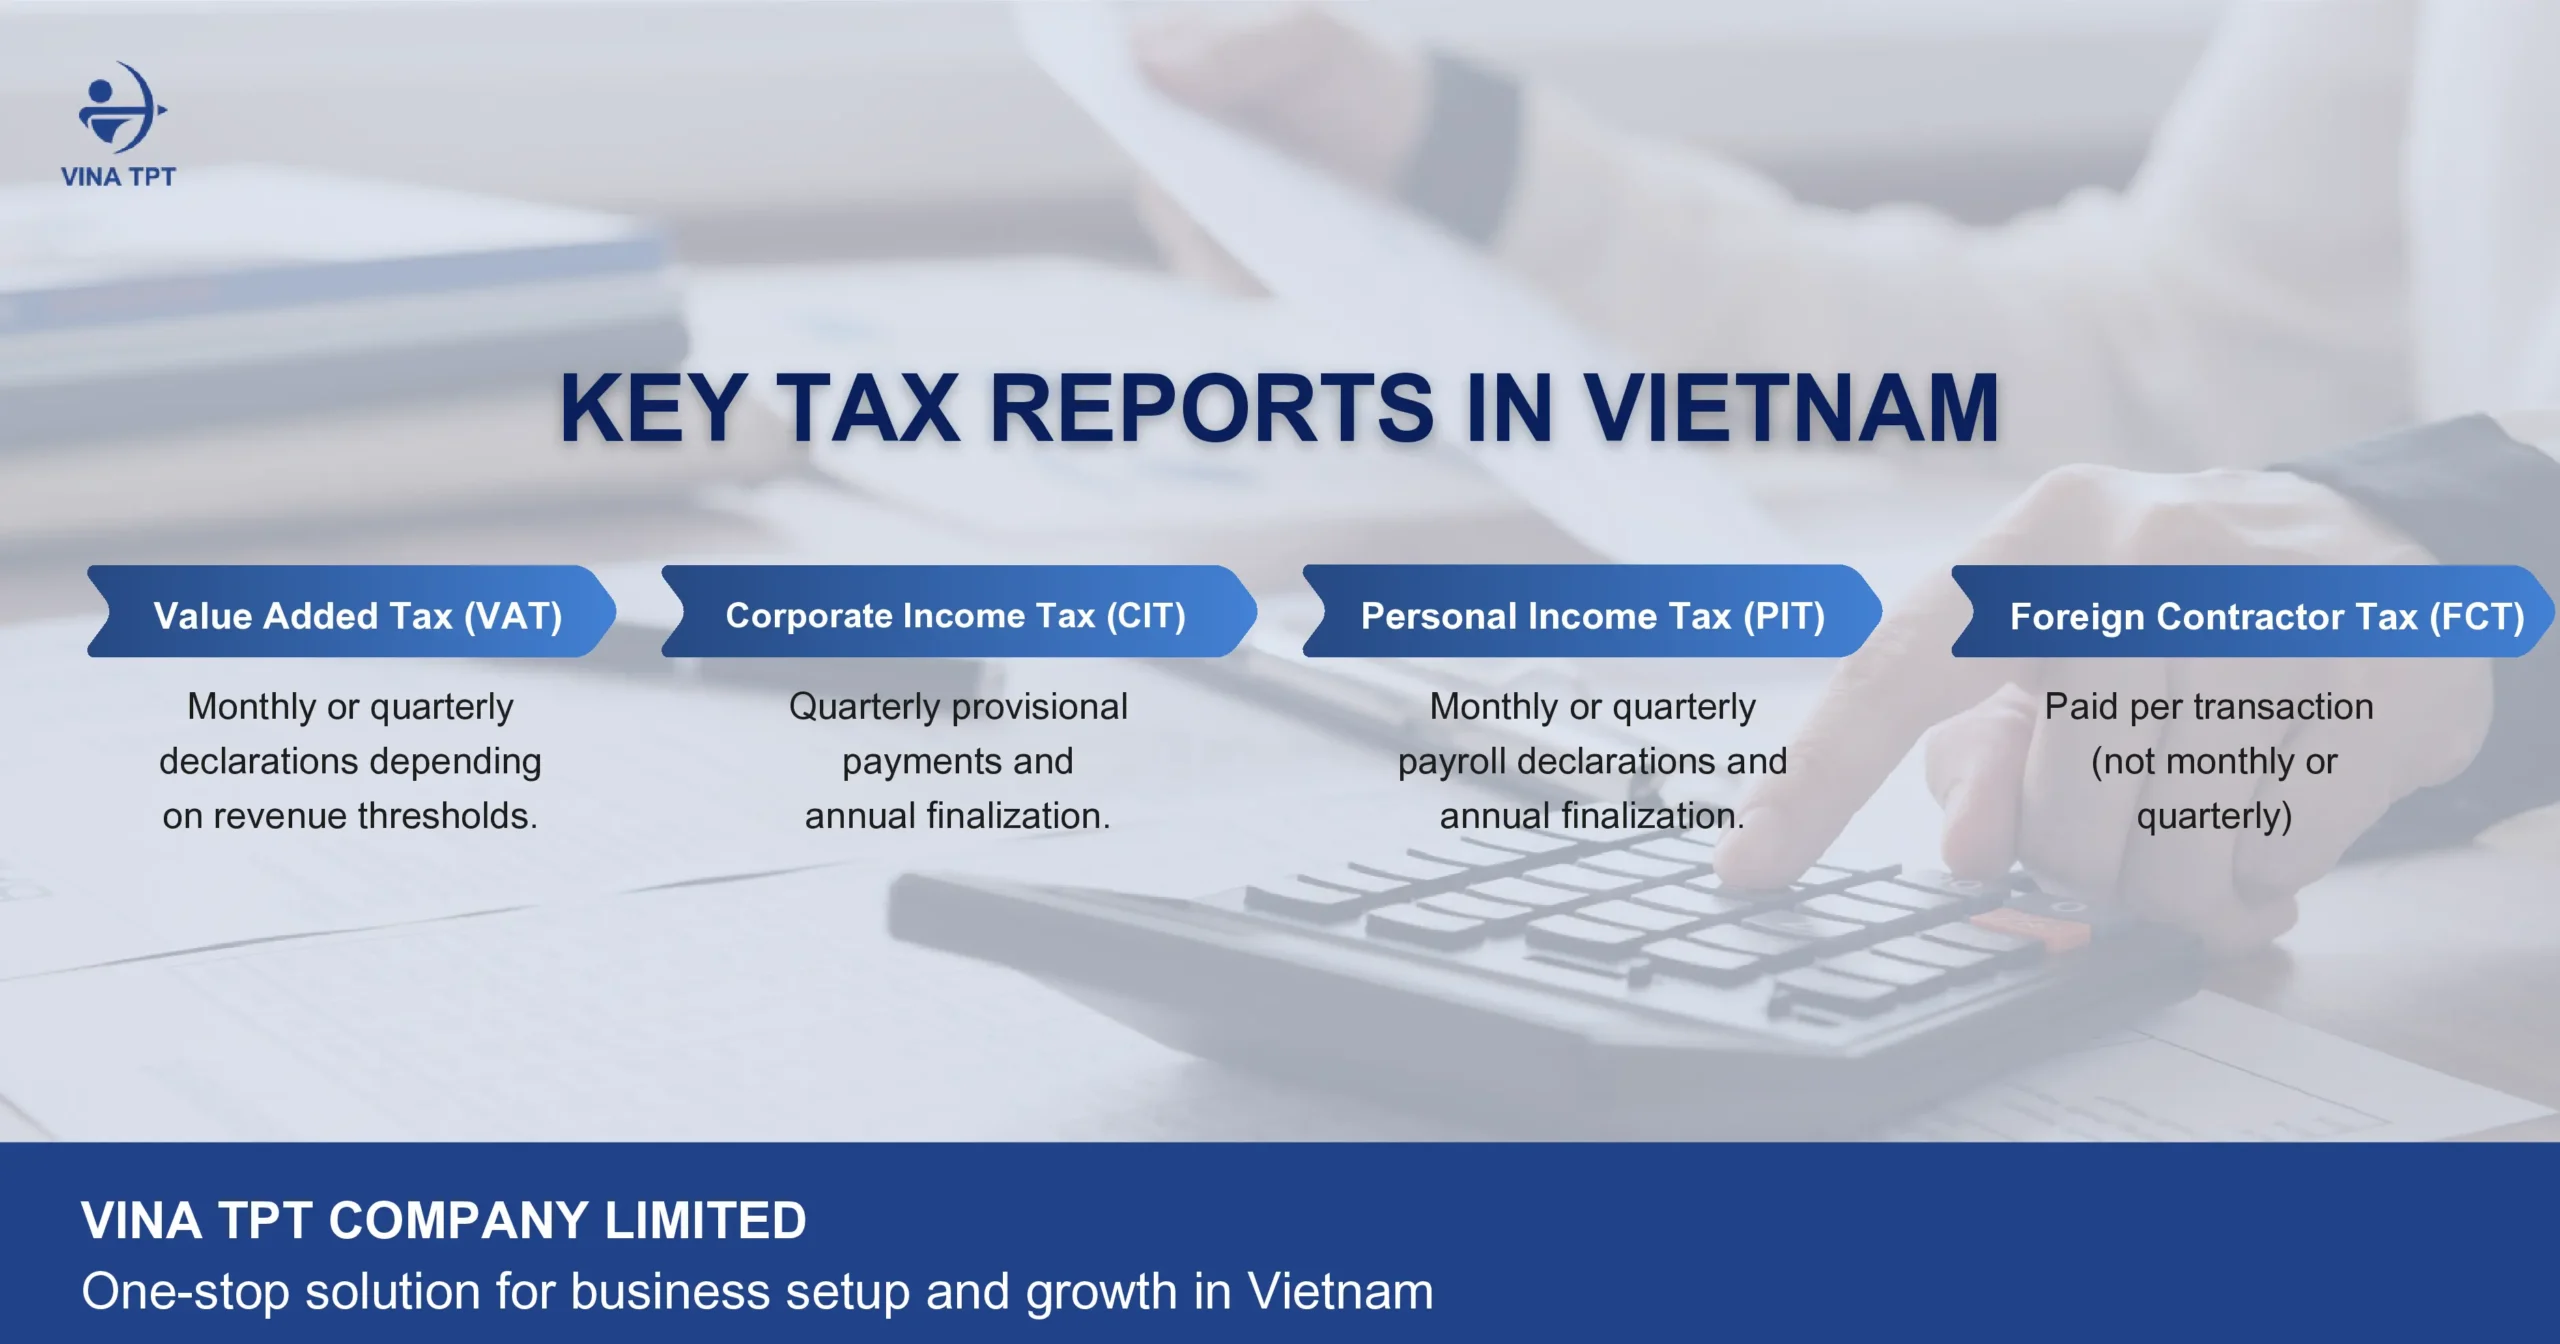
This article provides a comprehensive overview of tax compliance Vietnam FDI, an in-depth analysis of the four core taxes (VAT, CIT, PIT, FCT) with the latest legal obligations, and reveals Vina TPT’s specialized Vietnam tax obligations for foreign companies solutions to help investors take full control of their financial game in Vietnam.

Vietnam Tax Compliance for FDI Key Taxes & CPA Services

1. Value-Added Tax (VAT) – The Most Important Tax Obligation for all Businesses

Value-Added Tax (VAT) is an indirect tax with the highest transaction frequency and the strictest supervision from local tax authorities. It is a mandatory obligation applicable to all business sectors of FDI companies in Vietnam, including trading, manufacturing, services, import-export, and other fields.

1.1. Legal Basis & Declaration Cycle

According to the Law on Value-Added Tax 2008 (as amended and supplemented) and the latest guidance in Decree 181/2025/ND-CP, newly established FDI enterprises or those with annual revenue of VND 50 billion or less in the previous year must declare VAT on a quarterly basis. Enterprises with previous year revenue exceeding VND 50 billion are required to declare VAT on a monthly basis.

1.2. Strict Conditions for Input VAT Deduction

To be eligible for input VAT deduction, the accounting department of an FDI company must simultaneously meet the following conditions:

  • Have a valid VAT invoice (issued with a tax authority code under Decree 123/2020/ND-CP).
  • Have non-cash payment documents (bank transfer from the buyer’s account to the seller’s account) for invoices valued at VND 5 million or more (including VAT).
  • The purchased goods or services must be directly used for the production or business of goods and services subject to VAT.

2. Corporate Income Tax (CIT) – Profit-Based Tax & the Provisional Payment Calculation

Corporate Income Tax (CIT) directly affects the net profit of foreign investors. Understanding the provisional payment rules and tax incentive mechanisms is the key to optimizing capital efficiency.

2.1. Standard Tax Rate & Quarterly Provisional Payment Rule (80% Rule)

The standard Corporate Income Tax (CIT) rate in Vietnam is currently 20% on taxable income. However, according to the new regulations in 2025, certain enterprises that meet the preferential conditions may enjoy lower tax rates:

  • 15%: Applied to enterprises with annual total revenue not exceeding VND 3 billion.
  • 17%: Applied to enterprises with annual total revenue from over VND 3 billion up to VND 50 billion.

Special Note on the 80% Rule:

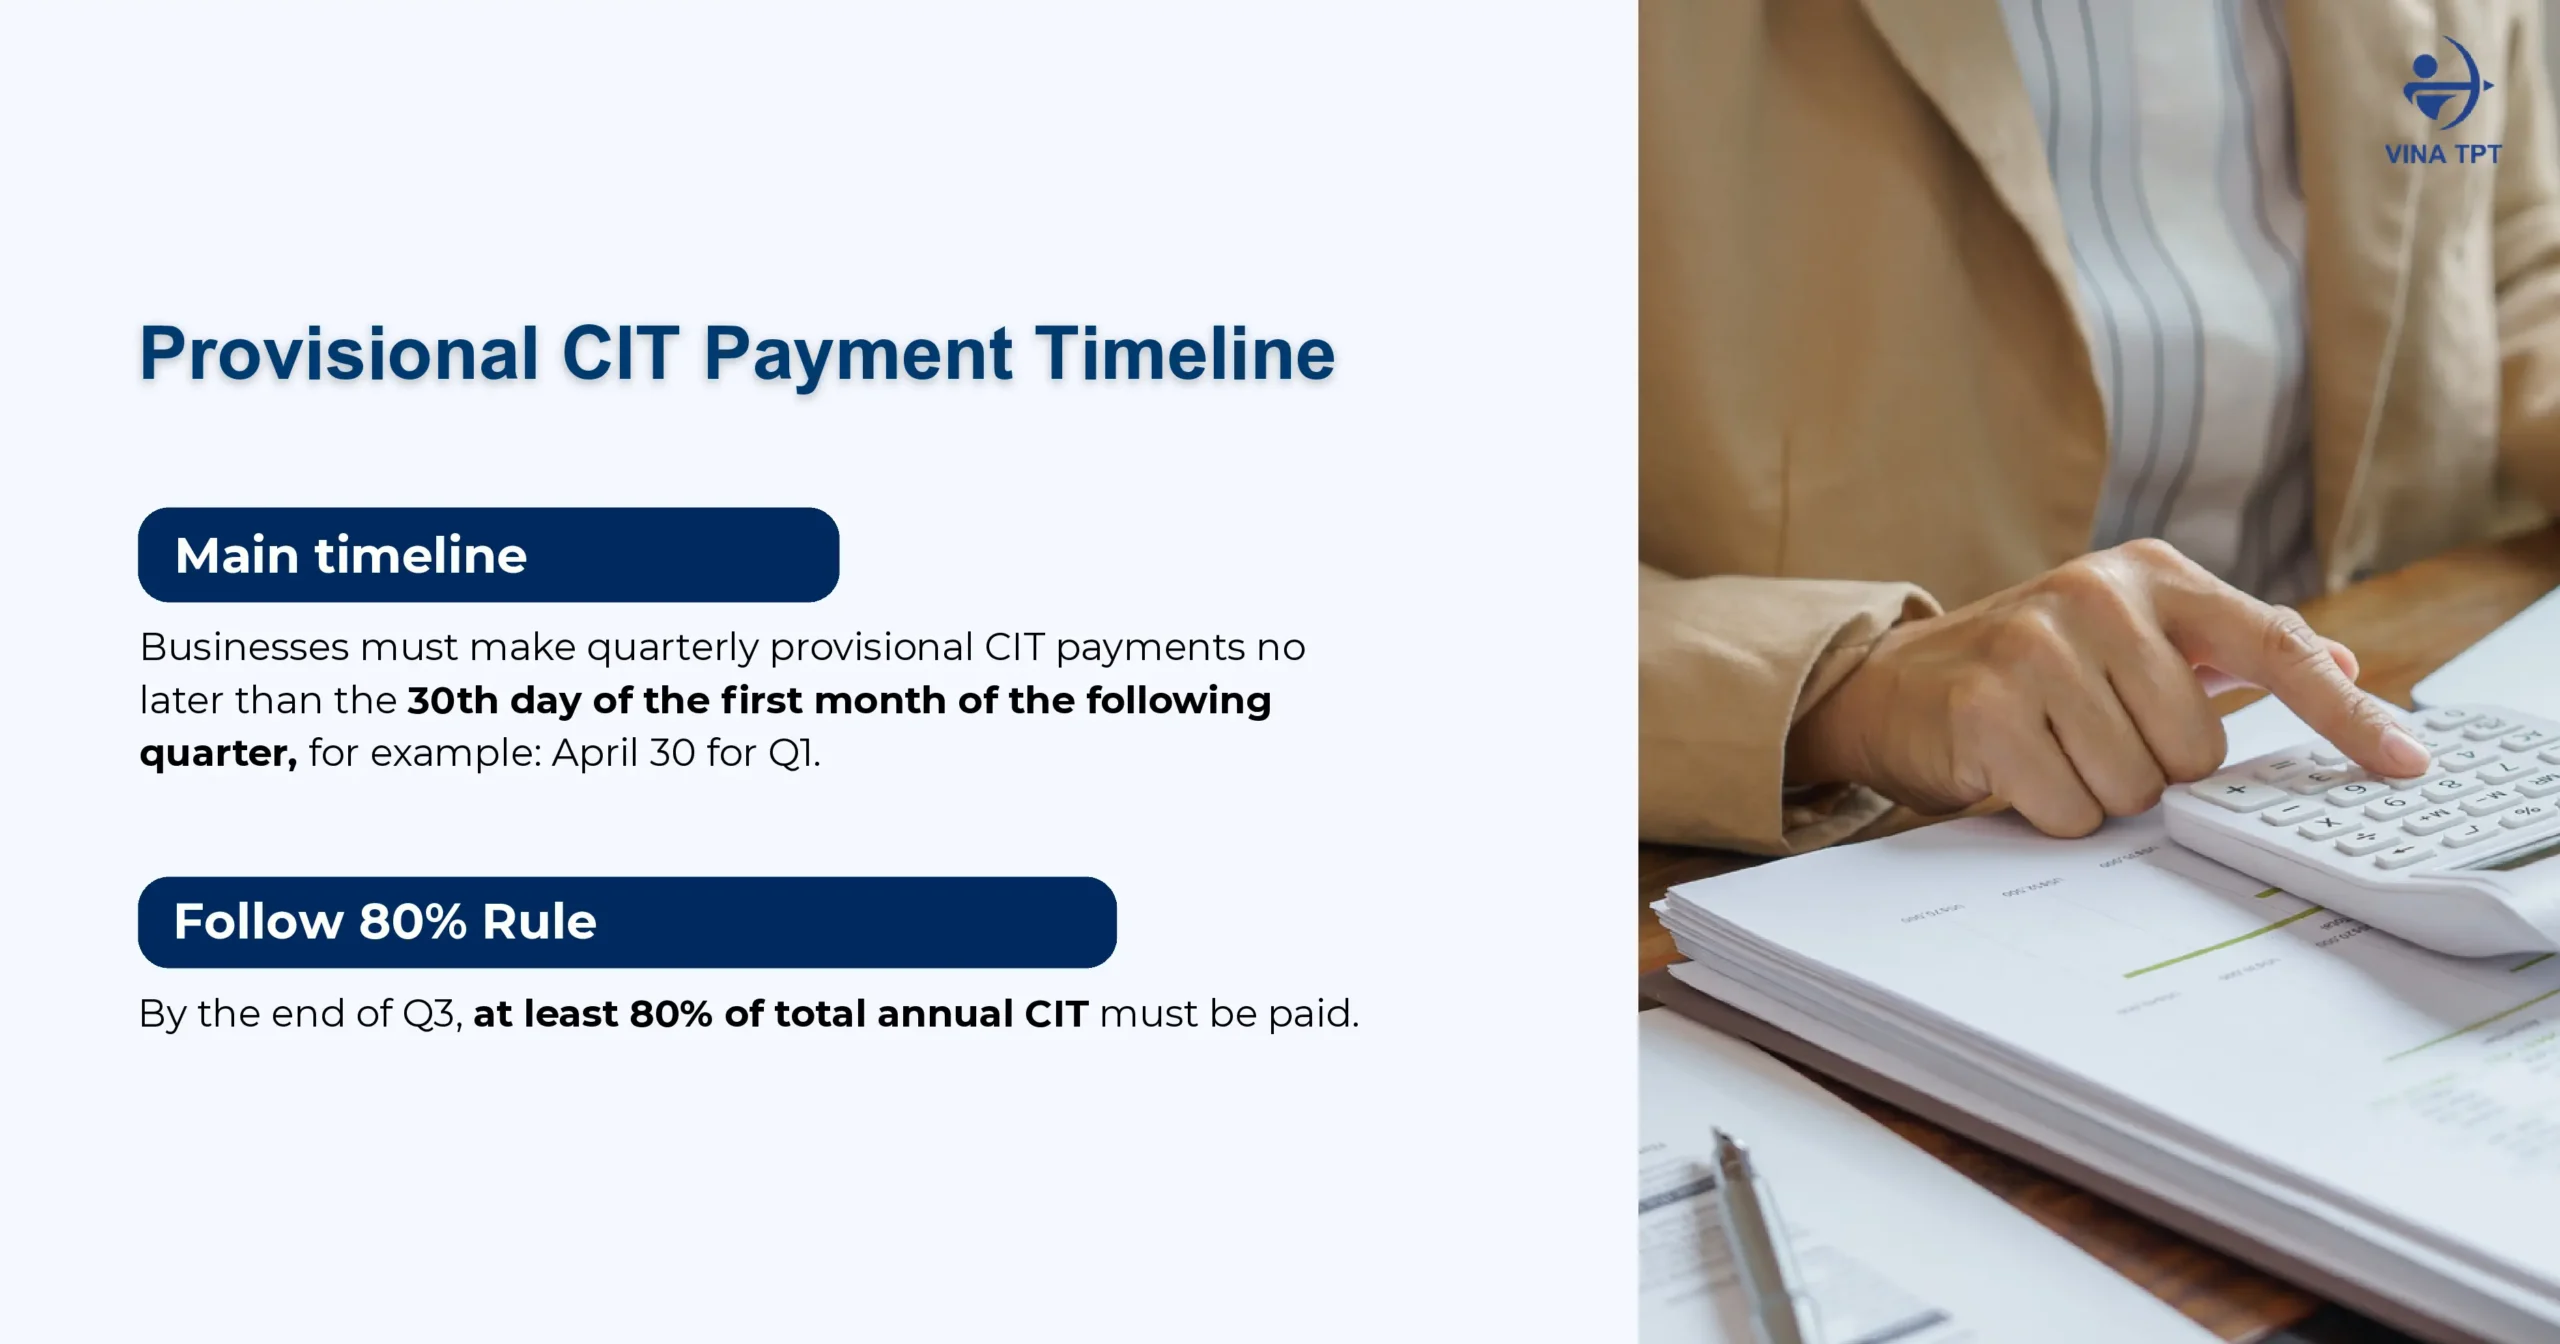
Special Note on the 80% Rule: According to current regulations, the total CIT amount provisionally paid for the four quarters of the tax year must not be less than 80% of the final CIT amount payable upon annual finalization. If the payment falls short of this 80% threshold, the company will be charged late payment interest (0.03% per day) on the shortfall, starting from the day after the deadline for the fourth-quarter tax payment.

2.2. Tax Incentive Mechanism (Tax Incentives) under the Law on Investment 2020

FDI companies can take advantage of attractive tax incentive packages if they meet the conditions regarding location or investment priority sectors according to Decree 31/2021/ND-CP:

Type of Incentive

Incentive Level

Conditions & Applicable Sectors

Preferential tax rate of 10% For 15 years (extendable to 30 years) High-tech projects, high-tech applications, R&D, renewable energy.
100% Exemption & 50% Reduction Exemption for 4 years, 50% reduction for the next 9 years Newly established projects in industrial parks, economic zones, or areas with particularly difficult socio-economic conditions.
Preferential tax rate of 15%–17% Applied throughout the project duration Enterprises meeting capital scale or large labor usage criteria as prescribed.

Key updates in 2025:

  • Enterprises are allowed to expand deductible expenses related to scientific research, digital transformation, new technology testing, emission reduction, and community activities.
  • If eligible for multiple incentive groups, the enterprise has the right to choose the most favorable incentive level.
  • Losses can be carried forward continuously for a maximum of 5 years, and up to 20% of taxable income may be set aside to establish a Science & Technology Development Fund (if used for the correct purposes).

Real-life example: A Korean technology corporation established a software factory in Ho Chi Minh City High-Tech Park. By correctly applying for CIT incentives, the company enjoys a 10% tax rate for 15 years, 100% CIT exemption for the first 4 years (from the year it has taxable income), and a 50% reduction for the next 9 years – saving millions of USD in taxes.

>>> For a more detailed and complete update on all Corporate Income Tax incentive policies in 2025, read the article: Tax Incentive in Vietnam 2025: Comprehensive Guide to Optimize Profits under New CIT Law

Vietnam Tax Compliance for FDI Key Taxes & CPA Services

Get Expert Advice on Tax Incentive Policies

3. Personal Income Tax (PIT) and Social Insurance Responsibilities for Personnel

Compliance with Personal Income Tax (PIT) and Social Insurance (BHXH) for the workforce – especially for foreign experts and managers (Expats) – always carries significant risks of additional tax assessments if residency status is not correctly classified.

3.1. PIT Withholding & Residency Classification Rules

FDI companies are obligated to withhold, declare, and pay Personal Income Tax (PIT) on a monthly or quarterly basis before paying income to employees:

  • Resident Individuals: Present in Vietnam for 183 days or more in a calendar year (or 12 consecutive months). Progressive tax rates from 5% to 35% apply on worldwide income (Global Income).
  • Non-Resident Individuals: A non-resident individual is a person who does not meet the conditions of a resident individual, specifically someone who is present in Vietnam for fewer than 183 days in the tax year and does not have a permanent residence in Vietnam.

3.2. Mandatory Social Insurance (BHXH) Responsibilities

According to the Law on Social Insurance and related regulations, FDI companies must contribute the following for employees:

  • Vietnamese Employees: Contributions to Social Insurance, Health Insurance, and Unemployment Insurance at a total rate of 32% (Employer: 21.5%, Employee: 10.5%).
  • Foreign Employees (Expats): Mandatory participation in Social Insurance and Health Insurance if they hold a Work Permit and have an employment contract that is indefinite or has a term of 1 year or longer.

>>> For more details: 

4. Foreign Contractor Tax (FCT) and Related Legal Obligations

Foreign Contractor Tax (FCT) is a special tax that many newly operating FDI companies often overlook, leading to declaration violations and penalties.

4.1. Nature & Mechanism of FCT Collection

FCT applies to foreign organizations and individuals who do not operate under Vietnamese law but generate income from providing services or goods associated with services in Vietnam (such as software royalties, parent company management consulting fees, cross-border digital marketing services, etc.).

FCT consists of two main components: VAT and Corporate Income Tax (or Personal Income Tax). The FDI company in Vietnam is responsible for withholding, declaring, and paying FCT on behalf of the foreign contractor before remitting payment.

Example: An FDI company pays USD 100,000 in software royalty fees to its parent company in Singapore. The company must determine the applicable FCT rate (typically 5% CIT on royalties), register a contractor tax code, and declare and pay FCT within 10 days from the payment date.

4.2. 2. Other Mandatory Fees & Periodic Reporting Obligations

In addition to the four main taxes, Vietnam tax obligations for foreign companies also include the Investment Activity Report (IAR): Periodic declaration and reporting of project implementation status on the National Investment Information System.

5. Benefits of Using Vina TPT’s Tax Compliance Services

When choosing to partner with Vina TPT, FDI companies are not simply using an external tax filing service – they are proactively equipping themselves with a solid “financial shield” for the entire operational process in Vietnam.

Instead of maintaining a bulky in-house accounting and tax team with high costs while still facing risks of staff turnover or lack of legal update capabilities, partnering with Vina TPT helps businesses optimize operating costs by up to 40%. More importantly, thanks to a 3-level independent quality control model operated by experienced CPA and Chief Accountant experts, all risks of additional tax assessments, administrative penalties, or errors during finalization are eliminated at the root.

In addition to legal safety, Vina TPT acts as a strategic advisor, helping businesses legally maximize tax incentives and optimize deductible expense structures in line with the spirit of the Corporate Income Tax Law. At the same time, all financial data is standardized into bilingual management reports (English & Vietnamese), creating a transparent information bridge that allows the Board of Directors and overseas Headquarters to easily grasp the accurate financial picture in real time. All of this brings complete peace of mind, allowing foreign investors to focus entirely on market expansion goals.

Are you concerned about tax compliance? Contact Vina TPT today to receive a free consultation and specialized tax compliance services.

BOOK A FREE CONSULTATION

Vietnam Tax Compliance for FDI Key Taxes & CPA Services


Accounting Advisory Services in Vietnam: Trusted CPA Expertise

Accounting Advisory Services in Vietnam Trusted CPA Expertise

Accounting Advisory Services in Vietnam Trusted CPA Expertise

When operating a foreign-invested enterprise (FDI) in Vietnam, the difference between “compliance accounting” and “strategic accounting advisory” is significant. The complexity of the tax policy system, Transfer Pricing regulations, and the differences between Vietnamese Accounting Standards (VAS) and International Financial Reporting Standards (IFRS) often expose management to hidden financial risks that standard data-entry services cannot detect.

This is why successful FDI companies always seek the support of accounting advisory services. Going far beyond simply cleaning the books or submitting reports on time, in-depth advisory services provide a comprehensive view of the financial landscape, helping investors legally optimize tax obligations, control audit risks, and confidently make strategic business decisions.

This article analyzes in detail the real value that a professional accounting advisory Vietnam service brings to your business, and how our team of CPA experts accompanies you to protect your invested capital in Vietnam.

1. What Challenges Does Accounting Advisory Solve for FDI Companies?

Rather than simply recording transactions that have already occurred, an in-depth accounting advisory services system is designed to proactively resolve the core issues throughout the entire operational cycle of FDI companies in Vietnam:

  • Standardization of Accounting Books & Document Management according to VAS: Ensures all transactions are supported by legal and valid documents as required by the Vietnamese Ministry of Finance. Electronic invoices and supporting documents are thoroughly reviewed and securely digitized, keeping the business always prepared for audits.
  • Financial Statement Reconciliation & Management Reporting: Converts data from VAS to IFRS or US GAAP for transparent reporting to overseas headquarters. At the same time, it builds a management reporting system (P&L, cash flow, cost by center) that helps leadership understand the real financial health for timely decision-making.
  • Tax Structure Optimization & VAT Refund Support: Develops legitimate deductible expense structures under the Corporate Income Tax Law and maximizes tax incentives by location and industry. Prepares and represents the company in VAT refund procedures for new investment projects or export activities quickly and legally.
  • Tax Health Check Program (Tax Review & Health Check): Conducts a comprehensive review of past accounting records and tax declarations to detect early risk points, eliminate illegitimate expenses, and propose corrective measures before the tax authorities issue an inspection decision.
  • Transfer Pricing Compliance Advisory: Assists in preparing transfer pricing documentation, advises on optimal debt-to-equity structures, helping the company achieve 100% legal compliance and avoid the risk of tax assessment.
  • Protection During Audits & Tax Inspections: Acts as the main point of contact when working directly with independent audit firms. Represents the company in providing in-depth explanations and maximally protects legitimate rights and interests before tax inspection teams.

2. How to Evaluate a Reputable and Suitable CPA Team for Your FDI Company

The quality of CPA advisory services Vietnam is not determined by beautiful promises, but directly by the practical capability and legal qualifications of the personnel who directly handle your company’s files. To avoid the risk of misplaced trust in inexperienced providers, foreign investors can evaluate a CPA team’s capability based on the following 3 golden criteria:

  1. Official Professional Credentials: The responsible experts must hold official CPA Vietnam certificates issued by the Ministry of Finance or reputable international certifications (CPA Australia, ACCA, CA). These serve as legal proof of their ability to sign reports, understand tax laws, and take professional responsibility before the law.
  2. Ability to “Translate” Between VAS and IFRS: For FDI companies, a good CPA must not only understand Vietnamese Accounting Standards (VAS) to work with tax authorities, but also master International Financial Reporting Standards (IFRS) to clearly explain financial data to overseas headquarters.
  3. Real-World Explanation Experience (Battle-tested Experience): Credentials are necessary, but hands-on experience representing companies during actual tax inspections and finalizations is what truly protects the investor’s capital.

Meeting these strict criteria, the core expert team at Vina TPT serves as a solid professional foundation for international investors:

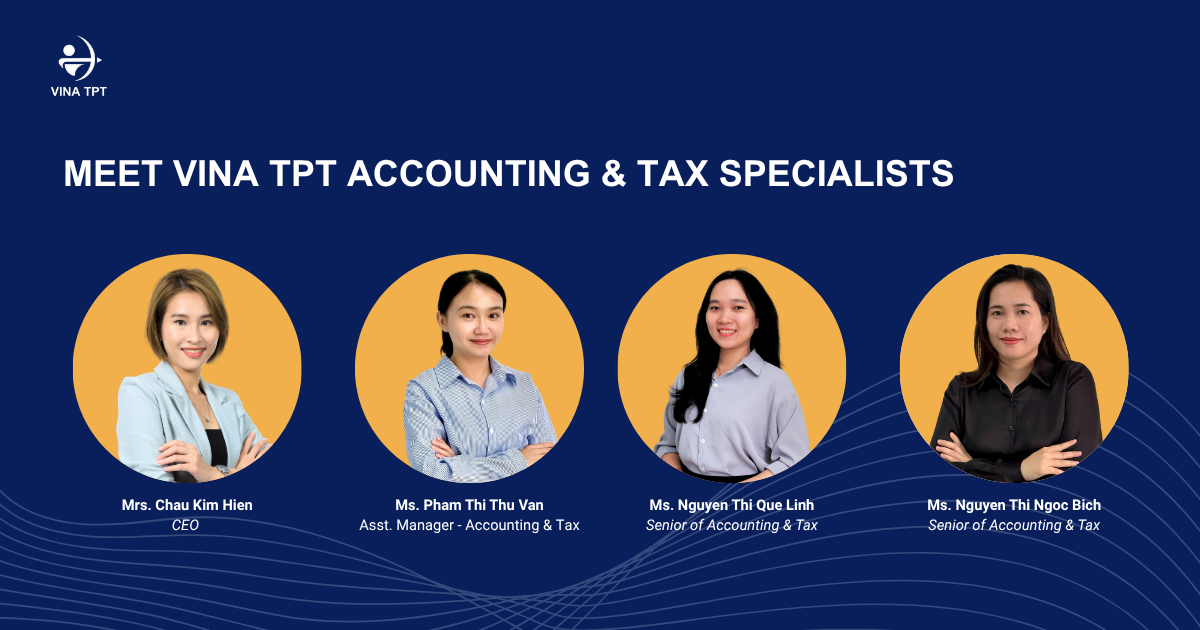
  • Mrs. Chau Kim Hien – Executive Director: With over 10 years of specialized experience in FDI finance and tax, Ms. Hiền directly advises on strategic matters for complex business models. She has particular strengths in bridging international IFRS management needs with local VAS implementation in Manufacturing, IT, Trading Services, and Construction sectors.
  • Ms. Pham Thi Thu Van – Assistant Manager – Accounting & Tax: A Certified Public Accountant (CPA) with over 7 years of hands-on experience. Ms. Vân specializes in establishing internal control systems, building transparent financial reporting structures, and optimizing tax risks for multinational corporations.
  • Mr. Huynh Quoc Khanh – Senior Accounting & Tax: Holds the Chief Accountant Certificate issued by the Ministry of Finance and has over 7 years of experience supporting Korean-invested enterprises. He is known for his ability to identify tax risks early and successfully represent clients during tax inspections.
  • Ms. Nguyen Thi Ngoc Bich – Senior Accounting & Tax: Holds the Chief Accountant Certificate issued by the Ministry of Finance and has over 7 years of experience in accounting and taxation, specializing in supporting Japanese enterprises across various industries. She is recognized for ensuring regulatory compliance while helping clients improve operational efficiency.

Notably, the entire team operates in a bilingual (English & Vietnamese) working model, helping investors fully understand every legal and financial issue without any language barriers.

3. 5 Core Questions When Choosing an Accounting Advisory Services Provider

To find a truly high-quality financial and accounting consulting partner and avoid the risk of choosing low-cost, low-capability providers, the Board of Directors of FDI companies should ask the following 5 direct questions during the partner evaluation process:

1. “What professional credentials do the team members directly handling our files hold, and how is the language coordination process handled?”

A common reality in the market is that many accounting firms use the reputation of senior experts to sign contracts, but later assign all bookkeeping work to staff with insufficient experience. FDI companies should request clear confirmation of the identity of the person directly responsible for their files. This person must hold reputable professional credentials (CPA, Chief Accountant Certificate, Tax Agent Certificate).

In addition, the language factor should be viewed realistically: a highly skilled technical expert does not necessarily need to be fluent in every local foreign language. A professional consulting firm will have a flexible coordination mechanism – if the responsible expert does not communicate directly in the investor’s language (such as Japanese or Chinese), the firm must have a dedicated financial interpreter team to ensure that all technical information is conveyed with 100% accuracy and is not distorted by language barriers.

2. “Is your service structure based on standard pre-packaged packages or do you offer tailored solutions designed for each industry?”

Every FDI company entering Vietnam has a different scale and budget orientation. A reputable consulting firm will offer standard accounting service packages – an optimized solution that helps the majority of small and medium-sized FDI companies quickly fulfill their legal compliance obligations at a highly reasonable cost.

However, for industries with complex financial structures and cash flows such as Real Estate, large-scale Manufacturing, F&B chains, or IT Technology, a high-end consulting firm will flexibly design (tailor) in-depth solutions based on an actual operational survey. The combination of cost-effective standard packages and flexible customized solutions is the key to fully meeting every investor’s needs.

3. “Does the firm have the capability to convert financial statements from VAS to international standards such as IFRS?” Compliance with Vietnamese Accounting Standards (VAS) is mandatory for working with local tax authorities. However, the Board of Directors and foreign shareholders need reports prepared under international standards IFRS for consolidated group reporting and accurate investment performance evaluation. A reputable accounting advisory services provider must act as a “standards bridge”, helping to convert accounting data transparently and accurately between the two systems.

4. “What is your quality control process for accounting books and tax reporting?” Errors in accounting and tax declarations often stem from individual oversight. To eliminate this risk, a professional consulting partner must operate a multi-layer quality control mechanism (Double-check or Triple-check). All data prepared by accountants must undergo independent review by a Chief Accountant or CPA before being officially submitted to state authorities or sent to clients.

5. “Does your firm commit to accompanying the company and directly representing it during tax inspections?” This is considered the highest “responsibility benchmark” of a consulting firm. The true capability of a partner is demonstrated by their willingness to stand up and defend the legality of the figures, invoices, and tax arguments they themselves prepared.

Asking these direct questions not only helps investors clearly see the real capability of the consulting firm but also serves as an important screening step to protect the company’s capital and reputation in the Vietnamese market. If you are looking for a partner that fully meets these strict standards, Vina TPT is the most comprehensive answer.

Explore Vina TPT's Accounting Advisory Services

4. Why International FDI Companies Choose Vina TPT’s Accounting Advisory Services

Meeting the strictest criteria of foreign investors, Vina TPT has established itself as a leading strategic financial and tax advisory partner in Vietnam thanks to the following outstanding competitive advantages:

  • Over 20 years of hands-on experience supporting FDI: We have a deep understanding of management mindsets, risk appetites, and cultural nuances of different investor groups (Japan, Korea, Singapore, Europe, US…).
  • 3-Level Quality Control Process: Every accounting and tax file undergoes rigorous review through three layers: Assistant -> Senior Accountant -> Manager. This “triple-check” mechanism ensures the highest accuracy and minimizes the risk of errors.
  • Direct Support from CPA & Chief Accountant Team: 100% of our clients’ accounting and tax files are handled by experts holding CPA qualifications and Chief Accountant certificates issued by the Ministry of Finance.
  • Tax Obligation Optimization & Operating Cost Savings: We help businesses proactively maximize legal tax incentives, build transparent cash flow structures, and completely eliminate risks of late-payment fines or additional tax assessments.
  • Sharp Management Reporting & IFRS Conversion: We provide leadership with accurate, detailed financial pictures in English/Vietnamese, strongly supporting the parent company in consolidated reporting and investment decision-making.
  • Flexible Remote Operation Support (Remote Support): Integrated with high-security cloud storage technology, allowing investors to easily monitor, control, and approve financial data in Vietnam in real time, even from abroad.

Are you looking for a reputable, high-standard accounting advisory services solution to standardize your financial system and optimize tax risks for your business? Contact Vina TPT today to receive a free consultation from our expert team.

BOOK A FREE CONSULTATION

 Accounting-Advisory-Services-in-Vietnam-Trusted-CPA-Expertise

Tax and Accounting Services in Vietnam: Comprehensive FDI Solutions

Tax-and-Accounting-Services-in-Vietnam

Tax and Accounting Services in Vietnam Comprehensive FDI Solutions

For multinational corporations and foreign investors establishing a legal entity in Vietnam, building a financial and accounting system that meets both local legal requirements and international management standards is always a challenging task. Language barriers, the differences between Vietnamese Accounting Standards (VAS) and International Financial Reporting Standards (IFRS), and the frequent adjustments to domestic tax policies often put FDI companies in a passive position.

Operating an in-house accounting team not only consumes a massive operating budget (OPEX) for salaries, insurance, and management software, but also carries significant risks from staff turnover. Even a small oversight in document recording or delayed tax declaration can lead to heavy administrative penalties, additional tax assessments with late payment interest, or disruptions to the entire supply chain.

To completely resolve these management bottlenecks, professional tax and accounting services have become an essential solution for FDI companies operating in Vietnam. By partnering with Vina TPT, you not only gain a team of experts who take full responsibility for the entire end-to-end accounting and tax process, but also completely free up internal resources to focus entirely on your core business growth objectives.

1. Accounting and Bookkeeping Services – The Foundation of Professional Tax and Accounting Services

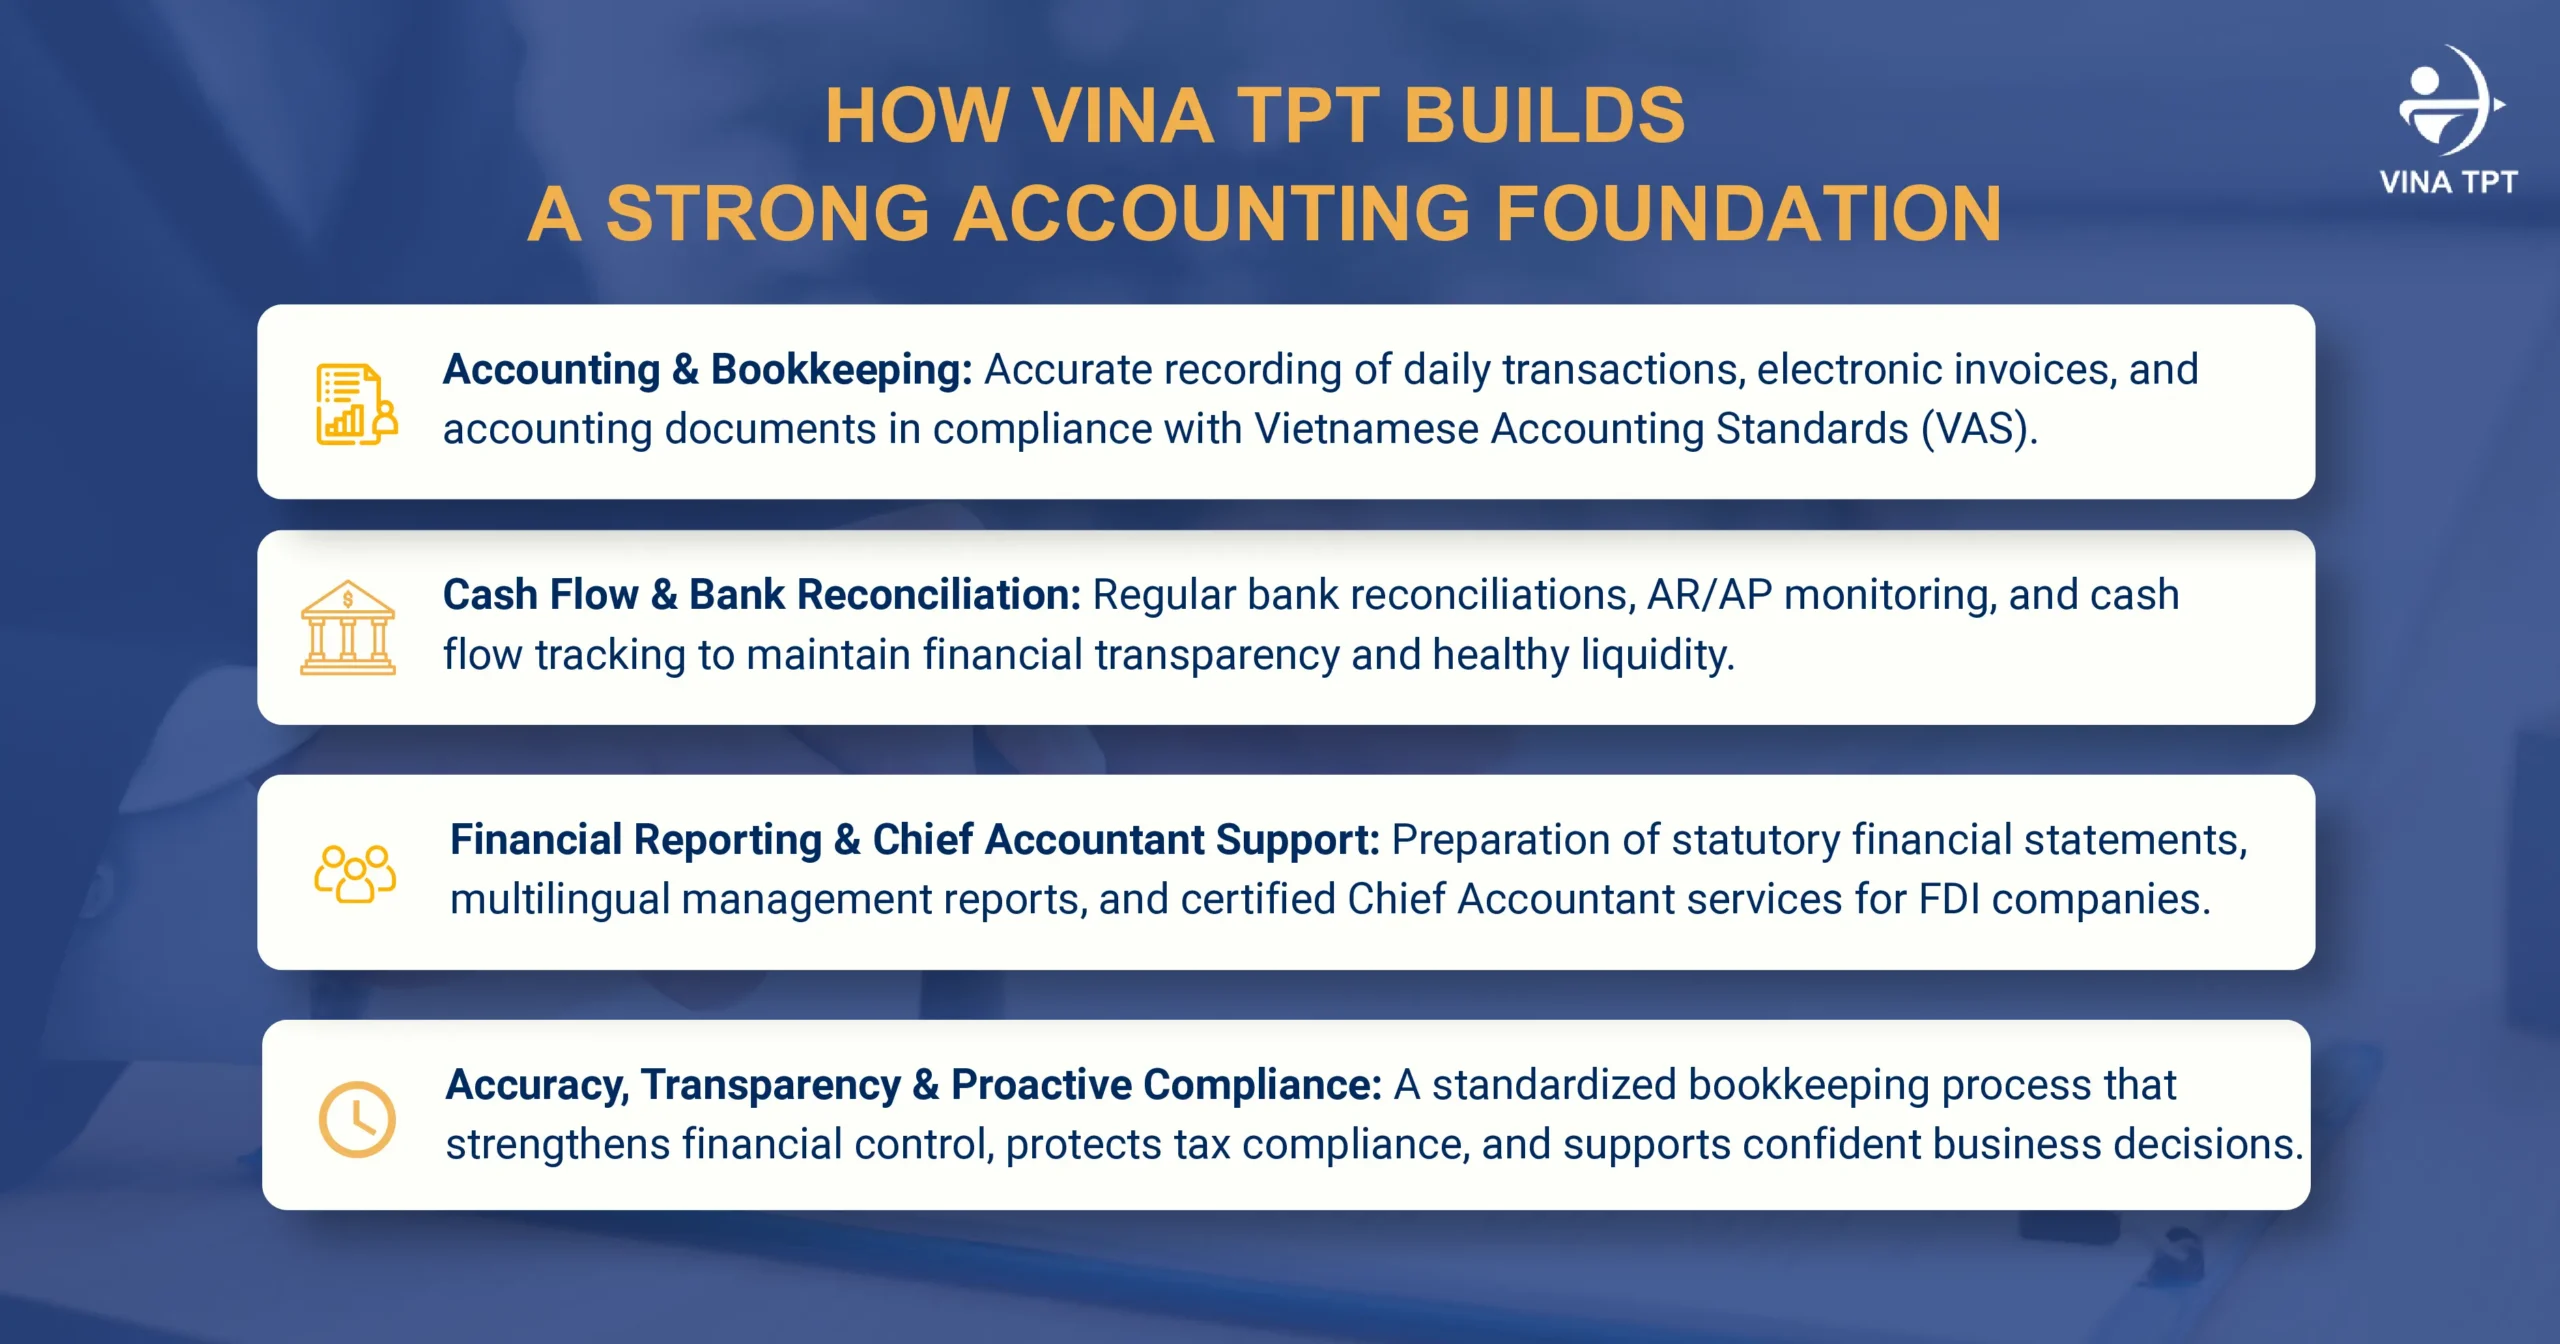
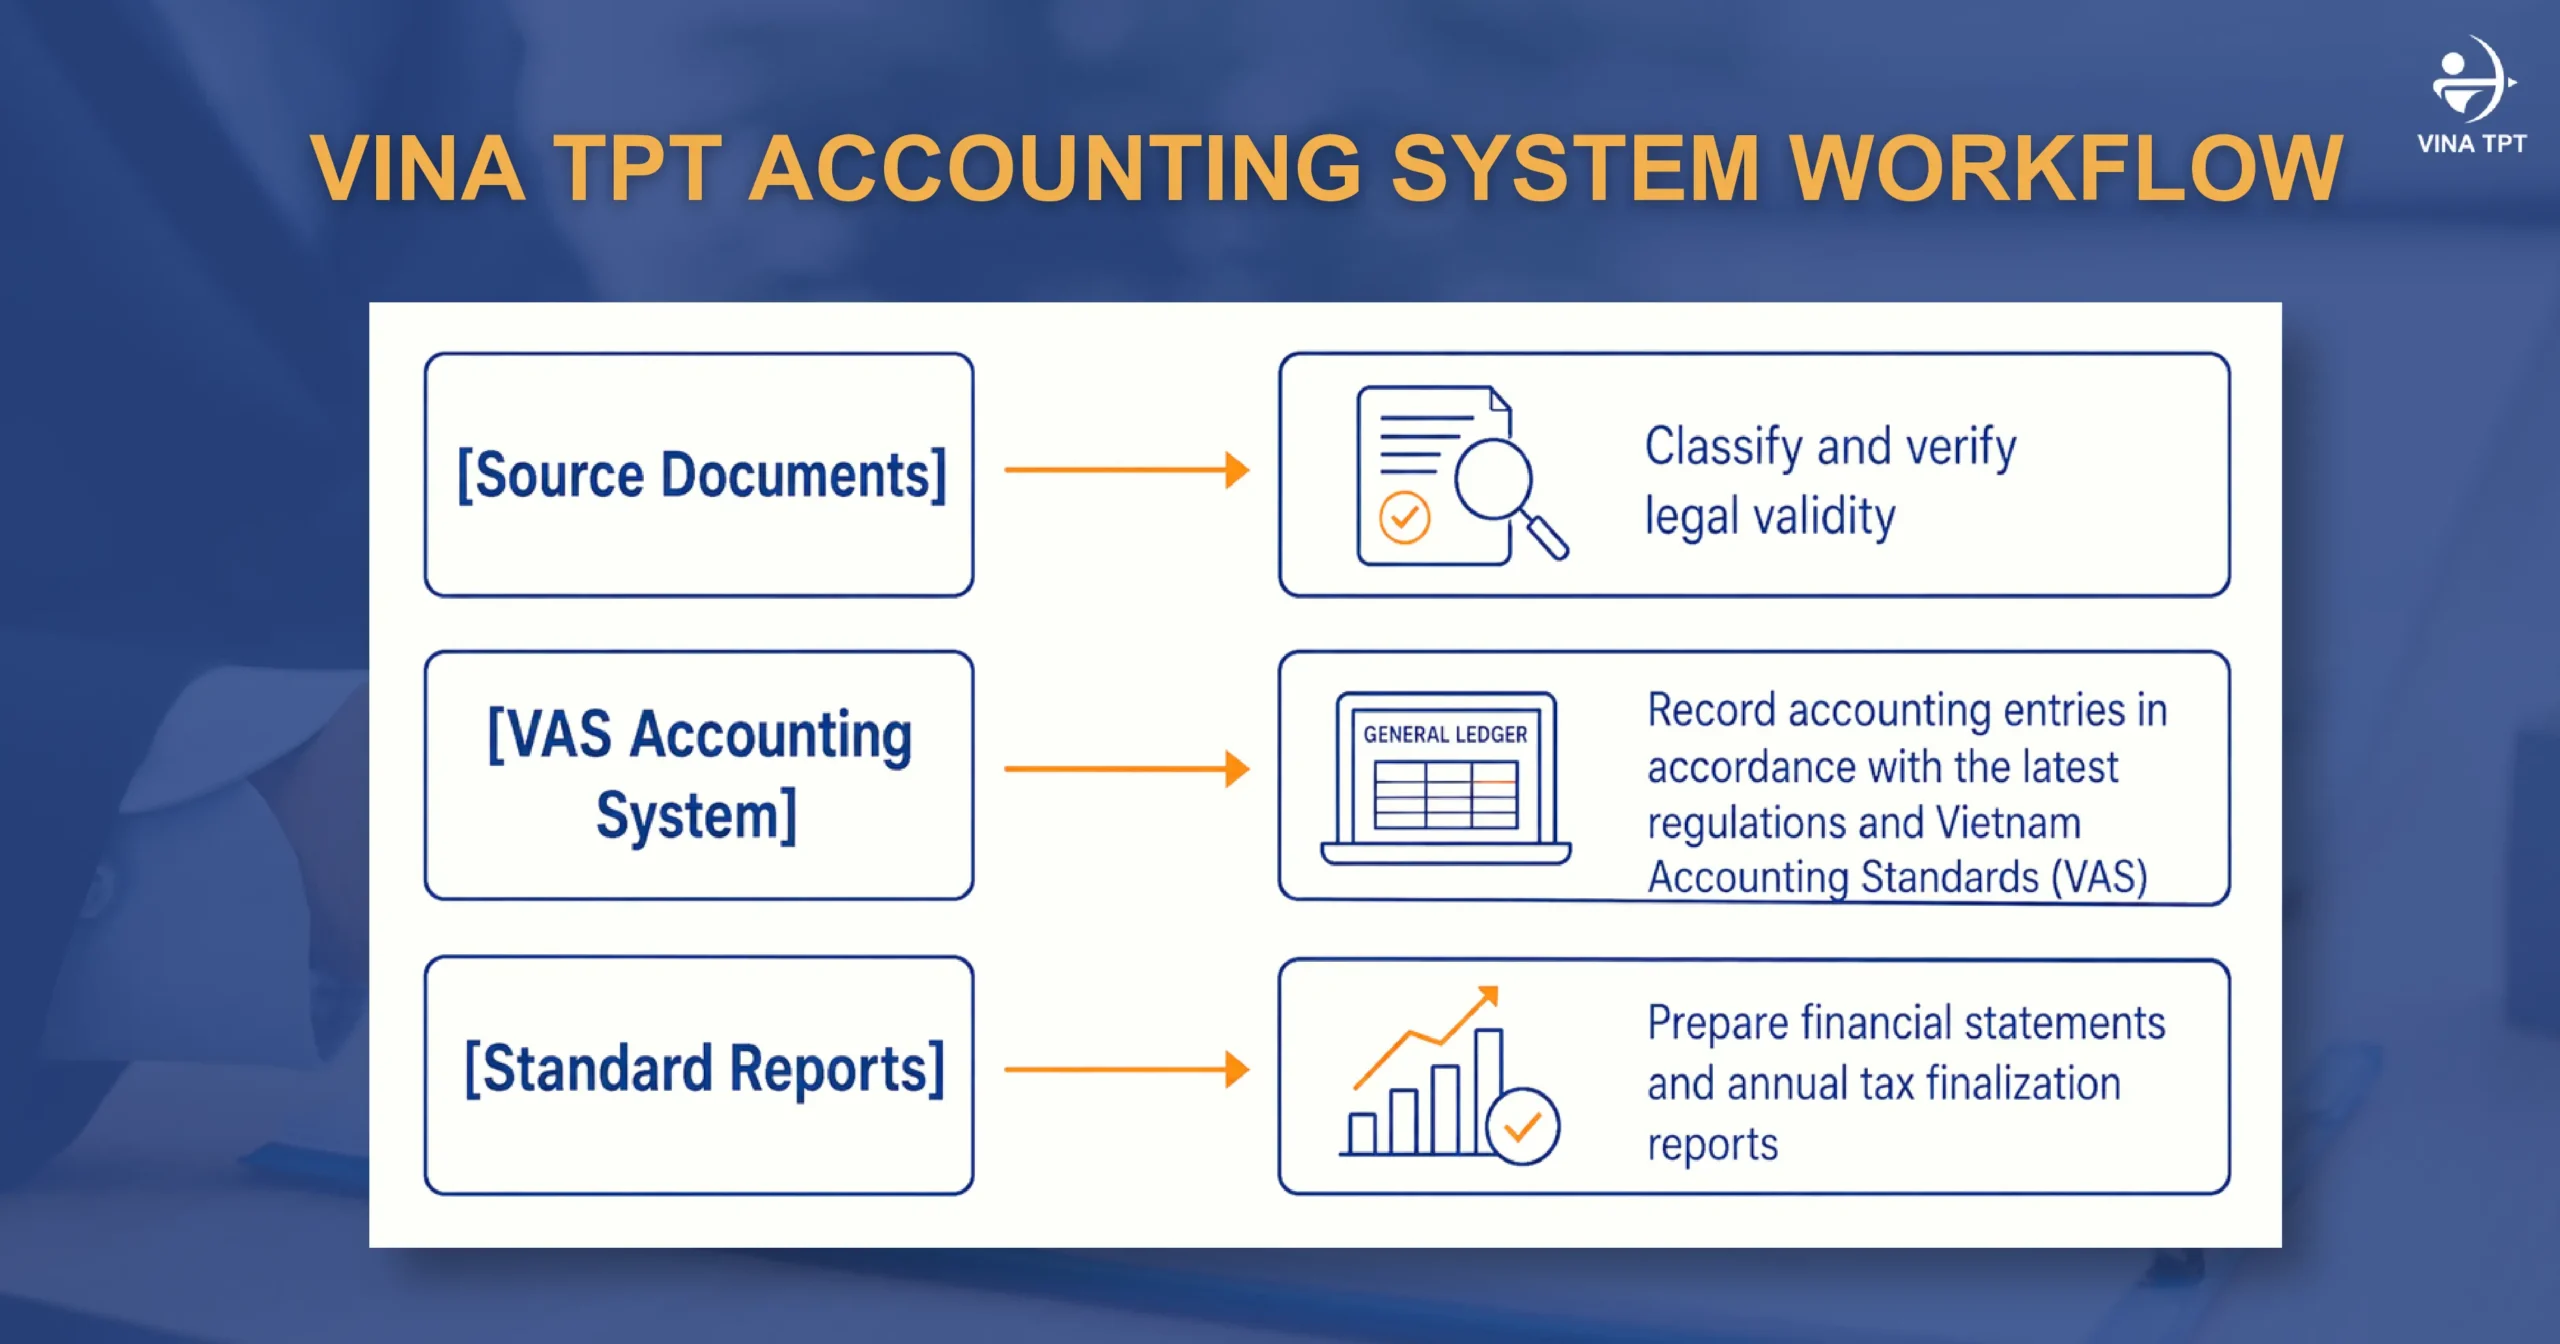
A compliant accounting ledger system is the “backbone” that truthfully reflects the financial health of the business. Through our professional bookkeeping services, Vina TPT standardizes the entire accounting workflow from raw documents to high-level management reports.

1.1. Daily Transaction Recording & Electronic Invoice Standardization

Our dedicated accounting team classifies and verifies the legality and validity of all input and output documents in accordance with Vietnamese Accounting Standards (VAS). All electronic invoices are checked for tax authority authentication codes under Decree 123/2020/ND-CP, eliminating the risk of posting invoices from high-risk tax entities.

1.2. Cash Flow Control & Automated Bank Reconciliation

Vina TPT performs regular bank statement reconciliations, closely monitors Accounts Receivable (AR) and Accounts Payable (AP). This rigorous cash flow control process helps foreign investors accurately understand the company’s liquidity and prevents sudden cash shortages.

1.3. Financial Statement & Multilingual Management Reporting

Beyond preparing the Balance Sheet, Profit & Loss Statement (P&L), and Cash Flow Statement according to VAS for submission to the authorities, Vina TPT also converts data into management reports in English, Japanese, and Chinese. This enables the Board of Directors and overseas Headquarters to easily evaluate business performance according to global management standards.

1.4. Chief Accountant Appointment

For newly established FDI companies that cannot immediately appoint a senior staff member, Vina TPT provides personnel holding the Chief Accountant Certificate issued by the Ministry of Finance to take legal responsibility, sign and approve accounting documents, and directly liaise with state authorities.

Operating Philosophy: Establishing these four closed-loop tasks is not merely about handling administrative paperwork. It reflects Vina TPT’s working spirit of “Accuracy – Transparency – Proactivity”. We understand that every number in the accounting books is tied to the investor’s legal safety and cash flow. By standardizing data from the smallest input transaction to multilingual management reports sent to the parent company, Vina TPT transforms the accounting system from a “compliance obligation” into a reliable management resource, helping FDI leadership stay fully in control during audits and confidently make strategic business decisions.

Tax and Accounting Services in Vietnam Comprehensive FDI Solutions

2. Tax Declaration Services – Optimizing Obligations & Managing Risks

In the structure of tax and accounting services, tax declaration and advisory play a decisive role in the legal safety of the investment project. As an experienced tax consultant, Vina TPT helps businesses comply with Vietnamese tax regulations while minimizing unnecessary risks. 

2.1. Accurate Periodic Tax Declaration & Filing

Vina TPT prepares and submits all periodic tax declarations (monthly or quarterly), including: Value-Added Tax (VAT), provisional Corporate Income Tax (CIT) according to the 80% rule before Q4, and Foreign Contractor Tax (FCT) arising from payments to international partners.

2.2. Year-End Tax Finalization & Refund Support

At the end of the fiscal year, we prepare CIT and PIT finalization dossiers for the entire workforce. In particular, Vina TPT supports businesses in building VAT refund dossiers for new investment projects or export activities, helping to release working capital for the company.

2.3. Tax Structure Advisory & Representation Before Tax Authorities

A proactive tax consultant also helps businesses prepare for tax audits and changes in tax regulations, Vina TPT helps businesses maximize legal tax incentive packages (CIT exemption/reduction in priority locations or sectors under the Law on Investment 2020). During tax inspections, our experts directly represent the company in explaining documents and protecting legitimate deductible expenses before the inspection team.

The close integration of periodic declarations, year-end finalization, and representation during inspections not only helps the company fulfill its obligations to the State Budget but also demonstrates Vina TPT’s role as a “proactive tax shield”. In Vietnam’s strict legal environment, tax advisory is not about finding ways to “circumvent the law”, but about legally optimizing cost structures and preparing for every possible inspection scenario. By establishing a tight document system from the beginning, Vina TPT helps foreign investors eliminate unnecessary penalty risks, protect invested capital, and always stay in control amid policy changes.

Book a Free Tax Filing Consultation

3. HR & Payroll Services – Seamless Integration with Accounting & Tax

In the operational model of FDI companies, HR management and payroll processing are not independent but directly linked to Personal Income Tax (PIT) and Social Insurance (BHXH) obligations. The lack of synchronization between employment contracts, salary policies, and Corporate Income Tax (CIT) reports often creates “loopholes” that tax authorities easily use to disallow labor expense deductions during finalization. Vina TPT’s in-depth Payroll services are designed to comprehensively resolve the complex connection between Labor Law, Social Insurance Law, and local Tax Law:

3.1. Accurate Salary Calculation, Information Security & Salary Scale Development

  • Salary Policy & Scale Development: Advise and design reasonable income structures (base salary, tax-exempt allowances, performance bonuses) that comply with Labor Law while optimizing Social Insurance and PIT costs for the company.
  • Accurate Payroll Processing & Absolute Confidentiality: Perform detailed calculations of salary, overtime pay, tax/insurance deductions, and issue bilingual payslips. Protect the salary information of executives and senior staff through a strict role-based access control storage system.

3.2. Social Insurance Obligation Management & PIT Withholding

  • Labor Records & Social Insurance Synchronization: Represent the company in handling all employee addition/termination procedures, closing Social Insurance books, and processing maternity, sickness, and other benefits with the Social Insurance Agency on time, avoiding late-payment penalties.
  • PIT Declaration & Withholding: Build a dependent deduction management file and perform PIT withholding according to progressive tax brackets for resident individuals or flat rates for non-resident individuals, ensuring 100% consistency with the annual financial statements.

3.3. Legal Procedure Standardization & Tax Risk Optimization for Foreign Personnel (Expats)

  • End-to-End Labor Legal Support: Provide comprehensive advisory and support for Work Permit applications, explanation of the need for foreign labor, Temporary Residence Card (TRC), and work visas, allowing foreign specialists to work legally with peace of mind.
  • Tax Residency Determination & Double Taxation Avoidance: Carefully analyze the actual number of days present in Vietnam to correctly determine tax obligations (Resident or Non-Resident Individual). At the same time, advise on applying Double Tax Avoidance Agreements (DTA) for foreign-sourced income of Expats, eliminating the risk of tax authorities pursuing additional assessments and late-payment penalties.

Operating Philosophy: By fully integrating Payroll and HR Compliance services into the Accounting & Tax system, Vina TPT creates a closed-loop HR-financial management cycle. We not only help businesses legally optimize labor costs but also protect the legitimacy of all personnel expenses before tax inspections, while creating an absolutely legally safe operating environment for your international team.

Tax and Accounting Services in Vietnam Comprehensive FDI Solutions

4. Benefits of Using Vina TPT’s Tax and Accounting Services

Switching to Vina TPT’s comprehensive tax and accounting services model brings FDI companies direct economic and operational benefits:

Comparison Criteria

In-House Accounting Team

Vina TPT All-in-One Solution

Operating Costs Expensive (salaries, social insurance, office space, software) Saves up to 20% of annual costs
Legal Capability Depends on 1–2 staff members’ competence 3-level review by CPA and Chief Accountant team
Operational Continuity Risk of disruption when staff leave 24/7/365 continuous operation commitment
Error Risk Company bears 100% of tax penalties Vina TPT commits to compensating for losses caused by advisory errors

The combination of deep expertise and secure cloud data storage technology allows foreign investors to maintain full remote financial control, eliminating language barriers through a consulting team fluent in English, Japanese, and Chinese.

5. Why Hundreds of FDI Companies Choose Vina TPT as Their Strategic Partner

Vina TPT has established itself as a trusted strategic partner for FDI enterprises in Vietnam by offering far more than traditional outsourcing – we deliver an end-to-end financial shield tailored to international business standards. Built on over 20 years of hands-on experience, our team possesses a profound understanding of the corporate governance mindsets, risk appetites, and distinct business cultures of investors from South Korea, Japan, Singapore, Europe, and the United States. To eliminate operational risk at its source, 100% of client files undergo a rigorous three-tier review process directly overseen by certified CPAs and Chief Accountants accredited by the Ministry of Finance, guaranteeing absolute compliance with both Vietnamese Accounting Standards (VAS) and local tax regulations.

To support seamless management for global headquarters, Vina TPT leverages an all-in-one integrated service model supported by modern, secure cloud infrastructure. By seamlessly synchronizing accounting, tax compliance, payroll, and legal advisory within a single framework, we eliminate data discrepancies and provide real-time, bilingual financial reporting. This high-level integration enables foreign directors and overseas parent companies to maintain transparent, effortless oversight of their local operations, transforming accounting from a administrative obligation into a reliable management asset.

The accounting system and tax policies in Vietnam carry inherent complexities that can directly impact the cash flow and sustainability of investment projects. Proactively partnering with a credentialed tax and accounting advisor is the most strategic move to optimize operating costs, mitigate compliance risks, and protect your investment capital for long-term growth.

BOOK A FREE CONSULTATION

Tax-and-Accounting-Services-in-Vietnam

Bookkeeping Services in Ho Chi Minh City, Vietnam | 20+ Years Experience with Vina TPT

Bookkeeping services in Vietnam for FDI companie


Bookkeeping services in Vietnam for FDI companie

Ho Chi Minh City is Vietnam’s largest economic center, home to thousands of FDI enterprises, startups, and trading companies. However, many businesses face challenges with bookkeeping and increasingly strict legal compliance. Even a small error in the books can lead to administrative fines, delayed tax refunds, or loss of investor confidence.

Professional bookkeeping services in Vietnam are not just about recording numbers, they are a vital tool that helps businesses control cash flow, comply with VAS standards, and maintain transparent financial reporting. This article explains bookkeeping services in Vietnam, selection criteria, and why Vina TPT is trusted by hundreds of FDI businesses.

1. What Do Bookkeeping Services in Vietnam Include?

A professional bookkeeping services in Vietnam package at international standards is far more than simply entering invoice data or mechanically recording receipts and payments. It is a comprehensive process of controlling, classifying, and systematizing all economic transactions of the business in accordance with current financial standards.

In Vietnam’s dynamic market, the bookkeeping services Ho Chi Minh City provided by Vina TPT serve as the backbone of the accounting information system. They transform raw data from daily business activities into legally valid financial reports, helping management make accurate business decisions.

Our in-depth bookkeeping management process is implemented comprehensively through the following core components:

  • Daily Transaction Recording According to VAS: Accurate classification and posting of all arising transactions (revenue, expenses, receivables/payables, fixed assets), ensuring the entire accounting ledger is updated in real time and strictly complies with the latest regulations of the Vietnamese Ministry of Finance.
  • Electronic Invoice and Accounting Document Management: Receiving, reviewing the legality and validity of all input and output VAT invoices. Promptly detecting and handling risky invoices from companies that have fled their registered addresses to protect the company’s legitimate deductible expenses.
  • Cash Flow Monitoring and Bank Reconciliation: Tight control of cash flow movements, performing monthly reconciliations between accounting books and actual bank statements from operating accounts and Direct Investment Capital Accounts (DICA) to minimize the risk of losses.
  • Financial Statement and Management Reporting: On a monthly or quarterly basis, our expert team prepares the balance sheet, profit & loss statement (P&L), cash flow statement, and in-depth management reports tailored to the requirements of overseas headquarters.
  • Support for Audit Preparation and Coordination with Independent Auditors: Organizing and scientifically archiving the document system. Representing the company in direct coordination with independent audit firms to complete the annual audit report on schedule.

Bookkeeping services in Vietnam for FDI companie

2. Key Criteria for Choosing Bookkeeping Services in Vietnam

The accounting service market in Vietnam is very diverse; however, finding a partner that truly understands the mindset of foreign investors is not easy. When selecting bookkeeping services Ho Chi Minh City, you need to thoroughly evaluate based on the following 4 core criteria:

2.1. Practical Experience in Professional Bookkeeping Vietnam of the Expert Team

The service provider must have a team of staff holding official accounting/tax agent certificates issued by the Ministry of Finance and extensive hands-on experience in handling special accounting situations for FDI companies. This capability is proven through years of operation in the market and the number of successful tax inspection cases they have represented clients in before the authorities.

2.2. Technology for Professional Bookkeeping Vietnam

For foreign investors who are not regularly present in Vietnam, the ability to interact remotely is critical. A reputable professional bookkeeping Vietnam provider must use modern cloud-based accounting software with high-standard data security systems, allowing you to access financial reports, track work progress, and approve documents anytime, anywhere safely.

2.3. Cost Transparency and Responsibility Commitment (SLA)

A professional service contract must clearly define the all-inclusive fee structure with absolutely no hidden costs during operation. At the same time, the Service Level Agreement (SLA) regarding report submission deadlines and specific material compensation responsibility for any errors caused by the accounting firm must be transparently stated in writing.

2.4. Strategic Advisory Capability and Long-Term Compliance Support

A good accounting firm does not stop at passively recording what has already happened. They must be able to proactively analyze data, provide early warnings on cash flow risks, advise on legal tax cost optimization solutions, and accompany the business throughout the 5-year tax finalization process.

3. Why Businesses Choose Vina TPT for Bookkeeping Services in Vietnam

With a journey of over 20 years specializing in supporting foreign investment capital flows into Vietnam, Vina TPT has established itself as one of the leading providers of bookkeeping services in Vietnam, particularly in the key market of Ho Chi Minh City.

We understand that behind every accounting figure lies the dedication and strategic capital of the investor. The core strength of Vina TPT lies in our team of experts, including Certified Public Accountants (CPA) and experienced tax agents. They not only possess deep professional expertise but also excellent command of specialized English, Japanese, and Chinese. This completely eliminates communication barriers and ensures all management reports are translated and explained clearly and accurately according to international management thinking.

Our expert team always works with dedication and proactively offers cost structure optimization solutions, helping you save time, minimize legal risks, and focus entirely on your core business growth objectives in Vietnam.

Are you looking for reliable bookkeeping services in Vietnam to standardize your accounting system and support long-term compliance?

BOOK A FREE CONSULTATION

How to Calculate Tax on Share Transfers for Individuals – 2026

The method of calculating the share transfer tax for individuals is one of the core legal concepts that any shareholder must firmly grasp before executing a transaction to transfer ownership rights in a joint-stock company. Correctly understanding and accurately applying the calculation procedure not only helps individuals proactively control their financial obligations but also maximizes the prevention of severe legal risks. In practice, numerous cases of misunderstanding the nature of cash flows or delayed declaration have resulted in heavy administrative penalties and arrears of late payment interest by the Tax Authority. Therefore, strict compliance with prevailing regulations is the safest solution to protect the legitimate rights and interests of both the transferor and the transferee.

When are individuals required to pay the share transfer tax?

An individual becomes liable for tax the moment a share transfer is officially finalized, reflecting a change in company ownership. To ensure transparent tax management, current regulations clearly outline the specific scope of application for different types of enterprises:

  • Time of Tax Liability: The share transfer tax is calculated based on the actual time of transferring share ownership as stipulated in the transfer contract, regardless of whether the transferor has received full payment or no payment at all from the counterpart.
  • Distinguishing between a Joint Stock Company (JSC) and a Limited Liability Company (LLC): Under the provisions of the Personal Income Tax (PIT) Law, capital transfer activities in a joint stock company (including both public and non-public companies) are uniformly classified and managed under the category of “securities transfers”. This is completely different from the “transfer of capital contributions” in a limited liability company, where tax liability only arises when the transaction generates a profit (the transfer price is higher than the cost price).

The essence of the regulation applying a fixed tax rate of 0.1% on the share transfer price is a strict control mechanism by the State. This mechanism is established to completely restrict situations where parties intentionally declare fictitious losses, undervalue transactions, or collude to falsify sales documents for tax evasion purposes, thereby causing revenue loss for the national budget.

The Most Updated Calculation Method for Tax on Share Transfers

Point b, Clause 4, Article 2 of Circular 111/2013/TT-BTC (amended by Article 4 of Circular 25/2018/TT-BTC) stipulates the incomes subject to Personal Income Tax (PIT) as follows:

“4. Income from capital transfers

Income from capital transfers is the personal income received, which includes:

…

b. Income from securities transfers, including: income from the transfer of shares, share purchase rights, bonds, treasury bills, fund certificates, and other types of securities as prescribed in Clause 1, Article 6 of the Law on Securities. Income from the transfer of shares by individuals in joint-stock companies in accordance with Clause 2, Article 6 of the Law on Securities and Article 120 of the Law on Enterprises.”

Furthermore, pursuant to Point b, Clause 2, Article 11 of Circular No. 111/2013/TT-BTC, which was amended and supplemented by Article 16 of Circular No. 92/2015/TT-BTC, personal income derived from securities transfers is subject to personal income tax at a flat rate of 0.1% based on the transfer value per transaction.

In accordance with this provision, the personal income tax liability for share transfers is calculated on the gross transfer value per transaction, irrespective of any capital gain or loss resulting from the variance between the sale and purchase prices.

f that transaction.

For example:

Assume Mr. A owns 10,000 shares of Joint Stock Company X (par value of VND 10,000 per share, equivalent to a cost basis of VND 100,000,000). Due to cash flow requirements, Mr. A decides to transfer his entire shareholding to Ms. B.

  • Scenario 1 (Transfer at a profit): Mr. A sells at a price of VND 15,000 per share. The total transfer price is VND 150,000,000.

==> Personal Income Tax payable = 150,000,000 x 0.1% = 150,000 VND

  • Due to difficult market conditions, Mr. A accepts a loss-cutting sale at a price of 8,000 VND/share. The total transfer price is 80,000,000 VND. Despite incurring a loss of 20,000,000 VND compared to the initial cost basis, Mr. A is still required to fulfill his tax obligation:–

==> Personal Income Tax payable = 80,000,000 x 0.1% = 80,000 VND

tax-rate-share-transfer

Deadline for filing tax returns for share transfers.

Accurately determining the filing deadline is crucial to the legality of the transaction and helps individuals avoid unnecessary late payment penalties from the tax authorities. According to current tax administration regulations, the timeline for filing and paying personal income tax on share transfer activities is specifically categorized based on the transaction method as follows:

  • Case of self-declaration by individuals: The deadline for filing tax returns is no later than the 10th (tenth) day from the effective date of the share transfer contract.
  • Case of tax declaration and payment on behalf by the enterprise: If a joint-stock company performs procedures to update its shareholder list without documents proving that the transferring individual has fulfilled their tax obligations, the enterprise is responsible for declaring and paying tax on behalf of that individual. The filing deadline is no later than the time of performing procedures to change shareholder information in the Shareholder Register or the management system of the Business Registration authority.

Deadline for tax payment: The last day of the tax filing deadline is also the deadline for completing the payment of tax into the State Budget.

>>>> Related articles:

[How to Calculate Personal Income Tax 2026 in Vietnam]

[Personal Income Tax 2026: Key Changes Directly Affecting Employees]

Vina TPT’s Share Transfer Tax Consulting and Declaration Services

With extensive experience supporting various enterprises in capital transfer transactions, Vina TPT provides comprehensive tax consulting and declaration services. We assist clients from determining tax obligations to completing filing procedures in accordance with current regulations. Our team of experts ensures that the transfer process is executed smoothly, saving time while ensuring full compliance with prevailing legal requirements.

  • Ensuring legal compliance: Reviewing the legality of contracts and supporting documents, and committing to legally optimizing the tax payable.
  • Time and cost efficiency: On behalf of our clients, we complete the entire system of tax declarations, file documents directly, and liaise with the competent tax authorities, thereby minimizing the need for travel.
  • Mitigating administrative penalties: Closely monitoring transaction timelines to ensure timely filing, thereby maximizing the protection of investors’ capital.

Connect with our experts today via the button below for a complimentary tax document review and consultation.

BOOK A FREE CONSULTATION

Conclusion

In summary, when executing a share transfer, individuals must remember the 0.1% tax rate applied to the transfer value (regardless of whether the transaction is profitable or results in a loss). The second key point is the tax filing deadline: tax returns must be submitted to the Tax Authority within 10 days from the effective date of the share transfer contract (or the date the change of ownership is completed in the shareholder register) to avoid late filing penalties. Proactively mastering these milestones and calculation rules is the key to ensuring that both individuals and enterprises operate safely, transparently, and sustainably.

Why-Startups-Need-the-Best-Accounting-Firms-in-Vietnam_-VTPT

2026 Tax Update: Corporate Tax Exemption for Businesses with Revenue Under 1 Billion VND

CI tax Exemption for Businesses with Revenue Under 1 Billion VND

Corporate income tax exemption

Corporate income tax exemption opportunities for small businesses in Vietnam have received a significant boost in 2026. To foster the recovery and sustainable growth of small-scale economic units, the Government officially issued Decree No. 141/2026/NĐ-CP on April 29, 2026, introducing a highly practical financial support policy. Under this new regulation, enterprises and business households with an annual revenue of less than 1 billion VND are entitled to a full exemption from Corporate Income Tax (CIT).  

This policy serves as a vital catalyst, not only reducing operational burdens but also providing a golden opportunity for business owners to reinvest and scale their operations. In this article, we will provide a detailed analysis of this new regulation, outline the eligibility criteria, and explore other Corporate Income Tax (CIT) incentives currently available to businesses in Vietnam. 

1. What Is the Corporate Income Tax Exemption for Businesses Under 1Billion VND? 

The fiscal strategy for 2026 places a strong emphasis on supporting small-scale economic units. On April 29, 2026, the Government officially issued Decree No. 141/2026/NĐ-CP, which introduces significant tax relief measures. This policy supplements Clause 15, Article 4 of Decree No. 320/2025/NĐ-CP, establishing a legal framework for Corporate Income Tax (CIT) exemption for enterprises and organizations with an annual revenue threshold of 1 billion VND or less. 

The Core Policy Explained 

The regulation provides a clear mechanism for determining eligibility and handling operational variations. Key components of the policy include: 

  • Revenue Determination: The annual total revenue used as the basis for the exemption includes revenue from the sale of goods and provision of services (excluding deductions), financial activity income, and other income recorded in the Appendix of Production and Business Performance Results from the preceding tax period. 
  • Pro-rata Calculation: For businesses operating for less than 12 months in the preceding year, revenue is annualized by dividing actual revenue by the number of months in operation and multiplying by 12. 
  • Exemption for New Establishments: Newly established businesses in the current tax period with projected revenue not exceeding 1 billion VND are not required to make provisional CIT payments. If the actual revenue eventually exceeds the 1 billion VND threshold by the end of the tax period, the enterprise must declare and finalize the tax accordingly, without being subject to late payment penalties. 
  • The Anti-Avoidance Clause: To maintain fiscal integrity, this exemption is strictly not applicable to subsidiaries or enterprises with affiliated relationships if the related business units in the network fail to meet the qualifying conditions specified in this Decree. 

2. Who Qualifies for This Tax Exemption? 

Determining whether your business falls under the scope of Decree No. 141/2026/NĐ-CP is essential for accurate tax planning. The policy is designed to support micro and small-scale operations; however, eligibility is contingent upon meeting specific operational and structural criteria. 

The following table provides a quick reference to help you self-assess your business’s eligibility: 

Entity Category  Eligibility Status  Key Requirement 
Small Enterprises  Eligible  Annual revenue ≤ 1 billion VND 
Registered Household Businesses  Eligible  Annual revenue ≤ 1 billion VND 
Newly Established Entities  Eligible (Conditional)  Projected revenue ≤ 1 billion VND 
Subsidiary Companies  Excluded  Depends on Parent Company’s revenue status 
Affiliated Enterprises  Excluded  If the affiliated network exceeds 1 billion VND 

Small Businesses & Household Businesses 

For the purposes of this exemption, “Small Businesses” include entities registered under the Law on Enterprises that maintain a modest operational footprint. Similarly, “Household Businesses” (Hộ kinh doanh) are eligible provided their annual revenue—comprising sales, services, financial income, and other miscellaneous income—remains below the 1-billion VND threshold. To ensure full compliance, businesses must maintain transparent accounting records, as the tax authority relies on the Appendix of Production and Business Performance Results from the preceding tax period to verify your eligibility. 

Crucial Warning: The Subsidiary Exception 

A common pitfall for many businesses is failing to account for the “Affiliated Relationship” clause. Per the stipulations in Decree 141/2026/NĐ-CP, the tax exemption is not applicable to any enterprise that acts as a subsidiary or is part of a larger business network (affiliated relationship) if the other entities within that network do not meet the exemption criteria. 

In essence, if your parent company or a related entity reports a total revenue exceeding 1 billion VND, your business is disqualified from claiming this tax exemption, regardless of how low your own individual revenue may be. We strongly advise conducting a thorough audit of your corporate ownership structure before declaring yourself exempt. 

2026 Tax Update tax Exemption for Businesses with Revenue Under 1 Billion VND

3. Additional Corporate Income Tax Incentives in 2026

3.1 Corporate Income Tax Rates: Standard vs. Preferential 

While the standard corporate income tax rate remains fixed at 20%, Vietnam’s 2026 fiscal framework provides a sophisticated, tiered structure designed to lower the entry barriers for SMEs and encourage sustainable investment. For strategic tax planning, it is crucial to understand that these rates are not “one size fits all” but are instead tiered based on annual revenue, reflecting the government’s support for business scaling. 

  • 15% CIT Rate (Micro-Enterprise Support): This rate is specifically intended for enterprises with annual revenue of VND 3 billion or less. It acts as a primary fiscal cushion, allowing micro-enterprises to preserve cash flow during their early development or stabilization phase. 
  • 17% CIT Rate (Growth-Oriented Support): Aimed at mid-sized businesses with annual revenue exceeding VND 3 billion up to VND 50 billion, this rate balances tax relief with the transition toward full-scale compliance, supporting businesses as they expand their operational footprint. 

EXPLORE OUR TAX ADVISORY SERVICES

3.2 Specialized Tax Determination 

In specific cases where the determination of actual costs and expenses is challenging—such as for certain foreign-owned enterprises or cooperatives—a direct tax rate on revenue may be applied. This mechanism ensures that businesses remain compliant without being hindered by overly burdensome accounting requirements for expense documentation. 

3.3 Additional Location-Based and Sectoral Incentives 

  • Location-Based Incentives: Businesses operating in designated Economic Zones, industrial parks, or underdeveloped provinces often benefit from extended tax holidays and additional reductions. 
  • Priority Sectors: High-tech projects and priority sectors may qualify for even further reduced CIT rates (e.g., 10%) for specified periods. 
  • R&D Deductions: Businesses investing in local technology development can claim additional deductions on taxable income, further reducing the overall effective tax rate. 

>> Reference:

Tax Incentive in Vietnam 2025: Comprehensive Guide to Optimize Profits under New CIT Law

Tax Breaks in Vietnam 2025 | Key CIT, VAT & PIT Updates

4. Handling Temporarily Paid CIT in Q1 2026

If your enterprise temporarily paid CIT for the first quarter of 2026 before the policy’s full implementation was processed, you are entitled to recover these funds. Follow these steps: 

  1. Audit: Confirm the amount paid in Q1 2026 against your actual annual revenue projection. 
  1. Declaration: Adjust your quarterly CIT declaration form to reflect the exempt status. 
  1. Offset/Refund: Contact your local tax office to request a tax offset (applying the overpaid amount to other obligations like PIT or VAT) or a formal tax refund according to the Law on Tax Administration. 

5. Maximize Your Tax Benefits with Vina TPT

Navigating the complexities of Vietnamese tax law—especially for FDI businesses and SMEs with intricate ownership structures—is a task that requires professional expertise. A minor error in interpreting revenue thresholds or subsidiary relationships can lead to significant penalties. 

At Vina TPT, we provide end-to-end accounting and tax advisory services tailored to your business model. We ensure that you not only remain 100% compliant with the latest 2026 regulations but also identify every legal opportunity to optimize your tax position. 

Contact Vina TPT today to schedule a consultation and let our experts secure your financial advantage in the current market.

BOOK A FREE CONSULTATION

Can an Invoice Issued with the Wrong Date Be Adjusted? Detailed Latest Guidelines for 2026

Instructions for handling invoices issued with the wrong date

Can an invoice issued with the wrong date be adjusted?

In practice, mistakes involving invoices issued with the wrong date are a constant, quiet source of anxiety for accountants and business owners alike. A single oversight regarding the date can lead to unnecessary legal risks, particularly as regulations governing electronic invoices become increasingly stringent. Are you struggling to figure out whether an invoice with an incorrect date can be adjusted? Will your enterprise face administrative penalties or be denied input VAT deductions?

Rest assured, the answer is YES, it can certainly be adjusted. However, enterprises must strictly comply with official invoice adjustment guidelines.

Specifically, under Decree No. 123/2020/ND-CP (along with amendments and supplements in Decree No. 70/2025/ND-CP applicable from June 2025), the resolution process has shifted toward issuing either an adjustment invoice or a replacement invoice.

Important Note: Canceling an invoice to reissue it from scratch is virtually no longer accepted for incorrect date errors, except in a few special technical scenarios. Executing a written agreement between both parties remains a mandatory legal step to protect your enterprise during tax audits.

This article synthesizes detailed instructions, step-by-step procedures, updated penalty rates, tax deduction guidelines, and key compliance notes to help you handle errors correctly, avoid fines, and ensure valid documentation according to the latest 2026 regulations.

1. What Is an Invoice Issued with the Wrong Date? Common Errors & Consequences

An invoice issued with the wrong date (issued at an improper time) occurs when an invoice is generated outside the timeframes specified under Article 9 of Decree No. 123/2020/ND-CP (as amended by Decree No. 70/2025/ND-CP). The proper time to issue an invoice is generally upon delivery of goods, completion of service provision, or final sign-off and handover.

Common Error Scenarios:

  • Generating an invoice prior to the actual date of goods delivery or service handover.
  • Generating an invoice many days or months after the delivery date (backdating or delayed issuance).
  • Recording an incorrect day, month, or year on the invoice compared to actual transaction facts.
  • Mismatched VAT tax declaration periods caused by improper timing.

Severe Consequences of Improper Handling:

  • Administrative tax fines concerning invoices (ranging from formal warnings to tens of millions of VND).
  • Disallowance of input VAT deductions (for the buyer) or rejection of legitimate business expenses (for the seller).
  • Elevated exposure to tax inspection and audit risks.
  • Adverse impacts on financial statements and corporate reputation.

Understanding these errors allows you to resolve issues proactively, swiftly, and in full compliance with the law.

2. Can an Invoice Issued with the Wrong Date Be Adjusted?

An invoice issued with the wrong date can be adjusted. Starting June 1, 2025, pursuant to Clause 13, Article 1 of Decree No. 70/2025/ND-CP amending Article 19 of Decree No. 123/2020/ND-CP, any errors on electronic invoices (including incorrect dates) cannot be canceled; instead, they must be addressed via an adjustment invoice or a replacement invoice.

Case 1: The Invoice Has Not Been Delivered to the Buyer

This is the easiest scenario to resolve because the invoice has not yet impacted the buyer, nor has it completed final data submission cycles.

Resolution Steps:

  1. The seller issues a replacement invoice for the erroneous invoice (replacement is preferred since the timing is completely wrong).
  2. The replacement invoice must feature the mandatory text: “Replacing invoice Form No…., Symbol…., No…., dated [Day]/[Month]/[Year]…”
  3. A written agreement is not required if the invoice has not been sent to the buyer.
  4. Once the replacement in voice is generated, the system automatically invalidates the original invoice within the tax authority database (under updated mechanisms).

Important Notes:

  • Take action immediately upon detecting the error to avoid disrupting VAT declaration cycles.
  • If the invoice was already granted a tax authority code but not yet delivered, follow the same replacement procedure.
  • Benefit: Involves no additional procedures with the buyer, minimizing dispute risks.

Adjusting an invoice issued with the wrong date

Case 2: The Invoice Has Been Delivered to the Buyer but Not Yet Declared for Tax

This situation commonly arises when an error is caught within the same reporting period.

Resolution Steps:

  1. Both parties (seller and buyer) execute a written agreement explicitly stating the error (wrong date), the adjustment content, and the original invoice information.
  2. The seller issues an adjustment invoice (most suitable when only the date is incorrect while all other details remain accurate) or a replacement invoice.
  3. Mandatory text required on the adjustment invoice: “Adjusting invoice Form No…., Symbol…., No…., dated [Day]/[Month]/[Year]…”
  4. Declare the adjustment or replacement invoice in the same reporting period as the original invoice to avoid supplementary returns.
  5. Send the written agreement along with the new invoice to the buyer and transmit data to the tax authority.

This method preserves document continuity, allowing the buyer to claim input VAT deductions normally without affecting tax reports.

Note: Executing a written agreement is mandatory when the buyer is a business enterprise, an organization, or a business household starting from June 1, 2025.

Case 3: The Invoice Has Been Delivered to the Buyer and Already Declared for Tax

This is the most complex scenario because it affects the tax declaration obligations of both parties.

Resolution Steps:

  1. Execute a written agreement between both parties detailing the mistake and corrective adjustments.
  2. Issue an adjustment invoice (preferred) or a replacement invoice featuring clear notation as outlined above.
  3. File supplementary VAT returns for the period in which the original invoice arose (if the incorrect date caused the invoice to fall into a different tax period) pursuant to supplementary declaration rules.
  4. Both the seller and the buyer must adjust their respective VAT returns.
Risks of Inaction: The seller faces administrative fines for improper invoice timing. The buyer risks having input VAT deductions disallowed if tax inspectors determine the documentation is invalid.

3. Step-by-Step Procedure for Handling Invoices Issued with the Wrong Date (E-Invoices)

Step 1: Agreement with the Buyer (Written Agreement / Minutes)

Prior to issuing a new invoice, the seller and buyer must draft a written agreement acknowledging the error (incorrect content and correction details). The document must state:

  • Original invoice information (Form number, Symbol, Invoice number, Date of issuance).
  • Nature of the error (incorrect date).
  • Adjustment content.
  • Digital signatures of both parties (if enterprises).

Step 2: Issue an adjustment invoice or replacement invoice

  • Adjustment invoice (most suitable when only the date is incorrect and values remain unchanged): Must state the mandatory text: “Adjustment for invoice form number… symbol… number… dated… month… year…”.
  • Replacement invoice: Used when errors are numerous or the entire invoice needs replacement. Must state: “Replacement for invoice form number… symbol… number… dated… month… year…”.

Step 3: Send the invoice & file supplementary tax declaration

  • Digitally sign and deliver to the buyer.
  • File a supplementary VAT tax declaration (if in a different period).

Procedure for handling invoices issued with the wrong date

4. Are incorrectly timed invoices penalized? Latest penalty rates

According to Article 24 of Decree 125/2020/ND-CP (as amended by Decree 310/2025/ND-CP effective January 16, 2026):

  • Warning penalty (if minor, with mitigating circumstances).
  • Monetary fine from VND 500,000 to VND 70 million depending on the number of invoices and the degree of impact on tax obligations (penalties increase progressively based on the number of violations).

Note: Penalties for organizations are double those for individuals. Mitigating circumstances apply if voluntarily remedied.

See also: Full-service accounting services

5. Can an incorrectly dated invoice be eligible for VAT deduction and expense accounting?

This is the primary concern for buyers: “Is this expense considered valid and eligible for VAT deduction?” In principle, an incorrectly timed invoice (an invoice issued after the transaction period) can still be accepted, provided it satisfies the following “three-legged stool”:

Authenticity of the transaction: This is a prerequisite. You must prove that goods/services were delivered and utilized for business operations prior to the invoice date.

Complete supporting dossier: Besides the incorrectly dated invoice, the documentation set must display temporal logic among records:

  • Economic contract (clearly specifying payment and handover terms).
  • Delivery note (seller) and Goods receipt note (buyer).
  • Handover record / Service acceptance record (matching the actual timing).
  • Non-cash payment vouchers via bank transfer (for invoices of VND 5 million or higher).
  • Seller compliance status: The seller must fully declare output tax and pay taxes for that invoice. If the seller absconds or fails to declare, the buyer faces a very high risk of VAT deduction disallowance.

Tax authorities generally evaluate substance over form. If the date error is merely an administrative oversight and the supporting documentation is complete, the buyer’s tax benefits will usually be protected.

6. Comparison between adjustment invoices and replacement invoices

Criteria Adjustment Invoice Replacement Invoice
When to use Partial error (only date, tax rate, or amount is wrong) Entirely incorrect or multiple errors
Mandatory text “Adjustment for invoice…” “Replacement for invoice…”
Impact on tax declaration Increase/decrease adjustment. Declared in the period the adjustment arises. Replacement declaration filed in the original period or discovery period (depending on the situation).
Advantages Preserves invoice numbering sequence, simpler Thoroughly resolves errors
Disadvantages Complex if there are multiple errors May affect invoice sequence numbering

An adjustment invoice can be issued multiple times for the same original invoice, whereas a replacement invoice can only be issued once for an erroneous invoice.

Conclusion

Therefore, the question “Can e-invoices issued with incorrect dates be adjusted?” has been answered along with step-by-step instructions following Decree 70/2025/ND-CP. Timely resolution not only helps avoid penalties but also protects tax deduction rights for both parties.

Advice: Establish a strict invoice issuance process and utilize reputable e-invoicing software equipped with effective error-correction features. When encountering complex situations, contact your managing tax office or tax experts at Vina TPT immediately for precise support.

Schedule a consultation with an expert

Tax and accounting services for FDI enterprises

What Foreign Investors Often Get Wrong About Tax Filing in Vietnam – Expert Advice

what-foreign-investors-often-get-wrong-about-tax-filing-in-vietnam-expert-advice

what-foreign-investors-often-get-wrong-about-tax-filing-in-vietnam-expert-advice

Many newly established FDI companies in Vietnam have had to pay fines of tens of millions of VND, or even had their tax codes suspended, simply because they misunderstood or overlooked their tax filing obligations.

In reality, from the moment a company receives its Enterprise Registration Certificate (ERC), its tax filing obligations officially come into effect. This means that even if the business has not yet generated revenue or begun full operations, tax filing in Vietnam is still a mandatory requirement.

However, many foreign investors still hold the misconception that “if there is no revenue, there is no need to file.” This common misunderstanding leads to unnecessary legal risks.

This article will help you clearly understand the most frequent mistakes in tax filing for FDI companies, while providing practical guidance to ensure proper compliance according to each filing period.

1. Common Tax Filing Mistakes That Lead to Penalties or Tax Code Suspension

Foreign investors often encounter unexpected issues when handling tax filing in Vietnam. Even experienced companies can make costly mistakes due to the complexity of local regulations. Below are the most common tax filing errors that FDI businesses frequently commit:

  • Failing to file tax returns when there is no revenue Many investors assume that “no revenue means no need to file.” In reality, according to the Law on Tax Administration 2019, once the Enterprise Registration Certificate (ERC) is issued, companies must still submit VAT returns, Personal Income Tax (PIT) declarations, and other required reports on time. Failure to do so can result in administrative fines and even suspension of the tax code.
  • Late filing or missing tax declarations Submitting a return even one day late can trigger penalties of 0.03% per day on the late-paid tax amount (as stipulated in Article 59 of the Law on Tax Administration 2019). Many FDI companies commonly forget to file monthly or quarterly VAT returns or provisional Corporate Income Tax (CIT) declarations.
  • Overlooking or incorrectly handling Foreign Contractor Tax (FCT / Withholding Tax) FCT is a withholding tax applied to payments made to foreign contractors or foreign experts (governed by Decree 81/2020/ND-CP and the Law on Corporate Income Tax). This is one of the most frequent mistakes and can lead to heavy penalties and complications when applying for future VAT refunds.
  • Failing to declare and pay License Tax (Thuế môn bài) Even with some relaxations in 2026, businesses are still required to declare and pay License Tax in accordance with Decree 139/2016/ND-CP (as amended and supplemented).
  • Neglecting to reconcile Input VAT invoices Input VAT refers to the value-added tax a business has paid to its suppliers. If invoices are not properly reconciled and supported as required under Clause 2, Article 14 of the Law on Value-Added Tax 2024, the company cannot claim input tax credits or refunds. This often results in significant “locked-up” capital.

Real-world consequences of these mistakes typically include substantial fines, prolonged tax audits, delays in visa and Temporary Residence Card (TRC) processing, and even loss of trust from partners and investors. In most cases, engaging a professional accounting service from the beginning is far more cost-effective than dealing with penalties and corrective procedures later.

what-foreign-investors-often-get-wrong-about-tax-filing-in-vietnam-expert-advice

2. Why Tax Filing Becomes a Major Challenge for New FDI Companies

Tax filing quickly becomes one of the biggest headaches for newly established FDI companies in Vietnam. Although the process has been digitized through the eTax system, significant differences in legal frameworks, administrative language, and compliance requirements still create substantial challenges for foreign investors from the very first months of operation.

The main reasons why tax filing feels so complex for new FDI companies include:

  • Lack of a local accounting team familiar with Vietnamese tax laws Most foreign investors do not have in-house staff who fully understand Vietnam’s tax system, including VAS, Circular 99/2025/TT-BTC, VAT, Corporate Income Tax (CIT), Personal Income Tax (PIT), Foreign Contractor Tax (FCT), and specialized reports such as the Investment Activity Report (IAR). Recruiting experienced local accountants with strong FDI knowledge is both difficult and expensive.
  • Unfamiliar with the electronic tax filing system (eTax) and administrative Vietnamese, all tax declarations must be submitted through the eTax platform entirely in Vietnamese, using complex legal terminology. Foreign investors often struggle to understand and accurately complete the required forms.
  • The common misconception that “no revenue means no filing is needed” This is one of the most frequent misunderstandings. In reality, once the Enterprise Registration Certificate (ERC) is issued, companies are still required to submit VAT returns, PIT declarations, and other periodic reports on time – even if they have not yet generated any revenue.
  • Lack of awareness of different filing deadlines Each type of tax has its own specific monthly, quarterly, or annual deadlines. Many new FDI companies miss submissions or file late simply because they lack a clear reminder system.
  • Difficulties in communicating and providing explanations to tax authorities When additional documents or clarifications are requested, communicating in Vietnamese and preparing materials according to the exact requirements of the tax office can be extremely time-consuming and frustrating.

These challenges often result in significant administrative fines, operational disruptions, delays in visa and Temporary Residence Card (TRC) processing, and even damage to the company’s credibility with partners and potential investors during the most critical early stage.

3. Best Practices to Ensure Accurate and Timely Tax Filing

In addition to remembering important deadlines, foreign investors should take the following concrete actions to ensure proper tax filing compliance:

Important Deadlines to Remember in 2026:

No.

Filing Period Type of Tax / Declaration

Note

1

Monthly VAT (if filing monthly) By the 20th of the following month

2

Quarterly VAT, provisional CIT, PIT, FCT By the 30th of the first month of the next quarter

This VAT requirement applies to businesses that declare VAT on a quarterly basis.

3

Annual Finalization of CIT and PIT Before March 31 of the following year

4

License Tax Within 30 days after receiving ERC (paid once per year)

Case Study: 

Company Ltd., an FDI company, received its Enterprise Registration Certificate (ERC) on January 15, 2026. Believing the common misconception that “no revenue means no need to file taxes,” the founder did not submit the Q1 VAT return or the Personal Income Tax (PIT) declaration.

As a result, the company was hit with late-filing penalties, required to submit multiple rounds of supplementary documents, and even had its tax code temporarily suspended for two weeks. The total cost – including administrative fines, lost time, and disrupted business operations.

This real-world example clearly illustrates that even if a company has not yet generated any revenue, it is still legally required to file VAT and PIT declarations on time from the very first quarter after incorporation. A seemingly small oversight in the early days can quickly escalate into significant financial losses and reputational damage.

Specific Actions Investors Should Take:

  • Set up automatic reminders for all tax filing deadlines
  • Prepare complete supporting documents and invoices from the very beginning
  • Use professional outsourced tax filing services from the first month of operation
  • Perform regular data checks and reconciliations (monthly)
  • Work with a Chief Accountant or a firm experienced in supporting FDI companies

In summary, tax filing is a process that needs careful preparation from the start and can be managed effectively with a clear checklist. If your internal team is not yet capable of handling it, investing in a professional service will help the business avoid major risks and focus on business development.

Get Your Free Investor Handbook 2026

4. Why Vina TPT is trusted by many FDI Companies for Tax Filing

With more than 20 years of experience working with FDI enterprises, Vina TPT fully understands the difficulties foreign investors face in the tax filing process in Vietnam.

We provide comprehensive services, including monthly, quarterly, and annual tax declarations, ensuring that businesses always comply with regulations and meet deadlines.

What makes Vina TPT different is our automatic deadline tracking and reminder system, which minimizes the risk of late or missed filings. In addition, our team can support three languages (English, Japanese, and Vietnamese) and work remotely, making the process convenient for foreign investors.

Thanks to our professional process and practical experience, Vina TPT helps businesses minimize the risk of fines, avoid tax code suspension, and maintain stable operations from the early stages.

Contact Vina TPT today for free consultation and professional tax filing support.

what-foreign-investors-often-get-wrong-about-tax-filing-in-vietnam-expert-advice

BOOK A FREE CONSULTATION