[Newsletter] September 2026 Tax Update: VAT Refund, PIT withholding, CIT & Invoice issuance 

Vietnam tax update september 2026

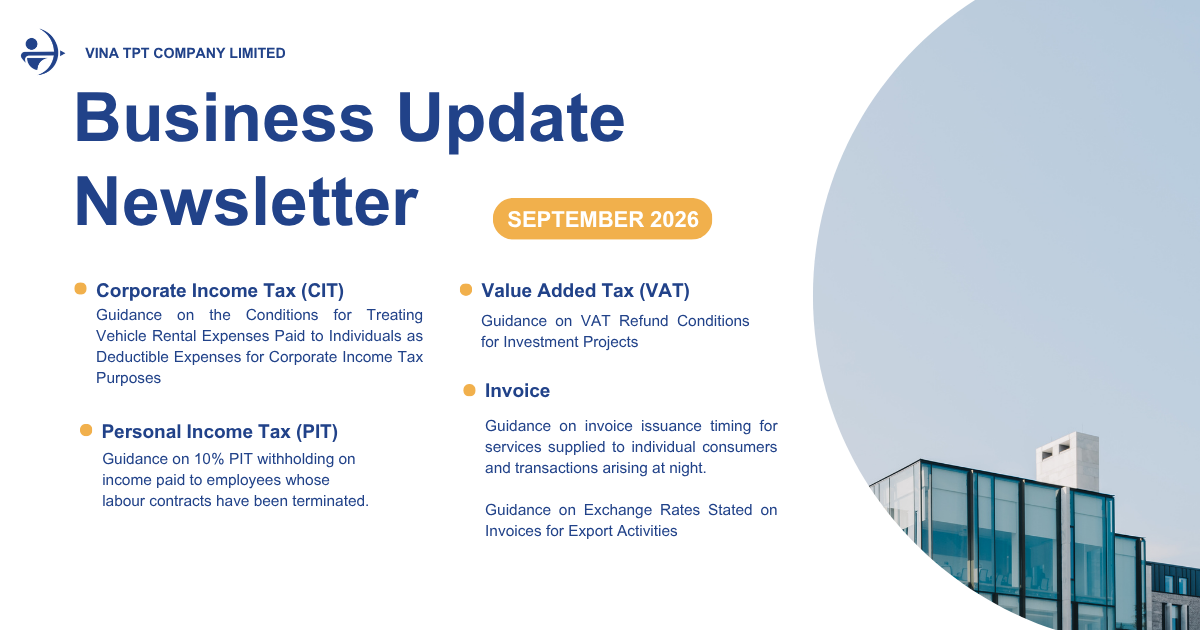
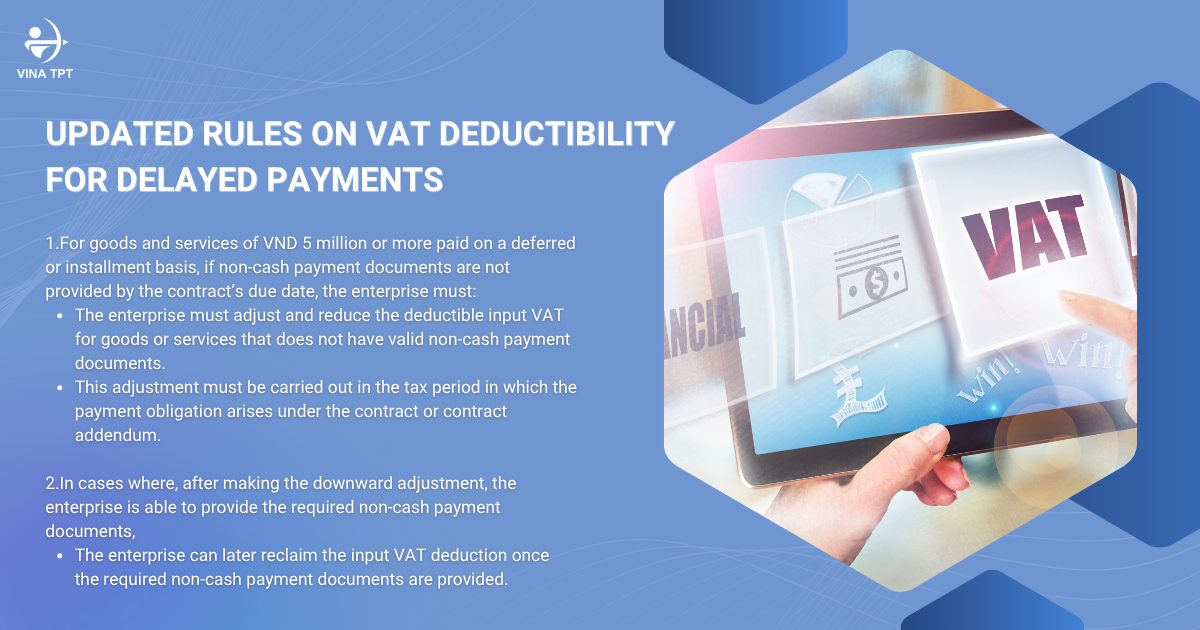
This September 2026 Vietnam tax update summarises recent guidance on VAT refunds for investment projects, deductible vehicle rental expenses, PIT withholding after employment termination, invoice issuance timing and exchange rates on export invoices. Each section highlights the relevant conditions and practical considerations to help businesses review their tax procedures and supporting documents. 

1. INVOICE

Guidance on invoice issuance timing for services supplied to individual consumers and transactions arising at night. 

Pursuant to Official Letter No. 6325/CT-QLNT dated August 26, 2026 of the Tax Department, guiding Article 9 of Decree No. 254/2026/NĐ-CP (effective July 1, 2026). 

Services supplied to individual consumers

For enterprises providing services to individual consumers, including banking; payment intermediary services; credit information services; securities business; crypto-asset transactions; support services for transactions on carbon exchanges; insurance business; money transfers via e-wallets; suspension and resumption of electricity supply; e-commerce; postal and transportation services supporting e-commerce; public passenger transport by metro and bus; passenger transport by taxi, contract vehicle, and two-wheeled motorcycle; parking services; cinema services; and other services, where such enterprises satisfy the conditions of having a software system capable of managing each transaction in detail and maintaining payment collection data in the system on a transaction-by-transaction basis: 

–  The seller shall prepare a Summary of E-Invoice Data for Sales of Goods and Provision of Services and a Detailed Statement of Transactions Arising During the Month or Quarter (covering the period from the first day to the last day of the relevant month or quarter), using the forms prescribed by the Minister of Finance, and submit them to the tax authority no later than the statutory deadline for submission of the Value Added Tax (“VAT”) return in accordance with the laws on tax administration. 

– Where a large volume of invoices is generated, the Summary of E-Invoice Data and the Detailed Statement of Transactions shall be divided into separate data files in accordance with the standard data format prescribed by the tax authority to ensure compliance with the technical requirements for data transmission and receipt. 

The seller is responsible for the accuracy of transaction information, must retain full detailed data for each transaction, and must ensure the data can be retrieved, reconciled and provided, together with related documents, on request of the tax authority or competent state agency. 

Transactions arising during night working hours

Where the seller has no automatic invoicing software and sells goods or supplies services during night working hours as defined by the Labor Code, the invoice must be issued no later than the next working day.ogether with the Appendix on VAT Refund Claim Information (Form No. 01-8/GTGT) as the basis for the tax authority to review and process the refund request. 

Guidance on Exchange Rates Stated on Invoices for Export Activities 

Pursuant to Official Letter No. 6810/CT-QLNT dated 14 September 2026 

In cases where economic or financial transactions are denominated in foreign currencies in accordance with foreign exchange regulations, the seller shall indicate on the invoice the exchange rate between the foreign currency and the Vietnamese Dong as prescribed in Point c.1, Clause 8 of the Appendix attached to Decree No. 254/2026/NĐ-CP. 

Pursuant to Clauses 1 and 5, Article 26 of the Law on Tax Administration No. 108/2025/QH15 and the accounting regulations, the exchange rate shown on the invoice shall be the actual transaction exchange rate determined in accordance with accounting laws and regulations.

2. PERSONAL INCOME TAX 

Guidance on 10% PIT withholding on income paid to employees whose labour contracts have been terminated. 

Pursuant to Official Letter No. 10049/NBI-QLDN1 dated August 3, 2026 of the Ninh Binh Provincial Tax Office, guiding Clauses 1 and 3, Article 26 and Clause 2, Article 50 of Decree No. 253/2026/NĐ-CP dated June 30, 2026 

– Where an employee is a resident individual whose labor contract was terminated on 30 June 2026, and the Company pays the employee’s salary for June 2026 on 10 July 2026, such payment shall be treated as a salary payment made to an individual whose labor contract has already been terminated. If the payment to each individual on each occasion is VND 5 million or more, the Company shall withhold personal income tax (“PIT”) at the rate of 10% before making the payment. If the payment is less than VND 5 million per payment, the Company shall withhold PIT at the rate of 10% only at the individual’s request. 

– The Company shall withhold PIT at the rate of 10% on taxable income from salaries and wages before making payment to the individual. Tax-exempt income prescribed by law, including remuneration for night work and overtime work, and salaries and wages paid for unused annual leave within the conditions, duration and limits prescribed by labor laws, shall not be included in the income subject to withholding. Any amount exceeding the statutory limits shall be included in taxable income. 

Compulsory insurance contributions, personal and dependent deductions, and other allowable deductions are taken into account in determining taxable income when applying the partially progressive tax tariff or upon annual PIT finalization, and shall not be deducted when applying the provisional 10% withholding rate prescribed in Clause 2, Article 50 of Decree No. 253/2026/ND-CP. 

3. VALUE ADDED TAX

Guidance on VAT Refund Conditions for Investment Projects 

Pursuant to Official Letter No. 7019/CT-QLNT dated 22 September 2026 issued by the Tax Department: 

Where, at the time of submitting the VAT refund application, a business establishment falls within the scope of cases eligible for a VAT refund in respect of an investment project, has input VAT that fully satisfies the conditions for VAT credit and refund in accordance with the VAT regulations, and has submitted a VAT refund application dossier in compliance with the tax administration regulations, the business establishment shall be considered for a VAT refund in respect of the investment project. 

Pursuant to Clause 4, Article 3 of Law on Investment No. 61/2020/QH14, Clause 2, Article 15 of Law on Value Added Tax No. 48/2024/QH15, and Article 30 of Decree No. 181/2025/ND-CP, there is no provision stipulating that the date of issuance of the Investment Registration Certificate (“IRC”) shall serve as the basis for determining the input VAT attributable to an investment project 

Where the Company has VAT invoices for purchased goods and services arising prior to the issuance of the IRC, if the Company is able to provide sufficient supporting documents and evidence demonstrating that such goods and services were actually purchased for the preparation and implementation of the investment project in accordance with the laws on investment, and the related input VAT satisfies the conditions for VAT credit and refund under the VAT regulations, such input VAT may be considered for credit and refund in respect of the investment project in accordance with the applicable regulations. 

4. CORPORATE INCOME TAX

Guidance on the Conditions for Treating Vehicle Rental Expenses Paid to Individuals as Deductible Expenses for Corporate Income Tax Purposes 

Pursuant to Official Letter No. 15944/DON-QLDN3 dated 18 August 2026 issued by the Dong Nai Tax Authority: 

  • Where an enterprise rents assets from an individual, the supporting documents required to substantiate the deductible expense include the asset lease agreement and documents evidencing payment of the rental fee. 
  • Where an enterprise rents assets from an individual and the lease agreement stipulates that the rental fee is exclusive of taxes (including value added tax and personal income tax), and the enterprise is required to declare and pay such taxes on behalf of the individual in accordance with the laws on tax administration, the taxes paid on behalf of the individual may also be treated as deductible expenses for corporate income tax purposes, provided that valid tax payment documents are available. 

5. Review Your Business’s Tax Compliance 

Vina TPT provides integrated accounting, tax, HR and payroll, legal and business advisory services for domestic and foreign-invested enterprises in Vietnam. From company establishment and post-licensing procedures to bookkeeping, financial reporting and ongoing compliance, we help businesses manage their obligations at each stage of their operations. 

Our tax services include tax filing and annual finalization, VAT refund assistance, tax health checks, transfer pricing and global minimum tax compliance. We also review supporting records, identify potential compliance gaps, and assist with documentation and explanations requested by tax authorities during tax reviews and inspections. 

If these updates affect your business, our team can help assess the implications, review your current procedures and recommend practical actions suited to your operations. 

Contact Vina TPT to Review Your Tax Compliance 
BOOK A FREE CONSULTATION

what-is-included-in-business-accounting-services-in-vietnam

Annual Tax Finalization in Vietnam 2026: Key Rules, Deadlines & Compliance Guide

annual-tax-finalization-in-vietnam-2026

annual-tax-finalization-in-vietnam-2026

Annual tax finalization is not simply a roll-up of the monthly or quarterly VAT and PIT returns. For the 2026 accounting period (ending on 31 December 2026 for companies that use a calendar financial year), the company must close its VAS books, prepare the annual financial statements, and finalize Corporate Income Tax (CIT) and Personal Income Tax (PIT). The usual statutory deadline is 31 March 2027.

In practice, foreign-invested (FDI) companies face a real risk of reassessment and late-payment interest in the annual tax-finalization period. The pressure points are usually the gap between provisional CIT paid over the four quarters and the tax due on finalization, errors in employee PIT finalization authorizations, and missing related-party transaction appendices.

This article sets out the full tax finalization Vietnam obligations for 2026 and the file the company should start preparing now.

1. What “Tax Finalization” Means in Vietnam

In Vietnam’s tax-administration system, annual tax finalization has a different legal character and a different scope of review from monthly or quarterly returns. Periodic filing only records provisional figures for the period. Tax finalization is the process of consolidating and reconciling all revenue, expenses, taxable income, and tax already paid across the full 12 months of the financial year, so that the tax the company and its employees actually owe, or are entitled to have refunded or offset, is fixed exactly.

The company’s annual tax-finalization file rests on two core obligations:

  • Corporate Income Tax (CIT) finalization: Determine total revenue, deductible expenses, upward and downward adjustments to taxable income, loss carry-forward, and the company’s official CIT for the year.
  • Personal Income Tax (PIT) finalization: Determine total salary and wage income the company paid during the year to all employees (local staff and foreign specialists), declare tax already withheld, and finalize on behalf of individuals who have authorized the company to do so.
  • Mandatory supporting documents: Annual financial statements prepared under VAS (independently audited for FDI companies) and the related-party transaction return set, if related-party relationships arose.

Under Article 44 of the Law on Tax Administration 2019, the annual tax-finalization file must be filed no later than the last day of the third month after the financial year ends.

2. Corporate Income Tax Finalization for 2026

CIT finalization for the 2026 tax year requires an exact match between the financial statements and the CIT finalization return (Form 03/TNDN), together with the loss-carry-forward and tax-incentive appendices, if any.

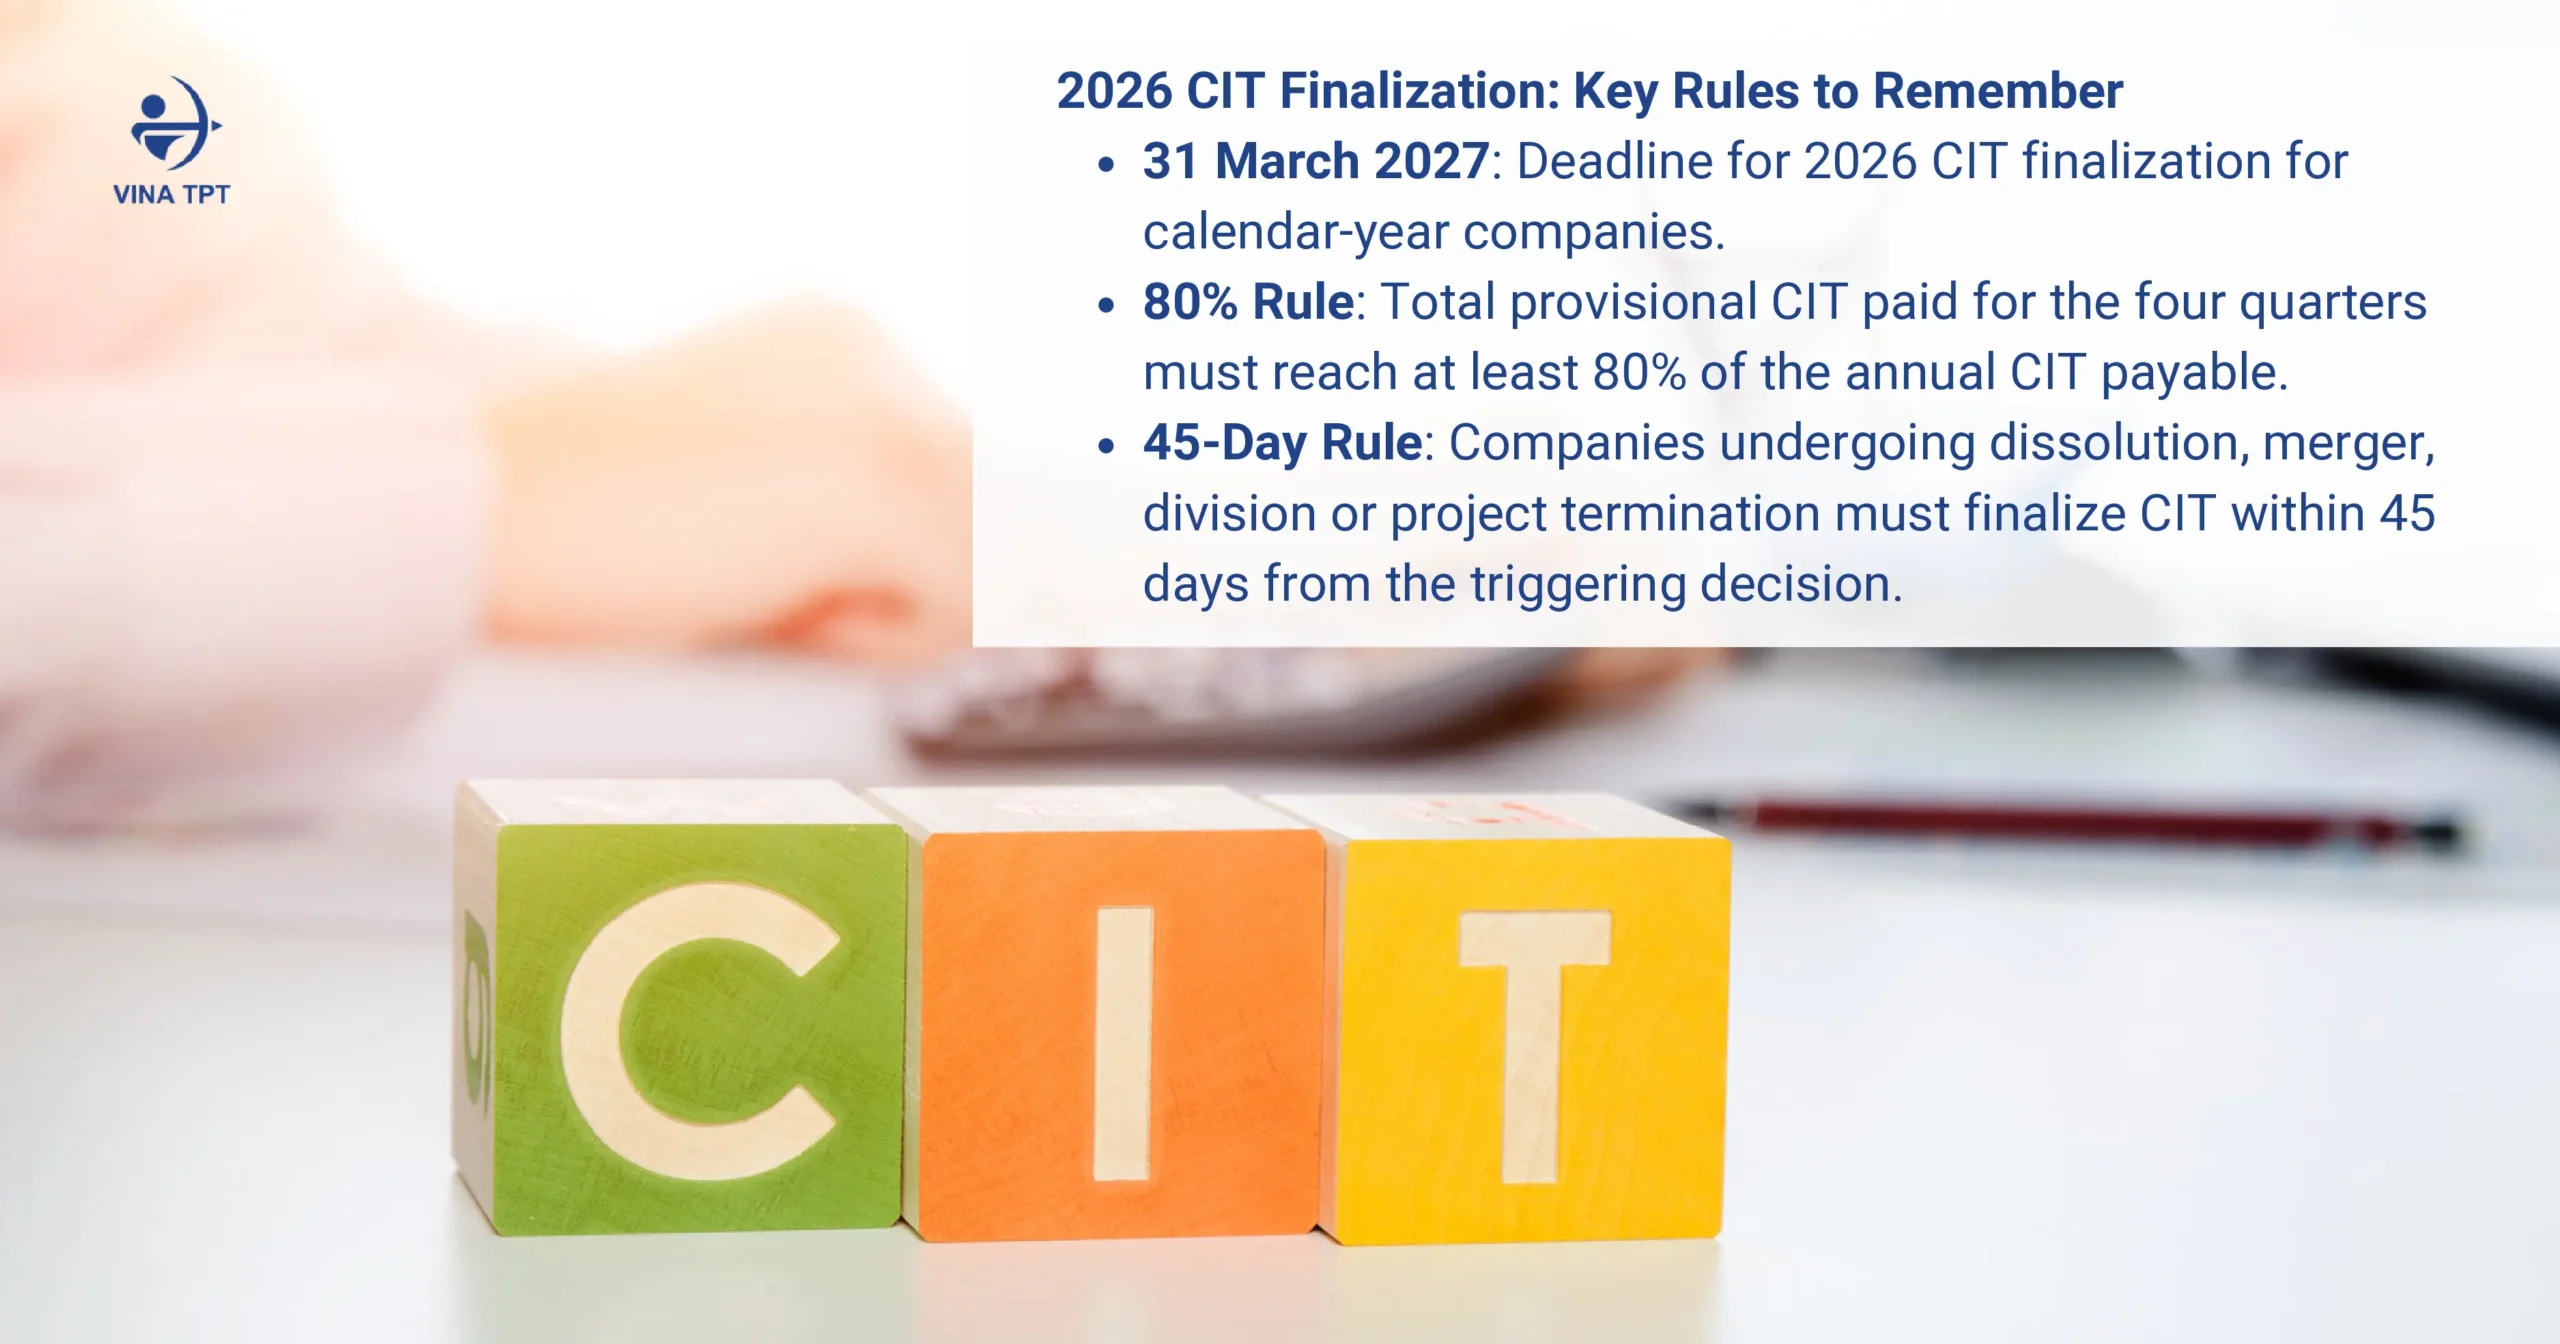
  • Filing deadline: For companies whose financial year matches the calendar year (1 January 2026 to 31 December 2026), the deadline for the 2026 CIT finalization return and the annual financial statements is 31 March 2027. For companies whose financial year does not follow the calendar year, the deadline is 90 days from the end of that financial year.
  • The 80% provisional-CIT rule: Under current rules, total provisional CIT paid over the four quarters of the tax year must not be less than 80% of the CIT due on the annual finalization return. If the four quarterly payments fall short of that 80% threshold, late-payment interest (0.03% per day) is charged on the shortfall from the day after the Quarter 4 payment deadline until the date the tax is actually paid.
  • 2026 support-policy update: If provisional CIT is deferred under a 2026 Government support measure (such as Decree 245/2026/ND-CP), the deferral changes only the payment date of the quarterly provisional tax. It does not change the filing deadline for the 2026 CIT finalization return, which must still be filed by 31 March 2027.
  • Event-based finalization: If a company is dissolved, bankrupt, divided, merged, converted in ownership, or ends a project in 2026, the CIT finalization file must be filed no later than the 45th day from the date of the decision that triggers the event. The company does not wait until the end of the financial year.

Explore Tax Advisory Services

annual-tax-finalization-in-vietnam-2026

3. PIT Finalization the Company Must File

When carrying out CIT and PIT finalization for 2026, the company acts as the income-paying organization. It must prepare the PIT finalization return (Form 05/QTT-TNCN) for all salary and wage income paid in 2026.

Key deadlines and legal points:

  • Deadline for the company (income-paying organization): The deadline to file the 2026 PIT finalization return for individuals who have authorized the company to finalize on their behalf is 31 March 2027.
  • Deadline for individuals who finalize directly: Individuals who must finalize directly with the tax office, those with income from more than one source, or foreign specialists whose contracts have ended, must file by the last day of the fourth month after the calendar year ends, which is 30 April 2027.
  • PIT rules updated from 2026: The 2026 finalization period applies the amended Personal Income Tax Law 2025 and Decree 253/2026/ND-CP (effective from 1 July 2026). The company must split income, family deductions, and tax-exempt items arising before and after 1 July 2026 exactly as the General Department of Taxation’s transitional guidance requires, so that tax withheld from staff is calculated correctly. The company finalizes only for individuals who have signed a labor contract of three months or more and who have submitted a valid tax-finalization authorization in the prescribed form.

4. Related-Party Forms Filed with CIT Finalization

For FDI companies, and for domestic companies that had related-party transactions in 2026, the related-party transaction return set is a mandatory part of the file and must be filed together with the CIT finalization return.

The related-party file submitted with finalization includes:

  • Appendix I: Information on related-party relationships and related-party transactions.
  • Appendices II and III: The list of information and documents to be provided in the Local File and the Master File.
  • Appendix IV: The Country-by-Country Report of the ultimate parent company (CbCR), if the company is in scope.

A company that bought or sold goods or services, borrowed, transferred technology, or paid a management fee to its parent or to other group companies must prepare and keep Transfer Pricing Documentation at its head office before finalization, ready to produce if the tax office inspects or audits.

5. Documents to Prepare Before the Deadline

For the tax finalization Vietnam period to run smoothly and avoid last-minute blocks, the accounting team must lock the full legal file before 31 March 2027. Do not wait until the filing week to start the reconciliation. The most common risk at this stage is not a missing return form. There is a shortage of original vouchers to explain and defend the figures already recorded in the books.

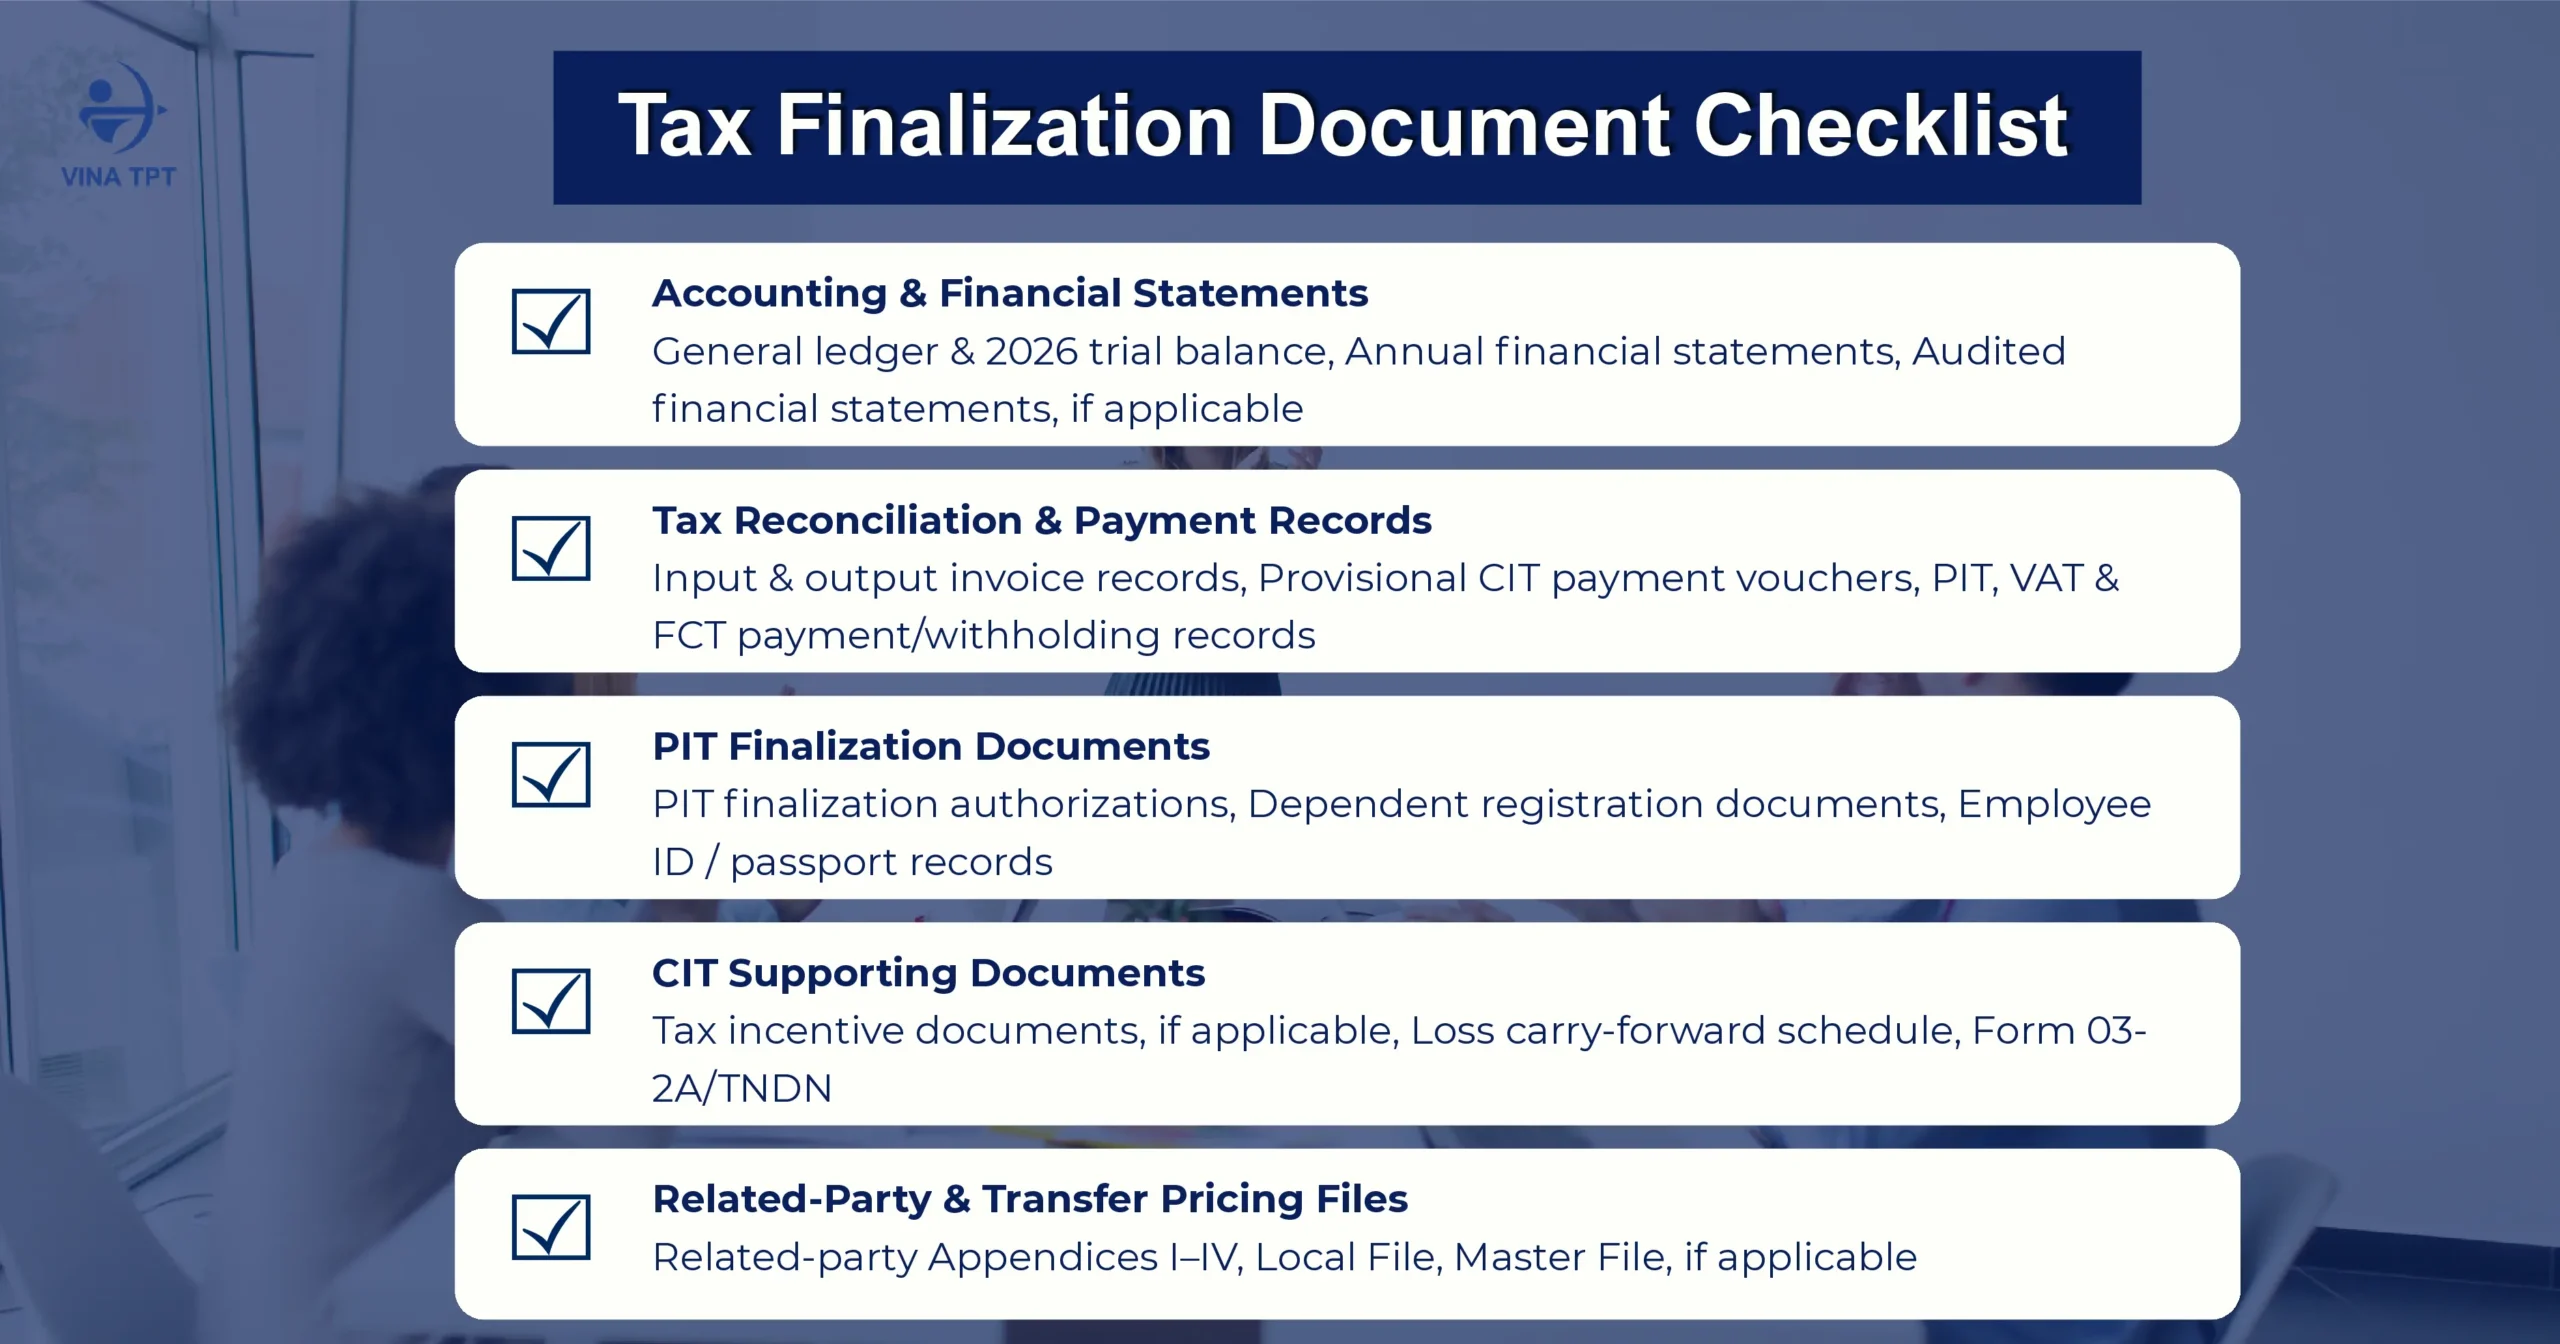
A legally complete annual tax-finalization file must cover these five core document groups:

  • VAS books and financial statements: This is the foundation of the file. Accounting must close the general ledger for all revenue, expense, tax, and capital accounts, together with the 2026 trial balance. For FDI companies that must be audited, the independently audited annual financial statements are the only legal basis for reconciling the CIT finalization return. Any gap between the finalization figures and the audit report will be the first point the tax office questions in an inspection.
  • Tax reconciliation and credit vouchers: This group covers the input and output invoice listings, VAT payment vouchers, the four quarterly provisional CIT payment vouchers, PIT withholding vouchers, and Foreign Contractor Tax (FCT) payment vouchers where payments were made abroad. A 100% match between the listings, the general ledger, and the periodic returns already filed during the year avoids complex supplementary filings before the year is closed.
  • PIT finalization authorization and deduction file: This applies only when the company finalizes on behalf of employees. The file includes the dependent-registration form, the PIT finalization authorization, and copies of personal identification (citizen ID or passport). A missing authorization, or a dependent registration filed after the deadline, will cause the family deduction to be excluded from the annual finalization – even if the income was actually withheld.
  • Tax-incentive file and loss-carry-forward schedule: This covers the legal documents confirming eligibility for CIT incentives, if any, and the schedule tracking losses carried from prior years into 2026 (Form 03-2A/TNDN). Without a valid loss-carry-forward schedule, prior-year losses will be disallowed as a deduction when CIT for this period is calculated.
  • Related-party transaction file (transfer pricing): This covers Appendices I–IV filed with the CIT finalization return, plus the transfer-pricing documentation (Local File and Master File). Every figure in the appendices must match the books exactly for intercompany loans, management fees, royalties, and internal purchases and sales. Leaving this work until March often produces large errors, because data collection and price benchmarking take time.

Reviewing and standardizing all five groups before the deadline turns tax finalization from a high-pressure risk review into a fast, safe, and fully controlled periodic filing.

annual-tax-finalization-in-vietnam-2026

6. Common Finalization Mistakes in 2026

The 2026 finalization period often produces reassessments and late-payment interest not because the company forgot to file, but because of these four data gaps.

  • Missing the 80% provisional CIT threshold: The company underestimates Quarter 4 revenue and expenses, so total provisional payments over the four quarters fall short of 80% of the CIT due on finalization. The tax system charges late-payment interest on the shortfall even if the annual return is filed on time. The way to limit this is to review Quarter 4 figures before locking the provisional payment, rather than scaling Quarter 3 revenue by an estimate.
  • PIT finalization for the wrong authorized persons: The company accepts an authorization to finalize for an individual with income from two or more sources, or for a person who does not meet the conditions to authorize. When the tax office reconciles the file, that portion of the company finalization is rejected. The employee must still finalize personally, and the company must explain the authorizations it accepted.
  • Missing related-party appendices: The company has loans, management fees, royalties, or purchases and sales with related parties, but does not file Appendices I–IV with the CIT finalization return. A missing appendix is a basis for the tax office to review interest expense and payments to related parties. Interest expense can be capped at 30% of EBITDA if the deduction conditions are not proven.
  • A gap between the financial statements and the CIT return: Accounting profit before tax on the financial statements differs from taxable income on the finalization return, and the company has no reconciliation of the adjustments: non-deductible expenses, temporary differences, tax incentives, or loss carry-forward. This is the first point an inspection asks about, because the two sets of figures must lead to the same taxable result.

All four errors can be handled if provisional payments, PIT authorization eligibility, related-party appendices, and the profit-adjustment schedule are reconciled before 31 March 2027.

7. How Vina TPT Supports Annual Tax Finalization

Preparing the 2026 CIT and PIT finalization file requires deep knowledge of VAS accounting and Vietnam’s Law on Tax Administration. Vina TPT provides a full-package annual tax-finalization service so FDI companies can close the year with confidence:

  • Data review and health check: Review the full 2026 books, flag non-deductible expense risks, and reconcile the 80% provisional CIT threshold before the filing deadline.
  • CIT and PIT finalization file: VAS financial statements, the CIT finalization return, the PIT finalization return, and filing on the company’s behalf through the e-tax system.
  • Related-party reporting (transfer pricing): Prepare Appendices I-IV and build a legally compliant transfer-pricing file (Local File and Master File).
  • Representation before the tax office: Explain figure differences directly and defend reasonable expenses during tax inspections.

Are you ready for the 2026 tax finalization period? Contact Vina TPT so our CPAs and tax specialists with more than 10 years of experience can review and lock an accurate file before the deadline.

BOOK A FREE CONSULTATION

What Is Included in Business Accounting Services in Vietnam?

what-is-included-in-business-accounting-services-in-vietnam

what-is-included-in-business-accounting-services-in-vietnam

You have just entered the Vietnamese market and are looking for a business accounting services provider that can optimize cost while still covering your basic compliance obligations. At this stage, many investors still do not have a clear picture of what they actually need: bookkeeping and tax filing only, or also payroll, labor reports, financial statements, and investment reports.

This article from Vina TPT breaks the work down by scope so you can choose an accounting services Vietnam package that matches real operating needs – complete on mandatory obligations, with nothing missing and nothing surplus relative to your current scale.

1. Bookkeeping and Daily Financial Records

The core foundation of any professional outsourcing accounting Vietnam solution is a daily bookkeeping system that is recorded accurately and in strict compliance with the Vietnamese Accounting Standards (VAS).

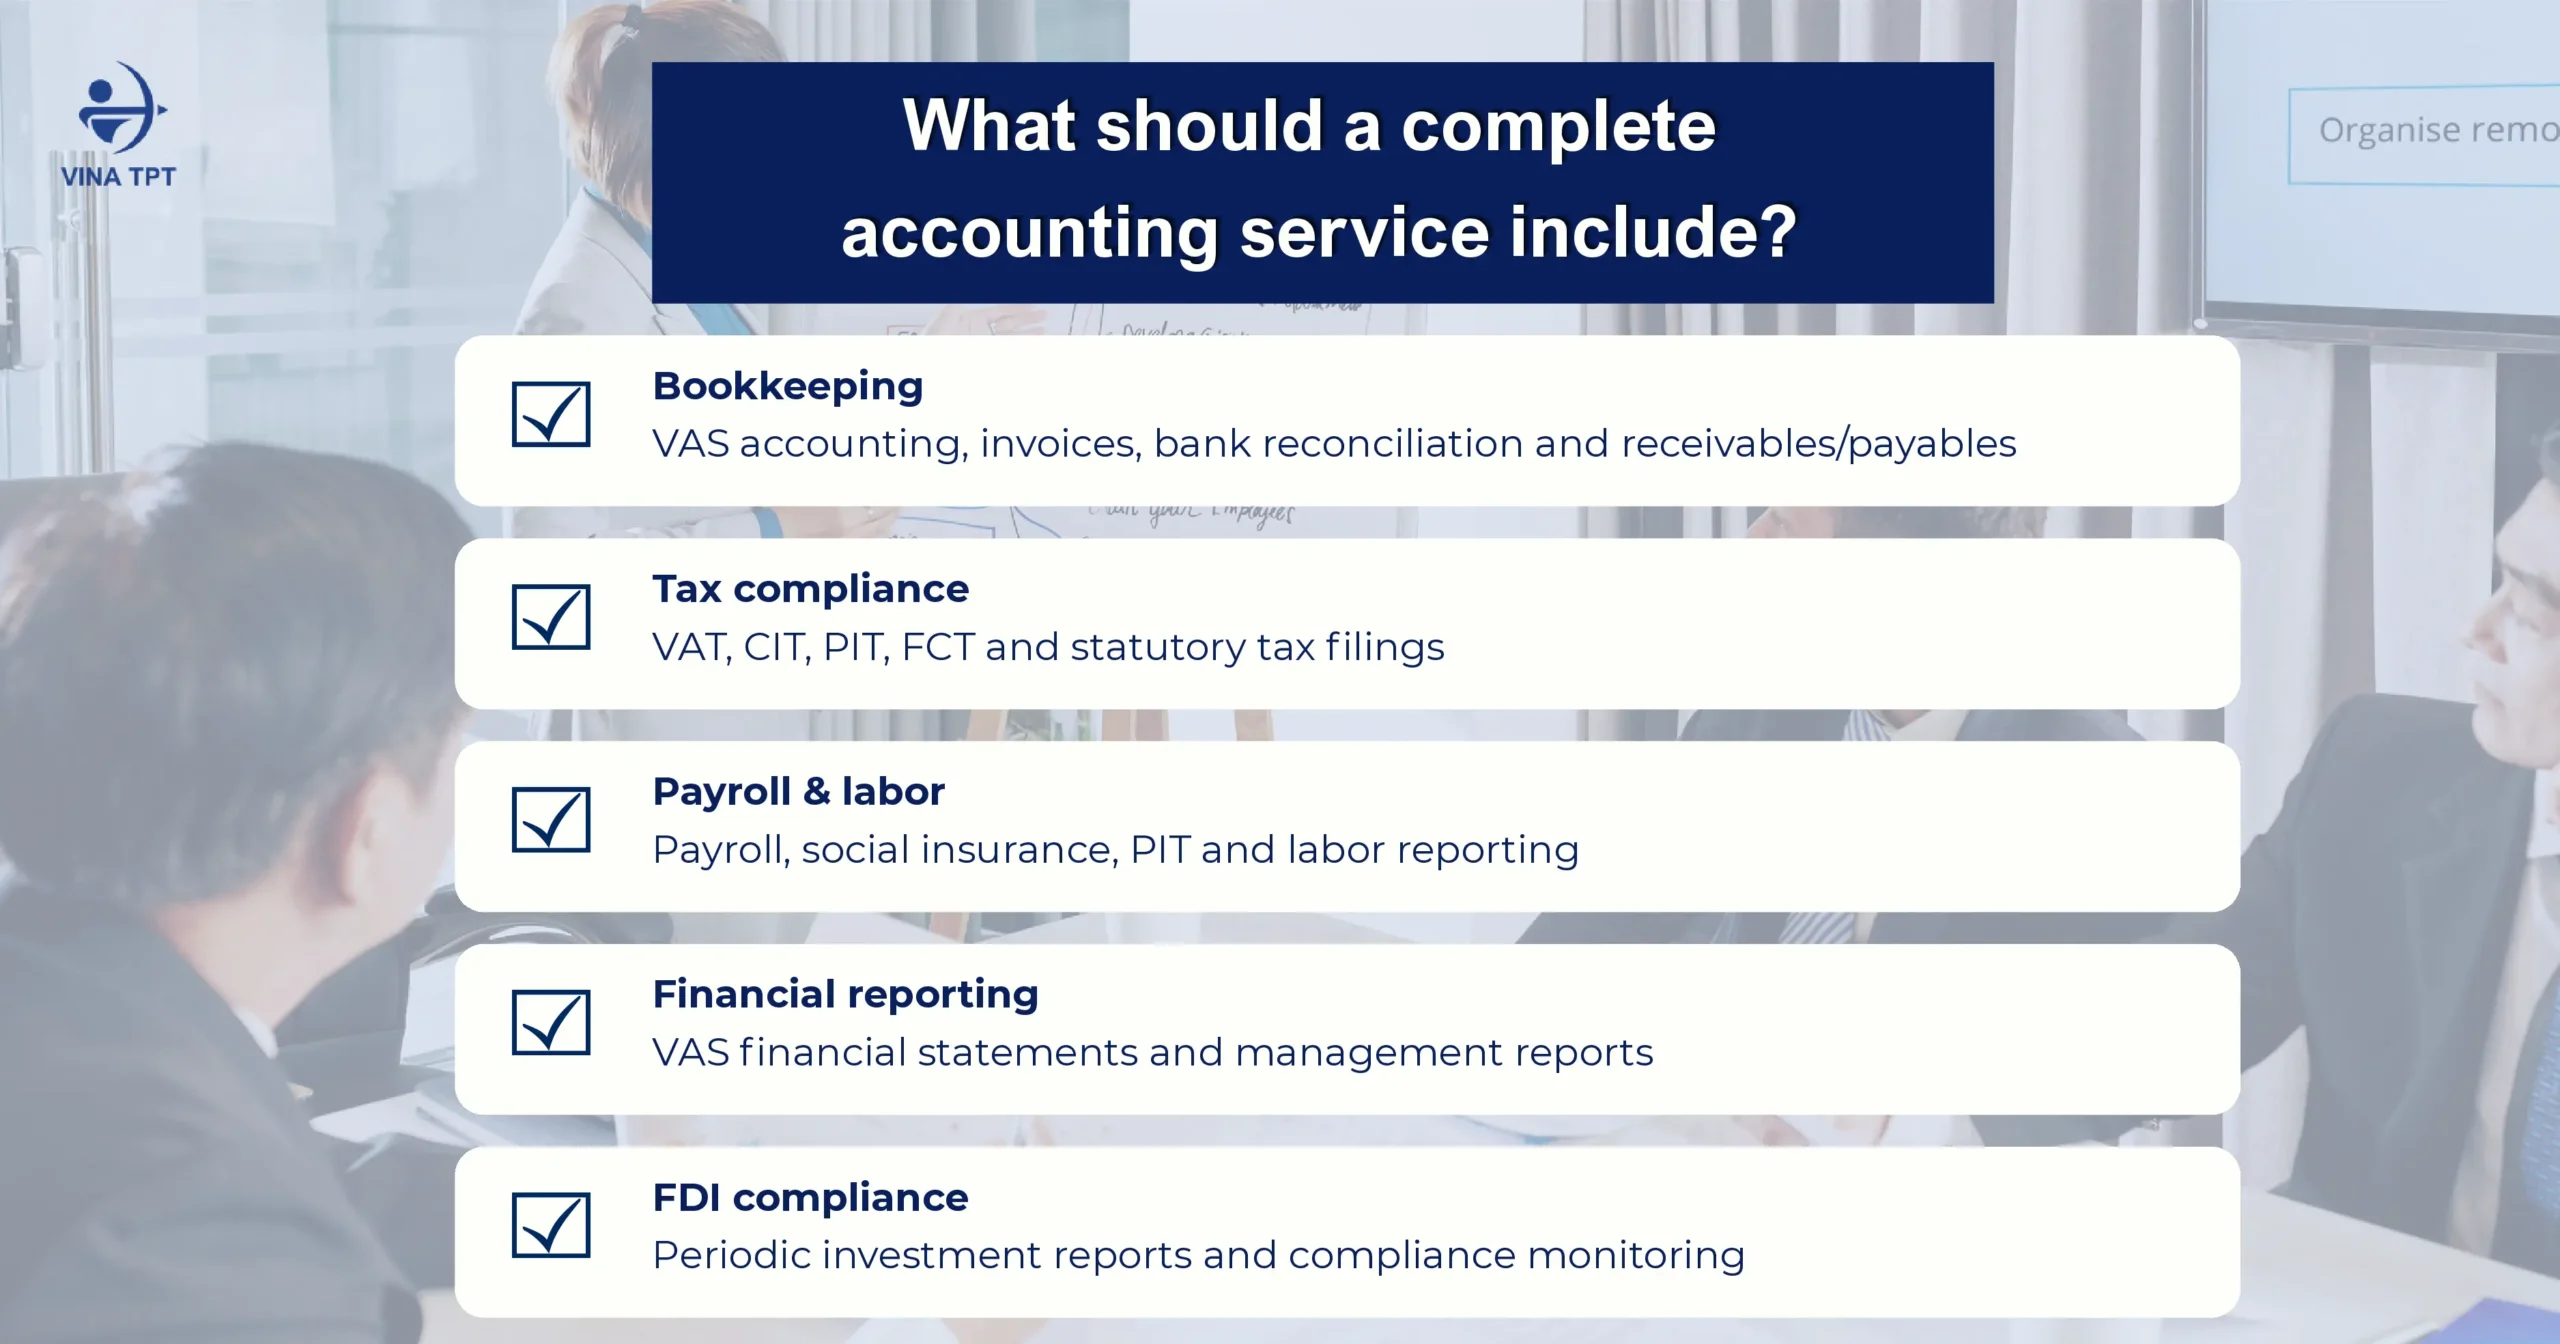
This workstream includes:

  • Document receipt and review: Checking the legality, validity, and reasonableness of all incoming and outgoing e-invoices, bank documents, commercial contracts, and customs declarations (if the company has import-export activities).
  • VAS bookkeeping: Recording in detail the transactions arising in revenue, expenses, fixed assets, prepaid expenses, inventory, and provisions under the correct VAS accounts.
  • Receivables, payables, and bank reconciliation: Reconciling bank statements (VND and foreign-currency accounts) and maintaining detailed records of customer receivables and supplier payables.

Vina TPT’s management view: Accounting data is not merely for internal storage. It must be of a standard that reconciles 100% with VAT returns, the annual audited financial statements, and FDI investment reports. If there is a discrepancy among these three data sources, the company faces a high risk of tax reassessment and significant penalties at finalization.

what-is-included-in-business-accounting-services-in-vietnam

2. Tax Compliance and Statutory Filings
Tax filing is the highest-risk workstream if the company does not keep up with changes in legal regulations. A provider of business accounting services is responsible for fulfilling all of the following obligations:

  • Value-Added Tax (VAT): Preparing and filing VAT returns on a monthly or quarterly basis; strictly reviewing input VAT deduction conditions (especially the mandatory bank-transfer requirement for invoices of VND 5 million or more).
  • Corporate Income Tax (CIT): Calculating quarterly provisional CIT (ensuring that the total provisional payments over four quarters are not lower than 80% of the amount payable on the annual finalization) and preparing the annual CIT finalization return.
  • Personal Income Tax (PIT): Filing withholding PIT returns monthly or quarterly and preparing the annual PIT finalization return for all employees.
  • Foreign Contractor Tax (FCT): Declaring and paying FCT arising from service contracts, royalties, international freight charges, or loan interest paid to foreign counterparties.
  • Business license fee and other taxes: Declaring and paying the business license fee at the beginning of the year, as well as natural resource tax and special consumption tax (if applicable).

The advisory firm must proactively track the tax calendar and alert the company to statutory deadlines in order to fully prevent late-payment penalties or a locked Tax Identification.

3. Payroll, PIT, Social Insurance and Labor Reports

Payroll cannot be separated from the accounting system. Errors in salary calculation and insurance will distort cash flow, affect deductible expenses for CIT purposes, and constitute labor-law violations.

A complete service package should include:

  • Payroll and insurance obligations: Preparing the payroll, issuing confidential payslips, calculating PIT withholdings, making social insurance, health insurance, and unemployment insurance contributions, and registering tax identification numbers and dependents for employees. For expatriates, the specialist must carefully check the Work Permit and Temporary Residence Card (TRC) conditions and correctly determine tax residency status (resident or non-resident) in order to calculate PIT accurately.
  • Five mandatory labor reports: In addition to tax returns, FDI companies are required to submit five periodic labor reports according to the standard schedule below:

Labor Report

Receiving Authority Filing Deadline

Prescribed Form

1. Report on labor utilization Department of Labor, Invalids and Social Affairs / Industrial Park or Economic Zone Management Board Twice a year: before 5 June and 5 December Form No. 01/PLI (Decree 145/2020/ND-CP)
2. Report on unemployment insurance participation Department of Labor, Invalids and Social Affairs Once a year: before 15 January of the following year Form No. 33 (Circular 28/2015/TT-BLDTBXH)
3. Occupational accident report Department of Labor, Invalids and Social Affairs Twice a year: before 5 July and 10 January of the following year Appendix XII (Decree 39/2016/ND-CP)
4. Occupational safety and hygiene report Department of Labor, Invalids and Social Affairs and Department of Health Once a year: before 10 January of the following year Appendix II (Circular 07/2016/TT-BLDTBXH)
5. Occupational health report District/City Medical Center Twice a year: before 5 July and 10 January of the following year Appendix 8 (Circular 19/2016/TT-BYT)

4. Financial Reporting and Management Reports

At the end of the financial year, the accounting services Vietnam provider prepares a complete set of financial statements under VAS, including the balance sheet, income statement, cash flow statement, and notes to the financial statements. This set of reports is the legal basis for the Tax Authority, the independent auditor, and submission to the statistics authority.

In addition to the statutory financial statements, the management of an FDI company also needs periodic monthly or quarterly Management Reports:

  • Profit and Loss (P&L) management report analyzing revenue and expenses
  • Cash flow management report
  • Aging report for accounts receivable and accounts payable

These management reports are presented in bilingual format (English – Vietnamese) so that Headquarters can monitor the financial health of the Vietnam entity without a language barrier.

Explore Vina TPT’s Accounting Services

5. Mandatory FDI Investment Reports

This is the obligation that many FDI companies miss when they use low-cost accounting packages. Missing investment reports not only leads to substantial administrative penalties but also creates serious bottlenecks when the company later adjusts its Investment Registration Certificate (IRC), increases capital, extends the project, or remits profits abroad.

Every foreign-invested enterprise (from 1% to 100% foreign capital) or project that has been granted an IRC is required to file investment reports. Even if the project has not yet generated revenue, is still in the construction phase, or has temporarily suspended operations, the company must still report (by declaring zero figures).

Investment reporting obligations consist of two main groups:

  1. Report on the Implementation of the Investment Project (filed online on the fdi.gov.vn system under Decree 96/2026/ND-CP)
  • Quarterly report: Filed before the 10th day of the first month of the following quarter. Content includes implemented investment capital, revenue, import-export value, headcount, amounts paid to the state budget, and land/water-surface use.
  • Annual report: Filed before 31 March of the following year. Content includes a comprehensive assessment of investment results, product sales, average employee income, operating costs, R&D activities, environmental impact, and the origin of the technology used.
  1. Investment Monitoring and Evaluation Report (under Decree 19/2026, Decree 96/2026, and Circular 44/2026/TT-BTC – Form 13)
  • Quarterly report: Filed before the 10th day of the first month of the following quarter.
  • Six-month report: Filed before 10 July of the current year.
  • Annual report: Filed before 10 February of the following year.

Vina TPT’s management view: Figures on the Investment Activity Report (IAR) must match the VAS accounting books and the tax returns. A discrepancy between the investment report and the audited financial statements is the first signal that the investment management authority and the tax authority will place the company on a specialized inspection list.

6. How to Choose the Right Business Accounting Services Package

To choose a suitable accounting compliance package, the Board of Directors of an FDI company should follow these steps:

  • Correctly determine scale and transaction profile: Assess the monthly volume of source documents, whether the company has import-export activities or Foreign Contractor Tax (FCT), the size of the workforce, and whether expatriates are employed.
  • Lock in the exact Scope of Work: Require the provider to state clearly in the contract whether the package covers only bookkeeping and tax filing, or a full package that includes payroll, labor reports, and periodic FDI investment reports.
  • Provider evaluation criteria: Prioritize a partner with hands-on FDI experience, a bilingual advisory team, a multi-level quality control (QC) process before filing, and the ability to represent the company directly before the Tax Authority and the investment management authority.
  • Clarify management reporting and the advisory layer: Ask whether the provider issues monthly management reports (P&L, cash flow, receivables and payables) and whether those reports are figures only or include commentary. At the same time, lock in the advisory scope in advance: filing only, or also support when a tax issue arises, an inspection is launched, or Headquarters needs an explanation of the figures.

7. How Vina TPT Delivers Business Accounting Services

Vina TPT provides a comprehensive business accounting services solution that gives FDI companies full legal peace of mind in Vietnam:

  • VAS bookkeeping and full-package tax filing: Recording the books under VAS and filing VAT, CIT, PIT, and FCT accurately and on time. The package also includes Chief Accountant services – a mandatory requirement for every FDI company, needed from company setup through the opening of the bank account.
  • Payroll administration and labor reports: Calculating salaries, optimizing insurance costs, completing expatriate PIT finalization, and filing all five mandatory labor reports.
  • Financial statements and FDI investment reports: Preparing the annual financial statements, supporting work with the independent auditor, and handling the full package of periodic investment monitoring reports.
  • Flexible operating model: Advising and delivering bilingual management reports (English – Vietnamese – Japanese), with remote or hybrid working arrangements depending on the company’s stage of development.
  • Continues to support in-depth services: VAT refunds, preparation and accompaniment during tax inspections, transfer pricing documentation, and advisory on mergers and acquisitions.

If your company wants to review its current compliance scope, contact Vina TPT today for an expert consultation on the most suitable solution.

BOOK A FREE CONSULTATION

what-is-included-in-business-accounting-services-in-vietnam

Common Tax Services in Vietnam and When Your Business Needs Them

common-tax-services-in-vietnam-and-when-your-business-needs-them

common-tax-services-in-vietnam-and-when-your-business-needs-them

In the Vietnamese market, B2B tax advisory firms rarely apply a single packaged model to every company. In actual operations, the service system is divided into two distinct work groups:

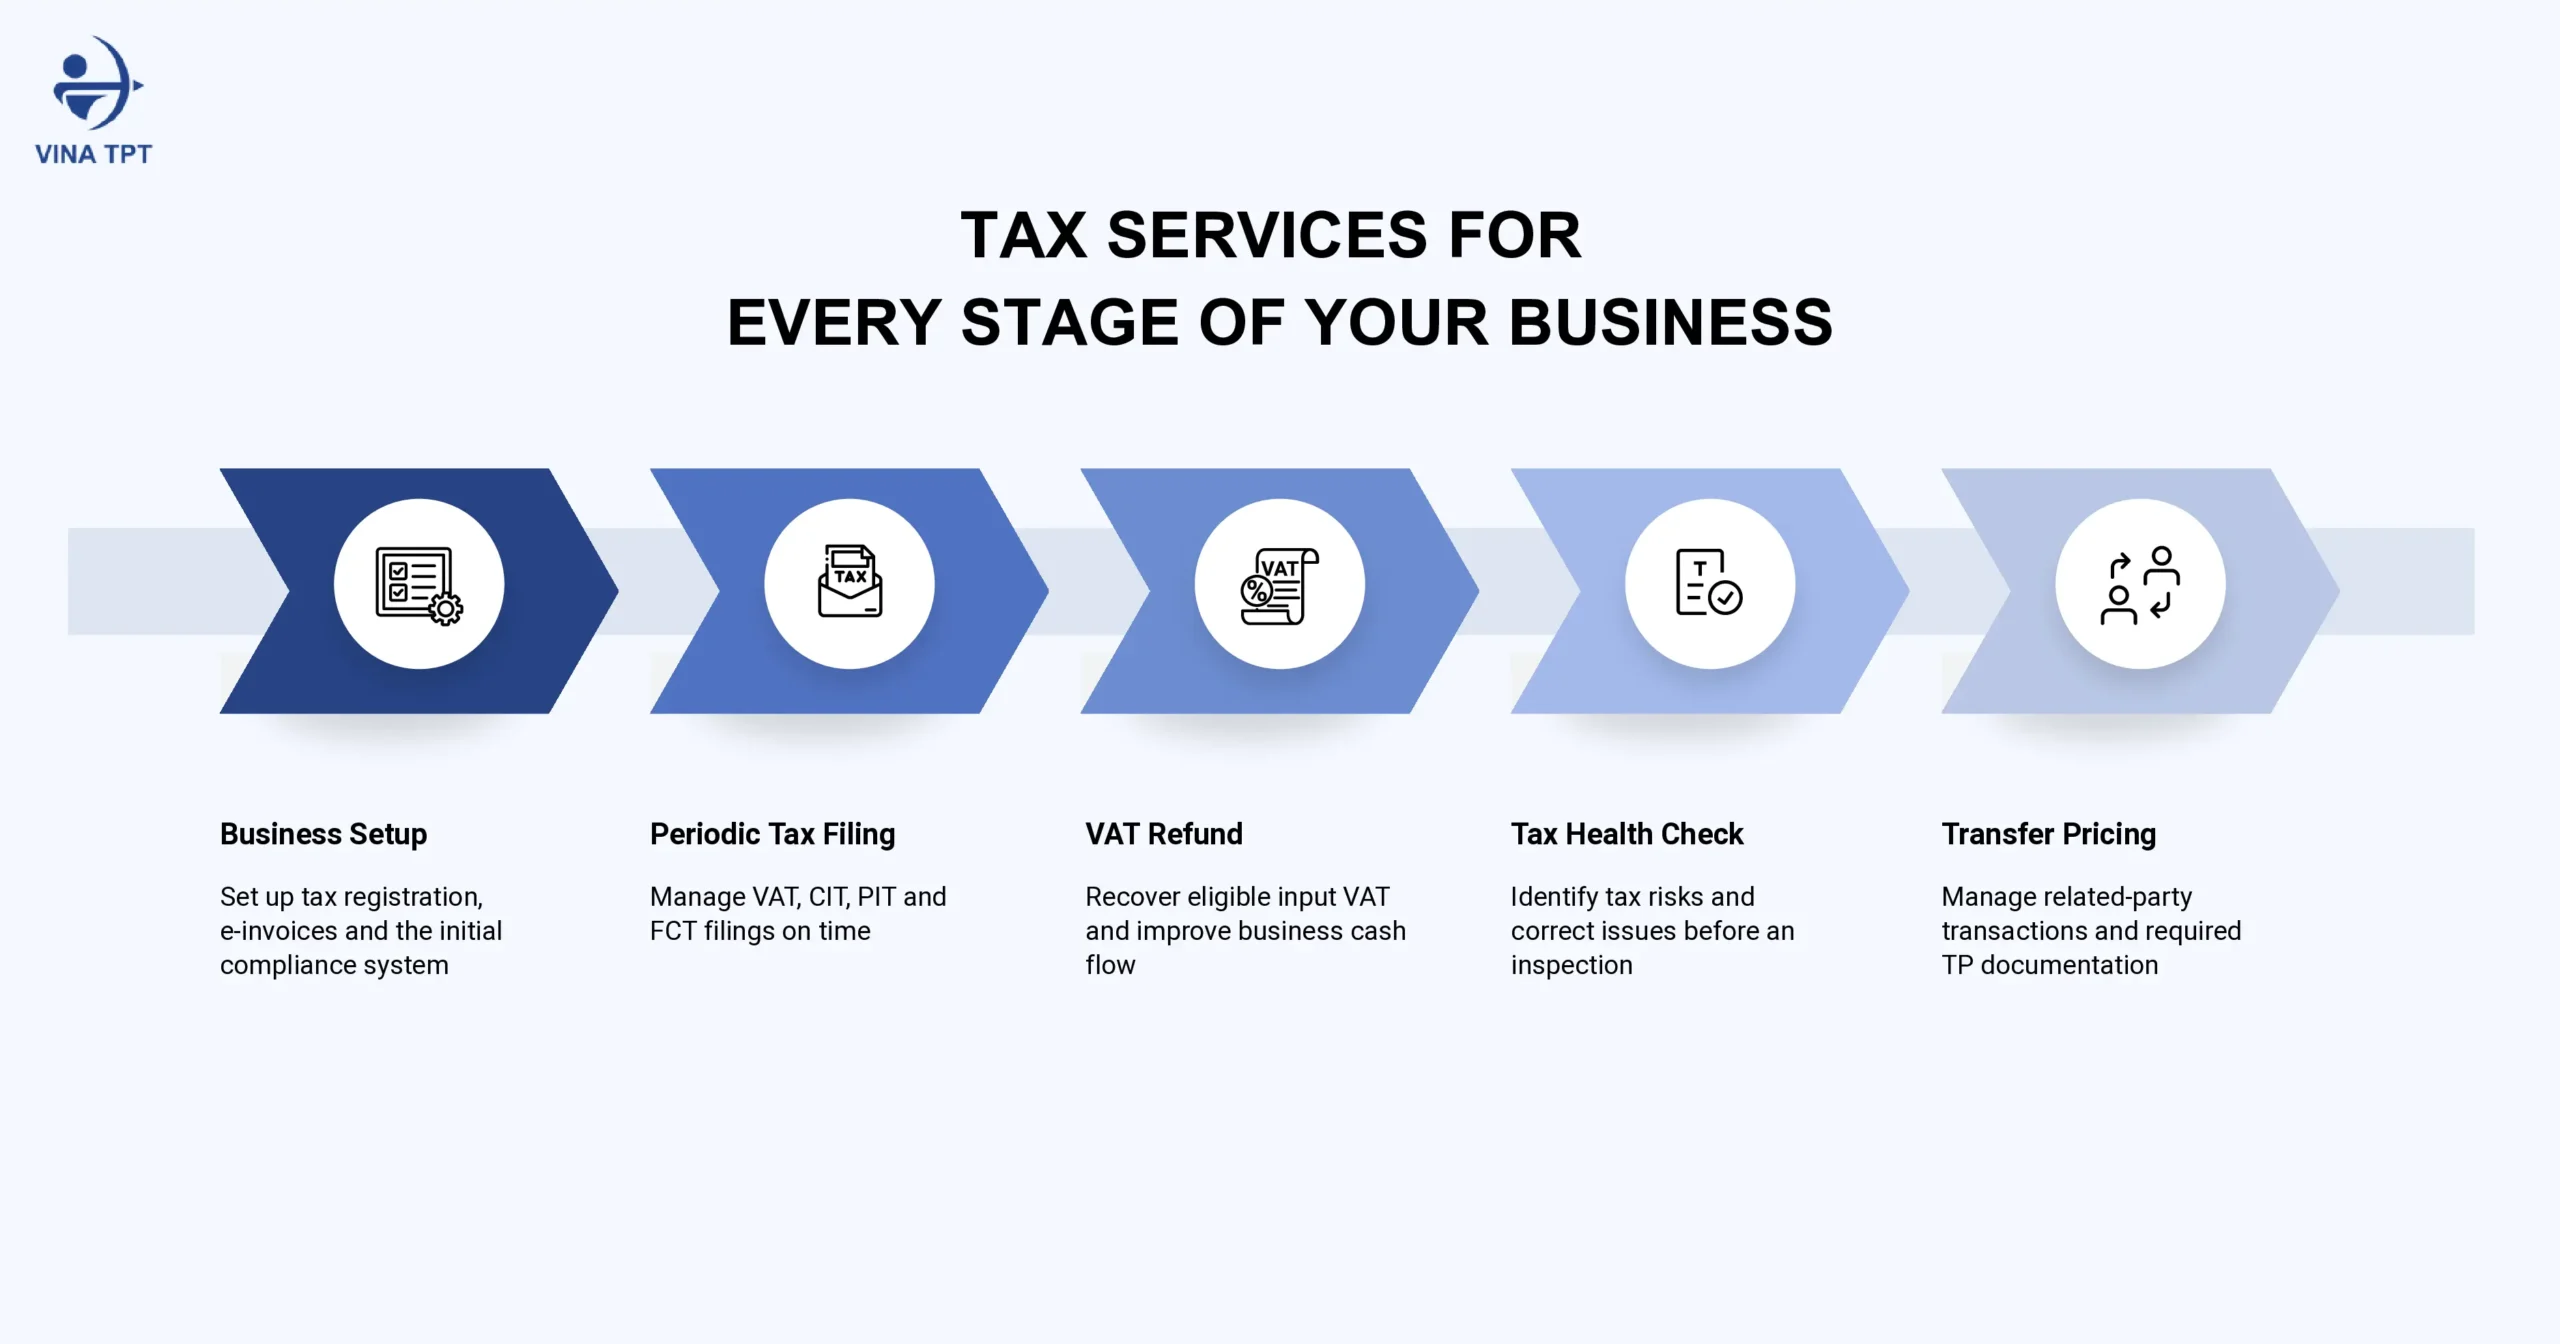
  • Periodic compliance (Tax Compliance) is the workstream a company must maintain throughout its operating life. The typical scope covers initial tax registration, determination of the filing method and filing period, and then the preparation and submission of periodic returns: VAT on a monthly or quarterly basis; withholding PIT on a monthly or quarterly basis plus the annual finalization; quarterly provisional CIT followed by the annual finalization; Foreign Contractor Tax (FCT) whenever an outbound payment is made; and the business license fee together with any industry-specific taxes. This workstream is tightly linked to the accounting books. A return is only correct when the VAT (tax services in vietnam), payroll, FCT, and CIT figures match the source documents already recorded.
  • In-depth advisory (Tax Advisory) comes into play when the company needs more than on-time filing and has to resolve a specific situation. Common services include VAT refunds to recover cash locked in uncredited input VAT; a Tax Health Check to surface risk before an inspection or a fundraising round; and related-party / Transfer Pricing compliance when there are dealings with a parent or group company. Choosing the right tax services in Vietnam therefore depends not only on company size, but also on its operating stage, transaction structure, and current tax risks.. Many FDI companies also need expatriate PIT finalization – because residency status, the Work Permit, and the tax calculation method for expats differ from those for local staff — as well as Global Minimum Tax advisory when the group falls within the scope of application. This is not ordinary monthly filing work.

Many FDI companies and SMEs fall into an “operating trap” by choosing the wrong service package at the wrong time. The result is wasted cost on one side and a serious risk of tax reassessment and administrative penalties on the other.

The article below examines the most common tax services in Vietnam, explains which businesses need each service, and identifies the right time to use them.

1. Common Tax Services in Vietnam

As an FDI company grows, the scope of tax services in Vietnam it requires also becomes more complex, moving from initial registration and periodic filing to specialized advisory work.

Understanding this structure helps the Board of Directors and the finance team choose the right service package at the right time, and keep figures consistent across accounting, tax, and investment reporting.

1.1. Initial Tax Registration 

This service layer is the first legal stepping stone immediately after company incorporation and establishes the foundation for tax compliance Vietnam requirements throughout the company’s operating life.

  • Scope of work: Registering the company’s Tax Identification Number (TIN), purchasing and activating a digital signature (CA token), registering e-invoices with the tax authority, determining the VAT calculation method (credit/deduction method or direct method), opening a bank account and notifying the tax authority of the account, and completing Level-2 VNeID identity for the Legal Representative.
  • Suitable for: Newly established FDI companies looking for tax services in Vietnam immediately after receiving an Enterprise Registration Certificate (ERC), particularly those preparing to commence operations without an in-house tax team.
  • When to implement: Immediately after the ERC is issued and before the first invoice is issued or any payment or capital contribution is received.

Vina TPT’s professional view: Configuring the wrong filing frequency (monthly versus quarterly, or vice versa) or choosing the wrong VAT method at this stage will create a chain of problems and force the company into complex explanation procedures with the managing tax authority.

1.2. Periodic Tax Filing (VAT, CIT, PIT, FCT, License Tax)

Periodic filing is one of the core tax services in Vietnam, covering recurring monthly, quarterly, and annual tax obligations for operating companies.

  • Scope of work:
    • Value-Added Tax (VAT): Preparing monthly or quarterly VAT returns and reconciling incoming and outgoing invoices on the General Department of Taxation’s e-invoice system.
    • Personal Income Tax (PIT): Filing monthly or quarterly withholding PIT returns and completing the annual PIT finalization for Vietnamese employees and expatriates.
    • Corporate Income Tax (CIT): Calculating and paying quarterly provisional CIT (ensuring that the four quarterly payments are not lower than 80% of the annual amount payable) and preparing the annual CIT finalization return.
    • Foreign Contractor Tax (FCT): Declaring and paying FCT on each occurrence or on a monthly basis whenever payments are made to foreign suppliers.
  • Suitable for: Every company operating in Vietnam. It is especially relevant for FDI companies with a complex cost structure, expatriate payroll, or outbound payments for royalties, loan interest, and international consulting services.
  • When to implement: From the first filing period after the Tax Identification Number (TIN) is issued – even if no revenue or expense has arisen yet – and on a continuous basis in line with statutory deadlines.

EXPLORE ACCOUNTING & TAX SERVICES

1.3. VAT Refund 

Among specialized tax services in Vietnam, VAT refund support goes beyond standard periodic filing (tax services in vietnam). It is a specialized advisory and dossier-handling process designed to recover eligible input VAT that has not yet been fully credited.

  • Scope of work: A VAT refund is not an extension of the monthly return. It is a specialized service: reviewing the legality of every incoming invoice, checking non-cash bank payment evidence, reconciling customs declarations and export contracts where goods are exported, preparing the refund dossier, filing it, and explaining it directly to the tax authority during the pre-refund or post-refund inspection.

The person handling the file must have processed real cases, because any document group can delay or reject the application. Invoices that do not qualify for credit, cash payments on transactions of VND 5 million or more, discrepancies between the VAT return and the export file, or explanations that do not match the books are the first points the tax authority will raise. Advice that stays theoretical – and has never followed a dossier through to a refund decision – will struggle to anticipate supplementary requests and the timeline for receiving the funds.

  • Suitable for: Companies whose accumulated uncredited input VAT is VND 300 million or more and that also meet all current refund conditions. For the detailed conditions and eligible cases, refer to VAT Refund in Vietnam 2025: Updated Conditions and Eligible Cases Explained.
  • When to implement: When the refundable VAT amount is material and the company needs to release frozen cash for reinvestment.

1.4. Tax Health Check and Risk Review

A Tax Health Check is one of the preventive tax services in Vietnam designed to identify compliance risks before they develop into larger issues during a tax inspection.

  • Scope of work rewritten: A Tax Health Check is an independent third-party review of the full set of accounting books, the tax compliance position, and the alignment between those two sources. The work covers examining source documents, VAS bookkeeping, a review of VAT, CIT, PIT, and FCT, identifying items at risk of being disallowed as deductible expenses, and then preparing a risk report with a plan to file supplementary returns if needed.

When the books and the tax returns are placed side by side, the company can see the gaps in control or in cash flow: invoices that do not qualify for credit, expenses lacking supporting documents, omitted FCT, off-track provisional CIT, or payroll figures that do not match PIT. From those discrepancies, the advisor proposes a suitable course of action: tightening the document process, amending returns, strengthening internal controls, or preparing an explanation file ahead of an inspection.

  • Suitable for: A Tax Health Check is suitable for companies that have operated for two to three years or more but have not yet gone through a tax inspection; companies preparing for an M&A transaction, a restructuring, or a fundraising round; companies that are about to change their accounting and tax service provider; or companies that want to review internal processes and put in place tighter controls over documents, filings, and figure reconciliation before risk is discovered from the outside.

1.5. Transfer Pricing and Related – Party Transactions

Transfer Pricing is the way a company prices transactions with related parties so that the price of goods, interest, royalties, or management fees has a comparable basis and is not treated as a tool for shifting profit between companies in the same group. Related-party transactions are those dealings: buying and selling goods, lending, receiving services, paying group management fees, or paying royalties to a parent, a subsidiary, a commonly owned company, or another party treated as related under Vietnamese tax law.

These transactions usually arise when an FDI company in Vietnam is not fully standalone. The company may import raw materials from a group plant, pay a management fee to an overseas headquarters, take an intra-group loan, or pay a royalty to use the parent’s brand and technology. Not every outbound payment is a related-party transaction – hiring an independent contractor, for example, may give rise only to FCT – but most companies that belong to a multinational group need to identify the correct counterparties before CIT finalization.

This is a specialized tax advisory Vietnam workstream. The tax authority does not only ask whether the return was filed; it asks whether the price and the profit margin are reasonable compared with independent dealings. Missing documentation, or internal pricing that is too high or too low, can lead to a deemed assessment and a tax reassessment. The company should therefore understand the nature of the transaction first, and only then move on to the appendices and the Transfer Pricing documentation.

Within specialized tax services in Vietnam, Transfer Pricing requires a more structured execution process once the nature of the related-party transactions has been correctly identified. The work does not stop at a year-end appendix; it runs across four layers.

  • Diagnostic review is the step of reading back every transaction with the parent and related companies: purchases and sales of goods, intra-group loans, group management fees, royalties, cost sharing, or the provision of services. The advisor identifies which transactions fall within the related-party scope, where current pricing sits, what is missing from the existing file, and which points the tax authority is likely to raise when the figures are compared with independent profit margins.
  • Compliance filings are the statutory reporting layer. The company must prepare Appendices I, II, III, and IV on related-party transactions and submit them with the annual CIT finalization return, usually within 90 days after the end of the financial year. A missing appendix or an incorrect line item is not only a formal error; it is a signal for the tax authority to look more closely at internal pricing.
  • Transfer Pricing documentation goes beyond the return. The company prepares and retains the Local File, the Master File (Global File), and the Country-by-Country Report (CbCR) if it is in scope, under Decree 132/2020/ND-CP and the current implementing guidance. This file set explains why the chosen price, royalty, or management fee was selected and which comparability method is being used.
  • Defense during inspection is the final layer. When the tax authority inspects Transfer Pricing, the advisor represents the company in explaining the pricing method, the profit margins, and the link between the documentation, the books, and the CIT return. Completing the first three layers early reduces the pressure at this stage.

This service is suitable for FDI companies that are members of a multinational group and buy or sell goods, provide services, lend, or franchise with related parties. Implementation should start as soon as related-party transactions arise – not wait until the finalization deadline is close. The file must be complete before the annual CIT finalization deadline so the company is not filing the return while still lacking documents when questions are asked.

common-tax-services-in-vietnam-and-when-your-business-needs-them

2. How Vina TPT Provides Tax Services in Vietnam

Vina TPT provides tax services in Vietnam for most types of companies operating in the country: newly established companies that need setup and periodic filing, SMEs with a stable transaction flow, and FDI companies that belong to a group and have a more complex cost structure. The foundation layer covers tax registration, e-invoices, VAT, CIT, PIT, and FCT filings, and the monthly, quarterly, and annual obligations that follow.

In parallel, the team includes CPA-qualified specialists and Chief Accountants who can support the deeper issues that a monthly return cannot resolve: VAT refunds, Tax Health Checks, expatriate PIT finalization, related-party / Transfer Pricing documentation, and advisory work when the company falls within the scope of the Global Minimum Tax.

  • Foundation compliance layer: Core tax services in Vietnam covering initial tax setup and timely VAT, CIT, PIT, and FCT filings aligned with the accounting books.
  • In-depth advisory layer: VAT refund dossiers, independent Tax Health Checks, and the review and preparation of Transfer Pricing documentation.
  • Integrated operating ecosystem: Connecting tax data with the VAS books, payroll and social insurance, financial statements, and FDI investment monitoring reports.

If your company is reviewing its current tax services in Vietnam – from periodic filing to VAT refunds, Tax Health Checks, or Transfer Pricing – contact Vina TPT for a tax roadmap that matches your operating stage and compliance needs.

BOOK A FREE CONSULTATION

What Does a Tax Consultant in Vietnam Actually Do?

what-does-a-tax-consultant-in-vietnam-actually-do

what-does-a-tax-consultant-in-vietnam-actually-do

If you are already doing business in Vietnam and looking for tax advisory support, the harder question is often not whether to hire someone, but which services a tax consultant Vietnam actually offers. Some firms only handle monthly filings. Others also cover VAT refunds, tax health checks, inspection support, and transfer pricing. The scope is not the same, and the right package depends on where your company is in its operating cycle.

This article maps the tax advisory Vietnam services most commonly provided in the market: the routine accounting – tax work that keeps filings on time, the specialized work that protects cash flow and inspection risk, and the point at which an FDI company should bring in a professional partner. The goal is to give you a clear picture of tax compliance Vietnam support before you choose a consultant.

1. What Accounting & Tax Consultant Services Cover Each Month

For FDI companies, the role of a tax consultant Vietnam never stands alone as “someone who just files returns.” It must be tied to the internal accounting system. Periodic tax compliance Vietnam requires absolute accuracy from incoming source documents through to the data submitted on the Tax Authority’s system.

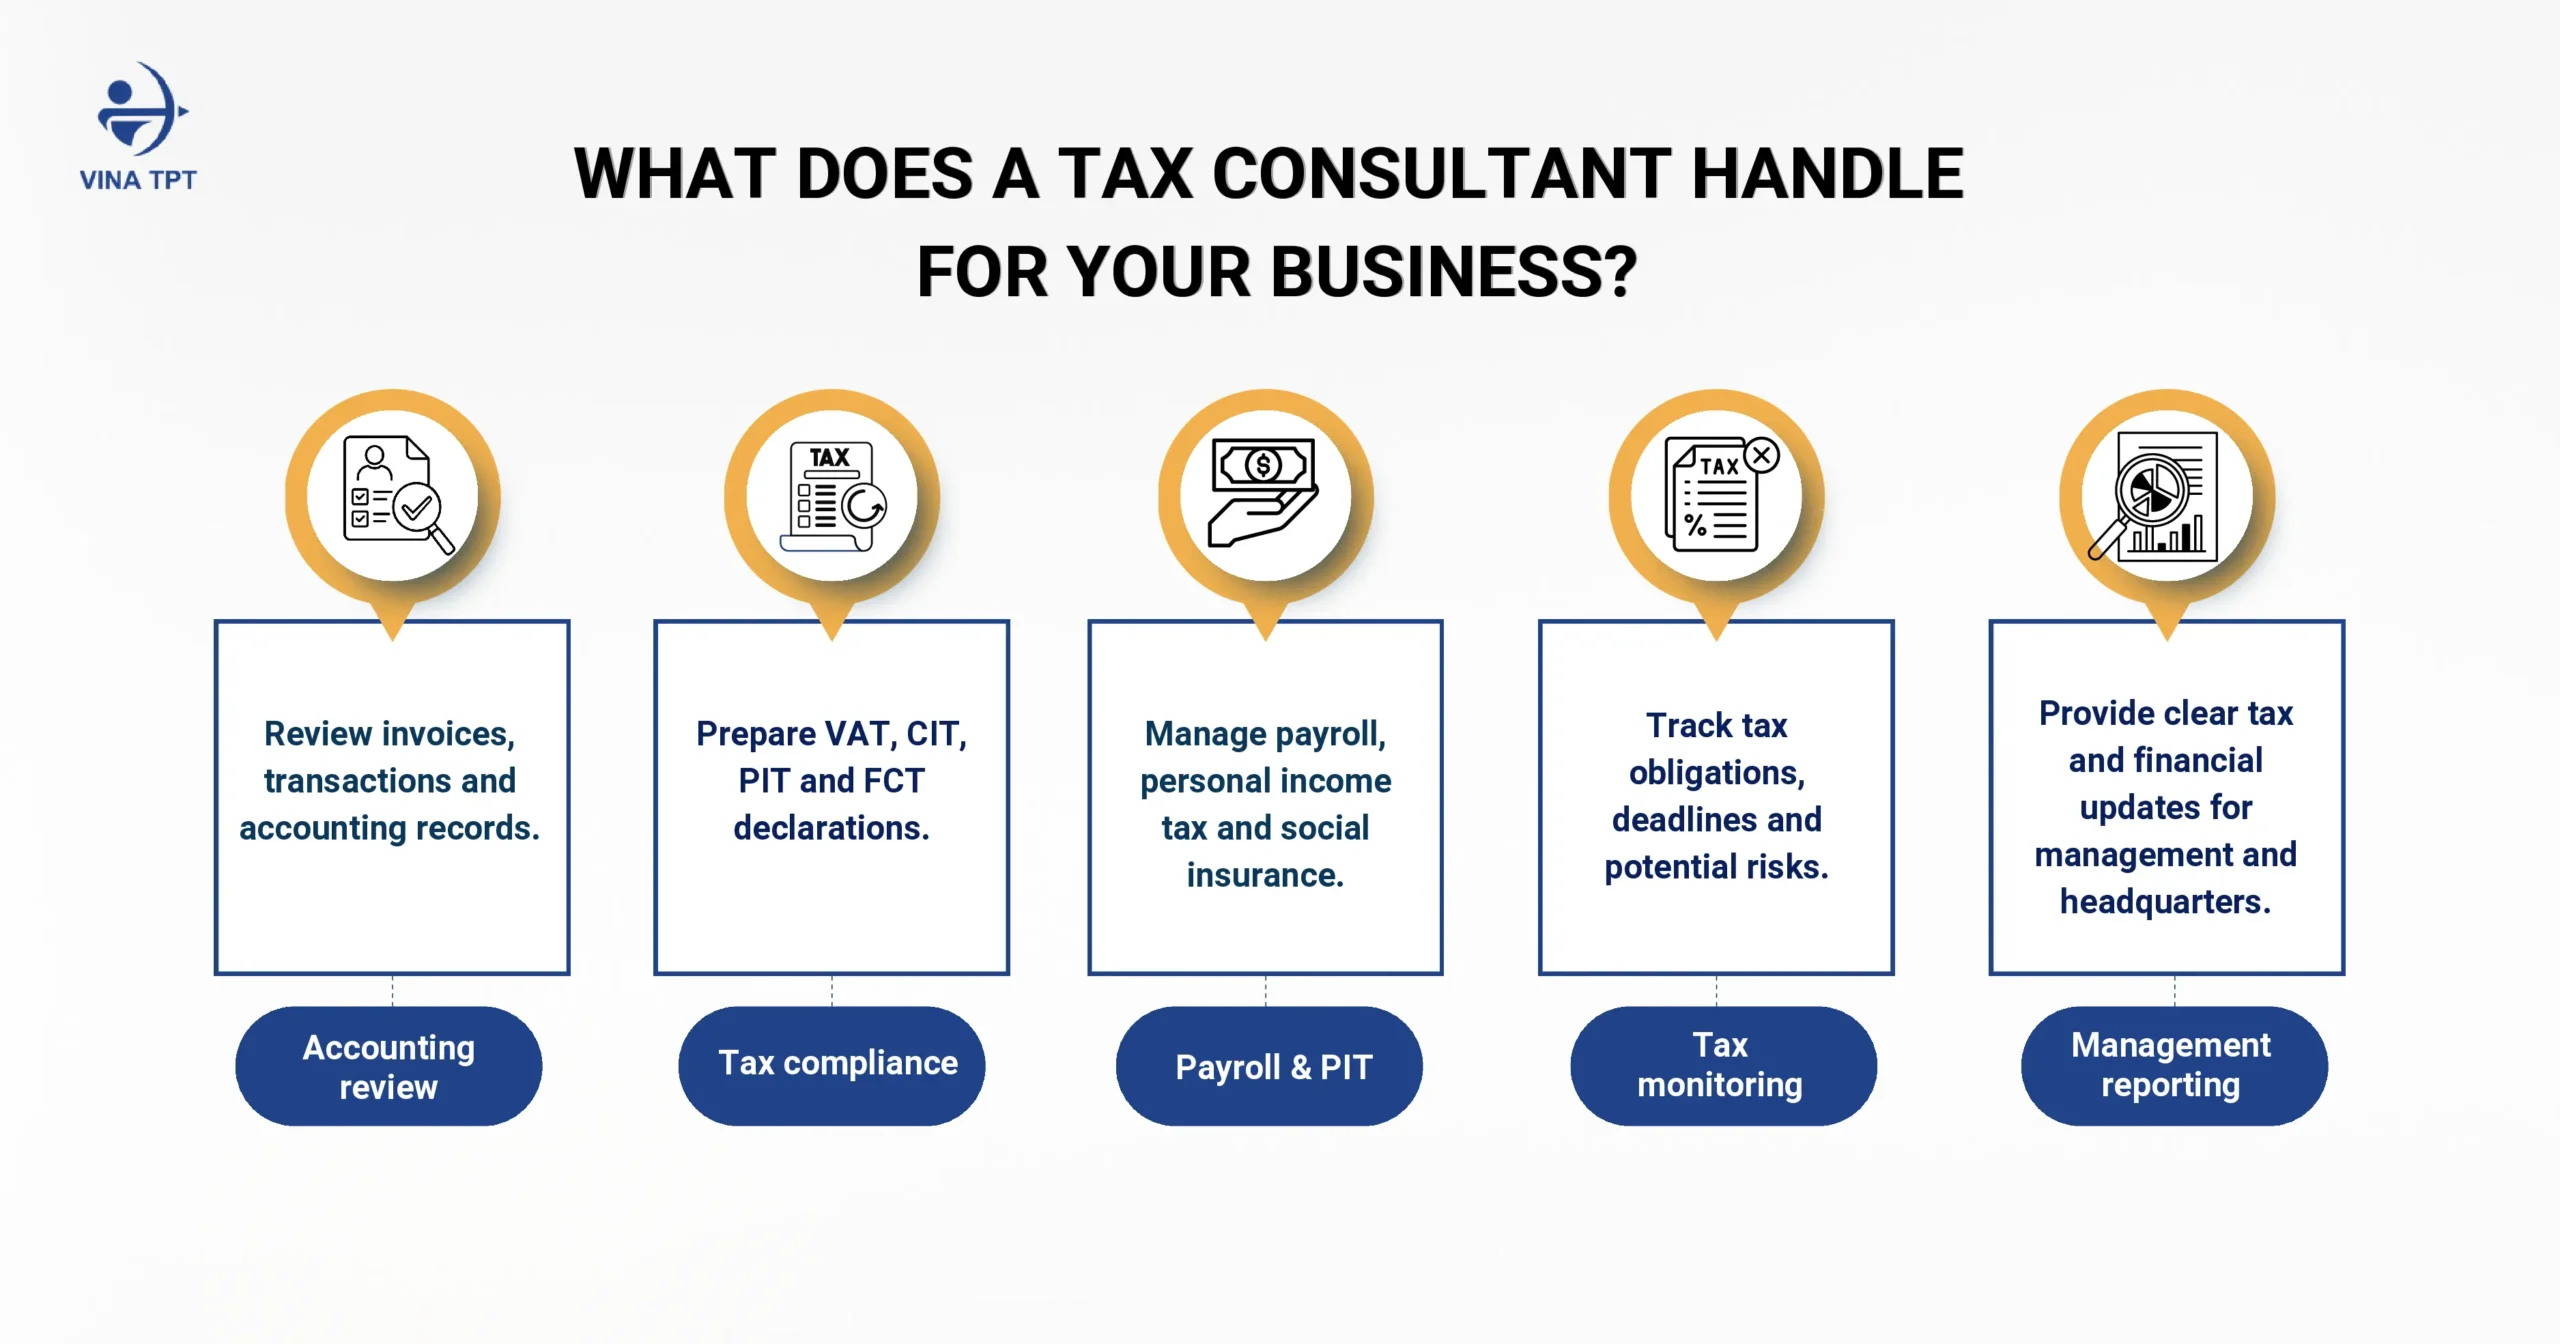
Below are the monthly and quarterly tasks that a professional tax advisory firm performs for FDI companies:

  • Document recording and e-invoice review: Receive all incoming and outgoing invoices and bank documents; review the legality, validity, and reasonableness of e-invoices on the General Department of Taxation portal to prevent risks from invoices issued by absconding or inactive companies.
  • Full identification of tax obligations arising in the period: Accurately assess the taxes the company must pay, including Value-Added Tax (VAT), Corporate Income Tax (CIT), Personal Income Tax (PIT), Foreign Contractor Tax (FCT), and the business license fee.
  • Preparation and on-time filing of tax returns: Build tax computation worksheets, prepare VAT and PIT returns on a monthly or quarterly basis, and file them through the e-tax portal before the statutory deadlines (the 20th of the following month or the last day of the first month of the following quarter), completely eliminating the risk of late-filing penalties.
  • Review of VAT deduction conditions and non-cash payment rules: Strictly check input VAT deduction conditions, especially the mandatory bank-transfer requirement for invoices of VND 5 million or more, and verify valid bank payment evidence.
  • Monitoring and balancing CIT provisional payments: Provisionally calculate actual quarterly profit to determine the CIT amount payable in advance, ensuring that the total provisional CIT paid over four quarters is not lower than 80% of the CIT payable on the annual finalization, thereby avoiding late-payment interest.
  • Monitoring of Foreign Contractor Tax (FCT): Declare and pay FCT promptly whenever outbound payments arise to international suppliers (software royalties, consulting fees, commercial commissions, foreign loan interest, etc.), preventing reassessment risk from omitted transactions.
  • Consolidated reporting for the Board of Directors and Headquarters: Prepare tax-obligation summaries and management reports in English and Vietnamese so that management in Vietnam and the overseas parent company can easily track cash flow and compliance status.

Vina TPT’s professional view: A full-package tax compliance service must deliver three core elements: clean accounting books + accurate tax returns + figures that reconcile between accounting and tax. If any one of these is missing, the tax position will be off even if the company still “files on time.”

2. When You Need Deeper Tax Consultant Support

Monthly filing work only keeps the company on the correct administrative rhythm. The actual operations of FDI companies regularly give rise to complex matters that require in-depth tax advisory Vietnam capability:

  • VAT refund consulting and implementation: For FDI companies with new investment projects or export businesses, the amount of undeducted input VAT is often substantial. A tax consultant Vietnam will review the entire legal dossier, the validity of invoices, export contracts, and bank payment evidence, then file the application and explain it directly to the Tax Authority in order to recover the refund into the company’s account.
  • Tax Health Check: A full review of the accounting books, tax returns, and supporting documents of prior financial years. This work helps the company proactively detect errors, non-deductible expenses, or potential violations before a tax inspection, fundraising, M&A, or share transfer takes place.
  • Inspection dossier preparation and representation before the Tax Authority: When a tax inspection or audit decision is issued, the advisor helps collect documents and prepare detailed explanations of sensitive expense items (entertainment, expatriate costs, foreign-exchange differences, etc.) in order to protect reasonable expenses as far as possible and minimize reassessment risk.
  • Related-party transaction management and Transfer Pricing (TP) documentation: Most FDI companies have transactions with the parent company or other related parties. The tax advisor is responsible for identifying the scope of related-party transactions, preparing the related-party transaction appendix attached to the CIT finalization return, and building the Transfer Pricing documentation set (Local File and Master File) in strict compliance with Decree 132/2020/NĐ-CP.

what-does-a-tax-consultant-in-vietnam-actually-do

3. When Does an FDI Company Need a Tax Consultant?

An FDI company should proactively look for a professional tax advisory partner when it falls into one of the following situations:

  • Newly established FDI company: It does not yet have a dedicated accounting and tax team that fully understands the Vietnamese legal system and needs to set up the initial books and compliance processes correctly.
  • Need for a VAT refund: It wants to shorten the refund timeline and ensure that the input dossier meets the Tax Authority’s inspection standards so that cash can be released sooner.
  • Related-party transactions: It needs advice on preparing Transfer Pricing documentation to the required standard in order to avoid the risk of the Tax Authority imposing prices and assessing additional CIT.
  • Change in capital structure or business model: It needs advice on the tax obligations arising from a capital transfer, asset transfer, or corporate restructuring.
  • Several years of operation without a proper tax finalization review: It is not certain that prior periods were fully compliant and needs a Tax Health Check to address risks proactively before an inspection decision is issued.

Explore Vina TPT’s Tax Consultant Support Services

4. What to Look for When Choosing a Tax Consultant in Vietnam

When selecting a tax compliance Vietnam partner, the Board of Directors should assess the following practical capability criteria:

  • Hands-on experience with FDI clients: A deep understanding of the relationship between VAS and IFRS, a firm grasp of Vietnamese tax regulations, and familiarity with the reporting culture of multinational groups.
  • Valid practicing certificates: Both the firm and its staff must hold the Certificate of Practice in Tax Procedure Services and the Accountant / Chief Accountant certificate as required by law.
  • Multi-level quality control (QC): Accounting data and tax returns must pass through at least two to three review layers (Specialist → Team Leader → Chief Accountant / Tax Director) before official filing.
  • Multilingual communication and reporting: The ability to advise and prepare management reports clearly in English and Vietnamese, enabling Headquarters to monitor compliance with ease.
  • Transparent service contract: A clear scope among monthly filing work, in-depth advisory, inspection support, and Transfer Pricing documentation.
  • Integrated payroll and accounting: Seamless connection between payroll processing and tax filing so that financial data remains consistent and no discrepancies arise at year-end finalization.

5. How Vina TPT Works as a Tax Consultant for FDI Companies

As a specialist advisory firm in finance, accounting, and tax for foreign-invested enterprises in Vietnam, Vina TPT delivers a two-layer tax advisory solution that helps companies optimize costs and control risk comprehensively.

The service areas Vina TPT implements for FDI companies include:

  • Recurring work: Full-package filing of VAT, CIT, PIT, and FCT; review of the legality of incoming documents; bookkeeping under VAS; payroll administration; and provision of a Chief Accountant.
  • Specialized work: Preparation of VAT refund dossiers; Tax Health Checks of prior-year books; preparation of inspection files and direct liaison during a tax inspection; and related-party transaction advisory and documentation.

Is your FDI company looking to review its current tax obligations in full, or do you need a reputable tax advisory partner for the long term? Contact Vina TPT today for a consultation on the most suitable service package – accurate, optimized, and free of unnecessary extra costs.

what-does-a-tax-consultant-in-vietnam-actually-do

BOOK A FREE CONSULTATION

30% CIT Reduction: New Tax Policy in Vietnam for 2026–2027 Tax Period

30% CIT Reduction for 2026 - 2027

30% CIT Reduction: New Tax Policy in Vietnam for 2026–2027 Tax Period 

Vietnam has introduced a new tax relief measure for the 2026 and 2027 tax periods under Resolution No. 43/2026/QH16. Eligible enterprises and organizations established under Vietnamese law with annual revenue of no more than VND 10 billion may receive a 30% reduction in corporate income tax (CIT) payable. 

The policy is intended to provide additional tax support for eligible businesses. However, the 30% reduction should not be confused with a 30% reduction in the statutory CIT rate. In practice, businesses need to determine their eligible CIT payable first, then apply the reduction in accordance with the applicable rules. 

What Does Resolution No. 43/2026/QH16 Say About the Tax Reduction? 

Resolution No. 43/2026/QH16 was issued by the National Assembly on 24 August 2026. The Resolution introduces tax reductions for both personal income tax (PIT) and corporate income tax (CIT) for the 2026 and 2027 tax periods as follows: 

“…

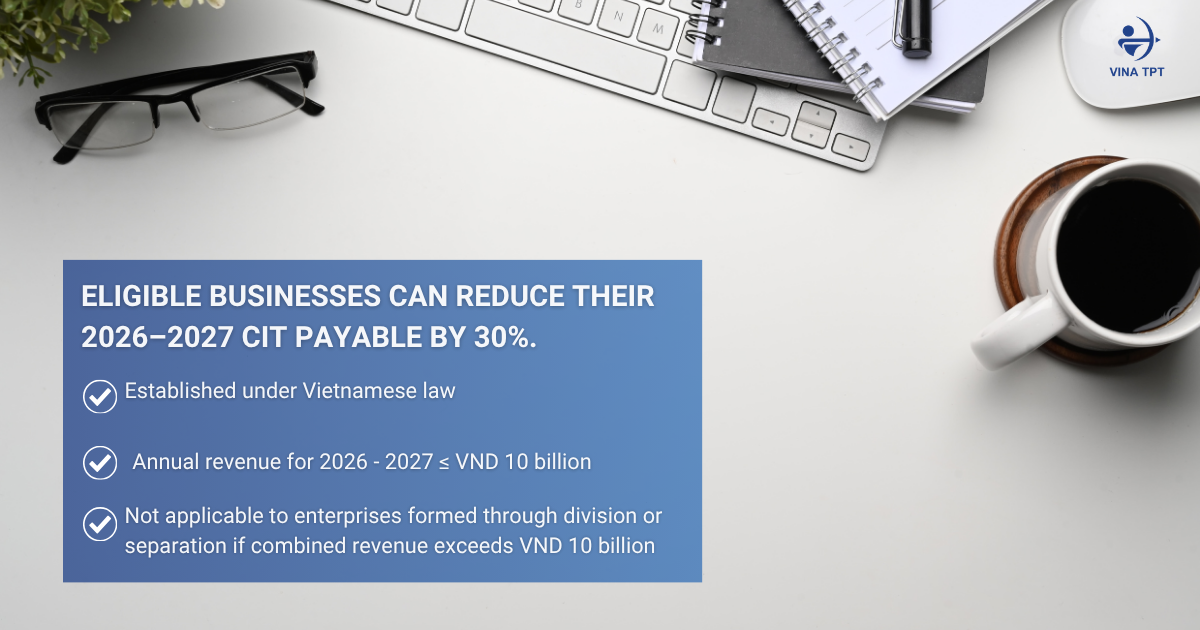
2. A 30% reduction in corporate income tax payable for the 2026 and 2027 tax periods shall apply to the income of enterprises and organizations established in accordance with Vietnamese law whose annual revenue in 2026 or 2027 does not exceed VND 10 billion. 

This reduction does not apply to enterprises established through the division or separation of an enterprise after the effective date of this Resolution, where the combined annual revenue of the enterprises resulting from such division or separation exceeds VND 10 billion in 2026 or 2027. 

In cases where an enterprise is already entitled to tax incentives under the Law on Corporate Income Tax or other laws or resolutions of the National Assembly, the corporate income tax reduction specified in this Clause shall be calculated based on the corporate income tax payable after deducting the applicable tax incentives.” 

30% CIT Reduction for Enterprises 

For CIT, eligible enterprises and organizations may receive a 30% reduction in CIT payable for the 2026 and 2027 tax periods if they are established under Vietnamese law and have annual revenue of no more than VND 10 billion in the relevant tax year. 

The reduction does not apply to enterprises formed through the division or separation of an existing enterprise after the Resolution takes effect if the combined annual revenue of the enterprises resulting from such division or separation exceeds VND 10 billion in the relevant year. 

For enterprises already benefiting from CIT incentives under the Law on Corporate Income Tax or other laws and resolutions of the National Assembly, the 30% reduction is calculated based on the CIT payable after the applicable tax incentives have been deducted. 

30% PIT Reduction for Business Individuals and Households 

Resolution 43 also provides a 30% reduction of PIT payable for the 2026 and 2027 tax periods for resident individuals earning business income whose annual revenue does not exceed VND 10 billion. 

Although the CIT and PIT provisions use a similar 30% reduction concept and a VND 10 billion revenue threshold, they apply to different taxpayers. 

Importantly, this 30% PIT reduction applies only to PIT arising from business income. It does not apply to PIT calculated on employment income, such as salary or wages received by individuals as employees. 

Eligible businesses can reduce their 2026–2027 CIT payable by 30%

What Is the Current CIT Rate in Vietnam? 

The 30% CIT reduction needs to be considered alongside the CIT rates currently applicable in Vietnam. 

Under the 2025 Law on Corporate Income Tax, the standard CIT rate is 20%, while 15% and 17% rates may apply to qualifying enterprises based on annual revenue and other statutory conditions. 

This makes it important to distinguish between two separate concepts: 

  1. CIT rate — the statutory rate used to calculate CIT liability. 
  2. 30% CIT reduction — a tax relief mechanism that reduces the resulting CIT payable for qualifying businesses. 

Reference: Updated 2025 | Corporate Income Tax Rates in Vietnam

Standard CIT Rate: 20% 

The general CIT rate under the 2025 Law on Corporate Income Tax is 20%, unless a different rate or preferential tax rate applies. 

For example:

If a company has VND 1 billion in taxable profit and the applicable CIT rate is 20%, its CIT payable before the reduction would be VND 200 million. And the company qualifies for the 30% CIT reduction under Resolution No. 43/2026/QH16, it would receive a reduction of VND 60 million (30% of VND 200 million) and would therefore pay VND 140 million in CIT.

=> In other words, the company effectively pays 70% of its applicable CIT liability. The statutory CIT rate, however, remains 20%; it is not reduced to 14%.

15% and 17% CIT Rates for Smaller Enterprises 

The 2025 Law on Corporate Income Tax introduced additional CIT rates for qualifying enterprises: 

Annual revenue condition  CIT rate 
No more than VND 3 billion  15% 
Over VND 3 billion to VND 50 billion  17% 
General rate  20% 

The law specifies that the revenue used to determine eligibility for the 15% and 17% rates is based on the total revenue of the immediately preceding CIT tax period, subject to the applicable rules. Certain types of income and enterprises are excluded from these reduced rates. 

Businesses should therefore avoid assuming that the VND 10 billion threshold under Resolution 43 and the thresholds for the 15% or 17% CIT rates operate in exactly the same way. 

Vina TPT – Accounting & Tax Services 

Vina TPT provides accounting, tax and business advisory support for companies operating in Vietnam, with experience supporting foreign-invested businesses and their ongoing compliance requirements. 

Our services cover accounting records, periodic tax declarations, CIT, VAT, PIT, foreign contractor tax, payroll and other tax-related compliance matters. 

For businesses reviewing their tax position for the 2026–2027 tax periods, our team can support the review of applicable CIT rules, tax incentives and compliance requirements based on the company’s specific circumstances. 

Need support with accounting and tax compliance in Vietnam? Contact Vina TPT to discuss your requirements. 

BOOK A FREE CONSULTATION


Vietnam Tax Updates August 2026: Key VAT, CIT, PIT, Foreign Contractor Tax, Tax Administration Changes

 vietnam-tax-updates-august-2026-cit-vat

Vietnam Tax Updates August 2026: Key VAT, CIT, PIT, Foreign Contractor Tax, Tax Administration Changes

Vietnam’s tax landscape continues to evolve, with several important changes and clarifications taking effect or being introduced in August 2026. This month’s updates cover key developments in Value Added Tax (VAT), Corporate Income Tax (CIT), Personal Income Tax (PIT), Foreign Contractor Tax (FCT), and tax administration.

Businesses and foreign-invested enterprises operating in Vietnam should pay close attention to these changes to stay compliant, avoid potential tax risks, and ensure timely adjustments to their tax and accounting practices.

New provisions regarding the tax period for newly established taxpayers and VAT refund applications for goods and services subject to the 5% VAT rate.

1. Tax calculation period for newly operating taxpayers

– According to Circular 89/2026/TT-BTC, updated and amended in Official Letter No. 5746/CT-CS dated August 10, 2026, newly established enterprises are allowed to default to quarterly VAT declarations. However, if the enterprise’s revenue in its first calendar year exceeds VND 50 billion (even if the enterprise has operated for less than 12 months in that financial year), it must mandatorily switch to monthly VAT declarations starting from the immediate next calendar year.

2. VAT Refund Dossier for Goods and Services subject to the 5% VAT rate

– New regulations govern the components of the input VAT refund application dossier for manufacturing goods and supplying services subject to the preferential 5% VAT rate. Accordingly, starting from the July 2026 tax period, taxpayers are required to declare the VAT refund claim directly on the VAT Return (Form No. 01/GTGT) and submit together with the Appendix on VAT Refund Claim Information (Form No. 01-8/GTGT) as the basis for the tax authority to review and process the refund request.

30% CIT Reduction for Tax Periods 2026 and 2027

According to the Resolution of the National Assembly on CIT reductions voted and approved on the afternoon of August 24, 2026, at the First Extraordinary Session of the 16th National Assembly

– A 30% reduction of CIT payable is granted to enterprises and organizations legally established under Vietnamese law with an annual total revenue of no more than VND 10 billion for the 2026 and 2027 tax periods. For enterprises currently enjoying other CIT incentives, the reduced tax amount will be calculated based on the actual CIT payable after deducting those existing tax incentives. For enterprises currently enjoying other CIT incentives, the reduced tax amount will be calculated based on the actual CIT payable after deducting those existing tax incentives. This Resolution takes effect from August 24, 2026, and applies directly to the tax periods of 2026 and 2027.

30% reduction of PIT payable for the tax periods of 2026 and 2027 for business individuals

Pursuant to Official Letter No. 7299/CTH-QLDN1 dated August 17, 2026 guiding the implementation of Decree No. 253/2026/NĐ-CP and the new PIT Law

30% reduction of PIT payable for the tax periods of 2026 and 2027 for business individuals

– Implementing a 30% reduction of PIT payable on income arising from production and business activities of resident individuals (including business households and individual businesses) with an annual revenue of no more than VND 10 billion.

Some Key Updates to Tax Administration Regulations

According to Circular 89/2026/TT-BTC updated in Official Letter 5746/CT-CS (August 10, 2026) and several new points in Circular 94/2026/TT-BTC

1. Shortening the time limit for tax payment extensions and late payment interest waivers

– The maximum time limit for tax authorities to assess and resolve dossiers requesting tax payment extensions, penalty waivers, or late payment interest waivers for enterprises is shortened from 10 working days to 07 working days.

2. Prioritizing tax refunds for highly compliant enterprises

According to the guidance in Circular No. 94/2026/TT-BTC on tax risk management, applying 3 risk levels: High risk, Medium risk, and Low risk

– High Risk: For taxpayers with high-risk tax refund dossiers, physical inspection at headquarters will be increased, with a mandatory “inspect first, refund later” approach applied to VAT, and post-refund audits conducted within 1 year.

– Medium Risk: For taxpayers with medium-risk tax refund dossiers: Within 03 years from the date of issuance of the refund decision, tax authorities will apply the “refund first, inspect later” method.

– Low Risk: For taxpayers with low-risk tax refund dossiers: Within 05 years from the date of issuance of the refund decision, tax authorities will apply the “refund first, inspect later” method.

3. General regulations on tax filing, calculation, and allocation

– Pending address changes: In case the tax filing deadline is due but the taxpayer has not completed procedures to change the headquarters address with the business registration authority or the tax office of the destination, the taxpayer must submit tax filing to the tax office of the departure location.

– Incorrect allocation: In case audits find that the taxpayer declared or allocated incorrectly, the directly managing tax authority will re-determine the amount to be allocated to the recipient provinces and handle administrative violations as prescribed (if any).

– No late payment interest on incorrect allocation: In case the taxpayer pays fully and on time but to the incorrect allocation area, the taxpayer will not have to pay late payment interest for the underpaid tax amount in the receiving allocation area. The directly managing tax authority will guide the taxpayer on performing a tax review or a refund-cum-offset procedure to adjust the revenue to the correct jurisdiction.

Amendment to the Tax Finalization Requirements upon Completion of a Foreign Contractor Agreement

Pursuant to Official Letter No. 5746/CT-CS dated August 10, 2026

VAT and CIT Tax Filing for Foreign Contractors and Foreign Subcontractors

– Amendments to the tax filing regulations for cases where Corporate Income Tax is calculated as a percentage of taxable revenue. Under the revised regulations, taxpayers are only required to submit a final tax declaration upon completion of a foreign contractor contract if there is a change (increase or decrease) in the amount of tax previously declared and paid.

– This completely abolishes the mandatory finalization obligation in all cases as previously required, and eliminates a series of accompanying documents such as Copies of the business registration certificate or professional practice license, a schedule of tax payment vouchers, the contract liquidation report, and appendices detailing the allocation of VAT payable by the foreign contractor to the localities entitled to receive the tax revenue.

Conclusion

The Vietnam Tax Updates August 2026 bring important changes and clarifications across VAT, CIT, PIT, Foreign Contractor Tax, and tax administration, including updates that may affect tax declarations, reporting obligations, and compliance procedures.

Businesses should review these changes carefully to understand how they may affect their tax compliance and reporting obligations, and make timely adjustments where necessary.

If you need assistance in interpreting these regulations or assessing their impact on your business, contact Vina TPT. Our accounting and tax professionals can provide practical guidance and support your business in maintaining compliance with Vietnam’s latest tax requirements.

BOOK A FREE CONSULTATION

How-to-Register-a-Company-in-Vietnam-Complete-Guide-to-IRC-and-ERC-for-Foreign-Investors

VAT Rate in Vietnam: Complete Guide to Value Added Tax Regulations

VAT Rate in Vietnam: Complete Guide to Value Added Tax Regulations

VAT Rate in Vietnam: Complete Guide to Value Added Tax Regulations

In corporate governance and financial compliance activities in Vietnam, accurately determining the VAT rate is not only a mandatory legal requirement but also a factor that directly influences pricing strategy, tax declaration efficiency, and cash flow circulation. Especially for foreign direct investment (FDI) enterprises, this tax requires the highest level of caution to minimize the risk of tax recovery or administrative penalties during operations.

Value Added Tax (VAT), or value added tax, is an important indirect tax that makes a major contribution to the state budget. It is calculated on the added value of goods and services arising throughout the entire process from production and distribution to consumption. To help enterprises gain a comprehensive understanding, this article compiles the latest regulations on the VAT rate Vietnam, provides a detailed analysis of the applicable tax rates in 2026, policy exemption and reduction cases, as well as core notes to help foreign investors ensure absolute legal compliance.

1. What is Value Added Tax (VAT) in Vietnam?

According to the Law on Value Added Tax of Vietnam, value added tax Vietnam is a tax applied to most types of goods and services used for production, business, and consumption purposes within the territory of Vietnam. The taxable objects cover a wide range, from domestic consumer goods to commercial services, excluding those items listed as non-taxable under specific provisions of the law.

Taxable subjects are defined as all organizations and individuals engaged in the production or trading of goods and services subject to VAT, or entities that import goods from abroad into Vietnam. From an economic management perspective, VAT not only ensures a stable and sustainable source of revenue for the national budget but also creates a transparent financial management mechanism through the invoice and supporting document system. A clear understanding of the nature of VAT will help foreign managers become more proactive in optimizing input costs and establishing standard compliance processes.

2. Current VAT Rates in Vietnam

The legal framework on the VAT rate Vietnam in 2026 categorizes goods and services into specialized tax rate groups in order to regulate the economy and support social welfare. The current system consists of three main tax rates along with a non-taxable group.

2.1. Standard Tax Rate of 10% and the Temporary Reduction Policy to 8% until the End of 2026

The 10% tax rate applies to most ordinary goods and services that fall outside preferential or export categories. However, to continue stimulating domestic consumption and supporting enterprises in production recovery, the Government has approved a temporary reduction of the VAT rate from 10% to 8%, which remains effective until 31 December 2026.

Enterprises should note that this 8% reduction policy does not apply universally across all sectors. Certain groups of goods and services are still required to apply the standard 10% rate, including:

  • Telecommunications services, financial activities, banking, securities, and insurance.
  • Real estate business and products from metals or mining products (excluding coal).
  • Goods subject to Special Consumption Tax (SCT) such as alcohol, beer, tobacco, and automobiles with fewer than 24 seats.

VAT Rate

Main Scope of Application

Practical Examples

8% (Until 31/12/2026) Ordinary consumer goods and services normally subject to 10% that are eligible for reduction. Consumer goods, food & beverage services, domestic logistics, processing manufacturing.
10% (Standard) Specific sectors not eligible for the VAT reduction. Telecommunications, banking, real estate, goods subject to Special Consumption Tax.
5% Essential goods and services, agriculture, healthcare, and education. Clean water, medical equipment, medicines, fertilizers, social housing.
0% Goods and services exported abroad or to non-tariff zones. Exported goods, international transportation, services provided to foreign partners.

2.2. Goods and Services Subject to 5% VAT Rate

The 5% tax rate is a preferential policy of the State applicable to groups of essential goods and services that serve people’s livelihoods, agricultural development, and social infrastructure. Common groups include:

Clean water used for production and daily living purposes (excluding bottled or containerized drinking water). Fertilizers, plant protection products, plant and animal growth stimulants. Medicines, vaccines, medical biological products, and specialized medical equipment and instruments. Teaching aids, educational materials, and specialized books. Certain agricultural, forestry, and aquatic products that have not been processed or have only undergone ordinary preliminary processing at the commercial trading stage, as well as social housing sale and lease projects as prescribed.

VAT Rate in Vietnam: Complete Guide to Value Added Tax Regulations

2.3. 0% VAT Rate and Exempt Cases

The 0% tax rate is designed to encourage export activities and enhance the competitiveness of Vietnamese products in the international market. The scope of application of the 0% rate includes goods exported abroad, goods sold into non-tariff zones for export production, international transportation services, and services provided directly to organizations and individuals overseas.

In addition, the law also specifies a list of VAT-exempt objects, such as self-produced agricultural products sold by the producers themselves, transfer of land use rights, credit services, securities, life insurance, and public healthcare and education services.

Core distinction between “0% Tax Rate” and “VAT-Exempt”:

  • 0% Tax Rate: The enterprise remains within the scope of VAT, and is therefore entitled to deduct and fully refund all input VAT paid on related production and business costs.
  • VAT-Exempt: The enterprise does not charge output VAT, but at the same time is not entitled to deduct or refund input VAT. This input tax must be included in production and business costs or the original cost of assets.

3. Key Compliance Requirements Related to VAT Rate
To maintain legal compliance and optimize the amount of deductible tax, enterprises must strictly comply with the current tax administration regulations:
Enterprises must fulfill their VAT declaration and payment obligations on a monthly or quarterly basis, depending on the total revenue of the immediately preceding year (enterprises with annual revenue of VND 50 billion or more are required to declare monthly). To be eligible for input VAT deduction, the enterprise must fully meet three mandatory conditions: possession of a valid VAT invoice; non-cash payment documents for invoices valued at VND 5 million or more (including tax); and the purchased goods or services must be used directly for the production or trading of goods and services subject to VAT.

In addition, the use of electronic invoices (with or without the tax authority’s code) is 100% mandatory. If an enterprise applies an incorrect VAT rate (for example, issuing an invoice at 8% for goods subject to the 10% rate), the enterprise will not only have to pay the underpaid tax and late payment interest but will also face serious administrative tax penalties.

EXPLORE TAX FILLING SERVICES

4. Practical Tips for Foreign Companies

To minimize financial errors when operating a business in Vietnam, foreign managers should keep the following practical experiences in mind:

Establish a process to accurately check and classify the enterprise’s goods and service categories right from the input stage. Because the 8% tax reduction policy contains many complex exceptions, the accounting department must carefully cross-check the economic industry codes and HS codes of the products to apply the correct tax rate.

Systematically store and organize all electronic invoices together with bank payment documents. This is the only legal basis that enables the enterprise to protect its rights to input VAT deduction and refund when the competent authorities conduct tax inspections or audits.

Proactively carry out periodic internal tax reviews (tax audits) of the tax declaration process to detect and correct errors in a timely manner before the Tax Authorities issue an inspection decision. In cases where the internal team does not have a deep understanding of the local tax legal system, the enterprise should consider cooperating with professional tax agency firms to ensure operational safety.

VAT Rate in Vietnam: Complete Guide to Value Added Tax Regulations

5. How Vina TPT Supports VAT Compliance
As a reputable firm specializing in financial consulting and tax compliance for FDI enterprises, Vina TPT provides comprehensive support solutions that help businesses optimize their VAT processes:
  • Tax Rate Consulting & Classification: Accurate assessment of product categories and advice on applying the correct VAT rate (clearly distinguishing between the 8%, 10%, 5%, and 0% groups).
  • Periodic Tax Declaration & Reporting: Preparation and submission of accurate monthly/quarterly VAT declarations in full compliance with statutory deadlines.
  • Input Deduction Review & Tax Refund Services: Appraisal of input invoice dossiers and representation of the enterprise in carrying out VAT refund procedures for investment projects and export activities.
  • Support During Tax Inspections: Direct explanation, protection of data, and safeguarding of the enterprise’s legitimate rights before the tax management authorities.

Conclusion

In summary, mastering the regulations on the VAT rate and accurately complying with the VAT declaration process is the golden key that enables FDI enterprises to operate safely, transparently, and sustainably in Vietnam.

Is your enterprise facing difficulties in determining the correct VAT rate or in need of professional tax declaration support? Contact Vina TPT today for a free consultation and experience our standard full-package accounting and tax services.

BOOK A FREE CONSULTATION

How Recent Vietnam Tax Reforms Impact FDI Business Accounting Requirements

vietnam-tax-reforms-impact-fdi-business-accounting

Vietnam business accounting and tax landscape is undergoing sweeping structural reforms between 2025 and 2026. Foreign Direct Investment (FDI) enterprises must align with five critical regulatory shifts: Decree 70/2025/ND-CP (e-invoicing rules), Circular 99/2025/TT-BTC (new accounting framework replacing Circular 200), the 2024 Value Added Tax (VAT) Law (effective July 1, 2025), the 2025 Corporate Income Tax (CIT) Law No. 67/2025/QH15, and the 2025 Personal Income Tax (PIT) Law. 

This guide examines the business impacts of Vietnam’s 2025–2026 tax and accounting reforms on foreign-invested firms under Vietnamese Accounting Standards (VAS).  

  • Key Overview: Recent Tax & Accounting Regulatory Reforms in Vietnam   
  • 5 Major Ways Tax Reforms Directly Affect FDI Business Accounting Requirements   
  • Comprehensive Business Accounting Services Tailored for FDI Enterprises 
  • Frequently Asked Questions 

Key Overview: Recent Accounting and Tax Regulatory Reforms in Vietnam 

The General Department of Taxation (GDT) and the Ministry of Finance (MOF) in Vietnam are rapidly accelerating digital tax administration, big-data cross-reconciliation, and international compliance integration. The modern regulatory environment leaves zero margin for record-keeping delays or bookkeeping discrepancies. 

For foreign-invested enterprises operating across Ho Chi Minh City (TPHCM), Hanoi, and key industrial zones, tax and accounting compliance is no longer a passive administrative routine. Regulatory compliance directly influences cash flow timing, profit repatriation, transfer pricing audit exposure, and corporate reputation. Understanding the full scope of informational and navigational requirements across legislative mandates is essential for maintaining tax health and operational continuity in Vietnam. 

Timeline of Critical Accounting and Tax Changes (2025–2026) 

  • 01/06/2025 — Decree 70/2025/ND-CP: Amends e-invoice regulations, enforcement mechanisms, data submission timing, and mandatory invoice contents. Introduces strict cut-offs for customs-linked transaction recording. 
  • 01/07/2025 — Law on VAT 2024 (Law No. 48/2024/QH15): Officially comes into force, tightening input VAT deduction criteria, mandating non-cash payment verification, and restricting VAT refund eligibility for export-import and investment projects. 
  • 01/10/2025 — Law on CIT 2025 (Law No. 67/2025/QH15): Takes effect for the 2025 tax year onwards, overhauling deductible expense conditions, related-party transaction controls, and foreign enterprise taxation rules. 
  • 01/01/2026 — Circular 99/2025/TT-BTC: Enforces a modernized accounting system replacing the decades-old Circular 200/2014/TT-BTC framework, altering chart of accounts, foreign exchange treatments, and financial statement presentations. 
  • 01/07/2026 — Law on Personal Income Tax 2025: Officially applies to individual income tax calculations, streamlining tax brackets and adjusting personal and dependent relief thresholds. 

5 Ways Accounting & Tax Reforms Impact FDI Business Accounting Requirements 

The convergence of these regulatory updates shifts tax compliance from periodic reporting to real-time verification. For FDI enterprises operating in Vietnam, structural mismatches between accounting entries, bank settlement records, customs declarations, and tax filings will automatically trigger tax authority risk alerts.

Decree 70/2025/ND-CP: Stricter E-Invoice and Transaction Recording Requirements

Decree 70/2025/ND-CP fundamentally alters the operational rules governing e-invoice generation, content accuracy, and timing. One of the most vital changes for export-oriented FDI companies is the strict requirement that e-invoices for exported goods must be issued no later than the next working day after customs clearance completion. 

Furthermore, Decree 70/2025 clarifies e-invoice requirements for cross-border digital services, software licenses, and complex intercompany transactions requiring multi-system data reconciliation. Accounting teams can no longer delay issuing invoices until month-end or quarter-end closing. Sales recognition, invoice logs, customs clearance timestamps, and tax declaration periods must be tightly aligned to avoid severe timing mismatch penalties. 

Expert Insight (Decree 70/2025): 

This is far more than an administrative “e-invoice compliance” task. For FDI enterprises engaged in import/export or cross-border intercompany service charges, an incorrect invoice issuance date directly disrupts revenue recognition timing under VAS/IFRS and invalidates 0% export VAT treatment during tax audits. 

Circular 99/2025/TT-BTC: New Accounting and Financial Reporting Requirements

Effective from January 1, 2026, Circular 99/2025/TT-BTC officially replaces the long-standing Circular 200 accounting regime. This represents the most comprehensive accounting overhaul in Vietnam over the past decade, introducing updated rules for accounting vouchers, the statutory chart of accounts, general ledger posting routines, foreign-exchange difference treatments, and year-end financial statement disclosures. 

Foreign-invested companies operating in Vietnam must systematically update their ERP systems (e.g., SAP, Oracle, Microsoft Dynamics) and local chart-of-accounts mapping. Simply rolling forward previous bookkeeping setups will result in non-compliant statutory financial statements, blocking profit remittance approvals from the State Bank of Vietnam (SBV) and tax authorities. 

Expert Insight (Circular 99/2025): 

Circular 99 is the cornerstone change for business accounting services. It directly dictates how transactions are recorded, books are closed, and statutory financial statements are compiled. FDI management must conduct an immediate ERP chart-of-accounts gap analysis prior to the 2026 fiscal year. 

EXPLORE ACCOUNTING SERVICES FOR FDI BUSINESS

2025 Personal Income Tax Law: Major Changes to Payroll Tax Calculations

Beginning in the 2026 tax assessment year, Vietnam’s Personal Income Tax system transitions from seven progressive tax brackets down to five streamlined tax brackets. Simultaneously, the personal deduction allowance increases to VND 15.5 million per month (VND 186 million annually), and the dependent allowance increases to VND 6.2 million per month per dependent. 

FDI employers employing expatriates, key foreign executives, and high-earning local personnel must reconfigure their HR payroll engine, employee tax profiles, dependent documentation archives, and monthly tax withholding logic. Given that expatriate compensation often involves gross-up packages, housing allowances, and school fee benefits, accurate PIT withholding calculations are vital to control corporate payroll costs. 

Expert Insight (2025 PIT Law): 

With foreign experts and senior management earning high income packages, the shift in progressive tax brackets directly recalibrates net compensation, tax gross-up expenses, and monthly corporate cash flow projections. Payroll accounting must be seamlessly integrated with corporate tax compliance. 

2025 Corporate Income Tax Law: Greater Focus on Taxable Income and Deductible Expenses

The 2025 Corporate Income Tax Law (No. 67/2025/QH15), effective October 1, 2025 and applicable to the 2025 tax year, establishes stringent conditions for deductible expenses, taxable income determination, tax incentive eligibility criteria, and foreign contractor income taxation. Foreign-invested businesses face heightened documentation standards for intercompany management fees, technical consulting services, trademark royalties, and interest deductions under transfer pricing rules (Decree 132/2020/ND-CP framework). 

Accounting teams must establish robust internal controls to substantiate economic substance, benefit tests, and direct transfer pricing documentation for all related-party transactions prior to year-end tax finalization. 

Expert Insight (2025 CIT Law): 

For FDI companies, CIT compliance extends far beyond multiplying accounting profit by 20%. The core challenge lies in proving that overseas parent company charges—such as regional management fees, IT allocations, and royalty fees—are fully deductible under Vietnamese tax rules with adequate supporting dossier proof. 

2025 Value Added Tax Law: Stricter Input VAT Deduction and Payment Controls

Enforced from July 1, 2025, the 2024 VAT Law drastically tightens input VAT deduction rules. Most notably, the statutory threshold for mandatory non-cash payment documentation is reduced from VND 20 million down to VND 5 million (VAT-inclusive) for any purchase transaction. Furthermore, transaction aggregation rules prevent split-invoicing tactics designed to bypass bank transfer requirements. 

Under these stricter rules, tax officers will automatically disallow input VAT deductions and corresponding CIT expense deductions if payment records fail to match the official corporate bank account of the issuing vendor. 

Expert Insight (2025 VAT Law): 

In daily accounting practice, accountants cannot merely verify whether an e-invoice is authentic on the GDT portal. They must perform a 3-way match: valid e-invoice + compliant non-cash payment proof + transaction contract/delivery note. Any flaw in payment evidence will trigger input VAT clawbacks and tax interest penalties. 

Vina TPT: Comprehensive Business Accounting Services Tailored for FDI Enterprises 

Vina TPT is a premier business consultancy and accounting firm operating in Ho Chi Minh City (TPHCM) and key economic hubs across Vietnam. We specialize in empowering Foreign Direct Investment (FDI) companies, foreign contractors, and multinational branches to navigate Vietnam’s complex regulatory environment with absolute financial clarity and 100% legal compliance.

Our tailored business accounting services bridge the critical gap between international financial management standards (IFRS/US GAAP) and mandatory Vietnamese statutory requirements (VAS, Circular 99/2025, GDT tax laws). 

Why Leading FDI Enterprises Choose Vina TPT: 

  • Full-Scope VAS & IFRS-Compliant Bookkeeping: Accurate monthly bookkeeping and statutory financial reporting under Vietnamese Accounting Standards (VAS) and IFRS upon request, delivered with comprehensive monthly management reports and dedicated bilingual accounting professionals. 
  • Periodic VAT Compliance & Filing: Complete preparation and timely filing of monthly or quarterly Value Added Tax (VAT) returns. 
  • Payroll Processing & Social Insurance Management: End-to-end payroll administration, precise salary calculations, gross-up tax modeling, and seamless handling of mandatory Social Insurance (SI/HI/UI) compliance and employee profiles. 
  • PIT Calculation & Periodic Tax Filing: Compliant Personal Income Tax (PIT) computation for both local and expatriate employees, dependent registrations, and preparation of periodic PIT declarations and annual tax finalizations. 
  • FDI Investment & Statutory Reporting: Timely preparation and submission of mandatory periodic investment activity reports to foreign investment authorities (MPI/DOIT), ensuring strict regulatory compliance for FDI projects. 
  • Back-Office & Document Administration: Comprehensive operational support including e-invoice issuance, systematic archiving of physical and digital accounting vouchers, and management of statutory business records. 
  • Proactive Tax Advisory & Regulatory Updates: Continuous monitoring and real-time updates on new tax and accounting regulations, backed by proactive advisory support to resolve operational queries and shield your business from compliance risks. 

Frequently Asked Questions (FAQ)

The 2025 CIT Law maintains tax incentives (e.g., 10-17% preferential tax rates, tax holidays, and 50% reduction periods) for targeted sectors like high-tech, green energy, and encouraged industrial zones. However, FDI firms must meet strict substance rules, investment capital disbursements, and accurate VAS accounting tracking under Circular 99 to retain these tax incentive benefits. 

FDI companies must submit monthly VAT and PIT returns by the 20th of the following month (or quarterly by the last day of the month following the quarter). Annual CIT finalization, PIT finalization, and audited financial statements prepared under VAS must be submitted within 90 days from the end of the fiscal year. 

No. All companies legally incorporated in Vietnam are strictly required to maintain statutory accounting records and submit tax returns in accordance with Vietnamese Accounting Standards (VAS) and Circular 99/2025/TT-BTC. While parent companies may request IFRS management reports, VAS remains the sole legal basis for local tax compliance and profit remittance. 

Need Professional Accounting & Tax Support for Your FDI Business? 

Contact Vina TPT today for a free consultation and customized solution tailored to your compliance needs! 

BOOK A FREE CONSULTATION

business-accounting-services


New Accounting and Tax Rules from July 2026: Important Notes for Compliance

new-accounting-and-tax-rules-from-july-2026-important-notes-for-compliance

new-accounting-and-tax-rules-from-july-2026-important-notes-for-compliance

1. From July 1, 2026, a series of important legal changes in the fields of accounting and tax officially take effect. The key focuses of this reform package include Decree 253/2026/ND-CP (guiding personal income tax), Circular 58/2026/TT-BTC (the new accounting regime), and the Tax Administration Law 2025 (Law on Tax Administration No. 108/2025/QH15).

For FDI enterprises, Accounting Departments, and Human Resources (HR) teams, these adjustments are not merely changes in administrative procedures. They directly impact payroll calculation processes, social insurance contributions, tax withholding, and the preparation of financial statements. Delays or inaccurate application of the new regulations can lead to declaration errors, administrative penalties, and strict inspections from the tax authorities.

This article summarizes the core new points together with practical notes to help businesses ensure tax compliance, proactively eliminate legal risks, and operate cash flow safely from the July 1, 2026 milestone.

5 Important Changes to Personal Income Tax under Decree 253/2026/ND-CP

Decree 253/2026/ND-CP introduces fundamental adjustments that directly affect personal income tax (PIT) obligations, which Accounting and Payroll departments must implement immediately:

1. Mid-shift / lunch meal allowance – tax-exempt up to VND 1.2 million per person per month

Pursuant to Point g, Clause 2, Article 8 of Decree 253/2026/ND-CP, from July 1, 2026, the tax exemption for mid-shift meal allowances is tightened under a fixed limit:

  • Cash payment: The mid-shift or lunch meal allowance paid in cash by the enterprise to employees is exempt from PIT up to a maximum of VND 1.2 million per person per month. Any amount exceeding this limit must be included in taxable income subject to PIT.
  • In-kind payment / meal vouchers: If the enterprise directly organizes a canteen, purchases industrial meal portions, or issues meal vouchers, the entire value of the meals is exempt from PIT, regardless of the form of payment.

Important note: The new regulation abolishes the previous principle that “whatever amount the enterprise stipulates in its internal regulations is exempt.” Accountants must review the company’s Financial Regulations and Labor Contracts to adjust payment norms to ensure compliance.

2. Increase in the 10% PIT withholding threshold to VND 5 million per payment

According to Clause 2, Article 50 of Decree 253/2026/ND-CP:

  • Organizations paying income are required to withhold 10% personal income tax (PIT) only when the payment reaches VND 5 million or more per time for individuals who have not signed a labor contract or have signed a labor contract of less than 3 months (replacing the previous threshold of VND 2 million per payment).
  • For payments below VND 5 million per time, the enterprise is not required to withhold the 10% tax, unless the individual specifically requests it.
  • Individuals who estimate that their total income after family deductions has not yet reached the taxable threshold may still submit a Commitment Letter to the enterprise to temporarily avoid the 10% withholding.

3. Salary and bonus payments to former employees still require 10% withholding

Decree 253/2026/ND-CP clarifies the withholding obligation for payments arising after the termination of the employment relationship. When an enterprise pays salary, bonuses, commissions, or other support amounts of VND 5 million or more per payment to former employees, the enterprise is required to withhold personal income tax (PIT) at the rate of 10%. Omitting this obligation will result in the enterprise being subject to additional tax assessments and late-payment penalties during the annual tax finalization.

4. Stricter deadline for registering dependents – before 31 December

Pursuant to Clause 2, Article 48 of Decree 253/2026/ND-CP, registration for family circumstance deductions for dependents must be completed before 31 December of the tax year. If the registration dossier is submitted after this deadline, the employee will not be entitled to the family circumstance deduction for that tax year, directly affecting the individual’s tax finalization benefits.

5. 100% tax exemption on overtime and night-shift pay

According to Article 26 of Decree 253/2026/ND-CP:

  • Enterprises are exempt from personal income tax (PIT) on the entire amount of overtime pay and night-shift pay, provided the conditions under the Labor Code are fully met (replacing the previous rule that only exempted the differential portion compared with normal working-day pay).
  • Conditions for application: The enterprise must maintain complete supporting documentation (night-shift/overtime timesheets, payroll calculations, and overtime assignment documents).
  • Effective date: Applicable from 1 January 2026 for resident individuals and from 1 July 2026 for non-resident individuals.

new-accounting-and-tax-rules-from-july-2026-important-notes-for-compliance

Circular 58/2026/TT-BTC: New Accounting Regime for Micro-Enterprises

In addition to tax regulations, the accounting and tax regime from July 1, 2026, marks an important change with the Ministry of Finance’s issuance of Circular 58/2026/TT-BTC (completely replacing Circular 132/2018/TT-BTC).

Circular 58/2026/TT-BTC provides detailed guidance on accounting documents, accounting books, and the preparation and presentation of financial statements for micro-enterprises, helping to simplify the accounting apparatus while still ensuring legal transparency.

Criteria for identifying a Micro-Enterprise (under Decree 80/2021/ND-CP):

  • Agriculture – Forestry – Fishery, Industry & Construction sectors: Average number of employees participating in social insurance per year does not exceed 10 people AND total annual revenue does not exceed VND 3 billion (or total capital does not exceed VND 3 billion).
  • Trade & Services sectors: Average number of employees participating in social insurance per year does not exceed 10 people AND total annual revenue does not exceed VND 10 billion (or total capital does not exceed VND 3 billion).
  • Flexible choice of accounting regime:

Micro-enterprises have the right to choose to apply the Accounting Regime for Small and Medium-sized Enterprises (Circular 133/2016/TT-BTC) if it better suits their management needs. However, the chosen accounting regime must be applied consistently throughout an entire financial year; any change of regime may only be made at the beginning of the following accounting year.

  • Financial Statement System for Micro-Enterprises:

Micro-enterprises that pay corporate income tax using the method based on taxable income must prepare annual financial statements in accordance with the guidance in Circular 58/2026/TT-BTC, including:

  • Statement of Financial Position (Form B01 – DNSN).
  • Income Statement (Form B02 – DNSN).

Key Points to Note under the Tax Administration Law 2025

The Tax Administration Law 2025 (Law on Tax Administration No. 108/2025/QH15, promulgated on 10 December 2025) takes effect from 1 July 2026. It introduces stricter sanctions to strengthen declaration discipline and enhance the transparency of electronic invoice data.

Shortening of the time limit for supplementary tax declaration dossiers to 5 years

One of the core changes that Accounting teams must particularly note under Clause 5, Article 12 of the Tax Administration Law 2025 is: The time limit allowing taxpayers to self-detect errors and submit supplementary declaration dossiers has been shortened from 10 years to 5 years, counted from the deadline for submitting the tax declaration dossier of the tax period containing the error.

Taxpayers may perform supplementary declarations within the 5-year period in the following cases:

  1. The supplementary declaration is made before the tax authority or competent authority issues a Decision on tax inspection or examination at the taxpayer’s premises.
  2. The supplementary tax declaration dossier does not fall within the scope and period of the inspection stated in the Inspection Decision.
  3. The dossier is not related to a case in which the investigating authority has requested that the status quo be maintained to serve a criminal investigation.

Risk warning: Shortening the adjustment period to 5 years requires enterprises to strengthen annual internal audits of accounting books, rather than allowing errors to accumulate over a longer period as in the past.

new-accounting-and-tax-rules-from-july-2026-important-notes-for-compliance

Immediate Actions FDI Enterprises Need to Take for Compliance

To maintain absolute tax compliance and optimize operating costs under the new regulations effective from 1 July 2026, FDI enterprises should immediately implement the following actions:

  • Review Salary & Benefit Policies: Adjust the mid-shift meal allowance (cap at VND 1.2 million per month if paid in cash) and the regulations on overtime and night-shift pay within the payroll software system.
  • Update the 10% Tax Withholding Process: Configure the accounting system to apply the new 10% withholding threshold for payments of VND 5 million or more per time to casual workers and former employees.
  • Accelerate Standardization of Dependents: Urge employees to complete supporting documents and submit family circumstance deduction registrations before 31 December.
  • Check the Synchronization of Accounting & Tax Data: Review the consistency between sales software, the electronic invoice system, and VAT/CIT tax declarations.
  • Update Enterprise Information: Review the head office address, lease agreements, and legal representative information on the enterprise registration portal to avoid being classified by the tax authorities as a “high-risk taxpayer.”

Conclusion

The legal changes in accounting and tax effective from 1 July 2026 present a challenge of rapid adaptation for Accounting and HR teams. Proactively reviewing accounting processes, updating new tax policies, and controlling electronic invoice data are the keys that help FDI enterprises operate safely, transparently, and sustainably in Vietnam.

The entire adjustment process must be carried out rigorously to maximize benefits for employees and protect the enterprise against tax inspections.

Follow the News & Insight & News section of Vina TPT for continuous updates on the latest in-depth analyses of Accounting and Tax policies in Vietnam.

BOOK A FREE CONSULTATION