Outsource Bookkeeping & Accounting for Singaporean Logistics Firms in Vietnam

Outsource Bookkeeping & Accounting for Singaporean Logistics Firms in Vietnam-VTPT

Outsource Bookkeeping & Accounting for Singaporean Logistics Firms in Vietnam-VTPT

1. The Financial Pulse of Every Logistics Company

In the world of logistics, everything revolves around numbers – from shipping costs, fuel costs to payments to suppliers. For Singaporean companies expanding operations in Vietnam, each month is a separate “financial cycle”. If a business is like a living body, monthly accounting is the “heartbeat” that keeps the system running smoothly. 

Recording, summarizing and reporting monthly financial information helps management understand the spending, revenue, and profit situation of each transportation route or each warehouse. Thanks to this data, businesses can quickly detect problems, for example, a certain route has an unusual increase in fuel costs, or a partner is late in paying and make adjustments within the month instead of waiting until the end of the fiscal year.

2. Inside a Typical Monthly Accounting Cycle

To put this into perspective, imagine a monthly accounting cycle in the logistics industry that starts with recording each bill of lading each shipment, each delivery becomes a financial data stream. The accounting department then reconciles it with the invoice from the transport provider, fuel payments, tolls, or warehousing costs.

In addition, the business must also take inventory of the inventory in the transit warehouse, calculate the loss and depreciation of the transport vehicles. Once all the data has been updated, the final step is to compile the monthly financial report including revenue, expenses, and profits.

A professional accounting bookkeeping service will take care of this entire process, ensuring that all the numbers are accurate, transparent, and updated promptly. This is especially important for companies with operations spread between Singapore and Vietnam, where small discrepancies in data can affect the entire reporting system.

GET A CUSTOMIZED ACCOUNTING SOLUTION

3. Why Outsource Bookkeeping Is Becoming a Strategic Move

In recent years, more and more Singapore logistics businesses have chosen to outsource bookkeeping instead of maintaining an in-house accounting team. The reason lies not only in saving on personnel costs, but also in accuracy and speed.

When outsourcing accounting services, businesses are supported by experienced specialists and modern software systems, allowing access to real-time data (real-time reporting). Managers in Singapore can immediately view the financial reports of the Vietnam branch at any time, without having to wait for manual file submission.

In addition, outsourced accounting services help increase cross-border transparency. All data is managed according to the same standards, avoiding discrepancies between countries. This not only helps the board of directors make decisions faster, but also minimizes risks in auditing and tax reporting.

4. Key Data Reports That Drive Logistics Decisions

In the logistics industry, financial data is not just a record but also a “compass” for all operational decisions. When properly compiled, monthly accounting reports become an “insight hub” that helps management see the big picture.

For example, an operating cost report might show that a shipping route from Ho Chi Minh City to Singapore is consuming more fuel than usual. A revenue report by route might show that domestic shipping is generating higher profit margins than international shipping. Or a profit report by partner helps managers see which partners are contributing the most to overall revenue.

Thanks to periodic reports, Singaporean investors no longer have to wait for annual audits to know the business situation. They can make quick decisions, reallocate resources, or adjust transportation strategies in just a few days, something that used to take months.

Download Vietnam Tax Handbook For Investor

Outsource Bookkeeping & Accounting for Singaporean Logistics Firms in Vietnam-VTPT

5. Compliance with Vietnamese Accounting Standards (VAS)

For foreign-invested logistics companies, especially those from Singapore, compliance with Vietnamese Accounting Standards (VAS) is mandatory. All financial statements, value-added tax (VAT) and corporate income tax (CIT) declarations must be prepared and submitted on time.

However, this is not easy, as the Vietnamese accounting system has many detailed regulations and is regularly updated. This is where a professional accounting bookkeeping service plays an important role: they help businesses ensure legal compliance, reconcile correct data, and maintain transparency in all financial data.

As a result, businesses avoid audit and tax risks, and can focus all their efforts on core activities like operating and expanding the logistics network.

6. Vina TPT Bookkeeping Service: Turning Numbers into Insights

When it comes to reliable outsourced accounting services in Vietnam, Vina TPT Bookkeeping Service is a prominent name. Vina TPT’s difference lies not only in accurate bookkeeping, but also in the ability to turn numbers into practical business strategies.

Vina TPT understands that each logistics enterprise has its own characteristics – from fleet size, warehouse model to transportation fee calculation. Therefore, they not only prepare financial reports according to VAS but also analyze monthly data, helping enterprises understand cost trends, route profits and the efficiency of each operation.

Through regular consulting sessions, the Vina TPT Bookkeeping Service team supports Singaporean enterprises to make more accurate investment decisions, manage cash flow more effectively, and gradually build a sustainable financial system in Vietnam.

Contact Vina TPT today for a free consultation and tailored solutions for your logistics business.

BOOK A FREE CONSULTATION

Vina TPT Accounting services

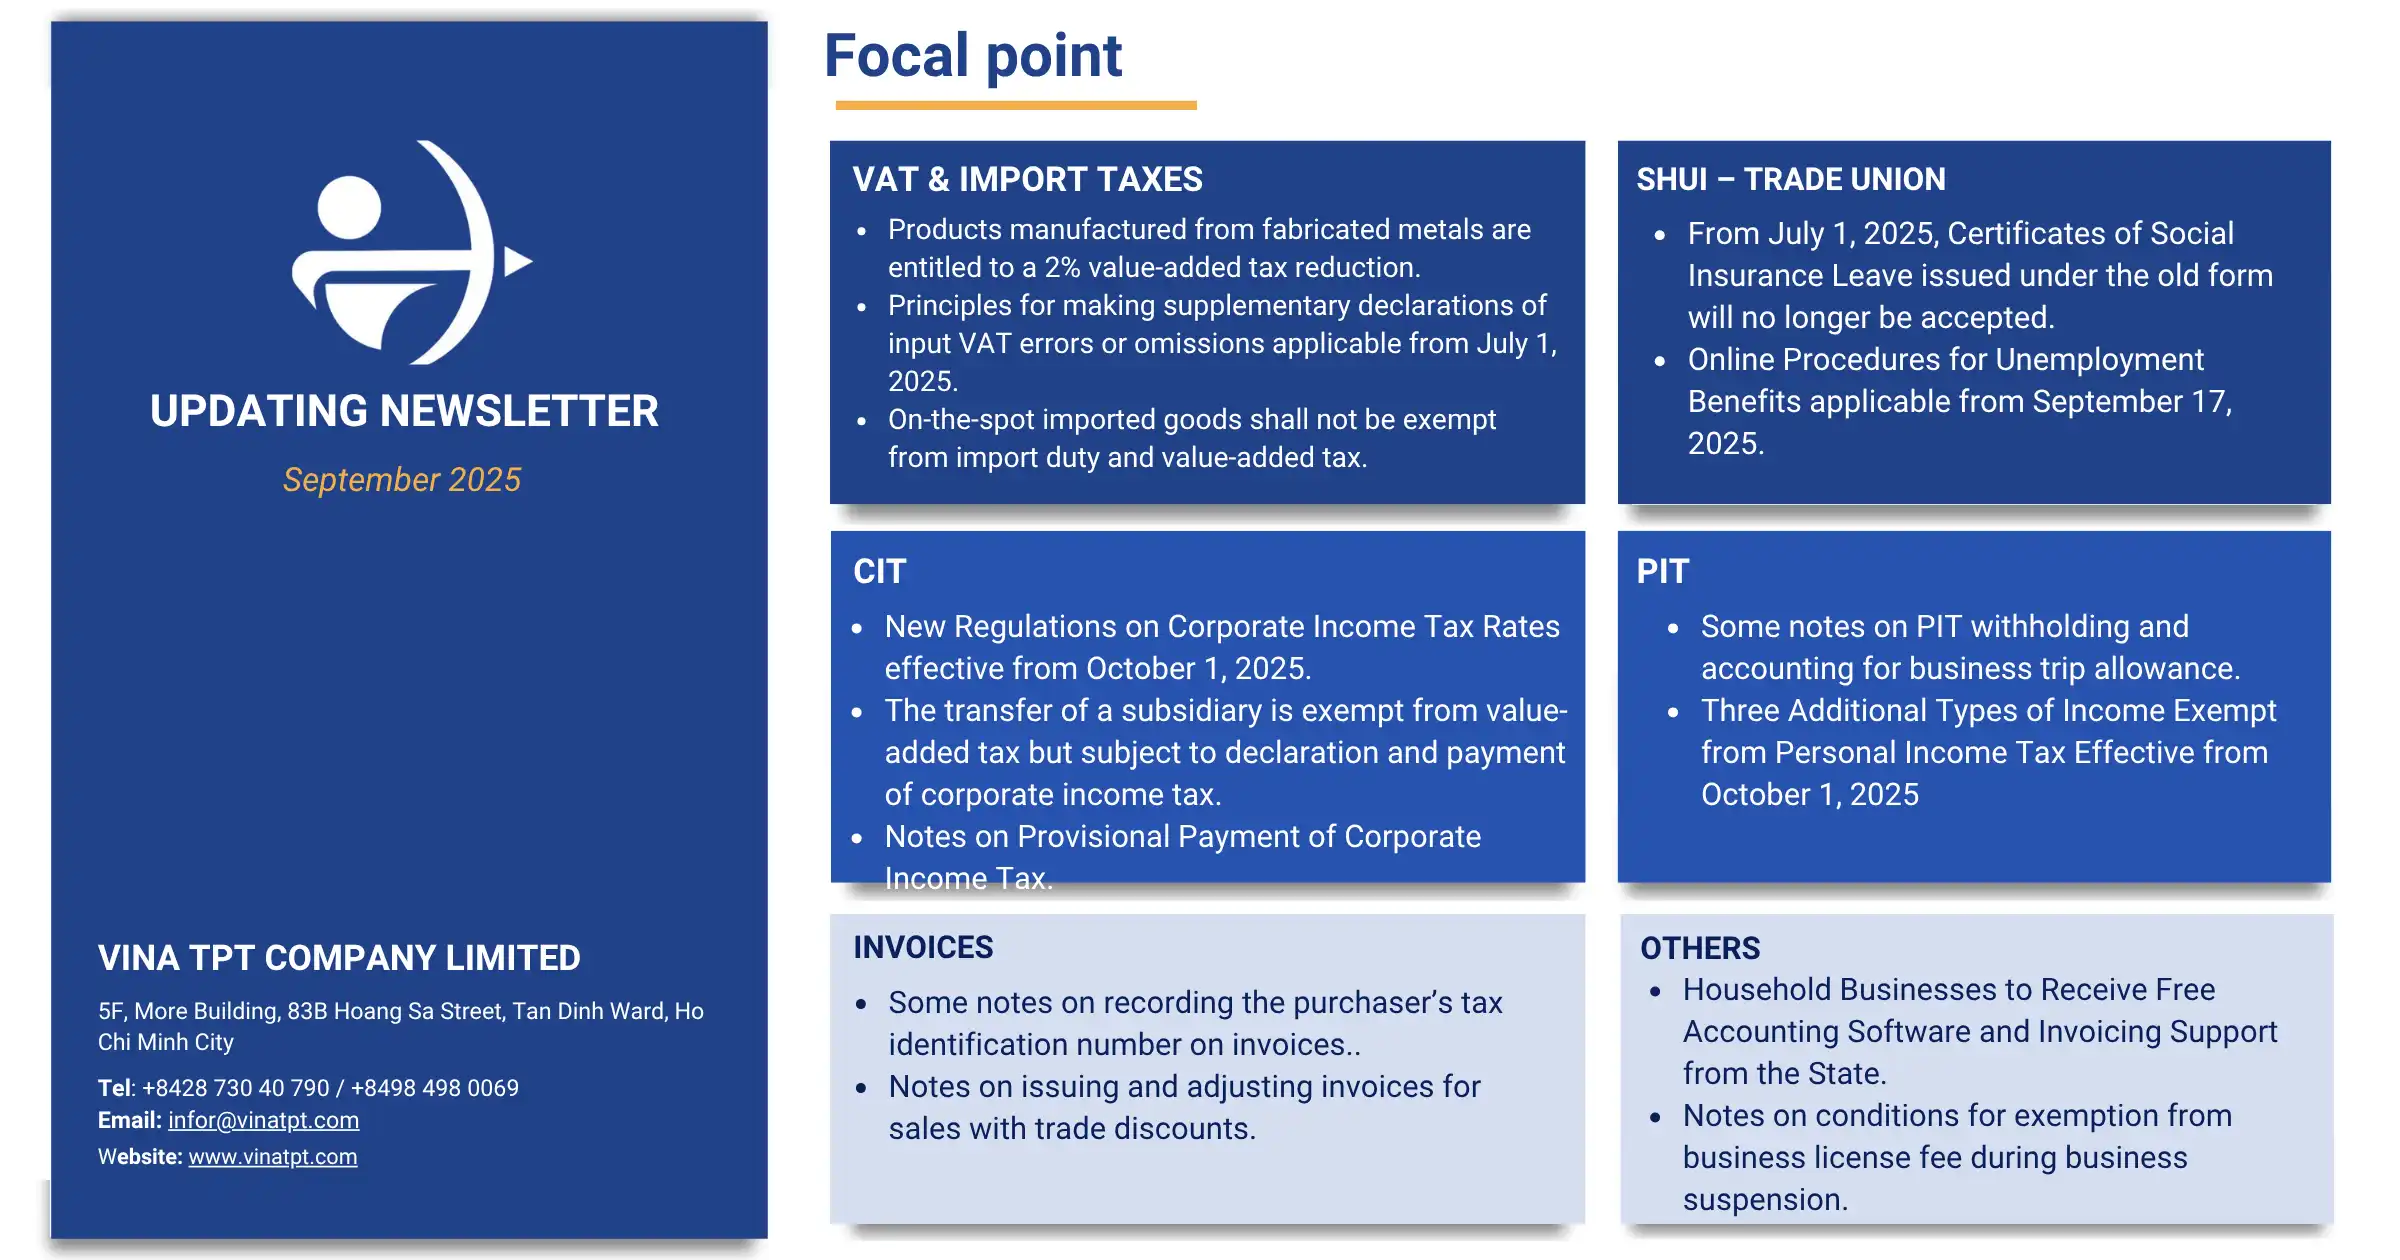
[Newsletter] Vietnam Tax Policy Updates September 2025- CIT, VAT, PIT and Social Insurance

Updates on new regulations regarding tax, e-invoices, and social insurance September 2025 (2)
As part of the Vietnam tax policy updates 2025, several new regulations related to Corporate Income Tax (CIT), Value Added Tax (VAT), Personal Income Tax (PIT), and social insurance are scheduled to take effect starting from September 2025. These changes are expected to directly impact financial reporting, payroll processes, and compliance operations across both Vietnamese and FDI enterprises.
To help businesses stay compliant and proactively adjust their internal procedures, this article provides a clear breakdown of the most important regulatory updates you need to be aware of.
In this article, we break down the most important tax regulations businesses need to prepare for in 2025.

1. Value-Added-Tax & IMPORT TAXES

1.a. Products manufactured from fabricated metals are entitled to a 2% value-added tax reduction.

Official Letter No. 6099/TCS3-QLDN2 dated September 11, 2025 of Dong Nai Tax Department regarding the case where a company manufactures and processes metal products, in which the determination of VAT reduction on sold products is made in accordance with Circular No. 174/2025/TT-BTC, specifically as follows:
  • The company shall identify its products based on the product codes, names, and descriptions provided in the Appendix issued together with Decision No. 43/2018/QD-TTg, and compare them with the List of goods and services not eligible for value-added tax (VAT) reduction issued together with Circular No. 174/2025/TT-BTC. In cases where the products fall under the List of goods attached to Circular No. 174/2025/TT-BTC, they shall not be entitled to VAT reduction.
  • For products manufactured from fabricated metals classified under Section 25, which are not included in the List of goods and services issued together with Circular No. 174/2025/TT-BTC, a VAT reduction shall apply.

1.b. Principles for making supplementary declarations of input VAT errors or omissions applicable from July 1, 2025.

Official Letter No. 3915/CT-CS dated September 18, 2025 of the Tax Department regarding VAT policies, specifically as follows:
  • The Tax Department stated that, from July 1, 2025, the Law on Value-Added Tax No. 48/2024/QH15 and Decree No. 181/2025/ND-CP have specifically provided regulations on the declaration and deduction of input VAT in cases of errors or omissions. Enterprises are therefore requested to study and comply with these provisions. Accordingly, under Point đ, Clause 1, Article 14 of Law No. 48/2024/QH15 and Clauses 5 and 6, Article 23 of Decree No. 181/2025/ND-CP, when errors or omissions in input VAT are detected, business establishments shall make supplementary declarations in accordance with the following principles:
  • A supplementary declaration shall be made in the month or quarter in which the error or omission in input VAT arises, if such error or omission results in an increase in tax payable or a reduction in refundable tax for that month or quarter.
  • A supplementary declaration shall be made in the month or quarter when the error or omission is detected, if such error or omission results in a decrease in tax payable, or only increases or decreases the amount of VAT to be carried forward to the subsequent period.

1.c. On-the-spot imported goods shall not be exempt from import duty and value-added tax.

Official Letter No. 22303/CHQ-GSQL dated September 5, 2025 of the Customs Department regarding on-the-spot imported goods, specifically as follows:
  • Clause 3 Article 3 of Law No. 90/2025/QH15 supplements Article 47a of the Customs Law, stipulating that on-the-spot import and export goods are goods delivered and received in Viet Nam under the designation of a foreign trader pursuant to sale, processing, leasing, or borrowing contracts. Cases that meet these conditions shall carry out customs procedures under Article 35 of Circular No. 08/2015/TT-BTC (as amended by Circular No. 167/2025/TT-BTC) and Article 86 of Circular No. 38/2015/TT-BTC (as amended by Circular No. 39/2018/TT-BTC).
  • According to Circular No. 134/2016/TT-BTC (as amended by Circular No. 18/2021/TT-BTC), in cases where on-the-spot imports are not registered under the processing type, the importer must declare and pay import duty based on the applicable duty rate and customs value at the time of registration. If import duty has been paid for production or business purposes and the imported products have been actually exported abroad or to a non-tariff zone, the paid duty shall be refunded in accordance with Article 36 of this Circular
  • On-the-spot import and export goods remain subject to VAT. Where goods are registered under other types (not processing), the taxpayer shall use code A11 (commercial import) or A12 (import for production and business) to declare and pay import duty and VAT.

2. Personal Income Tax (PIT)

2a. Some notes on PIT withholding and accounting for business trip allowance.

Official Letter No. 2284/CTH-QLDN1 dated September 15, 2025 of the Can Tho City Tax Department regarding taxable personal income (PIT) on business trip allowances, specifically as follows:
  • Taxable PIT income with respect to lump-sum business trip allowances: This is the portion of business trip allowances exceeding the limits prescribed by the State. Specifically: For employees working in business organizations and representative offices, the limit on business trip allowances shall be applied consistently with the level determined for corporate income tax (CIT) purposes. For employees working in international organizations or representative offices of foreign organizations, the limit on business trip allowances shall be applied in accordance with the regulations of such international organizations or representative offices of foreign organizations (see Point đ.4, Clause 2, Article 2 of Circular No. 111/2013/TT-BTC).
Travel expenses and accommodation costs for employees on business trips shall be deductible if supported by sufficient invoices and documents.
  • Where the enterprise has a financial/internal regulation stipulating allowances for travel, accommodation, and per diem for employees on business trips, and such regulation is properly implemented, these expenses shall be deductible.
  • Payment by employees’ personal bank cards for business trip expenses of VND 20 million or more (including airfares):
  • Such expenses shall be deductible if the following conditions are met:
  • Valid invoices and supporting documents are available.
  • A decision or written authorization for the employee’s business trip is issued.
  • The enterprise’s financial/internal regulation permits employees to pay using personal bank cards, with subsequent reimbursement by the enterprise.
  • Purchase of air tickets via e-commerce websites: The documents serving as the basis for deductibility include the electronic air ticket, boarding pass, and the enterprise’s non-cash payment vouchers showing the individual undertaking the transportation service.

Explore Tax Services in Viet Nam

2b. Three Additional Types of Income Exempt from Personal Income Tax Effective from October 1, 2025

According to the new provisions in the Law on Science, Technology and Innovation 2025 (No. 93/2025/QH15), effective from October 1, 2025, Clause 3, Article 71 of this Law supplements Points 18, 19, and 20 after Point 17 of Article 4 on tax-exempt income under the Law on Personal Income Tax 2007, as amended and supplemented.
Accordingly, from October 1, 2025, three additional types of income will be exempt from Personal Income Tax (PIT), including:
  • Income from salaries and wages received from performing science, technology, and innovation tasks.
  • Income from copyright related to science, technology, and innovation tasks when the results of such tasks are commercialized in accordance with the laws on science, technology, innovation, and intellectual property.
  • Income of individual investors and experts working for start-up innovation projects, founders of start-up enterprises, and individual investors contributing capital to venture capital funds.

3. Corporate Income Tax (CIT)
Corporate-income-tax-VinaTPT

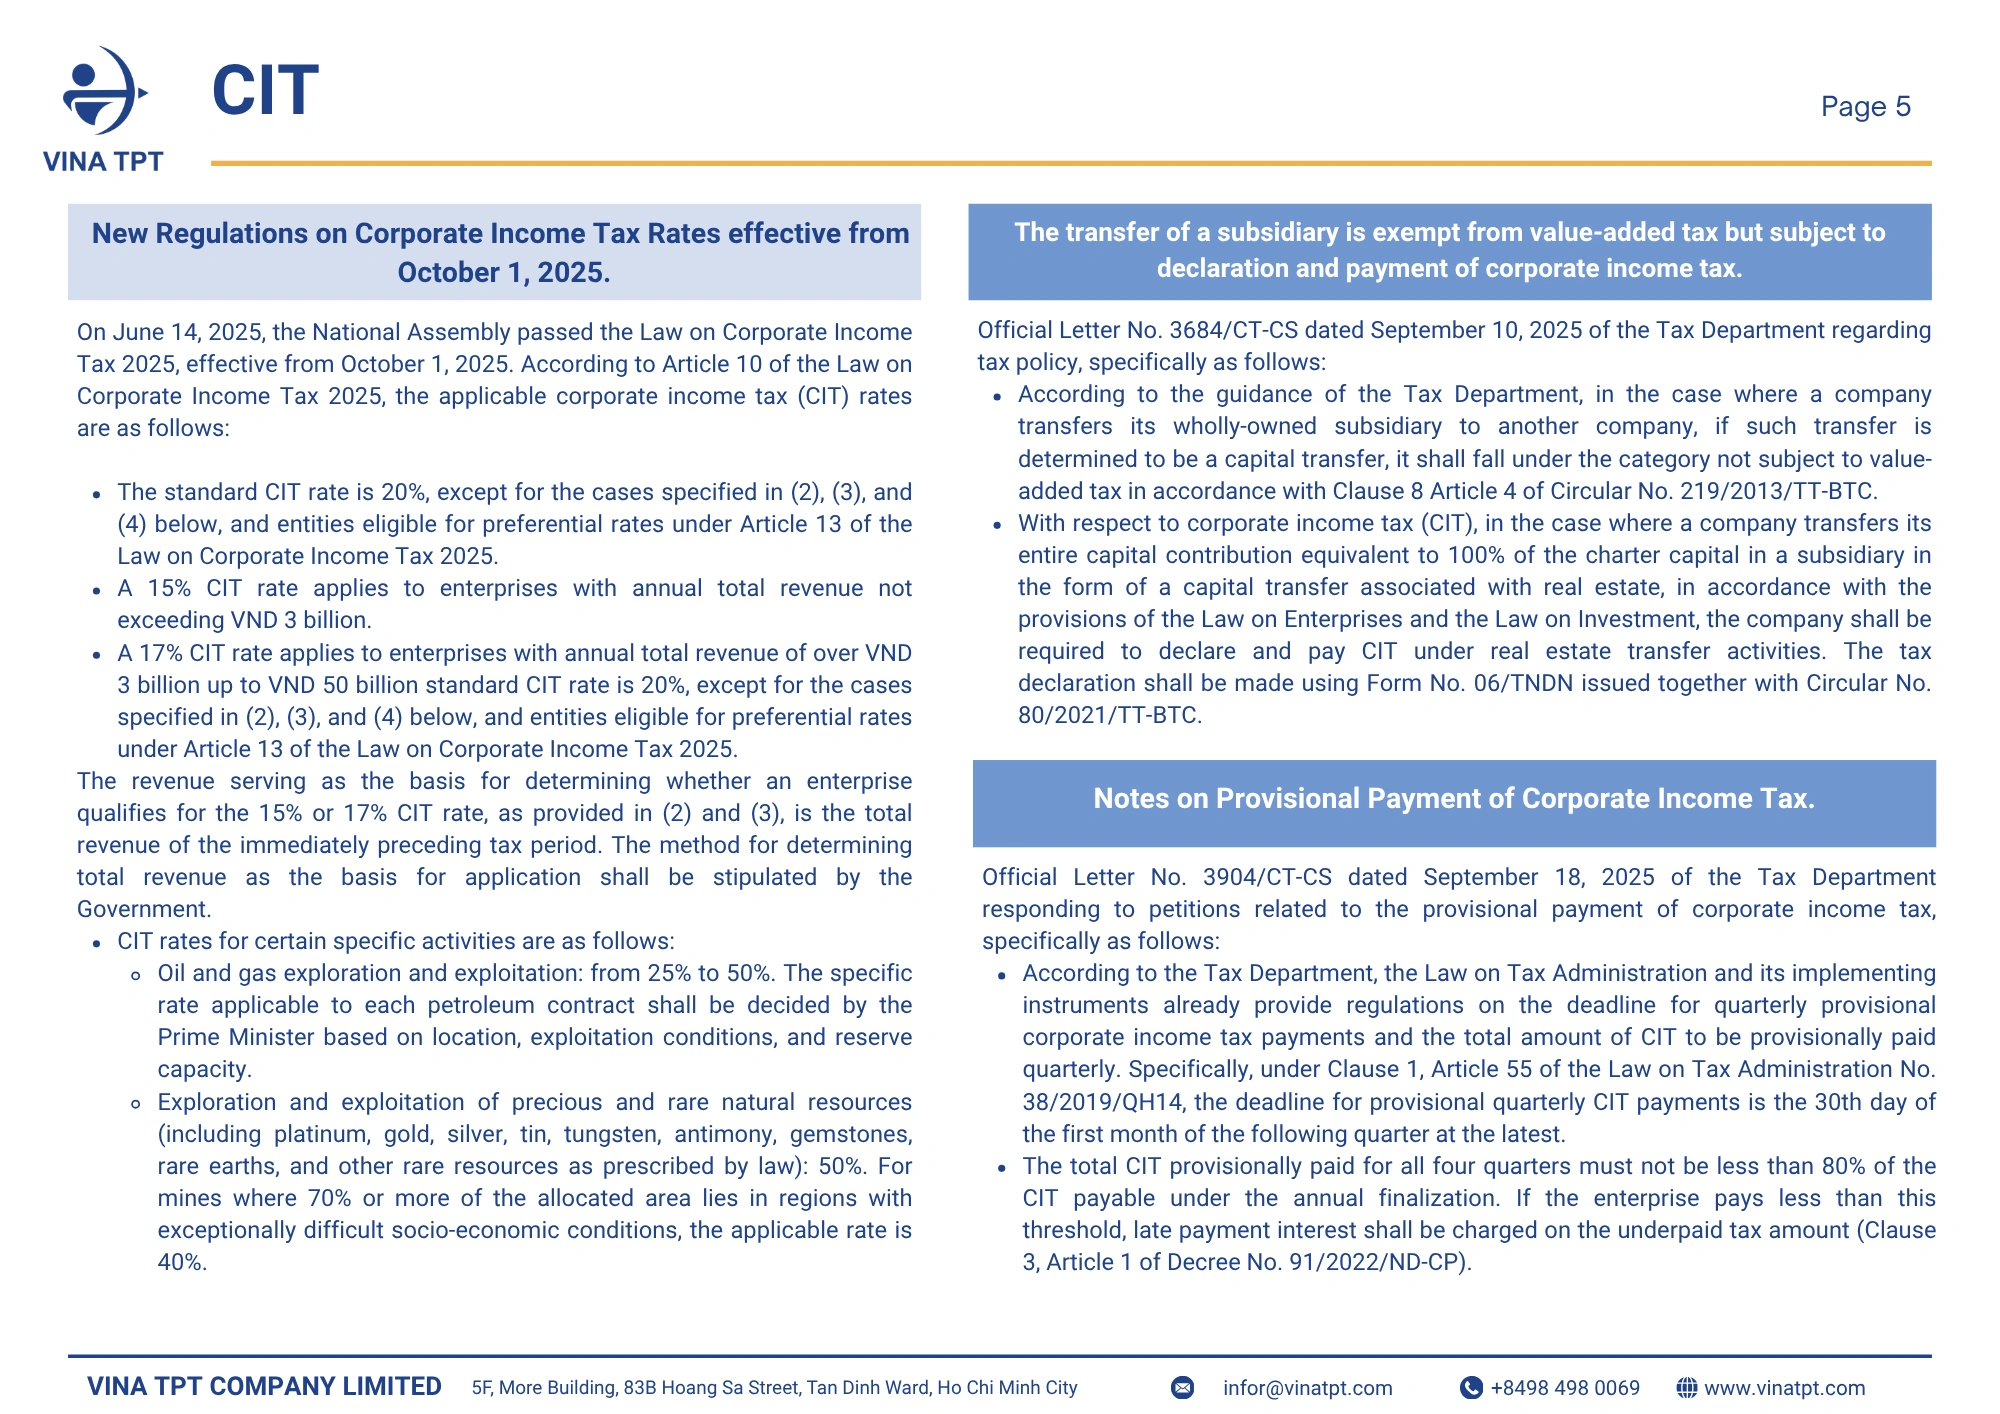
3a. New Regulations on Corporate Income Tax Rates effective from October 1, 2025.

On June 14, 2025, the National Assembly passed the Law on Corporate Income Tax 2025, effective from October 1, 2025. According to Article 10 of the Law on Corporate Income Tax 2025, the applicable corporate income tax (CIT) rates are as follows:
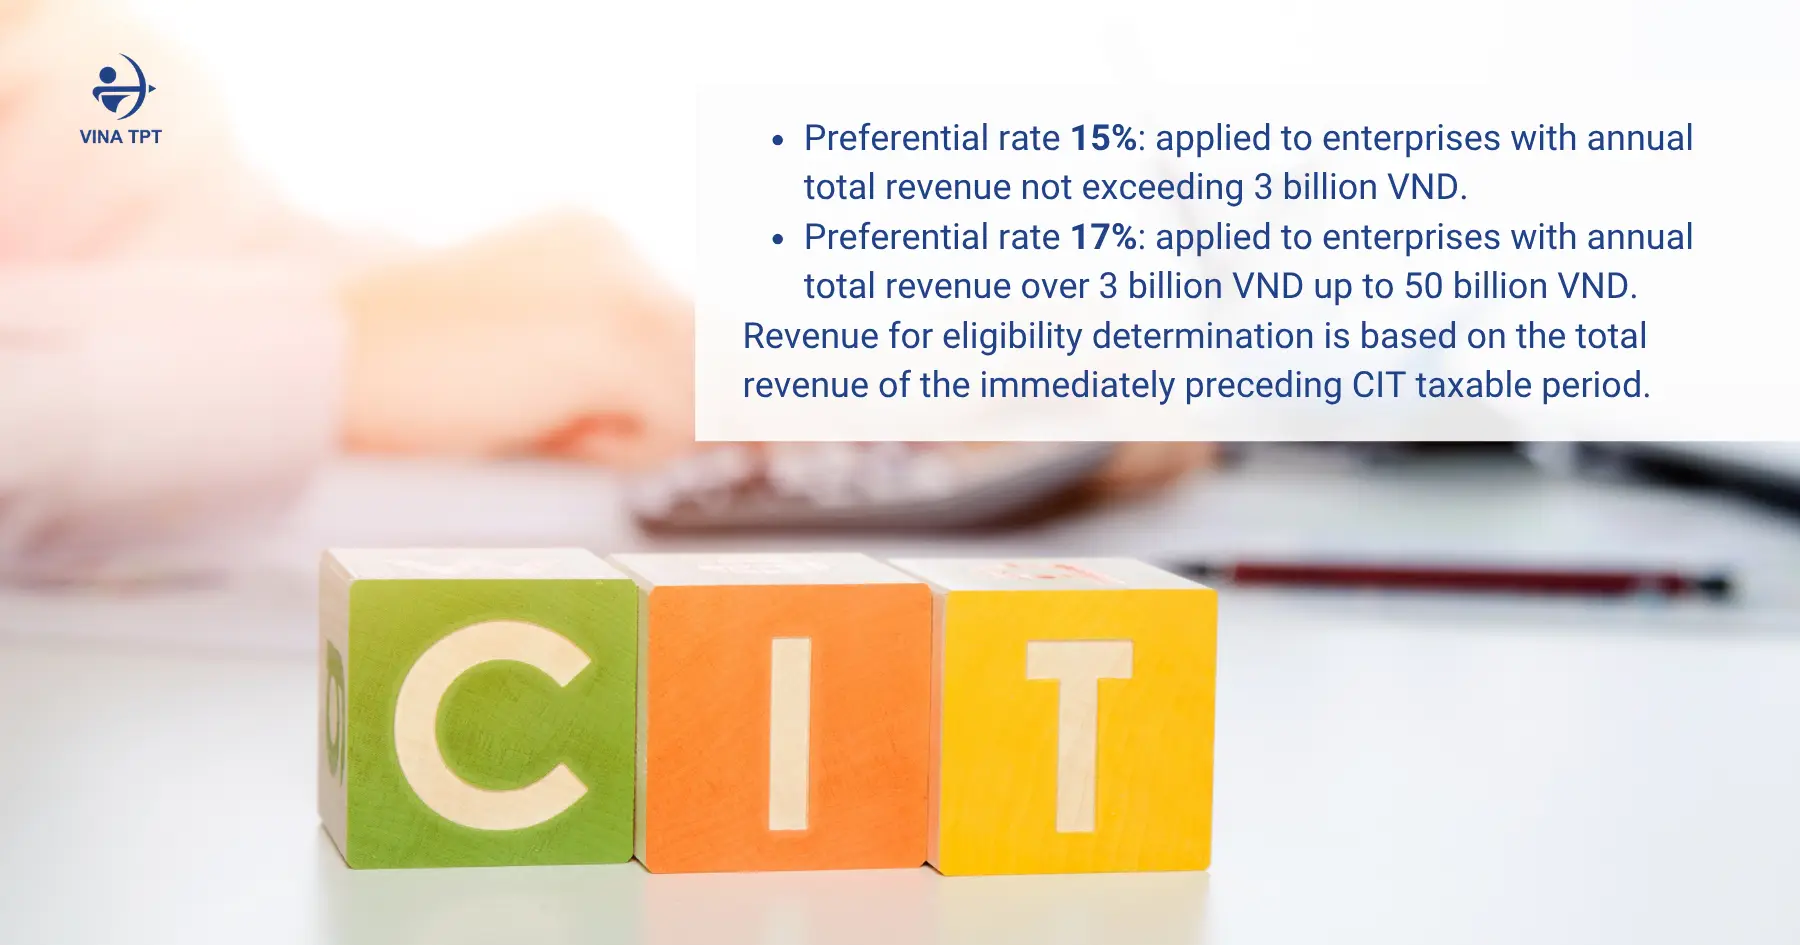
  • The standard CIT rate is 20%, except for the cases specified in (2), (3), and (4) below, and entities eligible for preferential rates under Article 13 of the Law on Corporate Income Tax 2025.
  • A 15% CIT rate applies to enterprises with annual total revenue not exceeding VND 3 billion.
  • A 17% CIT rate applies to enterprises with annual total revenue of over VND 3 billion up to VND 50 billion standard CIT rate is 20%, except for the cases specified in (2), (3), and (4) below, and entities eligible for preferential rates under Article 13 of the Law on Corporate Income Tax 2025
The revenue serving as the basis for determining whether an enterprise qualifies for the 15% or 17% CIT rate, as provided in (2) and (3), is the total revenue of the immediately preceding tax period. The method for determining total revenue as the basis for application shall be stipulated by the Government.
CIT rates for certain specific activities are as follows:
  • Oil and gas exploration and exploitation: from 25% to 50%. The specific rate applicable to each petroleum contract shall be decided by the Prime Minister based on location, exploitation conditions, and reserve capacity.
  • Exploration and exploitation of precious and rare natural resources (including platinum, gold, silver, tin, tungsten, antimony, gemstones, rare earths, and other rare resources as prescribed by law): 50%. For mines where 70% or more of the allocated area lies in regions with exceptionally difficult socio-economic conditions, the applicable rate is 40%.

3b. The transfer of a subsidiary is exempt from value-added tax but subject to declaration and payment of corporate income tax.

Official Letter No. 3684/CT-CS dated September 10, 2025 of the Tax Department regarding tax policy, specifically as follows:
  • According to the guidance of the Tax Department, in the case where a company transfers its wholly-owned subsidiary to another company, if such transfer is determined to be a capital transfer, it shall fall under the category not subject to value-added tax in accordance with Clause 8 Article 4 of Circular No. 219/2013/TT-BTC.
  • With respect to corporate income tax (CIT), in the case where a company transfers its entire capital contribution equivalent to 100% of the charter capital in a subsidiary in the form of a capital transfer associated with real estate, in accordance with the provisions of the Law on Enterprises and the Law on Investment, the company shall be required to declare and pay CIT under real estate transfer activities. The tax declaration shall be made using Form No. 06/TNDN issued together with Circular No. 80/2021/TT-BTC.

3c. Notes on Provisional Payment of Corporate Income Tax.

Official Letter No. 3904/CT-CS dated September 18, 2025 of the Tax Department responding to petitions related to the provisional payment of corporate income tax, specifically as follows:
  • According to the Tax Department, the Law on Tax Administration and its implementing instruments already provide regulations on the deadline for quarterly provisional corporate income tax payments and the total amount of CIT to be provisionally paid quarterly. Specifically, under Clause 1, Article 55 of the Law on Tax Administration No. 38/2019/QH14, the deadline for provisional quarterly CIT payments is the 30th day of the first month of the following quarter at the latest.
  • The total CIT provisionally paid for all four quarters must not be less than 80% of the CIT payable under the annual finalization. If the enterprise pays less than this threshold, late payment interest shall be charged on the underpaid tax amount (Clause 3, Article 1 of Decree No. 91/2022/ND-CP).

4. Social Insurance – Trade Union

a. From July 1, 2025, Certificates of Social Insurance Leave issued under the old form will no longer be accepted.

Official Letter No. 5761/BYT-KCB dated August 27, 2025 of the Ministry of Health regarding the settlement of difficulties in implementing social insurance regimes for employees, specifically as follows:
  • Accordingly, the Ministry of Health notes that Certificates of Social Insurance Leave issued prior to the effective date of Circular No. 25/2025/TT-BYT (July 1, 2025) shall remain valid as the basis for entitlement to social insurance benefits. For Certificates issued after July 1, 2025, it is mandatory to use the new form promulgated under Circular No. 25/2025/TT-BYT. The difference between the new form and the old form (issued under Circular No. 18/2022/TT-BYT) lies in the addition of information on the employee’s citizen identification number/identity card number/passport number/personal identification number; other contents remain unchanged from the old form.
  • During the initial implementation of Circular No. 25/2025/TT-BYT, for documents issued by hospitals still using the old form and not yet switched to the new form, in order to ensure employees’ rights and avoid inconvenience, the Ministry of Health has requested that enterprises prepare a list of employees whose documents were issued by hospitals in non-compliance with regulations, and submit an official letter to the Department of Health or the health authority of the relevant ministries/agencies managing such hospitals, requesting the supplementation of information on the documents already issued, as prescribed in Point b, Clause 4, Article 28 of Circular No. 25/2025/TT-BYT.
As for Certificates of Social Insurance Leave without the hospital’s seal due to the seal not yet being updated to the new address following a merger, the Ministry of Health has stated that, under Clause 8, Article 69 of Decree No. 188/2025/ND-CP, medical examination and treatment establishments are permitted to continue using their old seals until new seals are issued.

b. Online Procedures for Unemployment Benefits applicable from September 17, 2025.

Decision No. 1295/QD-TTPVHCC dated September 17, 2025 of the People’s Committee of Hanoi City announcing the List of administrative procedures on unemployment insurance to be piloted on the National Public Service Portal under the management competence of the Department of Home Affairs of Hanoi City, specifically as follows:
This Decision announces six procedures concerning the entitlement to and termination of unemployment benefits to be piloted by the Hanoi Department of Home Affairs on the National Public Service Portal as from September 17, 2025, including:
  • Settlement of entitlement to unemployment benefits
  • Monthly notification of job search activities.
  • Settlement of entitlement to unemployment benefits
  • Settlement of entitlement to unemployment benefits
  • Transfer of entitlement to unemployment benefits (integrated procedure for transfer-out and transfer-in).
  • Termination of entitlement to unemployment benefits.
This Decision takes effect from the date of signing.

5. OTHER

a. Household Businesses to Receive Free Accounting Software and Invoicing Support from the State.

Official Letter No. 3914/CT-CS dated September 18, 2025 of the Tax Department regarding the response to the petition of the Vietnam Banks Association:
  • With respect to the use of invoices by household businesses, the Tax Department notes that, pursuant to the provisions of Decree No. 70/2025/NĐ-CP, from June 1, 2025, when selling goods or providing services directly to consumers, household businesses under the lump-sum tax regime with annual revenue exceeding VND 1 billion must issue electronic invoices generated from cash registers connected to and transmitting data to the tax authority, and deliver such invoices to buyers. The electronic invoice data is already available on the tax authority’s system, allowing both sellers and buyers to look up invoices on the system without the need to print paper copies.
  • Under the current guidance provided in Circular No. 40/2021/TT-BTC, there is no provision requiring lump-sum household businesses to retain purchase invoices or supporting documents.
  • As stipulated at Point b, Clause 4, Article 13 of Circular No. 40/2021/TT-BTC, in cases where a lump-sum household business changes its business scale (premises size, labor use, or revenue), it must declare adjustments and supplements to the Tax Return using Form No. 01/CNKD. The tax authority, based on the household business’s tax return and the tax sector’s database, shall issue a Notice of adjustment of lump-sum tax if it determines that declared revenue has changed by 50% or more compared to the previously assessed lump-sum revenue, effective from the time of such change within the tax year.
Furthermore, pursuant to Clause 3, Article 12 of Resolution No. 198/2025/QH15, the State shall allocate funding to provide free shared digital platforms and accounting software for small and micro enterprises, household businesses, and individual business households. At present, the Ministry of Finance is drafting a Decree guiding the implementation of this Resolution, which will include provisions on the measures to support the free provision of shared digital platforms and accounting software for small and micro enterprises, household businesses, and individual businesses.

b. Notes on conditions for exemption from business license fee during business suspension.

Official Letter No. 1355/QNG-QLDN1 dated September 4, 2025, of the Quang Ngai Provincial Tax Department on guidance regarding business license fees
  • The conditions for exemption from the business license fee during business suspension are stipulated in Clause 2, Article 1 of Decree No. 22/2020/NĐ-CP and Clause 4, Article 1 of Circular No. 65/2020/TT-BTC, as follows: a written request for suspension of production and business operations must be submitted to the tax authority or the business registration authority before the deadline for payment of the business license fee (January 30 each year), and the business license fee of the year in which suspension is requested has not yet been paid.
  • Accordingly, if a Company has submitted a written request to the business registration authority to suspend production and business operations in the calendar year 2025 (from January 1 to December 31) before the license fee payment deadline (before January 30) and has not yet paid the 2025 business license fee, then the Company is not required to pay the license fee for 2025.
However, if the above conditions are not satisfied, the Company must pay the business license fee for 2025.

6. INVOICES

a. Some notes on recording the purchaser’s tax identification number on invoices.

Official Letter No. 3955/CT-CS dated September 19, 2025 of the Tax Department regarding e-invoices, specifically as follows:
  • The presentation of the buyer’s name, address, and taxpayer identification number on e-invoices shall comply with the provisions of Clause 5 and Point c, Clause 14, Article 10 of Decree No. 123/2020/ND-CP (as amended and supplemented at Points a and d, Clause 7, Article 1 of Decree No. 70/2025/ND-CP). Accordingly, in cases where the buyer is a business establishment with a TIN, the buyer’s name, address, and TIN stated on the invoice must be consistent with the information on the enterprise/branch registration certificate, household business registration certificate, tax registration certificate, or TIN notification
  • If the purchaser does not have a tax identification number, the TIN is not required to be shown on the e-invoice. In addition, in cases specified at Point c, Clause 14 , Article 10, it is not mandatory to indicate the purchaser’s name, address, or TIN on the invoice. As from June 1, 2025, where the purchaser provides a TIN or personal identification number, the invoice must also include such TIN or personal identification number.
  • For e-invoices generated from cash registers, the invoice must show the purchaser’s name, address, tax identification number/personal identification number/telephone number if so requested by the purchaser (see Clause 3, Article 11 of Decree No. 123/2020/ND-CP, as amended and supplemented under Clause 8, Article 1 of Decree No. 70/2025/ND-CP).

b. Notes on issuing and adjusting invoices for sales with trade discounts.

Official Letter No. 1802/CTH-QLDN3 dated September 3, 2025, of the Can Tho City Tax Department regarding trade discount invoices, specifically as follows:
In this document, the Can Tho City Tax Department provided guidance on determining VAT taxable prices in cases of trade discounts, how to present discount amounts on invoices, and how to handle adjustment invoices when discounts are based on quantity or sales volume. Specifically:
VAT taxable price: The VAT taxable price is the selling price after deducting the trade discount given to customers, excluding VAT (Clause 2, Article 14 of Decree No. 181/2025/NĐ-CP).
Presentation on invoices: The invoice must clearly indicate the trade discount amount (Point đ, Clause 6, Article 10 of Decree No. 123/2020/NĐ-CP.
Discounts based on quantity or sales volume:
  • Adjustment on the last purchase/next period invoice: The discount amount shall be adjusted on the sales/service invoice of the last purchase or subsequent period, ensuring the discount amount does not exceed the value of goods or services recorded on that invoice.
  • Issuing an adjustment invoice: An adjustment invoice may be issued together with a list of the invoices subject to adjustment, including amounts and tax adjustments. The list must be kept at the entity and presented upon request by the tax authority or other competent state authority (Clause 13, Article 1 of Decree No. 70/2025/NĐ-CP amending and supplementing Article 19 of Decree No. 123/2020/NĐ-CP.
  • Tax return adjustments: Based on the adjustment invoice and related records, both the buyer and the seller shall declare adjustments to sales revenue, purchase revenue, input and output VAT in the period when the adjustment invoice is issued.
  • Adjustment invoice for trade discounts: This is an adjustment invoice for previously issued invoices, used to adjust differences in amounts only; it is not used to declare sales revenue already incurred. Accordingly, in the electronic invoice system of the General Department of Taxation, the line “Total amount before tax” will display the trade discount amount, while the line “Total trade discount amount” will display as 0.

Contact us for support

📞 (+84) 984 980 069

📧 infor@vinatpt.com

🌐www.vinatpt.com

🏢 5th Floor, More Building, 83B Hoang Sa, Tan Dinh Ward, Ho Chi Minh City

accounting service Vietnam for FDI company vtpt

Entering Vietnam’s Clothing Market: A Practical Guide for Chinese Manufacturers

Vina TPT company registration service supporting Chinese clothing investors in Vietnam

business-license-in-vietnam-for-chinese-manufacturer

1. Why Vietnam Is the Next Stop for China’s Clothing Giants

Vietnam is emerging as one of the most dynamic consumer markets in Southeast Asia, especially in the fashion and retail sectors. The middle class is growing rapidly, average incomes are rising, and young people’s shopping trends are gradually shifting towards brands with unique styles and reasonable prices.

For foreign investors and Chinese fashion brands, obtaining a business license in Vietnam is the first important step to legally enter this fast-growing market. With proper licensing and strategic market entry, businesses can take full advantage of Vietnam’s expanding retail opportunities and rising consumer demand.

Vietnamese consumers, especially Gen Z and Millennials, prefer modern fashion that quickly updates global trends while maintaining high practicality. This creates a great advantage for Chinese businesses, which have the ability to produce quickly, flexibly, and at competitive costs.

Not only does Vietnam have great purchasing power, it is also a politically stable market, transparent in investment, and benefits from many free trade agreements (CPTPP, RCEP, EVFTA). In addition, obtaining a business license in Vietnam for fashion or retail activities has become increasingly streamlined, making importing, distributing, or opening Chinese fashion brands in Vietnam easier and more compliant than ever. business license in vietnam

2. Choosing the Right Market Entry Strategy

Chinese businesses can choose one of three popular models when expanding into the Vietnamese market:

  • Establishing a 100% foreign-owned company (WFOE): Suitable for brands that want to control the entire import-distribution-retail process. This model allows for opening physical stores or doing business online after obtaining the required business license in Vietnam.
  • Cooperating with local distributors: helps save costs, quickly access the market, and take advantage of the existing retail network.
  • Joint Venture: Cooperating with Vietnamese businesses to combine local knowledge with goods sources and management capacity from China.

Each form has its own advantages in terms of control level, cost and risk, so it is necessary to consult carefully before choosing.

3. Beyond Paperwork: Setting the Foundation for Operations

To open a business in Vietnam, businesses need to carry out some important legal procedures to have business license in Vietnam:

Investment Registration Certificate (IRC) if there is foreign capital. IRC is the first license allowing the investor to implement the project in Vietnam.

The required documents usually include:

  • Application for investment project implementation and Project proposal: stating the objectives, scale, location, investment capital, progress.
  • Proof of the investor’s financial capacity: bank statement, credit contract or collateral.
  • Legal documents of the investor:
    • Individual: Notarized passport, consular legalization.
    • Organization: Business registration certificate or equivalent document, consular legalization.
  • Project location: lease contract or land/office use rights certificate.

After the IRC is granted (or for 100% domestic-owned enterprises), the investor applies for an ERC – an official license for the enterprise to operate, and also the tax code of the company.

Enterprise Registration Certificate (ERC) at the Department of Planning & Investment. The ERC dossier usually includes:

  • Application for enterprise registration.
  • Company Charter: stipulates the organizational structure, powers of members/shareholders, capital ratio and management method.
  • List of members/shareholders and legal representatives: clearly state information, ownership ratio, voting rights.
  • Appointment decision and authorization letter (if any).
  • Capital contribution plan & financial evidence: bank statement or credit contract (especially important for large capital projects).

Register appropriate business lines, for example:

  • Wholesale and retail of garments and fashion accessories.
  • Import and export of fashion goods.
  • E-commerce business (if selling online).

The good news is that the fashion trade and distribution industry does not require any special sub-licenses, so the establishment procedure is quite simple and the processing time is fast.

After obtaining the business license in Vietnam, the business needs to register a tax code, open a bank account, issue electronic invoices and declare taxes periodically to operate legally.

CONSULT ON BUSINESS LICENSE IN VIETNAM

4. Workforce and Culture Integration

The Vietnamese market is diverse and can be divided into 3 key areas:

  • Ho Chi Minh City: a vibrant commercial center, suitable for young, dynamic fashion.
  • Hanoi: a traditional market, favoring brands with reliability and elegant designs.
  • Da Nang, Can Tho: emerging markets, low cost, easy to test retail models.

In addition to choosing a strategic business location, businesses need to:

  • Cooperate with logistics units to optimize shipping costs from China to Vietnam.
  • Build a localized marketing strategy, combining platforms such as TikTok, Shopee, Lazada and Facebook, which currently account for the majority of online fashion sales channels in Vietnam.
  • Understand Vietnamese fashion tastes: prioritize light, airy, easy-to-match and highly applicable products.

5. Local Compliance and Ethical Manufacturing

When operating in Vietnam, recruiting and managing local human resources is an important factor.

Chinese enterprises need to clearly understand the regulations on labor contracts, social insurance, and personal income tax (PIT) to avoid violations.

In addition, cultural differences should also be noted:

  • Vietnamese people value respect, gentleness, and collaboration in the working environment.
  • A team of dedicated employees, paid on time and transparently will help operations run smoothly, especially in the retail and customer care sectors.

Many foreign enterprises choose to outsource payroll and HR services to ensure compliance, optimize costs, and reduce administrative risks. In addition, working with a professional consulting partner also helps businesses handle legal procedures such as applying for a business license in Vietnam, registering employees, and setting up a compliant payroll system, ensuring smooth and lawful operations from the start.

6. How Vina TPT Helps You Scale Smoothly

Vina TPT Company Registration is a consulting and implementation unit for comprehensive services for foreign investors in Vietnam, especially Chinese enterprises in the fields of fashion, trade and light manufacturing.

We provide:

  • Investment consulting & legal structure according to the desired business model.
  • Business registration services (ERC, IRC), opening bank accounts, tax codes and electronic invoices.
  • Accounting, tax, payroll, periodic compliance management, ensuring transparent and legal operations.
  • Bilingual support in English – Vietnamese, helping businesses easily exchange and process documents.

With a team of experts with more than 2015 years of experience in the fields of foreign investment, finance and law, Vina TPT has accompanied hundreds of Chinese FDI companies to successfully expand in Vietnam – from establishment to stable operation.

7. From Setup to Growth: Building a Sustainable Clothing Brand in Vietnam

Vietnam is not only a “production hub” but also a booming consumer market with long-term potential.

Chinese businesses can take advantage of this market to build their brands, develop distribution channels, and expand into Southeast Asia.

With a deep understanding of Vietnam’s legal framework, tax regulations, and consumer market, Vina TPT helps you take every step with confidence – from setting up a legal entity and applying for business licenses in Vietnam, to managing finances and ensuring smooth operations.

Want to bring a Chinese fashion brand to Vietnam quickly and legally? 

Let Vina TPT accompany you through the entire process of company registration, compliance and tax accounting, helping you focus on developing your brand.

BOOK A FREE CONSULTATION

business-license-in-vietnam-for-chinese-manufacturer

Bridging VAS and J-GAAP: Accounting Outsourcing Solutions for Japanese Companies in Vietnam

Accounting and financial reporting for Japanese companies in Vietnam under VAS and J-GAAP standards

accounting-outsourcing-services-for-japanese

1. Japanese Firms Face Complex Financial Localization in Vietnam

Japanese corporations are known for their strict financial and accounting processes and high standards of transparency. However, when expanding operations to Vietnam, they face significant differences between Vietnamese accounting standards (VAS) and Japanese accounting standards (J-GAAP). This difference lies not only in the way revenue and expenses are recorded, but also affects the way financial statements are presented and reconciled between the parent company in Japan and its branch in Vietnam.

Many Japanese enterprises share that ensuring compliance with VAS as required by Vietnamese tax authorities while maintaining the internal reporting format according to J-GAAP is a complex problem. To handle these challenges efficiently, many turn to accounting outsourcing services provided by a professional accounting services company in Vietnam. These services not only ensure accurate reconciliation between the two systems but also support the preparation of bilingual reports and bank statements in Japanese, helping Japanese corporations maintain compliance, transparency, and efficiency across borders.

2. Challenges in Reconciling VAS and Japanese GAAP

What makes Japanese companies difficult is not only the difference in accounting regulations, but also in the actual operation process. The way revenue is recognized between the two systems can be different: VAS is based on the time of completion of the delivery obligation, while J-GAAP can record according to the contract conditions.

Another problem is the difference in exchange rates: VAS uses actual or average exchange rates, while J-GAAP may require re-recording at the end-of-period exchange rate, leading to discrepancies in consolidated reports. In addition, preparing bank statements in Japanese or bilingual financial statements to send to the parent company is also a significant challenge, requiring accounting personnel who are both knowledgeable in the field and fluent in the language.

In many cases, Japanese companies have to maintain two separate sets of accounting systems or spend a lot of time adjusting data. This not only increases operating costs but also prolongs the auditing process, reducing the effectiveness of internal financial management.

GET JAPAN-VIETNAM ACCOUNTING SUPPORT

3. Why Accounting Outsourcing Services Is the Optimal Solution

Accounting outsourcing services is becoming an inevitable trend in the Japanese business community in Vietnam. Instead of building a large internal team, businesses can cooperate with a professional unit – both understanding Vietnamese tax regulations and the J-GAAP system.

This solution helps businesses significantly save on personnel costs, minimize the risk of errors in declarations, and maintain standard bilingual financial reports (English – Japanese – Vietnamese), meeting the requirements of both tax authorities and parent companies. In particular, professional accounting service companies can build a data standardization process, ensuring that reports can be directly integrated into the group’s management system in Japan.

Accounting outsourcing services also helps businesses be more flexible – easily expanding or reducing the scale of accounting when there are changes in the project, without affecting the continuity of financial operations.

4. How Vina TPT Simplifies Accounting for Japanese Companies

Vina TPT Accounting Service is the leading accounting services company providing accounting and financial solutions for Japanese enterprises in Vietnam. We deeply understand the differences between VAS and J-GAAP and have built a specialized process to help Japanese clients localize their financial systems while maintaining the transparency standards of the parent corporation.

Vina TPT’s team of experts includes Japanese – English bilingual accountants and tax consultants, who are intensively trained in Japanese accounting standards, Vietnamese taxes, and specialized communication skills in Japanese. 

In particular, Mr. Le Quoc Duy, the chief expert in charge of Japanese customers, has more than 2015 years of experience working with large corporations in the fields of manufacturing, finance, and logistics of Japan in Vietnam.

accounting-outsourcing-services-for-japanese

We support businesses in the entire process:

  • Standardizing data and preparing bank statements in Japanese
  • Reconciling and converting reports from VAS to J-GAAP
  • Review documents before sending to HQ
  • And provide regular advice to ensure accuracy and compliance in the long term.

5. Build Transparent, Compliant and Cross-Cultural Financial Systems

With specialized accounting outsourcing services, Japanese enterprises in Vietnam not only solve compliance issues, but also create a transparent, reliable and cross-culturally compatible financial system. Standardized and bilingual financial data helps strengthen trust between the Vietnamese branch and the Japanese parent company, and facilitates smoother group audits.

In the long term, maintaining a transparent accounting and financial system not only helps companies control costs and optimize profits, but also demonstrates a standard operating philosophy that is consistent with Japanese business culture: accuracy – discipline – reliability.

Contact Vina TPT Accounting Service today for advice on outsourcing accounting solutions and bilingual financial reporting in accordance with J-GAAP standards. We help Japanese businesses in Vietnam operate more easily – accurately, compliantly and sustainably.

BOOK A FREE CONSULTATION

Accounting-and-financial-reporting-for-Japanese-companies-in-Vietnam

Accounting service for Chinese tech firms in Vietnam

Accounting services for Chinese tech companies in Vietnam

accounting-services-for-chinese-companies

1. Fast-Growing Chinese Tech Firms Need Smarter Accounting Services in Vietnam

The wave of Chinese technology companies shifting production and investment to Vietnam is taking place strongly. From electronics, hardware, software companies to technology startups, Vietnam has become an attractive destination thanks to its competitive labor costs, preferential tax policies and strategic position in the regional supply chain.

However, along with that expansion speed are challenges in financial management. As the scale of operations increases rapidly, companies face the challenge of controlling cash flow, standardizing accounting processes, and ensuring compliance with Vietnamese regulations, which are significantly different from the Chinese system. A smart, automated and transparent accounting system is the foundation for Chinese technology companies to maintain stability during their development in Vietnam.

2. Bridging the Gap Between Tech Expansion and Accounting Readiness

Most Chinese technology companies, when first investing in Vietnam, focus on production or R&D, paying little attention to building an internal accounting team with a good understanding of local laws. This leads to a fragmented financial system that lacks standardization, making it difficult to prepare tax and financial reports according to Vietnamese regulations.

In addition, differences in language, forms, tax declaration procedures and accounting standards (VAS vs CAS) put many businesses at risk of compliance. Even small errors in declaration or late submission of reports can lead to administrative fines, affecting the reputation of the business and long-term investment projects. Clearly, to operate effectively, Chinese technology companies need a reliable accounting partner who understands both the business language and the laws of the two countries.

3. Why Accounting Outsourcing and Payroll Services Ensure Agility and Compliance

Accounting services is a popular trend among FDI companies in Vietnam, especially in the technology industry. Instead of recruiting, training and maintaining an accounting department, enterprises can use the services of a professional unit – helping to save up to 40-60% of operating costs, while eliminating human resource risks.

Units specializing in providing accounting services such as Vina TPT not only process books, prepare financial reports, declare and settle taxes, but also integrate China payroll services, ensuring that salary calculation, personal income tax and social insurance deductions are performed correctly, transparently and bilingually. This is especially important for Chinese companies with multinational staff, requiring a payroll and tax calculation system that is both accurate and easy to understand.

As a result, businesses can focus resources on core activities – product, technology and market development,  ​​while accounting, tax and human resources are guaranteed to operate smoothly and in compliance with the law.

GET ADVICE ON ACCOUNTING SERVICES IN VIETNAM

4. Modern Accounting Services for Business Growth in the Tech Industry

In the digital age, accounting is no longer a manual task, but an important part of the operational strategy. Modern accounting solutions today apply cloud computing (cloud accounting), automate reporting, and standardize financial data according to VAS – IFRS to increase processing speed and minimize errors.

For technology businesses, this is even more important when it comes to tracking R&D costs, depreciation of technology assets, or calculating cost of goods in the supply chain. Digital accounting systems help businesses access financial data in real time, make faster decisions, and coordinate easily between branches in Vietnam – China.

In addition, standardizing financial reports according to international standards also helps businesses easily mobilize capital, cooperate in investment or IPO in the future, when financial transparency becomes a key factor of market confidence.

5. From Data to Decision: Turning Accounting Insights into Business Advantage

A good accounting system not only reflects the past but also forecasts the future. When properly analyzed and presented, financial data will become a powerful tool to support leaders in making strategic decisions.

Through indicators of cash flow, personnel cost ratio, investment efficiency and gross profit, businesses can identify risks early, allocate budgets reasonably and optimize operations. This is especially important for technology businesses – where changes occur rapidly and every financial decision directly affects competitiveness.

Therefore, accounting is not just a compliance task, but a strategic foundation to help Chinese technology businesses develop sustainably in Vietnam.

6. Vina TPT Accounting Service – Trusted Partner for Chinese Tech Firms in Vietnam

With more than 10 years of experience serving FDI companies, Vina TPT Accounting Services has become a strategic partner of many Chinese, Korean and Singaporean technology companies operating in Vietnam. We have a team of bilingual English-Vietnamese, who are deeply trained in financial regulations, Vietnamese tax laws and international reporting standards.

Vina TPT experts not only perform accurate operations but also provide strategic consulting: building a standardized financial system, internal control, optimizing costs and supporting businesses in converting to a digital accounting model.

Vina TPT is committed to providing comprehensive, transparent and absolutely confidential accounting services, helping Chinese technology enterprises confidently develop in Vietnam without worrying about legal or operational barriers.

Vina TPT Accounting Service for business – a solid financial foundation for the sustainable growth of Chinese technology enterprises in Vietnam.

BOOK A FREE CONSULTATION

accounting-services-for-chinese-companies

Tax incentives for Korean electronics factories in Vietnam

Korean electronics factory in Vietnam receiving tax incentives

tax-incentives-in-vietnam

1. Why Korean Electronics Manufacturers Choose Vietnam

Tax incentives in Vietnam have played a major role in making the country a top investment destination for Korean electronics corporations such as Samsung, LG, Hanwha, and SK over the past decade. Factors that make Vietnam stand out include competitive labor costs, political stability, a strategic location near the Asian supply chain, and especially the extensive Free Trade Agreements (FTA) system.

In particular, tax incentives in Vietnam for Korean investors have created a strong motivation for long-term manufacturing expansion, especially in high-tech and electronic component production. These incentives not only reduce the initial investment burden but also help Korean enterprises enhance profitability and competitiveness in the regional and global markets.

In addition, the Vietnamese government is actively attracting investment in the high-tech and electronic component manufacturing sectors – this is a great advantage for Korean factories that want to establish long-term manufacturing operations. Therefore, the tax incentives policy in Vietnam is also designed to provide maximum support to this group of businesses.

2. Overview of Tax Incentives in Vietnam for Foreign Manufacturers

Currently, Vietnam is applying many tax incentives in Vietnam for foreign investors, especially in the fields of manufacturing, high technology and industrial zones. These preferential policies are designed to encourage long-term investment and improve the competitiveness of enterprises:

  • Exemption from corporate income tax (CIT) for the first 2-4 years, 50% reduction for the next 4-9 years, depending on the scale and field of investment.
  • Exemption from import tax on machinery, equipment, components to create fixed assets or serve R&D.
  • Land lease incentives in industrial parks, high-tech parks, helping to significantly reduce initial investment costs.

In addition, Vietnam also implements a special tax holiday policy for high-tech manufacturing projects. These are important advantages that help Vietnam become an attractive destination for foreign investors looking for an efficient and stable production environment in the region.

GET TAX INCENTIVE CONSULTATION

3. Tax Incentives for Korean Factories in Vietnam: Key Benefits for Electronics Manufacturing Projects

Korean electronics factories investing in Vietnam often enjoy many outstanding incentives:

  • Corporate Income Tax (CIT): Preferential tax rate of only 10% for 15 years (compared to the standard rate of 20%), with a long tax exemption and reduction period.
  • Import Duty Exemption: Exemption from import tax on machinery, production lines, and components that cannot be produced domestically.
  • Land Rental Incentive: Exemption or reduction of land rent in industrial zones, especially in Bac Ninh, Thai Nguyen, and Hai Phong, where many Korean factories are concentrated.
  • Value Added Tax (VAT) Refund: For exporting enterprises, input VAT is quickly refunded, helping to improve cash flow.

These incentives help Korean electronics factories shorten the payback period and maximize profits during the expansion phase.

4. Compliance and Documentation Required to Access Tax Incentives in Vietnam

To enjoy tax incentives in Vietnam, businesses need to prepare complete documents according to regulations:

  • Investment Certificate (IRC) and Enterprise Registration Certificate (ERC) clearly stating the eligible business lines.
  • Documents proving that the project is in an incentive sector or area.
  • Financial statements, CIT declarations and annual investment activity reports.
  • Relevant import documents, invoices and contracts (for import tax exemptions).

Due to the strict review process, missing documents or incorrect declarations can cause businesses to lose their right to enjoy incentives or be subject to tax arrears.

5. Strategic Tax Planning with Vietnam Tax Specialists for Long-Term Profitability

To make the most of tax incentives in Vietnam, businesses need to build a long-term tax strategy that both ensures compliance with regulations and optimizes financial efficiency. Tax planning is not simply about compliance with obligations, but also a management tool that helps businesses maintain a competitive advantage and develop sustainably in the Vietnamese market.

Tax specialists play an important role in this process by helping businesses restructure their investment models to suit the locations and preferential fields, thereby maximizing tax benefits. They also support businesses in optimizing depreciation policies, transfer pricing and eligible expenses, helping to significantly reduce corporate income tax (CIT) obligations while still complying with regulations. At the same time, tax experts also periodically monitor tax compliance, detect potential risks early and limit the risk of being inspected or administratively sanctioned.

A well-thought-out tax plan not only provides short-term financial benefits, but also lays a solid foundation for future expansion and reinvestment, helping businesses maintain flexibility and stability in a rapidly changing economic landscape.

Download Vietnam Tax Handbook For Investor

6. Partnering with Vina TPT Tax Service for Comprehensive Tax Support and Incentive Application

Vina TPT Tax Service is a trusted tax consulting partner of hundreds of FDI enterprises, including many Korean electronics factories in Vietnam. Our team of experts includes tax consultants and legal experts with over 15 years of experience, with in-depth knowledge of tax regulations, accounting and investment incentives in Vietnam.

Vina TPT provides comprehensive support from:

  • Evaluating eligibility for tax incentives.
  • Preparing and submitting tax exemption/reduction applications.
  • Tax strategy consulting, risk management and periodic compliance audits.

With Vina TPT Tax Service, Korean electronics factories not only ensure compliance with regulations but also optimize costs and sustainable profits in Vietnam.

Contact Vina TPT Tax Service now to get advice from our tax experts on optimal tax incentives and costs for your business in Vietnam.

BOOK A FREE CONSULTATION

tax-incentives-in-vietnam

Business Established in Vietnam for Korean Electronics Manufacturers

Korean investor receiving business license in Vietnam

setting-up-electronics-business-in-Vietnam

1. Vietnam – The Next Hub for Korean Electronics Manufacturers

As Korean companies continue to look for new growth opportunities across Asia, Vietnam has become one of the most attractive destinations for manufacturing expansion. With a favorable investment climate and a streamlined business license in Vietnam process for foreign enterprises, Vietnam offers Korean electronics manufacturers an ideal entry point to establish long-term operations. Supported by government incentives and a robust supply chain ecosystem, the country is quickly evolving into a major production hub in the region.

Major corporations such as Samsung, LG, and Hanwha have established large-scale production complexes in Bac Ninh, Thai Nguyen, and Hai Phong, regions that are rapidly becoming Vietnam’s key electronics hubs, supported by modern logistics networks, seaports, and government investment incentives.

Moreover, Vietnam’s active participation in free trade agreements such as CPTPP and EVFTA has unlocked significant tariff advantages, enhancing its competitiveness in the global supply chain. A young, skilled workforce combined with the nation’s push for digital transformation positions Vietnam as the “new manufacturing base” for the global electronics industry, much like South Korea’s industrial rise in the 1990s.

For Korean investors, establishing a business in Vietnam not only optimizes production costs but also opens access to ASEAN, China, and India markets. By obtaining the appropriate business license in Vietnam and leveraging professional strategic consulting, Korean electronics enterprises can streamline the enterprise registration process and transform Vietnam into a sustainable hub for manufacturing and innovation in the region.

2. Strategic Considerations Before Enterprise Registration in Vietnam

Before starting the registration process, investors need to carefully consider strategic factors.

Location is key: Northern regions such as Bac Ninh, Hai Phong, Thai Nguyen currently have many Korean electronics factories, convenient for connecting and sharing the supply chain.

Legal form also directly affects the right to operate and tax obligations. Enterprises can choose to establish a 100% foreign-owned company, joint venture with a Vietnamese partner or open a representative office.

In addition, the domestic supply chain in Vietnam is expanding rapidly, providing components and logistics services suitable for electronics production. Understanding these factors helps Korean enterprises optimize costs and limit risks when entering new markets.

Book a Free Consultation on Your Business License

3. Understanding Business License in Vietnam and Compliance for Electronics Companies

After being granted the Investment Registration Certificate (IRC) and Enterprise Registration Certificate (ERC), the electronics enterprise needs to apply for a business license appropriate to the field of operation.

The electronics manufacturing industry has its own requirements on environmental safety, technology standards and fire prevention.

The estimated time for completion is:

Document preparation: 1-2 weeks, depending on the volume of documents and the level of complexity.

  • IRC appraisal: 20-45 working days.
  • ERC issuance: 10-20 working days after IRC (or similar if the enterprise is a domestic enterprise).

In fact, if the enterprise cooperates with a reputable company registration service, it will help the enterprise quickly handle the consular legalization, translation and submission of documents, shortening the time and increasing the possibility of being licensed the first time.

setting-up-electronics-business-in-Vietnam

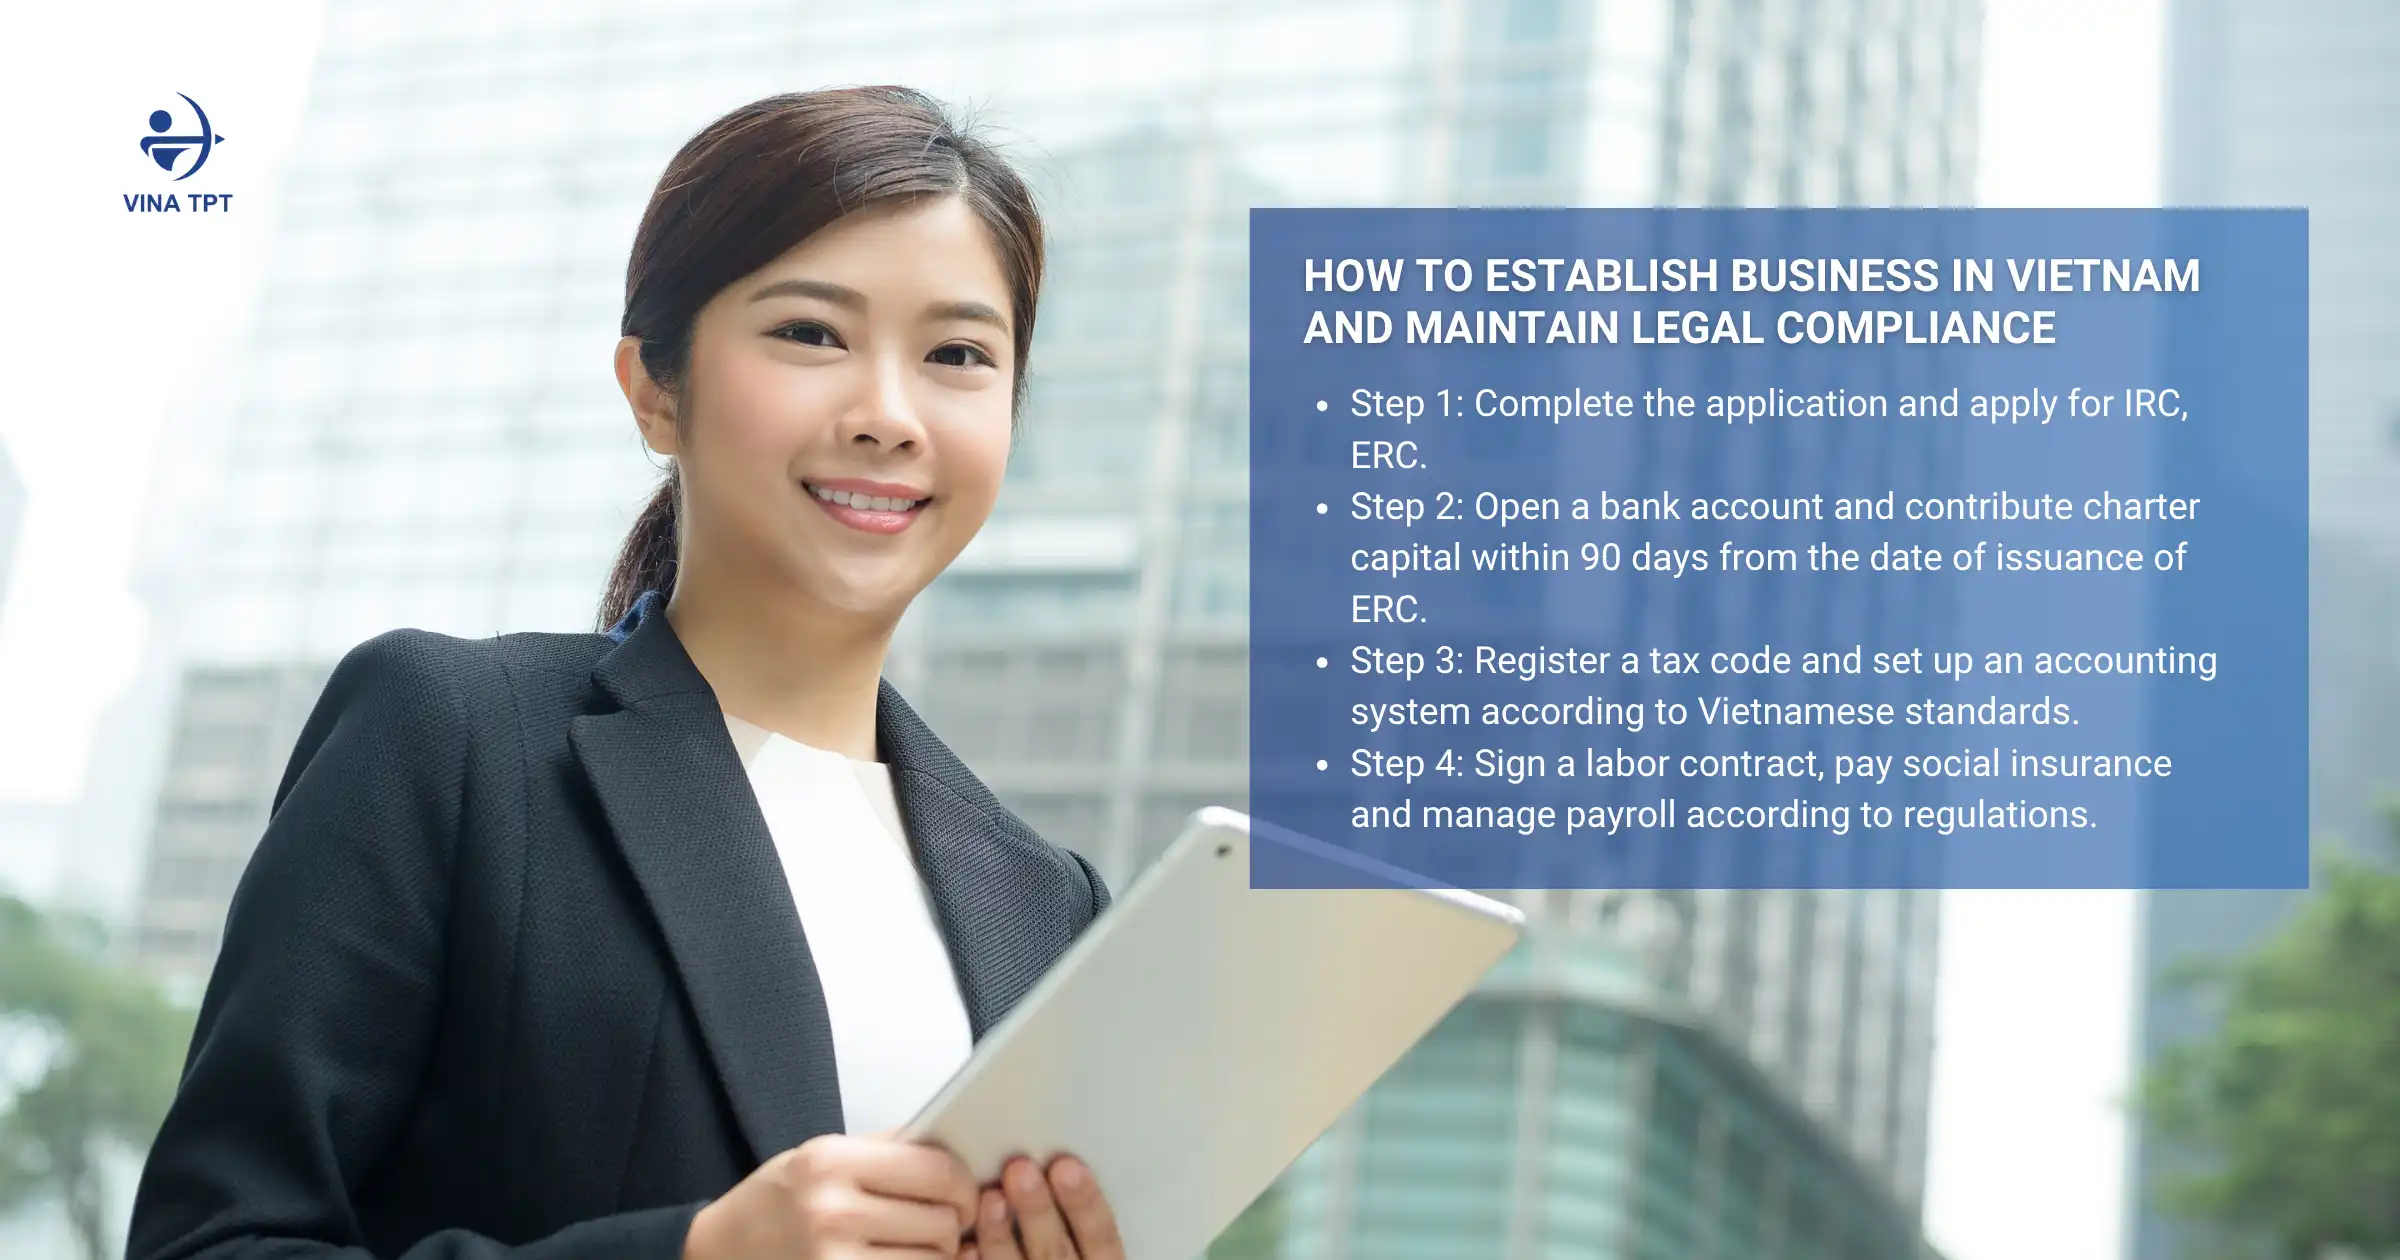
4. How to Establish Business in Vietnam and Maintain Legal Compliance

To successfully establish a business in Vietnam, investors need to take the following important steps:

Step 1: Complete the application and apply for Business License in Vietnam IRC, ERC.

If the project has FDI capital, IRC is the first license allowing the investor to implement the project in Vietnam.

The required documents usually include:

  • Application for investment project implementation and Project proposal: stating the objectives, scale, location, investment capital, progress.
  • Proof of the investor’s financial capacity: bank statement, credit contract or collateral.
  • Legal documents of the investor:
    • Individual: Notarized passport, consular legalization.
    • Organization: Business registration certificate or equivalent document, consular legalization.
  • Project location: lease contract or land/office use rights certificate.

After the IRC is granted (or for 100% domestic-owned enterprises), the investor applies for an ERC – an official license for the enterprise to operate, and also the tax code of the company.

The ERC dossier usually includes:

  • Application for enterprise registration.
  • Company Charter: stipulates the organizational structure, powers of members/shareholders, capital ratio and management method.
  • List of members/shareholders and legal representatives: clearly state information, ownership ratio, voting rights.
  • Appointment decision and authorization letter (if any).
  • Capital contribution plan & financial evidence: bank statement or credit contract (especially important for large capital projects).

Step 2: Open a bank account and contribute charter capital within 90 days from the date of issuance of ERC.

Step 3: Register a tax code and set up an accounting system according to Vietnamese standards.

Step 4: Sign a labor contract, pay social insurance and manage payroll according to regulations.

5. Vina TPT Company Registration – Partnering with Korean Electronics Manufacturers for a Sustainable Setup

With more than a decade of experience in investment consulting and business registration services, Vina TPT has successfully assisted hundreds of FDI enterprises, including a large number of Korean electronics manufacturers in establishing and expanding their operations in Vietnam.

Our comprehensive service scope covers every stage of the process — from investment model consulting and legal documentation, to business license application in Vietnam, business license renewal, and regulatory compliance. This integrated approach ensures a smooth and compliant market entry for Korean investors.

Backed by a team of seasoned professionals with in-depth knowledge of Vietnam’s business, tax, and labor laws, Vina TPT provides end-to-end business license advisory and compliance support, helping investors confidently execute their projects while focusing on production growth and long-term success.

Partnering with Vina TPT Business Advisory and Company Registration means more than saving time and costs. It’s about having a trusted local partner who truly understands how to help Korean investors establish, operate, and sustain successful ventures in Vietnam.

Contact Vina TPT for consultation and support on business registration in Vietnam quickly, legally and at optimal cost.

BOOK A FREE CONSULTATION

setting-up-electronics-business-in-Vietnam

VAT Refund in Vietnam 2025: Updated Conditions and Eligible Cases Explained

VAT Refund in Vietnam 2025 Updated Conditions and Eligible Cases Explained-VTPT

VAT Refund in Vietnam 2025_ Updated Conditions and Eligible Cases Explained - VTPT

1.What is a VAT Refund and When is a Business Entitled to it?

Value-Added Tax (VAT) refund refers to the process by which the State reimburses the amount of VAT that a business has either paid into the State budget or has not yet been deducted. When a business meets specific VAT refund conditions, it will be entitled to receive back the paid tax amount. The purpose of this policy is to prevent double taxation and to support businesses in investment or export activities.

Businesses are eligible for VAT refunds when they fall under the cases stipulated by law and meet the specific refund conditions applicable to their business type. Detailed information will be provided by Vina TPT in this article.

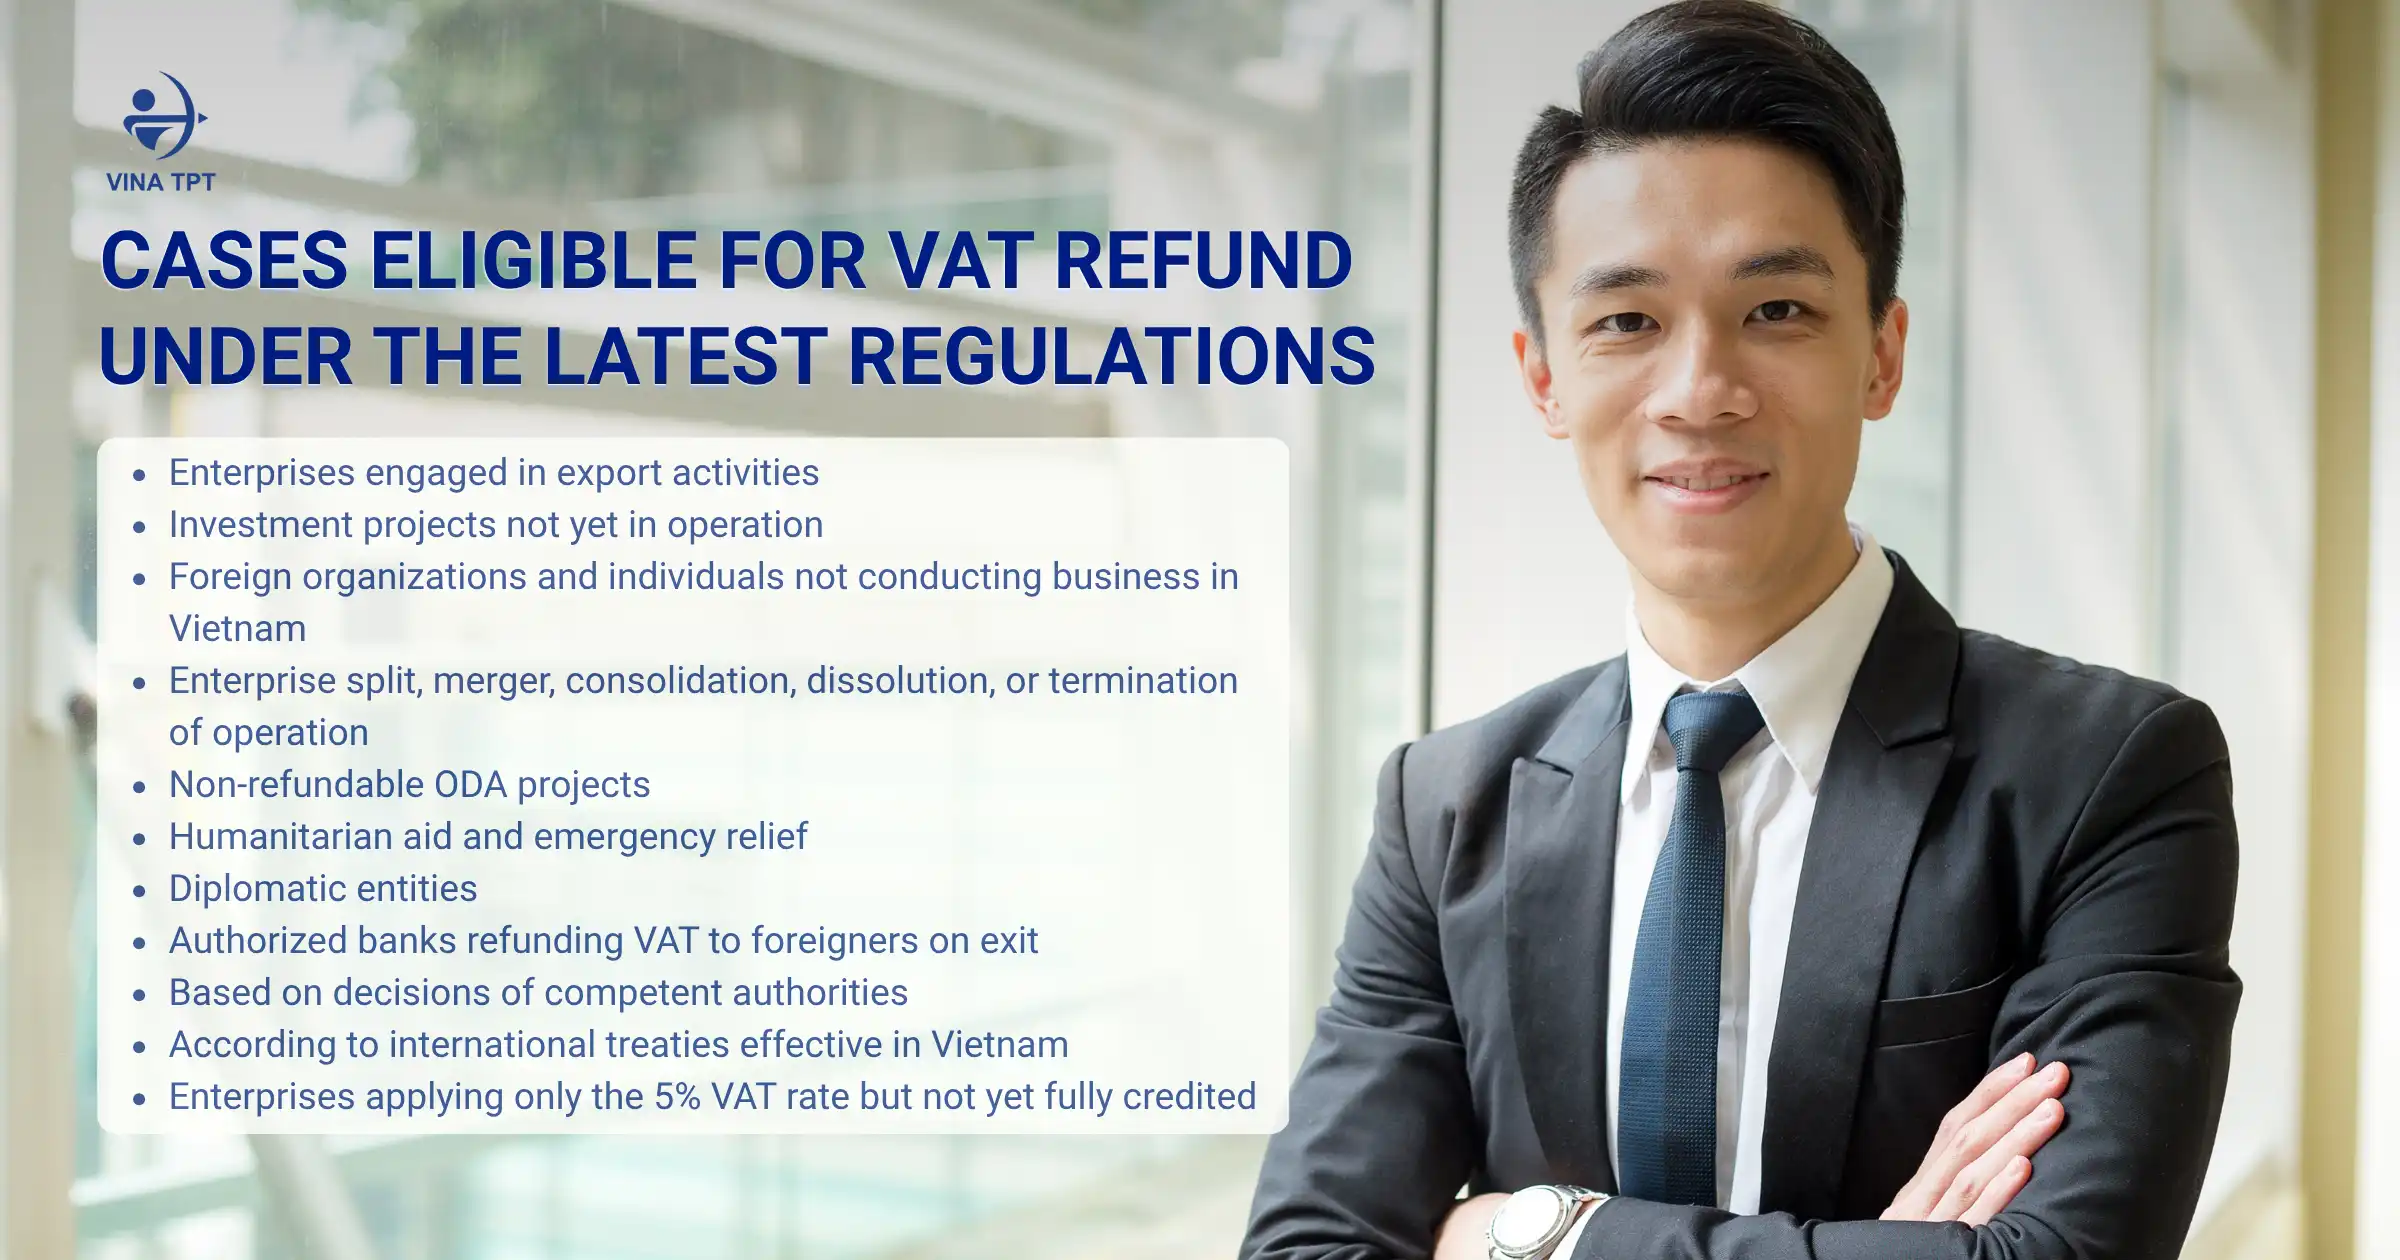
2.Cases Eligible for VAT Refund Under the Latest Regulations

VAT Refund in Vietnam 2025_ Updated Conditions and Eligible Cases Explained - VTPT

No.  Case eligible for VAT refund  Main conditions  Legal basis 
1  Enterprises engaged in export activities  Exported goods and services are subject to a 0% VAT rateInput VAT not yet credited is ≥ VND 300 million

Must have valid customs documents and bank payment records 

Article 13, VAT Law 2024 
2  Investment projects not yet in operation  The investment project has been duly registeredNo revenue has been generated

Input VAT not yet credited is ≥ VND 300 million 

Article 13, VAT Law 2024 
3  Enterprise split, merger, consolidation, dissolution, or termination of operation  The enterprise no longer operates to deduct input VATRemaining input VAT has not yet been credited  Article 13, Amended VAT Law 2008 
4  Foreign organizations and individuals not conducting business in Vietnam  Possess valid tax payment documentsDo not conduct regular business activities in Vietnam  Circular 219/2013/TT-BTC, Article 18 
5  Non-refundable ODA projects  Not using the state budget to pay VATPossess valid confirmation from the donor  VAT Law 2024, Circular 219 
6  Humanitarian aid and emergency relief  Must have a decision approving the receipt of aidMust provide valid documents related to goods and input invoices  Circular 219/2013/TT-BTC 
7  Đối tượng ngoại giao (miễn trừ)  Must have confirmation from the State Protocol DepartmentApplied under international treaties  Decree 134/2016/NĐ-CP 
8  Authorized banks refunding VAT to foreigners on exit  Must have a goods management systemMust prepare a tax refund list according to the prescribed form  Circular 92/2019/TT-BTC 
9  Based on decisions of competent authorities  Must have an official document/decision on tax refundApplied in special cases, subject to post-refund inspection  Decree 49/2022/NĐ-CP 
10  According to international treaties effective in Vietnam  Must fall under subjects clearly stated in the treatyMust provide complete dossiers and supporting documents  Law on International Treaties, Law on VAT 
11  Enterprises applying only the 5% VAT rate but not yet fully credited  Input VAT not yet credited ≥ 300 million VNDAfter 12 months or 4 consecutive quarters – applicable from 01/07/2025  Amended VAT Law 2024

 VAT 2025 Update:: The 2024 Value Added Tax (VAT) Law will officially take effect from July 1, 2025.

3. Conditions for VAT refund

Depending on the type of enterprise, the conditions for VAT refund may vary

3.1. For domestic enterprises 

  • Undeducted input VAT of at least VND 300 million
  • Có Valid e-invoices andnon-cash payments for invoices from VND 20 million
  • Not under tax enforcement measures or committing tax violations
  • Proper and timely tax declaration 

3.2. For exporting enterprises 

  • Export contracts, customs declarations, and bank payment documents 
  • Continuous undeducted VAT for 3 periods or at least VND 300 million in one period
  • Exported goods must be cleared through customs
  • No fraudulent invoice transactions 

Note: From 2025, under the amended VAT Law, exporters with undeducted VAT over VND 100 million in a period may apply for refund earlier, reducing waiting time.

3.3. For investment projects 

  • Must have an Investment Registration Certificate 
  • No revenue generated, but large undeducted VAT incurred 
  • Separate bank account for the project 
  • Separate accounting for project expenses 

3.4. For foreign organizations/individuals 

  • Valid proof of VAT paid in Vietnam 
  • Non-regular business activities 
  • Full compliance with tax declaration and refund procedures 

Explore Our Tax Services

 4. Cases Not Eligible for VAT Refund

(According to Circular 219/2013/TT-BTC, amended by Circular 130/2016/TT-BTC)

  • Investment projects with insufficient charter capital contribution
    If, by the time of filing the VAT refund application (from July 1, 2016 onwards), the enterprise has not contributed the full registered charter capital it will not be eligible for refund. Instead, the uncredited input VAT will only be carried forward to the next CIT period.
  • Conditional investment sectors not meeting requirements under the Law on Investment
    This includes cases where the enterprise has not obtained the necessary license, certificate of eligibility, or written approval from the competent authority.  
  • Violation of conditions during project implementation
    If, during the implementation, the project has its license or certificate revoked, or is found no longer to meet conditional business requirements, VAT refund will be suspended from that point onward.  
  • Projects involving natural resource/mineral exploitation or production with ≥ 51% cost structure derived from natural resources
    Applicable to projects licensed from July 1, 2016. The determination of the resource ratio is guided under Clause 23, Article 4 of Circular 219.  
  • Imported goods for export but not exported through the prescribed customs area
    VAT refund is not eligible if export procedures are not carried out at the designated customs office.  
  • Exported goods not completing customs procedures at the customs-controlled area
    In this case, VAT refund is also not eligible. 

5. Key Notes on VAT Refund for Businesses

  • Do not consolidate VAT refund applications across multiple periods unless specifically guided by regulations. 
  • Carefully check the payment timeline and payment conditions of each invoice. 
  • For exporting enterprises, clearly keep records of customs declarations, bills of lading, and payment documents.
  • Always review the validity of input invoices – especially those from new suppliers. 

6. Simplify Your VAT Refund with Vina TPT’s Professional Support

Navigating the VAT refund process in Vietnam can be complex, especially with changing tax regulations and documentation requirements. Vina TPT offers professional support to help businesses simplify every step, from eligibility assessment to refund application and follow-up with tax authorities. With deep expertise in Vietnamese tax law, our team ensures accuracy, compliance, and maximum refund value for your company. Partnering with Vina TPT means saving time, avoiding costly errors, and gaining peace of mind knowing your VAT refund is handled by trusted professionals. Let Vina TPT streamline your refund process efficiently and transparently.

Contact Vina TPT today to simplify your VAT refund process!

Discuss Your Case with Our Specialists

accounting skills

Tax Incentive in Vietnam 2025: Comprehensive Guide to Optimize Profits under New CIT Law

Overview of corporate tax incentives in Vietnam 2025 under the new CIT Law

Overview of corporate tax incentives in Vietnam 2025 under the new CIT Law

Tax Incentive: Comprehensive Guide to Corporate Tax Incentives in Vietnam 2025 – Optimize Profits with New CIT Law

With Vietnam’s Corporate Income Tax (CIT) Law 2025 officially in force from October 1, 2025, investors and CFOs are reassessing how to leverage tax incentives to strengthen profitability and compliance.

From 10 – 17% preferential CIT rates to multi-year tax holidays, the new regime gives both domestic and foreign companies more tools to optimize profits but only if you understand the rules.

In this guide, you’ll learn:

  1. What a tax incentive is and why it matters for 2025
  2. The main types of corporate tax incentives available in Vietnam
  3. Key eligibility requirements and risk management
  4. How to prepare and apply effectively with professional support

I. What is a Tax Incentive and Why Do Businesses Need to Know in 2025?

A tax incentive is a government policy designed to reduce or exempt tax liabilities for businesses that invest in targeted sectors or locations, with the aim of encouraging sustainable growth, innovation, and foreign direct investment (FDI).

Under the CIT Law 2025, tax incentives in Vietnam have evolved to:

  • Support the digital economy and green/clean industries.
  • Attract FDI via extended tax breaks and preferential schemes.
  • Motivate companies to reinvest profits inside Vietnam rather than only extracting them.

In today’s competitive ASEAN environment, understanding tax incentives isn’t optional, it’s a survival and growth strategy.

The standard corporate income tax rate remains 20 %. However, preferential rates are flexibly applied:

  • 15 % for enterprises with annual revenue ≤ VND 3 billion
  • 17 % for enterprises with revenue over VND 3 billion up to VND 50 billion
  • In specific cases (e.g., foreign-owned enterprises, cooperatives…) where cost/expense determination is difficult, a direct tax rate on revenue may apply

II. Key 2025 Updates: Major Types of Corporate Tax Incentives in Vietnam

Key Corporate Tax Incentives in Vietnam 2025

1. Expanded deductible expenses under the 2025 CIT Law

Enterprises are now allowed to deduct additional expenses related to scientific research, digital transformation, testing new technologies, emission reduction, and community activities. This aims to create favorable conditions for businesses to pursue sustainable growth and innovation.

2. Incentives by sector, location, and investment project

Investment projects in high-tech sectors such as semiconductor production, AI, data centers, automobile manufacturing, and electronic device production are eligible for a preferential tax rate of 10% for up to 15 years.
Expansion projects applying clean technologies or contributing to environmental improvements may also qualify for tax exemptions or reductions if they meet specific requirements.

3. Clear incentive rules to avoid overlapping

If an enterprise falls under multiple incentive categories, it has the right to choose the most favorable one.
In cases where preferential provisions exist under specialized laws, the 2025 CIT Law will take precedence, except for specially regulated circumstances.

4. Loss carry-forward and Science & Technology Development Fund

Enterprises are allowed to carry forward losses continuously for up to 5 years.
They may allocate up to 20% of annual taxable income to establish a Science & Technology Development Fund, provided it is used for the correct purposes.

To explore how our consulting team can help you secure and optimize CIT incentives effectively, visit our dedicated Tax Consulting Service page for more details.

Explore Tax Consulting Services

III. Common Mistakes and How to Avoid – Plus Profit Optimization

Even with the best intentions, many businesses still miss out on their tax incentive benefits due to simple yet costly mistakes. Below are the most common pitfalls and how to fix them effectively.

  1. Late or incomplete applications: One of the most frequent issues arises from delayed or missing documentation.
    How to avoid: Ensure all required forms and supporting evidence are submitted before your project begins generating income to maintain eligibility.
  2. Ignoring Permanent Establishment (PE) rules: With the 2025 update redefining PE status, overlooking this change can lead to unexpected tax liabilities.
    How to avoid: Reassess your operational and contractual structure under the new PE definition to avoid misclassification.
  3. Overlooking Double Taxation Treaties (DTT): Many foreign investors fail to leverage DTT benefits, leading to duplicate tax payments.
    How to avoid: Coordinate early with professional consultants to utilize DTT relief and minimize cross-border tax exposure.
  4. Unclear bookkeeping and expense tracking: Incomplete financial records can weaken your eligibility for incentives and invite compliance risks.
    How to avoid: Implement digital accounting and reporting systems to ensure transparency and traceability.
  5. No profit optimization strategy: Securing an incentive is only the first step, maximizing its impact requires strategic planning.
    How to avoid: Partner with Vina TPT’s tax consultants to align your incentive structure with long-term financial goals and ROI optimization.

IV. What Should Businesses Prepare to Seize Opportunities from the 2025 CIT Law?

To stay ahead of regulatory changes and fully capitalize on new incentives, businesses must prepare proactively and strategically:

  • Review and assess impact: Conduct a detailed analysis of current financial performance, income, expenses, and business operations. Identify any necessary adjustments to comply with the new Corporate Income Tax (CIT) Law.
  • Understand eligibility criteria for incentives: Study the specific requirements for benefiting from the 2025 CIT incentives. Ensure your business meets all conditions before submitting any application.
  • Update accounting and financial systems: Make sure your accounting software and bookkeeping procedures comply with new regulations on revenue and expense recognition.
  • Train internal teams: Equip your finance and accounting personnel with updated knowledge through training sessions or specialized CIT 2025 courses.
  • Seek expert consultation: Engaging professional tax advisors is a smart move to avoid compliance risks and legally optimize your tax obligations.

Instead of navigating complex tax regulations on your own, you can connect directly with VINA TPT – trusted partner specializing in tax, accounting, and financial consulting ready to support your business in maximizing benefits under the 2025 CIT Law.

Conclusion

Tax incentives in Vietnam are more than just government policy, they’re a strategic growth lever for businesses preparing to thrive in the 2025 landscape.

Key takeaways:

  • Vietnam offers preferential CIT rates of 10 – 17% for up to 30 years.
  • Incentives now extend to green, digital, and financial sectors.
  • Compliance and timing remain critical to securing approval.

V. Why Partnering with Vina TPT Is the Most Effective Way to Leverage Tax Incentives?

The 2025 CIT incentives offer substantial opportunities to reduce tax burdens and enhance profits, but leveraging them effectively isn’t always simple. Businesses must interpret complex eligibility criteria, prepare accurate documentation, and meet strict compliance deadlines. Without expert guidance, it’s easy to miss optimal incentive schemes or face regulatory risks. That’s why partnering with a professional tax consulting firm becomes a strategic advantage.

Vina TPT Tax Service is a trusted advisor to hundreds of FDI and domestic enterprises, including manufacturing, technology, and service companies across Vietnam. Our team consists of senior tax consultants and legal experts with over 15 years of experience in tax planning, accounting compliance, and investment incentives.

We provide end-to-end support, including:

  • Assessing eligibility for tax incentives under the 2025 CIT Law
  • Structuring incentive applications for maximum tax savings
  • Preparing and submitting exemption/reduction dossiers
  • Designing long-term tax strategies aligned with business growth objectives
  • Conducting compliance audits and managing tax risks

With Vina TPT Tax Service, businesses are not only compliant but also positioned to optimize costs and secure sustainable profitability through legally maximized tax benefits.

Contact Vina TPT today and ensure your business fully capitalizes on Vietnam’s 2025 tax incentive opportunities.

Contact Vina TPT for Consultation

Expert-Vietnam-VinaTPT

Tax Breaks in Vietnam 2025 | Key CIT, VAT & PIT Updates

1/ Overview of Tax Breaks and Their Importance for FDI Businesses 

Tax breaks, also known as tax incentives, are government measures that reduce or exempt taxes to support businesses and individuals. These aim to boost investment, drive economic growth, and ease financial burdens. In Vietnam, tax breaks typically include exemptions, reduced rates, or deductible expenses. They help companies lower operating costs, boost net profits, and expand operations—especially amid post-pandemic recovery and global competition. 

For foreign direct investment (FDI) businesses, tax breaks serve as both financial tools and strategic advantages to attract capital. Under the 2025 Corporate Income Tax Law (No. 67/2025/QH15), these policies align with international commitments like the 15% global minimum tax. This creates competitive edges, encourages reinvestment, and generates jobs in Vietnam. 

Here’s a summary of key benefits for FDI businesses: 

  • Reduced operating costs: Save 10-15% on tax obligations, improving cash flow. 
  • Increased profits: Support expansion in production and research and development (R&D). 
  • Talent attraction: PIT tax breaks lower taxes for foreign experts. 
  • Sustainability support: Promote investments in green sectors and high-tech industries. 

Explore the common tax breaks available in Vietnam to maximize benefits for your FDI enterprise. 

2/ Common Types of Tax Breaks Currently Available 

Vietnam’s government is refining tax policies to aid businesses during economic recovery, focusing on priority sectors like technology, green manufacturing, and exports. Starting in 2025, incentives apply to key taxes: Corporate Income Tax (CIT), Value-Added Tax (VAT), and Personal Income Tax (PIT). Each targets different groups and goals, helping FDI businesses cut financial loads and enhance competitiveness. Below is a comparison table: 

Tax Type  Main Incentives  Applicable Entities  Duration 
CIT  Exemption for 2-4 years, 50% reduction thereafter  FDI businesses in priority sectors  6-15 years 
VAT  Reduction from 10% to 8%  Goods and services (exclusions apply)  Until December 31, 2026 
PIT  Family deduction of VND 11 million/month (rising to VND 15.5 million/month from 2026)  Individuals and foreign experts as residents  Annual 

2.1 Corporate Income Tax (CIT) Incentives Effective from October 1, 2025 

Corporate Income Tax (CIT) directly impacts FDI business profits. From October 1, 2025, the 2025 CIT Law (No. 67/2025/QH15) expands incentives to attract high-quality investments. FDI enterprises starting new projects in high-tech fields, disadvantaged areas, or economic zones qualify for CIT exemptions for 2-4 initial years and a 50% reduction for the next 4-9 years. Preferential rates can drop to 10% for specially prioritized projects, 15% for small and medium enterprises, or 17% for investments in favored locations. 

Incentives are categorized by: 

  • Sector: High-tech, education, healthcare—exemption for 4 years, 50% reduction for 9 years. 
  • Location: Disadvantaged areas—10% rate for 15 years. 
  • Investment scale: Projects over EUR 750 million apply the 15% global minimum tax. 

Summary table: 

Incentive Type  Conditions  Duration  Reduction Level 
Exemption  High-tech projects  4 years  100% 
Rate reduction  Favored locations  15 years  10-17% 
50% reduction  New investment projects  4-9 years  50% 

Impact on FDI businesses: 

  • Cost savings up to 20-30%, boosting net profits and reinvestment. 
  • Encourages production growth and local job creation. 

Example: An FDI company investing USD 100 million in a high-tech zone could save tens of millions in taxes over the first 10 years. 

FDI enterprises should consult tax experts early to ensure proper reporting, legal workforce use, and eligibility maintenance. Compliance from the start avoids audits, penalties, and maximizes legal tax breaks. 

Maximize Your Tax Incentives Today

2.2 Value-Added Tax (VAT) Incentives Effective from July 1, 2025 

From July 1, 2025, Decree 174/2025/ND-CP reduces Value-Added Tax (VAT) from 10% to 8% until December 31, 2026, to stimulate consumption and support business recovery. This applies to most goods and services, excluding telecommunications, finance, and real estate. For FDI businesses, VAT tax breaks lower input costs, enhance cash flow, and strengthen export competitiveness. 

Specific benefits: 

  • Lower production costs: Imported materials face reduced VAT. 
  • Export support: Exported goods at 0% VAT, plus 8% reduction on related services. 

Example: An FDI firm exporting high-tech software enjoys full VAT exemption, saving 8-10% on costs. 

Key procedures: 

  • Declare VAT using new forms and electronic invoices. 
  • Collect valid documents for deductions or refunds. 
  • Note: Does not apply to specially taxed imports. 

2.3 Personal Income Tax (PIT) Incentives 

Personal Income Tax (PIT) continues to directly impact the income of workers, especially foreign experts in FDI enterprises.
From 2026, the personal allowance has been adjusted upwards to VND 15.5 million/month for the taxpayer themselves and VND 6.2 million/month for each dependent. This increase in allowances helps reduce tax obligations, improve disposable income, and enhance the attractiveness of the Vietnamese labor market.
At the same time, the PIT tax schedule has been simplified, reduced from 7 brackets to 5, with progressive tax rates.

PIT tax breaks for FDI businesses: 

  • Reduced taxes for foreign experts: Residents (present in Vietnam 183+ days/year) get deductions, cutting personnel costs. 
  • Exemptions for certain income: Stock transfers (if qualified) and foreign allowances. 

Notes: 

  • Register dependents electronically with tax authorities. 
  • Update income regularly to prevent back taxes. 

From 2026, updated policies will help FDI firms attract top global talent more easily. 

Download Vietnam Tax Handbook For Investor

3/ Key Benefits: How Tax Breaks Help Save Costs and Expand Business 

Tax breaks directly cut tax liabilities, increasing net profits and providing capital for FDI businesses to reinvest. Experts estimate savings of 10-20% on overall costs, enabling scale-up and global competition. 

Analysis from three angles: 

  • Financial: CIT and VAT reductions improve cash flow and reduce quarterly tax debts. 
  • Strategic: Encourage investments in priority areas like green technology, enhancing brand value. 
  • Human resources: PIT incentives lower salary costs, aiding recruitment of international and local experts. 

In summary, tax breaks not only save costs but also unlock business growth, allowing FDI enterprises to contribute sustainably to Vietnam’s economy. 

4/ Leveraging Tax Breaks with Vina TPT Tax Services 

To fully utilize tax breaks, FDI businesses need professional guidance from firms like Vina TPT—a Vietnam-based expert in tax and accounting. With experience supporting hundreds of FDI clients, Vina TPT identifies suitable incentives, prepares compliant files, and handles timely declarations to avoid audits. 

Standout advantages: 

  • Expertise across industries, from manufacturing to technology. 
  • Team knowledgeable in Vietnamese and international tax laws, with multilingual support. 
  • Transparent reporting and competitive fees for cost optimization. 

Support process: 

  • Assess your business and identify applicable incentives. 
  • Recommend tax plans and prepare registration documents. 
  • Implement declarations and monitor policy updates. 
  • Conduct regular reviews for ongoing compliance. 

Tax breaks are essential for FDI businesses in Vietnam to optimize costs, boost profits, and expand investments—especially with 2025 updates like the 8% VAT reduction and CIT incentives for priority sectors. These changes support economic recovery and position Vietnam as an attractive destination for foreign investment. 

Has your business maximized current tax incentives? Contact Vina TPT Tax Services today for a detailed analysis and tailored tax solutions—ensuring compliance and maximum savings! 

Talk to a Tax Specialist

Vina TPT Accounting services