


The list of foreign contractors registered for tax in Vietnam has officially surpassed 300 global enterprises, marking a fundamental transformation in cross-border tax administration since the General Department of Taxation launched its dedicated e-portal (etaxvn.gdt.gov.vn) under Circular 80/2021/TT-BTC. This compliance framework standardizes operations for global technology corporations in Vietnam while removing the withholding and reporting burdens formerly imposed on tens of thousands of domestic enterprises and foreign-invested enterprises (FIEs) procuring international services.
1. Legal Framework: Determining Foreign Contractor Tax (FCT) Obligations
When procuring digital or cross-border services from foreign entities, corporate accounting and tax teams must accurately classify the supplier under one of the two statutory categories:
Category 1: Foreign Contractor IS directly registered for tax in Vietnam
- Identification: The foreign contractor is issued a 10-digit tax identification number (TIN)—typically prefixed with 9000…—and directly files and settles Value Added Tax (VAT) and Corporate Income Tax (CIT) periodically via the General Department of Taxation portal.
- Obligation of the Vietnamese Buyer: Exempt from withholding, filing, or paying FCT on behalf of the foreign supplier under Circular 103/2014/TT-BTC.
Category 2: Foreign Contractor is NOT directly registered for tax in Vietnam
- Obligation of the Vietnamese Buyer: The local enterprise must compute, withhold, and declare FCT (VAT and CIT components) prior to executing outward remittances to the overseas vendor, subsequently remitting the withheld taxes to the state budget in accordance with statutory deadlines.
2. Representative Overseas Suppliers Registered for Direct Tax Filing
As cross-border digital transactions continue to expand, the official list of foreign contractors registered via the General Department of Taxation’s electronic portal is continuously updated. Recent quarters have seen a notable wave of international SaaS providers, enterprise development tools, digital travel platforms, and next-generation AI platforms formalizing their tax obligations directly with Vietnamese tax authorities.
For corporate finance and accounting teams, tracking these newcomers across the list of foreign contractors registered with local tax authorities is essential to avoid unnecessary withholding on compliant partners or administrative oversights during month-end expense reconciliation. The table below highlights notable international contractors that have recently completed their direct tax registration:
| Legal Entity Name | Tax Code (TIN) | Industry / Platform | Effective Date |
| CFI EDUCATION INC. | 9000591158 | Professional E-Learning (Corporate Finance Institute) | 22/10/2026 |
| Replit, inc | 9000591119 | Cloud Development & Collaborative AI IDE | 19/10/2026 |
| AIRGSM PTE. LTD | 9000591101 | Telecommunications & Global Travel eSIM (Airalo) | 19/10/2026 |
| STRAVA, INC. | 9000590997 | Fitness Tracking & Subscription Services | 12/10/2026 |
| SOUNDCLOUD GLOBAL LIMITED & Co. KG | 9000590690 | Digital Audio & Music Streaming | 24/09/2026 |
| Photoroom | 9000590394 | Generative AI Image Editing & Enterprise APIs | 10/09/2026 |
| RTB Marketing & Tech Services Ltd | 9000590355 | Programmatic Advertising & AdTech Infrastructure | 09/09/2026 |
| Travelscape, LLC | 9000590323 | Online Travel Distribution (Expedia Group) | 07/09/2026 |
| Amazon Advertising Canada, Inc. | 9000590242 | Digital Advertising & E-Commerce Media Services | 04/09/2026 |
| Lovable Labs Incorporated | 9000590235 | Full-Stack Generative AI Software Development | 04/09/2026 |
For internal audits, invoice cross-referencing, and rapid TIN lookup, download the standardized dataset of 300+ registered foreign entities:
DOWNLOAD The Master List of 300+ Registered Foreign Contractors3. Requirements for CIT Deductibility for Vietnamese Companies
To claim payments made to directly registered overseas suppliers as deductible expenses for CIT purposes, businesses must maintain a cohesive audit trail:
-
Service Contract or Online Terms of Service (ToS): The executed bilateral contract or an archived digital agreement accepted upon corporate account activation.
-
Commercial Invoice / Receipt: An invoice issued directly by the foreign contractor displaying:
-
Description of the service rendered, billing period, and billed currency/amount.
-
The supplier’s Vietnamese 10-digit tax identification number (
9000...). -
Registered corporate name, official address, and tax code of the purchasing enterprise in Vietnam.
-
-
Non-Cash Payment Documentation:
-
Bank debit advice / payment order originating from the buyer’s corporate bank account; or
-
Corporate credit card statement bearing the company’s name, accompanied by verified electronic payment confirmations.
-
-
Supplier Tax Status Verification Record: A timestamped portal lookup screenshot or printed PDF generated from the General Department of Taxation portal corroborating the supplier’s active tax code at the transaction date.
>>> See more: Vietnam Foreign Contractor Tax: Ultimate Guide for 2025
4. 3-Step Verification Guide on the General Department of Taxation Portal
To cross-check whether your vendor appears on the current list of foreign contractors registered for direct tax filing—and ensure your company is legally exempt from withholding FCT—finance teams can verify real-time status in three steps:
- Step 1: Access the official General Department of Taxation e-portal for foreign contractors: etaxvn.gdt.gov.vn.
- Step 2: Select the module “Taxpayer Information Inquiry” (Tra cứu thông tin người nộp thuế).
- Step 3: Enter the 10-digit tax code or the official legal name as registered on the commercial invoice (do not use abbreviations or trade aliases). The system will return the tax registration date, official corporate headquarters, and current operational status.
5. Key Compliance Considerations for Accounting & Tax Teams
- Brand vs. Legal Entity Discrepancy: Multinationals routinely contract through regional subsidiaries across different jurisdictions. Withholding exemptions apply strictly when the invoice is issued by the exact legal entity registered with a Vietnamese tax code. If a transaction is invoiced by an unregistered affiliate under the same parent brand, local FCT withholding obligations remain mandatory.
- Point-in-Time Liability Assessment: Tax exposure is determined by the contractor’s status at the time of payment execution or expense recognition. Verification should be documented concurrently with payment approvals.
- Dynamic Master File Updates: New foreign contractors complete direct tax registrations quarterly. Accounting departments should maintain and review their internal approved vendor lists periodically to avoid inadvertent withholding on compliant suppliers or non-compliance penalties on unregistered vendors.
(Compiled, structured, and cross-referenced based on the official administrative list of foreign contractors registered under the Portal for Overseas Suppliers – General Department of Taxation of Vietnam).
Foreign direct investment (FDI) enterprises and multinational corporations operating in Vietnam operate under strict regulatory scrutiny regarding Transfer Pricing Vietnam compliance. The General Department of Taxation actively identifies profit shifting, scrutinizes cross-border transactions, and targets artificial margin compression.
At the center of this enforcement architecture stands Decree 132/2020/ND-CP, which establishes rigorous documentation standards aligned with the OECD’s Base Erosion and Profit Shifting (BEPS) Action 13 framework. Navigating these requirements demands meticulous preparation: failure to maintain compliant contemporaneous files exposes taxpayers to severe tax reassessments, aggressive expense disallowance, and statutory penalties.
Key Takeaways for Taxpayers:
- Decree 132 applies to all domestic and cross-border related-party transactions (RPTs).
- Net interest expense deductions are capped at 30% of EBITDA across all debt instruments once RPTs exist.
- Compliance mandates both annual disclosure forms and a contemporaneous three-tiered documentation package.
- Missing filing deadlines or presenting unverified benchmarks allows tax authorities to adjust profits directly to the median range.
1. Regulatory Framework & Key Triggers Under Decree 132
Vietnam’s transfer pricing regime operates strictly under the principle of substance-over-form. Decree 132/2020/ND-CP regulates how associated enterprises determine transaction prices, allocate operating costs, and establish taxable income for Corporate Income Tax (CIT) purposes. The framework hinges on identifying associated relationships and controlling allowable deductions.
1.1 How Related-Party Relationships Are Defined
Under Article 5 of Decree 132, two entities are classified as related parties when one party participates directly or indirectly in the management, control, capital contribution, or financing of the other. Critical legal triggers include:
- Equity Ownership Threshold: One enterprise directly or indirectly holds at least 25% of the owner’s equity in the second enterprise.
- Financing & Guarantee Exposure: One enterprise guarantees or extends loans to another, provided the loan capital represents at least 25% of the borrowing entity’s equity and constitutes more than 50% of its total medium- and long-term debts.
- Management & Control: An enterprise appoints more than 50% of the board of directors or controls key executive decisions of another.
- Commercial Dependency: One entity accounts for more than 50% of the total sales or purchase turnover of the other entity under exclusive commercial arrangements.
Common Audit Trap: Many independent foreign enterprises mistakenly trigger related-party status simply by securing a large commercial bank loan backed by a parent company guarantee, unaware that passing the 25% equity and 50% debt threshold subjects their entire cost structure to Decree 132.
1.2 The 30% EBITDA Cap on Net Interest Expense
Under Clause 3, Article 16 of Decree 132/2020/ND-CP, the cap on deductible loan interest expenses is stipulated as follows:
- Interest Cap: Total net interest expense (interest expense incurred during the period minus interest income from deposits and loans) deductible for Corporate Income Tax (CIT) purposes shall not exceed 30% of the total net operating profit plus net interest expense and depreciation/amortization expenses (EBITDA).
- Negative EBITDA: If the taxpayer’s EBITDA is negative or zero, the entire net interest expense incurred in the period is non-deductible.
- Carry-Forward of Disallowed Interest: Any net interest expense exceeding the 30% cap can be carried forward to subsequent tax periods when determining total deductible interest expense. The continuous carry-forward period must not exceed 05 consecutive years, starting from the year following the incurred year.
- Excluded Entities: This cap does not apply to credit institutions, insurance enterprises, securities companies, and certain ODA-funded projects or concessional government loans as prescribed by law.
2. Who Must Prepare Documentation? Exemptions and Safe Harbors
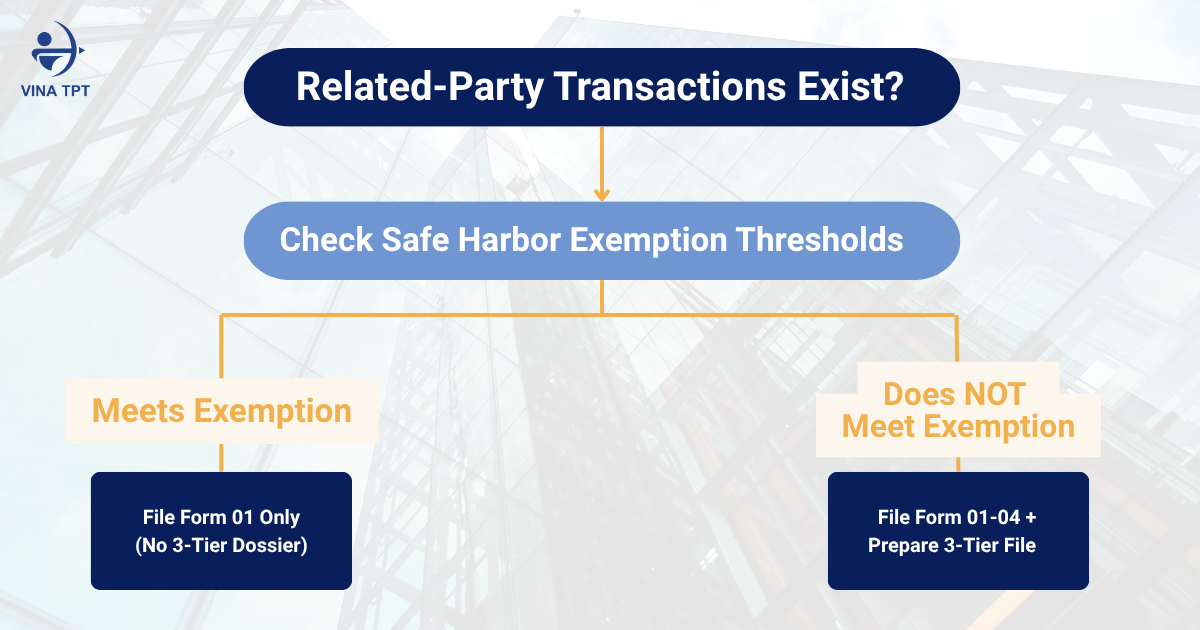
Enterprises engaging in related-party transactions must assess their eligibility under the safe harbor provisions of Decree 132 before committing resources to full documentation packages
2.1 Full Exemption Thresholds
Under Clause 2, Article 19 of Decree 132/2020/ND-CP, taxpayers are exempt from preparing Transfer Pricing Documentation (Local File, Master File, and CbCR) if they qualify under any of the following cases:
- Revenue and Transaction Threshold: Total revenue in the tax period is under VND 50 billion and the total value of related-party transactions is under VND 30 billion.
- Advance Pricing Agreement (APA): The taxpayer has entered into an APA and submits the required annual APA reports in compliance with applicable regulations.
- Simple Business Operations Meeting Margin Thresholds: The taxpayer performs routine functions, incurs no revenue or expenses from intangibles, generates revenue under VND 200 billion, and achieves an operating margin (EBIT to net revenue) of at least:
» 5% for distribution.
» 10% for manufacturing.
» 15% for toll processing/contract manufacturing.
Note: Taxpayers exempt from TP documentation are still required to submit the prescribed TP disclosure forms with their annual CIT return.
2.2 Form Disclosure vs. Contemporary Documentation
Taxpayers frequently confuse filing exemptions with complete reporting waivers:
- Exempt Taxpayers (Form-Only): Qualifying for a documentation safe harbor waives only the burden of drafting the Local File, Master File, and CbCR. The taxpayer remains legally obligated to declare its related parties and transactions on Form 01 attached to the annual CIT finalization dossier.
- Non-Exempt Taxpayers (Full Dossier): Must file the required statutory appendices (Forms 01, 02, 03, and 04) and compile contemporaneous three-tier files prior to the CIT filing date, storing them locally for immediate tax authority audit requests.
3. The Three-Tier Documentation Structure Explained
Decree 132 aligns Vietnam’s compliance rules directly with the OECD BEPS Action 13 three-tiered documentation standard. This integrated structure provides tax authorities with a clear overview from local operations up to global value chains.
3.1 Local File vs. Master File Requirements
The Local File and Master File address different operational dimensions of an enterprise:
| Criterion | Local File (Hồ sơ quốc gia) | Master File (Hồ sơ tập đoàn toàn cầu) |
| Primary Scope | Entity-level activities within Vietnam. | Global operations of the multinational group (MNE). |
| Core Content | • Detailed Functional, Asset, and Risk (FAR) analysis.
• Local management structure and business strategy.
• Intercompany pricing agreements and material transaction values.
• Financial reconciliations and local economic benchmarking studies.
|
• Global organizational structure and geographical presence.
• Five primary drivers of group profitability.
• Intangible asset (IP) development and ownership strategies.
• Intercompany financial arrangements and treasury policies.
• Consolidated financial statements.
|
| Source of Preparation | Formulated directly by the Vietnamese subsidiary and local tax advisors. | Drafted by the global ultimate parent entity and localized for submission in Vietnam. |
3.2 Country-by-Country Reporting (CbCR)
Country-by-Country Reporting (Báo cáo lợi nhuận liên quốc gia) maps where value, employees, assets, and tax liabilities sit across worldwide tax jurisdictions.
- Reporting Threshold: Mandated for multinational groups with consolidated global revenue of at least VND 18,000 billion (approx. EUR 750 million) in the preceding tax period.
- Filing Obligations for Vietnamese Subsidiaries: If the Ultimate Parent Entity (UPE) is located in a foreign jurisdiction that has an effective Automatic Exchange of Information (AEOI) treaty with Vietnam, the local subsidiary only needs to file a formal notification letter. If no functional exchange agreement exists, or if the UPE fails to file, the Vietnamese entity must submit the CbCR copy directly to the local tax department.
4. Benchmarking Methodology: Establishing the Arm’s Length Range
A transfer pricing study relies on an Economic Analysis that proves all intercompany pricing reflects independent market outcomes (the Arm’s Length Principle).
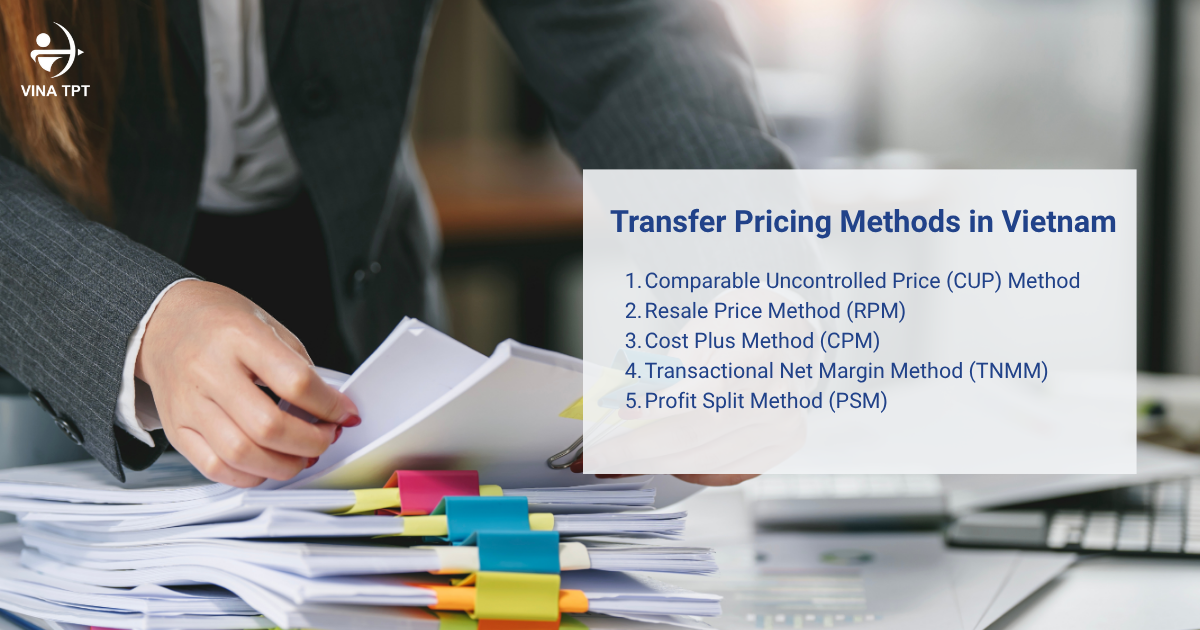
4.1 Common Transfer Pricing Methods in Vietnam
Decree 132 outlines five formal pricing methods:
- Comparable Uncontrolled Price (CUP) Method: Directly compares transaction prices to external or internal market prices; standard for commodities and plain vanilla financing.
- Resale Price Method (RPM): Evaluates gross margins earned in related purchases against resale to independent parties; best for routine distributors.
- Cost Plus Method (CPM): Adds an appropriate gross markup to direct and indirect production costs; ideal for contract manufacturers and routine service providers.
- Transactional Net Margin Method (TNMM): Examines operating profit relative to an appropriate base (costs, sales, or assets). TNMM is the most common method in Vietnam because local contract manufacturers and toll processors rarely possess reliable public gross-margin data or exact product-level comparables.
- Profit Split Method (PSM): Allocates combined operating profit from complex, integrated transactions where both parties contribute unique intangibles.
4.2 Database Screening & Interquartile Range
In accordance with Articles 17 and 18 of Decree 132/2020/ND-CP, the three-step screening and calculation process to determine the arm’s length range is conducted as follows:
- Quantitative Screening: Automatic filtering via commercial databases based on industry classification codes (SIC/NACE), comparable geographic markets, active operational status (at least 3 consecutive operating years), minimum revenue thresholds, availability of sufficient financial data, and verified independence (related-party ownership below 25%).
- Qualitative Screening: Manual review of annual reports, financial statements, company websites, and business descriptions to assess comparability in Functions, Assets, and Risks (FAR analysis). Companies engaged in diversified operations without segmented data or possessing unique, valuable intangibles are rejected.
- Calculation of the Arm’s Length Range: Profit Level Indicators (such as OP/OR, Berry Ratio, or OP/TC) of the accepted comparable companies are compiled, excluding entities with extreme or persistent losses. Under Decree 132, the standard arm’s length range is determined using the interquartile method, spanning from the 25th percentile ($Q_1$) to the 75th percentile ($Q_3$), with the median value serving as the primary benchmark.
5. Compliance Timelines, Penalties, and Audit Red Flags
Transfer pricing compliance requires strict adherence to statutory deadlines and proactive risk management to avoid audits.
5.1 Submission Deadlines and Inspection Timelines
- Statutory Filing Deadline: Transfer pricing disclosure forms (Forms 01 to 04) must be submitted along with the annual Corporate Income Tax finalization return no later than the last day of the 3rd month following the close of the calendar/financial year (typically March 31).
- Documentation Availability: Three-tier transfer pricing files must be completed and stored contemporaneously prior to the tax filing date.
- Inspection Response Window: Upon receiving a formal written demand from tax authorities:
- Taxpayers have 30 business days to deliver the complete transfer pricing documentation during standard audits.
- The timeline drops to 15 business days during pre-audit consultation proceedings.
- Language Requirement: Documentation must be provided in Vietnamese. Master files or transaction agreements drawn up in foreign languages must include verified Vietnamese translations when requested.
5.2 Audit Triggers and Consequences of Non-Compliance
Tax bureaus use data-driven algorithms to flag high-risk taxpayers. Common audit triggers include:
- Reporting consecutive multi-year operating losses while continuing to expand local production footprints or report surging revenues.
- Maintaining profit margins significantly lower than the benchmarked industry average in the same province.
- Making substantial royalty, software license, or management fee payments to offshore affiliates in low-tax jurisdictions.
- Unbalanced functional and asset profiles (e.g., operating as an asset-heavy toll manufacturer while absorbing all inventory risks).
6. Comprehensive Transfer Pricing Advisory Services by Vina TPT
Navigating Decree 132 requires local tax insight, economic modeling expertise, and defendable empirical benchmarks. Vina TPT provides specialized transfer pricing solutions that protect multinational enterprises from tax adjustments while ensuring operational compliance across Vietnam.
End-to-End Transfer Pricing Compliance Solutions by Vina TPT
- Diagnostic TP Risk Reviews (Health Check): Auditing existing related-party structures, intercompany contracts, and commercial terms to highlight adjustment exposures before authorities launch an audit.
- Three-Tier Dossier Preparation: Drafting compliant, localized Local Files, Master Files, and statutory disclosures (Forms 01 through 04) tailored to your operational realities in Vietnam.
- Defensible Economic Benchmarking: Accessing certified global financial databases to develop verifiable, robust peer groups that withstand rigorous scrutiny from local tax offices.
- Supply Chain Restructuring & APAs: Structuring intercompany transaction flows, intangibles licensing, and negotiating Advance Pricing Agreements (APAs) with the General Department of Taxation.
Audit Defense Support & Consultation Process
When tax authorities challenge your documentation, having the right team beside you makes all the difference. Vina TPT works alongside your internal finance teams during transfer pricing audits by:
- Reconciling technical differences directly with tax audit teams.
- Defending functional characterizations and screening criteria.
- Preventing arbitrary adjustments to the median range.
Mitigating tax exposure through early transfer pricing compliance is vastly superior to managing retrospective tax adjustments. Partner with Vina TPT today to evaluate your risk profile and secure a customized compliance roadmap for your enterprise.
Opening a company in Vietnam raises three separate questions: how can you enter the country, can you legally work for your business, and how long can you stay?
Understanding visa, work permit and TRC requirements in Vietnam helps foreign investors plan their business activities and relocation together. Your nationality, investment structure, personal capital contribution and actual working role all matter.
Quick answer: A visa establishes your immigration purpose, a work permit or applicable exemption addresses your right to work, and a Temporary Residence Card (TRC) provides residence under an eligible category. Registering a company does not automatically satisfy all three requirements.
Vietnam Visa vs Work Permit vs TRC: What Is the Difference?
Visa Establishes Your Entry and Stay Purpose
A Vietnamese visa supports entry and temporary stay for a specified purpose, such as business activities, investment or employment. The visa category should reflect your circumstances.
Visa validity and permission to remain during a particular visit are related but distinct. Always check your authorized temporary stay rather than relying only on the visa’s expiry date.
Work Permit Addresses Your Right to Work
A work permit authorizes a foreign national to work under the approved employment arrangement. Certain individuals qualify for an exemption, subject to the relevant conditions and procedures.
Neither owning a business nor holding an investor visa automatically resolves the work authorization question.
TRC Supports Longer-Term Residence
A TRC allows an eligible foreign national to reside in Vietnam for the card’s validity period and has visa-substitute value. It does not independently establish permission to work and is different from permanent residence.
| Document | Main purpose | What it does not establish by itself |
| Visa | Entry and stay for an approved purpose | A universal right to work |
| Work permit | Authorization for the approved work arrangement | Immigration permission to enter or remain |
| TRC | Residence under an eligible category | Work authorization or permanent residence |
These documents operate under separate immigration and employment requirements.
Which Visa Categories Matter to Foreign Investors?
1. Business Visa Vietnam (DN1 and DN2)
- DN1 applies to foreigners working with enterprises and other organizations having legal personality under Vietnamese law.
- DN2 applies to activities such as offering services, establishing a commercial presence and other activities under treaties to which Vietnam is a party.
Meeting a distributor and taking an operational role in a Vietnamese company are different activities. A DN visa does not itself provide a work permit exemption.
| Scenario | Visa Category to Consider |
| A Singaporean investor visits Vietnam to meet advisers, explore the market and discuss opportunities with potential partners before making an investment decision. | DN1, with sponsorship from an eligible enterprise or organization. |
| A representative of a Korean company visits Vietnam to negotiate a contract with a local distributor. | DN1, for business dealings with a Vietnamese enterprise. |
| A representative of a foreign enterprise enters Vietnam to offer services or establish a commercial presence under applicable international commitments. | DN2, subject to the relevant eligibility requirements. |
2. DT1, DT2, DT3 and DT4 Investor Visas
Investor visas cover qualifying foreign investors and representatives of foreign organizations investing in Vietnam. Classification depends on the relevant capital contribution or statutory investment criteria.
| Visa | Main classification criteria | Maximum visa validity |
| DT1 | Capital contribution of at least VND 100 billion, or qualifying investment-incentive sectors or locations | 5 years |
| DT2 | From VND 50 billion to below VND 100 billion, or qualifying government-designated encouraged sectors | 5 years |
| DT3 | From VND 3 billion to below VND 50 billion | 3 years |
| DT4 | Below VND 3 billion | 1 year |
| DN1 / DN2 | Qualifying business activities | 1 year |
| LD1 / LD2 | Qualifying employment circumstances | 2 years |
These are statutory ceilings, not guaranteed periods. Investor classification also requires appropriate supporting records.
3. LD1 and LD2 Work Visa Vietnam
- LD1 concerns foreign workers qualifying under the work-permit-exempt framework, with the applicable supporting basis.
- LD2 concerns foreign workers who require a work permit.
LD visas generally apply to foreign experts and employees coming to Vietnam to work for a company or organization. LD1 applies to those eligible for a work permit exemption, while LD2 applies to those required to hold a work permit.
Do Foreign Investors and Business Owners Need a Work Permit?
Investing in a Company and Working for It Are Different Activities
Holding an investment and actively working for the business require different assessments. Managing employees, directing operations or providing technical services may bring you within the foreign-worker framework.
The assessment should consider your actual activities, not simply whether your title says “investor” or whether you receive a local salary.
Work Permit Exemptions for Qualifying Capital Contributors
Under Article 7 of Decree 219/2025/ND-CP, the following capital contributors qualify for specified exemptions:
| Company type | Qualifying position | Required personal capital contribution |
| Limited liability company | Owner or capital-contributing member | At least VND 3 billion |
| Joint stock company | Chairperson or member of the Board of Directors | At least VND 3 billion |
For a joint stock company, merely being a shareholder does not establish the exemption described above; the qualifying board position also matters.
Representatives of Corporate Investors Need a Separate Assessment
Suppose an overseas company invests in a Vietnamese subsidiary and appoints a foreign director. The subsidiary’s investment capital is not automatically the director’s personal contribution.
The representative must therefore assess the applicable work permit requirement or another exemption based on their own circumstances. An investor visa issued in a representative capacity is not sufficient evidence of the personal-contribution exemption.
Exemption Does Not Always Mean No Paperwork
For the qualifying capital contributors listed above, Article 9(4) provides a notification procedure rather than an application for an exemption certificate. Notification must be made to the competent authority at least three working days before the expected start of work.
Other exemption categories may require different procedures. The employer should identify the correct exemption and retain evidence supporting it.
Which Investors Can Obtain a Vietnam Temporary Residence Card?
Investor TRCs Under DT1, DT2 and DT3
Eligible investors and representatives may apply for investor TRCs under DT1, DT2 or DT3. Immigration authorities assess the applicant’s status and supporting investment records.
| Category | TRC available under this category? | Maximum TRC validity |
| DT1 | Yes, subject to eligibility | 10 years |
| DT2 | Yes, subject to eligibility | 5 years |
| DT3 | Yes, subject to eligibility | 3 years |
| DT4 | No DT4 TRC category | Not applicable |
| LD1 / LD2 | Yes, subject to employment-related conditions | 2 years |
| DN1 / DN2 | No DN1 or DN2 TRC category | Not applicable |
A TRC must expire at least 30 days before the passport expires. Consequently, a short remaining passport validity can reduce the residence period granted.
Why DT4 Does Not Qualify for an Investor TRC
DT4 holders cannot obtain a TRC under the DT4 category. However, this does not permanently exclude them from residence cards.
A person who independently meets another category’s requirements may apply under that category. For example, an eligible working business owner may assess an employment-based route.
Work-Based TRCs Under LD1 and LD2
Employment-based TRCs require the appropriate work-related basis and sponsorship. Their statutory maximum is two years; the actual period depends on the supporting documents and applicable conditions.
A work permit holder should coordinate the residence application with the permit’s remaining validity rather than assume a full two-year card will be issued.
Is a TRC Mandatory for Staying in Vietnam?
A TRC is not mandatory simply because you own a company or intend to stay for an extended period. You may remain under another valid immigration basis within your authorized stay.
However, preparing a TRC application does not automatically extend an expiring stay.
How Does Investment Capital Affect Your Visa, Work Permit and TRC?
Personal Capital Contribution vs Total Company Capital
Start with three questions: who is the registered investor, how much capital belongs to that person or entity, and which documents prove the investment?
For the capital-contributor work permit exemption, your personal qualifying contribution matters. The company’s total capital cannot automatically be attributed to each shareholder, member or representative.
DT3 vs DT4: What Changes Around the VND 3 Billion Threshold?
The threshold affects investor visa classification and residence options, but employment exemptions must still be assessed separately.
The following examples assume the investment and working arrangements are properly documented:
| Illustrative situation | Work authorization assessment | Residence route to assess |
| Individual contributes VND 1 billion and actively manages the company | Work permit generally required unless another exemption applies | DT4 visa; employment-based residence if eligible |
| Individual contributes VND 5 billion as a member of an LLC | Assess the qualifying capital-contributor exemption and notification | DT3 investor TRC |
| Overseas company invests and sends a director | Assess the director’s own work arrangement; no automatic personal-contribution exemption | Representative investor or employment route, depending on eligibility |
Why Company Registration Alone Does Not Guarantee Residence
An Enterprise Registration Certificate (ERC) or Investment Registration Certificate (IRC) documents business or investment matters. Neither replaces the separate immigration and employment assessment.
Evaluate residence objectives before finalizing the investment structure, especially where the business will be owned by an overseas company rather than directly by the relocating individual.
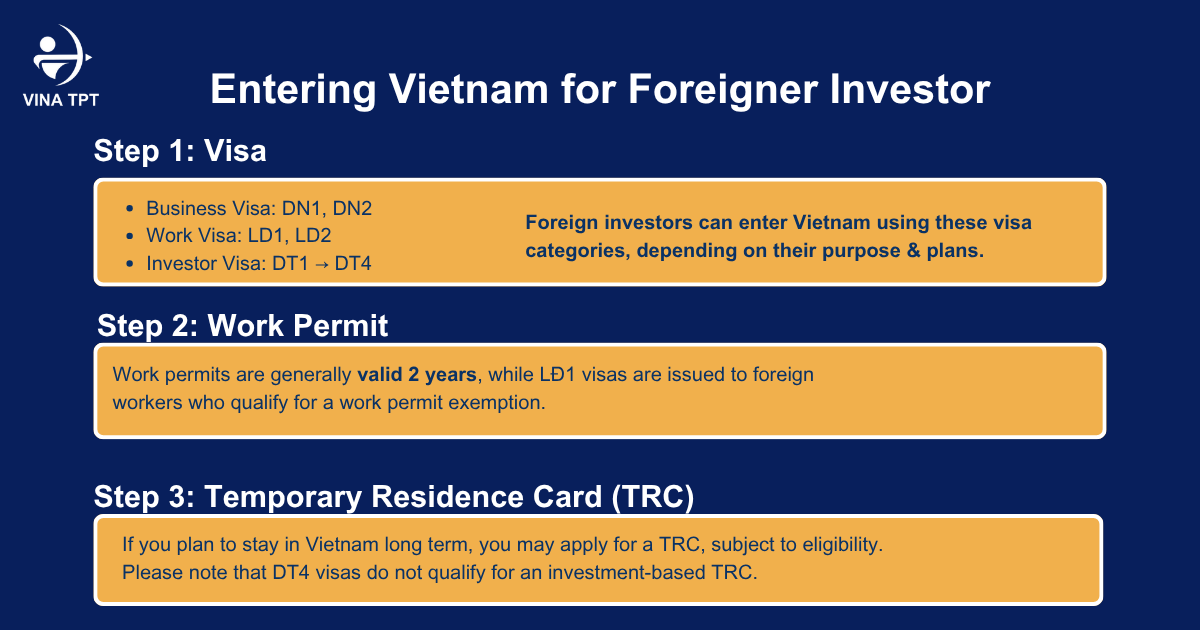
What Is the Application Process for Foreign Investors?
Step 1 — Assess Your Investment, Role and Intended Stay
Prepare details of your nationality, investment structure, contribution, working responsibilities, current immigration status and intended stay. Include accompanying family members when planning relocation.
Step 2 — Identify the Appropriate Visa and Sponsor
Match the visa to your actual purpose and identify the appropriate sponsoring entity. Check that personal, company and investment records consistently describe the proposed arrangement.
Step 3 — Complete Work Permit or Exemption Requirements Where Applicable
If you will work in Vietnam, establish whether a work permit, exemption certificate or notification procedure applies. Prepare the relevant evidence and complete the required steps before commencing work.
Step 4 — Apply for the Appropriate Residence Status
Assess the appropriate visa or TRC route. Vietnamese law permits visa-purpose changes in specified circumstances, including qualifying investment and employment cases; approval is not automatic.
Confirm the current filing requirements before assuming you must leave Vietnam or can complete everything domestically.
Step 5 — Maintain Temporary Residence Registration and Track Expiry Dates
Ensure temporary residence registration is completed and monitor passport, visa, work authorization and TRC dates. Reassess the documents when your employer, sponsor, passport, investment or working role changes.
An investor route and an employee route do not necessarily follow an identical application sequence.
Plan Your Visa, Work Permit and TRC With Vina TPT
Vina TPT helps foreign investors assess visa, work permit, exemption and TRC requirements alongside their business establishment and HR compliance needs.
Our team can review your investment structure, contribution, proposed role and intended stay, then discuss the relevant procedures and supporting documents. Share your nationality, ownership details, current immigration status and relocation plans to identify practical next steps.
Discuss Your Vietnam Visa and Residence Requirements
This September 2026 Vietnam tax update summarises recent guidance on VAT refunds for investment projects, deductible vehicle rental expenses, PIT withholding after employment termination, invoice issuance timing and exchange rates on export invoices. Each section highlights the relevant conditions and practical considerations to help businesses review their tax procedures and supporting documents.
1. INVOICE
Guidance on invoice issuance timing for services supplied to individual consumers and transactions arising at night.
Pursuant to Official Letter No. 6325/CT-QLNT dated August 26, 2026 of the Tax Department, guiding Article 9 of Decree No. 254/2026/NĐ-CP (effective July 1, 2026).
Services supplied to individual consumers
For enterprises providing services to individual consumers, including banking; payment intermediary services; credit information services; securities business; crypto-asset transactions; support services for transactions on carbon exchanges; insurance business; money transfers via e-wallets; suspension and resumption of electricity supply; e-commerce; postal and transportation services supporting e-commerce; public passenger transport by metro and bus; passenger transport by taxi, contract vehicle, and two-wheeled motorcycle; parking services; cinema services; and other services, where such enterprises satisfy the conditions of having a software system capable of managing each transaction in detail and maintaining payment collection data in the system on a transaction-by-transaction basis:
– The seller shall prepare a Summary of E-Invoice Data for Sales of Goods and Provision of Services and a Detailed Statement of Transactions Arising During the Month or Quarter (covering the period from the first day to the last day of the relevant month or quarter), using the forms prescribed by the Minister of Finance, and submit them to the tax authority no later than the statutory deadline for submission of the Value Added Tax (“VAT”) return in accordance with the laws on tax administration.
– Where a large volume of invoices is generated, the Summary of E-Invoice Data and the Detailed Statement of Transactions shall be divided into separate data files in accordance with the standard data format prescribed by the tax authority to ensure compliance with the technical requirements for data transmission and receipt.
The seller is responsible for the accuracy of transaction information, must retain full detailed data for each transaction, and must ensure the data can be retrieved, reconciled and provided, together with related documents, on request of the tax authority or competent state agency.
Transactions arising during night working hours
Where the seller has no automatic invoicing software and sells goods or supplies services during night working hours as defined by the Labor Code, the invoice must be issued no later than the next working day.ogether with the Appendix on VAT Refund Claim Information (Form No. 01-8/GTGT) as the basis for the tax authority to review and process the refund request.
Guidance on Exchange Rates Stated on Invoices for Export Activities
Pursuant to Official Letter No. 6810/CT-QLNT dated 14 September 2026
In cases where economic or financial transactions are denominated in foreign currencies in accordance with foreign exchange regulations, the seller shall indicate on the invoice the exchange rate between the foreign currency and the Vietnamese Dong as prescribed in Point c.1, Clause 8 of the Appendix attached to Decree No. 254/2026/NĐ-CP.
Pursuant to Clauses 1 and 5, Article 26 of the Law on Tax Administration No. 108/2025/QH15 and the accounting regulations, the exchange rate shown on the invoice shall be the actual transaction exchange rate determined in accordance with accounting laws and regulations.
2. PERSONAL INCOME TAX
Guidance on 10% PIT withholding on income paid to employees whose labour contracts have been terminated.
Pursuant to Official Letter No. 10049/NBI-QLDN1 dated August 3, 2026 of the Ninh Binh Provincial Tax Office, guiding Clauses 1 and 3, Article 26 and Clause 2, Article 50 of Decree No. 253/2026/NĐ-CP dated June 30, 2026
– Where an employee is a resident individual whose labor contract was terminated on 30 June 2026, and the Company pays the employee’s salary for June 2026 on 10 July 2026, such payment shall be treated as a salary payment made to an individual whose labor contract has already been terminated. If the payment to each individual on each occasion is VND 5 million or more, the Company shall withhold personal income tax (“PIT”) at the rate of 10% before making the payment. If the payment is less than VND 5 million per payment, the Company shall withhold PIT at the rate of 10% only at the individual’s request.
– The Company shall withhold PIT at the rate of 10% on taxable income from salaries and wages before making payment to the individual. Tax-exempt income prescribed by law, including remuneration for night work and overtime work, and salaries and wages paid for unused annual leave within the conditions, duration and limits prescribed by labor laws, shall not be included in the income subject to withholding. Any amount exceeding the statutory limits shall be included in taxable income.
Compulsory insurance contributions, personal and dependent deductions, and other allowable deductions are taken into account in determining taxable income when applying the partially progressive tax tariff or upon annual PIT finalization, and shall not be deducted when applying the provisional 10% withholding rate prescribed in Clause 2, Article 50 of Decree No. 253/2026/ND-CP.
3. VALUE ADDED TAX
Guidance on VAT Refund Conditions for Investment Projects
Pursuant to Official Letter No. 7019/CT-QLNT dated 22 September 2026 issued by the Tax Department:
Where, at the time of submitting the VAT refund application, a business establishment falls within the scope of cases eligible for a VAT refund in respect of an investment project, has input VAT that fully satisfies the conditions for VAT credit and refund in accordance with the VAT regulations, and has submitted a VAT refund application dossier in compliance with the tax administration regulations, the business establishment shall be considered for a VAT refund in respect of the investment project.
Pursuant to Clause 4, Article 3 of Law on Investment No. 61/2020/QH14, Clause 2, Article 15 of Law on Value Added Tax No. 48/2024/QH15, and Article 30 of Decree No. 181/2025/ND-CP, there is no provision stipulating that the date of issuance of the Investment Registration Certificate (“IRC”) shall serve as the basis for determining the input VAT attributable to an investment project
Where the Company has VAT invoices for purchased goods and services arising prior to the issuance of the IRC, if the Company is able to provide sufficient supporting documents and evidence demonstrating that such goods and services were actually purchased for the preparation and implementation of the investment project in accordance with the laws on investment, and the related input VAT satisfies the conditions for VAT credit and refund under the VAT regulations, such input VAT may be considered for credit and refund in respect of the investment project in accordance with the applicable regulations.
4. CORPORATE INCOME TAX
Guidance on the Conditions for Treating Vehicle Rental Expenses Paid to Individuals as Deductible Expenses for Corporate Income Tax Purposes
Pursuant to Official Letter No. 15944/DON-QLDN3 dated 18 August 2026 issued by the Dong Nai Tax Authority:
- Where an enterprise rents assets from an individual, the supporting documents required to substantiate the deductible expense include the asset lease agreement and documents evidencing payment of the rental fee.
- Where an enterprise rents assets from an individual and the lease agreement stipulates that the rental fee is exclusive of taxes (including value added tax and personal income tax), and the enterprise is required to declare and pay such taxes on behalf of the individual in accordance with the laws on tax administration, the taxes paid on behalf of the individual may also be treated as deductible expenses for corporate income tax purposes, provided that valid tax payment documents are available.
5. Review Your Business’s Tax Compliance
Vina TPT provides integrated accounting, tax, HR and payroll, legal and business advisory services for domestic and foreign-invested enterprises in Vietnam. From company establishment and post-licensing procedures to bookkeeping, financial reporting and ongoing compliance, we help businesses manage their obligations at each stage of their operations.
Our tax services include tax filing and annual finalization, VAT refund assistance, tax health checks, transfer pricing and global minimum tax compliance. We also review supporting records, identify potential compliance gaps, and assist with documentation and explanations requested by tax authorities during tax reviews and inspections.
If these updates affect your business, our team can help assess the implications, review your current procedures and recommend practical actions suited to your operations.
Contact Vina TPT to Review Your Tax Compliance
From 28 September 2026, electronic identification accounts for foreigners are no longer classified as Level 1 or Level 2. Under Decree 320/2026/ND-CP, which amends Decree 69/2024/ND-CP, foreign nationals follow a single registration procedure.
The updated rules also broaden eligibility. Foreign nationals who have lawfully entered Vietnam can apply when needed, extending eligibility beyond those legally residing in the country.
This guide to VNeID for foreigners explains the benefits, eligibility requirements, documents to prepare, application steps and processing times.
1. Why Should Register VNeID for Foreigners?
VNeID is Vietnam’s national electronic identification application. It allows foreign nationals to manage their digital identity, access integrated information and documents, and use services connected to the electronic identification and authentication system.
The practical value of VNeID for foreigners lies in supporting everyday needs, including banking verification, online administrative procedures and access to electronic documents.
Identity Verification for Banking Services
At participating banks, VNeID supports identity verification and biometric matching. Completing these checks helps foreign customers meet the requirements for digital banking functions, including online transfers and payments.
Applicants must still satisfy the bank’s account opening requirements and provide the necessary documents. Having VNeID does not automatically allow a foreign customer to open an account entirely online at every bank.
Access to Online Public Services
Foreign nationals can use their electronic identification accounts to sign in, verify their identity and access procedures through public service systems that support VNeID.
This makes it easier to submit applications and receive notifications online, reducing the need to visit an authority for every stage of a procedure. Steps requiring physical attendance must still be completed as instructed.
Management of Electronic Documents
VNeID enables users to access information and documents integrated into their accounts, such as residence card information where integration and use are supported.
When handling procedures or transactions, receiving authorities and organisations use integrated information according to the applicable regulations. This helps reduce repeated declarations and requests to present original documents or copies already available through the application.
Registration of a Company’s Electronic Identification Account
For foreign investors who have established a company in Vietnam and also serve as its legal representative, a personal VNeID account supports registration of the company’s electronic identification account.
This helps the business verify its identity and access online public services available to organisations.
These benefits depend on the information integrated into the account and the systems supported by each bank, authority or service provider. Check the receiving organisation’s requirements before using VNeID for a particular transaction.
2. Who Can Apply for VNeID in Vietnam?
Foreign nationals can apply for an electronic identification account when needed if they:
- Have lawfully entered Vietnam; or
- Are legally residing in Vietnam.
Eligibility for VNeID for foreigners is not limited to employees or investors. Employment in Vietnam is therefore not stated as a prerequisite under this provision.
Foreign children under 14 and individuals under guardianship or representation can also register. They must follow the procedure involving their representative or guardian.
Do Foreigners Still Need a Level 2 Account?
From 28 September 2026, electronic identification accounts for foreign nationals are issued without a level classification.
Older guides may describe separate Level 1 and Level 2 procedures. Applicants should follow the updated registration requirements rather than rely on those earlier instructions.
3. What Should You Prepare Before Registration?
Preparing your documents and contact information before visiting the immigration authority can make the process easier. The following checklist covers the main requirements and practical preparations for VNeID for foreigners.
Passport or International Travel Document
- Applicants must present their passport or another document valid for international travel.
- Check your personal details before the visit so that the information you provide is consistent, particularly your full name, date of birth, nationality and document number.
Mobile Phone Number Registered in Your Name
- Foreign applicants must provide a mobile phone number registered in their own name.
- Check your subscription details with your mobile service provider. Using a number does not necessarily mean that the subscription is registered under your identity.
- For children under 14 and applicants under guardianship or representation, the representative or guardian uses a number registered in their own name.
Email Address, if Available
- Provide an email address if you have one. Email is one of the channels through which the registration result may be communicated.
- Choose an address you check regularly and confirm that it is entered correctly.
Information Required by Form TK01
- Applicants must provide complete and accurate information using Form TK01, the prescribed electronic identification account application form.
- This includes the registered mobile phone number, email address if available, and any additional information requested for integration into the national identification application.
Smartphone for Using the Application
- The receiving officer guides applicants in downloading, installing and entering information in the application.
- Bringing a compatible smartphone with internet access is therefore useful. Make sure you can install the application and access the contact channels provided during registration.
| What to prepare | What to check |
|---|---|
| Passport or international travel document | Bring it to present to the receiving officer |
| Mobile phone number | Confirm that it is registered in the required person’s name |
| Email address | Prepare an accessible address, if available |
| Application information | Ensure your details match your travel document |
| Smartphone | Check that it can install and run the application |
Where Do Foreigners Register?
Applications for VNeID for foreigners are made in person at the immigration authority of the provincial-level police.
Before travelling, confirm the office address, opening hours and any local instructions concerning appointments or application reception.
This is particularly helpful if you need time away from work, must travel to the office, or will attend with a child or represented applicant.
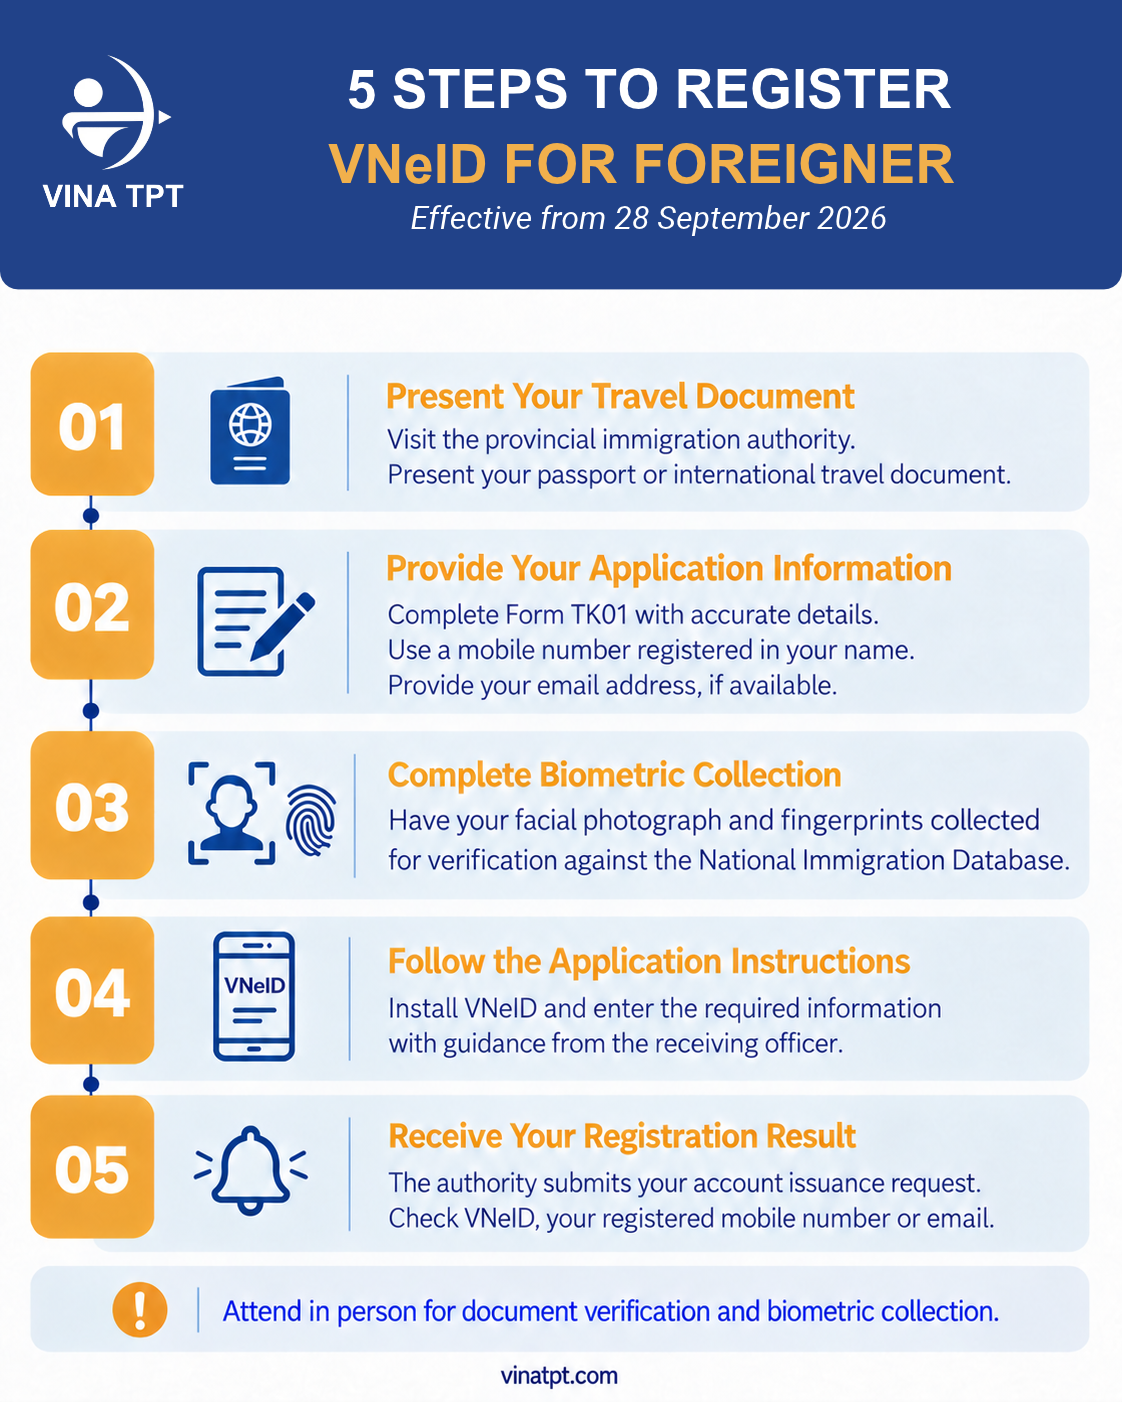
4. How to Register for VNeID in Vietnam
The registration process involves presenting your identity document, providing application information and completing biometric collection.
Step 1: Present Your Travel Document
Visit the immigration authority, request an electronic identification account and present your passport or international travel document.
An in-person visit forms part of the registration procedure for VNeID for foreigners. Downloading the application alone does not complete the process.
Step 2: Provide Your Application Information
Provide complete and accurate information using Form TK01.
Give the receiving officer your registered mobile phone number, email address if available, and any additional information you wish to integrate into the application.
Review your details carefully. If you notice an incorrect name, passport number or contact detail, inform the officer before submission.
Step 3: Complete Biometric Collection
The receiving officer enters your information into the electronic identification and authentication system.
The officer also captures your facial photograph and collects your fingerprints to authenticate your information against the National Immigration Database.
Applicants must attend in person for these biometric steps.
Step 4: Follow the Application Instructions
The officer guides you in downloading and installing the national identification application and entering the required information.
If your device encounters a technical problem, explain it to the officer so that you can receive appropriate guidance.
Step 5: Receive Your Registration Result
After completing the necessary steps, the immigration authority sends the account issuance request to the authority managing and operating the electronic identification and authentication system.
The result is communicated through one of these channels:
- The national identification application;
- Your registered mobile phone number; or
- Your email address.
Keep these channels accessible and follow the instructions accompanying the notification.
5. How Long Does Registration Take?
The processing time for VNeID for foreigners depends on whether the applicant’s facial photograph and fingerprints are already available in the National Immigration Database.
| Database status | Statutory processing period |
|---|---|
| Facial photograph and fingerprints are already available | No more than 2 working days |
| Facial photograph and fingerprints are not yet available | No more than 5 working days |
These periods are measured in working days. Allow for weekends and public holidays when estimating when you may receive the result.
If no notification arrives after the applicable period, contact the receiving authority for guidance. First, check the application, phone messages and email.
6. Registration for Foreign Children Under 14
Foreign children under 14 must visit the immigration authority together with their representative or guardian.
The representative or guardian uses a mobile phone number registered in their own name to provide the information and register the child’s electronic identification account.
The same arrangements apply to foreign nationals under guardianship or representation.
Families should arrange for both the applicant and the representative or guardian to attend, rather than assume that the representative can complete the procedure alone.
7. Vina TPT’s Support with VNeID for Foreigners
Vina TPT helps foreign nationals understand the registration requirements and prepare the necessary documents and information. We guide clients through the process so they can plan their visit and reduce difficulties caused by incomplete or inconsistent details.
For foreign investors who also serve as the legal representative of a Vietnamese company, we provide guidance on registering the company’s electronic identification account after personal registration has been completed.
Applicants must still attend the relevant authority for verification and biometric collection as required.
Contact Vina TPT for support with VNeID for foreigners and guidance on the registration procedure applicable to your circumstances.
Legal basis: Decree 69/2024/ND-CP, as amended by Decree 320/2026/ND-CP. This article covers the registration procedure for foreign nationals effective from 28 September 2026.
Cost of Starting a Business in Vietnam: A Guide for Foreign Investors
What Is the Cost of Starting a Business in Vietnam? For foreign investors, registration fees are only part of the answer. You also need to budget for incorporation services, the capital you commit to the company, and the costs of operating and meeting compliance requirements after registration.
These amounts serve different purposes. Service fees pay for work performed by an advisor. Contributed capital goes into the company under its capital contribution plan. Office rent, accounting and staffing are operating expenses. Separating them gives you a clearer picture of both your setup costs and your first-year cash requirements.
What Is the Cost of Starting a Business in Vietnam?
There is no standard price for every foreign-invested company. Your total budget depends on your proposed business activities, investor documents, location, licensing requirements and the scope of your service provider’s quote.
| Cost to budget for | When it arises | How to plan for it |
| Incorporation service and applicable filing fees | Before and during registration | Request a quote that clearly states what is included. |
| Preparation of documents overseas | Before filing | Check the translation and consular legalization requirements for each document. |
| Additional licenses, if required | During or after registration | Assess them against your specific business activities. |
| Capital contribution | According to the applicable contribution schedule | Plan this separately from service fees. |
| Office and initial operating costs | Before or shortly after operations begin | Include deposits, rent, equipment and staffing. |
| Accounting, tax and compliance | After incorporation | Set a recurring budget that also covers annual obligations. |
Three budgets every investor should keep separate
Incorporation costs cover the work needed to establish the company. Contributed capital is the amount investors commit to the company in its registration documents; it is not a fee paid to an advisor. First-year operating costs cover the office, accounting, people and other resources the company needs to function.
After receiving an incorporation quote, ask two further questions: How much capital will you need to prepare, and which services will start generating costs after the company is registered?
1. One-Time Costs Before and During Incorporation
Advisory firms in Vietnam commonly quote a package price for company formation. However, the work included in each package can differ. Understanding the components is essential before comparing prices.
1.1 Government filing and publication fees
Some registration and publication procedures may carry official fees. Check which applicable charges are included in your advisor’s quote and whether the advisor will pay them on your behalf during the filing process.
These charges should not be confused with the former annual business license fee (lệ phí môn bài). According to government guidance, taxpayers have not been required to pay that annual fee since 1 January 2026. xaydungchinhsach.chinhphu.vn
1.2 Translation, notarization and consular legalization
Documents issued outside Vietnam may need additional preparation before they can be used in an application. Requirements depend on the investor, the type of document and the country where it was issued.
Distinguish between work carried out in Vietnam, such as applicable translation and notarization, and work that must be arranged overseas, such as consular legalization. Costs incurred in the investor’s home country are often outside the scope of a Vietnam-based advisor’s package. Request a tailored document checklist early to avoid having to prepare documents twice.
1.3 Legal advisory and company incorporation service fees
Advisory firms in Vietnam generally quote an all-in package for a defined scope of work rather than charging separately for every step. Depending on the proposal, the package may cover advice on the investment structure and business activities, preparation and follow-up of applications, applicable government fees, and certain notarization work in Vietnam.
As a planning estimate, USD 1,800–2,700 may cover advisory and incorporation services together with a company seal, digital signature and initial tax procedures. This is an indicative range for a particular scope of work, not a fixed price for every investor. The final quote depends on the complexity of the application, the services included, the provider’s experience and its specific commitments regarding scope, timing and responsibility for handling the application.
Before selecting a provider, ask for a written list of inclusions and separately charged items. Pay particular attention to document legalization overseas, additional licenses and post-incorporation support.
2. Cost of Starting a Business | After the Company Is Registered
Receiving the company’s registration documents is a major milestone, but further tasks may be needed before operations can begin.
| Post-registration task | Question to check against your budget |
| Company seal | Is it included in the package or purchased separately? |
| Digital signature | Who purchases and renews it, and what is its validity period? |
| Bank accounts | How far does the advisor’s support extend, and what documents or in-person steps does the bank require? |
| Initial tax procedures | Will the incorporation advisor handle these, or will they pass to the accounting team? |
| E-invoices | Are provider and software fees quoted separately? |
| Accounting setup | Who will establish the books, chart of accounts and document retention process? |
Assign responsibility for each task in writing. This helps ensure a clear handover from the incorporation team to the people managing the company’s accounting and tax work.
To get an accurate cost estimate, contact a consulting firm such as Vina TPT. We will help you break down the potential costs of establishing your company in Vietnam, including incorporation fees, additional expenses and post-licensing requirements. Our initial consultation is free, giving you a clearer understanding of the budget you need before moving forward.
3. Ongoing Compliance Costs for an FDI Company
After incorporation, the company needs a budget for accounting, tax and applicable reporting obligations. The cost depends on transaction volume, staffing, reporting needs and how much work the internal team will handle.
Accounting, tax filing and financial reporting
A basic accounting proposal may focus on bookkeeping and periodic tax filings. Management reports, bilingual reports and complex transactions may require a broader service scope. When requesting a quote, share your expected document volume, activities, hiring plans and reporting requirements.
An in-house accounting team also requires a budget for salaries, software, training and review. Compare the scope of work and responsibility, not just the monthly price of an outsourced service.
Statutory audit and investment reporting
Include the annual financial statement audit in your budget. Vietnam’s Ministry of Finance has confirmed that foreign-invested enterprises are subject to an annual financial statement audit regardless of company size. Investment reporting is a separate workstream: determine which reports apply and who will prepare the information needed for them. ttcg.mof.gov.vn
Payroll, insurance and expatriate administration
If the company plans to hire employees, budget for payroll, applicable insurance administration and employment documentation. If it will employ foreign nationals, assess immigration and work authorization services separately. These costs depend on your hiring plans and are not automatically included in an incorporation package.
Budgeting for Office Space, People and Operations
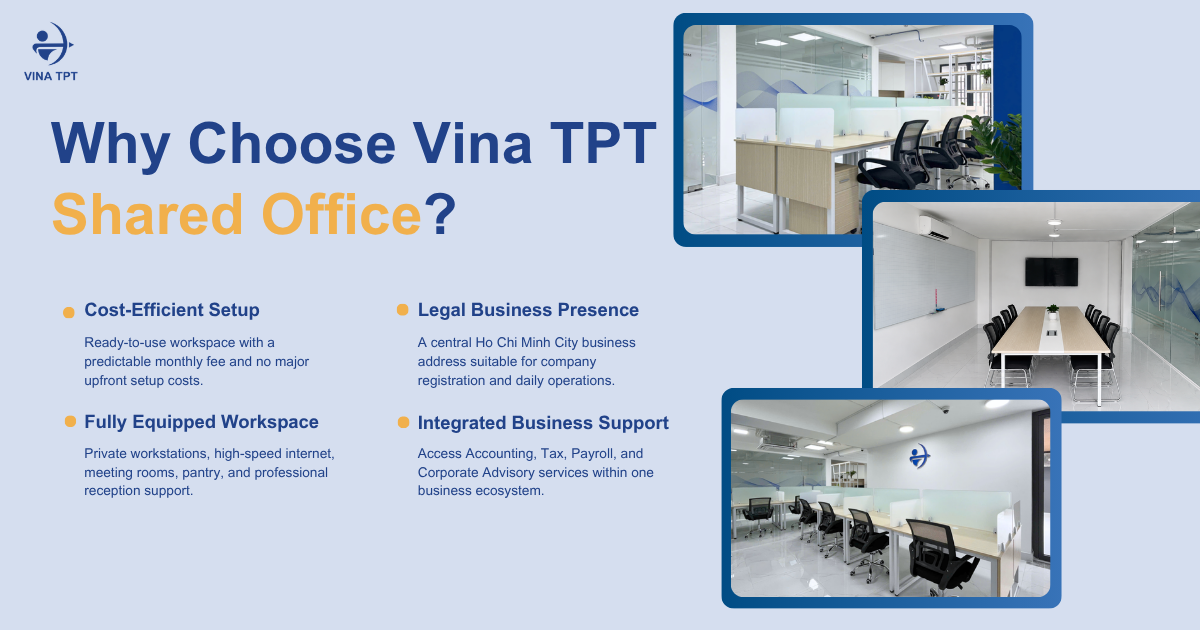
Your first-year budget should also account for premises, lease deposits, employees, computers, software, banking and day-to-day administration. The proposed registered address must be assessed against the company’s activities and the requirements of its application.
For suitable businesses establishing a presence in Ho Chi Minh City, Vina TPT Shared Office offers a combination of business address, workspace, and access to company formation, accounting and tax services. The address must be reviewed for each application. Under the applicable service proposal, office rental charges begin once the company has been established, helping investors plan costs during the registration period.
Explore Our Business Setup Services
Example: A First-Year Budget for a Foreign-Invested Service Company
Consider a small or medium-sized service company that plans to use one workspace, hire a limited number of employees and outsource its accounting. The table below is a budgeting template, not a quotation. Enter amounts from the proposals you receive.
| Cost item | Before or during incorporation | After registration | Classification |
| Incorporation package | According to the quote | — | One-time setup cost |
| Overseas document legalization | Based on the documents required | — | One-time, case-dependent cost |
| Additional licenses, if applicable | According to the quote | May also arise later | Case-dependent cost |
| Capital contribution | Prepare a funding plan | Contribute under the applicable schedule | Company capital; exclude from the setup-fee total |
| Office | A deposit may be required | Recurring rent | Operating cash requirement |
| Seal, digital signature and initial systems | Check the package scope | May require purchase or renewal | Initial or recurring cost |
| Accounting and tax | Select a provider | According to the contract | Recurring compliance cost |
| Audit | Plan and confirm the scope | Annual fee | Annual compliance cost |
| Payroll and employment administration | Plan if hiring | Monthly or per case | Operating and compliance cost |
| Contingency | Set aside an allowance | Review as operations begin | Budget reserve |
Calculate three separate totals: what you will pay to establish the company, the capital you need to contribute, and the cash needed for 12 months of operations and compliance. A trading company or business in a regulated sector may need additional budget lines for licenses, premises, goods and activity-specific requirements.
4. How to Avoid Unexpected Setup Costs
| Common issue | What to do early |
| Business activities are described too broadly or imprecisely | Define your products, services and sales model before requesting a quote. |
| Investor documents are prepared incorrectly | Request a checklist tailored to the investor and the country of issue. |
| The proposed address is unsuitable | Check the location against your activities before signing a lease. |
| The budget stops at incorporation | Forecast accounting, audit, office and staffing costs for the first year. |
| The quote does not clearly state exclusions | Request a written list of included and excluded services and a payment schedule. |
Frequently Asked Questions
Can a foreign investor own 100% of a company in Vietnam?
This may be possible, depending on the proposed activities and applicable market access conditions. Confirm the ownership structure before finalizing the budget and preparing the application.
Do I need to contribute all registered capital upfront?
No. You do not need to contribute the full amount when filing the incorporation application. For a limited liability company, the registered charter capital must generally be contributed within 90 days of the Enterprise Registration Certificate (ERC) being issued. Plan the transfer of funds before receiving the ERC.
Do service and trading companies have different setup costs?
They may. Business activities, licensing, location, goods and operating requirements can all affect the incorporation scope and first-year budget.
Can I use a shared office address to register a company?
Potentially, provided the address is suitable for the planned activities and the application requirements. With Vina TPT Shared Office, we can provide the relevant legal documents for the premises to support the company registration process. Our team will assess whether the address is appropriate for your proposed activities before preparing the application.
What information do I need to provide for an incorporation quote?
Tell us your proposed business activities, the specific products or services you will offer, and how the company will operate—for example, whether it will manufacture, import, distribute or provide services in Vietnam. Please also share the investor’s nationality or country of incorporation, the proposed ownership structure and location. This allows Vina TPT to identify the relevant procedures, define the service scope and flag costs outside a standard incorporation package.
Get a Cost Estimate for Your Vietnam Business Setup
Vina TPT supports foreign investors with company formation and the accounting, tax and administrative work that follows. Share your proposed activities and investment plan with our team. We can review the scope and prepare a proposal that clearly identifies included services, separately charged expenses, capital needs and ongoing costs.
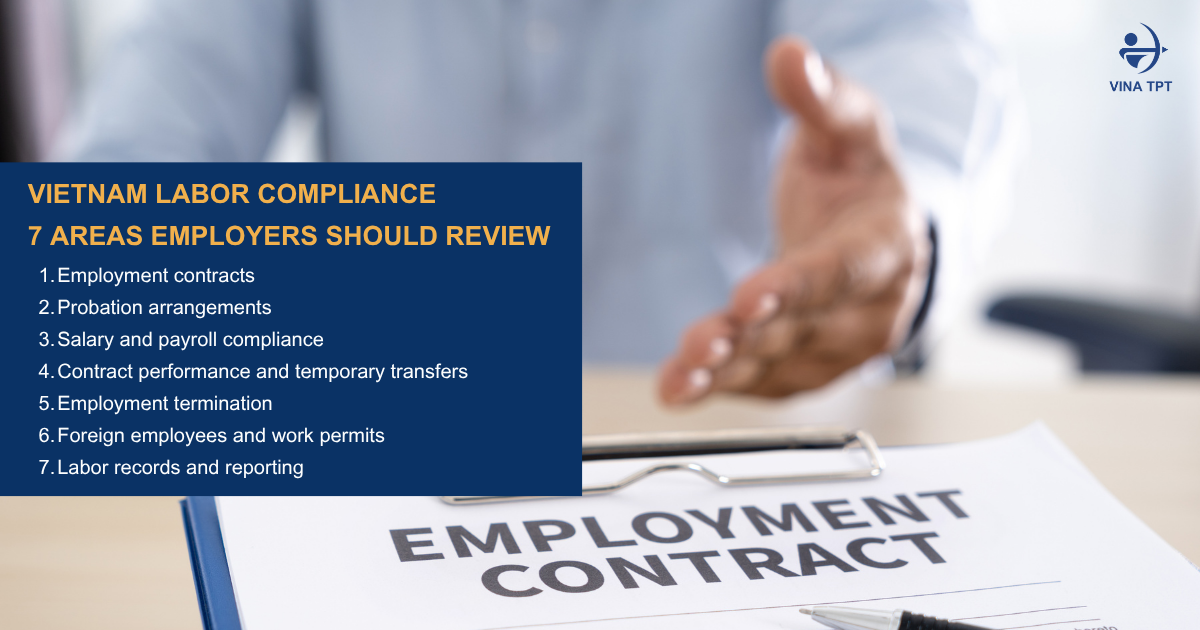
Vietnam labor compliance: Employment contracts, payroll records and work permits are part of a company’s day-to-day operations. Errors in these areas can also lead to administrative fines and obligations to pay employees amounts owed. Based on the information provided on Decree 283/2026/ND-CP, effective from September 10, 2026, sets out administrative penalties for violations in the fields of labor and social insurance.
For businesses in Vietnam, this makes it important to review everyday HR practices, from employment contracts and payroll to work permits and labor records. Below are seven areas employers should pay particular attention to.
1. Employment contracts
Employers may face penalties for failing to sign a written employment contract when required, using the wrong type of contract, or omitting essential terms. Retaining an employee’s original identity documents, diplomas or certificates, and requiring a deposit or other asset as security for the contract, are also identified as violations.
The supplied material states that fines for violations concerning the form, type or contents of an employment contract range from VND 2 million to VND 25 million, depending on the number of affected employees. Retaining original documents or requiring a deposit may result in a fine of VND 20 million to VND 25 million.
Legal reference: Article 15 of Decree 283/2026/ND-CP.
2. Probation arrangements
A business should check how often it applies probation to a position, how long probation lasts and what salary the employee receives. The material specifies that probation should not be applied more than once for the same job, should not exceed the statutory period, and should be paid at no less than 85% of the salary for that job.
Employers must also communicate the probation result and enter into an employment contract when the employee meets the requirements in cases prescribed by law. Some violations carry fines of VND 500,000 to VND 1 million. Applying probation more than once, exceeding the permitted period or paying probation salary incorrectly may result in fines of VND 2 million to VND 5 million. An employer may also be required to pay the outstanding salary or enter into an employment contract.
Legal reference: Article 16 of Decree 283/2026/ND-CP.
3. Salary and payroll compliance
Payroll compliance extends beyond calculating monthly salaries. According to the supplied material, businesses may be fined VND 5 million to VND 10 million for certain failures involving salary scales, payroll tables, labor norms or bonus policies. These include failing to establish or disclose them, failing to consult the workplace employee representative organization when required, providing a noncompliant payslip, or failing to ensure equal pay for work of equal value.
Other salary violations include late or insufficient payment of contractual wages, overtime pay, night-work pay or work-stoppage pay. Improper deductions, failure to pay for unused annual leave when employment ends, and failures concerning salary during a temporary transfer or work suspension are also listed. The stated fine ranges depend on the number of affected employees:
| Affected employees | Fine range |
| 1–10 | VND 5–10 million |
| 11–50 | VND 10–20 million |
| 51–100 | VND 20–30 million |
| 101–300 | VND 30–40 million |
| 301 or more | VND 40–50 million |
Paying below the government-prescribed minimum wage carries separate stated ranges: VND 20–30 million for 1–10 affected employees, VND 30–50 million for 11–50, and VND 50–75 million for 51 or more.
The material also addresses employees who are not subject to compulsory social, health and unemployment insurance. Their employer must pay an additional amount alongside salary equivalent to the employer’s contribution obligations. Failure to pay all or part of this amount may result in fines ranging from VND 3 million to VND 20 million, depending on the number of affected employees.
Depending on the violation, the business may be required to pay outstanding or late salary plus interest, or the unpaid insurance-equivalent amount plus interest.
Legal reference: Article 23 of Decree 283/2026/ND-CP.
4. Contract performance and temporary transfers
When assigning an employee to different work, businesses should review the notice given, the reason and duration of the transfer, and whether the employee’s consent is required. The supplied material also identifies risks in assigning a workplace different from that stated in the contract or failing to take an employee back after a period of contract suspension.
Fines for certain violations may range from VND 1 million to VND 7 million. The material lists higher ranges for workplace sexual harassment that does not reach the level of a criminal offence (VND 15–30 million) and coercion or mistreatment of employees (VND 50–75 million).
Legal reference: Article 17 of Decree 283/2026/ND-CP.
5. Employment termination
At the end of an employment relationship, employers should check whether written notice is required and whether all payments and documents have been completed. This includes employee entitlements, applicable severance or job-loss allowances, social and unemployment insurance procedures, and the return of documents or provision of relevant records when requested.
The stated fine for failing to give required written notice is VND 1 million to VND 3 million. Violations involving payments, allowances or post-termination documents may carry fines of VND 1 million to VND 20 million, depending on the number of affected employees.
Legal reference: Article 18 of Decree 283/2026/ND-CP.
6. Foreign employees and work permits
Businesses employing foreign nationals should review whether each employee holds a valid work permit or confirmation of exemption, and whether their actual work matches the permit. They should also check notification obligations when an employee works in multiple provinces or cities, as well as procedures for returning a permit or exemption confirmation when required.
According to the supplied material, a foreign employee working without a valid work permit or exemption confirmation may face a fine of VND 15 million to VND 25 million. For an employer using foreign employees without valid permits, the stated fines are VND 30–45 million for 1–10 employees, VND 45–60 million for 11–20, and VND 60–75 million for 21 or more. In some cases, a foreign employee may also be expelled from Vietnam.
Legal reference: Article 13 of Decree 283/2026/ND-CP.
7. Labor records and reporting
Workforce administration includes declarations of labor use, a labor management register, reports on changes in employment, and registration or updates to labor registration information.
The supplied material indicates fines of approximately VND 1 million to VND 10 million for violations involving declarations or the labor management register. Failure to register or update labor registration information may result in fines of VND 5–10 million for 1–50 employees, VND 10–15 million for 51–100, and VND 15–20 million for 101 or more.
Legal references: Articles 11 and 12 of Decree 283/2026/ND-CP.
Download Vina TPT’s checklist to review your company’s compliance with the seven employment areas covered in this article.
Download the Compliance Checklist for Labor & SHUI
Vina TPT – Review HR & Payroll Records Regularly
Administrative fines are only one possivinable consequence of a compliance gap. Depending on the violation, a business may also need to pay outstanding wages or benefits, pay interest, complete missing documents or fulfil other outstanding obligations. Regular reviews of employment contracts, payroll records, social insurance documents, work permits and labor reports can help businesses identify issues that need attention.
Vina TPT provides businesses in Vietnam with support across company incorporation, accounting, tax, HR and payroll, and business compliance. For the matters covered in this article, our HR and payroll services support salary calculation, social insurance record management, personal income tax calculation and filing, and related workforce administration.
Contact Vina TPT to discuss your company’s HR and payroll needs and the wider support required to manage your operations in Vietnam.
Decree 283/2026/NĐ-CP governs administrative penalties in the fields of labor, social insurance, and Vietnamese workers working abroad under contracts. Issued on July 15, 2026, it took effect on September 10, 2026, replacing Decree No. 12/2022/NĐ-CP.
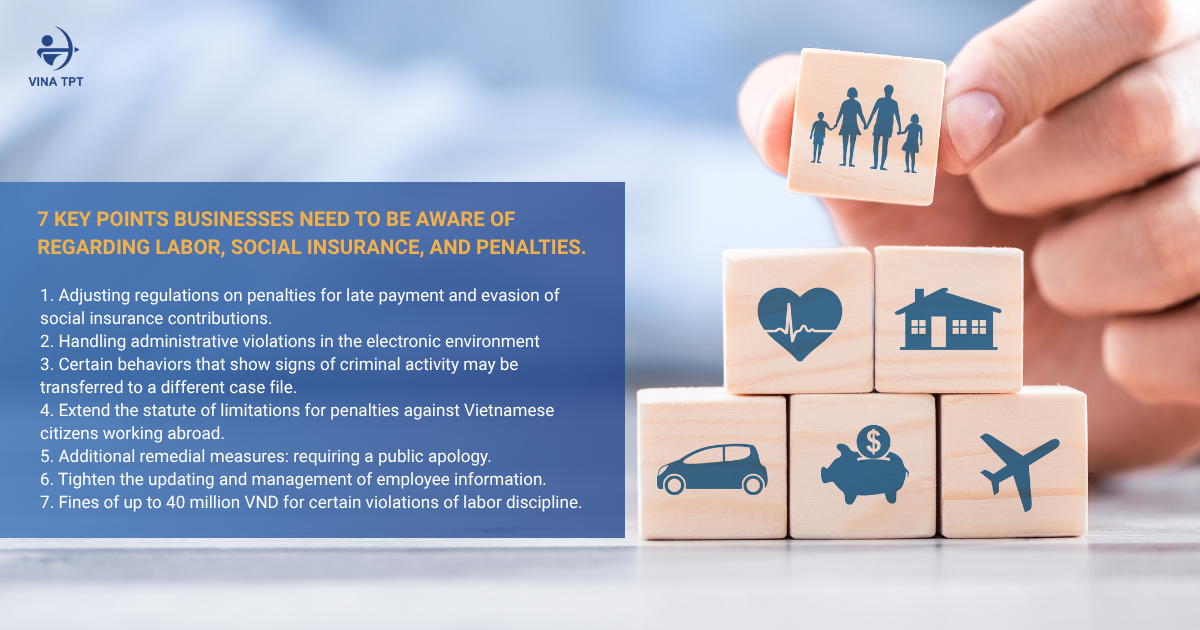
Compared with the previous regulations, Decree 283/2026/NĐ-CP introduces several notable provisions concerning late payment and evasion of compulsory social insurance and unemployment insurance contributions, employee data management, handling violations electronically, and labor discipline.
Below are seven points businesses should review to comply with the new regulations.
1. Revised penalties for late payment and evasion of social insurance and unemployment insurance contributions
Businesses should pay particular attention to the new rules on late payment and evasion of compulsory social insurance and unemployment insurance contributions.
Late payment of compulsory social insurance contributions
Under Article 43 of Decree No. 283/2026/NĐ-CP, late payment of compulsory social insurance contributions may be penalized based on a percentage of the total overdue amount.
Specifically:
- A warning may be issued if the amount involved is less than VND 400,000 at the time the violation is officially recorded.
- A fine of 12% to 15% of the total overdue compulsory social insurance contributions may be imposed, subject to the prescribed maximum of VND 75 million.
- The business must also pay the outstanding contributions in full and an additional amount equal to 0.03% per day, calculated on the overdue amount and period in accordance with the regulations.
Evasion of compulsory social insurance contributions
Evasion of compulsory social insurance contributions is subject to a fine of 18% to 20% of the total amount evaded, subject to the prescribed maximum.
The Decree also sets out separate provisions for employers that fail to register, or fail to register all individuals required to participate in compulsory social insurance, after a period of 60 days.
The penalty is determined based on the number of affected employees.
Late payment and evasion of unemployment insurance contributions
Similarly, Articles 45 and 46 of Decree 283/2026/NĐ-CP separately address late payment and evasion of unemployment insurance contributions.
Late payment may be subject to a fine of 12% to 15% of the total overdue amount, up to the prescribed maximum of VND 75 million.
Evasion may be subject to a fine of 18% to 20% of the total amount evaded, up to the prescribed maximum of VND 75 million.
In addition to fines, businesses must implement the applicable remedial measures.
Businesses should note: When determining the fine applicable to an organization, they need to consult the provisions on fines for organizations in Decree No. 283/2026/NĐ-CP, rather than directly applying only the amount stated for each violation.
2. Handling administrative violations electronically
Decree No. 283/2026/NĐ-CP adds provisions for handling administrative violations electronically when the relevant infrastructure, technical, and information requirements are met.
Violation records, decisions, and related documents may be sent through prescribed electronic channels, including:
- The email address that the individual in violation or the representative of the organization in violation has provided to the competent authority;
- The national digital identification application or an electronic identification account that meets authentication requirements;
- Applications specified in sector-specific legal documents;
- SMS messages sent to a previously provided phone number; and
- The email addresses of the fine collection agency and other relevant agencies for enforcement purposes.
Businesses should therefore keep the contact details, email addresses, and electronic accounts used in dealings with state authorities up to date to avoid missing notices or documents relating to violations.
3. Cases showing signs of criminal activity may be referred to competent authorities
Under Decree 283/2026/NĐ-CP, if an act shows signs of a crime during the review or handling of a violation, the official handling the case must refer the relevant file to the competent criminal proceedings authority.
Notable acts include:
- Using forged papers or documents;
- Illegally accessing, sharing, using, buying, selling, or exchanging information or data in the employee database that has not been made public by a competent authority;
- Infringing an employee’s honor, reputation, or dignity during disciplinary proceedings;
- Exploiting activities involving Vietnamese workers working abroad to organize illegal departures, exploitation, or forced labor; and
- Repeatedly violating the rules by assigning workers aged 15 to under 18 to prohibited jobs or workplaces.
These provisions highlight the need for businesses to pay close attention to the accuracy of personnel records, data security, and procedures for handling employee matters.
4. Longer limitation period for violations involving Vietnamese workers working abroad
Decree No. 283/2026/NĐ-CP sets the following limitation periods for imposing administrative penalties:
- One year for administrative violations relating to labor and social insurance; and
- Two years for administrative violations involving Vietnamese workers working abroad under contracts.
The limitation period for violations in the field of sending Vietnamese workers abroad under contracts has therefore increased from one year to two years.
Businesses operating in this field should take the new period into account when reviewing records, contracts, and related compliance obligations.
5. Additional remedial measure: mandatory public apology
Alongside fines, Decree 283/2026/NĐ-CP adds or further specifies remedial measures, including a mandatory public apology in certain cases.
This measure may apply to specified acts, such as:
- Workplace sexual harassment that does not warrant criminal prosecution;
- Forced labor or mistreatment of employees that does not warrant criminal prosecution;
- Requiring an employee to perform a labor contract to repay a debt owed to the employer; and
- Certain violations relating to the organization and operation of trade unions.
Depending on the violation, a business may also be required to reinstate an employee, pay wages, or refund amounts it collected.
When reviewing compliance, businesses should therefore consider all applicable remedial measures as well as the potential fine.
6. Stricter requirements for updating and managing employee information
Decree No. 283/2026/NĐ-CP also addresses the provision, updating, and management of employee information.
For employees subject to compulsory social insurance, failure to provide information, or provision of incomplete or inaccurate information for labor registration, may be subject to penalties under the regulations.
Employment service businesses are required to:
- Create and update employee data;
- Manage employer data;
- Protect the safety and confidentiality of personal data; and
- Protect the safety and confidentiality of labor data and employment transaction data.
The Decree also prescribes penalties for illegally accessing, sharing, using, buying, selling, or appropriating employee data that has not been made public. In particular:
- Illegal access, sharing, or use of data may be subject to the prescribed fines; and
- Illegal buying, selling, exchanging, or appropriation of data may be subject to a fine of up to VND 70 million if the conduct does not warrant criminal prosecution.
Businesses should use these provisions to review how they manage personnel records, personal information, social insurance data, and internal data access rights.
7. Fines of up to VND 40 million for certain labor discipline violations
Article 25 of Decree 283/2026/NĐ-CP prescribes penalties for certain violations concerning labor discipline and material liability.
Businesses may be penalized for:
- Failing to inform employees of the internal labor regulations;
- Failing to display the main provisions of the internal labor regulations at the workplace;
- Failing to establish written internal labor regulations when required;
- Failing to register the internal labor regulations as required;
- Applying internal labor regulations that are not yet effective or are no longer effective;
- Taking disciplinary action without following the required procedures or limitation period; or
- Suspending an employee from work contrary to the regulations.
Notably, certain serious violations may be subject to fines of VND 20–40 million, including:
- Imposing a monetary fine or deducting wages instead of taking disciplinary action;
- Taking disciplinary action for conduct that is not specified in the applicable regulations;
- Imposing multiple forms of disciplinary action for a single violation; or
- Taking disciplinary action against an employee during a period when the law prohibits it.
Depending on the circumstances, a business may also be required to reinstate the employee, pay wages, refund amounts collected, or issue a public apology.
Conclusion
Decree 283/2026/NĐ-CP introduces several notable changes to administrative penalties relating to labor, social insurance, unemployment insurance, and Vietnamese workers working abroad under contracts.
For businesses, compliance extends beyond paying social insurance contributions on time. It also involves managing employment records, updating data, establishing and registering internal labor regulations, following proper disciplinary procedures, and protecting employee information.
Reviewing and updating internal procedures can help businesses reduce the risk of violations and manage their workforce in accordance with current regulations.
Need to review your employment records and social insurance compliance?
Vina TPT provides HR & Payroll services and labor compliance advice, supporting businesses with personnel management and their social insurance obligations under current regulations.

30% CIT Reduction: New Tax Policy in Vietnam for 2026–2027 Tax Period
Vietnam has introduced a new tax relief measure for the 2026 and 2027 tax periods under Resolution No. 43/2026/QH16. Eligible enterprises and organizations established under Vietnamese law with annual revenue of no more than VND 10 billion may receive a 30% reduction in corporate income tax (CIT) payable.
The policy is intended to provide additional tax support for eligible businesses. However, the 30% reduction should not be confused with a 30% reduction in the statutory CIT rate. In practice, businesses need to determine their eligible CIT payable first, then apply the reduction in accordance with the applicable rules.
What Does Resolution No. 43/2026/QH16 Say About the Tax Reduction?
Resolution No. 43/2026/QH16 was issued by the National Assembly on 24 August 2026. The Resolution introduces tax reductions for both personal income tax (PIT) and corporate income tax (CIT) for the 2026 and 2027 tax periods as follows:
“…
2. A 30% reduction in corporate income tax payable for the 2026 and 2027 tax periods shall apply to the income of enterprises and organizations established in accordance with Vietnamese law whose annual revenue in 2026 or 2027 does not exceed VND 10 billion.
This reduction does not apply to enterprises established through the division or separation of an enterprise after the effective date of this Resolution, where the combined annual revenue of the enterprises resulting from such division or separation exceeds VND 10 billion in 2026 or 2027.
In cases where an enterprise is already entitled to tax incentives under the Law on Corporate Income Tax or other laws or resolutions of the National Assembly, the corporate income tax reduction specified in this Clause shall be calculated based on the corporate income tax payable after deducting the applicable tax incentives.”
30% CIT Reduction for Enterprises
For CIT, eligible enterprises and organizations may receive a 30% reduction in CIT payable for the 2026 and 2027 tax periods if they are established under Vietnamese law and have annual revenue of no more than VND 10 billion in the relevant tax year.
The reduction does not apply to enterprises formed through the division or separation of an existing enterprise after the Resolution takes effect if the combined annual revenue of the enterprises resulting from such division or separation exceeds VND 10 billion in the relevant year.
For enterprises already benefiting from CIT incentives under the Law on Corporate Income Tax or other laws and resolutions of the National Assembly, the 30% reduction is calculated based on the CIT payable after the applicable tax incentives have been deducted.
30% PIT Reduction for Business Individuals and Households
Resolution 43 also provides a 30% reduction of PIT payable for the 2026 and 2027 tax periods for resident individuals earning business income whose annual revenue does not exceed VND 10 billion.
Although the CIT and PIT provisions use a similar 30% reduction concept and a VND 10 billion revenue threshold, they apply to different taxpayers.
Importantly, this 30% PIT reduction applies only to PIT arising from business income. It does not apply to PIT calculated on employment income, such as salary or wages received by individuals as employees.
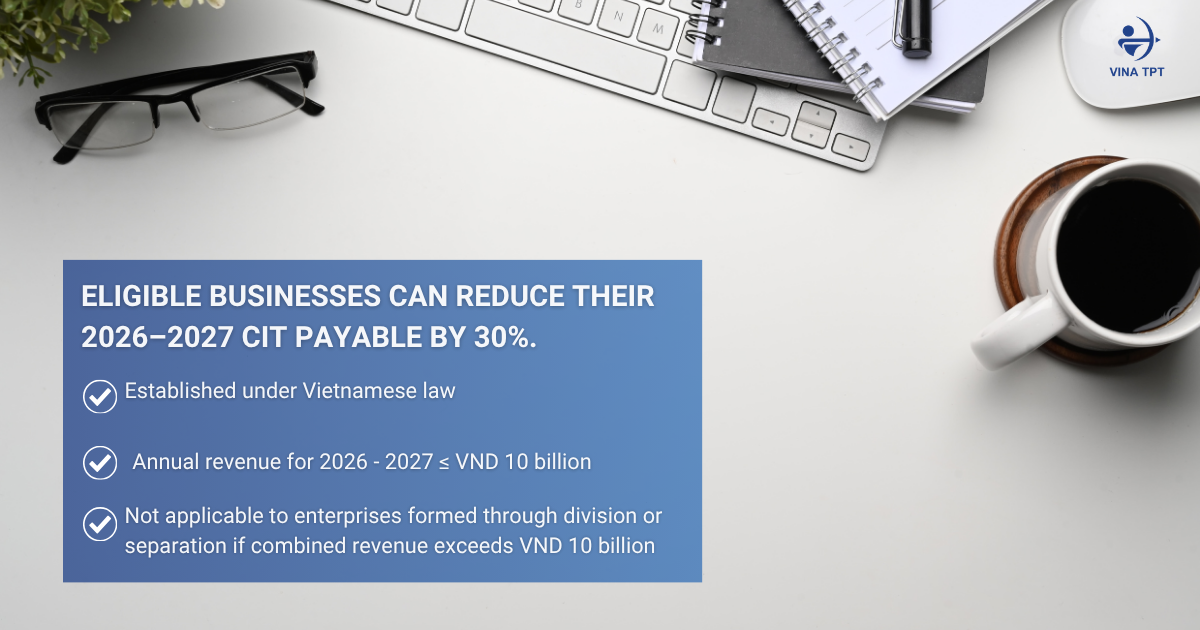
What Is the Current CIT Rate in Vietnam?
The 30% CIT reduction needs to be considered alongside the CIT rates currently applicable in Vietnam.
Under the 2025 Law on Corporate Income Tax, the standard CIT rate is 20%, while 15% and 17% rates may apply to qualifying enterprises based on annual revenue and other statutory conditions.
This makes it important to distinguish between two separate concepts:
- CIT rate — the statutory rate used to calculate CIT liability.
- 30% CIT reduction — a tax relief mechanism that reduces the resulting CIT payable for qualifying businesses.
Reference: Updated 2025 | Corporate Income Tax Rates in Vietnam
Standard CIT Rate: 20%
The general CIT rate under the 2025 Law on Corporate Income Tax is 20%, unless a different rate or preferential tax rate applies.
For example:
If a company has VND 1 billion in taxable profit and the applicable CIT rate is 20%, its CIT payable before the reduction would be VND 200 million. And the company qualifies for the 30% CIT reduction under Resolution No. 43/2026/QH16, it would receive a reduction of VND 60 million (30% of VND 200 million) and would therefore pay VND 140 million in CIT.
=> In other words, the company effectively pays 70% of its applicable CIT liability. The statutory CIT rate, however, remains 20%; it is not reduced to 14%.
15% and 17% CIT Rates for Smaller Enterprises
The 2025 Law on Corporate Income Tax introduced additional CIT rates for qualifying enterprises:
| Annual revenue condition | CIT rate |
| No more than VND 3 billion | 15% |
| Over VND 3 billion to VND 50 billion | 17% |
| General rate | 20% |
The law specifies that the revenue used to determine eligibility for the 15% and 17% rates is based on the total revenue of the immediately preceding CIT tax period, subject to the applicable rules. Certain types of income and enterprises are excluded from these reduced rates.
Businesses should therefore avoid assuming that the VND 10 billion threshold under Resolution 43 and the thresholds for the 15% or 17% CIT rates operate in exactly the same way.
Vina TPT – Accounting & Tax Services
Vina TPT provides accounting, tax and business advisory support for companies operating in Vietnam, with experience supporting foreign-invested businesses and their ongoing compliance requirements.
Our services cover accounting records, periodic tax declarations, CIT, VAT, PIT, foreign contractor tax, payroll and other tax-related compliance matters.
For businesses reviewing their tax position for the 2026–2027 tax periods, our team can support the review of applicable CIT rules, tax incentives and compliance requirements based on the company’s specific circumstances.
Need support with accounting and tax compliance in Vietnam? Contact Vina TPT to discuss your requirements.