Vietnam Salary Regulations 2026: Minimum Wage, Base Salary & Insurance Caps

vietnam-salary-regulations

vietnam salary regulations

Is your foreign-invested enterprise (FDI) fully prepared for the upcoming payroll shifts? 2026 marks a year of major regulatory changes in Vietnam salary regulations, featuring two significant adjustments: the Regional Minimum Wage hike in January and the Base Salary increase in July. For foreign investors, HR professionals, and internal accounting teams, navigating these dual updates is critical to optimizing labor costs and avoiding severe compliance penalties. This ultimate guide will walk you through the essential 2026 salary policies, insurance caps, and overtime rules to ensure your business remains 100% compliant. 

Core Principles of Salary Regulations in Vietnam 

Before diving into the specific 2026 updates, it is vital to understand the foundational rules governing payroll under the Vietnam Labor Code 2019. Adhering to these legal baselines is the first step for any foreign-invested enterprise (FDI) to build a compliant and risk-free HR framework.

According to the Labor Code, all employment contracts and company policies must strictly observe the following core principles:

  • Equality and Non-Discrimination: Employers must pay equal salaries for equal work, regardless of gender, nationality, or social background. Vietnam strictly enforces this principle to ensure fairness in the workplace.

  • Currency of Payment: By default, salaries for Vietnamese employees must be paid in Vietnamese Dong (VND). However, FDI companies and foreign employers are legally permitted to pay expatriate employees in foreign currencies (e.g., USD).

  • Timely and Full Payment: Salaries must be paid fully and on time according to the agreed-upon labor contract. Late payments are strictly regulated by law and may incur mandatory interest penalty payments to the employee if delayed beyond permissible force majeure limits.

2026 Regional Minimum Wage Updates (Effective Jan 1, 2026) 

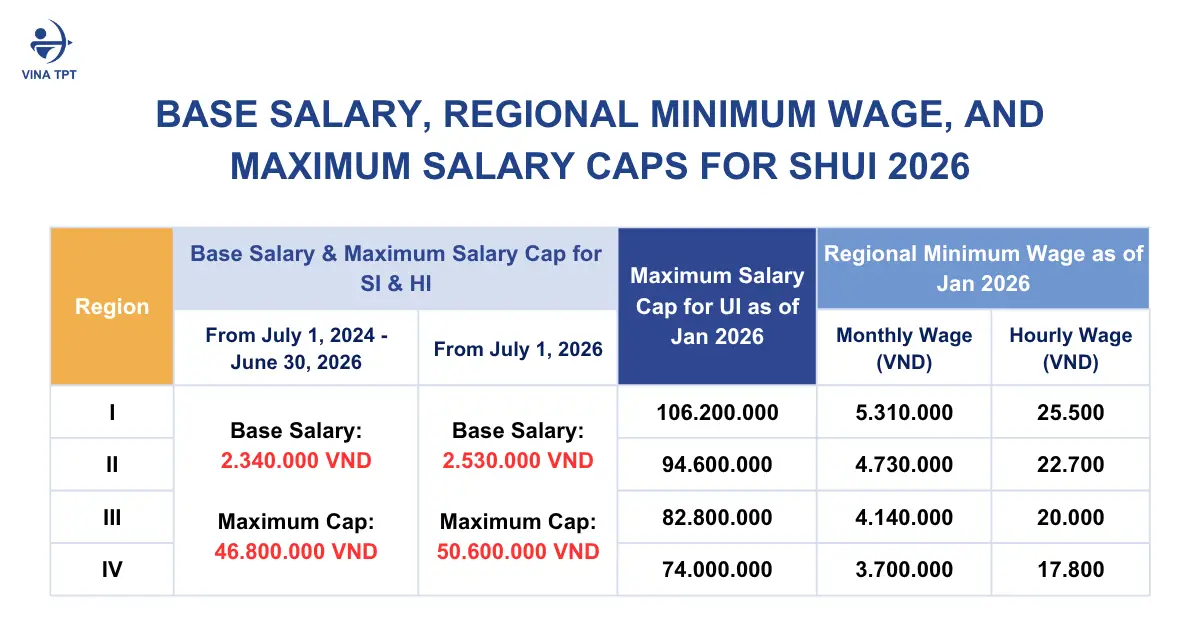
The first major milestone of 2026 is the implementation of Decree 293/2025/ND-CP, which officially increases the Regional Minimum Wage by an average of 7.2%. This minimum wage serves as the absolute floor for negotiating monthly salaries for full-time workers operating under normal conditions. 

Minimum Wage Table by Region (I, II, III, IV) 

FDI companies typically operate in major economic hubs, mostly falling under Region I and II. Here are the updated 2026 rates: 

Region  2026 Monthly Minimum Wage (VND)  Key Applicable Areas 
Region I  5,310,000 VND  Ho Chi Minh City, Hanoi, Binh Duong, Dong Nai, Hai Phong… 
Region II  4,730,000 VND  Da Nang, Can Tho, specific provincial cities 
Region III  4,140,000 VND  Provincial towns and emerging industrial zones 
Region IV  3,690,000 VND  All other rural and remaining areas 

>>>>Read more: Regional Minimum Wage 2026 in Vietnam: Latest Updates and Key Changes

Impact on Unemployment Insurance (UI) Caps 

Critical Compliance Note: The Regional Minimum Wage does not just dictate base pay; it also sets the ceiling for Unemployment Insurance (UI). By law, the maximum salary for calculating UI contributions is capped at 20 times the Regional Minimum Wage. For employees in Region I, the 2026 UI contribution cap is now 106,200,000 VND (20 x 5,310,000 VND). 

The New Base Salary Increase (Effective July 1, 2026) 

While the minimum wage targets the private sector, the Base Salary (Lương cơ sở) under Decree 161/2026/ND-CP primarily dictates public sector wages. However, FDI companies must pay close attention to this decree because the Base Salary directly controls the maximum caps for mandatory social and health insurances in the private sector. 

How Base Salary Affects Social & Health Insurance Caps 

Effective July 1, 2026, the Base Salary will increase to 2,530,000 VND. The legal formula for capping Social Insurance (SI) and Health Insurance (HI) contributions is 20 times the Base Salary. 

  • New SI & HI Cap Calculation: 20 x 2,530,000 VND = 50,600,000 VND. 
  • Impact: Any gross salary exceeding 50,600,000 VND will only be subject to SI and HI calculations up to this absolute ceiling. HR departments must update their payroll software before July 2026 to reflect this new cap and avoid overpaying or underpaying state insurances. 
base-salary-2026-vietnam-minimum-wage-caps

Overtime Pay and Night Shift Salary Regulations 

Vietnamese labor law provides strict guidelines for overtime (OT) and night shift compensation to protect worker rights. FDI businesses must accurately calculate these multipliers: 

  • Regular Workdays: OT is paid at 150% of the standard hourly rate. 
  • Weekly Days Off: OT is paid at 200% of the standard hourly rate. 
  • Public Holidays and Paid Leave: OT is paid at 300% of the standard hourly rate (in addition to the regular holiday pay). 
  • Night Shifts: Working at night (from 22:00 to 06:00) entitles the employee to an additional 30% night shift allowance, plus further multipliers if the night shift falls on an overtime day. 

DISCOVER PAYROLL SERVICES

The 13th-Month Salary and Bonus Regulations: Is It Mandatory?  

A frequent question from foreign investors is whether the 13th-month salary is a legal requirement. According to Vietnam’s salary regulations, a 13th-month bonus is not strictly mandatory by law. It is legally considered a “bonus” based on company performance and employee productivity. 

However, it is a deeply ingrained market norm. More importantly, if the 13th-month salary is explicitly written into the Labor Contract or the Collective Labor Agreement (CLA), it becomes legally binding and must be paid regardless of the company’s financial status that year. 

FDI Compliance: A 5-Step Payroll Audit Checklist 

To ensure a smooth transition into the 2026 fiscal year, internal accounting and HR teams should execute the following 5-step checklist: 

  1. Review Labor Contracts: Ensure no employee in Region I is being paid below the new 5,310,000 VND threshold.
  2. Update Payroll Software: Adjust system parameters to reflect the January Minimum Wage UI caps and the July Base Salary SHI caps.
  3. Adjust Insurance Contributions: Re-declare insurance levels with the local Social Insurance Authority based on the new ceilings.
  4. Recalculate HR Budgets: Factor the 7.2% wage increase and higher insurance caps into your H2 2026 operational budget.
  5. Consult a Tax Expert: Review your Personal Income Tax (PIT) and payroll structures to optimize tax efficiency for both local and expatriate staff. 

Frequently Asked Questions (FAQs) on Salary Regulations 

  1. Can salaries be paid in USD?

Yes, but only for expatriates (foreign workers). Under Vietnam’s foreign exchange controls, salaries for Vietnamese citizens must be denominated and paid in VND. 

  1. What is the penalty for late salary payment?

If a salary payment is delayed by more than 15 days (due to force majeure), the employer must compensate the employee with an additional amount. This penalty is calculated based on the delayed amount multiplied by the State Bank of Vietnam’s 1-month deposit interest rate. 

  1. Are probationary salaries subject to full insurance?

No. Probationary salaries must be at least 85% of the official job salary. Furthermore, mandatory social insurance contributions are generally not required during a standard probation period (which lasts up to 60 days). 

Vietnam’s salary regulations in 2026 bring a layer of complexity that can easily trigger administrative penalties if mishandled. From navigating dual wage increases to calculating exact insurance caps and PIT deductions, the margin for error is slim. 

Why Vina TPT is the Trusted Choice for Payroll Services in Vietnam  

With over 20 years of experience supporting FDI companies and remote teams, Vina TPT offers a specialized, secure, and fully compliant remote payroll service tailored to Vietnam’s latest legal frameworks. 

We handle complex salary calculations, social and health insurance management, unemployment insurance caps, PIT withholding, and digital payslips—entirely online with real-time dashboards. Our team provides excellent English support, utilizes a highly secure cloud system, and operates under a clear Service Level Agreement (SLA). This gives foreign investors complete confidence and 100% compliance, even when you are not physically present in Vietnam. 

Contact Vina TPT today for a free consultation and to experience professional remote payroll services. Let our experts handle your payroll and labor compliance so you can focus seamlessly on growing your core business. 
BOOK A FREE CONSULTATION

payroll-services-in-vietnam-vina-tpt

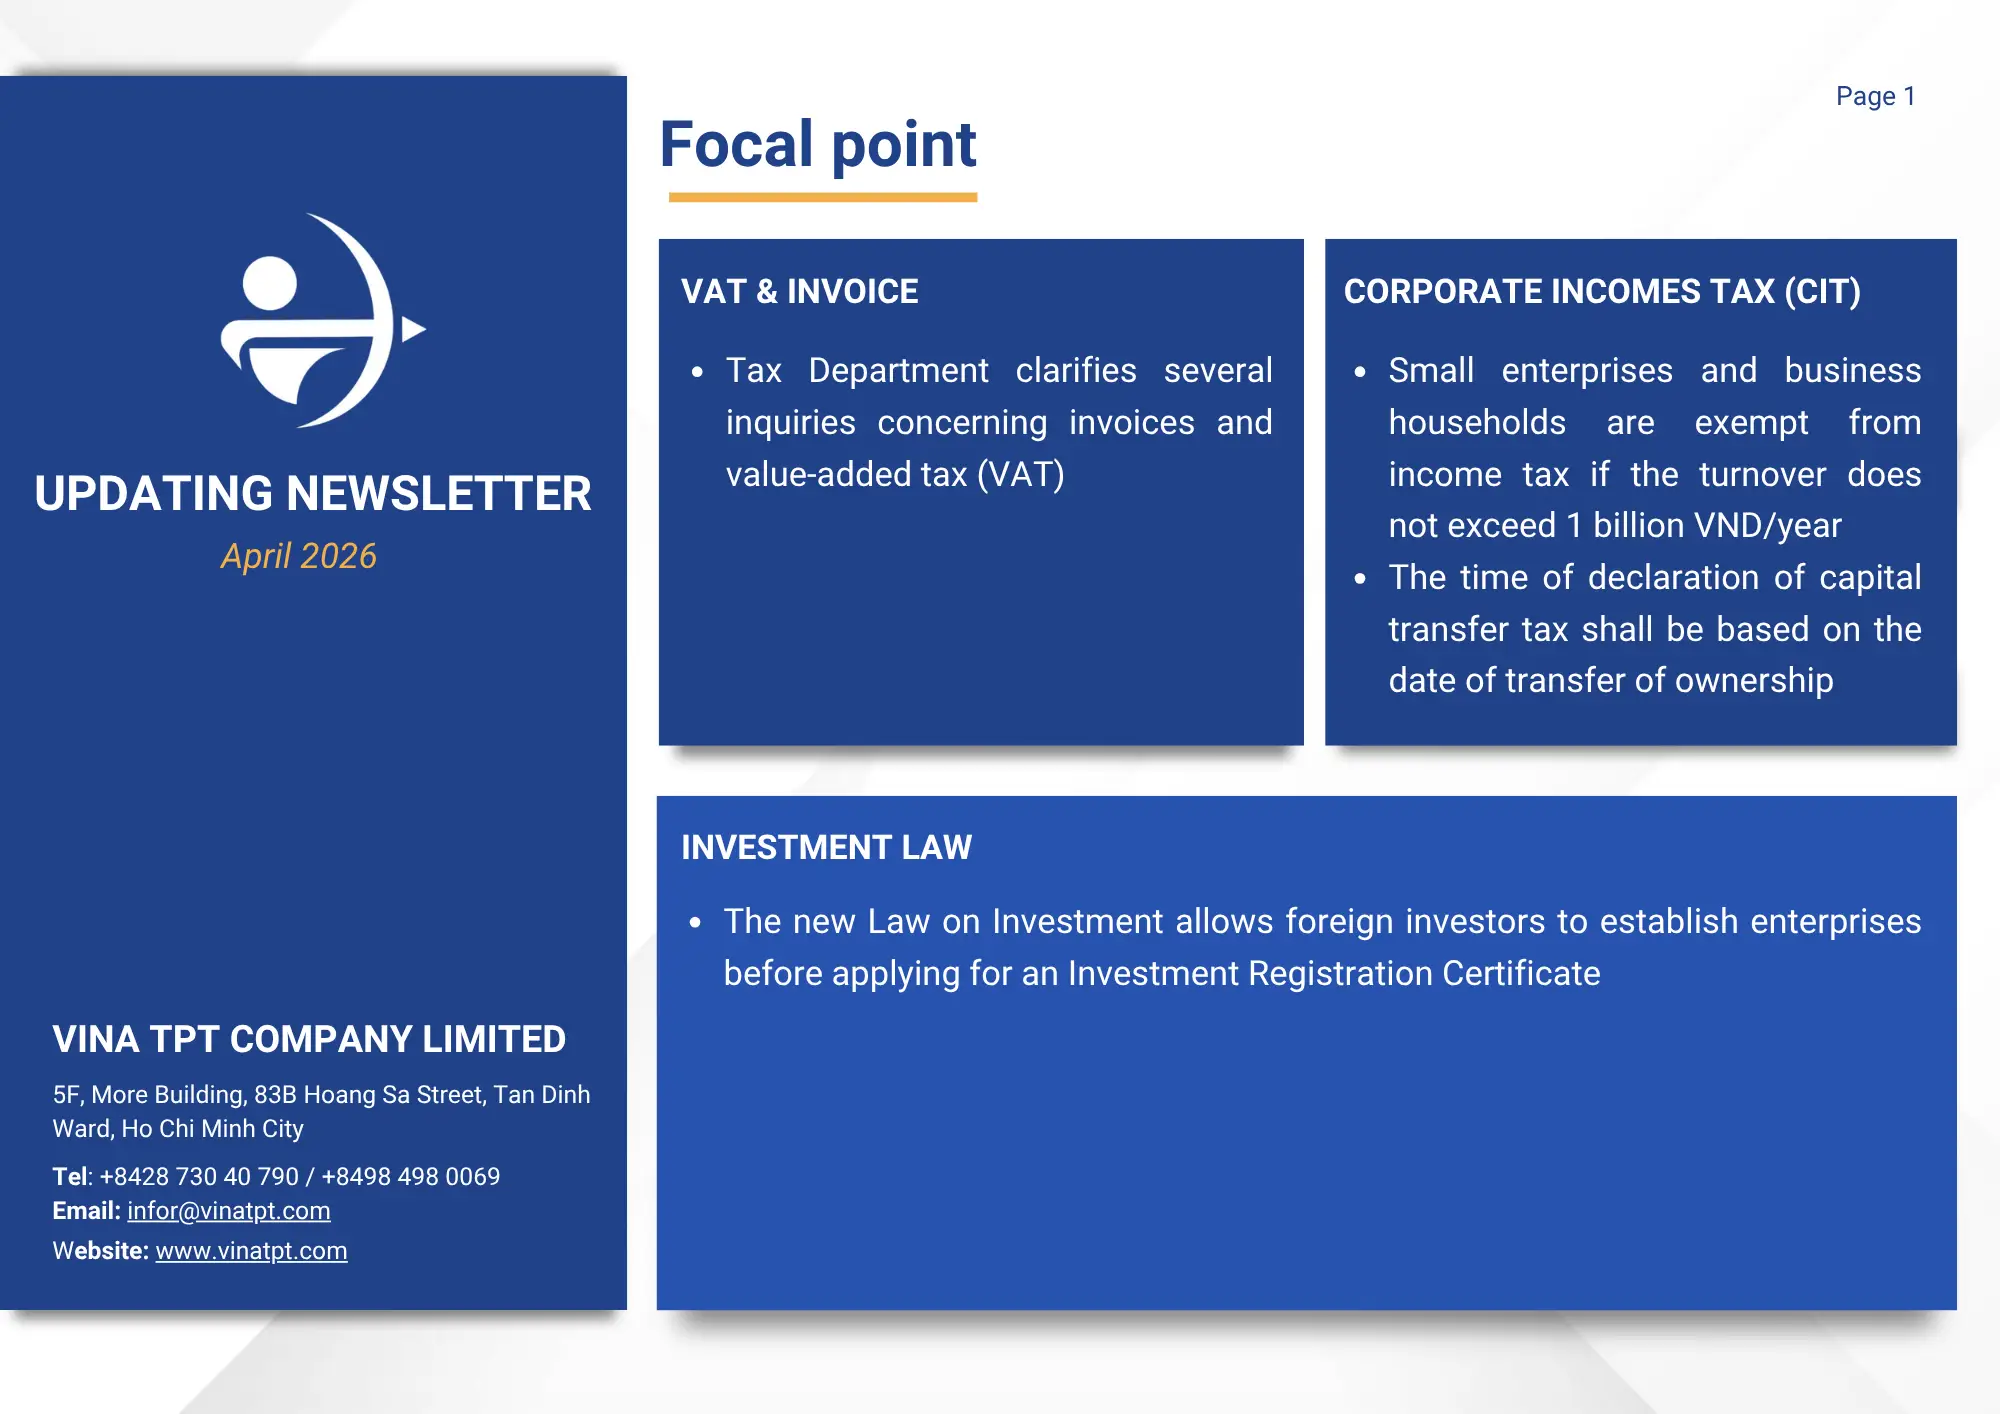
[Newsletter] Vietnam Tax & Investment Updates – April 2026

The Vietnam tax & legal landscape for foreign-invested enterprises (FDI) has undergone significant adjustments as of April 2026. From new corporate income tax (CIT) exemptions for small businesses to modernized investment registration procedures and clarified invoicing regulations, staying informed is critical for operational compliance. This update provides a comprehensive overview of the latest decrees and official letters that will impact your business strategy in Vietnam.

New Tax Exemption Threshold for Small Businesses (Decree 141/2026/ND-CP)

The Government of Vietnam recently promulgated Decree No. 141/2026/ND-CP (effective from January 1, 2026), amending policies for business households and individuals, as well as measures guiding the implementation of the Law on Corporate Income Tax.

Key Changes

  • Exemption Threshold: The government has raised the income tax exemption threshold for business households and individuals to VND 1 billion per year.
  • CIT Exemption: Small businesses with an annual turnover not exceeding VND 1 billion are also exempt from CIT starting in 2026.
  • Overpaid Tax Handling: For small businesses that temporarily paid CIT in the first quarter of 2026, such amounts will be offset or refunded according to overpaid tax principles.

This exemption policy does not apply to small businesses that operate as subsidiaries if their parent company reports a total annual revenue exceeding VND 1 billion.

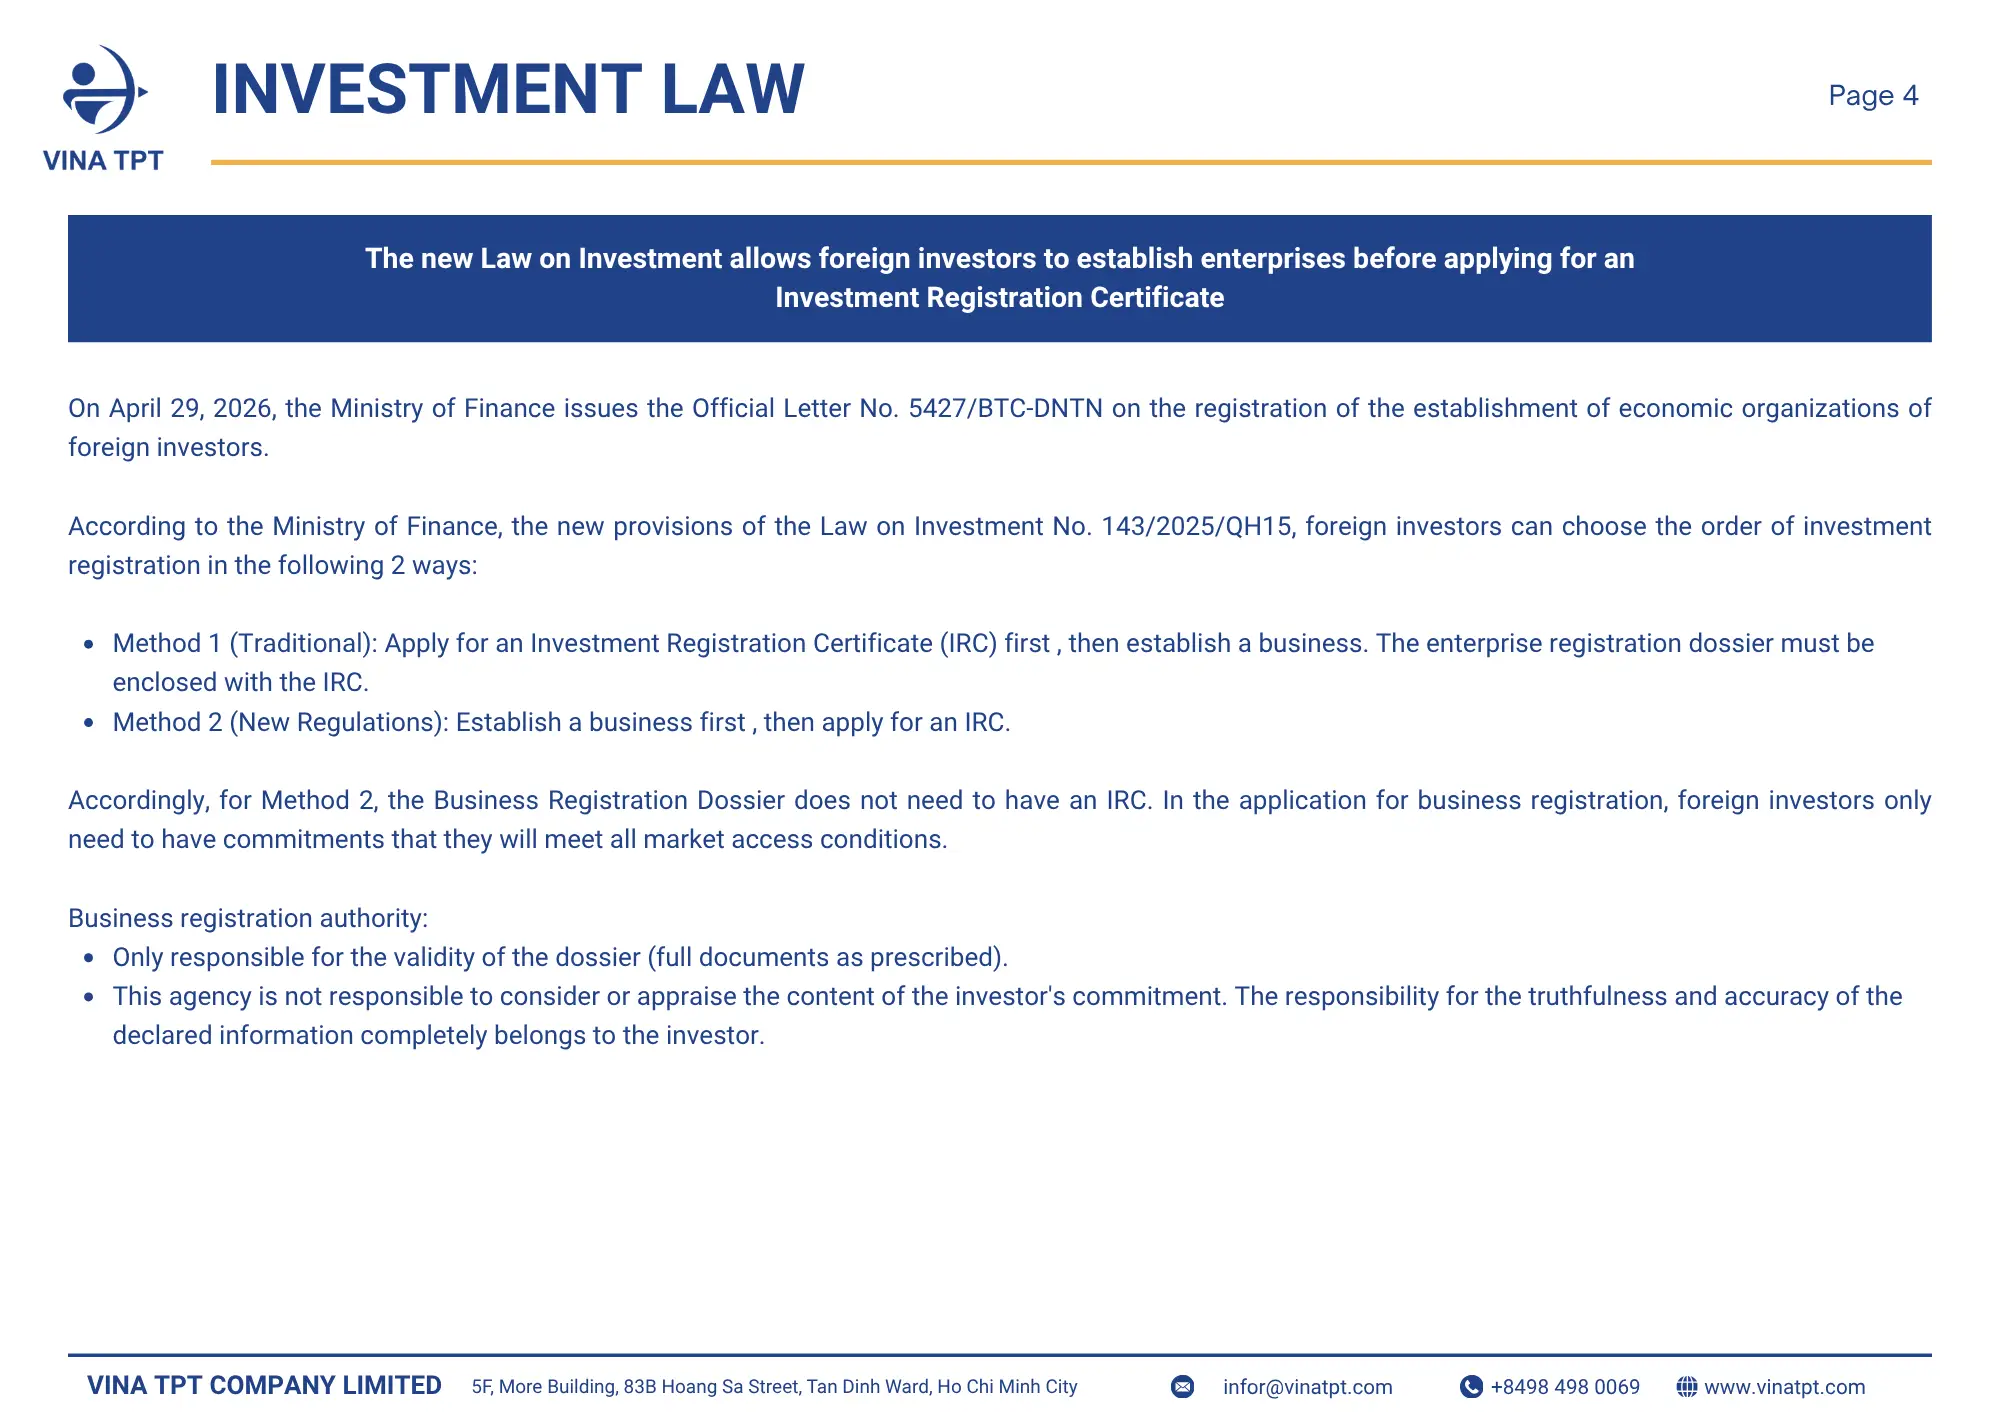
Streamlining FDI Entry: Business Establishment Before IRC

On April 29, 2026, the Ministry of Finance issued Official Letter No. 5427/BTC-DNTN, clarifying new provisions under the Law on Investment No. 143/2025/QH15. Foreign investors now have greater flexibility in the order of their investment registration.

Comparison of Investment Registration Methods

Method Registration Order Requirements
Method 1 (Traditional) Apply for IRC first, then establish business Enterprise registration dossier must include the IRC
Method 2 (New) Establish business first, then apply for IRC Business registration dossier does not require IRC

Under Method 2, foreign investors only need to provide formal commitments that they will meet all market access conditions. The business registration authority is responsible only for verifying the validity of the dossier; it is not responsible for appraising the content of the investor’s commitment, which remains the sole responsibility of the investor.

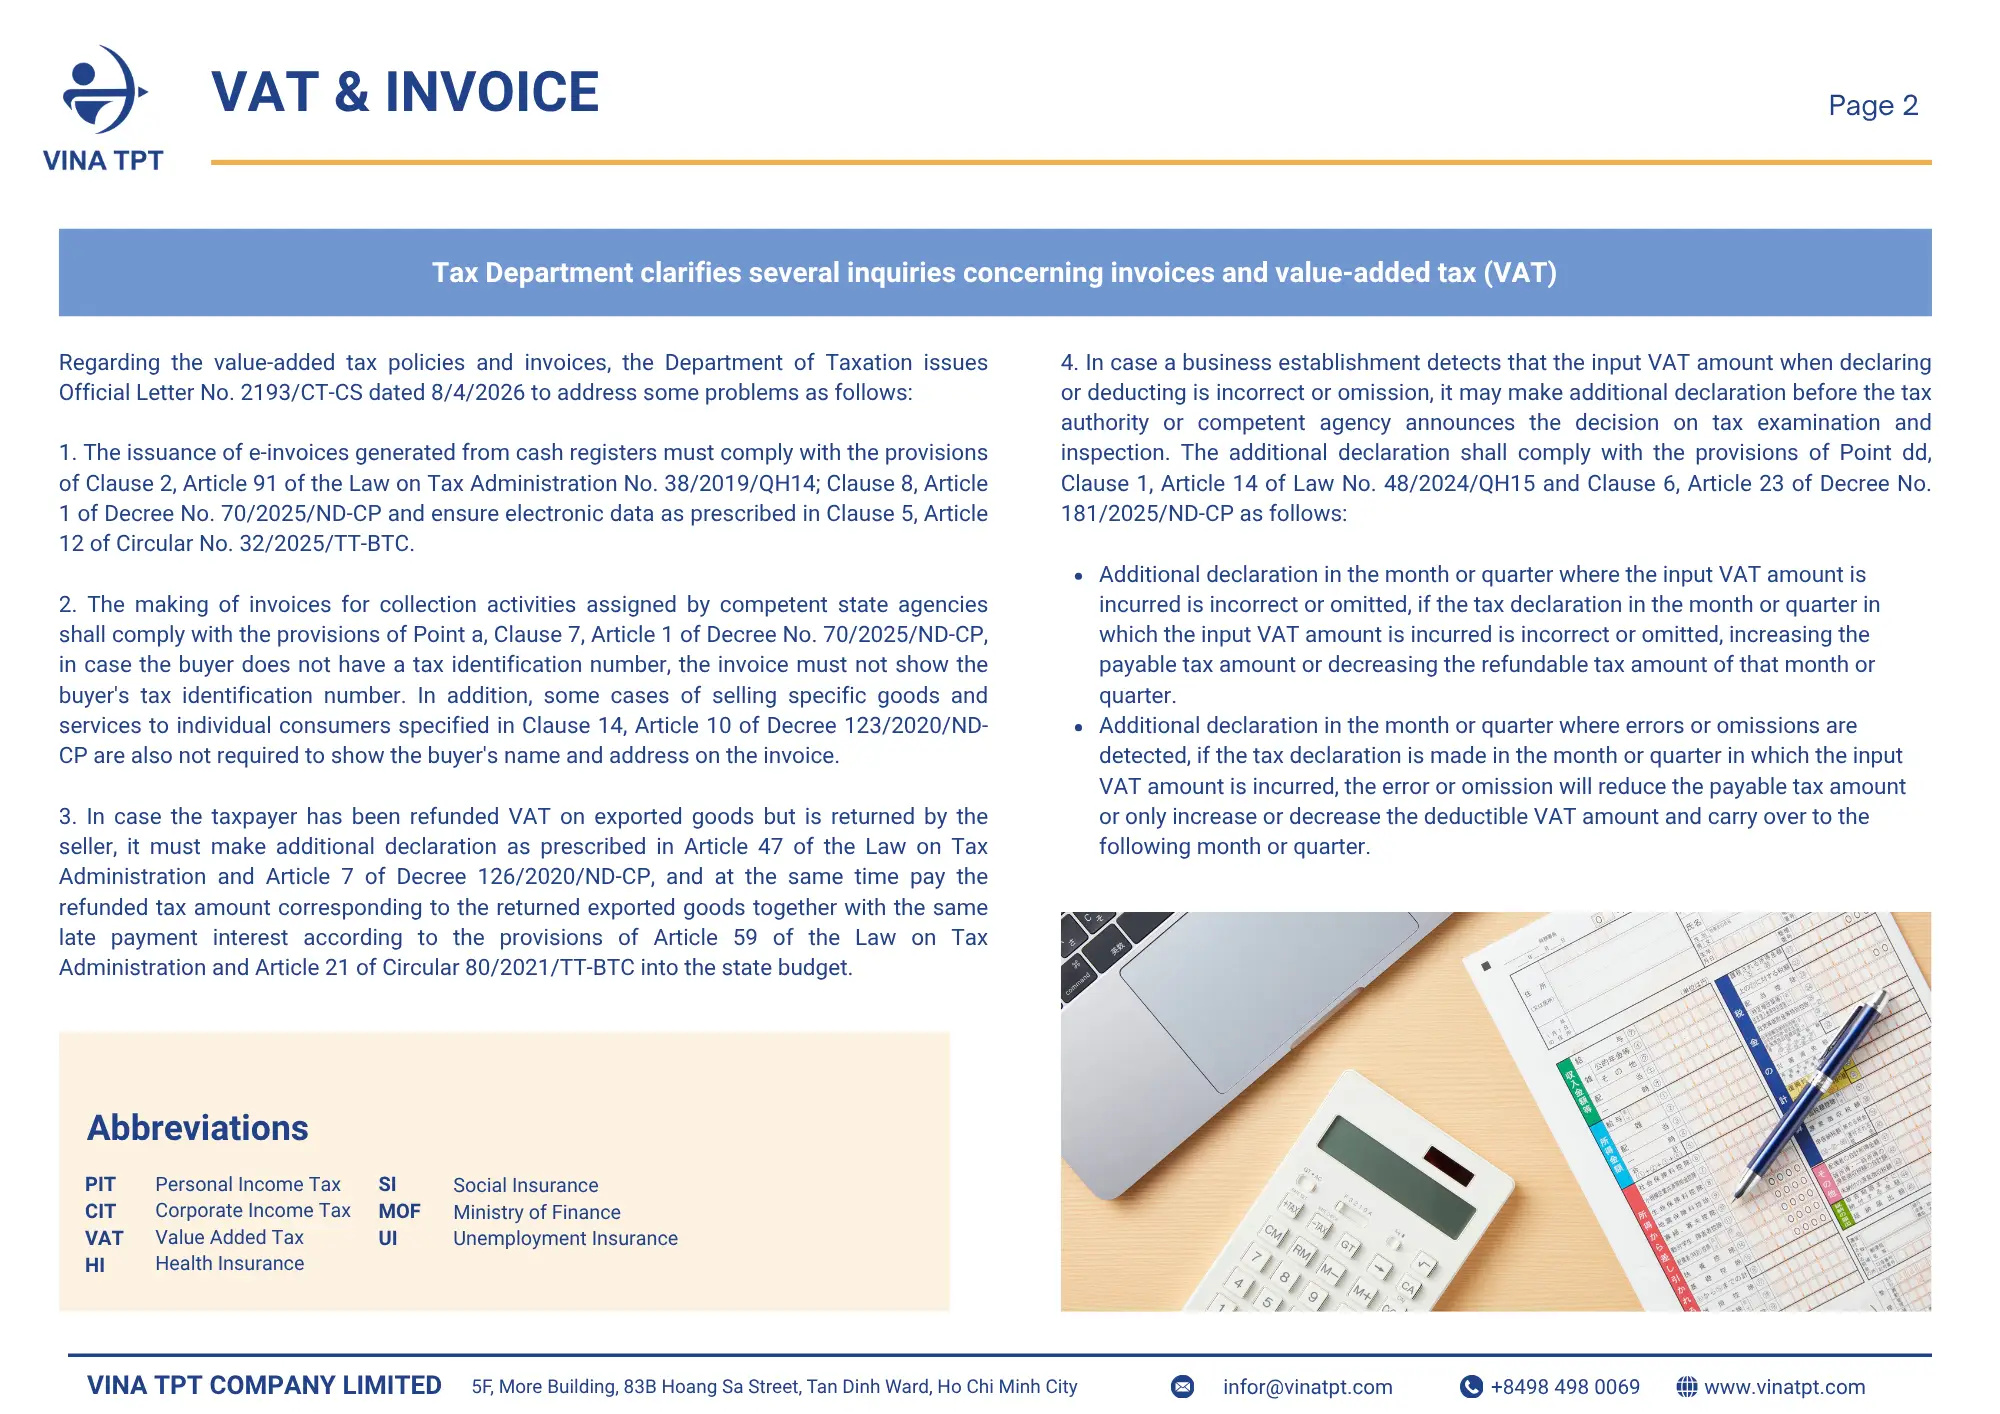
Updates on E-Invoices and VAT Compliance (Official Letter 2193/CT-CS)

The Department of Taxation issued Official Letter No. 2193/CT-CS on April 8, 2026, to address ongoing concerns regarding electronic invoices and value-added tax (VAT).

Critical Compliance Points

  1. Cash Register Invoices: E-invoices generated from cash registers must strictly comply with Clause 2, Article 91 of the Law on Tax Administration and relevant decrees to ensure data integrity.
  2. Collection Activities: For invoices related to collections assigned by state agencies, if the buyer lacks a tax identification number, the invoice must not display one. Additionally, specific goods/services sold to individual consumers are exempt from showing the buyer’s name and address.
  3. Exported Goods Returns: If exported goods for which VAT was previously refunded are returned, taxpayers must file an additional declaration (Article 47, Law on Tax Administration) and pay back the refunded tax plus late payment interest.
  4. Input VAT Corrections: If a business discovers errors in input VAT deduction, they may file an additional declaration before the tax authority announces an official inspection decision.
    • If the error increased the payable tax, it is declared in the month/quarter the error was incurred.

If the error reduced the payable tax or impacted deductible VAT, it may be adjusted in the period the error was detected.

Capital Transfer Tax: Determining the Precise Taxable Timing

Regarding share transfer activities, the Tax Department noted in Official Letter No. 2710/CT-CS (April 28, 2026) that the time of determining taxable income from capital transfer is the time of actual transfer of capital ownership under the transfer contract.

  • Ownership-Based: This timing applies regardless of whether the payment has been collected or not.
  • Declaratory Responsibility: The Vietnamese company where the capital transfer between foreign investors occurs is responsible for declaring and paying the tax on behalf of the foreign investor, pursuant to Circular 78/2014/TT-BTC.

Frequently Asked Questions (FAQs)

Q: If my small business is a subsidiary, am I eligible for the new CIT exemption?

A: No, if your parent company has a total annual revenue exceeding VND 1 billion, the subsidiary is not entitled to this specific exemption.

Q: Can I establish a business in Vietnam before getting an Investment Registration Certificate?

A: Yes, under the new Law on Investment No. 143/2025/QH15, you may establish the business first and apply for the IRC later.

Q: What if I detect an input VAT error after the tax period has passed?

A: You may make an additional declaration, provided the tax authority has not yet announced a decision on tax examination or inspection.

Conclusion & Strategic Consultation

The legal landscape in 2026 presents both new opportunities and complex compliance requirements. Ensuring your business remains aligned with these updates is essential to avoid penalties and optimize tax efficiency.

If you require professional guidance on restructuring your tax filings, managing investment registration, or ensuring compliance with the latest VAT regulations, our team is ready to assist.

Contact us today for a comprehensive legal and tax consultation tailored to your FDI business in Vietnam.

BOOK A FREE CONSULTATION

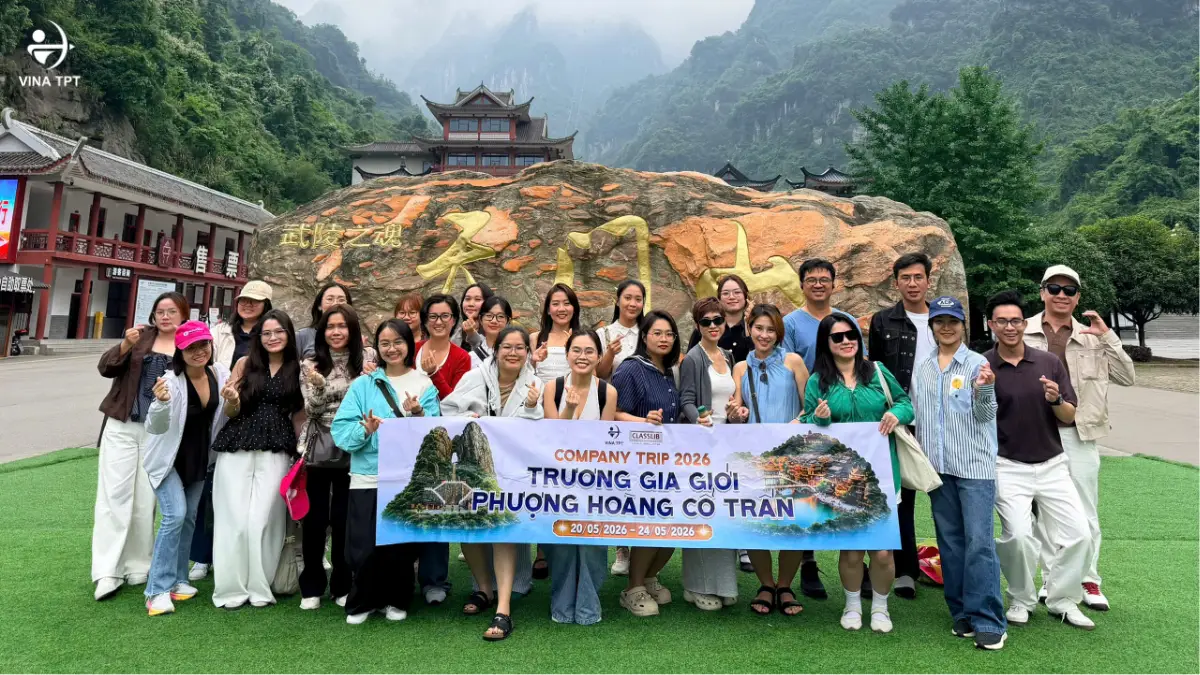
[China] Company Trip: Well-Deserved Reward and a Journey to Expand Global Perspectives

Every tax season leaves behind intellectual challenges, late-night shifts illuminated by endless numbers, and meticulous document reviews by the Vina TPT team. Understanding that our most valuable assets are our diligent and passionate employees, the Board of Directors recently organized a special journey to Enshi – Zhangjiajie – Fenghuang Ancient Town (China). Far from a conventional retreat, this trip served as a meaningful token of appreciation. It offered every team member an opportunity to step out of their comfort zones, broaden their worldviews, and collectively recharge their batteries for upcoming milestones.

A Well-Deserved Reward After a High-Pressure Tax Season

For a professional firm that always prioritizes service quality and client satisfaction, the recent period was a demanding test of both mental strength and endurance for our entire workforce. Intense deadline pressures and the need for absolute mathematical accuracy were ultimately rewarded by the absolute trust of our partners and clients.

Consequently, this company trip was much more than a routine annual benefit. It was the most sincere “thank you” from the leadership team to every single member—those who dedicated themselves wholeheartedly day and night. After hours of intense work, strolling together along the tranquil Tuojiang River in Fenghuang Ancient Town served as an invaluable emotional remedy to wash away fatigue and restore inner balance.

The Leadership’s Vision: Learning and Expanding Worldviews

At Vina TPT & Classlib, we believe that top-tier talent should not only excel within the four walls of an office but should also possess rich life experiences and an open mindset. Field trips, physical exposure, and firsthand experiences allow everyone to gain their own profound insights.

  • Learning from the Grandeur of Nature and Human Innovation: Witnessing how humans engineered the magnificent mountain-spanning cable car system or the Glass Skywalk (San Dao Jing) at an altitude of over 1,400 meters, each member drew personal lessons about the power of willpower and breakthrough thinking.

  • Immersing in Cultural Experiences to Enrich Mindsets: Exposure to a new culture, savoring local cuisine, and admiring thousands of years of ancient architecture significantly enriched our team’s life experiences. As our worldviews expand, our perspectives on work and our approaches to solving client problems become more multi-dimensional, flexible, and creative.

Recharging Warriors’ Spirits for Ambitious Goals

The Gala Dinner night exploded with the slogan “Work Hard, Play Hard,” bringing this meaningful journey to a spectacular close. Returning from the trip, the suitcases of every Vina TPT member held not only beautiful souvenirs but, more importantly, a fully renewed warrior spirit.

Our journey to Zhangjiajie flawlessly fulfilled its mission: honoring hard work, connecting hearts, and inspiring breakthroughs. The leadership’s commitment to investing in people and corporate culture reaffirms that Vina TPT remains an ideal workplace—a place where every individual is valued, nurtured, and given the opportunity to experience, learn, and grow comprehensively.

Become a Part of the Vina TPT Family

Are you looking for a “work hard, play hard” environment where you can gain hands-on experience dealing with complex operations for foreign-invested enterprises, and wrap up busy project seasons with amazing journeys to expand your worldview alongside incredible teammates?

Vina TPT is continuously welcoming talented individuals to join us on our path of creating sustainable value.

👉 Explore our latest career opportunities today:

How to apply:

📩 Send your CV to email: adm@vinatpt.com
📌 Email Subject: [Position] – Full Name
For any questions, please contact our hotline/Zalo: 0984 980 069 or fanpage of Vina TPT

Can an Invoice Issued with the Wrong Date Be Adjusted? Detailed Latest Guidelines for 2026

Instructions for handling invoices issued with the wrong date

Can an invoice issued with the wrong date be adjusted?

In practice, mistakes involving invoices issued with the wrong date are a constant, quiet source of anxiety for accountants and business owners alike. A single oversight regarding the date can lead to unnecessary legal risks, particularly as regulations governing electronic invoices become increasingly stringent. Are you struggling to figure out whether an invoice with an incorrect date can be adjusted? Will your enterprise face administrative penalties or be denied input VAT deductions?

Rest assured, the answer is YES, it can certainly be adjusted. However, enterprises must strictly comply with official invoice adjustment guidelines.

Specifically, under Decree No. 123/2020/ND-CP (along with amendments and supplements in Decree No. 70/2025/ND-CP applicable from June 2025), the resolution process has shifted toward issuing either an adjustment invoice or a replacement invoice.

Important Note: Canceling an invoice to reissue it from scratch is virtually no longer accepted for incorrect date errors, except in a few special technical scenarios. Executing a written agreement between both parties remains a mandatory legal step to protect your enterprise during tax audits.

This article synthesizes detailed instructions, step-by-step procedures, updated penalty rates, tax deduction guidelines, and key compliance notes to help you handle errors correctly, avoid fines, and ensure valid documentation according to the latest 2026 regulations.

1. What Is an Invoice Issued with the Wrong Date? Common Errors & Consequences

An invoice issued with the wrong date (issued at an improper time) occurs when an invoice is generated outside the timeframes specified under Article 9 of Decree No. 123/2020/ND-CP (as amended by Decree No. 70/2025/ND-CP). The proper time to issue an invoice is generally upon delivery of goods, completion of service provision, or final sign-off and handover.

Common Error Scenarios:

  • Generating an invoice prior to the actual date of goods delivery or service handover.
  • Generating an invoice many days or months after the delivery date (backdating or delayed issuance).
  • Recording an incorrect day, month, or year on the invoice compared to actual transaction facts.
  • Mismatched VAT tax declaration periods caused by improper timing.

Severe Consequences of Improper Handling:

  • Administrative tax fines concerning invoices (ranging from formal warnings to tens of millions of VND).
  • Disallowance of input VAT deductions (for the buyer) or rejection of legitimate business expenses (for the seller).
  • Elevated exposure to tax inspection and audit risks.
  • Adverse impacts on financial statements and corporate reputation.

Understanding these errors allows you to resolve issues proactively, swiftly, and in full compliance with the law.

2. Can an Invoice Issued with the Wrong Date Be Adjusted?

An invoice issued with the wrong date can be adjusted. Starting June 1, 2025, pursuant to Clause 13, Article 1 of Decree No. 70/2025/ND-CP amending Article 19 of Decree No. 123/2020/ND-CP, any errors on electronic invoices (including incorrect dates) cannot be canceled; instead, they must be addressed via an adjustment invoice or a replacement invoice.

Case 1: The Invoice Has Not Been Delivered to the Buyer

This is the easiest scenario to resolve because the invoice has not yet impacted the buyer, nor has it completed final data submission cycles.

Resolution Steps:

  1. The seller issues a replacement invoice for the erroneous invoice (replacement is preferred since the timing is completely wrong).
  2. The replacement invoice must feature the mandatory text: “Replacing invoice Form No…., Symbol…., No…., dated [Day]/[Month]/[Year]…”
  3. A written agreement is not required if the invoice has not been sent to the buyer.
  4. Once the replacement in voice is generated, the system automatically invalidates the original invoice within the tax authority database (under updated mechanisms).

Important Notes:

  • Take action immediately upon detecting the error to avoid disrupting VAT declaration cycles.
  • If the invoice was already granted a tax authority code but not yet delivered, follow the same replacement procedure.
  • Benefit: Involves no additional procedures with the buyer, minimizing dispute risks.

Adjusting an invoice issued with the wrong date

Case 2: The Invoice Has Been Delivered to the Buyer but Not Yet Declared for Tax

This situation commonly arises when an error is caught within the same reporting period.

Resolution Steps:

  1. Both parties (seller and buyer) execute a written agreement explicitly stating the error (wrong date), the adjustment content, and the original invoice information.
  2. The seller issues an adjustment invoice (most suitable when only the date is incorrect while all other details remain accurate) or a replacement invoice.
  3. Mandatory text required on the adjustment invoice: “Adjusting invoice Form No…., Symbol…., No…., dated [Day]/[Month]/[Year]…”
  4. Declare the adjustment or replacement invoice in the same reporting period as the original invoice to avoid supplementary returns.
  5. Send the written agreement along with the new invoice to the buyer and transmit data to the tax authority.

This method preserves document continuity, allowing the buyer to claim input VAT deductions normally without affecting tax reports.

Note: Executing a written agreement is mandatory when the buyer is a business enterprise, an organization, or a business household starting from June 1, 2025.

Case 3: The Invoice Has Been Delivered to the Buyer and Already Declared for Tax

This is the most complex scenario because it affects the tax declaration obligations of both parties.

Resolution Steps:

  1. Execute a written agreement between both parties detailing the mistake and corrective adjustments.
  2. Issue an adjustment invoice (preferred) or a replacement invoice featuring clear notation as outlined above.
  3. File supplementary VAT returns for the period in which the original invoice arose (if the incorrect date caused the invoice to fall into a different tax period) pursuant to supplementary declaration rules.
  4. Both the seller and the buyer must adjust their respective VAT returns.

Risks of Inaction: The seller faces administrative fines for improper invoice timing. The buyer risks having input VAT deductions disallowed if tax inspectors determine the documentation is invalid.

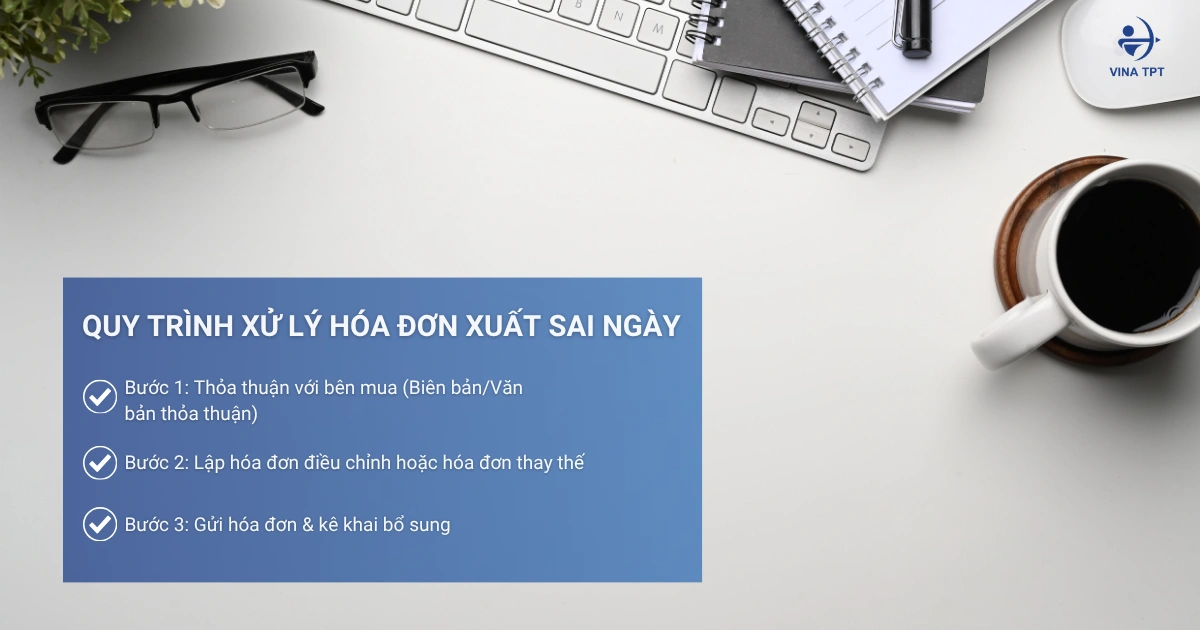
3. Step-by-Step Procedure for Handling Invoices Issued with the Wrong Date (E-Invoices)

Step 1: Agreement with the Buyer (Written Agreement / Minutes)

Prior to issuing a new invoice, the seller and buyer must draft a written agreement acknowledging the error (incorrect content and correction details). The document must state:

  • Original invoice information (Form number, Symbol, Invoice number, Date of issuance).
  • Nature of the error (incorrect date).
  • Adjustment content.
  • Digital signatures of both parties (if enterprises).

Step 2: Issue an adjustment invoice or replacement invoice

  • Adjustment invoice (most suitable when only the date is incorrect and values remain unchanged): Must state the mandatory text: “Adjustment for invoice form number… symbol… number… dated… month… year…”.
  • Replacement invoice: Used when errors are numerous or the entire invoice needs replacement. Must state: “Replacement for invoice form number… symbol… number… dated… month… year…”.

Step 3: Send the invoice & file supplementary tax declaration

  • Digitally sign and deliver to the buyer.
  • File a supplementary VAT tax declaration (if in a different period).

Procedure for handling invoices issued with the wrong date

4. Are incorrectly timed invoices penalized? Latest penalty rates

According to Article 24 of Decree 125/2020/ND-CP (as amended by Decree 310/2025/ND-CP effective January 16, 2026):

  • Warning penalty (if minor, with mitigating circumstances).
  • Monetary fine from VND 500,000 to VND 70 million depending on the number of invoices and the degree of impact on tax obligations (penalties increase progressively based on the number of violations).

Note: Penalties for organizations are double those for individuals. Mitigating circumstances apply if voluntarily remedied.

See also: Full-service accounting services

5. Can an incorrectly dated invoice be eligible for VAT deduction and expense accounting?

This is the primary concern for buyers: “Is this expense considered valid and eligible for VAT deduction?” In principle, an incorrectly timed invoice (an invoice issued after the transaction period) can still be accepted, provided it satisfies the following “three-legged stool”:

Authenticity of the transaction: This is a prerequisite. You must prove that goods/services were delivered and utilized for business operations prior to the invoice date.

Complete supporting dossier: Besides the incorrectly dated invoice, the documentation set must display temporal logic among records:

  • Economic contract (clearly specifying payment and handover terms).
  • Delivery note (seller) and Goods receipt note (buyer).
  • Handover record / Service acceptance record (matching the actual timing).
  • Non-cash payment vouchers via bank transfer (for invoices of VND 5 million or higher).
  • Seller compliance status: The seller must fully declare output tax and pay taxes for that invoice. If the seller absconds or fails to declare, the buyer faces a very high risk of VAT deduction disallowance.

Tax authorities generally evaluate substance over form. If the date error is merely an administrative oversight and the supporting documentation is complete, the buyer’s tax benefits will usually be protected.

6. Comparison between adjustment invoices and replacement invoices

Criteria Adjustment Invoice Replacement Invoice
When to use Partial error (only date, tax rate, or amount is wrong) Entirely incorrect or multiple errors
Mandatory text “Adjustment for invoice…” “Replacement for invoice…”
Impact on tax declaration Increase/decrease adjustment. Declared in the period the adjustment arises. Replacement declaration filed in the original period or discovery period (depending on the situation).
Advantages Preserves invoice numbering sequence, simpler Thoroughly resolves errors
Disadvantages Complex if there are multiple errors May affect invoice sequence numbering

An adjustment invoice can be issued multiple times for the same original invoice, whereas a replacement invoice can only be issued once for an erroneous invoice.

Conclusion

Therefore, the question “Can e-invoices issued with incorrect dates be adjusted?” has been answered along with step-by-step instructions following Decree 70/2025/ND-CP. Timely resolution not only helps avoid penalties but also protects tax deduction rights for both parties.

Advice: Establish a strict invoice issuance process and utilize reputable e-invoicing software equipped with effective error-correction features. When encountering complex situations, contact your managing tax office or tax experts at Vina TPT immediately for precise support.

Schedule a consultation with an expert

Tax and accounting services for FDI enterprises

Payment Authorization | Conditions, Documentation, and Accounting Procedures

Conditions for payment authorization

Having business partners transfer funds on your behalf to pay for goods, or having employees pay in advance for the company, are situations that frequently arise in enterprises. However, without meticulous recordkeeping, this convenience turns into a risk, leaving accountants vulnerable to the rejection of deductible business expenses, the loss of input VAT deductibility, or severe administrative tax penalties during audit settlements.

In practice, tax authorities fully accept third-party payment transactions, provided you thoroughly understand the regulations and prepare carefully.

How can you legalize these cash flows with absolute safety? In this article, Vina TPT will resolve all doubts with detailed instructions on the conditions for recording authorized payment expenses, along with a checklist of required documents compiled from the latest tax official letters.

Overview of Payment Authorization (Paying on Behalf Of) in Enterprises

During business operations, cash flow does not always travel directly from the buyer’s account to the seller’s account. In many cases, due to operational requirements, enterprises must utilize a third party to handle payments to vendors.

What is Payment Authorization?

Payment authorization (paying on behalf of another party) is an arrangement in which an enterprise (Party A – Buyer/Authorizing Party) enters into a written agreement to designate a third party (Party B – Authorized Party) to make payments on its behalf to a supplier (Party C) for goods or services purchased.

The essence of this transaction is a cash flow movement through an intermediary. Although Party B’s bank account directly disburses funds to Party C, the underlying business expense and ownership rights of the goods or services belong entirely to Party A.

Common Scenarios Requiring Payment Authorization

In practice, accounting departments frequently encounter payment authorization under the following forms:

  • Parent company paying on behalf of a subsidiary: Frequently occurs when a newly incorporated subsidiary has not yet opened a bank account or is facing temporary liquidity issues.
  • Business partner (customer) settling bills on your behalf: Customer X owes money to your company. At the same time, your company owes supplier Y. You execute payment authorization procedures for Customer X to transfer funds directly to settle the debt owed to supplier Y.
  • Individual paying on behalf of the company: Directors, department heads, or employees use personal bank cards or cash to pay in advance for procurement or business travel expenses, after which the company carries out reimbursement procedures.

2. Conditions for accounting authorized expenditures as deductible expenses

To ensure a payment made through a third party is accepted by tax authorities as a deductible expense when calculating Corporate Income Tax (CIT), an enterprise must prove the legitimacy of the transaction through core requirements.

General Principles for Deductible Expenses when Calculating CIT

Pursuant to Point c2, Paragraph 1, Article 9 of Decree No. 320/2025/ND-CP:

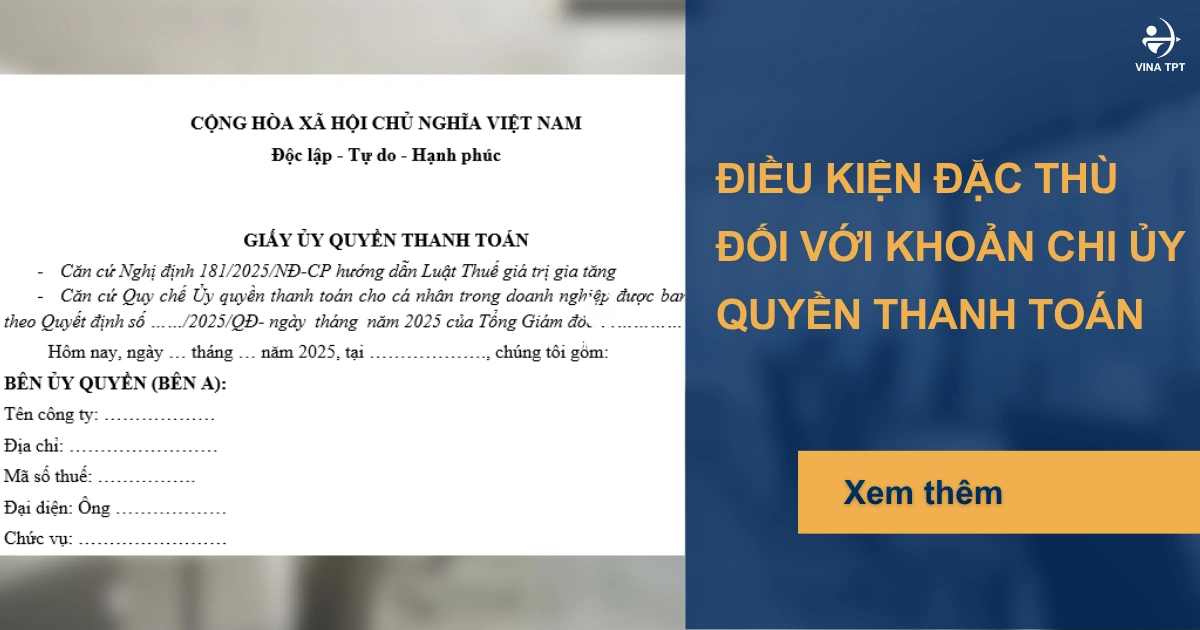
“c2) In cases where an enterprise incurs expenses resulting from authorizing or assigning employees to directly purchase goods or services to serve the enterprise’s production and business operations valued at 5 million VND or more, and such expenses are paid by the employee using non-cash payment services, these expenses shall be included in deductible expenses if all of the following conditions are met: Legitimate invoices and supporting documents as prescribed by laws on accounting, invoices, and documents are present; financial regulations, internal rules, or decisions of the enterprise specifying the authorization or permission for employees to pay for goods and services serving business operations are in place; and such expenses are subsequently reimbursed by the enterprise to the employee;”
This rule is reaffirmed in Official Letter No. 619/VLO-QLDN3 dated March 6, 2026, issued by the Tax Department of Vinh Long Province regarding deductible expenses for CIT calculation purposes.

A business expense qualifies as deductible when it satisfies 3 fundamental conditions:

  1. The expense actually arises in connection with the enterprise’s production and business activities.
  2. The expense is supported by adequate legal invoices and documentation as required by law.
  3. For single-transaction invoices for goods and services valued at 5 million VND or more (inclusive of VAT), non-cash payment vouchers are MANDATORY.

Specific Conditions for Authorized Payment Expenses

Common Risk: Accountants often mistakenly assume that a Bank Debit Advice (issued to the party paying on behalf) is sufficient. However, without proper legal agreements, tax authorities reserve the right to disallow the entire expense.

To account for authorized payments safely, enterprises must ensure:

  • Written Agreements: Payment authorization must be clearly defined within the initial commercial contract, an attached contract addendum, or a standalone Power of Attorney / Authorization Contract signed and stamped by participating parties.
  • Accurately Named Invoices: VAT invoices or sales invoices issued by the supplier (Party C) MUST state the name, address, and tax code of the Authorizing Party (Party A – the actual buyer), and must never be issued in the name of the party paying on behalf (Party B).
  • Transparent Cash Flow: When reimbursing the party paying on behalf, the enterprise must also use non-cash payment methods.

Payment Authorization Form

Detailed Accounting Guidelines for Payment Authorization (With Examples)

From an accounting standpoint, journal entries must reflect the true nature of liabilities. Payments made on behalf of another entity are not recorded as revenue or expenses for the party making the payment. We use other receivables/payables accounts (Account 1388, Account 3388) as intermediary accounts.

Accounting Entries for the Authorizing Party (The Party Requesting Payment on Its Behalf)

When buying goods or services and relying on a third party for settlement, the accountant records the asset/expense and recognizes a liability to the paying party:

Step 1: Record expenses, inventory/assets, and liabilities for payments made on behalf

  • Debit Account 152, 153, 156, 211, 641, 642… (Value of goods/services excluding VAT)
  • Debit Account 1331 (Deductible input VAT – if applicable)
  • Credit Account 3388 – Other payables (Detailed sub-account for the company paying on behalf).

Step 2: When reimbursing funds to the party that paid on your behalf

  • Debit Account 3388 (Detailed sub-account for the company paying on behalf)
  • Credit Account 112 (Bank deposits).

Accounting Entries for the Authorized Party (The Party Paying on Behalf)

The paying party functions solely as a payment intermediary; therefore, it only records journal entries related to cash flow and receivables, and must never record entries to Account 511 or Accounts 632/642.

Step 1: When disbursing funds from the bank to pay on behalf

  • Debit Account 1388 – Other receivables (Detailed sub-account for the requesting company)
  • Credit Account 112 (Bank deposits).

Step 2: When receiving reimbursement from the requesting company

  • Debit Account 112 (Bank deposits)
  • Credit Account 1388 (Detailed sub-account for the requesting company).

Practical Case Example

Manufacturing Company A purchases raw materials from Company C for a total payment value of 50,000,000 VND (inclusive of 10% VAT). The invoice issued by Company C is made under Company A’s name.

Due to temporary cash flow constraints, Company A executes an Authorization Contract requesting Company B (a business partner) to transfer 50,000,000 VND from Company B’s bank account to Company C’s bank account. One week later, Company A transfers 50,000,000 VND back to reimburse Company B.

Specific Journal Entries:

At Company A (Buyer – Requesting payment on its behalf):

Based on Company C’s invoice and the Authorization Contract, record inventory intake:

  • Debit Account 152: 45,454,545 VND
  • Debit Account 1331: 4,545,455 VND
  • Credit Account 3388 (Details for Company B): 50,000,000 VND

When transferring funds to reimburse Company B:

  • Debit Account 3388 (Details for Company B): 50,000,000 VND
  • Credit Account 112: 50,000,000 VND

At Company B (Party paying on behalf):

When transferring 50 million VND to Company C:

  • Debit Account 1388 (Details for Company A): 50,000,000 VND
  • Có TK 112: 50.000.000 VNĐ

When receiving the 50 million VND reimbursement from Company A:

  • Debit Account 112: 50,000,000 VND
  • Credit Account 1388 (Details for Company A): 50,000,000 VND

Discover Accounting Services

Important Notes on Input VAT and Foreign Contractor Tax (FCT) in Payment Authorization

Third-party transactions are key focal points during tax audits. To ensure compliance, keep these tax aspects in mind.

Conditions for Input VAT Deduction

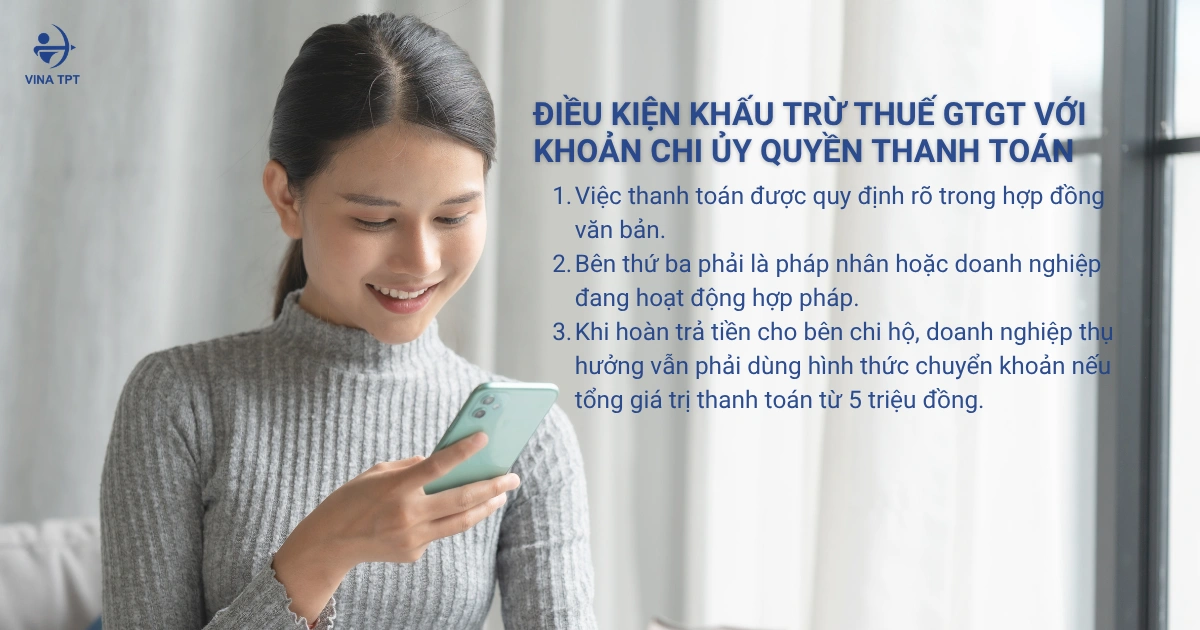
Pursuant to Official Letter No. 1619/CT-CS, to qualify for input VAT deduction on purchased goods and services valued at 5 million VND or more, debt offset settlements or payments via third parties are deemed valid non-cash payments if:

  1. Payment via third parties / payment authorization is explicitly stipulated in a written agreement.
  2. The third party is a legally operating entity or individual.
  3. When reimbursing the paying party, the beneficiary enterprise must still use bank transfers if the total transaction value reaches the mandatory non-cash payment threshold.

Payment Authorization Involving Foreign Partners

When a Vietnamese enterprise enters into an import contract for services, copyrights, or goods bundled with services from a foreign supplier (without a commercial presence in Vietnam) and authorizes another party to pay, the obligation to declare and pay Foreign Contractor Tax (FCT) remains with the Vietnamese enterprise (the Authorizing Party).

The paying party merely acts as a remittance agent and is not responsible for FCT declaration unless there is a specific agreement authorizing them to declare and pay taxes on behalf of the principal.

Frequently Asked Questions on Payment Authorization

Can an individual be authorized to make payments on behalf of a Company?

Yes, it is permitted. According to guidance official letters, Directors or staff members may use personal bank accounts or credit cards to settle payments for company goods and services. However, the company MUST maintain Financial Management Regulations or Internal Expenditure Rules detailing this process, accompanied by a Payment/Reimbursement Request and personal bank statements showing funds transferred to the vendor (if required).

How should input invoices with the wrong recipient name be handled?

  • If the vendor mistakenly issues the invoice stating the “Paying Party’s Name/Tax ID” instead of the “Actual Buyer (Authorizing Party)”, the invoice is invalid. Resolution steps:
  • Both parties draft an Invoice Adjustment Minutes clearly stating the reason for the error (misstatement of the paying party’s details).
  • The vendor issues an Adjusted Invoice or Replacement Invoice sent to the actual buyer with correct details, serving as the basis for accounting and tax declarations.

Are corporate purchases of agricultural products from non-business individuals via payment authorization considered valid expenses?

In this case, expenses are non-deductible due to the lack of valid invoices and supporting documentation prescribed under accounting and tax invoice regulations.

Summary

Accounting for payment authorization is straightforward regarding double-entry bookkeeping, but presents tax compliance risks if supporting documentation is neglected. To protect corporate expenses, keep these 3 core rules in mind:

(1) Always maintain clear written authorization agreements.

(2) Ensure VAT invoices are issued under the actual buyer’s name.

(3) Execute non-cash payments for transaction values of 5 million VND or higher.

We hope this guide facilitates your payment authorization procedures. If your enterprise requires specialized partnership in bookkeeping and tax compliance, contact Vina TPT for expert accounting consultation!

Contact us for a consultation today.

Vina TPT Accounting Services

Starting an Import Export Company in Vietnam: A Guide to Licenses & Procedures

starting a import export company in vietnam

Import export company in Vietnam – is 100% foreign ownership allowed in this sector?

Vietnam has emerged as one of Southeast Asia’s most dynamic trading hubs, supported by a strong network of Free Trade Agreements (FTAs) including CPTPP, EVFTA, UKVFTA, and RCEP. These agreements provide preferential tariff rates, streamlined market access, and enhanced supply chain efficiency for both import and export activities. Combined with modern logistics infrastructure such as the deep-water ports at Cai Mep-Thi Vai and Cat Lai, along with expanding international airports, Vietnam offers foreign investors an ideal gateway to establish an import export company in Vietnam. 

In 2026, the Law on Investment 2025 (effective from March 1, 2026, with conditional business lines from July 1, 2026) introduces significant improvements, including an optional ERC-first pathway and a substantial reduction in conditional sectors. This guide provides a clear, up-to-date roadmap for setting up a 100% foreign-owned (FDI) import-export company in Vietnam, covering the legal framework, licensing steps, post-incorporation compliance, tax obligations, and practical FAQs. 

1/ Legal Framework for Import Export Company in Vietnam

Vietnam’s investment regime for foreign direct investment (FDI) in trading activities is based on the Law on Investment 2025, the Law on Enterprises 2020 (as amended), and the Law on Foreign Trade Management 2017. Since its WTO accession in 2007, Vietnam has progressively liberalized trading rights and grants national treatment to properly registered foreign-invested enterprises (FIEs). 

Key features under the 2025 Law include: 

  • 100% foreign ownership permitted for most general trading, import, and export activities. 
  • Trading rights automatically granted through registered business lines (VSIC codes) in the IRC and ERC, allowing import and export of non-prohibited goods. 
  • Reduction of approximately 38 conditional business lines and revision of another 20 sectors (effective July 2026), making the setup process more investor-friendly. 
  • Optional ERC-first approach: Eligible investors can incorporate the company before obtaining the Investment Registration Certificate (IRC), with the IRC to be secured within 12 months. 

Understanding Trading Rights: Import, Export, and Distribution 

Import export company in Vietnam – clear differentiation helps prevent common compliance issues:

  • Export rights: Allow purchasing goods domestically and exporting them. FDI companies generally enjoy this without additional licensing for non-restricted items. 
  • Import rights: Permit bringing goods into Vietnam for resale, processing, or internal use, in line with the registered business scope. 
  • Distribution rights (wholesale/retail): More strictly regulated and may require additional approval from the Department of Industry and Trade (DoIT), especially for certain consumer goods. Pure import-export operations typically do not need full distribution rights. 

Accurate registration of VSIC codes and project objectives is essential to avoid customs delays or operational restrictions. 

2/ Step-by-Step Licensing Process for FDI Import Export Company in Vietnam

The licensing process has become more flexible in 2026. The traditional route is IRC → ERC, but the new optional ERC-first path accelerates initial incorporation for qualifying projects. The overall timeline is typically 4–8 weeks, handled mainly by the provincial Ministry of Finance.

Foreign investors are required to obtain two key certificates before operating a business, including an import export company in Vietnam.

Step 1: Securing the Investment Registration Certificate (IRC) 

The IRC approves the investment project, including capital, location, objectives, and business lines. 

Required documents include:

  • Application form for investment registration. 
  • Detailed investment project proposal (business activities, capital sources, and timeline). 
  • Proof of the investor’s financial and legal capacity (bank statements, audited accounts, or commitments; passports and business documents must be consular legalized and translated into Vietnamese). 
  • Proof of business address (lease agreement or ownership documents). 

Processing time: Approximately 5-7 weeks for standard projects (longer for conditional cases). 

The IRC serves as the legal foundation for company formation and trading rights. 

EXPLORE SET UP COMPANY SERVICES

Step 2: Obtaining the Enterprise Registration Certificate (ERC) 

Apply for the ERC via the National Business Registration Portal to establish the legal entity and obtain a tax code. 

Key documents: import export company in Vietnam

  • Copy of IRC (if applicable). 
  • Company charter. 
  • List of members/shareholders and legal representative details. 
  • Power of attorney (if needed). 

Processing time: 7 – 10 working days.

The ERC enables opening a Direct Investment Capital Account (DICA), signing contracts, and starting preparatory operations. 

>>> Reference: Essential Step For Setting Up a Company in Vietnam| Trading Businesses

Step 3: The Mandatory “Business License” for Trading Activities 

For pure import export company in Vietnam, no separate general trading license is required beyond properly registered business lines in the IRC/ERC, thanks to Vietnam’s WTO commitments. Trading rights are embedded in these certificates. 

However, attention is needed in the following cases: 

  • Distribution/wholesale activities: May require a specific Business License for goods trading and related activities from the Department of Industry and Trade (DoIT). 
  • Restricted or conditional goods (e.g., rice, sugar, petroleum, tobacco, certain chemicals): Additional permits or quotas from relevant ministries are mandatory. 
  • Post-setup: Register for a customs code if engaging in frequent import/export operations. 

Always cross-check HS codes against the latest prohibited and restricted lists (updates to Decree 69/2018/ND-CP and its successors). Many investors overlook the DoIT sub-license when distribution elements are involved, leading to compliance gaps. 

import export company in vietnam

3/ Essential Post-Incorporation Compliance & Tax Planning 

After obtaining the licenses, the focus shifts to operational readiness and risk mitigation. 

Capital Contribution Rules (The 90-Day Deadline) 

Investors must fully contribute the registered charter capital within 90 days from the date of ERC issuance (excluding time for asset transportation, import, and ownership transfer). Failure to meet this deadline may result in administrative fines, blocked bank transactions, or requirements to adjust the charter capital. Choose a realistic capital level that matches your anticipated trade volume. All capital contributions must be made through the dedicated DICA. 

Overview of Tax Planning  

  • Corporate Income Tax (CIT): Standard rate of 20%. Preferential rates (10% for 15 years or 17% for 10 years) and exemptions are available for encouraged sectors, locations, or export-oriented projects. 
  • Value-Added Tax (VAT): 0% on exports (with possible refund of input VAT); standard 10% or reduced rates on imports and domestic sales. 
  • Import/Export Duties: Preferential or zero rates under FTAs, with exemptions on machinery and equipment for qualifying projects. 

Early tax planning helps optimize cash flow, especially for export-focused businesses. 

4/ Key Taxes FDI Trading Companies in Vietnam Must Comply With 

FDI trading companies must comply with the following key taxes: 

  • VAT: Charged on imports (creditable or refundable for exporters); 0% rate on qualified exports. 
  • CIT: 20% on taxable profits, with available incentives and 5-year loss carry-forward. 
  • Personal Income Tax (PIT): Progressive rates from 5% to 35% on employee salaries, plus withholding on certain foreign payments. 
  • Import/Export Duties: Calculated based on HS codes and applicable FTAs — critical for profit margin planning. Restricted goods may be subject to quotas or special taxes. 
  • Foreign Contractor Withholding Tax: Applies to payments for overseas services (combined CIT + VAT). 

Maintaining accurate accounting records is essential for claiming VAT refunds and duty exemptions. Audits and customs inspections are common, so robust bookkeeping is highly recommended. For specific goods such as petroleum or rice, additional excise or consumption taxes may apply. 

>>> Download Vietnam Tax Handbook For Investor

5/ FAQ: Frequently Asked Questions about Setting Up an Import Export Company in Vietnam 

> What is the minimum capital requirement? 

There is no statutory minimum capital for general trading companies. However, the charter capital should be realistic and sufficient for the intended business scale. Typical starting amounts range from USD 20,000 to USD 100,000 or more, depending on operations. 

> How long does the entire licensing process take? 

Usually 6–8 weeks for obtaining the business license for import–export activities. Additional time is required for restricted goods or distribution rights. 

> Which items are restricted or prohibited? 

Prohibited items include weapons, explosives, and certain used consumer goods. Restricted items (requiring special licenses or quotas) include rice, petroleum products, tobacco, sugar, certain chemicals, and cultural products. FDI companies often face limitations when exporting rice or trading petroleum. 

> Do I need a physical office or warehouse? 

A registered business address is mandatory. Virtual offices have certain limitations; however, at the initial stage, you may use a virtual office to complete the company registration before securing a suitable physical location. 

Warehousing requirements will depend on your specific business model. 

> Can business lines be amended later? 

Yes, you can amend or add business lines later. This process requires approval from the licensing authority. 

6/ Conclusion & Strategic Consultation Offer for Import Export Company in Vietnam

In 2026, establishing an import export company in Vietnam has never been more accessible, thanks to the streamlined Law on Investment 2025, strong FTA benefits, and excellent logistics infrastructure. By properly following the IRC and ERC process, registering accurate trading rights, meeting the 90-day capital contribution deadline, and maintaining tax compliance, foreign investors can successfully enter one of Asia’s most promising trade markets. 

However, nuances related to conditional goods, distribution rights, and post-setup obligations still require careful attention to avoid unnecessary delays or penalties. 

Our specialized Vina TPT legal team provides comprehensive support for FDI company formation, licensing, tax optimization, and ongoing compliance tailored specifically for import export businesses in Vietnam.  

Contact Vina TPT today for a personalized consultation and turn your import-export ambitions into a compliant and profitable operation in Vietnam. 

BOOK A FREE CONSULTATION

(This guide is based on regulations as of April 2026. Laws and implementing decrees may be updated — please consult official authorities or qualified legal and tax advisors for your specific situation.) 

establish import export company in vietnam with vina tpt

[Newsletter] Vietnam Tax Policy Updates February 2026 – VAT, CIT, PIT, and Tax Administration

Vietnam Tax Policy Updates Vina TPT

The Vietnam Tax Policy Updates for February 2026 have been officially released, marking a significant shift in the regulatory framework for VAT, CIT, FCT, and tax administration procedures. For FDI enterprises operating in Vietnam, staying closely aligned with these Vietnam Tax Policy Updates is the key to maintaining compliance, optimizing cash flow, and preparing for future tax audits.

1. Value Added Tax Updates

Advertising Revenue from YouTube Subject to 10% VAT Rate

According to Official Letter No. 1068/CT-CS issued on February 12, 2026, the information in the Vietnam Tax Policy Updates clarifies the VAT obligations for digital content creators:

  • Period before July 1, 2025: In cases where a company receives revenue sharing (typically 55%) from Google (YouTube) through video uploads, this total income is identified as revenue from advertising activities. Accordingly, the enterprise is mandatory to declare and pay VAT at a rate of 10%.

  • Period from July 1, 2025 onwards: VAT policies will be strictly applied according to the Law on Value Added Tax No. 48/2024/QH15. Businesses should pay special attention to invoice and document conditions to correctly apply these new regulations.

2. Corporate Income Tax & Foreign Contractor Tax

Reforming Documentation Procedures for International Transactions

This month’s Vietnam Tax Policy Updates record significant efforts in reducing administrative procedures related to CIT and FCT:

  • FCT Compliance: An important change is the abolition of the requirement to submit copies of business licenses or practice certificates of foreign contractors to the tax authorities. Instead, taxpayers only need to store these documents at the enterprise’s headquarters for tax administration inspection purposes upon request.

  • CIT Finalization: The tax administration authority has issued new general declaration forms for CIT and host country profits, helping to simplify calculations for petroleum activities (including forms 03-1A, 03-1B, 03-1C/TNDN).

  • Collateral Assets: Quarterly tax declaration dossiers for credit institutions declaring on behalf of taxpayers with collateral have also been officially abolished, helping to reduce the periodic reporting burden.

3. Personal Income Tax Updates

Significant Simplification of Family Circumstance Deduction Dossiers

A prominent highlight in the Vietnam Tax Policy Updates this time is the reduction of unnecessary paperwork for PIT from salaries and real estate transfers:

  • PIT from Salaries & Wages: Employees and businesses no longer have to submit copies of tax deduction documents if the paying organization has sent full electronic data to the tax administration system.

  • Dependent Registration: Separate dependent registration forms (Form 07/DK-NPT-TNCN, 07/THDK-NPT-TNCN) are officially abolished. Instead, this information will be integrated directly into the individual’s first-time tax registration process.

  • Real Estate Transfer: Dossiers are simplified to the maximum by removing the requirement to submit copies of identity cards (CCCD) and notarized transfer contracts. Taxpayers only need to provide simple photocopies instead of originals or certified copies as before.

4. Land Use Tax & Petroleum Activities

New Forms to Improve Management Efficiency

To improve efficiency in tax administration, the Vietnam Tax Policy Updates have introduced updated forms:

  • Non-agricultural Land Use Tax: A new declaration form has been issued, allowing taxpayers to directly register for tax exemption or reduction on the declaration without having to prepare a separate dossier as previously required.

  • Petroleum Sector: Natural resource tax, CIT, and host country profits have now been consolidated into general declaration forms for both provisional calculation and year-end finalization, creating data synchronization.

5. Tax Administration: Penalty Framework under Decree 310

Effectively starting from January 16, 2026, Vietnam Tax Policy Updates emphasize the amendments in Decree No. 310/2025/ND-CP. This decree changes the face of tax administration activities through:

  • Invoice Penalties: Adjusting the fine bracket for acts of issuing invoices at the wrong time or failing to issue invoices according to regulations.

  • Aggravating Circumstances: Clearly defining “large-scale” violations based on the number of violating invoices or the total amount of tax evaded (including VAT, CIT, etc.).

  • Right to Accountability: Updating new procedures allowing taxpayers to exercise their right to accountability before official administrative sanction decisions are issued.

6. Transitional Provisions for 2026

Understanding the transition period is the most critical part of the Vietnam Tax Policy Updates to avoid systematic errors:

  • For the 2025 Tax Period: Businesses continue to perform declaration and finalization according to the old forms prescribed in Decree 126/2020/ND-CP and Circular 80/2021/TT-BTC.

  • For Tax Periods from 2026 onwards: All new forms mentioned in this Vietnam Tax Policy Updates newsletter regarding VAT, CIT, and FCT will officially become mandatory.

Conclusion

The updates in the Vietnam Tax Policy Updates for February 2026 show a clear trend: Simplifying administrative procedures while tightening tax discipline through digitalization. Proactively adjusting to these new regulations is a vital factor for every business.

At Vina TPT, we specialize in handling complex situations related to VAT, CIT, and FCT. Our team of experts is always ready to ensure that your tax administration processes are fully compliant with the latest changes from the Vietnam Tax Policy Updates.

Contact Vina TPT today for professional tax advice!

Vina TPT Tax Expert analyzing Vietnam Tax Policy Updates 2026

[Hiring] SENIOR HUMAN RESOURCES CONSULTANT

1. ABOUT VINA TPT

Vina TPT is an Accounting – Tax – HR – Business Advisory services company. We focus on providing value-added financial consulting services which aim at creating a strong competitive advantage for our clients in a rapidly changing environment. 

2. Recruitment position

We are currently seeking a Senior Human Resource Consultant to join our team. This role offers an excellent opportunity for experienced HR professionals to work closely with FDI companies in Vietnam and deliver comprehensive HR solutions in a dynamic, international business environment.

As a Senior Human Resource Consultant, you will be involved in end-to-end HR service delivery, including recruitment support, labor contract management, payroll and benefits administration, and handling employee relations matters. You will also play a key role in ensuring compliance with Vietnamese labor regulations while supporting clients in their day-to-day HR operations.

This position is ideal for candidates who are detail-oriented, proactive, and eager to further develop their expertise in HR consulting, while building long-term career growth in a professional services setting.

3. Working location: 

Vina TPT office – 83B Hoang Sa, Tan Dinh Ward, HCMC 

4. Job description / Main responsibility: 

As a Senior Human Resources Consultant, you will be able to participate in providing HR services for FDI companies in Vietnam. You will have the opportunity to gain critical skills that are essential to advance career paths in the field of HR services. 

  • Receive and process recruitment-related documents, including posting job openings, screening candidates, scheduling interviews, and tracking results; 
  • Perform procedures related to labor contracts, including drafting contracts, managing employee records, and monitoring contract expiration dates; 
  • Manage the salary and benefits system, including calculating salaries, bonuses, allowances, and insurance benefits; 
  • Resolve labor relations issues, including disciplinary actions, handling complaints, and advising employees on labor law-related matters; 
  • Perform other HR administrative tasks, including managing employee records, tracking leave days, and updating employee information; 
  • Other tasks/duties as requested by clients/service team leaders, etc. 

5. Requirements: 

Educational Background: 

– Bachelor’s degree in Human Resource Management, Law, Economics, or related fields; 

– Professional certifications such as SHRM-CP, SHRM-SCP, or equivalent are preferred. 

Work Experience: 

– At least 03 years of experience in Human Resources, including at least 02 years in a similar position; 

– Experience working in a multinational corporation or FDI company is preferred; 

– Experience working in HR consulting firms, global management consulting firms, or specialized consulting firms, or internal experience in large-scale projects is a plus. 

Skills and Knowledge: 

– Proficient in English (both speaking and writing); 

– Excellent communication, presentation, and negotiation skills; 

– Knowledge of Vietnam Labor Law and regulations related to FDI companies; 

– Comprehensive HR management skills, including recruitment, training, performance management, compensation and benefits, and labor relations; 

– Problem-solving, critical thinking, and effective teamwork skills; 

– Ability to work independently and under high pressure; 

– Proficient in HR management software and office productivity tools; 

– Experience in change management and HR transformation is a plus; 

– Demonstrated success in current role and experience in one or more of the company’s core capabilities. 


6. Benefits: 

Salary and Bonuses: 

  • Gross Salary: Basic Salary + Allowances à NEGOTIABLE 

+ Basic Salary: From 60% or more of Gross Salary (social insurance contributions based on the Basic Salary) 

+ Allowances: about 40% 

  • Bonuses: 13th-month salary + performance-based bonus (based on individual KPI evaluation and company business performance). 

Evaluation: 

  • Performance evaluation: one per year; 
  • Salary review: one per year (based on evaluation results and company business performance). 

Other Benefits: 

  • Insurance:
    • Social insurance, health insurance, unemployment insurance in accordance with the law; 
    • Supplementary health insurance (private insurance) for employees and their families (depending on position and seniority). 
  • Leave: 12 annual leave days. 
  • Health check-up: Annual health check-up. 
  • Training and Development:
    • Opportunities to participate in professional training courses to improve skills; 
    • Training cost support (depending on the program and company regulations); 
    • Career development and promotion opportunities within the company. 
  • Working Environment:
    • Professional, dynamic, and friendly working environment; 
    • Opportunities to work with leading experts in the industry; 
    • Participation in team-building activities and company events. 
  • Other Benefits:
    • Travel and business trip allowance (if applicable); 
    • Other employee benefits policies. 

How to Apply

If you are passionate about content creation and want to start your marketing career with real-world experience, please send your CV and a short cover letter (if available) to:

📩 Email: trunghieunhi@vinatpt.com (CC email: infor@vinatpt.com)
📌 Email Subject: [Senior HR Consultant] – Full Name

For any questions, please contact our hotline/Zalo: 0984 980 069

Contact VINA TPT for Support

📞 (+84) 984 980 069
📧 infor@vinatpt.com
🌐 www.vinatpt.com
🏢 5th Floor, More Building, 83B Hoang Sa, Da Kao Ward, District 1, HCMC 

Outsourced Bookkeeping Services in Vietnam: Why It Helps Businesses Grow Faster

compare-in-house-outsourced-bookkeeping-services-vina-tpt-2

Managing in-house financial records often drains vital time and capital that should be spent on business expansion. Instead of struggling with complex tax compliance and reporting, savvy businesses are turning to outsourced bookkeeping to reduce overhead costs and guarantee professional accuracy. 

This article explores how outsourced bookkeeping services as a strategic growth engine, highlighting the specific challenges it solves, the seamless workflow provided by Vina TPT, and the ideal timing to transition for maximum operational freedom.

1. What is Outsourced Bookkeeping?

Outsourced bookkeeping means delegating your daily financial tasks: transaction recording, bank reconciliations, invoice management, financial statements, VAT/CIT reporting, and compliance to a professional external team. Unlike hiring a full-time accountant (with high salary, benefits, and training needs), you pay a fixed monthly fee for expert, scalable support.

This model is perfect for SMEs and foreign-invested companies in Vietnam that want to avoid local accounting complexities while staying compliant with VAS, IFRS, and tax regulations.

Learn more about Vietnamese accounting standards (VAS)

2. Key Challenges of In-House Bookkeeping That Slow Growth

In-house bookkeeping often creates hidden barriers:

  • High salary costs for qualified accountants (VND 15 – 30 million/month + insurance and bonuses).
  • Constant training to keep up with frequent law changes (VAT adjustments, e-invoice mandates, CIT updates in 2026).
  • Risk of penalties from errors in reporting or late filings (fines can reach tens of millions VND).
  • Management time wasted on admin instead of sales, product development, or market expansion.
  • Difficulty scaling during rapid growth or seasonal peaks without adding headcount.

These issues can consume 20–30% of operational budget and delay business momentum.

compare-in-house-outsourced-bookkeeping-services-vina-tpt

3. How Outsourced Bookkeeping Accelerates Business Growth

Partnering with Vina TPT for outsourced bookkeeping drives faster growth by:

  • Offering predictable low costs, typically 30% cheaper than in-house, freeing capital for marketing, hiring, or R&D.
  • Ensuring expert compliance, our team is always updated on 2026 regulations, eliminating penalty risks and audit stress.
  • Providing scalable support, handle increased transactions or headcount seamlessly without hiring extra staff.
  • Delivering faster, accurate reporting and real-time financial insights for better strategic decisions.
  • Allowing focus on core business, leaders concentrate on sales, innovation, and expansion instead of paperwork.

Explore Outsourced Bookkeeping Services

4. How Vina TPT’s Outsourced Bookkeeping Service Works

Vina TPT’s service is designed to be simple, secure, and efficient for foreign and local businesses.

Process overview:

  1. Free consultation & needs assessment: We discuss your business size, transaction volume, current setup, and goals.
  2. Secure data handover: Transfer existing records (bank statements, invoices, contracts) via encrypted portal.
  3. Daily/weekly bookkeeping: Our certified accountants record transactions, reconcile accounts, manage payables/receivables, and prepare trial balances.
  4. Monthly compliance & reporting: Deliver accurate financial statements, VAT/CIT returns, e-invoice filings, and tax declarations on time.
  5. Ongoing advisory & support: Unlimited queries, year-end audit preparation, and strategic financial guidance.

All work is 100% compliant with Vietnamese laws, using secure cloud tools. Pricing is transparent and flexible, starting from VND 3 million/month based on volume (no hidden fees).

5. When to Choose Outsourced Bookkeeping

This serivce is the strategic choice for newly established startups, SMEs with 1 to 50 employees, and high-growth firms looking to scale without administrative friction. It is particularly essential for businesses navigating complex compliance requirements, such as VAT, CIT, and e-invoicing allowing leadership to mitigate regulatory risks while focusing entirely on expansion. By transitioning to this service, companies can ensure professional financial management while maintaining the agility needed to thrive in a competitive market.

6. Conclusion

Outsourced bookkeeping eliminates major growth barriers: high costs, compliance headaches, and time lost on admin. With Vina TPT, you get reliable, expert support at a fraction of the cost—freeing your team to focus on what drives success: expansion and innovation.

Ready to accelerate your growth? Contact Vina TPT today for a free consultation and personalized cost-saving assessment. Let our experts handle your bookkeeping so you can build your future in Vietnam.

BOOK A FREE CONSULTATION

Set Up Company Service in Vietnam for Foreigners – Expert Setup & Free Consultation 2026

set-up-company-in-vietnam-for-foreigners-Vina-tPT

Vietnam remains a top FDI destination in 2026, with strong economic growth, favorable FTAs, and attractive incentives in high-tech, manufacturing, and renewable energy sectors. For foreign investors, accessing this market through company formation offers huge potential, but the process involves complex regulations, IRC/ERC registration, document legalization, and compliance hurdles that can be time-consuming and risky without proper support.

In this article, we provide a clear, step-by-step guide on how to use our set up company service in Vietnam for foreigners. We cover detailed timelines, required documents, costs, and key steps, while highlighting how Vina TPT’s professional service makes the entire process fast, compliant, and hassle-free Law on Investment 2020 (Luật đầu tư 2020)

1. Why Choose Vietnam for Company Setup in 2026

Vietnam continues to be a premier investment hub, allowing 100% foreign ownership in most industries and offering no minimum capital requirements for many sectors. Investors can also benefit from generous tax incentives, including CIT reductions and exemptions for priority projects. In 2026, the landscape is even more efficient; with e-ID integration and streamlined online submissions via the National Business Registration Portal, utilizing a professional set up company service ensures a faster, more transparent, and fully compliant entry into this booming market.

Types of Business Entities for Foreigners

Entity Type Foreign Ownership Minimum Capital Main Activities Allowed Best For
100% Foreign-Owned LLC 100% No (most sectors) Full trading, manufacturing, services Most foreign investors
Joint Venture Partial Varies Shared ownership with local partner Restricted sectors
Branch Office 100% No Same as parent company (limited scope) Expanding existing business
Representative Office 100% No Market research, liaison only Testing market before full setup

The 100% Foreign-Owned LLC is the most popular and flexible option for foreigners seeking full control.

set-up-company-in-vietnam-for-foreigners-Vina-tPT-2

2. Step-by-Step Set Up Company Process

The entire process typically takes 2 – 4 months in 2026, depending on sector, document readiness, and province.

  1. Step 1: Obtain IRC (30 – 45 Working Days) Submit your investment dossier – including the business plan, legalized parent company certificates, and office lease – to the DPI. This certificate approves your project’s scale and legitimacy. Non-conditional sectors often see faster approval through 2026’s expedited digital tracks.
  2. Step 2: Get ERC (7 -10  Working Days) Once the IRC is approved, file for your Enterprise Registration Certificate via the National Portal. This step officially establishes your legal entity and tax ID. The process is now fully streamlined online, ensuring a rapid turnaround for foreign investors.
  3. Step 3: Post-Setup Tasks (1 – 3 Weeks) Finalize operations by engraving the company seal, opening corporate bank accounts, and registering for e-invoices. Be mindful that delays often stem from document legalization or specific sub-license requirements. Our set up company service at Vina TPT proactively manages these hurdles to keep your launch on track.

Explore the Service

3. Common Challenges and How Vina TPT’s Set Up Company Service Helps You Succeed

Foreign investors often encounter delays from incorrect document legalization, misunderstanding conditional sectors, or missing the 90-day capital contribution deadline after ERC issuance. Choosing the wrong entity or location can also lead to higher costs and ongoing compliance issues.

Vina TPT’s set up company service gives you a clear edge:

  • End-to-end support: We manage everything—from free company name check, document preparation & legalization, IRC/ERC submission, to bank account opening, tax registration, and full post-setup compliance.
  • Faster timeline: With over 20 years of experience and strong relationships with DPI offices nationwide, we complete most setups in 2–3 months (often faster than average).
  • Risk-free & fully compliant: 100% data protection, transparent fixed pricing (no hidden fees), and zero-penalty guarantee through expert legal review.
  • Exclusive advantages: Free initial consultation, name availability check, and feasibility assessment before you commit—saving you time and avoiding costly mistakes.

Hundreds of clients from the US, EU, Japan, Singapore, and Korea have successfully launched their businesses in Vietnam through Vina TPT—focusing on growth instead of paperwork.

set-up-company-in-vietnam-for-foreigners-Vina-tPT-3

4. Start Your Business Journey in Vietnam with Vina TPT

Setting up a company in Vietnam in 2026 is more accessible than ever, thanks to streamlined regulations and strong FDI support. With the right partner, you can go from idea to operational business quickly, compliantly, and cost-effectively.

Ready to get started? Contact Vina TPT today for your free consultation, company name check, and personalized set up company service plan. Let our experts handle the details so you can focus on building your success in Vietnam.

BOOK A FREE CONSULTATION