What Is Included in Business Accounting Services in Vietnam?

what-is-included-in-business-accounting-services-in-vietnam

what-is-included-in-business-accounting-services-in-vietnam

You have just entered the Vietnamese market and are looking for a business accounting services provider that can optimize cost while still covering your basic compliance obligations. At this stage, many investors still do not have a clear picture of what they actually need: bookkeeping and tax filing only, or also payroll, labor reports, financial statements, and investment reports.

This article from Vina TPT breaks the work down by scope so you can choose an accounting services Vietnam package that matches real operating needs – complete on mandatory obligations, with nothing missing and nothing surplus relative to your current scale.

1. Bookkeeping and Daily Financial Records

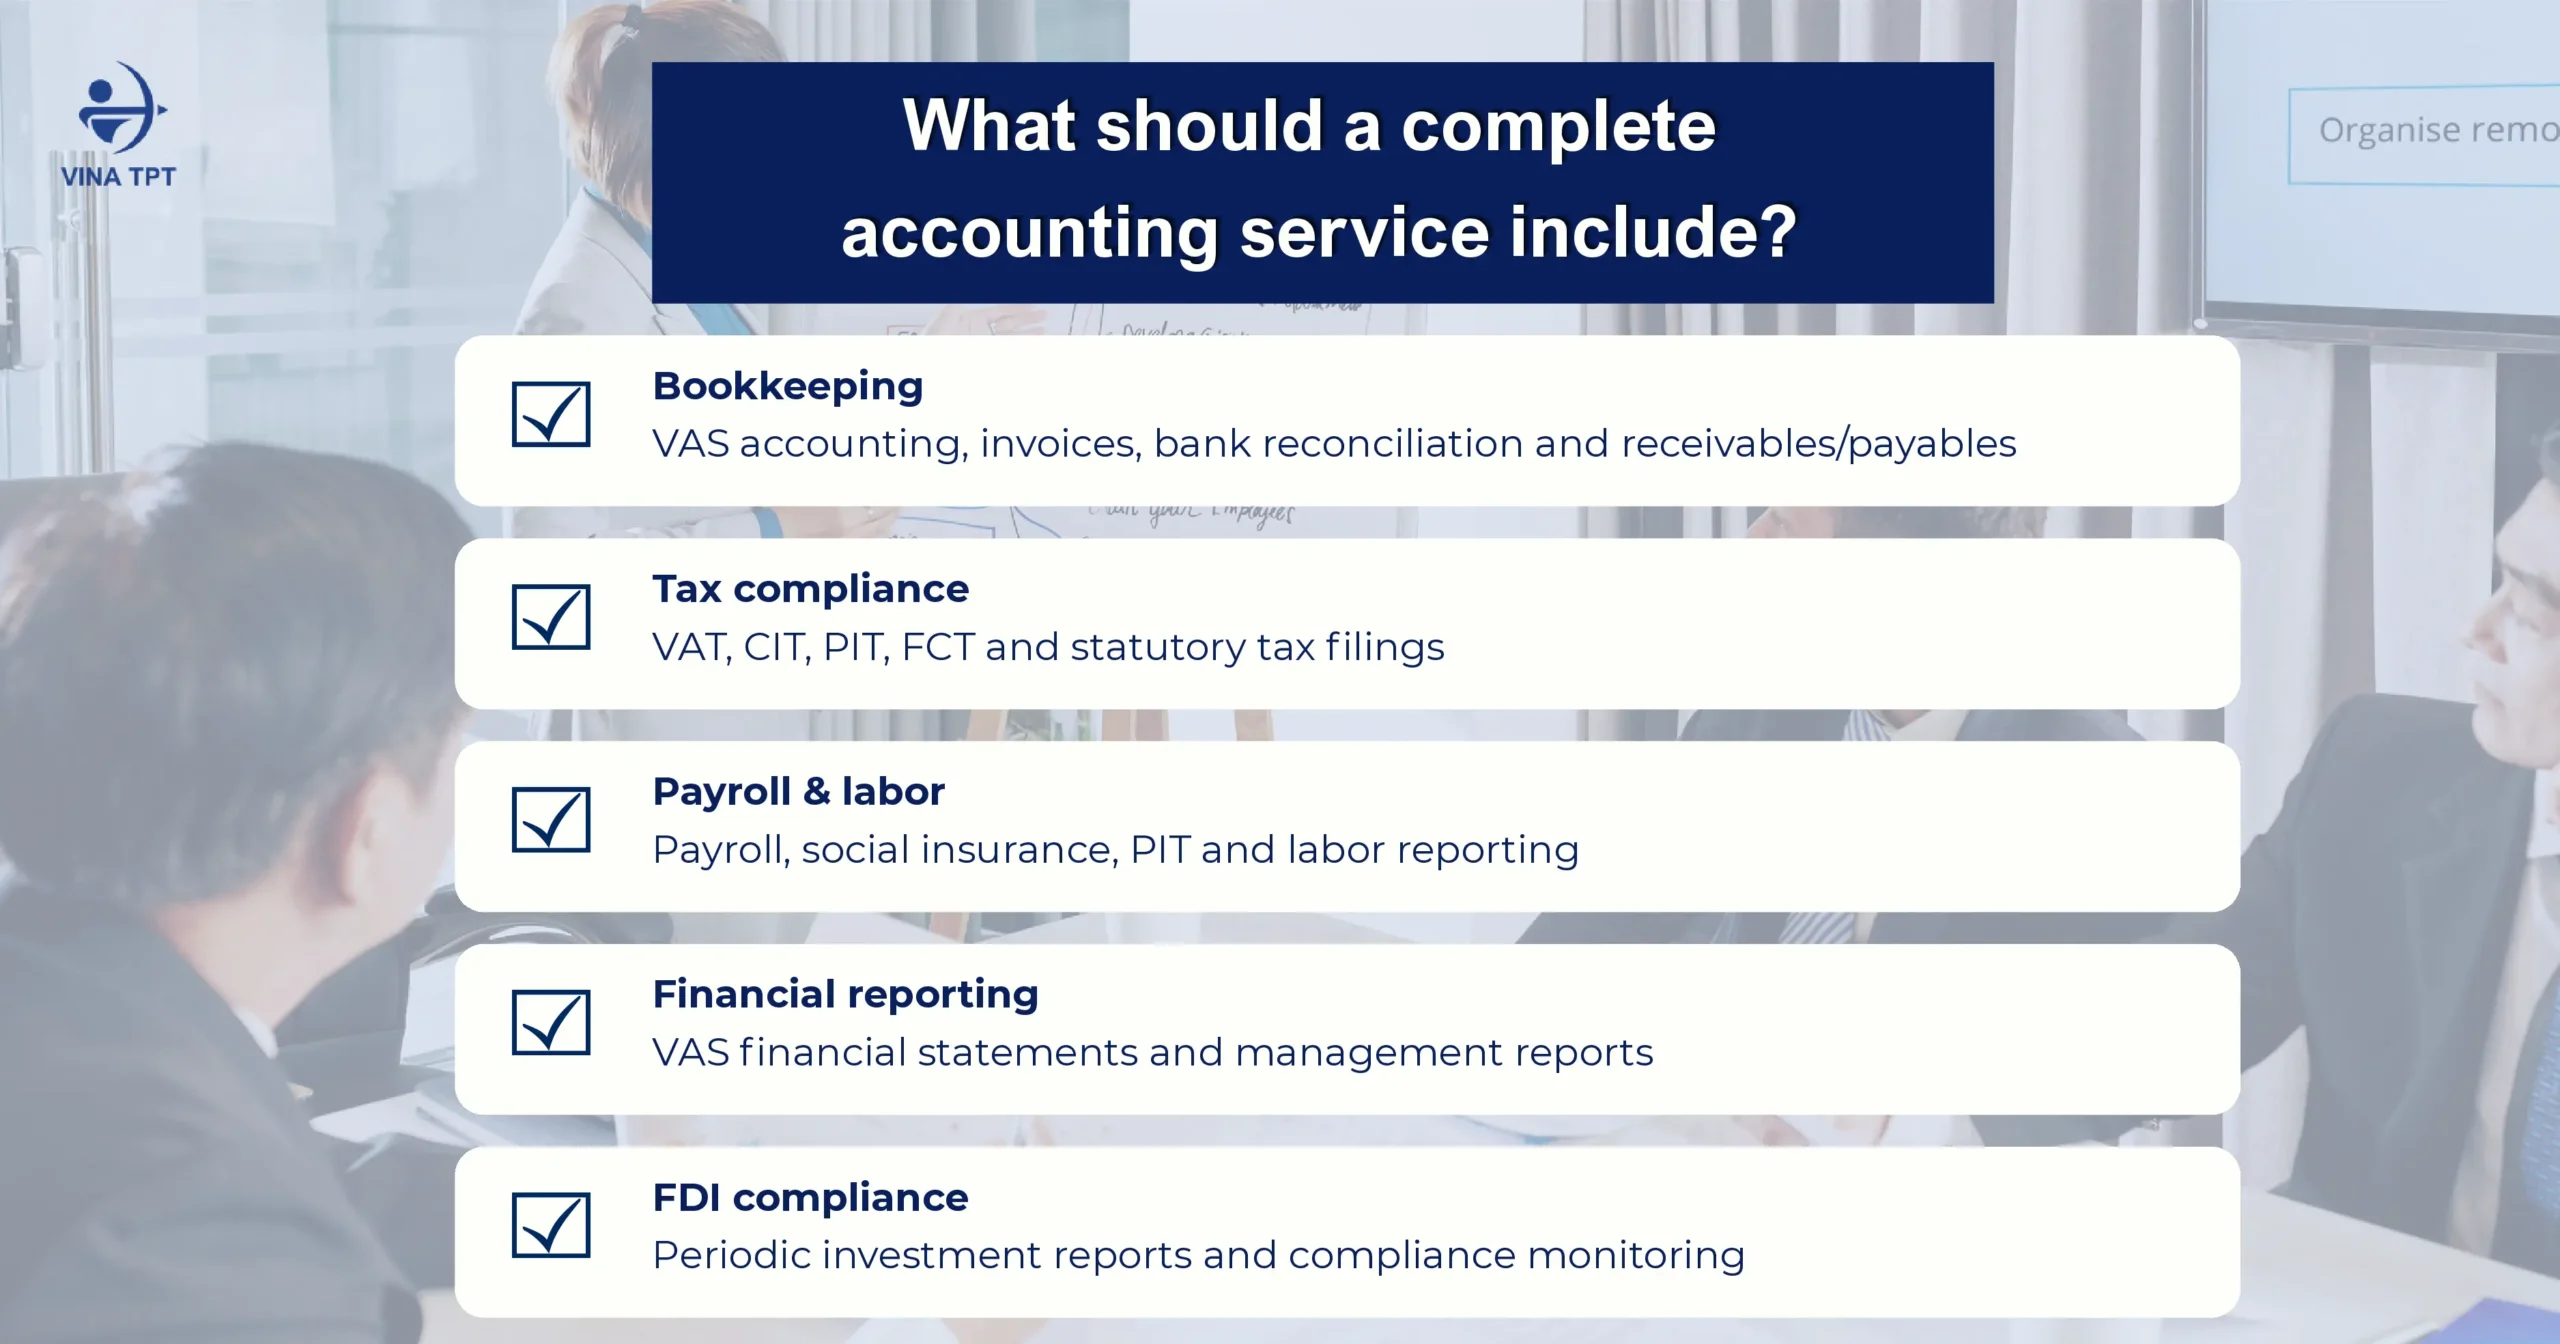
The core foundation of any professional outsourcing accounting Vietnam solution is a daily bookkeeping system that is recorded accurately and in strict compliance with the Vietnamese Accounting Standards (VAS).

This workstream includes:

  • Document receipt and review: Checking the legality, validity, and reasonableness of all incoming and outgoing e-invoices, bank documents, commercial contracts, and customs declarations (if the company has import-export activities).
  • VAS bookkeeping: Recording in detail the transactions arising in revenue, expenses, fixed assets, prepaid expenses, inventory, and provisions under the correct VAS accounts.
  • Receivables, payables, and bank reconciliation: Reconciling bank statements (VND and foreign-currency accounts) and maintaining detailed records of customer receivables and supplier payables.

Vina TPT’s management view: Accounting data is not merely for internal storage. It must be of a standard that reconciles 100% with VAT returns, the annual audited financial statements, and FDI investment reports. If there is a discrepancy among these three data sources, the company faces a high risk of tax reassessment and significant penalties at finalization.
what-is-included-in-business-accounting-services-in-vietnam

2. Tax Compliance and Statutory Filings

Tax filing is the highest-risk workstream if the company does not keep up with changes in legal regulations. A provider of business accounting services is responsible for fulfilling all of the following obligations:

  • Value-Added Tax (VAT): Preparing and filing VAT returns on a monthly or quarterly basis; strictly reviewing input VAT deduction conditions (especially the mandatory bank-transfer requirement for invoices of VND 5 million or more).
  • Corporate Income Tax (CIT): Calculating quarterly provisional CIT (ensuring that the total provisional payments over four quarters are not lower than 80% of the amount payable on the annual finalization) and preparing the annual CIT finalization return.
  • Personal Income Tax (PIT): Filing withholding PIT returns monthly or quarterly and preparing the annual PIT finalization return for all employees.
  • Foreign Contractor Tax (FCT): Declaring and paying FCT arising from service contracts, royalties, international freight charges, or loan interest paid to foreign counterparties.
  • Business license fee and other taxes: Declaring and paying the business license fee at the beginning of the year, as well as natural resource tax and special consumption tax (if applicable).

The advisory firm must proactively track the tax calendar and alert the company to statutory deadlines in order to fully prevent late-payment penalties or a locked Tax Identification.

3. Payroll, PIT, Social Insurance and Labor Reports

Payroll cannot be separated from the accounting system. Errors in salary calculation and insurance will distort cash flow, affect deductible expenses for CIT purposes, and constitute labor-law violations.

A complete service package should include:

  • Payroll and insurance obligations: Preparing the payroll, issuing confidential payslips, calculating PIT withholdings, making social insurance, health insurance, and unemployment insurance contributions, and registering tax identification numbers and dependents for employees. For expatriates, the specialist must carefully check the Work Permit and Temporary Residence Card (TRC) conditions and correctly determine tax residency status (resident or non-resident) in order to calculate PIT accurately.
  • Five mandatory labor reports: In addition to tax returns, FDI companies are required to submit five periodic labor reports according to the standard schedule below:

Labor Report

Receiving Authority Filing Deadline

Prescribed Form

1. Report on labor utilization Department of Labor, Invalids and Social Affairs / Industrial Park or Economic Zone Management Board Twice a year: before 5 June and 5 December Form No. 01/PLI (Decree 145/2020/ND-CP)
2. Report on unemployment insurance participation Department of Labor, Invalids and Social Affairs Once a year: before 15 January of the following year Form No. 33 (Circular 28/2015/TT-BLDTBXH)
3. Occupational accident report Department of Labor, Invalids and Social Affairs Twice a year: before 5 July and 10 January of the following year Appendix XII (Decree 39/2016/ND-CP)
4. Occupational safety and hygiene report Department of Labor, Invalids and Social Affairs and Department of Health Once a year: before 10 January of the following year Appendix II (Circular 07/2016/TT-BLDTBXH)
5. Occupational health report District/City Medical Center Twice a year: before 5 July and 10 January of the following year Appendix 8 (Circular 19/2016/TT-BYT)

4. Financial Reporting and Management Reports

At the end of the financial year, the accounting services Vietnam provider prepares a complete set of financial statements under VAS, including the balance sheet, income statement, cash flow statement, and notes to the financial statements. This set of reports is the legal basis for the Tax Authority, the independent auditor, and submission to the statistics authority.

In addition to the statutory financial statements, the management of an FDI company also needs periodic monthly or quarterly Management Reports:

  • Profit and Loss (P&L) management report analyzing revenue and expenses
  • Cash flow management report
  • Aging report for accounts receivable and accounts payable

These management reports are presented in bilingual format (English – Vietnamese) so that Headquarters can monitor the financial health of the Vietnam entity without a language barrier.

Explore Vina TPT’s Accounting Services

5. Mandatory FDI Investment Reports

This is the obligation that many FDI companies miss when they use low-cost accounting packages. Missing investment reports not only leads to substantial administrative penalties but also creates serious bottlenecks when the company later adjusts its Investment Registration Certificate (IRC), increases capital, extends the project, or remits profits abroad.

Every foreign-invested enterprise (from 1% to 100% foreign capital) or project that has been granted an IRC is required to file investment reports. Even if the project has not yet generated revenue, is still in the construction phase, or has temporarily suspended operations, the company must still report (by declaring zero figures).

Investment reporting obligations consist of two main groups:

  1. Report on the Implementation of the Investment Project (filed online on the fdi.gov.vn system under Decree 96/2026/ND-CP)
  • Quarterly report: Filed before the 10th day of the first month of the following quarter. Content includes implemented investment capital, revenue, import-export value, headcount, amounts paid to the state budget, and land/water-surface use.
  • Annual report: Filed before 31 March of the following year. Content includes a comprehensive assessment of investment results, product sales, average employee income, operating costs, R&D activities, environmental impact, and the origin of the technology used.
  1. Investment Monitoring and Evaluation Report (under Decree 19/2026, Decree 96/2026, and Circular 44/2026/TT-BTC – Form 13)
  • Quarterly report: Filed before the 10th day of the first month of the following quarter.
  • Six-month report: Filed before 10 July of the current year.
  • Annual report: Filed before 10 February of the following year.

Vina TPT’s management view: Figures on the Investment Activity Report (IAR) must match the VAS accounting books and the tax returns. A discrepancy between the investment report and the audited financial statements is the first signal that the investment management authority and the tax authority will place the company on a specialized inspection list.

6. How to Choose the Right Business Accounting Services Package

To choose a suitable accounting compliance package, the Board of Directors of an FDI company should follow these steps:

  • Correctly determine scale and transaction profile: Assess the monthly volume of source documents, whether the company has import-export activities or Foreign Contractor Tax (FCT), the size of the workforce, and whether expatriates are employed.
  • Lock in the exact Scope of Work: Require the provider to state clearly in the contract whether the package covers only bookkeeping and tax filing, or a full package that includes payroll, labor reports, and periodic FDI investment reports.
  • Provider evaluation criteria: Prioritize a partner with hands-on FDI experience, a bilingual advisory team, a multi-level quality control (QC) process before filing, and the ability to represent the company directly before the Tax Authority and the investment management authority.
  • Clarify management reporting and the advisory layer: Ask whether the provider issues monthly management reports (P&L, cash flow, receivables and payables) and whether those reports are figures only or include commentary. At the same time, lock in the advisory scope in advance: filing only, or also support when a tax issue arises, an inspection is launched, or Headquarters needs an explanation of the figures.

7. How Vina TPT Delivers Business Accounting Services

Vina TPT provides a comprehensive business accounting services solution that gives FDI companies full legal peace of mind in Vietnam:

  • VAS bookkeeping and full-package tax filing: Recording the books under VAS and filing VAT, CIT, PIT, and FCT accurately and on time. The package also includes Chief Accountant services – a mandatory requirement for every FDI company, needed from company setup through the opening of the bank account.
  • Payroll administration and labor reports: Calculating salaries, optimizing insurance costs, completing expatriate PIT finalization, and filing all five mandatory labor reports.
  • Financial statements and FDI investment reports: Preparing the annual financial statements, supporting work with the independent auditor, and handling the full package of periodic investment monitoring reports.
  • Flexible operating model: Advising and delivering bilingual management reports (English – Vietnamese – Japanese), with remote or hybrid working arrangements depending on the company’s stage of development.
  • Continues to support in-depth services: VAT refunds, preparation and accompaniment during tax inspections, transfer pricing documentation, and advisory on mergers and acquisitions.

If your company wants to review its current compliance scope, contact Vina TPT today for an expert consultation on the most suitable solution.
BOOK A FREE CONSULTATION

what-is-included-in-business-accounting-services-in-vietnam

Establish a Small Business in Vietnam: How to Start?

establish-a-small-business-in-vietnam-how-to-start

establish-a-small-business-in-vietnam-how-to-start

Small-scale investors who want to establish a business in Vietnam often do not know whether to start with the legal structure, the capital level, or the dossier. Many confuse a Representative Office with a company that can issue invoices, choose a registered address that does not meet registration requirements, or submit overseas documents that have not been consular-legalized. The result is that the IRC/ERC file is returned and the timeline for opening a store or signing the first contract is stretched.

This article breaks the process into steps for a small business in Vietnam: choosing the entity type, checking ownership conditions, working through the IRC and ERC, selecting an address when you have just arrived, preparing personal documents, and then looking at both setup cost and ongoing cost. The aim is to see the full operating cycle – not stop on the day the license is issued.

1. Choose the Right Legal Structure for a Small Business in Vietnam

Choosing the right legal structure from the outset is a foundational decision. It directly affects the company’s governance model, financial liability, and ability to raise capital later. The three legal-entity models that foreign investors in Vietnam most often consider today are the single-member limited liability company, the limited liability company with two or more members, and the joint-stock company.

For small and mid-sized foreign investors, the limited liability company (LLC) remains the most practical and widely used option. This structure limits the investor’s financial liability to the committed charter capital and keeps personal or parent-company assets separate from operating risk in Vietnam. The LLC’s governance is also relatively lean: it is not required to form a Board of Directors or a complex General Meeting of Shareholders of the kind a joint-stock company must maintain, so business decisions can be made faster and with more flexibility. The investor may hold 100% foreign ownership or form a joint venture with a local partner.
A joint-stock company (JSC), by contrast, requires at least three founding shareholders and is bound by stricter rules on meetings, voting, and reporting. This model is a genuine fit only if the investor plans a stock-exchange listing or intends to raise capital from venture funds in the near term.

Vina TPT’s professional recommendation: If your goal is to bring a product or service to market quickly, sign commercial contracts, and issue lawful invoices, start by establishing an LLC. When the business scale grows and you need to bring in more shareholders, the company can legally convert to another enterprise type.

For dossier requirements and LLC registration conditions, refer to Vietnam LLC Registration Requirements: A Complete Guide for Investor.

2. Ownership Rules and Investment Conditions for Small Business in Vietnam

Vietnam’s investment environment is now relatively open: foreign investors may hold 100% ownership in most ordinary business lines such as management consulting, information technology, software services, and manufacturing. The legal framework still maintains, however, a list of conditional business lines for foreign investors.

The sectors that a small business in Vietnam often targets – direct-to-consumer trading and retail, food and beverage (F&B), and some logistics services – all sit in the conditional market-access group. For these lines, the law may cap the foreign capital ratio, require a Vietnamese joint-venture partner, or require the company to obtain a Retail License or another industry-specific sub-license after incorporation.
As a rule, Vietnam’s Law on Investment does not impose a single minimum charter-capital figure across all sectors (except certain finance, banking, and real-estate lines that require statutory capital). The registered capital must still correspond to the project scale, the business line, and the costs set out in the investment proposal.

Vina TPT’s management view: The investment registration authority will assess the project’s feasibility against the capital you commit. If a company registers a retail or F&B line but declares a charter capital that is too low (for example under USD 5,000-10,000), the file is easily refused or sent back for an explanation of financial capacity, because that amount cannot cover rent, equipment, and initial operating costs. In addition, the investor must contribute 100% of the registered charter capital within 90 days from the date the Enterprise Registration Certificate (ERC) is issued.

3. Step-by-Step Process to Establish a Small Business in Vietnam

Setting up a foreign-invested company in Vietnam is more complex than forming a domestic company because it runs through two separate licensing stages: investment project approval and legal-entity formation. Completing the steps out of order, or leaving gaps in the early dossier, can stall the entire timeline.
The standardized process follows these sequential steps:

Step 1: Industry Survey and Preparation of the Investment Dossier

Before commencing the company establishment procedures, the investor needs to accurately determine the business industry codes according to the Vietnam Standard Industrial Classification (VSIC) and cross-check them against the WTO Commitments Schedule and the Law on Investment to verify market access conditions. Certain sectors classified as conditional business lines will require additional specialized licenses or compliance with standards related to capital, personnel, and facilities. At this stage, the investor is advised to contact a local consulting firm for support in reviewing the industry codes and assessing the project’s feasibility.

Explore Business Setup Services

After identifying the suitable industry, the investor proceeds to prepare the investment dossier under the guidance of the service provider. Documents of the investor (whether an individual or an organization) must be consular-legalized abroad before being brought to Vietnam for use. The consular legalization process usually takes 14 to 30 days, depending on the procedures of each embassy/consulate and the respective country.

Estimated time for the entire step: approximately 5-7 working days (excluding consular legalization time).

Step 2: Submission of the Application for the Investment Registration Certificate (IRC)

The investment dossier is submitted to the Department of Finance. The competent authority will appraise the market conditions, project location, and the investor’s financial capacity before officially issuing the IRC.

Estimated time: 30 – 45 working days.

Step 3: Submission of the Application for the Enterprise Registration Certificate (ERC)

After obtaining the IRC, the enterprise submits the legal entity establishment dossier to apply for the ERC. The business registration authority will appraise the company name, head office address, and governance structure. Once the ERC is completed, the enterprise code is simultaneously created on the National Business Registration Information System.

Estimated time: 14 – 20 working days.

Step 4: Opening a Bank Account, Engraving the Company Seal, and Making Capital Contribution

The enterprise proceeds to engrave the legal seal, publish the seal specimen, and open a Direct Investment Capital Account (DICA) at a commercial bank licensed to operate in Vietnam. Under the law, the investor must complete the transfer of the entire committed charter capital into the DICA within a maximum of 90 days from the date the ERC is issued.

Implementation time: Within 90 days as prescribed by law.

Step 5: Completion of Tax Registration and Post-Establishment Compliance

The enterprise purchases a digital signature (USB Token), installs the company signboard at the head office, carries out initial tax registration, submits the business license fee declaration, and registers the electronic invoice system. At the same time, the company completes labor registration and social insurance procedures if employees are officially hired, and registers the enterprise electronic identity account (VNeID for enterprises) to facilitate electronic administrative procedures and transactions with state authorities.

Estimated time: 14 – 30 working days. 

4. Selecting a Compliant Address for Your Small Business in Vietnam

The head-office address is one of the most important legal elements in a company-setup dossier. Under Vietnam’s Law on Enterprises and Law on Housing, the registered address must be a real location, with a clear cadastral identity and a lawful right of use. It must not be placed in a residential apartment or a collective housing block.

For a small business in Vietnam that has just entered the market, a long-term traditional office lease often creates a heavy financial burden. A deposit of three to six months, fit-out costs, and high monthly rent consume a large share of the budget before the company has generated any revenue.
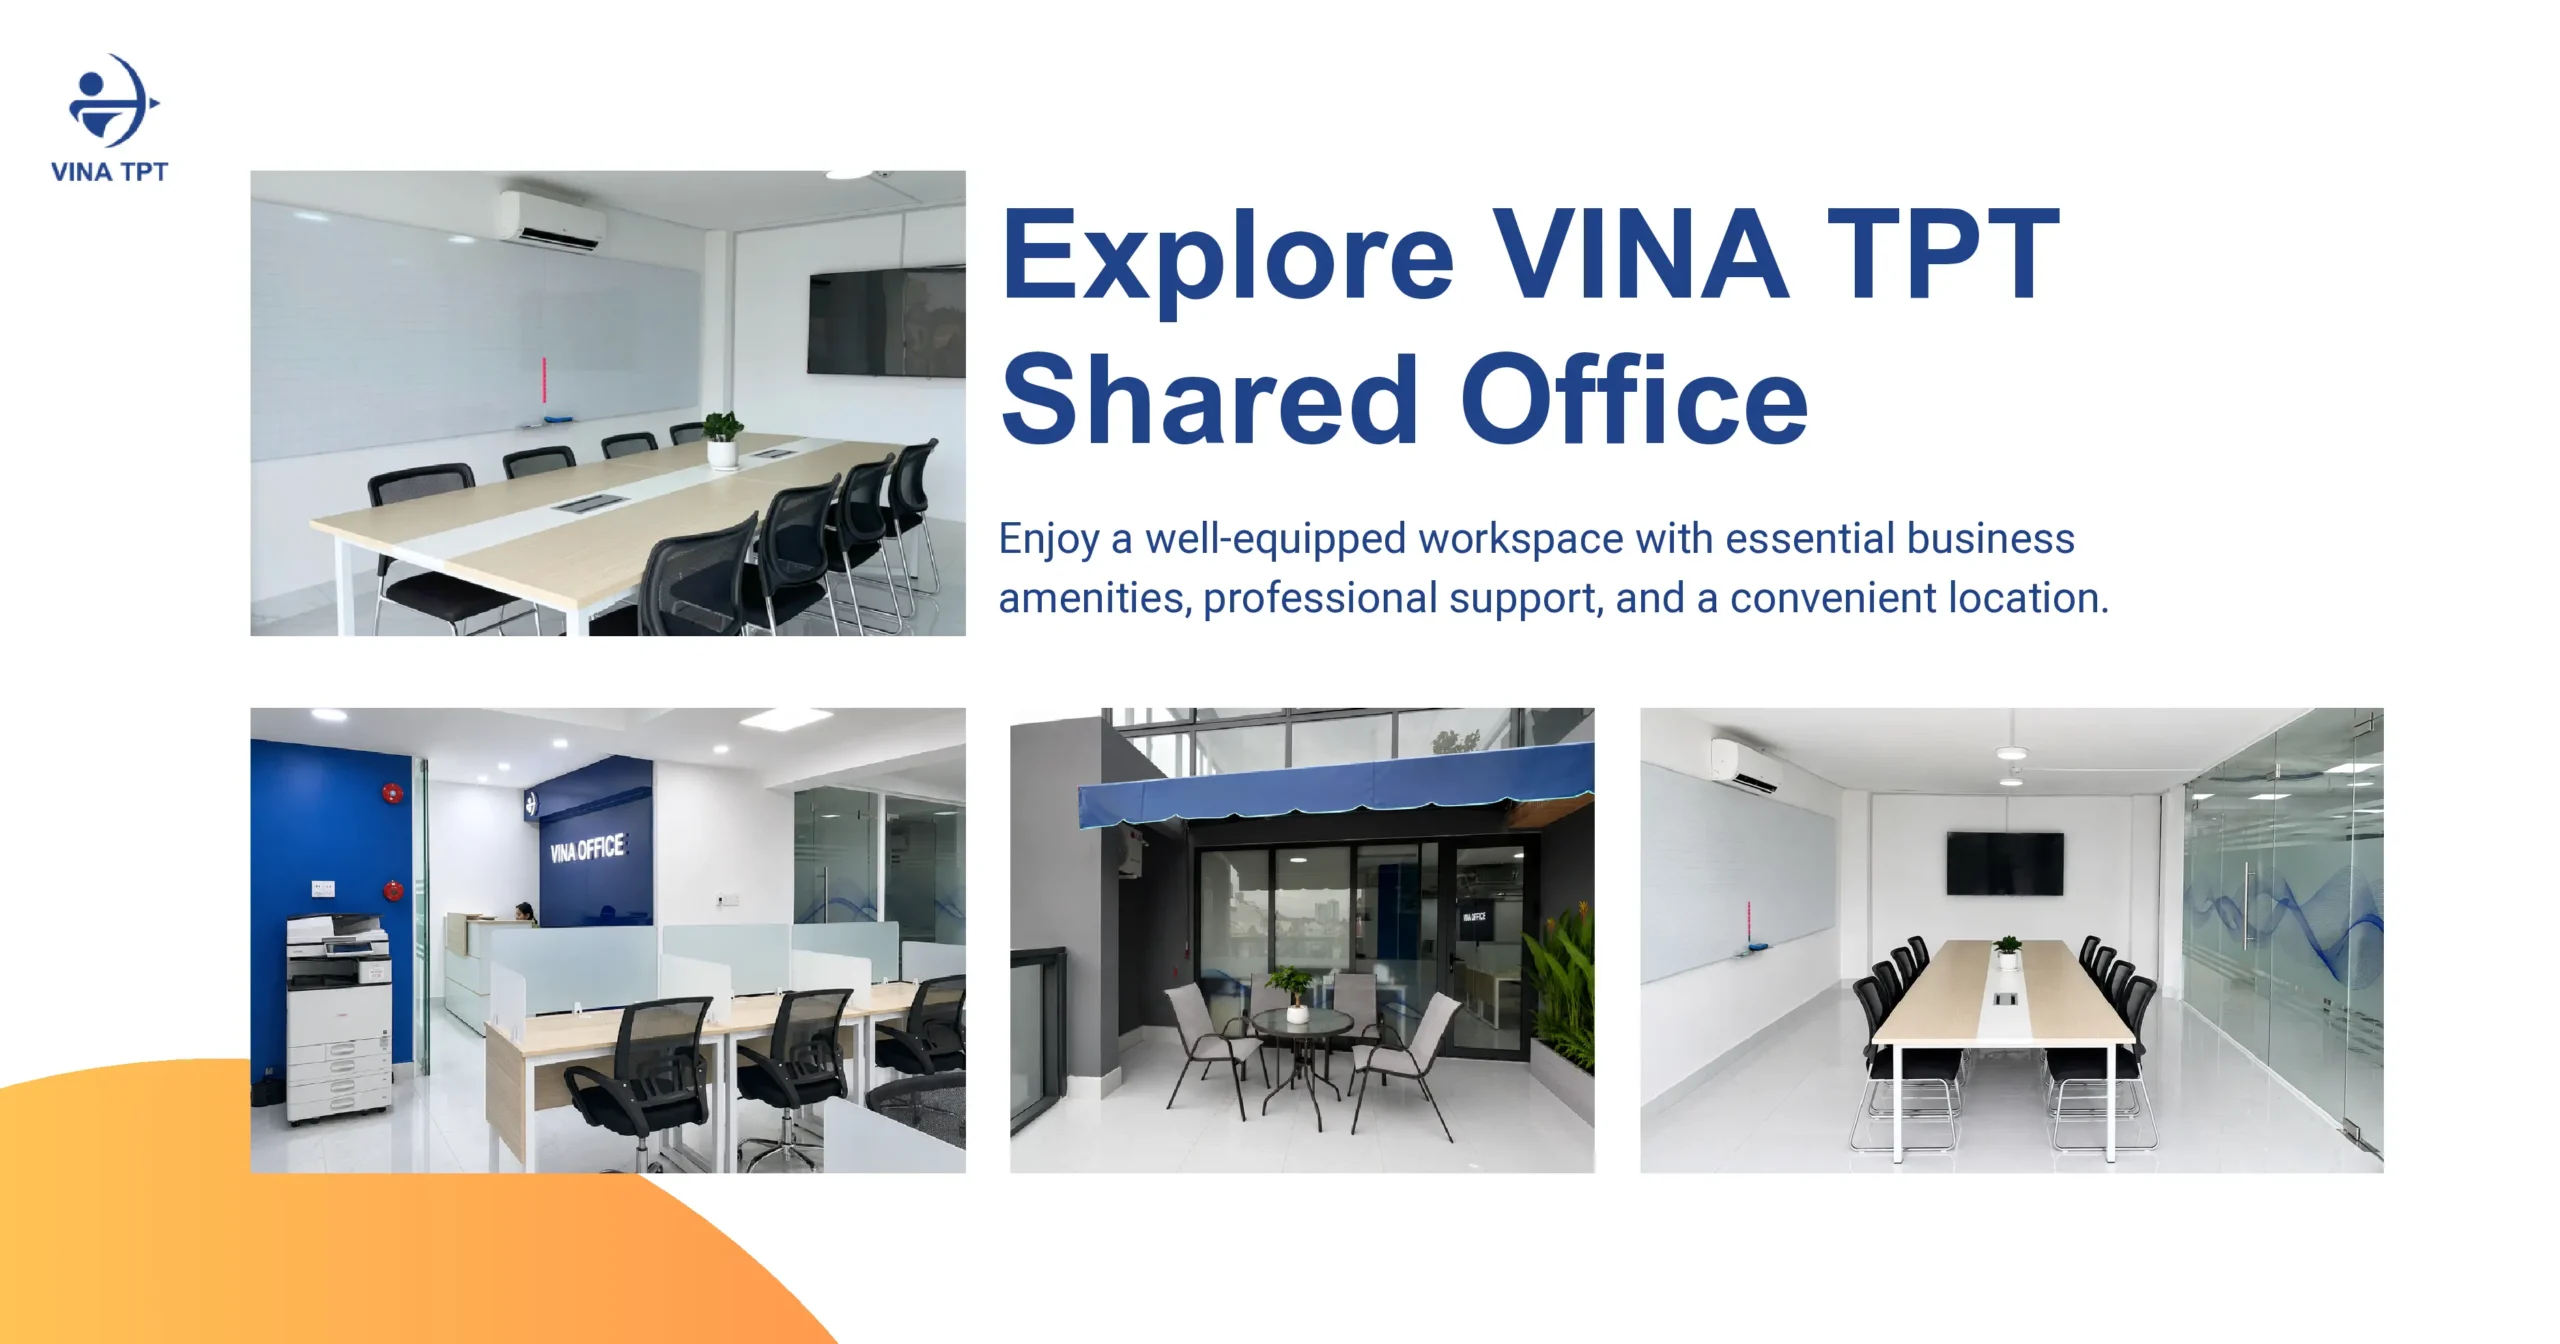
To solve that cost problem, a Shared Office or Serviced Office is the most practical option at the launch stage. A standard Shared Office address does more than supply a lawful business-registration address for the IRC/ERC file. It also meets the tax authority’s on-site inspection criteria: a company signboard, a reception desk, staff answering the phone, and a meeting room when an inspection team visits.

Vina TPT provides a Shared Office package on Hoang Sa Street in District 1, Ho Chi Minh City. The package includes a lawful business-registration address, a proper company nameplate, professional reception, and a modern meeting-room system. This solution can reduce initial fixed costs by up to 80% and makes it straightforward to upgrade to a Private Office when headcount grows.

establish-a-small-business-in-vietnam-how-to-start

5. Required Documents and Legalization for Small Business Foreign Investors

Preparing the legal documents is the bottleneck that costs investors the most time. Every document issued by a foreign authority must go through consular legalization and a notarized Vietnamese translation before it can be filed with the competent authorities in Vietnam.

For an individual foreign investor, the standard dossier includes these core documents:

  • Personal passport: A copy of the investor’s valid passport, consular-legalized and accompanied by a notarized translation.
  • Proof of financial capacity: The investor’s most recent bank statement, showing a balance equal to or greater than the charter capital committed to the company. This document must also be consular-legalized.
  • Head-office premises file: An office lease or deposit agreement in Vietnam, together with the land-use rights certificate or other legal papers proving the landlord’s right to lease.
  • Application forms and investment proposal: The investment-registration and enterprise-registration forms prepared to the templates of the Ministry of Planning and Investment.

Note: Personal details (full name, passport number, permanent address) and project particulars (company name, head-office address, charter capital) must match 100% across every document – from the foreign-language original and the notarized translation through to the forms filed with the state authorities. Even a small discrepancy in a character or in the transliteration of a name can send the file back so that consular legalization has to be redone from the start.

6. Realistic Setup Costs and Operating Budget for Small Business in Vietnam

To manage cash flow effectively, the investor needs to separate one-time setup cost from the operating budget for the first 12 months. Preparing funds only for the licensing stage and overlooking post-establishment compliance is the main reason many companies end up in a financially passive position.

The basic cost groups are structured as follows:

One-time setup costs

  • State fees for the IRC, the ERC, enterprise information publication, and seal engraving.
  • Notarization, consular legalization, and translation of foreign documents.
  • Legal advisory and representation fees for filing the IRC/ERC dossier.
  • First-year rent for the registered address or a Shared Office.
  • Purchase of a digital signature (CA Token for 1–3 years) and e-invoice software.

Ongoing compliance and operating costs

  • Accounting and tax: Monthly or quarterly bookkeeping and tax filing, plus annual financial statements under VAS.
  • Labor and payroll: Salary calculation, personal tax-code registration, and social insurance contributions for staff.
  • Investment reporting: Periodic investment monitoring reports on the fdi.gov.vn system.
  • Sub-licenses: Maintenance or renewal of a retail business license or other industry-specific licenses, where applicable.

7. The Full Journey to Establish a Small Business in Vietnam at a Glance

To give investors a complete picture of the path from idea to the company actually starting operations, Vina TPT summarizes the execution cycle in the step-by-step table below:

No. Main step

Step details

1 Survey and structuring Choose the entity type (LLC) and review industry conditions
2 Legal preparation Consular-legalize personal documents and lease a Shared Office
3 Investment licensing File the dossier and obtain the Investment Registration Certificate (IRC)
4 Enterprise licensing File the dossier and obtain the Enterprise Registration Certificate (ERC)
5 Post-licensing Engrave the seal, open the DICA/VND accounts, and contribute full capital typically within 90 days
6 Operational activation Tax registration, CA Token, e-invoices, and sub-licenses where required
7 Ongoing compliance VAS accounting, tax, payroll, and investment reporting

8. How Vina TPT Helps You Establish a Small Business in Vietnam

Establishing a small business in Vietnam does not end on the day you hold the ERC. It is an ongoing process of keeping legal compliance aligned throughout the company’s life. Vina TPT is a B2B advisory firm that provides an end-to-end solution ecosystem so foreign investors can grow the business with confidence:

  • Legal structure and industry advisory: Assessing market-access conditions, advising on the capital model, and building a business-line list that is tax-efficient.
  • Full-package licensing: Standardizing the dossier, supporting translation and consular legalization, and representing the investor in filings for the IRC, ERC, and sub-licenses.
  • Registered head-office address: A compliant Shared Office in District 1, Ho Chi Minh City, that meets the tax authority’s inspection standards.
  • Post-establishment operating ecosystem: Full management of VAS accounting and bookkeeping, tax filing, payroll, social insurance, and periodic investment monitoring reports.

Are you planning to establish a business in Vietnam and need a safe, cost-efficient execution path? Contact Vina TPT’s specialist team for in-depth support today.

BOOK A FREE CONSULTATION

establish-a-small-business-in-vietnam-how-to-start

Common Tax Services in Vietnam and When Your Business Needs Them

common-tax-services-in-vietnam-and-when-your-business-needs-them

common-tax-services-in-vietnam-and-when-your-business-needs-them

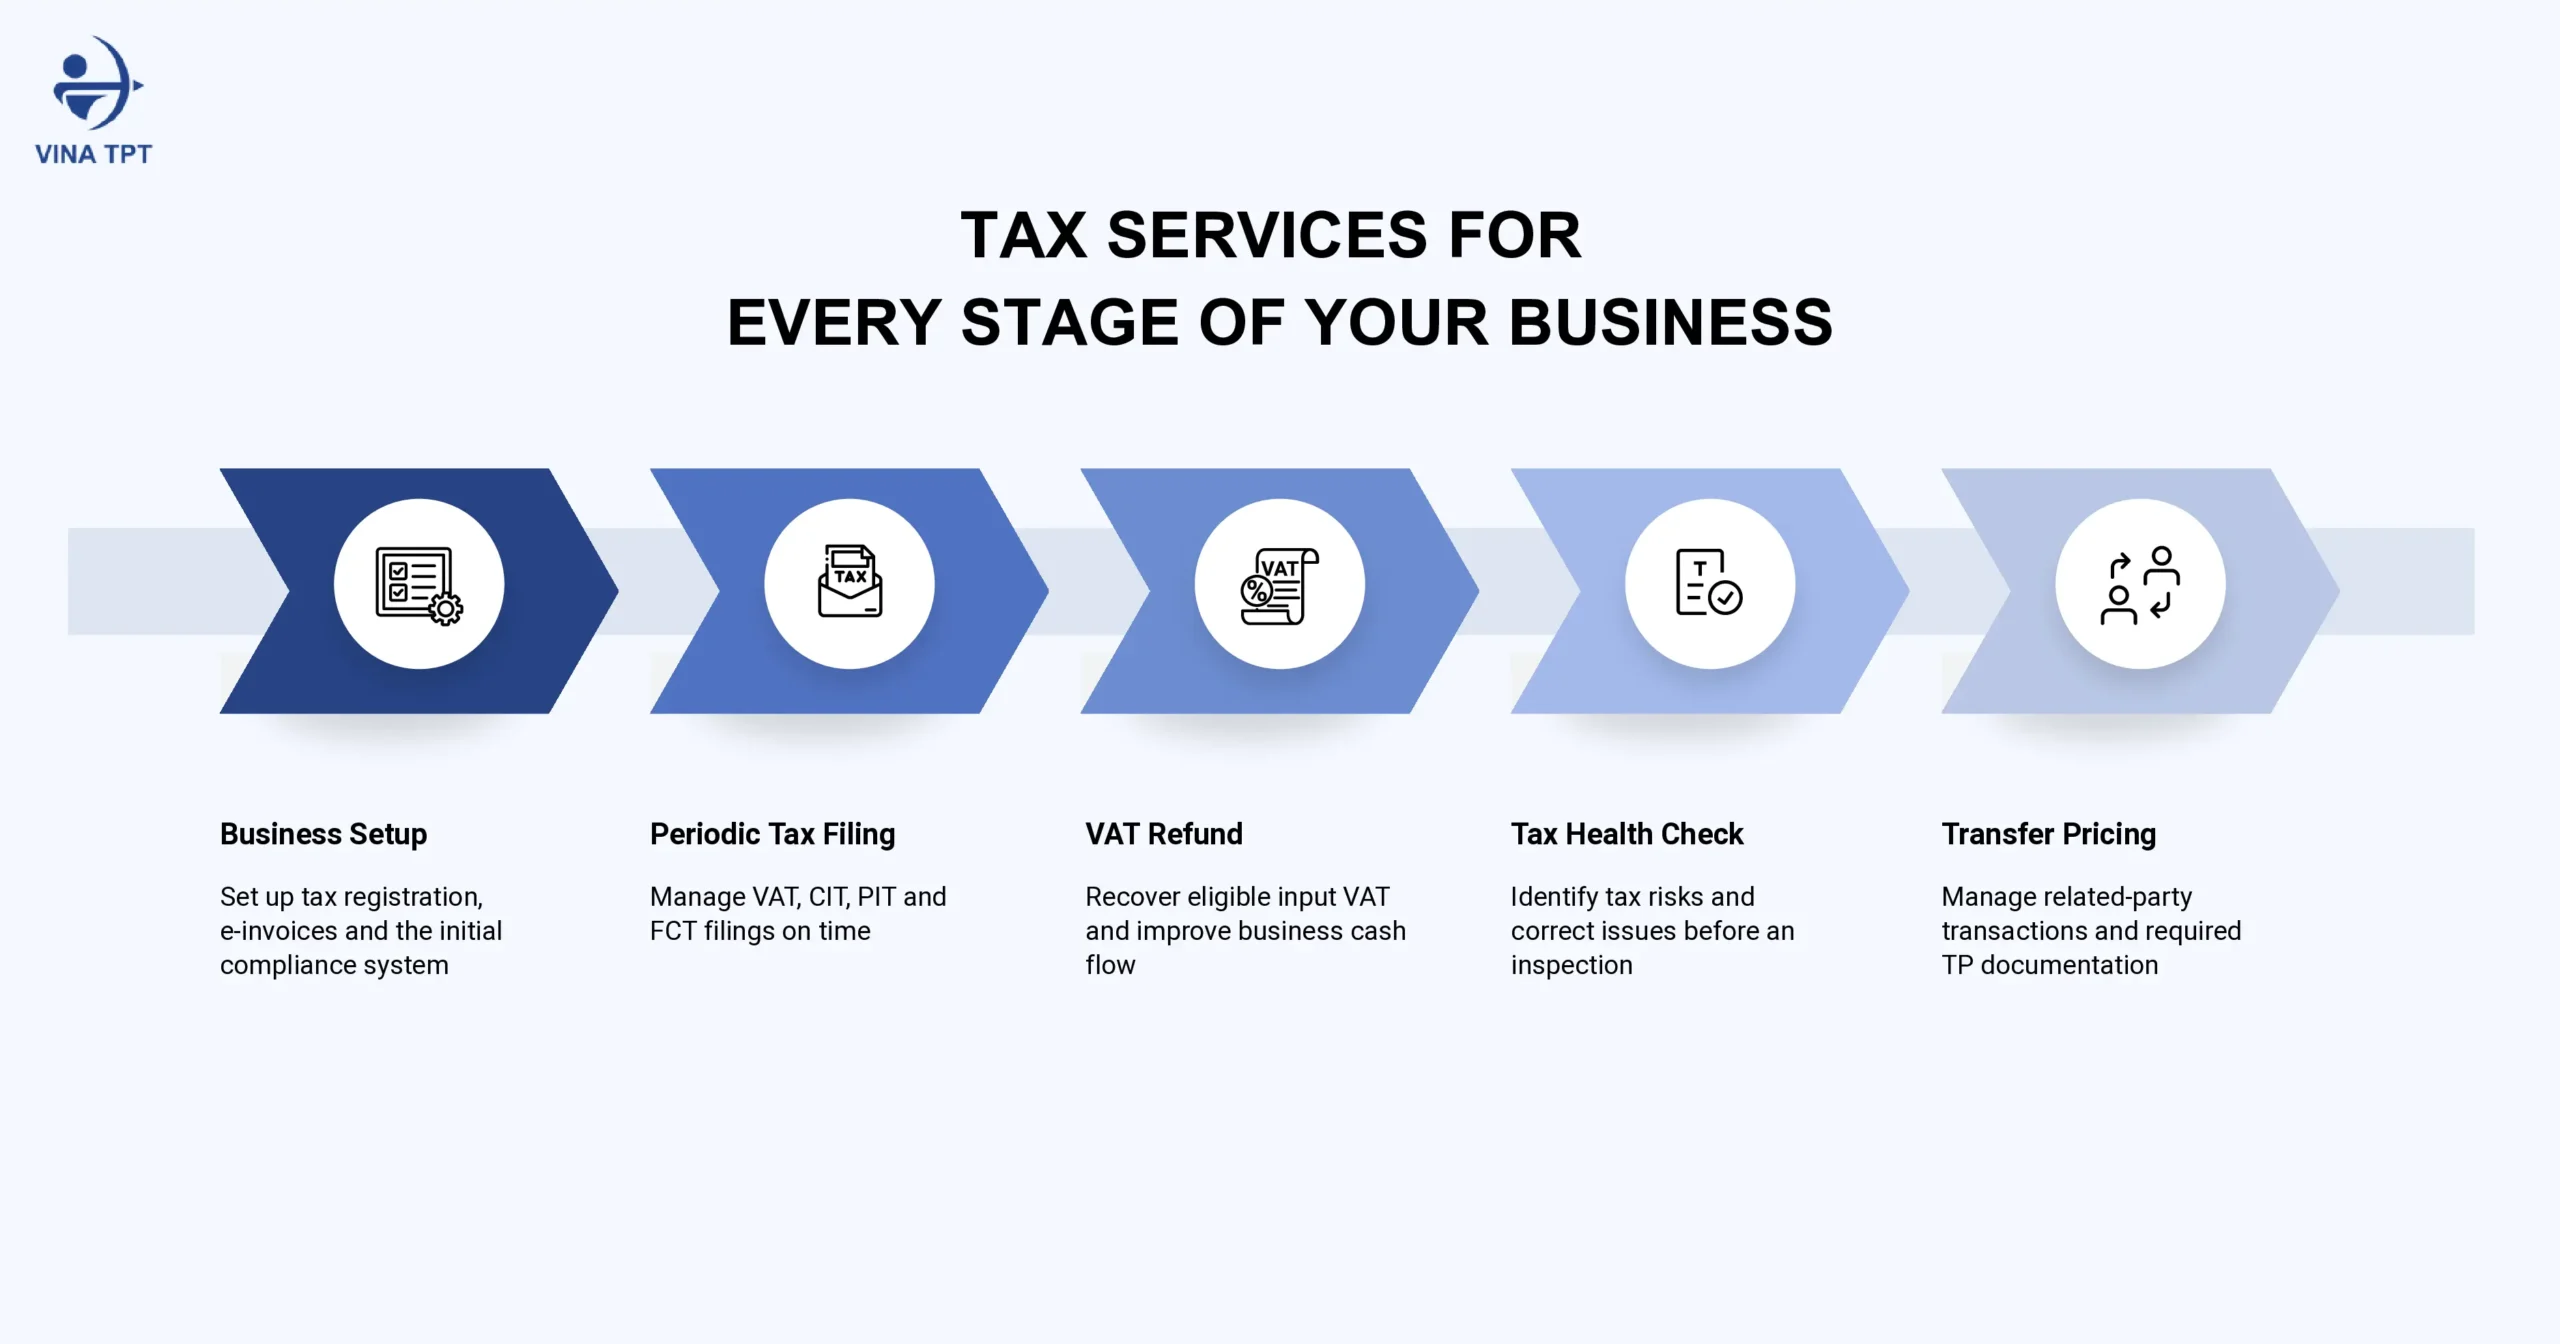
In the Vietnamese market, B2B tax advisory firms rarely apply a single packaged model to every company. In actual operations, the service system is divided into two distinct work groups:

  • Periodic compliance (Tax Compliance) is the workstream a company must maintain throughout its operating life. The typical scope covers initial tax registration, determination of the filing method and filing period, and then the preparation and submission of periodic returns: VAT on a monthly or quarterly basis; withholding PIT on a monthly or quarterly basis plus the annual finalization; quarterly provisional CIT followed by the annual finalization; Foreign Contractor Tax (FCT) whenever an outbound payment is made; and the business license fee together with any industry-specific taxes. This workstream is tightly linked to the accounting books. A return is only correct when the VAT (tax services in vietnam), payroll, FCT, and CIT figures match the source documents already recorded.
  • In-depth advisory (Tax Advisory) comes into play when the company needs more than on-time filing and has to resolve a specific situation. Common services include VAT refunds to recover cash locked in uncredited input VAT; a Tax Health Check to surface risk before an inspection or a fundraising round; and related-party / Transfer Pricing compliance when there are dealings with a parent or group company. Choosing the right tax services in Vietnam therefore depends not only on company size, but also on its operating stage, transaction structure, and current tax risks.. Many FDI companies also need expatriate PIT finalization – because residency status, the Work Permit, and the tax calculation method for expats differ from those for local staff — as well as Global Minimum Tax advisory when the group falls within the scope of application. This is not ordinary monthly filing work.

Many FDI companies and SMEs fall into an “operating trap” by choosing the wrong service package at the wrong time. The result is wasted cost on one side and a serious risk of tax reassessment and administrative penalties on the other.

The article below examines the most common tax services in Vietnam, explains which businesses need each service, and identifies the right time to use them.

1. Common Tax Services in Vietnam

As an FDI company grows, the scope of tax services in Vietnam it requires also becomes more complex, moving from initial registration and periodic filing to specialized advisory work.

Understanding this structure helps the Board of Directors and the finance team choose the right service package at the right time, and keep figures consistent across accounting, tax, and investment reporting.

1.1. Initial Tax Registration 

This service layer is the first legal stepping stone immediately after company incorporation and establishes the foundation for tax compliance Vietnam requirements throughout the company’s operating life.

  • Scope of work: Registering the company’s Tax Identification Number (TIN), purchasing and activating a digital signature (CA token), registering e-invoices with the tax authority, determining the VAT calculation method (credit/deduction method or direct method), opening a bank account and notifying the tax authority of the account, and completing Level-2 VNeID identity for the Legal Representative.
  • Suitable for: Newly established FDI companies looking for tax services in Vietnam immediately after receiving an Enterprise Registration Certificate (ERC), particularly those preparing to commence operations without an in-house tax team.
  • When to implement: Immediately after the ERC is issued and before the first invoice is issued or any payment or capital contribution is received.

Vina TPT’s professional view: Configuring the wrong filing frequency (monthly versus quarterly, or vice versa) or choosing the wrong VAT method at this stage will create a chain of problems and force the company into complex explanation procedures with the managing tax authority.

1.2. Periodic Tax Filing (VAT, CIT, PIT, FCT, License Tax)

Periodic filing is one of the core tax services in Vietnam, covering recurring monthly, quarterly, and annual tax obligations for operating companies.

  • Scope of work:
    • Value-Added Tax (VAT): Preparing monthly or quarterly VAT returns and reconciling incoming and outgoing invoices on the General Department of Taxation’s e-invoice system.
    • Personal Income Tax (PIT): Filing monthly or quarterly withholding PIT returns and completing the annual PIT finalization for Vietnamese employees and expatriates.
    • Corporate Income Tax (CIT): Calculating and paying quarterly provisional CIT (ensuring that the four quarterly payments are not lower than 80% of the annual amount payable) and preparing the annual CIT finalization return.
    • Foreign Contractor Tax (FCT): Declaring and paying FCT on each occurrence or on a monthly basis whenever payments are made to foreign suppliers.
  • Suitable for: Every company operating in Vietnam. It is especially relevant for FDI companies with a complex cost structure, expatriate payroll, or outbound payments for royalties, loan interest, and international consulting services.
  • When to implement: From the first filing period after the Tax Identification Number (TIN) is issued – even if no revenue or expense has arisen yet – and on a continuous basis in line with statutory deadlines.

EXPLORE ACCOUNTING & TAX SERVICES

1.3. VAT Refund 

Among specialized tax services in Vietnam, VAT refund support goes beyond standard periodic filing (tax services in vietnam). It is a specialized advisory and dossier-handling process designed to recover eligible input VAT that has not yet been fully credited.

  • Scope of work: A VAT refund is not an extension of the monthly return. It is a specialized service: reviewing the legality of every incoming invoice, checking non-cash bank payment evidence, reconciling customs declarations and export contracts where goods are exported, preparing the refund dossier, filing it, and explaining it directly to the tax authority during the pre-refund or post-refund inspection.

The person handling the file must have processed real cases, because any document group can delay or reject the application. Invoices that do not qualify for credit, cash payments on transactions of VND 5 million or more, discrepancies between the VAT return and the export file, or explanations that do not match the books are the first points the tax authority will raise. Advice that stays theoretical – and has never followed a dossier through to a refund decision – will struggle to anticipate supplementary requests and the timeline for receiving the funds.

  • Suitable for: Companies whose accumulated uncredited input VAT is VND 300 million or more and that also meet all current refund conditions. For the detailed conditions and eligible cases, refer to VAT Refund in Vietnam 2025: Updated Conditions and Eligible Cases Explained.
  • When to implement: When the refundable VAT amount is material and the company needs to release frozen cash for reinvestment.

1.4. Tax Health Check and Risk Review

A Tax Health Check is one of the preventive tax services in Vietnam designed to identify compliance risks before they develop into larger issues during a tax inspection.

  • Scope of work rewritten: A Tax Health Check is an independent third-party review of the full set of accounting books, the tax compliance position, and the alignment between those two sources. The work covers examining source documents, VAS bookkeeping, a review of VAT, CIT, PIT, and FCT, identifying items at risk of being disallowed as deductible expenses, and then preparing a risk report with a plan to file supplementary returns if needed.

When the books and the tax returns are placed side by side, the company can see the gaps in control or in cash flow: invoices that do not qualify for credit, expenses lacking supporting documents, omitted FCT, off-track provisional CIT, or payroll figures that do not match PIT. From those discrepancies, the advisor proposes a suitable course of action: tightening the document process, amending returns, strengthening internal controls, or preparing an explanation file ahead of an inspection.

  • Suitable for: A Tax Health Check is suitable for companies that have operated for two to three years or more but have not yet gone through a tax inspection; companies preparing for an M&A transaction, a restructuring, or a fundraising round; companies that are about to change their accounting and tax service provider; or companies that want to review internal processes and put in place tighter controls over documents, filings, and figure reconciliation before risk is discovered from the outside.

1.5. Transfer Pricing and Related – Party Transactions

Transfer Pricing is the way a company prices transactions with related parties so that the price of goods, interest, royalties, or management fees has a comparable basis and is not treated as a tool for shifting profit between companies in the same group. Related-party transactions are those dealings: buying and selling goods, lending, receiving services, paying group management fees, or paying royalties to a parent, a subsidiary, a commonly owned company, or another party treated as related under Vietnamese tax law.

These transactions usually arise when an FDI company in Vietnam is not fully standalone. The company may import raw materials from a group plant, pay a management fee to an overseas headquarters, take an intra-group loan, or pay a royalty to use the parent’s brand and technology. Not every outbound payment is a related-party transaction – hiring an independent contractor, for example, may give rise only to FCT – but most companies that belong to a multinational group need to identify the correct counterparties before CIT finalization.

This is a specialized tax advisory Vietnam workstream. The tax authority does not only ask whether the return was filed; it asks whether the price and the profit margin are reasonable compared with independent dealings. Missing documentation, or internal pricing that is too high or too low, can lead to a deemed assessment and a tax reassessment. The company should therefore understand the nature of the transaction first, and only then move on to the appendices and the Transfer Pricing documentation.

Within specialized tax services in Vietnam, Transfer Pricing requires a more structured execution process once the nature of the related-party transactions has been correctly identified. The work does not stop at a year-end appendix; it runs across four layers.

  • Diagnostic review is the step of reading back every transaction with the parent and related companies: purchases and sales of goods, intra-group loans, group management fees, royalties, cost sharing, or the provision of services. The advisor identifies which transactions fall within the related-party scope, where current pricing sits, what is missing from the existing file, and which points the tax authority is likely to raise when the figures are compared with independent profit margins.
  • Compliance filings are the statutory reporting layer. The company must prepare Appendices I, II, III, and IV on related-party transactions and submit them with the annual CIT finalization return, usually within 90 days after the end of the financial year. A missing appendix or an incorrect line item is not only a formal error; it is a signal for the tax authority to look more closely at internal pricing.
  • Transfer Pricing documentation goes beyond the return. The company prepares and retains the Local File, the Master File (Global File), and the Country-by-Country Report (CbCR) if it is in scope, under Decree 132/2020/ND-CP and the current implementing guidance. This file set explains why the chosen price, royalty, or management fee was selected and which comparability method is being used.
  • Defense during inspection is the final layer. When the tax authority inspects Transfer Pricing, the advisor represents the company in explaining the pricing method, the profit margins, and the link between the documentation, the books, and the CIT return. Completing the first three layers early reduces the pressure at this stage.

This service is suitable for FDI companies that are members of a multinational group and buy or sell goods, provide services, lend, or franchise with related parties. Implementation should start as soon as related-party transactions arise – not wait until the finalization deadline is close. The file must be complete before the annual CIT finalization deadline so the company is not filing the return while still lacking documents when questions are asked.

common-tax-services-in-vietnam-and-when-your-business-needs-them

2. How Vina TPT Provides Tax Services in Vietnam

Vina TPT provides tax services in Vietnam for most types of companies operating in the country: newly established companies that need setup and periodic filing, SMEs with a stable transaction flow, and FDI companies that belong to a group and have a more complex cost structure. The foundation layer covers tax registration, e-invoices, VAT, CIT, PIT, and FCT filings, and the monthly, quarterly, and annual obligations that follow.

In parallel, the team includes CPA-qualified specialists and Chief Accountants who can support the deeper issues that a monthly return cannot resolve: VAT refunds, Tax Health Checks, expatriate PIT finalization, related-party / Transfer Pricing documentation, and advisory work when the company falls within the scope of the Global Minimum Tax.

  • Foundation compliance layer: Core tax services in Vietnam covering initial tax setup and timely VAT, CIT, PIT, and FCT filings aligned with the accounting books.
  • In-depth advisory layer: VAT refund dossiers, independent Tax Health Checks, and the review and preparation of Transfer Pricing documentation.
  • Integrated operating ecosystem: Connecting tax data with the VAS books, payroll and social insurance, financial statements, and FDI investment monitoring reports.

If your company is reviewing its current tax services in Vietnam – from periodic filing to VAT refunds, Tax Health Checks, or Transfer Pricing – contact Vina TPT for a tax roadmap that matches your operating stage and compliance needs.

BOOK A FREE CONSULTATION

How to Start an International Business in Vietnam?

how-to-start-an-international-business-in-vietnam

how-to-start-an-international-business-in-vietnam

The FDI picture in Vietnam is expanding at pace. Disbursed capital reached a record USD 27.62 billion in 2025, and in the first six months of 2026 registered capital jumped to USD 34.65 billion, up 61% year on year. A consumer market of VND 7,093 trillion is driving global brands such as OH!SOME, Saizeriya, Pin Wei, Shake Shack… to keep expanding their legal entities and on-the-ground retail networks.

With a rapidly growing middle class, improving logistics infrastructure, and a new generation of FTAs, Vietnam offers significant opportunities for investors looking to establish an international business in Vietnam.

Working alongside FDI companies, this article from Vina TPT maps the full market-entry roadmap: choosing the form of legal presence, reviewing conditional business lines, obtaining the IRC and ERC, and building a tax, accounting, and labor system that is complete and correct from day one.

1. Choose the Right Form of Presence First

The first step in establishing an international business in Vietnam is not choosing a brand name. It is selecting the form of legal presence that accurately matches the investor’s business objectives.

  • Limited Liability Company (LLC): This is the most common and optimal model, accounting for more than 90% of FDI projects in Vietnam. It applies limited liability within the scope of contributed capital, has a relatively flexible governance structure, and allows 100% foreign ownership in most business lines. It is the most suitable choice for trading, services, manufacturing, and technology activities.
  • Representative Office (RO): An RO only serves as a liaison, market-research, and trade-promotion unit. Vietnamese law strictly prohibits an RO from conducting direct profit-making activities. It may not sign commercial contracts (except under a valid power of attorney), issue invoices, or collect payment from customers. Many foreign investors set up an RO because they assume the procedures are simpler, then later have to dissolve it and incorporate a company because the RO cannot carry out business operations.
  • Joint Stock Company (JSC): This form is suitable for large-scale projects that plan to raise capital from multiple shareholders or aim for a stock-exchange listing. However, the governance structure and internal regulations of a JSC are significantly more complex than those of an LLC.

2. Check Market Access and Conditional Business Lines

Before establishing an international business in Vietnam, foreign investors must carefully review the market-access conditions for their intended business lines under the Law on Investment, the WTO Commitments Schedule, and relevant Free Trade Agreements.

  • Fully open sectors: Foreign investors are permitted to hold 100% of charter capital (for example: management consulting, manufacturing, software, and wholesale trading).
  • Conditional market-access sectors: These may impose a cap on foreign ownership (foreign room), a required form of investment (such as a joint venture with a domestic partner), or experience and capability requirements.
  • Sub-license / Business License requirements: Sensitive sectors or those that directly affect consumers – such as retail (import-export and retail distribution), F&B, education, logistics, pharmaceuticals, and e-commerce – require a specialized license after the company has been established.
  • Investment capital requirements: General law does not prescribe a minimum charter capital for every sector, but the registered capital must be commensurate with the project scale and the feasibility of the business plan. Capital that is too low will lead the licensing authority to refuse project approval or to request repeated additional explanations.

3. Step-by-Step: Set Up International Business in Vietnam

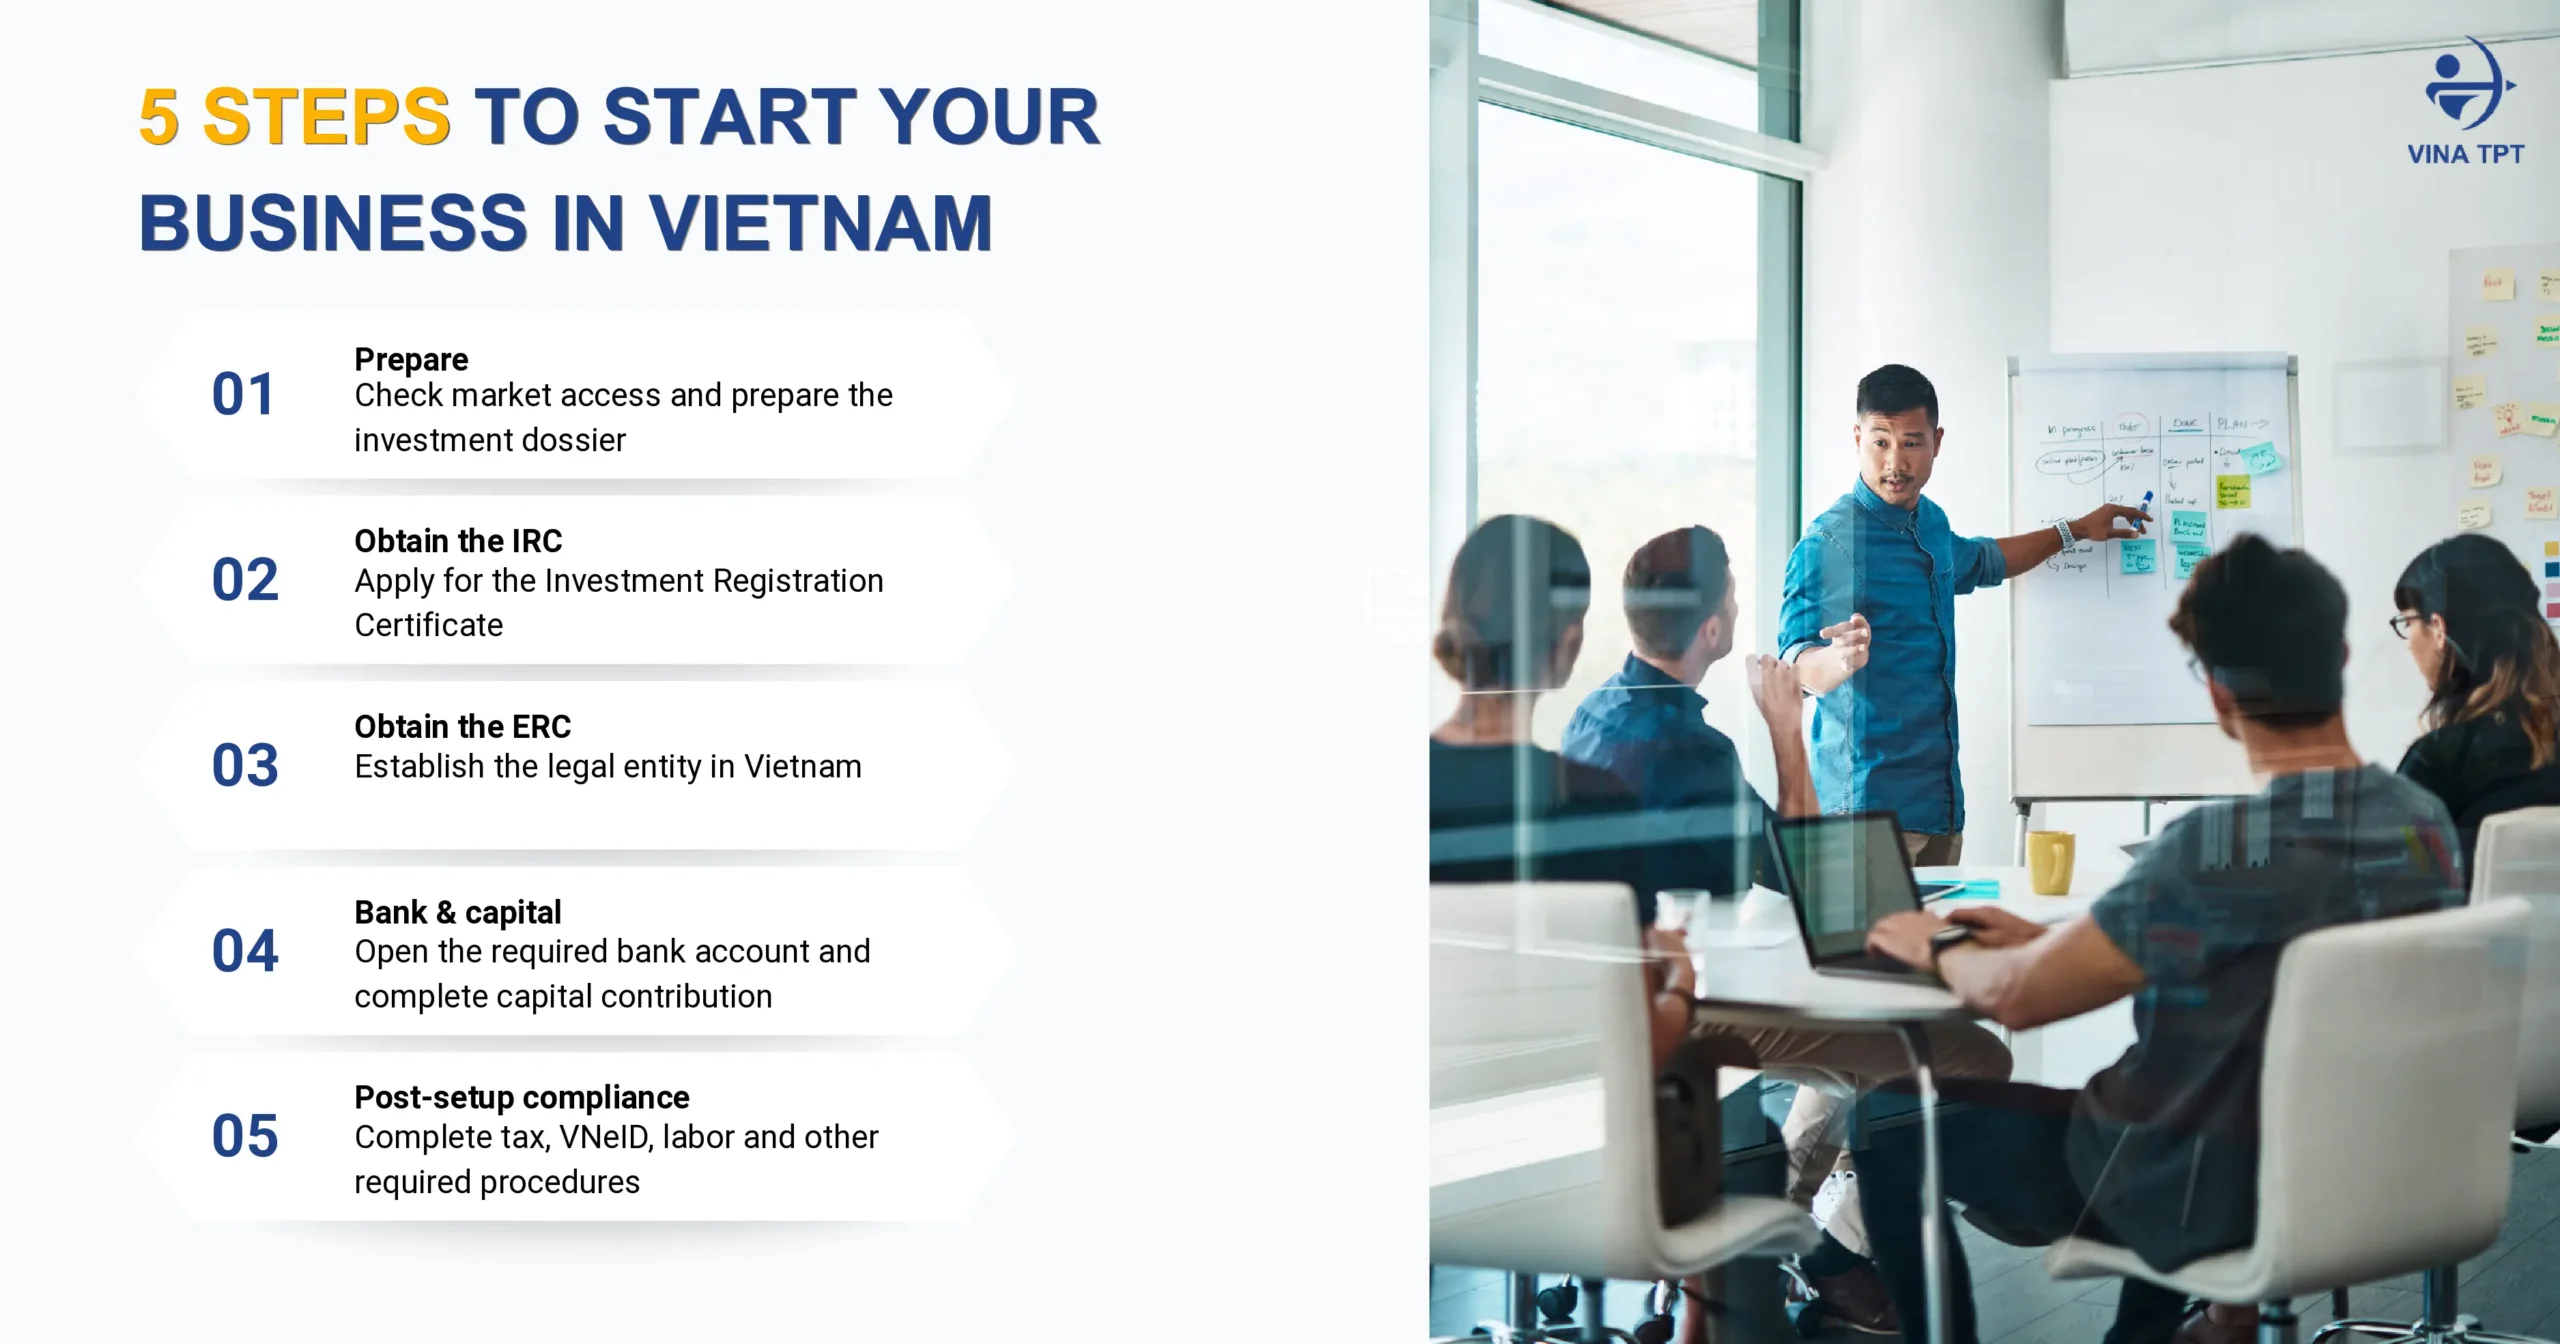
The standardized process answering the question of how to register a company in Vietnam for foreign investors consists of the following 5 core stages:

Step 1: Industry Survey and Preparation of the Investment Dossier

Before commencing the company establishment procedures, the investor needs to accurately determine the business industry codes according to the Vietnam Standard Industrial Classification (VSIC) and cross-check them against the WTO Commitments Schedule and the Law on Investment to verify market access conditions. Certain sectors classified as conditional business lines will require additional specialized licenses or compliance with standards related to capital, personnel, and facilities. At this stage, the investor is advised to contact a local consulting firm for support in reviewing the industry codes and assessing the project’s feasibility.

After identifying the suitable industry, the investor proceeds to prepare the investment dossier under the guidance of the service provider. Documents of the investor (whether an individual or an organization) must be consular-legalized abroad before being brought to Vietnam for use. The consular legalization process usually takes 14 to 30 days, depending on the procedures of each embassy/consulate and the respective country.

Estimated time for the entire step: approximately 5-7 working days (excluding consular legalization time).

Step 2: Submission of the Application for the Investment Registration Certificate (IRC)

The investment dossier is submitted to the Department of Finance. The competent authority will appraise the market conditions, project location, and the investor’s financial capacity before officially issuing the IRC.

Estimated time: 30 – 45 working days.

Step 3: Submission of the Application for the Enterprise Registration Certificate (ERC)

After obtaining the IRC, the enterprise submits the legal entity establishment dossier to apply for the ERC. The business registration authority will appraise the company name, head office address, and governance structure. Once the ERC is completed, the enterprise code is simultaneously created on the National Business Registration Information System.

Estimated time: 14 – 20 working days.

Step 4: Opening a Bank Account, Engraving the Company Seal, and Making Capital Contribution

The enterprise proceeds to engrave the legal seal, publish the seal specimen, and open a Direct Investment Capital Account (DICA) at a commercial bank licensed to operate in Vietnam. Under the law, the investor must complete the transfer of the entire committed charter capital into the DICA within a maximum of 90 days from the date the ERC is issued.

Implementation time: Within 90 days as prescribed by law.

Step 5: Completion of Tax Registration and Post-Establishment Compliance

The enterprise purchases a digital signature (USB Token), installs the company signboard at the head office, carries out initial tax registration, submits the business license fee declaration, and registers the electronic invoice system. At the same time, the company completes labor registration and social insurance procedures if employees are officially hired, and registers the enterprise electronic identity account (VNeID for enterprises) to facilitate electronic administrative procedures and transactions with state authorities.

Estimated time: 14 – 30 working days. 

Explore Company Registration Service

how-to-start-an-international-business-in-vietnam

4. Tax, Accounting and Labor Obligations After Setup

Once an international business in Vietnam is legally established, ongoing tax, accounting, labor, and investment reporting obligations arise immediately, regardless of whether the company has recorded any revenue.

  • Tax obligations: The company must declare and pay on time Value-Added Tax (VAT), Corporate Income Tax (CIT), Personal Income Tax (PIT) for employees, and Foreign Contractor Tax (FCT) whenever payments are made to international counterparties.
  • Accounting standards and audit: Accounting books must be maintained under the Vietnamese Accounting Standards (VAS). An FDI company is required to appoint a legally qualified Chief Accountant and must have its annual financial statements audited by an independent audit firm in Vietnam before submitting them to the tax and statistics authorities.
  • Labor law and expatriate compliance: The company must enter into labor contracts and make mandatory social insurance contributions. When employing foreign nationals, it must complete the Work Permit or Work Permit exemption procedures and obtain a Temporary Residence Card (TRC) to ensure lawful residence.
  • Investment Activity Report (IAR): This is a mandatory quarterly and annual reporting obligation on the National Foreign Investment Information System. Discrepancies between investment report figures and the audited financial statements can result in significant administrative penalties.

5. Practical Challenges Foreign Founders Often Underestimate

During implementation, many international investors run into bottlenecks because they underestimate Vietnam’s administrative barriers:

  • Registered office address barrier: Vietnamese regulations require a business to have a lawful registered office address that is suitable for business registration and can be verified by the relevant authorities. For foreign investors, setting up a traditional office from the beginning can be time-consuming and costly, as it may involve finding a suitable premises, negotiating and signing a lease, arranging the office, and preparing the necessary supporting documents. To save time and reduce initial setup costs, many investors therefore consider a Shared Office during the early stage of establishing their business. A suitable Shared Office can provide a lawful business address together with the necessary legal documents and support for an on-site inspection by the tax authority when required.
  • Requirements for the Legal Representative: The company must have at least one Legal Representative who resides regularly in Vietnam. This person must complete Personal Tax Identification Number registration, obtain a Work Permit, and activate Level-2 VNeID identity so that they can use a digital signature on public service systems.
  • Timeline slippage versus the original plan: Actual dossier review often takes longer than the theoretical timeline if overseas legal documents have consular-legalization defects, translations are inaccurate, or the explanation of the investment capital source does not meet the competent authority’s requirements.
  • Timeline slippage versus the original plan: Actual dossier review often takes longer than the theoretical timeline if overseas documents have consular-legalization defects, translations are inaccurate, or the explanation of the investment capital source does not meet the competent authority’s requirements.

For that reason, investors should appoint a partner for company setup, Chief Accountant support, and tax compliance from the dossier-preparation stage – rather than splitting the work into two phases of “get the license first, find an accountant later.”

6. How Vina TPT Supports International Business Setup in Vietnam

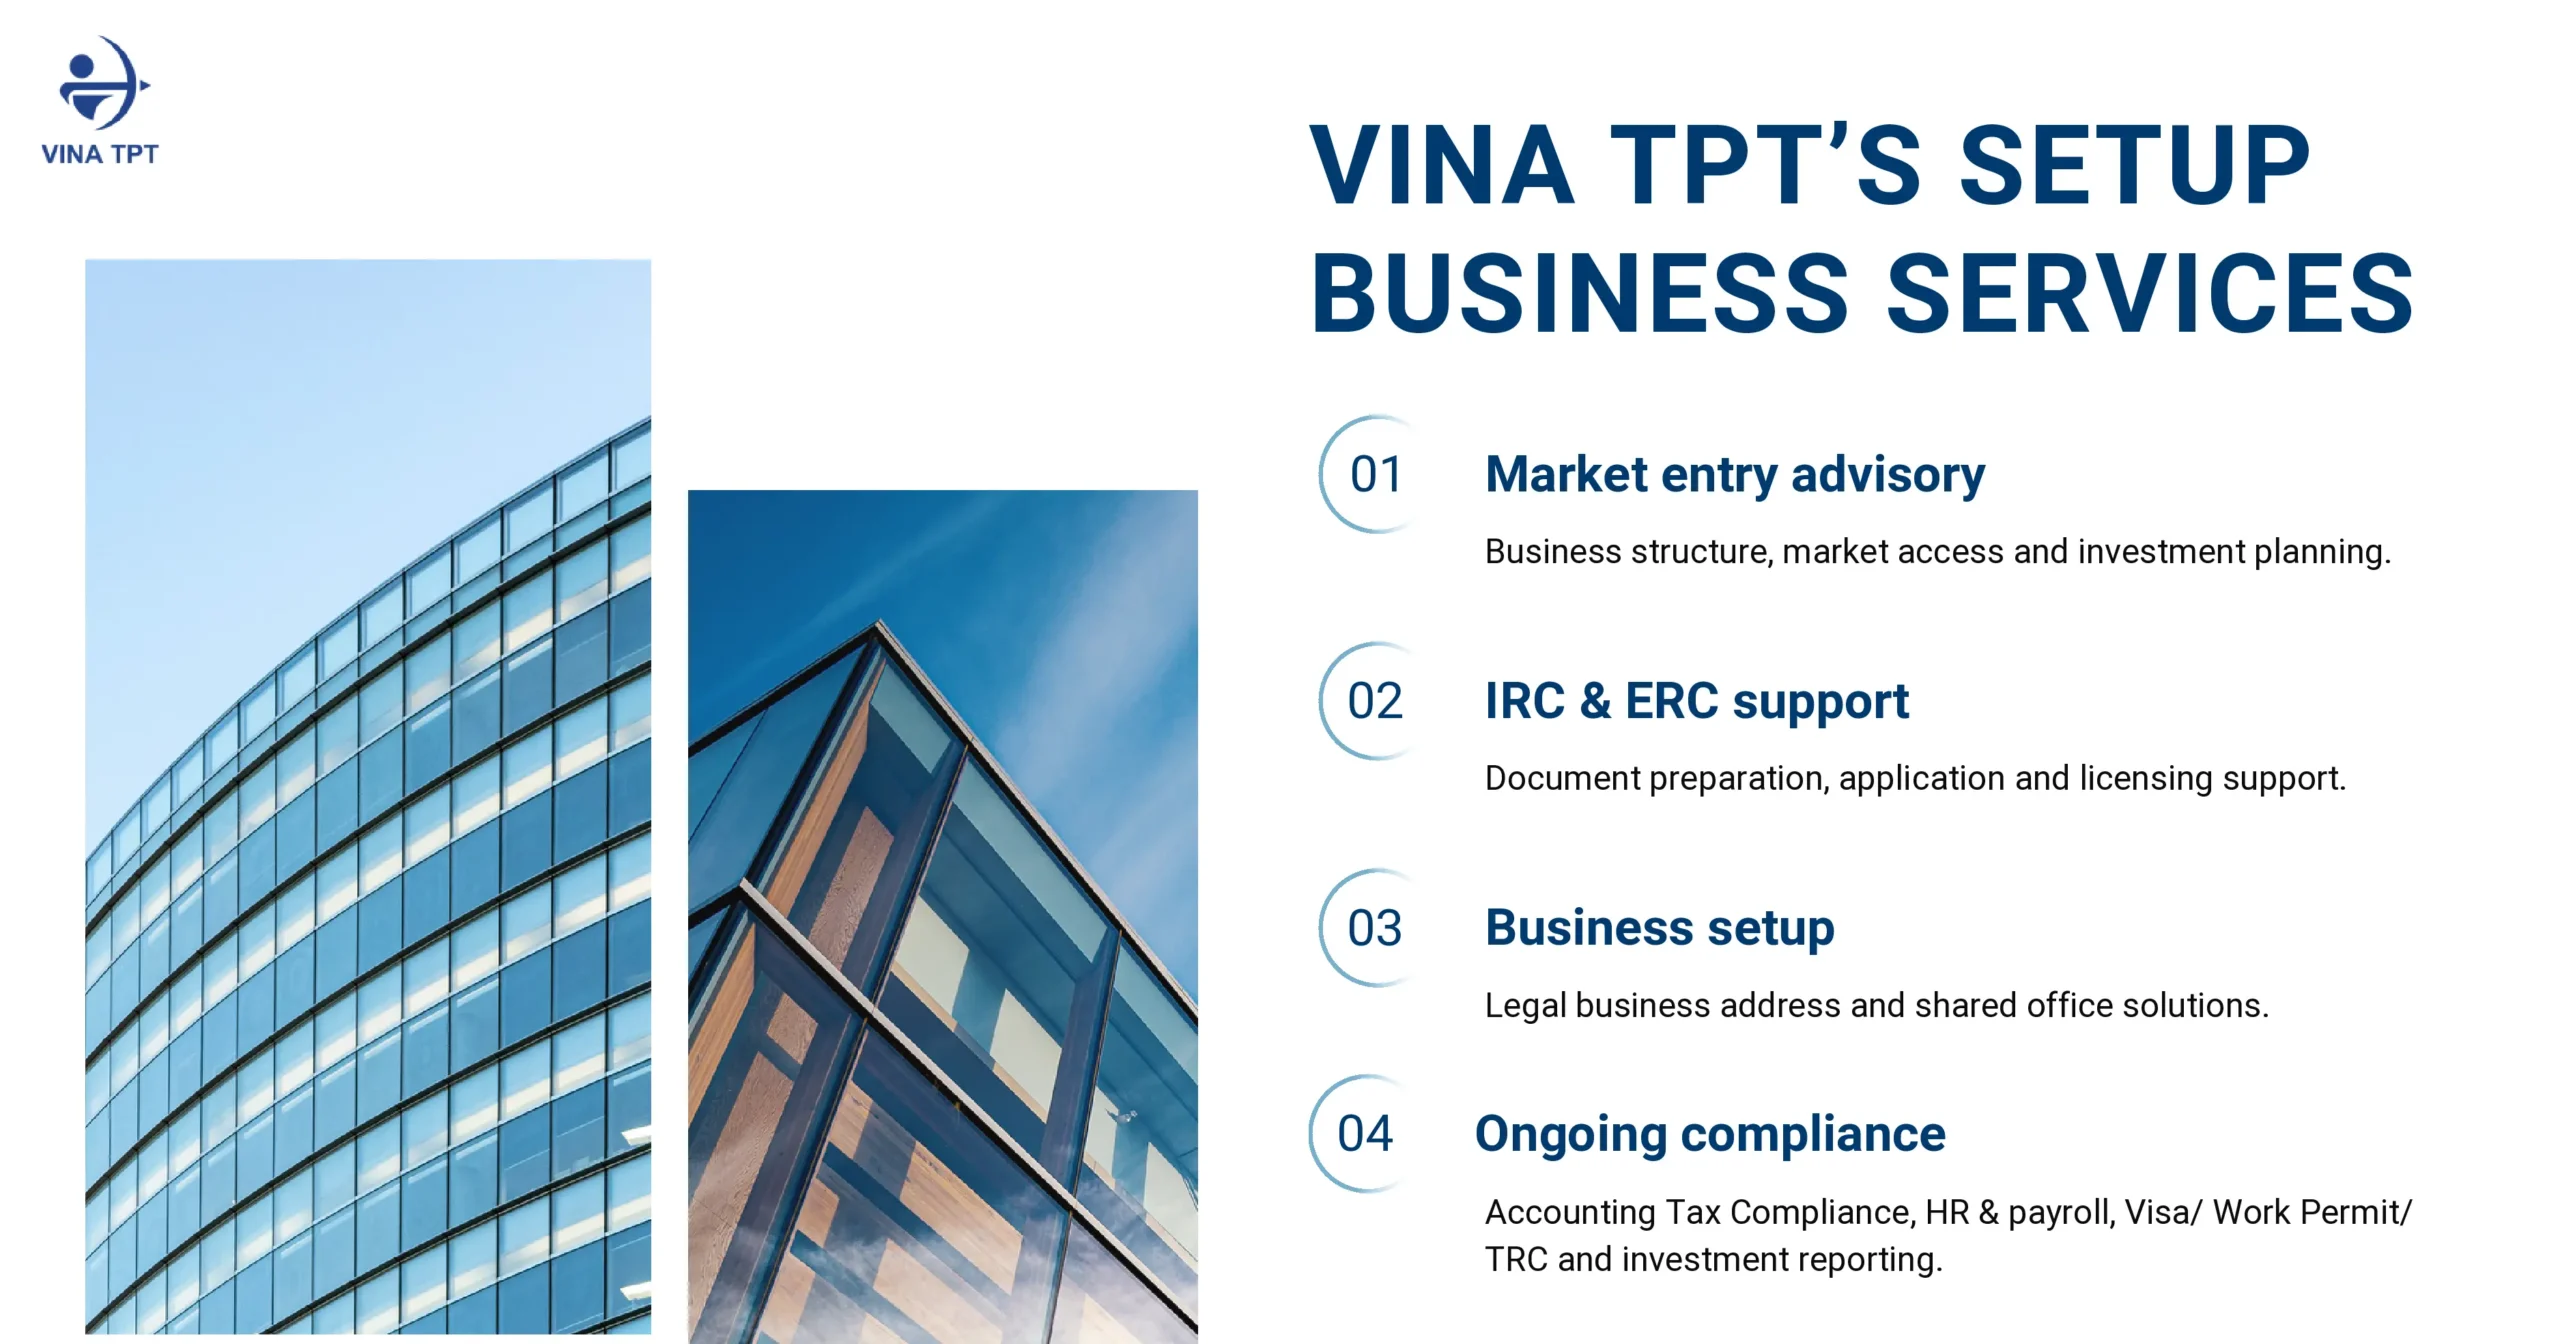
As a leading B2B advisory firm in accounting, tax, and corporate law for FDI companies in Vietnam, Vina TPT provides an end-to-end solution from market entry through to stable operations:

  • Legal structure and business-line advisory: We assess market-access conditions and recommend a capital structure and form of presence that is tax-efficient.
  • Full-package licensing: We prepare a compliant dossier and represent the investor before state authorities to obtain the IRC, ERC, and all required specialized business licenses.
  • Lawful registered office: Vina TPT provides a business registration address and a Shared Office solution that is legally qualified and meets the tax authority’s on-site inspection requirements. Refer to Shared Office Vietnam: A Smart Workspace Solution for Startups and FDI Companies to choose the right office model before you file the IRC/ERC dossier. 
  • Post-establishment management system: We deliver a full package covering VAS accounting and bookkeeping, financial statement, tax filing, HR & payroll, Work Permits, and periodic Investment Activity Reports (IAR).

Are you preparing a plan to start business in Vietnam? Contact Vina TPT’s specialist team today for an in-depth advisory roadmap and a complete company setup solution that is legally sound and operationally efficient.

BOOK A FREE CONSULTATION

how-to-start-an-international-business-in-vietnam

What Does a Tax Consultant in Vietnam Actually Do?

what-does-a-tax-consultant-in-vietnam-actually-do

what-does-a-tax-consultant-in-vietnam-actually-do

If you are already doing business in Vietnam and looking for tax advisory support, the harder question is often not whether to hire someone, but which services a tax consultant Vietnam actually offers. Some firms only handle monthly filings. Others also cover VAT refunds, tax health checks, inspection support, and transfer pricing. The scope is not the same, and the right package depends on where your company is in its operating cycle.

This article maps the tax advisory Vietnam services most commonly provided in the market: the routine accounting – tax work that keeps filings on time, the specialized work that protects cash flow and inspection risk, and the point at which an FDI company should bring in a professional partner. The goal is to give you a clear picture of tax compliance Vietnam support before you choose a consultant.

1. What Accounting & Tax Consultant Services Cover Each Month

For FDI companies, the role of a tax consultant Vietnam never stands alone as “someone who just files returns.” It must be tied to the internal accounting system. Periodic tax compliance Vietnam requires absolute accuracy from incoming source documents through to the data submitted on the Tax Authority’s system.

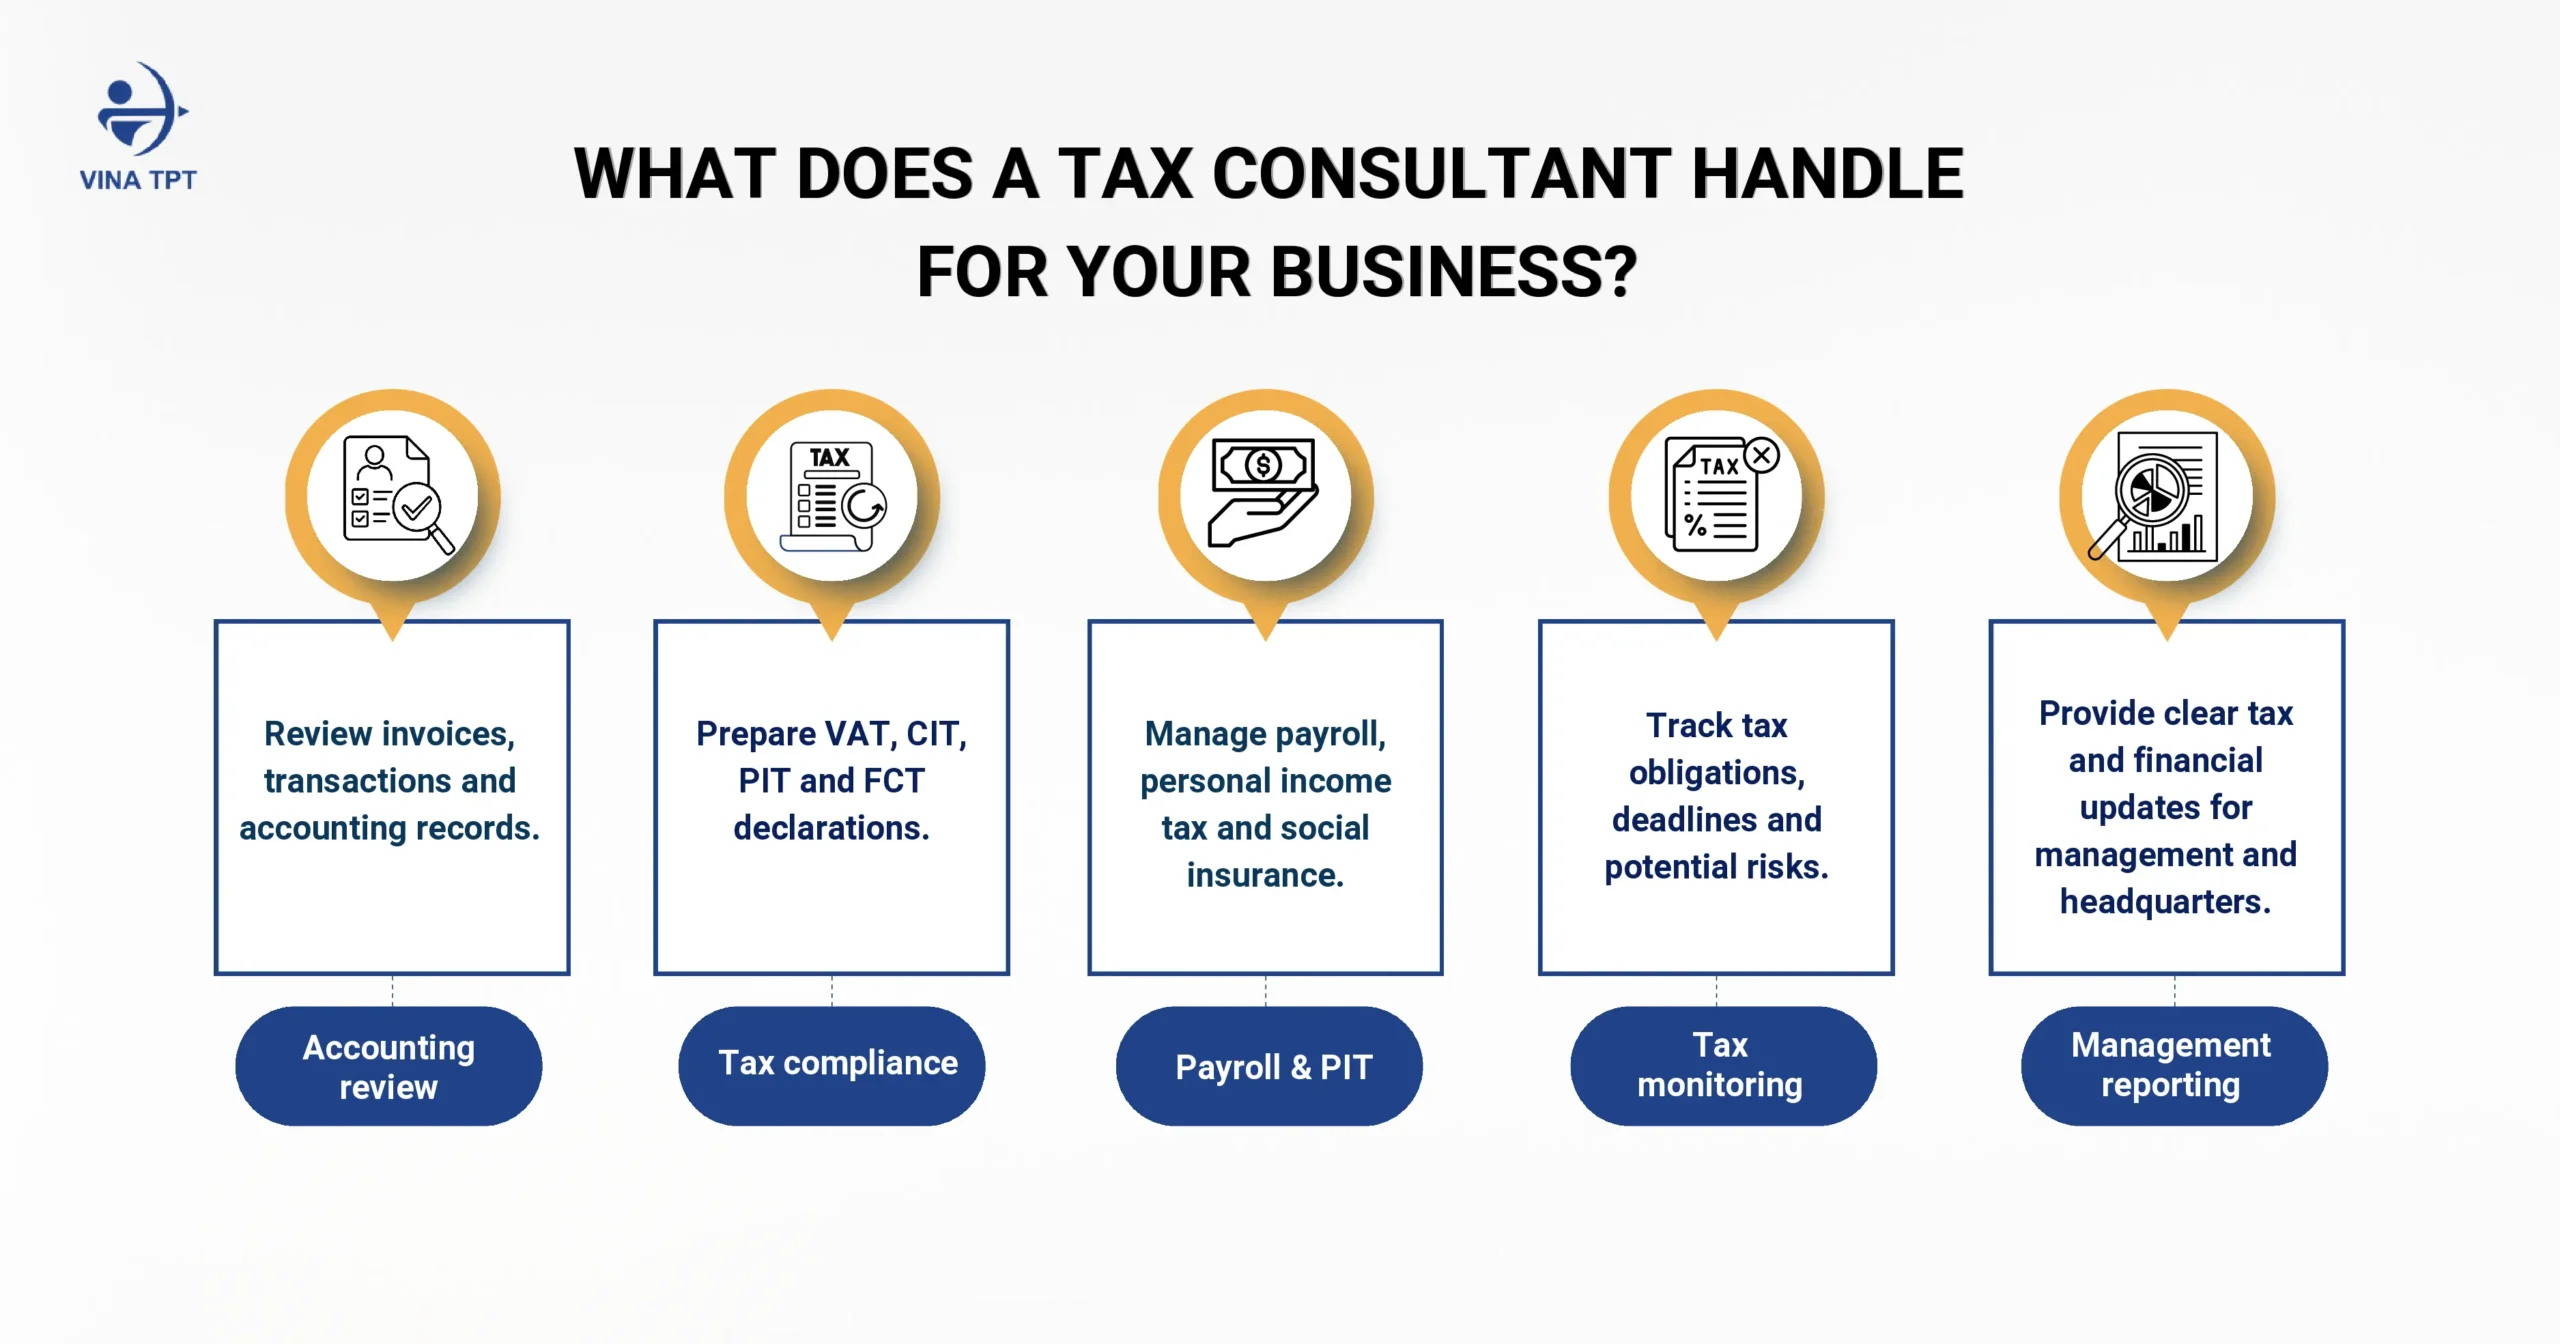
Below are the monthly and quarterly tasks that a professional tax advisory firm performs for FDI companies:

  • Document recording and e-invoice review: Receive all incoming and outgoing invoices and bank documents; review the legality, validity, and reasonableness of e-invoices on the General Department of Taxation portal to prevent risks from invoices issued by absconding or inactive companies.
  • Full identification of tax obligations arising in the period: Accurately assess the taxes the company must pay, including Value-Added Tax (VAT), Corporate Income Tax (CIT), Personal Income Tax (PIT), Foreign Contractor Tax (FCT), and the business license fee.
  • Preparation and on-time filing of tax returns: Build tax computation worksheets, prepare VAT and PIT returns on a monthly or quarterly basis, and file them through the e-tax portal before the statutory deadlines (the 20th of the following month or the last day of the first month of the following quarter), completely eliminating the risk of late-filing penalties.
  • Review of VAT deduction conditions and non-cash payment rules: Strictly check input VAT deduction conditions, especially the mandatory bank-transfer requirement for invoices of VND 5 million or more, and verify valid bank payment evidence.
  • Monitoring and balancing CIT provisional payments: Provisionally calculate actual quarterly profit to determine the CIT amount payable in advance, ensuring that the total provisional CIT paid over four quarters is not lower than 80% of the CIT payable on the annual finalization, thereby avoiding late-payment interest.
  • Monitoring of Foreign Contractor Tax (FCT): Declare and pay FCT promptly whenever outbound payments arise to international suppliers (software royalties, consulting fees, commercial commissions, foreign loan interest, etc.), preventing reassessment risk from omitted transactions.
  • Consolidated reporting for the Board of Directors and Headquarters: Prepare tax-obligation summaries and management reports in English and Vietnamese so that management in Vietnam and the overseas parent company can easily track cash flow and compliance status.

Vina TPT’s professional view: A full-package tax compliance service must deliver three core elements: clean accounting books + accurate tax returns + figures that reconcile between accounting and tax. If any one of these is missing, the tax position will be off even if the company still “files on time.”

2. When You Need Deeper Tax Consultant Support

Monthly filing work only keeps the company on the correct administrative rhythm. The actual operations of FDI companies regularly give rise to complex matters that require in-depth tax advisory Vietnam capability:

  • VAT refund consulting and implementation: For FDI companies with new investment projects or export businesses, the amount of undeducted input VAT is often substantial. A tax consultant Vietnam will review the entire legal dossier, the validity of invoices, export contracts, and bank payment evidence, then file the application and explain it directly to the Tax Authority in order to recover the refund into the company’s account.
  • Tax Health Check: A full review of the accounting books, tax returns, and supporting documents of prior financial years. This work helps the company proactively detect errors, non-deductible expenses, or potential violations before a tax inspection, fundraising, M&A, or share transfer takes place.
  • Inspection dossier preparation and representation before the Tax Authority: When a tax inspection or audit decision is issued, the advisor helps collect documents and prepare detailed explanations of sensitive expense items (entertainment, expatriate costs, foreign-exchange differences, etc.) in order to protect reasonable expenses as far as possible and minimize reassessment risk.
  • Related-party transaction management and Transfer Pricing (TP) documentation: Most FDI companies have transactions with the parent company or other related parties. The tax advisor is responsible for identifying the scope of related-party transactions, preparing the related-party transaction appendix attached to the CIT finalization return, and building the Transfer Pricing documentation set (Local File and Master File) in strict compliance with Decree 132/2020/NĐ-CP.

what-does-a-tax-consultant-in-vietnam-actually-do

3. When Does an FDI Company Need a Tax Consultant?

An FDI company should proactively look for a professional tax advisory partner when it falls into one of the following situations:

  • Newly established FDI company: It does not yet have a dedicated accounting and tax team that fully understands the Vietnamese legal system and needs to set up the initial books and compliance processes correctly.
  • Need for a VAT refund: It wants to shorten the refund timeline and ensure that the input dossier meets the Tax Authority’s inspection standards so that cash can be released sooner.
  • Related-party transactions: It needs advice on preparing Transfer Pricing documentation to the required standard in order to avoid the risk of the Tax Authority imposing prices and assessing additional CIT.
  • Change in capital structure or business model: It needs advice on the tax obligations arising from a capital transfer, asset transfer, or corporate restructuring.
  • Several years of operation without a proper tax finalization review: It is not certain that prior periods were fully compliant and needs a Tax Health Check to address risks proactively before an inspection decision is issued.

Explore Vina TPT’s Tax Consultant Support Services

4. What to Look for When Choosing a Tax Consultant in Vietnam

When selecting a tax compliance Vietnam partner, the Board of Directors should assess the following practical capability criteria:

  • Hands-on experience with FDI clients: A deep understanding of the relationship between VAS and IFRS, a firm grasp of Vietnamese tax regulations, and familiarity with the reporting culture of multinational groups.
  • Valid practicing certificates: Both the firm and its staff must hold the Certificate of Practice in Tax Procedure Services and the Accountant / Chief Accountant certificate as required by law.
  • Multi-level quality control (QC): Accounting data and tax returns must pass through at least two to three review layers (Specialist → Team Leader → Chief Accountant / Tax Director) before official filing.
  • Multilingual communication and reporting: The ability to advise and prepare management reports clearly in English and Vietnamese, enabling Headquarters to monitor compliance with ease.
  • Transparent service contract: A clear scope among monthly filing work, in-depth advisory, inspection support, and Transfer Pricing documentation.
  • Integrated payroll and accounting: Seamless connection between payroll processing and tax filing so that financial data remains consistent and no discrepancies arise at year-end finalization.

5. How Vina TPT Works as a Tax Consultant for FDI Companies

As a specialist advisory firm in finance, accounting, and tax for foreign-invested enterprises in Vietnam, Vina TPT delivers a two-layer tax advisory solution that helps companies optimize costs and control risk comprehensively.

The service areas Vina TPT implements for FDI companies include:

  • Recurring work: Full-package filing of VAT, CIT, PIT, and FCT; review of the legality of incoming documents; bookkeeping under VAS; payroll administration; and provision of a Chief Accountant.
  • Specialized work: Preparation of VAT refund dossiers; Tax Health Checks of prior-year books; preparation of inspection files and direct liaison during a tax inspection; and related-party transaction advisory and documentation.

Is your FDI company looking to review its current tax obligations in full, or do you need a reputable tax advisory partner for the long term? Contact Vina TPT today for a consultation on the most suitable service package – accurate, optimized, and free of unnecessary extra costs.

what-does-a-tax-consultant-in-vietnam-actually-do

BOOK A FREE CONSULTATION

Documents Required (IRC-ERC) for Vietnam Company Registration

documents-required-for-vietnam-company-registration

documents-required-for-vietnam-company-registration

Incomplete dossiers or documents that have not been properly notarized, translated, or consular-legalized are a common reason why Vietnam company registration is delayed or has to be resubmitted. Many foreign investors prepare only part of the paperwork, submit the application, and then receive a request for supplementary documents because the passport, bank statements, or parent company charter do not yet meet Vietnam’s requirements.

To register a foreign-invested company, investors typically need two closely linked dossiers: the application for the Investment Registration Certificate (IRC) and the application for the Enterprise Registration Certificate (ERC). This article separates the checklist for individual investors and corporate investors, helping you prepare the correct documents from the outset.

1. Overview of Vietnam Company Registration Documents

In the Vietnam company registration process, the IRC dossier is used to substantiate the investment project: who the investor is, how much capital will be contributed, where the project will be implemented, and whether the business lines are permitted. The ERC dossier is used to establish the legal entity: the company name, charter capital, legal representative, and registered office address.

Several principles apply to both dossiers:

  • Copies generally need to be notarized.
  • Foreign-language documents require a notarized Vietnamese translation.
  • Many documents issued by a foreign organization must be consular-legalized before they can be used in Vietnam.
  • Information across the entire dossier must be consistent: investor name, passport number, registered capital, and registered office address.

2. Documents Required from Individual Foreign Investors

Individual investors usually have a slimmer dossier than a parent company, but financial capacity evidence and registered office documents still need to be prepared accurately for Vietnam company registration.

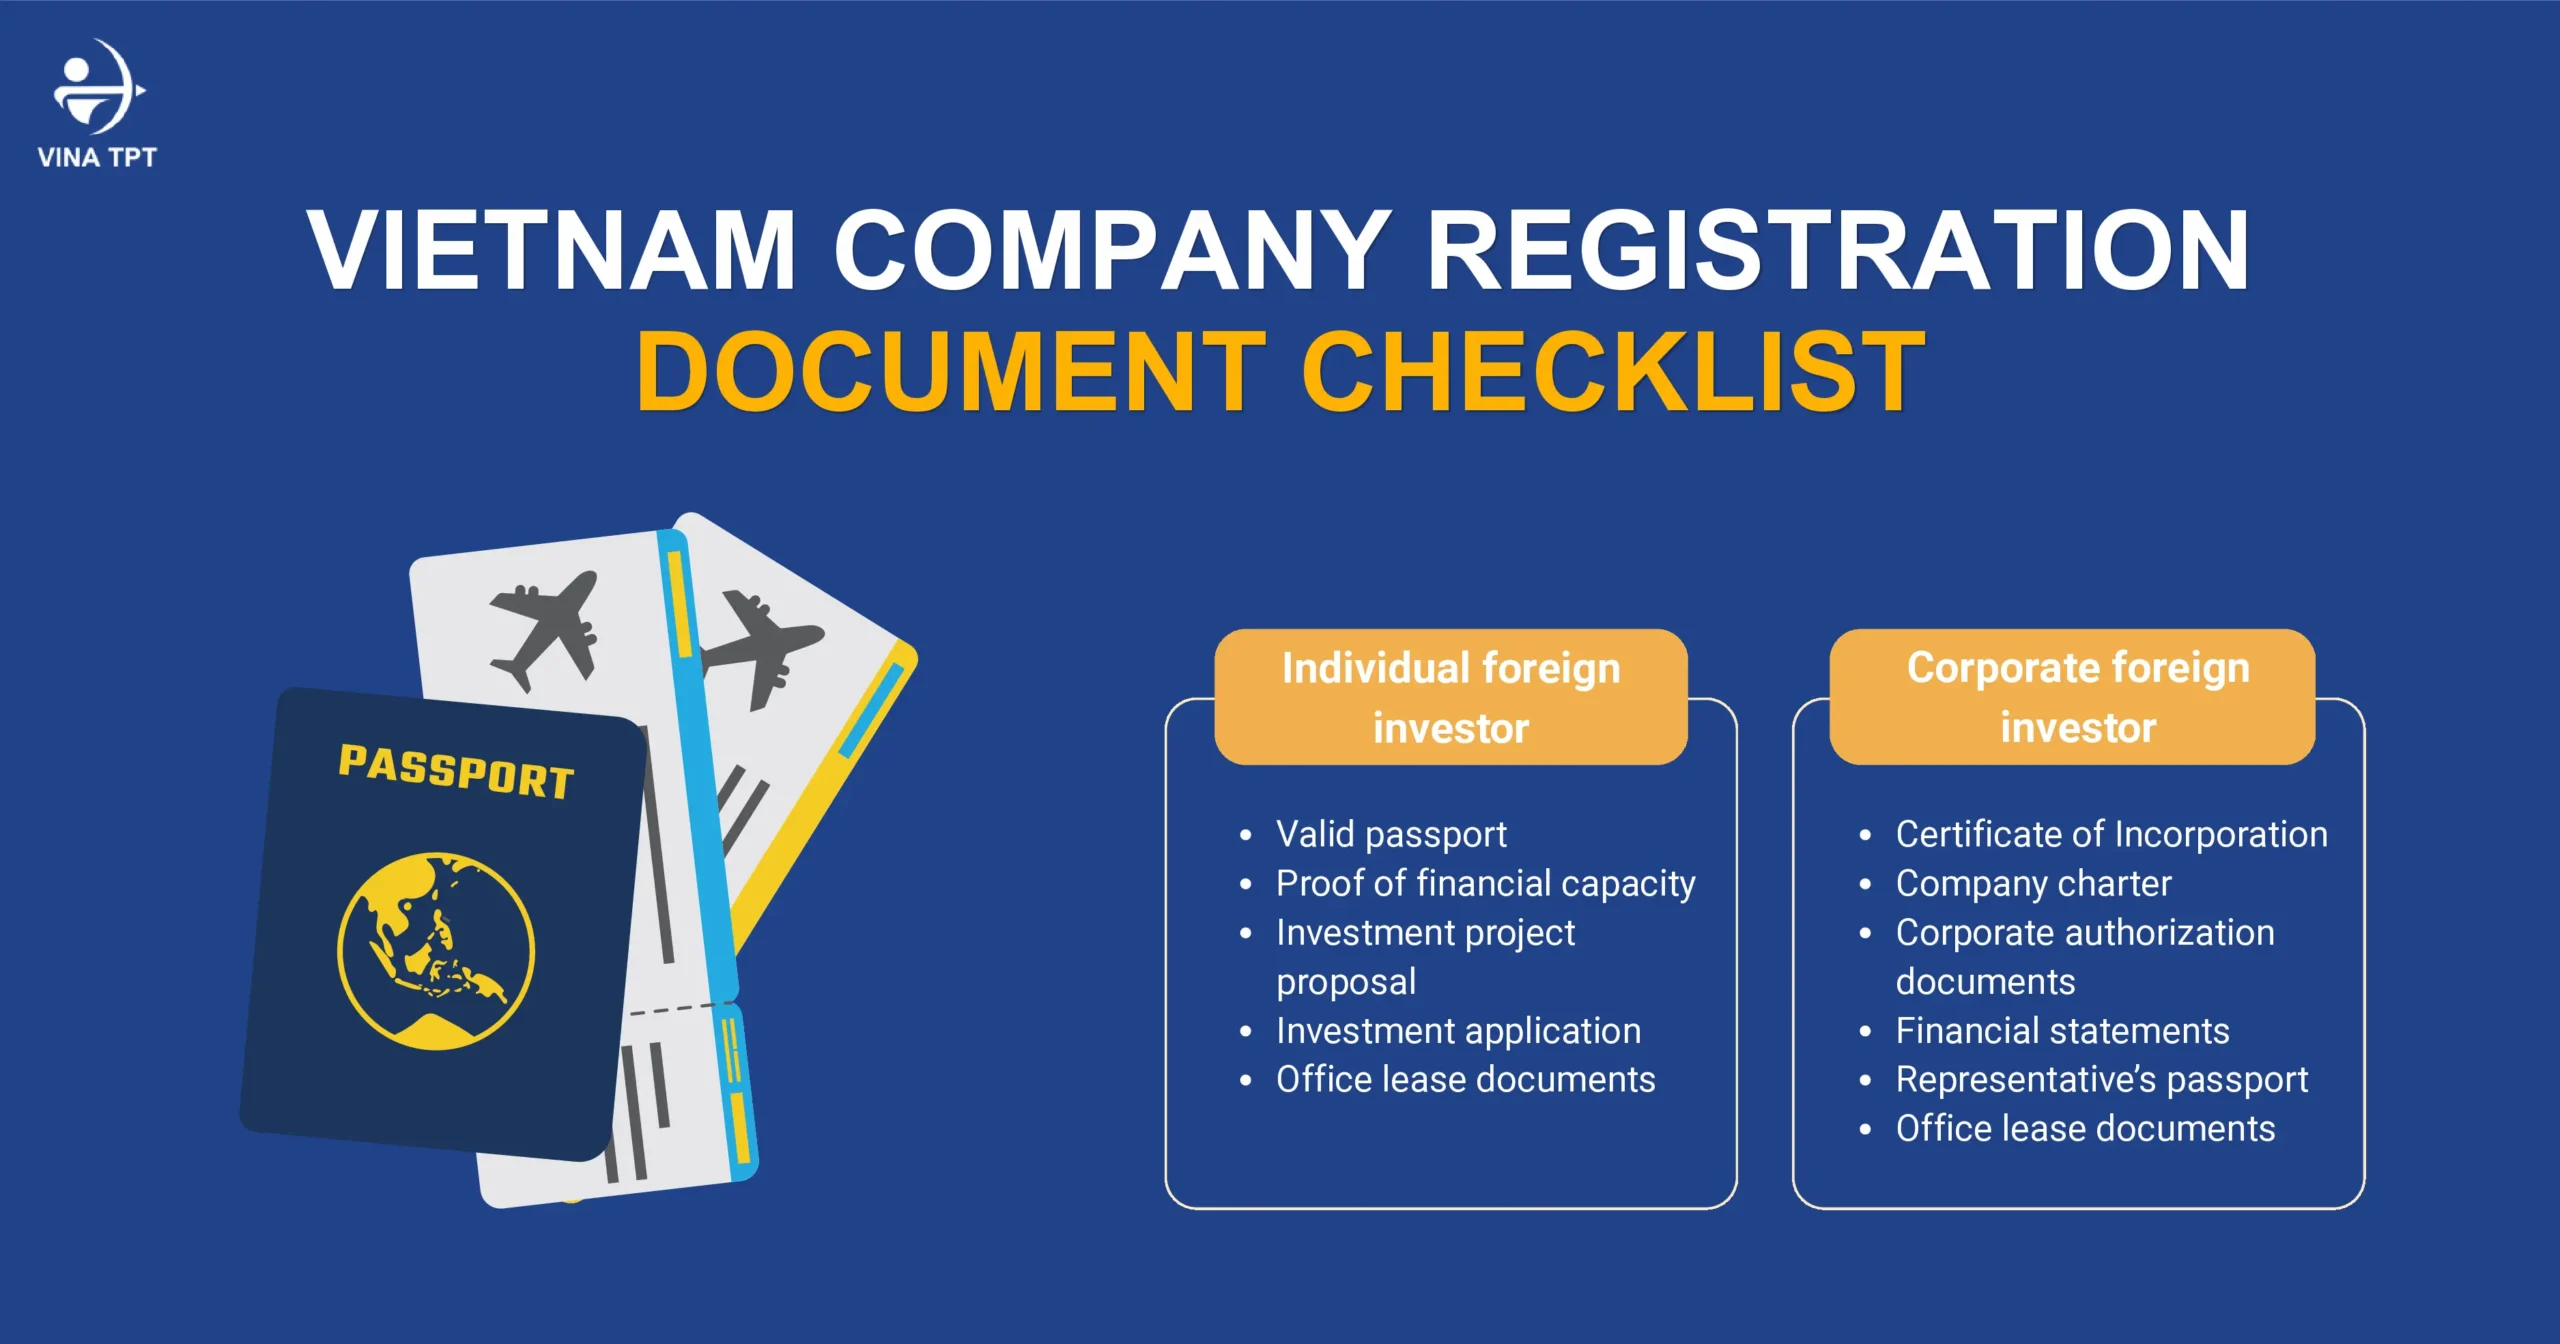
Common IRC ERC required documents for individual investors include:

  • A valid passport (notarized copy; consular legalization of an individual passport is not always mandatory and depends on the receiving authority’s requirements)
  • A bank balance confirmation or savings book in the investor’s name to prove financial capacity
  • An investment project proposal covering the objectives, capital, location, implementation schedule, and socio-economic benefits
  • A written request to implement the investment project
  • A lease agreement for the registered office or documents proving the right to use the premises

The bank balance should be commensurate with the registered scale and business lines. If the balance is too low relative to the intended sector, the receiving authority often requests additional explanations.

documents-required-for-vietnam-company-registration

3. Documents Required from Corporate Foreign Investors

When the investor is a foreign organization, the dossier is more extensive because Vietnamese authorities need to verify the legal status of the parent company.

Important note: the foreign investor must be a company. A private enterprise, household business, or any form that is not a corporate legal entity is generally not accepted as an organizational investor.

Typical documents include:

  • Certificate of Incorporation of the parent company
  • The charter or equivalent constitutional documents
  • A list of members/the Board of Directors and the person authorized to sign the dossier
  • Financial statements for the last two years, preferably audited
  • A financial commitment letter from the parent company or a credit institution (if required)
  • Passport of the person authorized to sign the dossier
  • A lease agreement for the premises in Vietnam

For Vietnam company registration, most documents issued abroad must be consular-legalized and accompanied by a notarized Vietnamese translation. Missing the legalization step is one of the most common reasons why corporate dossiers are delayed.

4. Additional Documents Often Requested During Vietnam Company Registration

Even when the main dossier is already fairly complete, the licensing authority may still request additional documents.

Documents commonly required as supplements include:

  • A technology explanation, if the project is subject to technology appraisal
  • Documents related to conditional business lines
  • A power of attorney authorizing a consulting firm to submit the dossier
  • Information on the person in charge of accounting or the Chief Accountant

The registration authority typically requests further explanations when the registered capital is low relative to the business lines, the registered office address is unclear, or the lease agreement does not yet qualify as a business registration address. Preparing these points in advance can make the Vietnam company registration process smoother and reduce the number of times the dossier has to be supplemented.

Explore Vina TPT’s FDI Company Registration Services

5. Common Document Mistakes That Delay Registration

In practice, the Vietnam company registration process often faces administrative obstacles that stem from avoidable mistakes in document preparation. Below is a detailed analysis of the most common errors that cause a dossier to be rejected or returned for repeated revisions:

  • Missing consular legalization or following the wrong process: Many investors only have documents notarized in their home country and overlook the certification stamp of the Vietnamese Embassy or Consulate. In some cases, legalization is completed by the wrong competent authority, rendering the documents legally invalid in Vietnam.
  • Notarized translations that do not match the original: Inconsistent translation of technical terms, company proper names, or omitted clauses in the parent company’s charter will be identified by the reviewing officer and result in the dossier being returned.
  • Expired bank statements or financial confirmations: Bank balance confirmations or savings books typically remain valid for only 30 to 90 days from the date of issue. Submitting an expired statement leads the registration authority to question the investor’s current financial capacity.
  • A leased registered office that does not qualify for business use: Renting a residential apartment, a condotel unit, or signing a lease for a building that has not been completed or does not have a commercial office function. Once the authority verifies the address, the dossier will be immediately suspended.
  • Inconsistent information across documents: Even a single-character discrepancy in the investor’s name, overseas registered address, passport number, or capital contribution ratio among the lease agreement, charter, investment project proposal, and financial confirmation documents.

6. How Vina TPT Helps Prepare Vietnam Company Registration Documents

Preparing a foreign-invested company registration dossier on your own requires a deep understanding of the Law on Investment, the Law on Enterprises, and the consular legalization rules. Vina TPT provides a full-package consulting and dossier completion solution that helps investors save both time and cost:

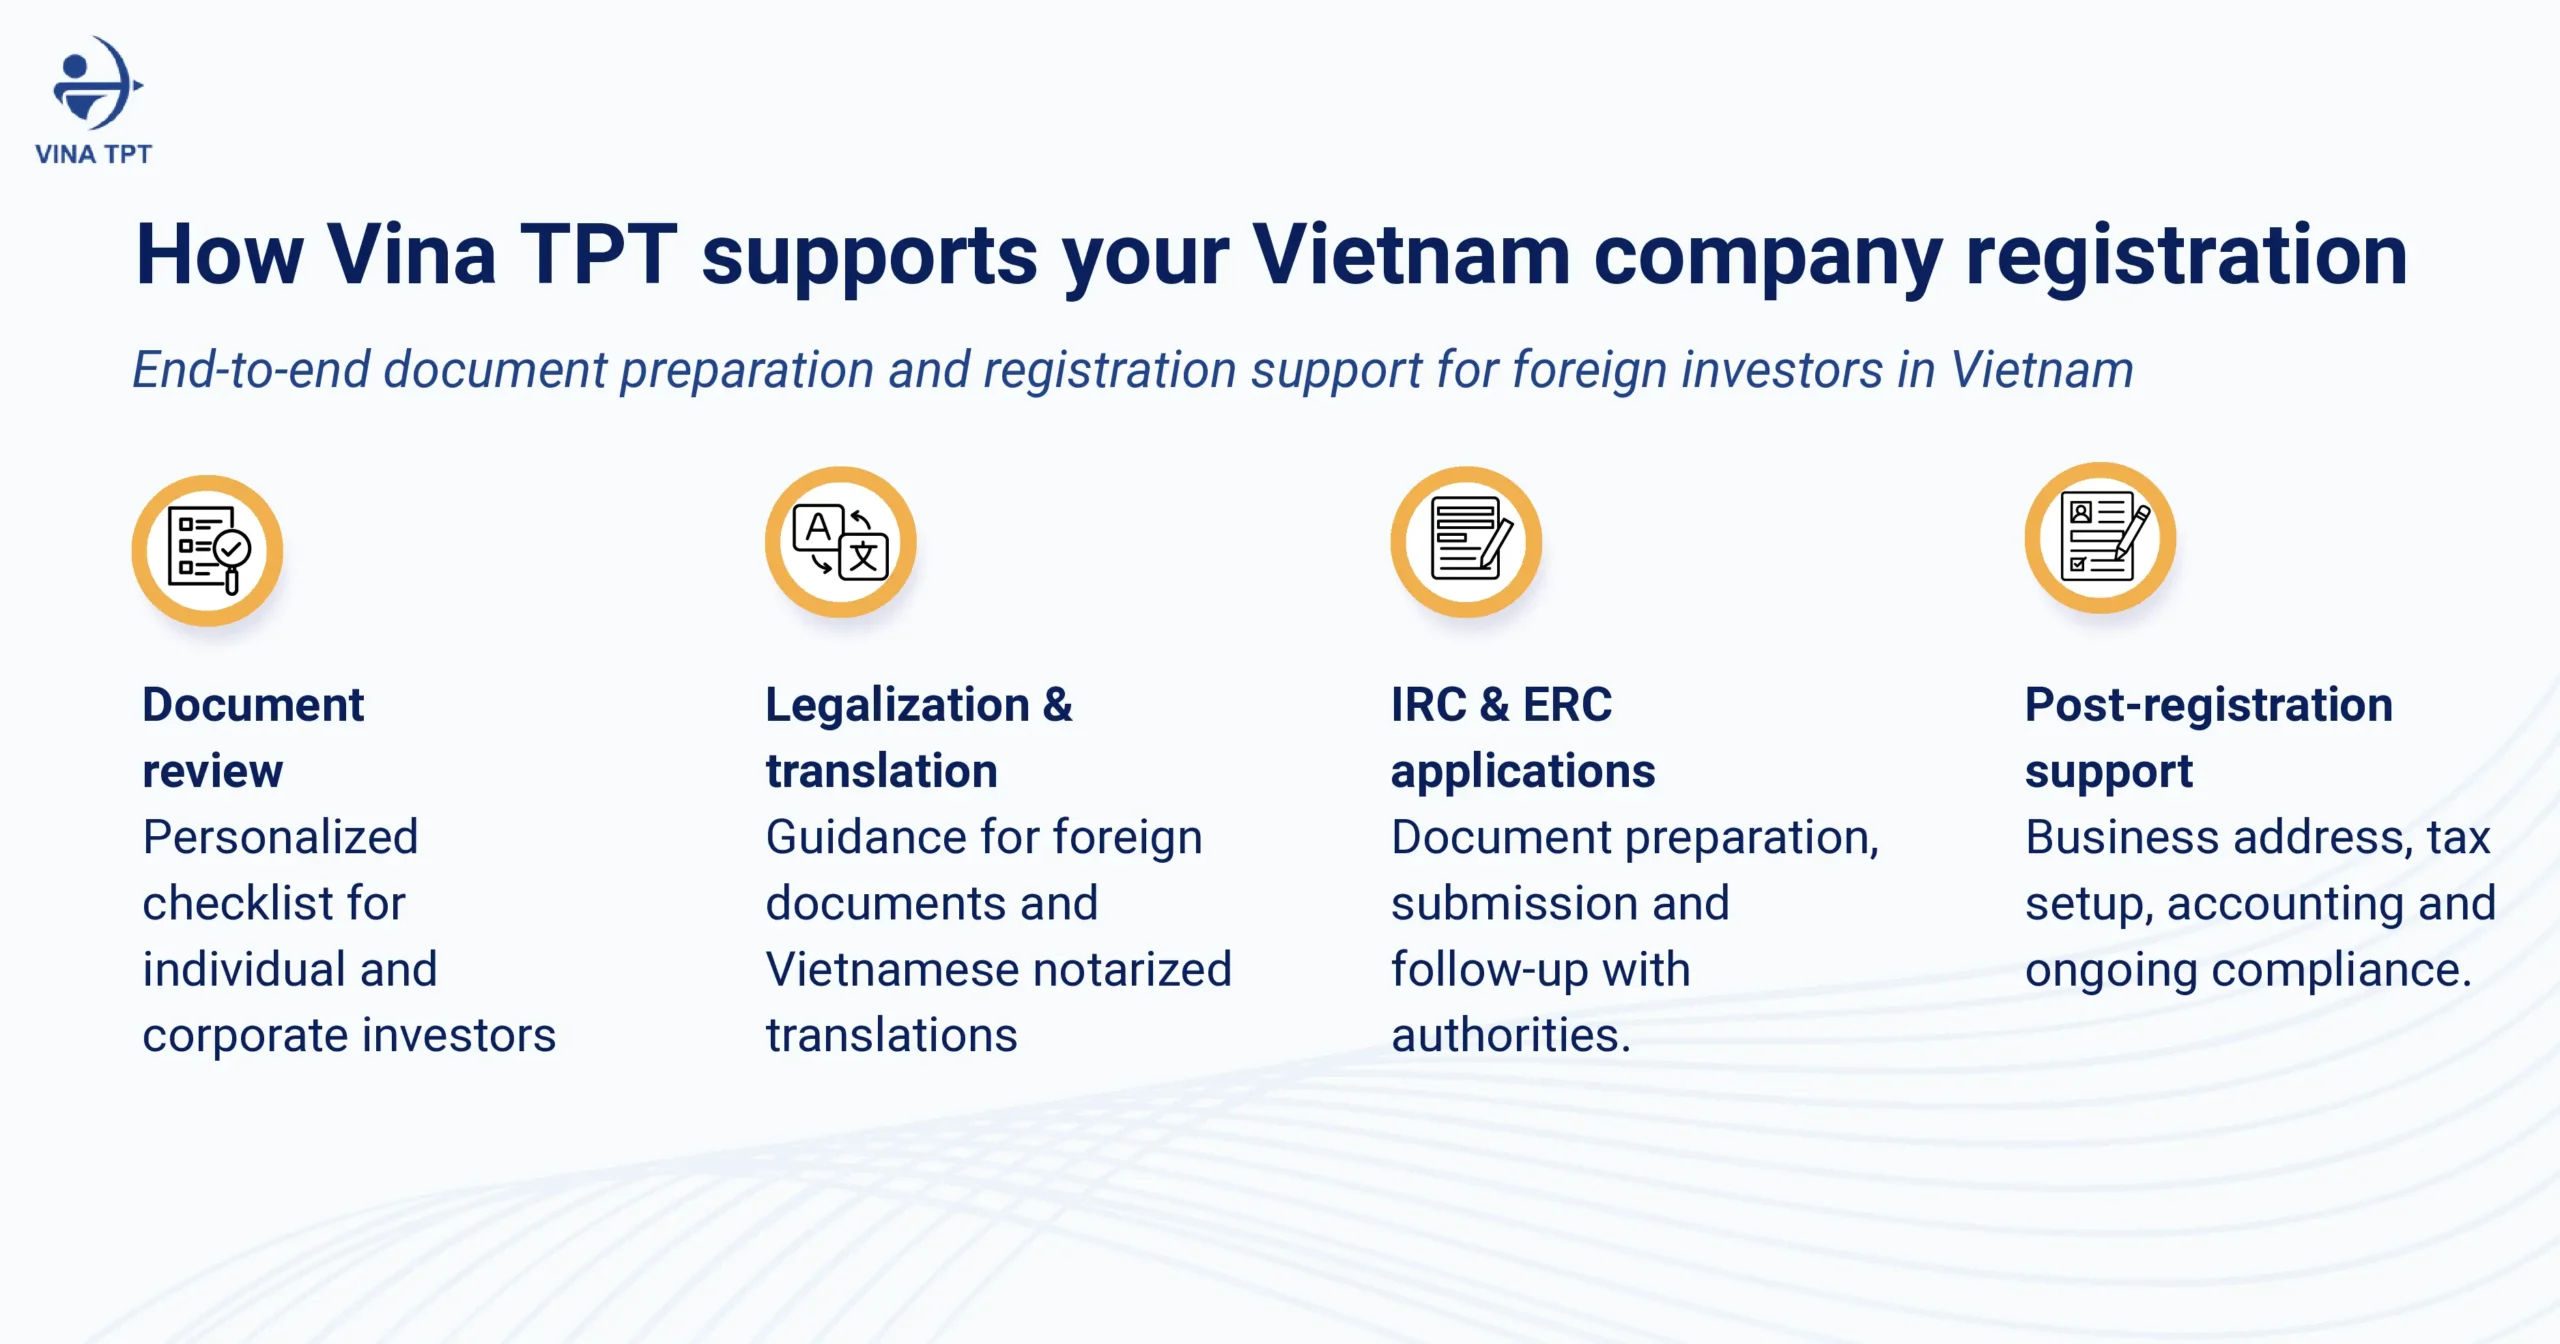
  • Personalized review and checklist: We analyze the project scale and investor structure (individual or organization) to build a document list that is 100% accurate, avoiding both missing and unnecessary paperwork.
  • Consular legalization guidance and professional translation: We provide detailed guidance on the legalization process in each home country and prepare notarized Vietnamese translations that accurately reflect legal and economic terminology.
  • Drafting of the Investment Project Proposal and the IRC–ERC dossier: We prepare an optimized Investment Project Proposal on the investor’s behalf, with a clear justification of economic efficiency, labor utilization, and the capital disbursement schedule.
  • Dossier submission and liaison with state authorities: We submit the application to the Department of Finance or the Industrial Park Management Board, closely monitor the processing timeline, and proactively handle any issues that arise.
  • Legal registered office solution: We support the lease of a business registration address (Shared Office) with a complete set of legal documents that fully meets the authority’s premises inspection requirements.
  • Post-establishment compliance support: We assist with opening a Direct Investment Capital Account (DICA), completing initial tax registration, and preparing periodic investment reports so the company can operate smoothly immediately after licensing.

If you are preparing for Vietnam company registration and want to minimize the risk of a returned dossier or repeated resubmissions, contact Vina TPT today to receive a standardized document checklist and a free legal consultation before filing.

BOOK A FREE CONSULTATION

documents-required-for-vietnam-company-registration

Shared Office Ho Chi Minh City – Vina TPT Workspace for Foreign Companies

Shared-Office-Ho-Chi-Minh-City-Vina-TPT-Workspace-for-Foreign-Companies

Shared-Office-Ho-Chi-Minh-City-Vina-TPT-Workspace-for-Foreign-Companies

Are you looking for a shared office Ho Chi Minh City model that offers a strategic transportation location, integrates modern operational facilities, and fully meets 100% of the legal requirements for a business registration address?

Vina TPT Shared Office in the center of Ho Chi Minh City delivers a comprehensive and professional workspace solution, designed to the highest standards to precisely meet the stringent requirements of foreign-invested companies (FDI), international representative offices, and dynamic startups. We invite you to explore the actual working experience here and select the most suitable space model for your enterprise’s development roadmap.

1. Prime Location in the Heart of Ho Chi Minh City

An ideal workspace not only provides comfort for employees but also serves as an important catalyst that elevates the brand image in the eyes of business partners.

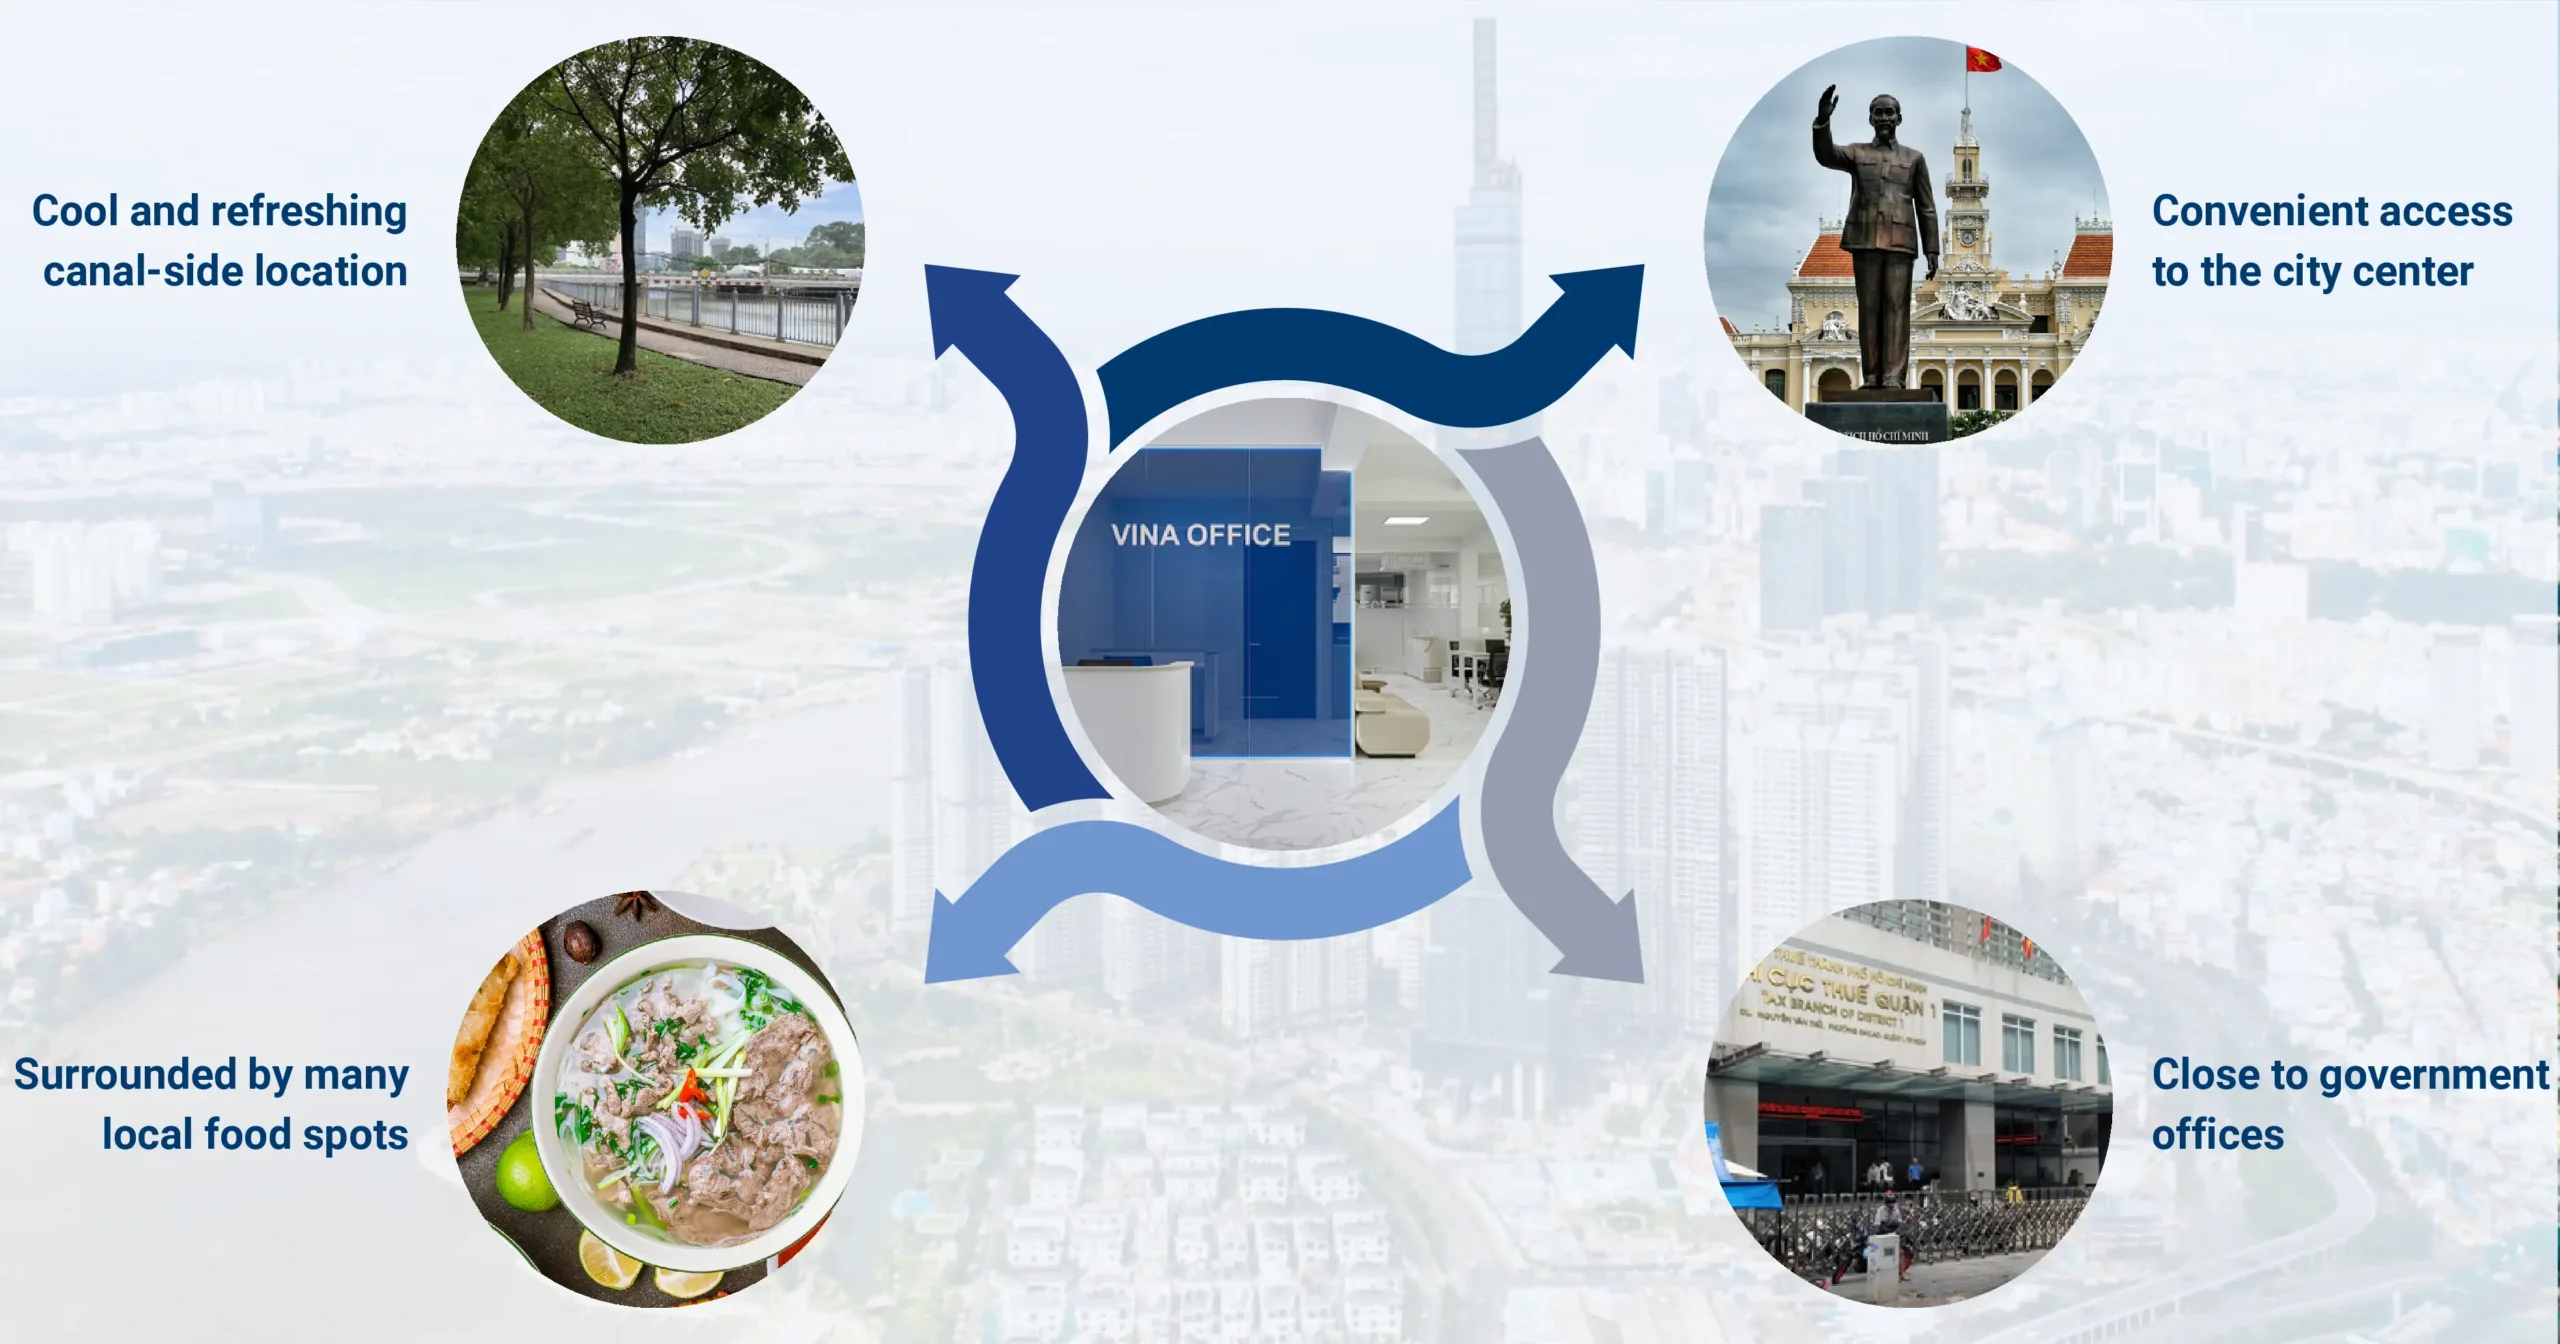
  • Prestigious Commercial Address: 5th Floor, Building 75/18-20-22 Hoang Sa Street, Saigon Ward, Ho Chi Minh City.
  • Flexible Connectivity: Located along the green Hoang Sa Canal, the space offers a quiet and airy atmosphere while still ensuring instant connectivity to key administrative and financial centers such as District 1, District 3, and Binh Thanh area.

This location enables the team to move easily, significantly reduces daily commuting time, and creates an extremely professional and polished first impression during meetings with clients and international partners.

Shared-Office-Ho-Chi-Minh-City-Vina-TPT-Workspace-for-Foreign-Companies

2. Flexible Workspace Options: Dedicated Desk & Private Office

Understanding the flexible nature of headcount among foreign enterprises when first entering the market, Vina TPT Shared Office provides two optimally designed space models:

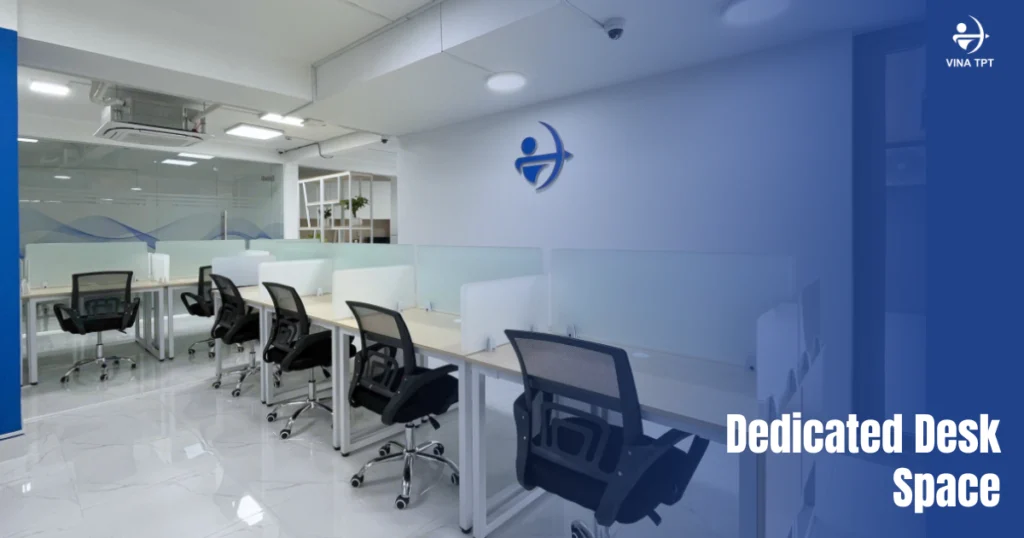
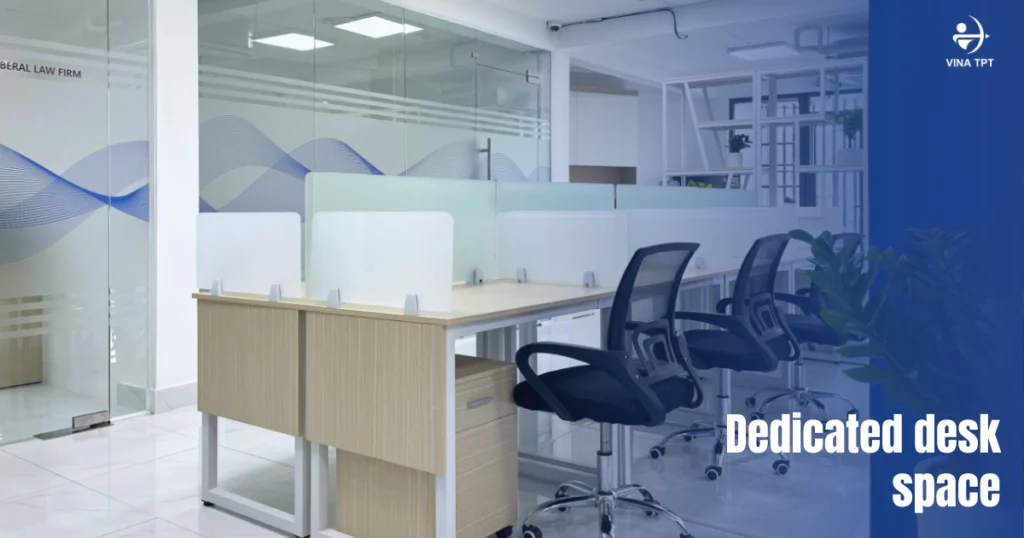
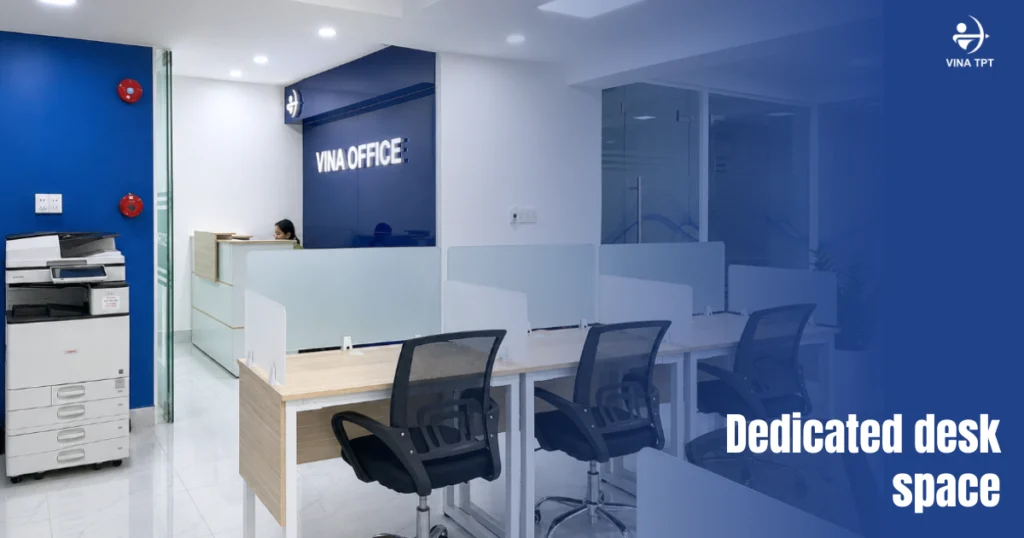
  • Dedicated Desk: A fixed individual workstation within a high-end shared space. This is the perfect choice for independent professionals, individual entrepreneurs, or lean teams of 1 to 3 people who need a focused, professional environment with full amenities.
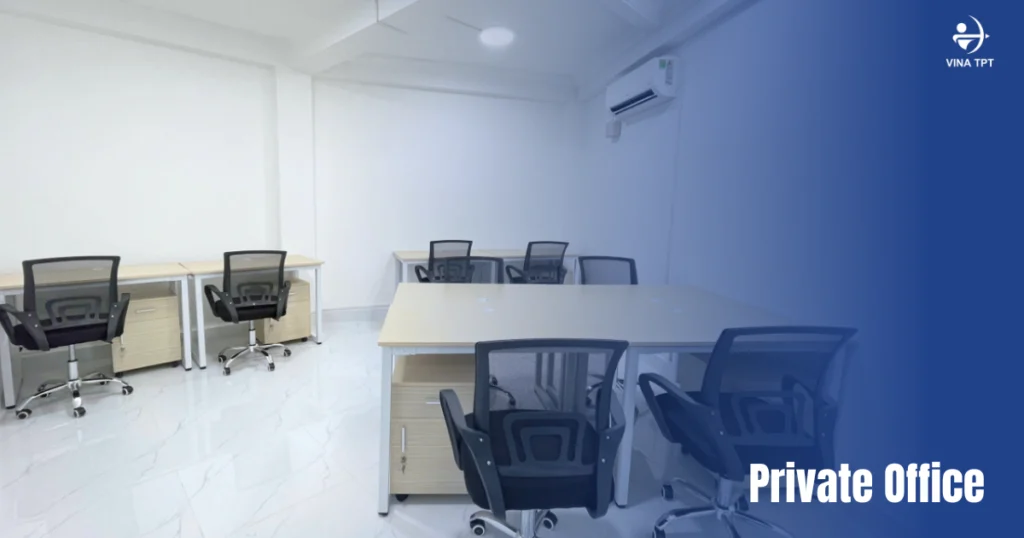
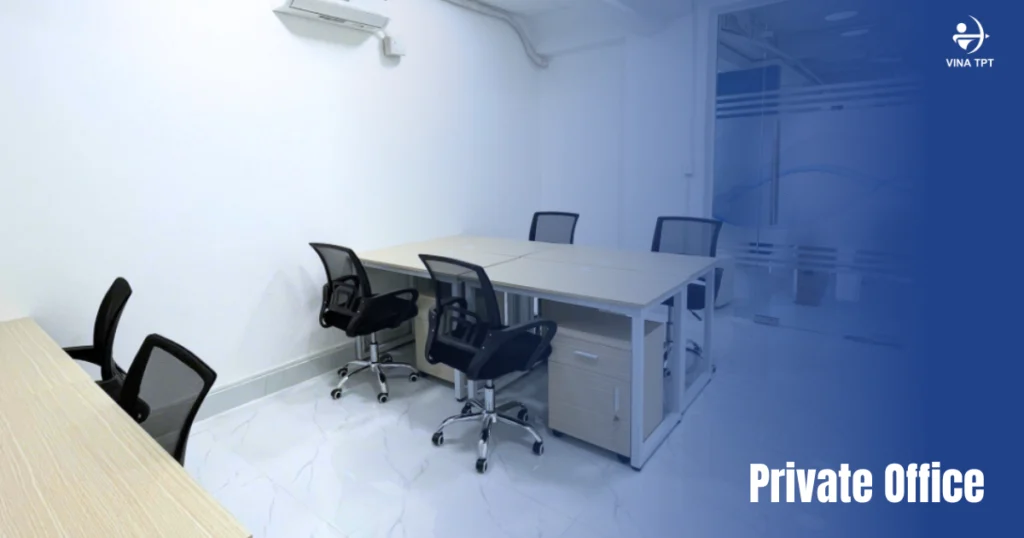
  • Private Office: Fully equipped private workspaces with 6 to 8 seats, featuring individual locking systems that ensure absolute information security. This model is specifically designed for FDI enterprises or branch offices that require a quiet internal discussion space and frequent client meetings.

The outstanding advantage of this model lies in its seamless scalability. Enterprises can start with a dedicated desk and easily upgrade to a private office within the same building as the team grows, ensuring continuity of operations without any disruption.

3. Fully Equipped Amenities for Daily Operations

All operational amenities at Vina TPT shared office Ho Chi Minh City are packaged into a transparent monthly fee, helping enterprises manage their budget clearly and completely eliminate hidden costs:

  • High-End Technical Infrastructure: Dedicated high-speed fiber optic internet, free lighting and air-conditioning systems.
  • Multilingual Reception Team: Professional receptionists who represent the enterprise in welcoming clients and handling daily correspondence and administrative parcels.
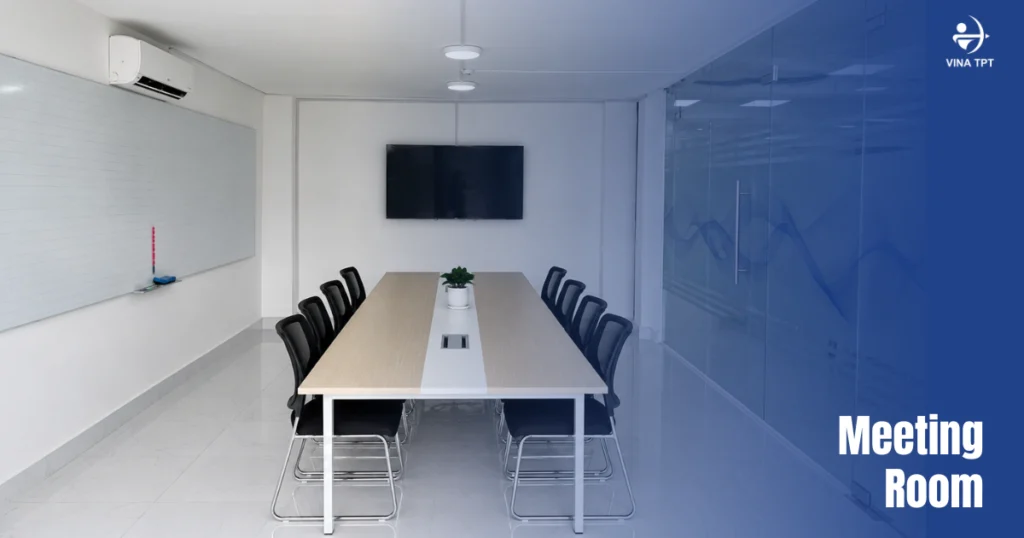
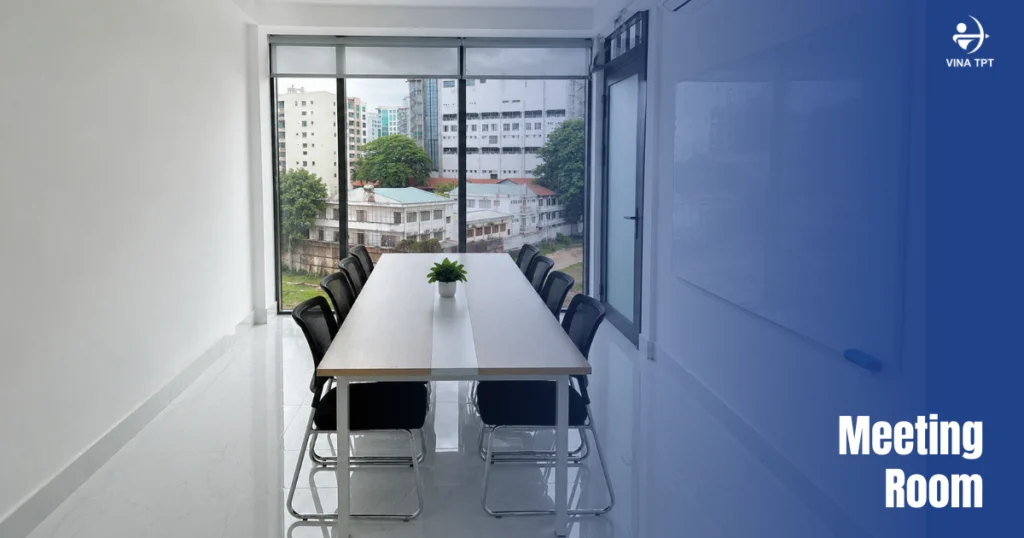
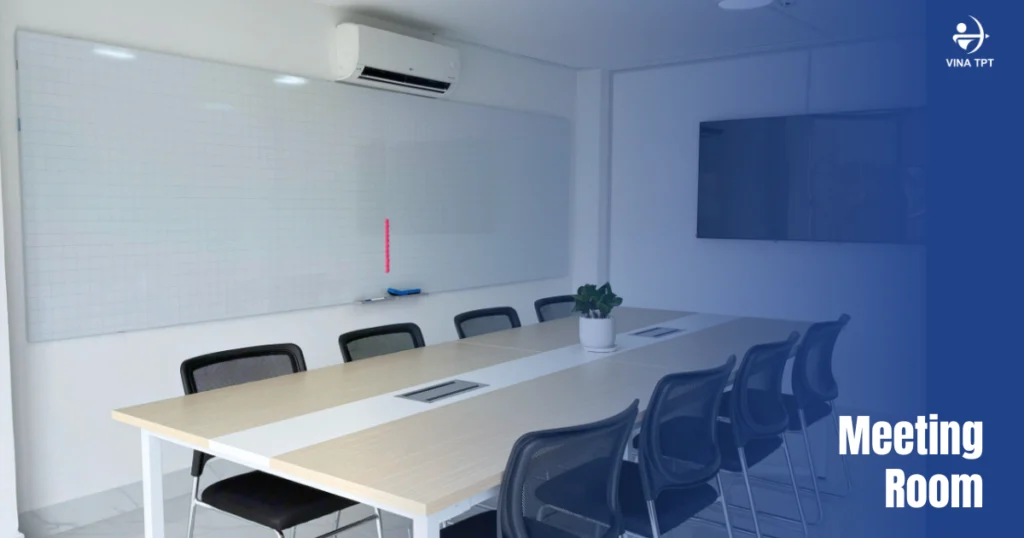
  • Integrated Meeting Room System: Elegant meeting rooms with a capacity of up to 15 people, fully equipped with presentation screens, whiteboards, and online conferencing devices.
  • Printing & Document Processing: High-capacity multifunction printers and scanners available in the shared area.
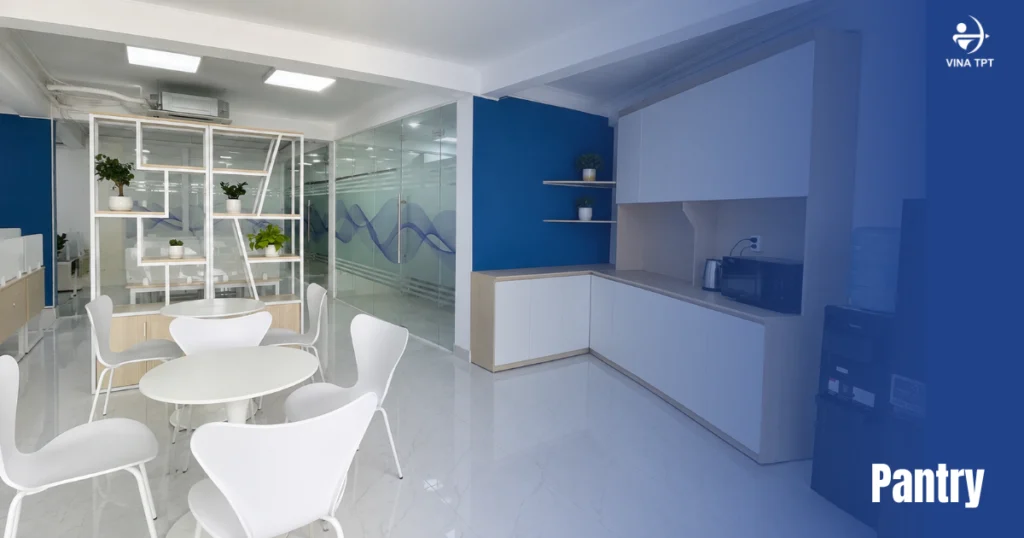
  • Pantry & Relaxation Zone: Complimentary high-quality tea and coffee, equipped with a refrigerator, microwave, and a refined lounge area for receiving guests.
  • Security & Parking: 24/7 security control system and convenient parking areas for motorcycles and cars for both employees and visitors.
  • Legal Business Registration Address: Provision of a complete set of premises documents to support ERC, IRC licensing procedures and tax registration.


4. More Than Just a Shared Office – Complete Business Support

The greatest difference of Vina TPT Shared Office compared to pure office rental providers on the market is its deep integration within a full-package corporate service ecosystem.

When operating here, international investors not only secure an ideal workspace but also receive continuous legal and financial support:

  • Company Establishment Consulting: Full-package support for obtaining the Investment Registration Certificate (IRC) and the Enterprise Registration Certificate (ERC).
  • Accounting – Tax – Payroll Services: Expert teams directly handle tax declarations, prepare financial statements, manage payroll, and process social insurance for employees.
  • Ensuring Legal Compliance: Consulting and representation of the enterprise in dealings with state management authorities, including support for Work Permit and Temporary Residence Card (TRC) procedures for foreign personnel.

The strategic benefit for investors is the ability to work with a single partner for the entire office infrastructure and operational procedures, optimizing management costs and completely eliminating risks that arise from coordinating with multiple separate third parties.

5. Who Is Vina TPT Shared Office Suitable For?

The shared office Ho Chi Minh City model of Vina TPT is specifically tailored to optimally serve the following groups of enterprises:

  • Foreign direct investment (FDI) companies newly entering the Vietnamese market that need a legal headquarters to carry out IRC and ERC licensing procedures.
  • Startups and small-to-medium enterprises (SMEs) seeking a flexible space solution to minimize initial capital expenditure (CAPEX).
  • International corporations that need to establish a representative office or short-term project team in Ho Chi Minh City within a secure and professional private office space.
  • Organizations looking for a fully integrated service solution that perfectly combines shared office space with professional accounting–tax and human resource–payroll management systems.

Contact Vina TPT today for a free consultation, to schedule an on-site visit of the Private Office & Dedicated Desk spaces, and to receive the most preferential quotation.

BOOK A FREE CONSULTATION

VAT Rate in Vietnam: Complete Guide to Value Added Tax Regulations

VAT Rate in Vietnam: Complete Guide to Value Added Tax Regulations

VAT Rate in Vietnam: Complete Guide to Value Added Tax Regulations

In corporate governance and financial compliance activities in Vietnam, accurately determining the VAT rate is not only a mandatory legal requirement but also a factor that directly influences pricing strategy, tax declaration efficiency, and cash flow circulation. Especially for foreign direct investment (FDI) enterprises, this tax requires the highest level of caution to minimize the risk of tax recovery or administrative penalties during operations.

Value Added Tax (VAT), or value added tax, is an important indirect tax that makes a major contribution to the state budget. It is calculated on the added value of goods and services arising throughout the entire process from production and distribution to consumption. To help enterprises gain a comprehensive understanding, this article compiles the latest regulations on the VAT rate Vietnam, provides a detailed analysis of the applicable tax rates in 2026, policy exemption and reduction cases, as well as core notes to help foreign investors ensure absolute legal compliance.

1. What is Value Added Tax (VAT) in Vietnam?

According to the Law on Value Added Tax of Vietnam, value added tax Vietnam is a tax applied to most types of goods and services used for production, business, and consumption purposes within the territory of Vietnam. The taxable objects cover a wide range, from domestic consumer goods to commercial services, excluding those items listed as non-taxable under specific provisions of the law.

Taxable subjects are defined as all organizations and individuals engaged in the production or trading of goods and services subject to VAT, or entities that import goods from abroad into Vietnam. From an economic management perspective, VAT not only ensures a stable and sustainable source of revenue for the national budget but also creates a transparent financial management mechanism through the invoice and supporting document system. A clear understanding of the nature of VAT will help foreign managers become more proactive in optimizing input costs and establishing standard compliance processes.

2. Current VAT Rates in Vietnam

The legal framework on the VAT rate Vietnam in 2026 categorizes goods and services into specialized tax rate groups in order to regulate the economy and support social welfare. The current system consists of three main tax rates along with a non-taxable group.

2.1. Standard Tax Rate of 10% and the Temporary Reduction Policy to 8% until the End of 2026

The 10% tax rate applies to most ordinary goods and services that fall outside preferential or export categories. However, to continue stimulating domestic consumption and supporting enterprises in production recovery, the Government has approved a temporary reduction of the VAT rate from 10% to 8%, which remains effective until 31 December 2026.

Enterprises should note that this 8% reduction policy does not apply universally across all sectors. Certain groups of goods and services are still required to apply the standard 10% rate, including:

  • Telecommunications services, financial activities, banking, securities, and insurance.
  • Real estate business and products from metals or mining products (excluding coal).
  • Goods subject to Special Consumption Tax (SCT) such as alcohol, beer, tobacco, and automobiles with fewer than 24 seats.

VAT Rate

Main Scope of Application

Practical Examples

8% (Until 31/12/2026) Ordinary consumer goods and services normally subject to 10% that are eligible for reduction. Consumer goods, food & beverage services, domestic logistics, processing manufacturing.
10% (Standard) Specific sectors not eligible for the VAT reduction. Telecommunications, banking, real estate, goods subject to Special Consumption Tax.
5% Essential goods and services, agriculture, healthcare, and education. Clean water, medical equipment, medicines, fertilizers, social housing.
0% Goods and services exported abroad or to non-tariff zones. Exported goods, international transportation, services provided to foreign partners.

2.2. Goods and Services Subject to 5% VAT Rate

The 5% tax rate is a preferential policy of the State applicable to groups of essential goods and services that serve people’s livelihoods, agricultural development, and social infrastructure. Common groups include:

Clean water used for production and daily living purposes (excluding bottled or containerized drinking water). Fertilizers, plant protection products, plant and animal growth stimulants. Medicines, vaccines, medical biological products, and specialized medical equipment and instruments. Teaching aids, educational materials, and specialized books. Certain agricultural, forestry, and aquatic products that have not been processed or have only undergone ordinary preliminary processing at the commercial trading stage, as well as social housing sale and lease projects as prescribed.

VAT Rate in Vietnam: Complete Guide to Value Added Tax Regulations

2.3. 0% VAT Rate and Exempt Cases

The 0% tax rate is designed to encourage export activities and enhance the competitiveness of Vietnamese products in the international market. The scope of application of the 0% rate includes goods exported abroad, goods sold into non-tariff zones for export production, international transportation services, and services provided directly to organizations and individuals overseas.

In addition, the law also specifies a list of VAT-exempt objects, such as self-produced agricultural products sold by the producers themselves, transfer of land use rights, credit services, securities, life insurance, and public healthcare and education services.

Core distinction between “0% Tax Rate” and “VAT-Exempt”:

  • 0% Tax Rate: The enterprise remains within the scope of VAT, and is therefore entitled to deduct and fully refund all input VAT paid on related production and business costs.
  • VAT-Exempt: The enterprise does not charge output VAT, but at the same time is not entitled to deduct or refund input VAT. This input tax must be included in production and business costs or the original cost of assets.

3. Key Compliance Requirements Related to VAT Rate

To maintain legal compliance and optimize the amount of deductible tax, enterprises must strictly comply with the current tax administration regulations:

Enterprises must fulfill their VAT declaration and payment obligations on a monthly or quarterly basis, depending on the total revenue of the immediately preceding year (enterprises with annual revenue of VND 50 billion or more are required to declare monthly). To be eligible for input VAT deduction, the enterprise must fully meet three mandatory conditions: possession of a valid VAT invoice; non-cash payment documents for invoices valued at VND 5 million or more (including tax); and the purchased goods or services must be used directly for the production or trading of goods and services subject to VAT.

In addition, the use of electronic invoices (with or without the tax authority’s code) is 100% mandatory. If an enterprise applies an incorrect VAT rate (for example, issuing an invoice at 8% for goods subject to the 10% rate), the enterprise will not only have to pay the underpaid tax and late payment interest but will also face serious administrative tax penalties.

EXPLORE TAX FILLING SERVICES

4. Practical Tips for Foreign Companies

To minimize financial errors when operating a business in Vietnam, foreign managers should keep the following practical experiences in mind:

Establish a process to accurately check and classify the enterprise’s goods and service categories right from the input stage. Because the 8% tax reduction policy contains many complex exceptions, the accounting department must carefully cross-check the economic industry codes and HS codes of the products to apply the correct tax rate.

Systematically store and organize all electronic invoices together with bank payment documents. This is the only legal basis that enables the enterprise to protect its rights to input VAT deduction and refund when the competent authorities conduct tax inspections or audits.

Proactively carry out periodic internal tax reviews (tax audits) of the tax declaration process to detect and correct errors in a timely manner before the Tax Authorities issue an inspection decision. In cases where the internal team does not have a deep understanding of the local tax legal system, the enterprise should consider cooperating with professional tax agency firms to ensure operational safety.

VAT Rate in Vietnam: Complete Guide to Value Added Tax Regulations

5. How Vina TPT Supports VAT Compliance

As a reputable firm specializing in financial consulting and tax compliance for FDI enterprises, Vina TPT provides comprehensive support solutions that help businesses optimize their VAT processes:

  • Tax Rate Consulting & Classification: Accurate assessment of product categories and advice on applying the correct VAT rate (clearly distinguishing between the 8%, 10%, 5%, and 0% groups).
  • Periodic Tax Declaration & Reporting: Preparation and submission of accurate monthly/quarterly VAT declarations in full compliance with statutory deadlines.
  • Input Deduction Review & Tax Refund Services: Appraisal of input invoice dossiers and representation of the enterprise in carrying out VAT refund procedures for investment projects and export activities.
  • Support During Tax Inspections: Direct explanation, protection of data, and safeguarding of the enterprise’s legitimate rights before the tax management authorities.

Conclusion

In summary, mastering the regulations on the VAT rate and accurately complying with the VAT declaration process is the golden key that enables FDI enterprises to operate safely, transparently, and sustainably in Vietnam.

Is your enterprise facing difficulties in determining the correct VAT rate or in need of professional tax declaration support? Contact Vina TPT today for a free consultation and experience our standard full-package accounting and tax services.

BOOK A FREE CONSULTATION

How to Register a Company in Vietnam: Complete Guide to IRC and ERC for Foreign Investors

How-to-Register-a-Company-in-Vietnam-Complete-Guide-to-IRC-and-ERC-for-Foreign-Investors

How-to-Register-a-Company-in-Vietnam-Complete-Guide-to-IRC-and-ERC-for-Foreign-Investors

For international investors, the decision to register a company in Vietnam is a strategic step toward unlocking the dynamic growth potential of the Southeast Asian market. However, establishing a commercial presence here requires the enterprise to complete two foundational legal procedures: obtaining the Investment Registration Certificate (IRC) and the Enterprise Registration Certificate (ERC). These two documents constitute the highest legal basis confirming the foreign investor’s operational status and project ownership rights.

A thorough understanding of the legal nature of these certificates and accurate dossier preparation from the very first step will help investors minimize appraisal time, avoid administrative obstacles, and bring the project into official operation as quickly as possible. This article provides a comprehensive practical guide covering the process of how to register a company in Vietnam, the mandatory list of documents, implementation timelines, and the most effective cost-optimization solutions.

1. Understanding IRC and ERC to Register Company in Vietnam

Before commencing any legal procedures, investors need to clearly distinguish the specialized roles as well as the interconnected relationship between the two core certificates in Vietnam’s investment legal system.

  • Investment Registration Certificate (IRC) is the Investment Registration Certificate, a mandatory document for most foreign direct investment (FDI) projects. This certificate records detailed information about the investment project, including project objectives, investment capital scale, capital contribution schedule, project location, and related investment incentives. The IRC serves as the “passport” confirming that the foreign project fully meets the conditions for market entry into Vietnam.
  • Enterprise Registration Certificate (ERC) is the Enterprise Registration Certificate, the official document that records the establishment of the company’s legal entity. The ERC contains basic information including the company name, enterprise code (which also serves as the tax identification number), head office address, legal representative, and charter capital. Once the ERC is issued, the enterprise officially acquires independent legal entity status and full rights and obligations under the Law on Enterprises.

Regarding their legal relationship, the IRC ERC Vietnam procedures are closely linked. Normally, the IRC is a prerequisite for the competent authority to issue the ERC. However, under current investment law updates, the process has become more flexible for certain service sectors, allowing optimization of the licensing sequence to help investors shorten the time required to launch business operations.

How-to-Register-a-Company-in-Vietnam-Complete-Guide-to-IRC-and-ERC-for-Foreign-Investors

2. Step-by-Step Process to Register a Company in Vietnam

The standardized process answering the question of how to register a company in Vietnam for foreign investors consists of the following 5 core stages:

Step 1: Industry Survey and Preparation of the Investment Dossier

Before commencing the company establishment procedures, the investor needs to accurately determine the business industry codes according to the Vietnam Standard Industrial Classification (VSIC) and cross-check them against the WTO Commitments Schedule and the Law on Investment to verify market access conditions. Certain sectors classified as conditional business lines will require additional specialized licenses or compliance with standards related to capital, personnel, and facilities. At this stage, the investor is advised to contact a local consulting firm for support in reviewing the industry codes and assessing the project’s feasibility.

After identifying the suitable industry, the investor proceeds to prepare the investment dossier under the guidance of the service provider. Documents of the investor (whether an individual or an organization) must be consular-legalized abroad before being brought to Vietnam for use. The consular legalization process usually takes 14 to 30 days, depending on the procedures of each embassy/consulate and the respective country.

Step 2: Submission of the Application for the Investment Registration Certificate (IRC)

The investment dossier is submitted to the Department of Finance. The competent authority will appraise the market conditions, project location, and the investor’s financial capacity before officially issuing the IRC.

—> Estimated time: 30 – 45 working days.

Step 3: Submission of the Application for the Enterprise Registration Certificate (ERC)

After obtaining the IRC, the enterprise submits the legal entity establishment dossier to apply for the ERC. The business registration authority will appraise the company name, head office address, and governance structure. Once the ERC is completed, the enterprise code is simultaneously created on the National Business Registration Information System.

—> Estimated time: 14 – 20 working days.

Step 4: Opening a Bank Account, Engraving the Company Seal, and Making Capital Contribution

The enterprise proceeds to engrave the legal seal, publish the seal specimen, and open a Direct Investment Capital Account (DICA) at a commercial bank licensed to operate in Vietnam. Under the law, the investor must complete the transfer of the entire committed charter capital into the DICA within a maximum of 90 days from the date the ERC is issued.

—>Implementation time: Within 90 days as prescribed by law.

Step 5: Completion of Tax Registration and Post-Establishment Compliance

The enterprise purchases a digital signature (USB Token), installs the company signboard at the head office, carries out initial tax registration, submits the business license fee declaration, and registers the electronic invoice system. At the same time, the company completes labor registration and social insurance procedures if employees are officially hired, and registers the enterprise electronic identity account (VNeID for enterprises) to facilitate electronic administrative procedures and transactions with state authorities.

—> Estimated time: 7-10 working days.

3. Required Documents to Register Company in Vietnam

The list of documents prepared for the IRC ERC Vietnam process is specifically categorized based on the legal status of the investing entity:

For Individual Investors:

  • A copy of a valid passport (notarized as required).
  • Documents proving financial capacity: Bank account statement or bank balance confirmation letter showing an amount equivalent to or greater than the total expected investment capital.
  • Investment Project Proposal: Clearly stating the objectives, scale, investment capital, capital mobilization plan, and project location.
  • Headquarters location dossier: Office lease agreement and documents proving the lessor’s lawful right to use the premises (Land Use Rights Certificate, building construction permit).

For Organizational / Corporate Investors:

  • A copy of the Enterprise Registration Certificate, Business Extract, or parent company Charter (must be consular-legalized and notarized translation into Vietnamese).
  • Audited financial statements of the parent company for the two most recent years to prove financial capacity.
  • Power of attorney authorizing the representative to manage the capital contribution and a copy of the authorized representative’s passport.
  • Investment Project Proposal and the dossier proving the legality of the head office location in Vietnam.

EXPLORE OUR COMPANY SETUP SERVICE

4. Timeline and Common Challenges When Registering a Company in Vietnam

Although the statutory total time to complete both certificates is approximately 4 to 6 weeks, in practice the process may be faster or take longer depending on the completeness of the dossier and any administrative obstacles that arise:

  • Appraisal of Conditional Business Lines: Sectors such as real estate, education, healthcare, and wholesale/retail of goods often require inter-ministerial consultation, causing the IRC processing time to extend beyond the expected timeline.
  • Unconvincing Financial Dossier: Licensing authorities reject applications due to unclear proof of capital sources or bank balances that do not match the capital contribution schedule registered in the Investment Project Proposal.
  • Delays in Consular Legalization: Documents originating from the investor’s home country are prepared incorrectly, missing the authentication seals of the Ministry of Foreign Affairs or the Vietnamese Embassy/Consulate in the host country.
  • Headquarters Address Issues: The registered address does not meet legal standards, is located in a residential apartment building, or the lessor fails to provide sufficient documents proving the right to operate the premises.

5. Practical Tips to Register Company in Vietnam Smoothly

To ensure the process of registering a company in Vietnam proceeds smoothly while saving time and budget, investors should apply the following practical recommendations:

Optimize dossier preparation by thoroughly reviewing consular-legalized documents right from the home country. Preparing a detailed Investment Project Proposal with clear arguments demonstrating financial capacity will help minimize the risk of repeated requests for supplementary explanations from the competent authorities.

Utilize a legal business registration address solution from reputable shared office models, such as Vina TPT’s shared office. This approach helps the enterprise optimize fixed costs in the initial stage while ensuring a complete set of documents proving lawful use of the premises that meet the standards required for submission with the IRC/ERC dossier.

Partner with a consulting firm that has strong professional expertise in FDI investment advisory. The deep understanding of local procedures possessed by the expert team will help the enterprise shape an optimal legal structure and significantly shorten the dossier processing time.

How-to-Register-a-Company-in-Vietnam-Complete-Guide-to-IRC-and-ERC-for-Foreign-Investors

6. How Vina TPT Helps Foreign Investors Register Company (IRC ERC Vietnam)

With extensive experience supporting hundreds of international investment projects, Vina TPT delivers a full-package solution that helps foreign investors register a company in Vietnam in the safest and most professional manner:

  • Investment Structure & Industry Consulting: Assessment of market access conditions, advice on selecting suitable industry codes, and establishment of an optimal corporate governance model.
  • Full-Package IRC & ERC Dossier Service: Drafting of the entire document list and representation of the investor in direct dealings with the Department of Planning and Investment to obtain the certificates promptly.
  • Legal Business Registration Address Solution: Provision of a prestigious Shared Office service in central Ho Chi Minh City that fully meets 100% of the legal conditions for IRC and ERC licensing as well as bank account opening.
  • Integrated Post-Establishment Ecosystem: Continued support for the enterprise in fulfilling compliance obligations related to Tax, Accounting, Payroll Management, Social Insurance, and Legal Representative services.
  • Multilingual Expert Team: Transparent and direct consulting in English, Vietnamese, Japanese, and Chinese, completely eliminating language barriers for foreign investors.

Conclusion

The process of registering a company in Vietnam through the issuance of the IRC ERC Vietnam certificates is a critical starting milestone that lays a solid foundation for the enterprise’s growth in the Vietnamese market.

Are you looking for a reliable partner to turn your investment and business plans into reality? Contact Vina TPT today for a free consultation and experience comprehensive FDI company establishment services.

BOOK A FREE CONSULTATION

How-to-Register-a-Company-in-Vietnam-Complete-Guide-to-IRC-and-ERC-for-Foreign-Investors

Is a Shared Office a Valid Company Registration Address?

Is-a-Shared-Office-a-Valid-Company-Registration-Address

Is-a-Vina-tPT-Shared-Office-a-Valid-Company-Registration-Address

Many foreign investors preparing to establish a company in Vietnam often face a core question: “Is a shared office model accepted as a legal company registration address under current Vietnamese law?”

This is a particularly important legal issue, as the company registration address plays a decisive role in the appraisal of applications for the Investment Registration Certificate (IRC) and Enterprise Registration Certificate (ERC). It also directly affects all subsequent tax declaration procedures and bank account opening processes.

The article below will provide a detailed answer to this question, while offering a comprehensive perspective on the legal conditions, operational benefits, and key considerations for investors when choosing this model.

1. What is a Company Registration Address in Vietnam?

According to the provisions of the Law on Enterprises of Vietnam, the enterprise registration address (head office) is the actual contact location of the enterprise within the territory of Vietnam. The address must be clearly identified, including house number, alley, lane, street, road, or village, hamlet, commune, ward, town, district, urban district, town, provincial city, province, or centrally governed city.

A legally compliant headquarters address must meet the following basic requirements:

  • Actual Presence: It must be a real location that can be contacted and can easily receive administrative notices and correspondence.
  • Legal Right of Use: The enterprise must prove its lawful right of use through a lease agreement, borrowing agreement, or the lessor’s ownership certificate.
  • Safety & Fire Prevention: The headquarters building must fully comply with standards on structural safety, fire prevention and fighting (PCCC), and land-use planning under construction law.

The registration address is not only the basis for state management authorities to issue the operating license (ERC), but also the legal foundation for the tax authorities to exercise direct management, for banks to appraise corporate bank account opening dossiers, and a cornerstone of trust when establishing transactions with business partners.

2. Can a Shared Office Be Used as a Company Registration Address?

According to the Law on Enterprises, the enterprise registration address (head office) must be the actual contact address of the enterprise within the territory of Vietnam. This address must be clearly identified (house number, street, ward/commune, district, province/city) and meet the following basic conditions:

  • Actual Presence: It must be a real location that can be contacted and can receive administrative notices and correspondence.
  • Legal Right of Use: The enterprise must prove its lawful right of use through a lease agreement, borrowing agreement, or documents proving the lessor’s ownership rights.
  • Safety & Fire Prevention and Fighting: The building/headquarters must comply with standards on structural safety, fire prevention and fighting (PCCC), and planning under construction law.

Therefore, a shared office can fully be used as a company registration address if it meets all the conditions listed above.

In practice, professional shared office providers supporting FDI enterprises can provide a company registration address that meets these requirements, subject to the legal status and documentation of the specific premises.

Is-a-Shared-Office-a-Valid-Company-Registration-Address

3. Benefits of Using a Shared Office as a Company Registration Address

Choosing a shared office as a company registration address can deliver significant financial and operational benefits for foreign investors entering the Vietnamese market. The most easily recognizable benefit is the ability to optimize operating budgets, enabling the enterprise to save up to 80% of costs compared to signing a long-term contract to lease and fit out a traditional office space solely for the purpose of obtaining a business registration location.

Beyond the cost equation, this solution also elevates brand positioning, as the enterprise naturally owns a transaction address located in prestigious high-rise buildings in the city center. This professional presence builds significant trust among partners, clients, and regulatory authorities alike. Furthermore, the flexibility of shared offices allows the enterprise to easily expand its workspace as headcount grows without disrupting the original legal structure. Most importantly, the use of a well-managed actual workspace helps the enterprise maintain continuous legal compliance and completely eliminates the risk of having its Tax Identification Number (MST) locked due to suspicions of non-operation at the registered headquarters.

4. Risks When Choosing a Company Registration Address

Although using shared space as a headquarters address is legal, investors still need to exercise caution regarding potential operational risks:

  • Lessor Lacking Legal Capacity: Some small-scale space providers do not have the legal function or permission from the building owner to sublease, resulting in the business registration dossier being rejected by the Department of Planning and Investment.
  • Address Listed on Tax Warning Lists: If a location has too many “shell” companies registered but not actually operating, the tax authorities may place that address under priority inspection, affecting the company’s ability to issue electronic invoices.
  • Lack of Support During On-Site Inspections: When state management authorities conduct unannounced inspections, if the lessor does not assist in verifying the enterprise’s presence, the company risks having its Tax Identification Number locked due to “non-operation at the registered address.”

Is a Shared Office a Valid Company Registration Address (2)

6. How Vina TPT Shared Office Supports Company Registration

Vina TPT provides a full-package solution that supports company registration in combination with shared office rental services for foreign investors in Vietnam.

When clients use Vina TPT’s company establishment service, we can simultaneously provide a shared office that serves as a legal company registration address, together with the supporting office documentation required for the registration process. This solution enables the enterprise to fully meet legal requirements right from the stage of applying for the IRC and ERC, while saving costs compared to leasing a traditional office.

After the company is established, Vina TPT continues to support key operational services, including:

  • Provision of a Legal Business Registration Address: Ensures a standard commercial address that fully meets legal conditions for ERC and IRC registration, bank account opening, and VAT invoice issuance.
  • Full-Package Office Dossier Support: Ready preparation of the lease agreement, copies of premises documents, and legal confirmations to support the appraisal process by state authorities.
  • All-in-One Integrated Solution: Perfectly combines workspace infrastructure with Company Establishment Consulting, Accounting – Tax Services, and Payroll Management.
  • Legal Compliance Support: The Vina TPT team directly assists with installing the company signboard, welcoming on-site inspection teams from the Tax Authorities, and professionally receiving administrative correspondence.

Thanks to this integrated model, investors only need to work with a single partner for both establishment procedures and workspace, making the process of starting a business in Vietnam faster, more convenient, and fully compliant with regulations.

Are you looking for a legally compliant and prestigious company registration address in Ho Chi Minh City? Contact Vina TPT today for a free consultation on the Shared Office solution and full-package company establishment procedures.

BOOK A FREE CONSULTATION