Vietnam Company Incorporation: Our Role & Your Preparation 

vietnam-company-incorporation-what-we-handle-and-what-you-need-to-prepare

vietnam-company-incorporation-what-we-handle-and-what-you-need-to-prepare You need a partner who carries out Vietnam company incorporation in full compliance with the law and in the correct document sequence. However, before cooperation begins, the most important thing is for the investor to clearly understand which part of the work you must prepare and which part the advisory firm will be responsible for drafting, filing, and tracking. Clearly defining this boundary helps founders avoid missing original documents and stay in control of the timeline without wasting time waiting for the advisory firm to handle tasks that depend on decisions from the investor’s side.

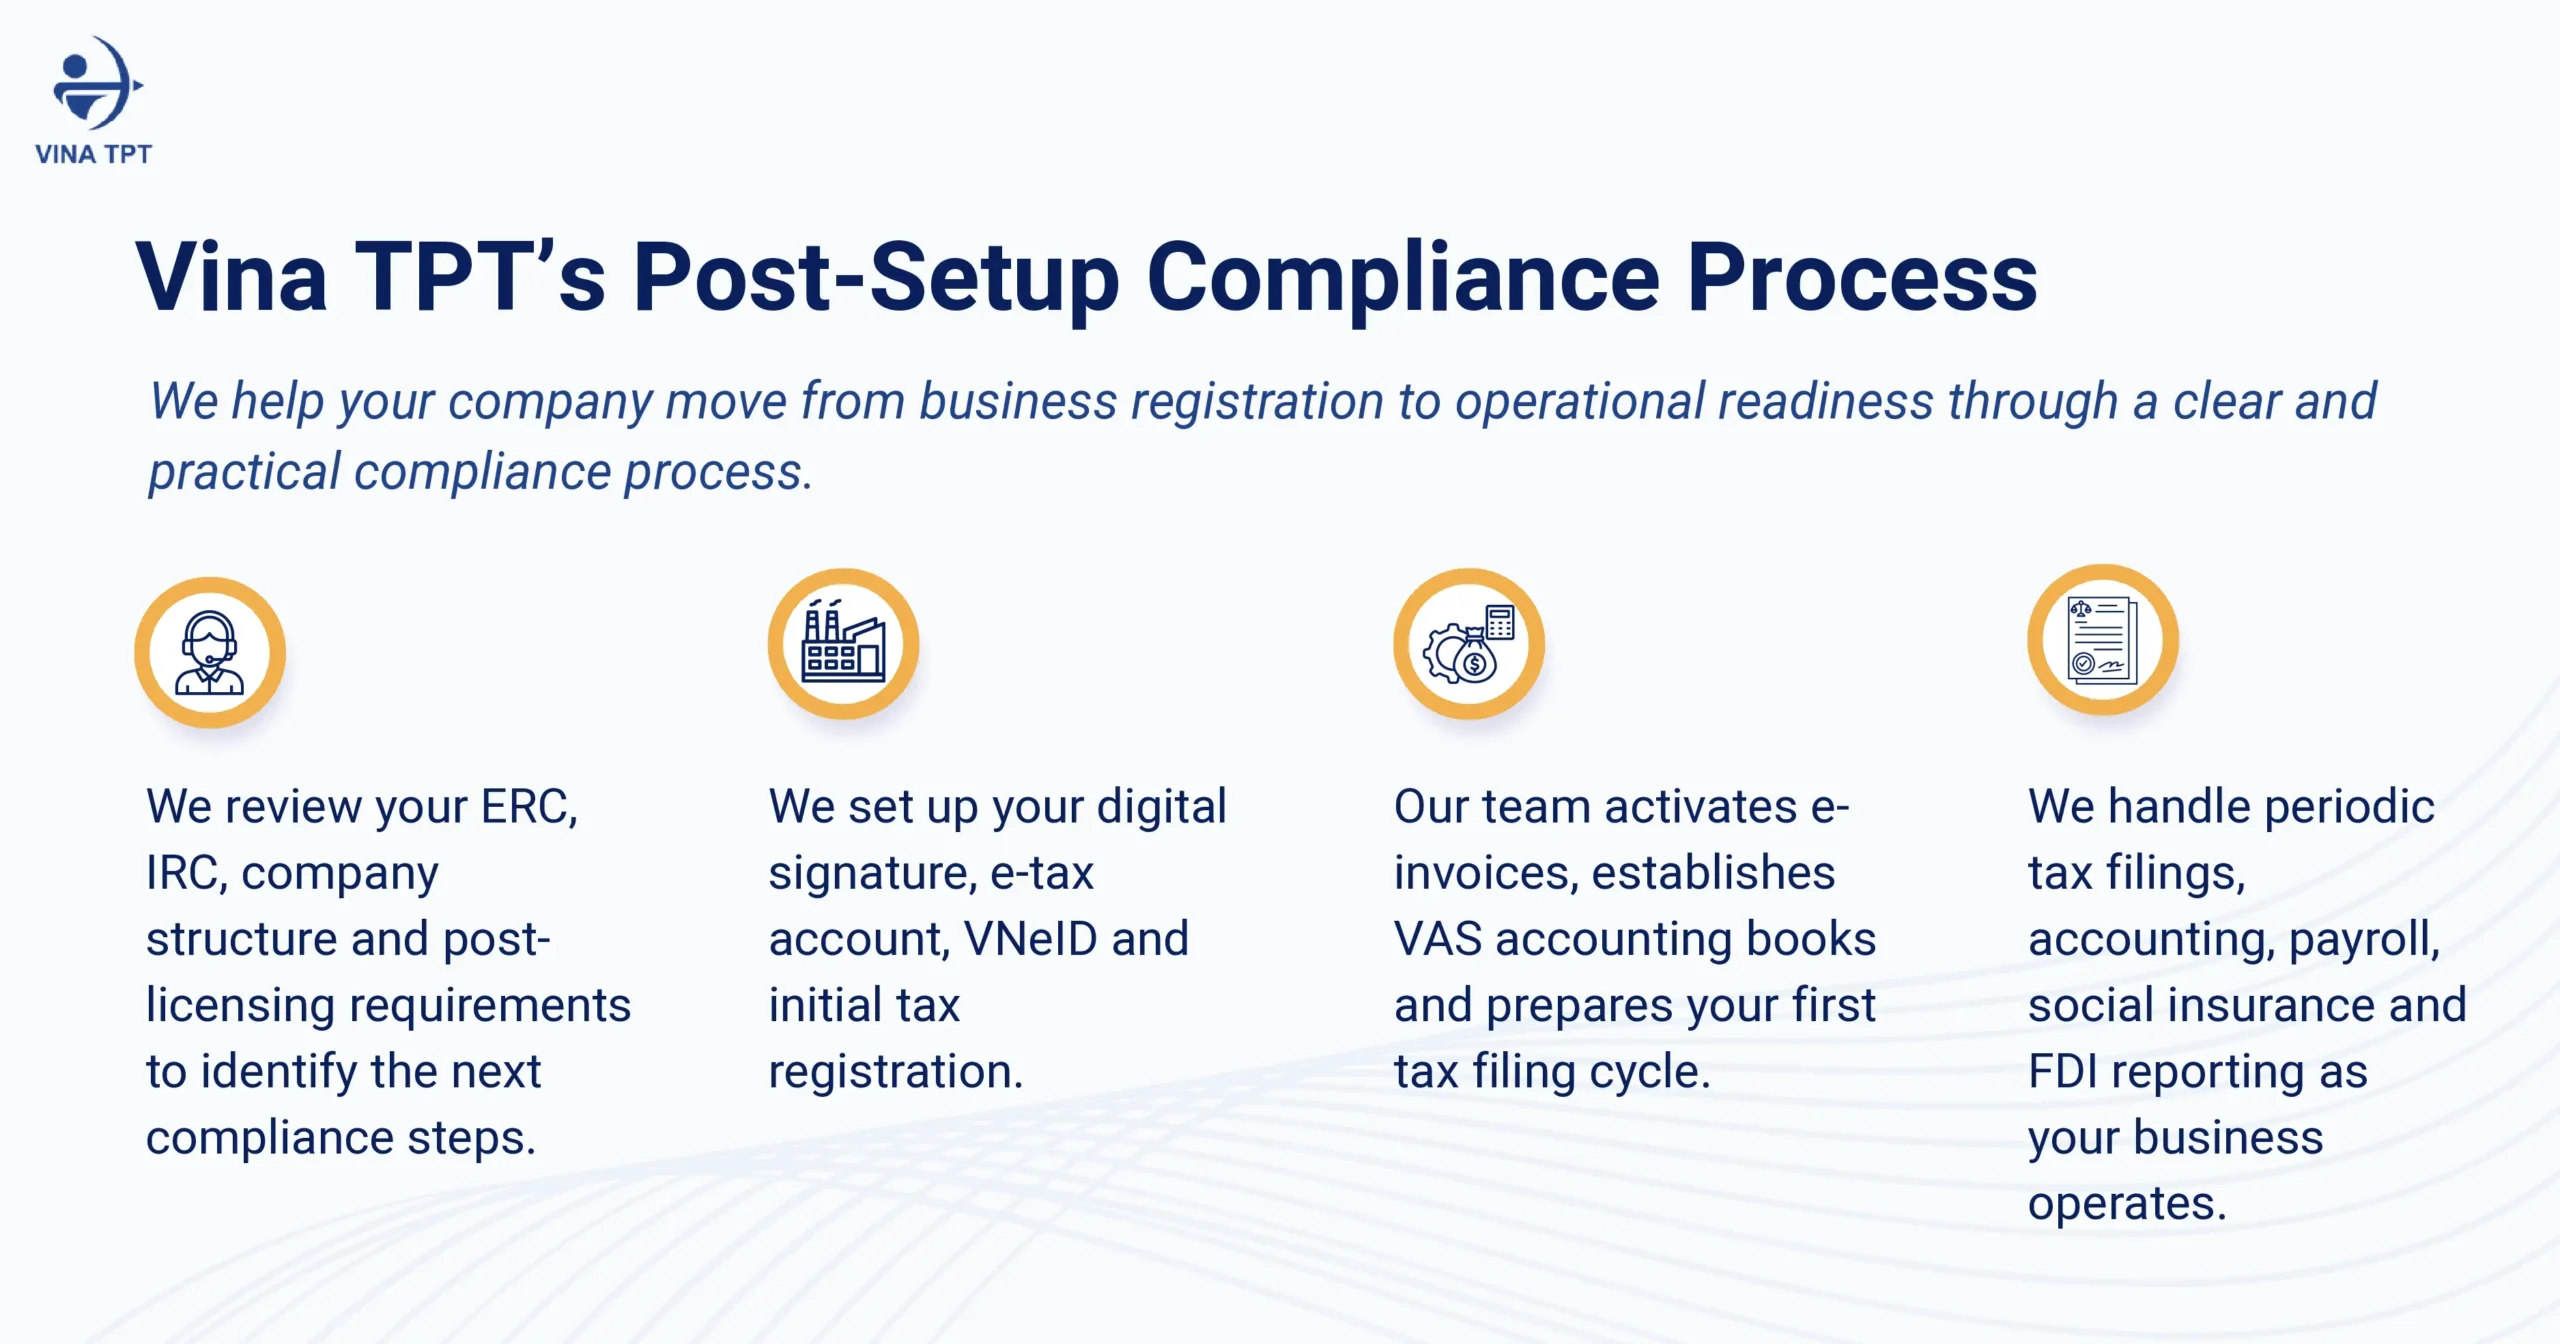
Drawing on our experience as an investment advisory firm, we explain how Vina TPT manages the Vietnam company incorporation process, what documents investors need to prepare, and how both parties coordinate from business activity planning and IRC/ERC filing to post-licensing procedures.

1. Confirm the Entity and Sector Before Any Filing

The first step in Vietnam company incorporation is to determine the appropriate legal structure and registered business activities before preparing the application documents. A Limited Liability Company is the optimal and most common choice when the investor wants to sell goods, provide services, and issue VAT invoices in Vietnam. A Joint Stock Company is more suitable when you plan to raise capital or gather multiple shareholders from the outset. Note that a Representative Office (RO) cannot replace a newly established company if your objective is to record revenue directly in Vietnam.

In parallel, Vina TPT will review market-access conditions: whether the sector allows 100% foreign ownership, whether a sub-license is required, and whether the capital contribution scale is commensurate with the operating model.

To receive accurate advice and the most optimal solution, the investor needs to describe their business plan clearly:

  • If trading: Do you plan to wholesale or retail to end consumers? What are the specific products? Will you conduct import-export activities or only domestic distribution?
  • If operating F&B or services: Where do you plan to open the location? Will you sell alcohol, beer, tobacco, or accompanying entertainment services? vietnam company incorporation 

The more detailed the information you provide, the more streamlined and focused the list of next steps Vina TPT provides, ensuring the company both complies with the law and operates commercially smoothly right after licensing.

2. IRC and ERC Licensing: Clear Division of Work and Timelines

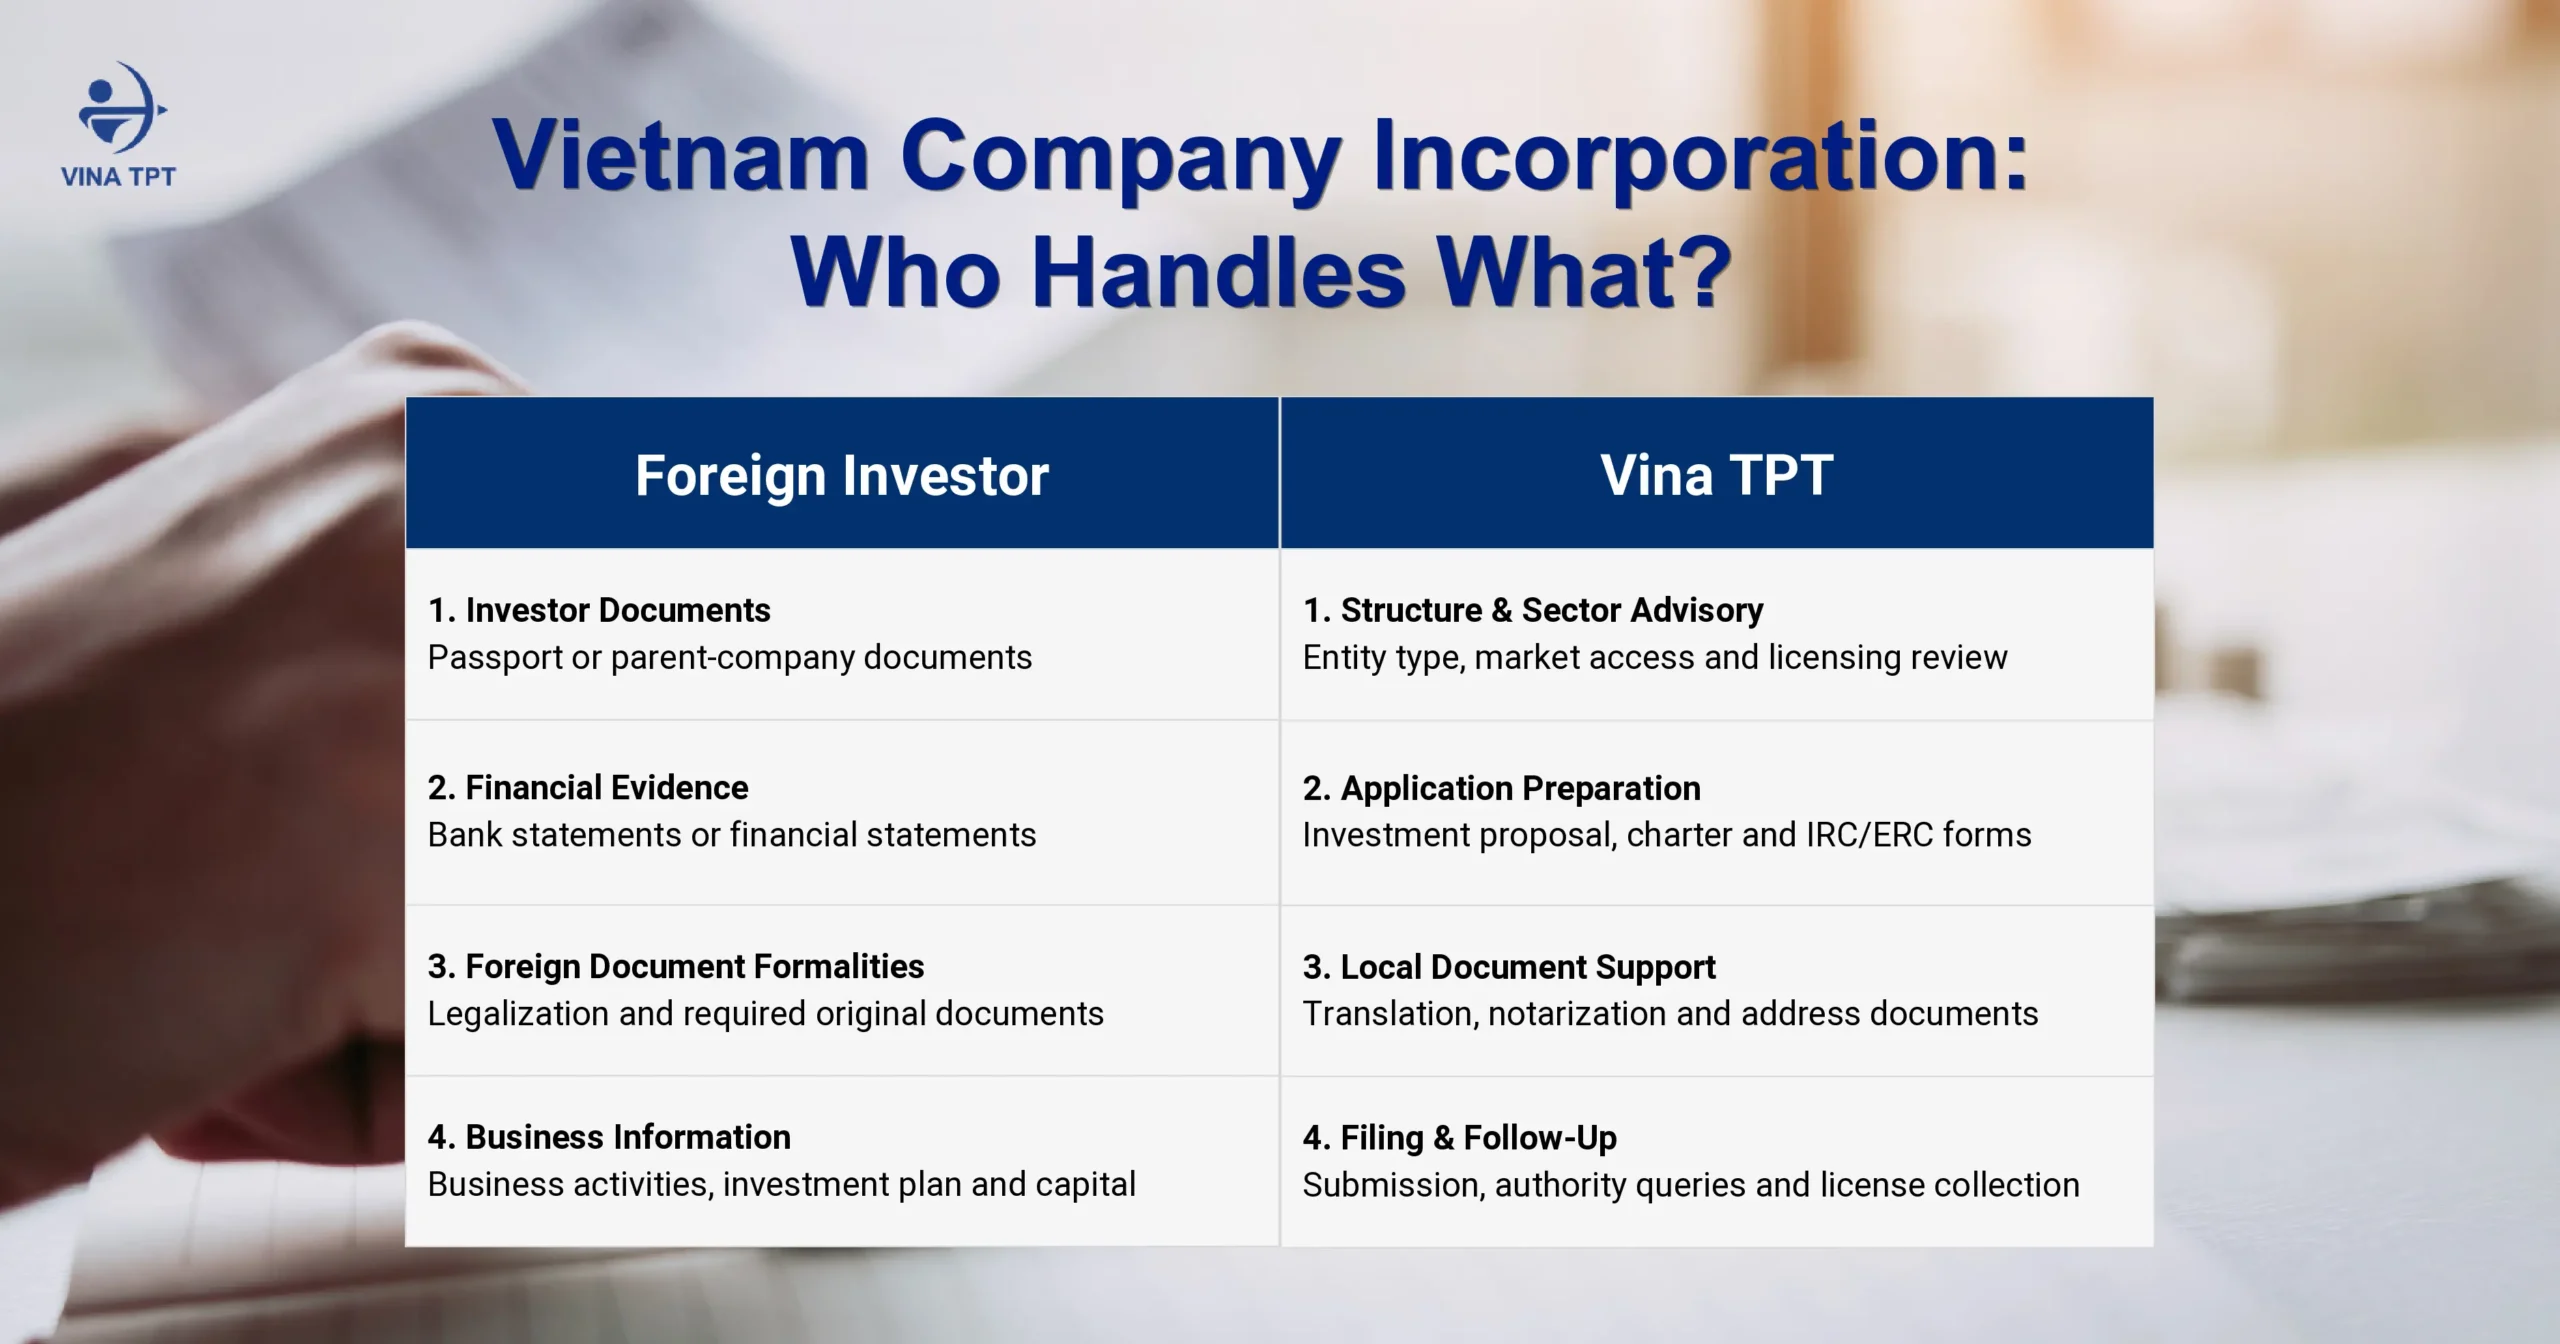
The process of filing for the Investment Registration Certificate (IRC) and the Enterprise Registration Certificate (ERC) requires a clear division of work between the investor and Vina TPT to ensure the licensing timeline proceeds accurately according to plan.

Investor’s responsibilities (Your Part)

The investor is responsible for preparing the input information and the original legal documents from the country of origin:

  1. Detailed business information and plan: Provide a specific description of the products, services, commercial model, target market, and capital utilization plan. This is the core basis for Vina TPT to prepare the investment project proposal and register the appropriate industry codes.
  2. Legal-entity / personal documents (already consularized): A copy of a valid passport (for individual investors) or Certificate of Incorporation / extract of parent company information (for corporate investors). All documents issued by foreign authorities must be notarized and consularized at the Vietnamese Embassy/Consulate in the home country before being sent to Vietnam.
  3. Proof of financial capacity (already consularized): Audited financial statements for the most recent 2 years (for the parent company) or a bank account balance confirmation of the investor showing a balance corresponding to the registered capital. These documents must be consularized together with the legal-entity file to ensure validity when submitted to the investment registration authority.

Vina TPT’s responsibilities (Our Part)

Vina TPT is responsible for all technical stages, translation, and coordination with the Department of Finance in Vietnam:

  • Drafting in detail the full IRC and ERC application file, the investment project proposal, the company charter, standard registration forms, and the office lease contract (in the case of using an address provided by Vina TPT).
  • Performing judicial notarized translation into Vietnamese for all foreign documents as soon as the consularized originals are received.
  • Representing the client in working with, filing documents, proactively providing explanations, and handling supplementary rounds with the Department of Planning and Investment (or the Management Board of the Industrial Park/Economic Zone).

Implementation process and reference timeline

  • Procedure sequence: File and receive the IRC first (investment project approval), then file and receive the ERC (legal-entity establishment). Where the project meets market-access conditions under the Law on Investment 2025, the processing can be optimized according to the latest operational guidance.
  • Reference timeline: Approximately 4–8 weeks from the date Vina TPT receives the complete set of valid consularized original documents.
  • Personnel aspect: The investor is not required to be continuously present in Vietnam throughout the process. The appearance of the Legal Representative or an authorized individual will be scheduled flexibly by Vina TPT according to each specific working milestone.
vietnam-company-incorporation-what-we-handle-and-what-you-need-to-prepare

3. Use a Valid Address If You Do Not Have an Office Yet

In the FDI company formation file in Vietnam, the business premises lease contract is one of the most important legal documents. The investment registration authority and the tax authority apply location-inspection rules to foreign-invested companies that are far stricter than those for domestic companies, to ensure the project has a real operating location and complies with specialized zoning.

The business registration address must be in a building with a commercial or office function. Residential apartments or collective housing are completely ineligible for registering a company headquarters or for receiving tax officers for on-site inspections.

For investors who have not yet secured a permanent office, a legally compliant shared office can be a practical solution during the Vietnam company incorporation process, helping reduce initial costs while providing a suitable registered business address.

Vina TPT provides a legal business registration address solution in a central location, accompanied by a full office lease contract for filing the incorporation application, integrated with professional reception and meeting-room services. This solution gives the company a legal address immediately to receive the ERC, and when the workforce expands, you can move to a private office without encountering initial procedural obstacles.

>>>> See also: Shared Office Ho Chi Minh City – Vina TPT Workspace for Foreign Companies

4. Post-Licensing & Initial Tax Registration Requirements

The Vietnam company incorporation process does not end when the Enterprise Registration Certificate (ERC) is issued. Foreign investors must also complete the relevant post-licensing procedures before their companies are fully prepared for operations. Even though the legal entity has been formed, the company still cannot issue invoices or contribute capital if the following post-licensing legal obligations have not been completed:

  • Company Seal & Digital Signature (Token): Engrave the legal-entity seal to complete the legal validity of internal documents and transactions. At the same time, the company needs to register and purchase an electronic digital signature (Token/HSM CA) for filing tax reports, declaring social insurance, and conducting electronic transactions with state authorities.
  • Initial Tax Registration: Complete the initial tax registration file with the directly managing tax office. This step includes registering the accounting regime (VAS standards), selecting the fixed-asset depreciation method, registering the company’s financial year, appointing the Chief Accountant / person in charge of accounting, and activating the electronic tax account (eTax).
  • Corporate VNeID identity: Activate the electronic identity account for the organization under current regulations.
  • Open bank accounts and contribute capital: Open the Direct Investment Capital Account (DICA) and the VND current account. The investor must transfer 100% of the registered capital contribution within 90 days from the ERC issuance date (or according to the schedule recorded on the IRC). Late capital contribution will result in administrative fines and the risk of license revocation.

5. How Vina TPT Supports Vietnam Company Incorporation

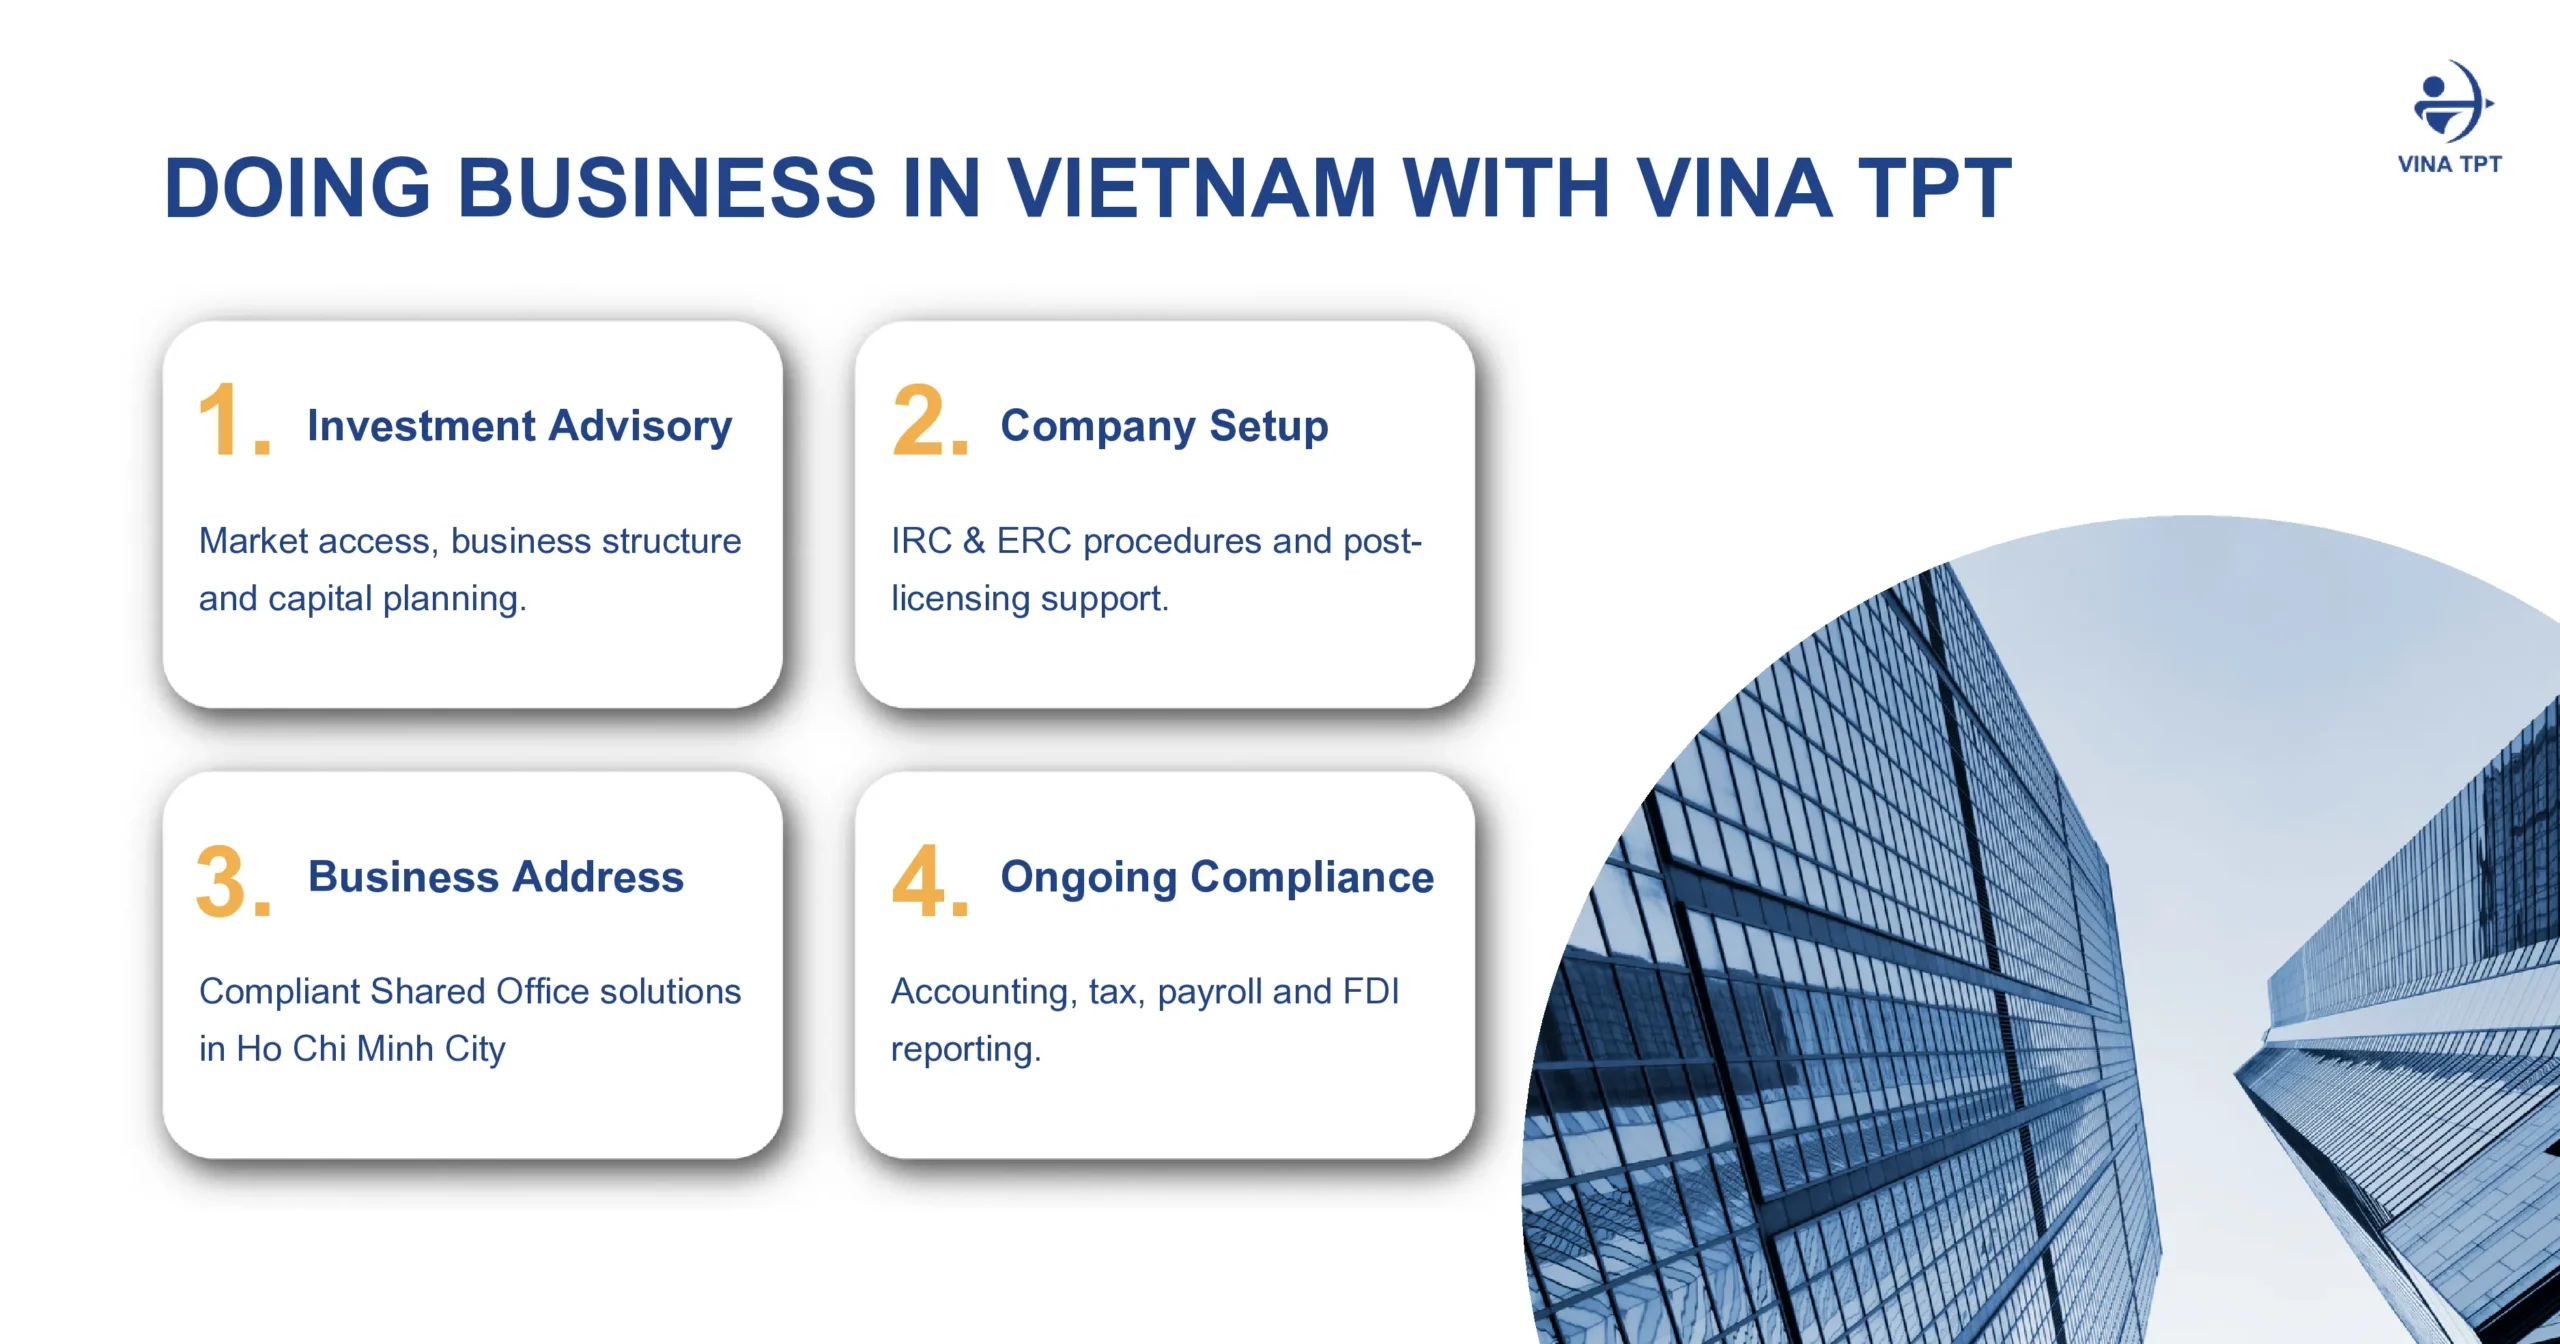
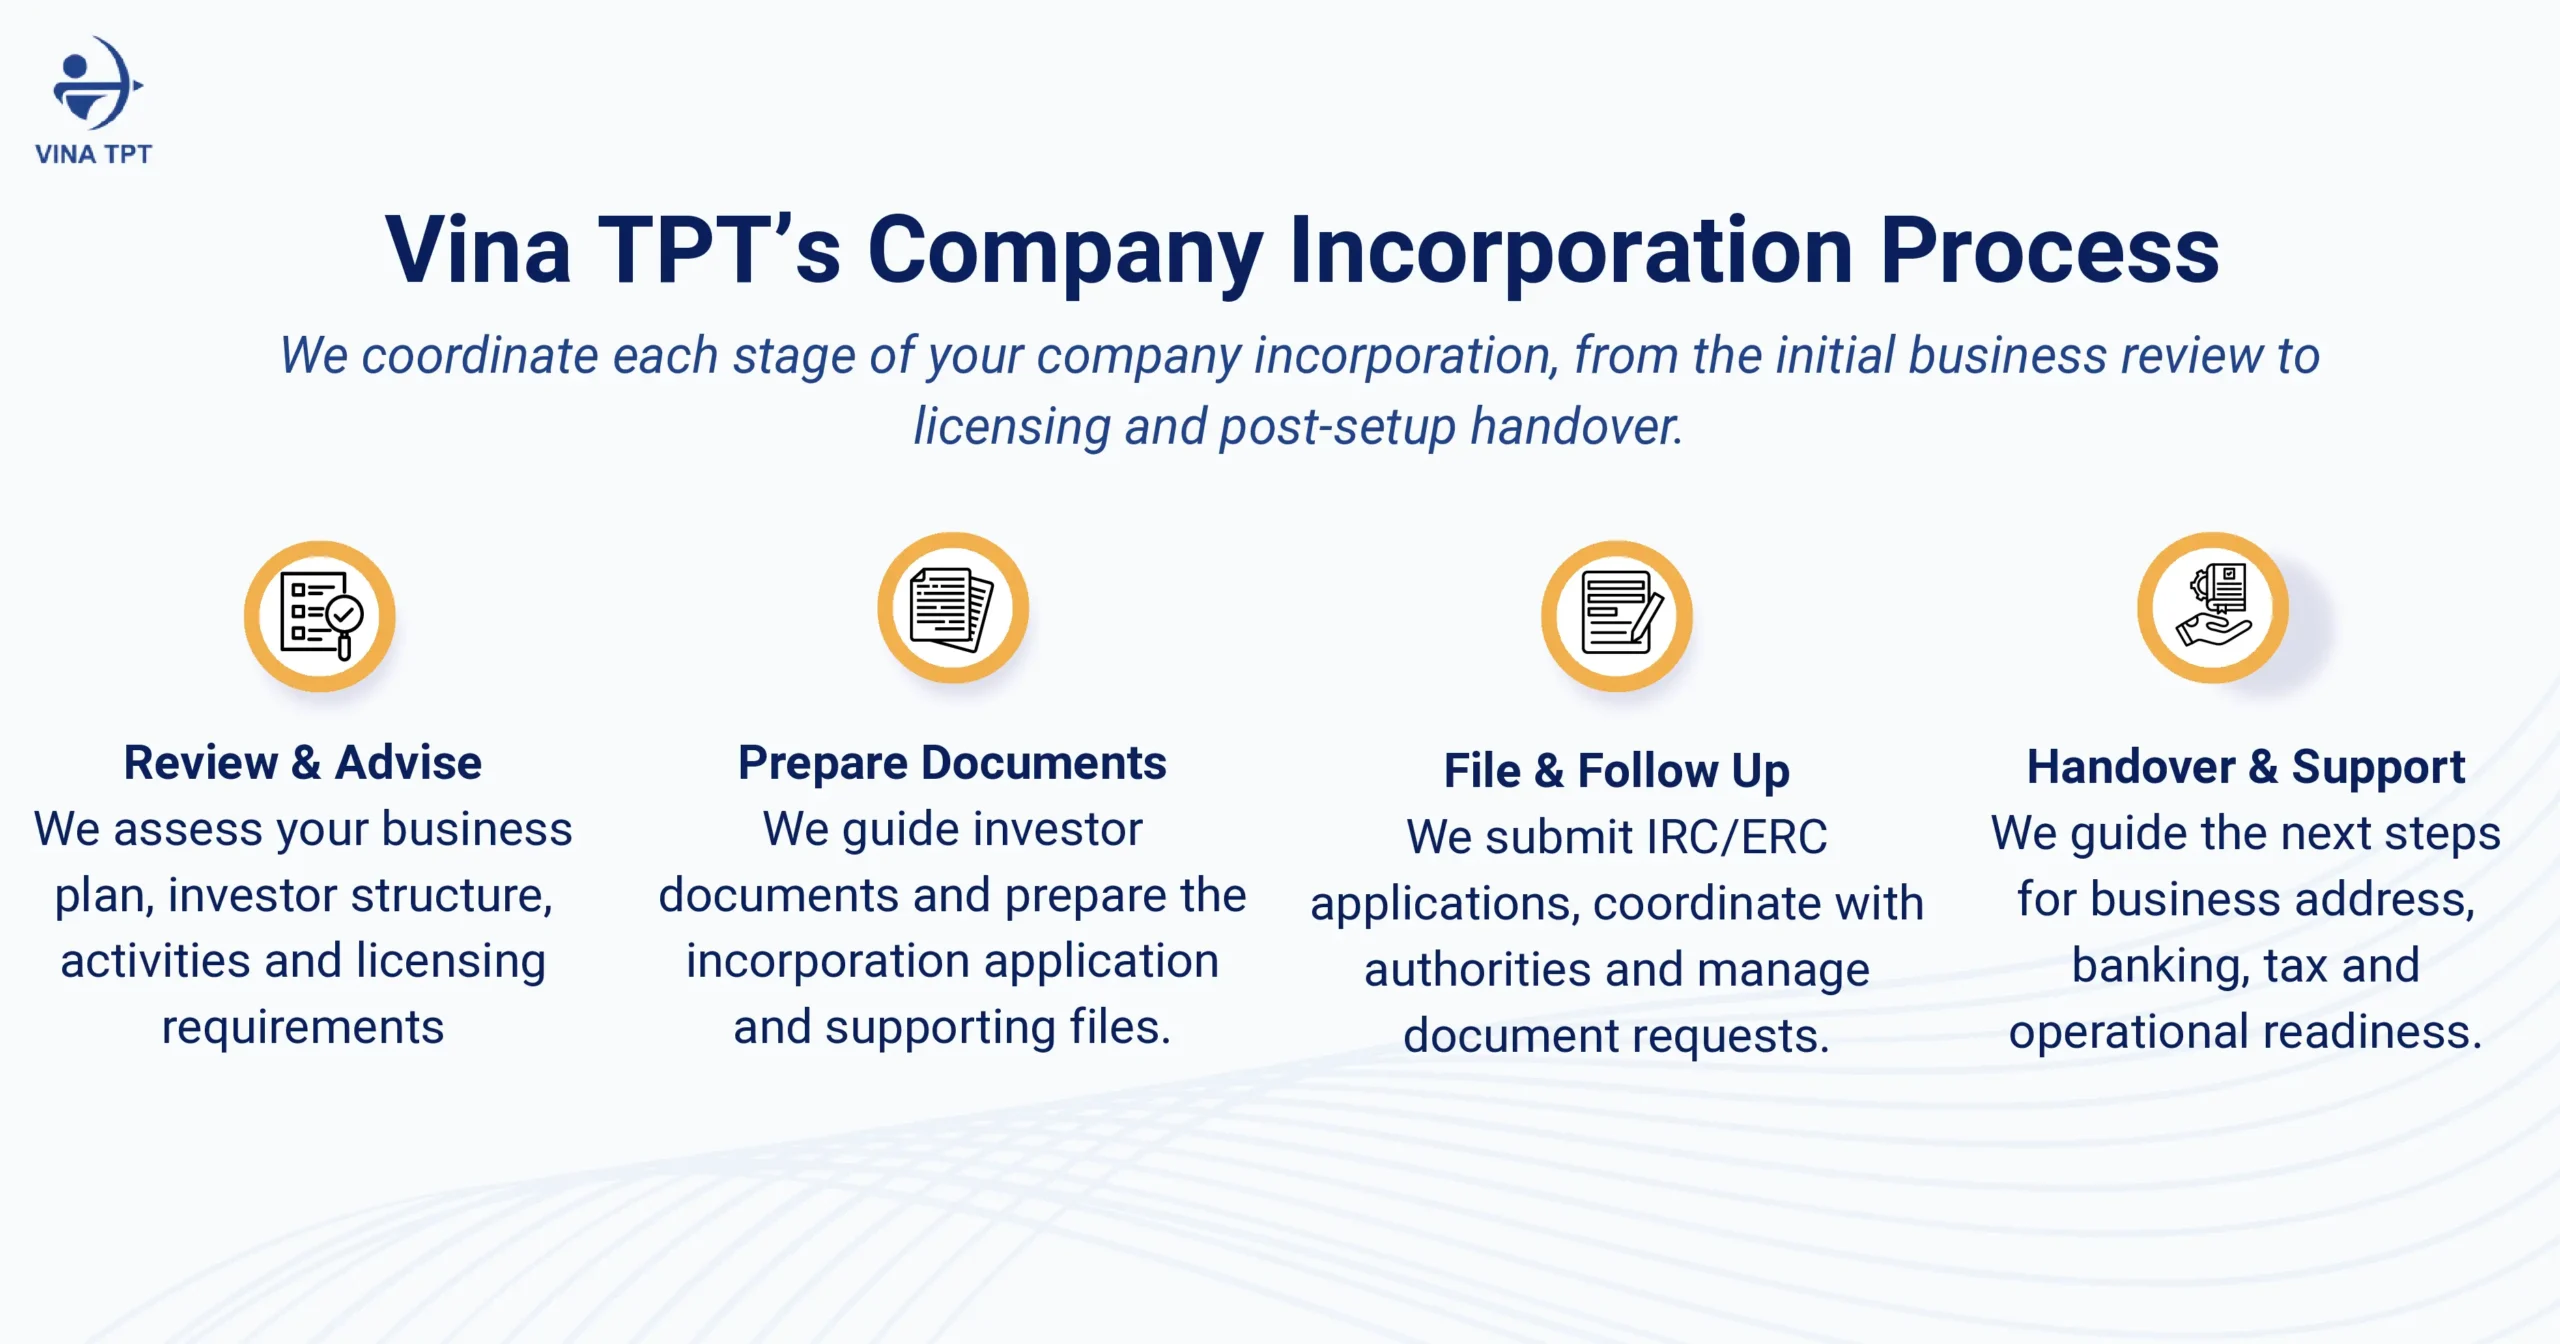
With over 20 years of practical experience in FDI investment advisory, accounting, and corporate legal services, Vina TPT provides comprehensive Vietnam company incorporation support, from initial business planning and licensing to post-establishment compliance.

  • End-to-end process: Advise on entity type and business lines – Draft an accurate file – Represent in filing and receiving the IRC/ERC – Provide a business registration address – Hand over the full initial tax and bank-account procedure package.
  • Bilingual communication: The team works fluently in English and Vietnamese, supporting effective remote operations for founders who do not yet reside in Vietnam.
  • Clear service-boundary commitment: We take the highest responsibility for the accuracy of the file and the working timeline with state authorities, based on the information and legal documents provided by the investor.

Please send Vina TPT information on (1) the intended business sector and (2) the investor type (individual or parent company organization). We will send you the document checklist and a detailed implementation roadmap completely free of charge. Contact Vina TPT today.
vietnam-company-incorporation-what-we-handle-and-what-you-need-to-prepare

BOOK A FREE CONSULTATION

Vietnam Visa, Work Permit and TRC: A Guide for Foreign Investors 

Visa-work-permit-trc-vietnam

a-guide-for-foreigner-investor-entering-vietnam

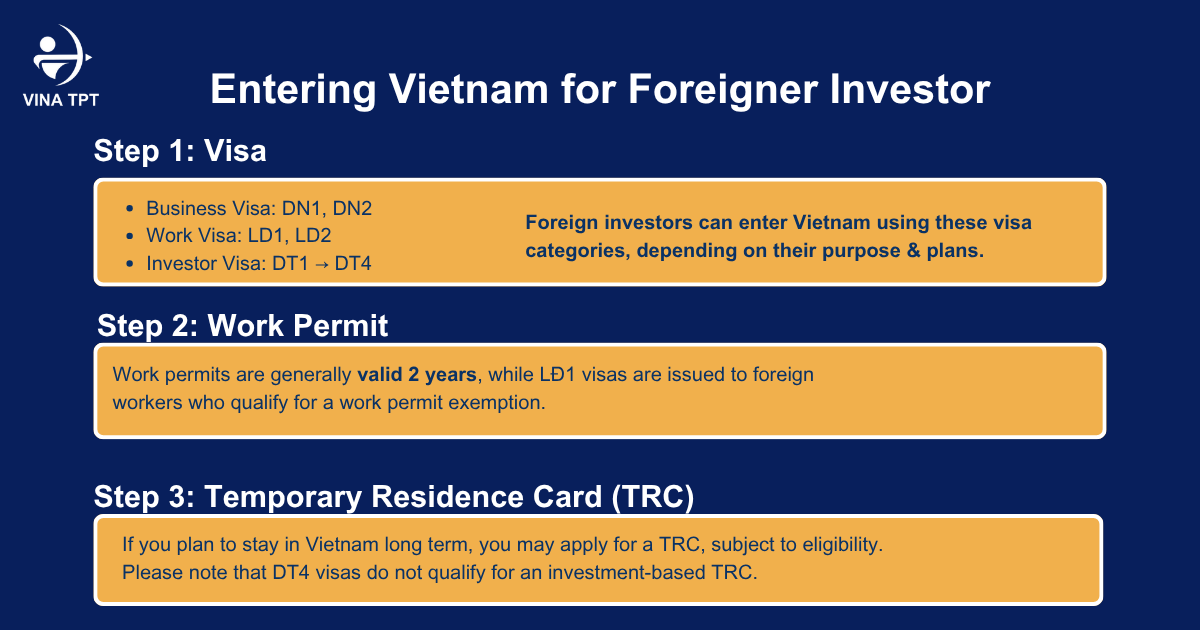
Opening a company in Vietnam raises three separate questions: how can you enter the country, can you legally work for your business, and how long can you stay? 

Understanding visa, work permit and TRC requirements in Vietnam helps foreign investors plan their business activities and relocation together. Your nationality, investment structure, personal capital contribution and actual working role all matter. 

Quick answer: A visa establishes your immigration purpose, a work permit or applicable exemption addresses your right to work, and a Temporary Residence Card (TRC) provides residence under an eligible category. Registering a company does not automatically satisfy all three requirements. 

Vietnam Visa vs Work Permit vs TRC: What Is the Difference? 

Visa Establishes Your Entry and Stay Purpose 

A Vietnamese visa supports entry and temporary stay for a specified purpose, such as business activities, investment or employment. The visa category should reflect your circumstances. 

Visa validity and permission to remain during a particular visit are related but distinct. Always check your authorized temporary stay rather than relying only on the visa’s expiry date. 

Work Permit Addresses Your Right to Work 

A work permit authorizes a foreign national to work under the approved employment arrangement. Certain individuals qualify for an exemption, subject to the relevant conditions and procedures. 

Neither owning a business nor holding an investor visa automatically resolves the work authorization question. 

TRC Supports Longer-Term Residence 

A TRC allows an eligible foreign national to reside in Vietnam for the card’s validity period and has visa-substitute value. It does not independently establish permission to work and is different from permanent residence. 

Document  Main purpose  What it does not establish by itself 
Visa  Entry and stay for an approved purpose  A universal right to work 
Work permit  Authorization for the approved work arrangement  Immigration permission to enter or remain 
TRC  Residence under an eligible category  Work authorization or permanent residence 

These documents operate under separate immigration and employment requirements. 

Which Visa Categories Matter to Foreign Investors? 

1. Business Visa Vietnam (DN1 and DN2)

  • DN1 applies to foreigners working with enterprises and other organizations having legal personality under Vietnamese law. 
  • DN2 applies to activities such as offering services, establishing a commercial presence and other activities under treaties to which Vietnam is a party. 

Meeting a distributor and taking an operational role in a Vietnamese company are different activities. A DN visa does not itself provide a work permit exemption. 

Scenario  Visa Category to Consider 
A Singaporean investor visits Vietnam to meet advisers, explore the market and discuss opportunities with potential partners before making an investment decision.  DN1, with sponsorship from an eligible enterprise or organization. 
A representative of a Korean company visits Vietnam to negotiate a contract with a local distributor.  DN1, for business dealings with a Vietnamese enterprise. 
A representative of a foreign enterprise enters Vietnam to offer services or establish a commercial presence under applicable international commitments.  DN2, subject to the relevant eligibility requirements. 

2. DT1, DT2, DT3 and DT4 Investor Visas 

Investor visas cover qualifying foreign investors and representatives of foreign organizations investing in Vietnam. Classification depends on the relevant capital contribution or statutory investment criteria. 

Visa  Main classification criteria  Maximum visa validity 
DT1  Capital contribution of at least VND 100 billion, or qualifying investment-incentive sectors or locations  5 years 
DT2  From VND 50 billion to below VND 100 billion, or qualifying government-designated encouraged sectors  5 years 
DT3  From VND 3 billion to below VND 50 billion  3 years 
DT4  Below VND 3 billion  1 year 
DN1 / DN2  Qualifying business activities  1 year 
LD1 / LD2  Qualifying employment circumstances  2 years 

These are statutory ceilings, not guaranteed periods. Investor classification also requires appropriate supporting records. 

3. LD1 and LD2 Work Visa Vietnam

  • LD1 concerns foreign workers qualifying under the work-permit-exempt framework, with the applicable supporting basis. 
  • LD2 concerns foreign workers who require a work permit. 

LD visas generally apply to foreign experts and employees coming to Vietnam to work for a company or organization. LD1 applies to those eligible for a work permit exemption, while LD2 applies to those required to hold a work permit. 

Do Foreign Investors and Business Owners Need a Work Permit? 

Investing in a Company and Working for It Are Different Activities 

Holding an investment and actively working for the business require different assessments. Managing employees, directing operations or providing technical services may bring you within the foreign-worker framework. 

The assessment should consider your actual activities, not simply whether your title says “investor” or whether you receive a local salary. 

Work Permit Exemptions for Qualifying Capital Contributors 

Under Article 7 of Decree 219/2025/ND-CP, the following capital contributors qualify for specified exemptions: 

Company type  Qualifying position  Required personal capital contribution 
Limited liability company  Owner or capital-contributing member  At least VND 3 billion 
Joint stock company  Chairperson or member of the Board of Directors  At least VND 3 billion 

For a joint stock company, merely being a shareholder does not establish the exemption described above; the qualifying board position also matters. 

Representatives of Corporate Investors Need a Separate Assessment 

Suppose an overseas company invests in a Vietnamese subsidiary and appoints a foreign director. The subsidiary’s investment capital is not automatically the director’s personal contribution. 

The representative must therefore assess the applicable work permit requirement or another exemption based on their own circumstances. An investor visa issued in a representative capacity is not sufficient evidence of the personal-contribution exemption. 

Exemption Does Not Always Mean No Paperwork 

For the qualifying capital contributors listed above, Article 9(4) provides a notification procedure rather than an application for an exemption certificate. Notification must be made to the competent authority at least three working days before the expected start of work. 

Other exemption categories may require different procedures. The employer should identify the correct exemption and retain evidence supporting it. 

Which Investors Can Obtain a Vietnam Temporary Residence Card? 

Investor TRCs Under DT1, DT2 and DT3 

Eligible investors and representatives may apply for investor TRCs under DT1, DT2 or DT3. Immigration authorities assess the applicant’s status and supporting investment records. 

Category  TRC available under this category?  Maximum TRC validity 
DT1  Yes, subject to eligibility  10 years 
DT2  Yes, subject to eligibility  5 years 
DT3  Yes, subject to eligibility  3 years 
DT4  No DT4 TRC category  Not applicable 
LD1 / LD2  Yes, subject to employment-related conditions  2 years 
DN1 / DN2  No DN1 or DN2 TRC category  Not applicable 

A TRC must expire at least 30 days before the passport expires. Consequently, a short remaining passport validity can reduce the residence period granted. 

Why DT4 Does Not Qualify for an Investor TRC 

DT4 holders cannot obtain a TRC under the DT4 category. However, this does not permanently exclude them from residence cards. 

A person who independently meets another category’s requirements may apply under that category. For example, an eligible working business owner may assess an employment-based route. 

Work-Based TRCs Under LD1 and LD2 

Employment-based TRCs require the appropriate work-related basis and sponsorship. Their statutory maximum is two years; the actual period depends on the supporting documents and applicable conditions. 

A work permit holder should coordinate the residence application with the permit’s remaining validity rather than assume a full two-year card will be issued. 

Is a TRC Mandatory for Staying in Vietnam? 

A TRC is not mandatory simply because you own a company or intend to stay for an extended period. You may remain under another valid immigration basis within your authorized stay. 

However, preparing a TRC application does not automatically extend an expiring stay. 

How Does Investment Capital Affect Your Visa, Work Permit and TRC? 

Personal Capital Contribution vs Total Company Capital 

Start with three questions: who is the registered investor, how much capital belongs to that person or entity, and which documents prove the investment? 

For the capital-contributor work permit exemption, your personal qualifying contribution matters. The company’s total capital cannot automatically be attributed to each shareholder, member or representative. 

DT3 vs DT4: What Changes Around the VND 3 Billion Threshold? 

The threshold affects investor visa classification and residence options, but employment exemptions must still be assessed separately. 

The following examples assume the investment and working arrangements are properly documented: 

Illustrative situation  Work authorization assessment  Residence route to assess 
Individual contributes VND 1 billion and actively manages the company  Work permit generally required unless another exemption applies  DT4 visa; employment-based residence if eligible 
Individual contributes VND 5 billion as a member of an LLC  Assess the qualifying capital-contributor exemption and notification  DT3 investor TRC 
Overseas company invests and sends a director  Assess the director’s own work arrangement; no automatic personal-contribution exemption  Representative investor or employment route, depending on eligibility 

Why Company Registration Alone Does Not Guarantee Residence 

An Enterprise Registration Certificate (ERC) or Investment Registration Certificate (IRC) documents business or investment matters. Neither replaces the separate immigration and employment assessment. 

Evaluate residence objectives before finalizing the investment structure, especially where the business will be owned by an overseas company rather than directly by the relocating individual. 

vietnam visa-work permit-trc

What Is the Application Process for Foreign Investors? 

Step 1 — Assess Your Investment, Role and Intended Stay 

Prepare details of your nationality, investment structure, contribution, working responsibilities, current immigration status and intended stay. Include accompanying family members when planning relocation. 

Step 2 — Identify the Appropriate Visa and Sponsor 

Match the visa to your actual purpose and identify the appropriate sponsoring entity. Check that personal, company and investment records consistently describe the proposed arrangement. 

Step 3 — Complete Work Permit or Exemption Requirements Where Applicable 

If you will work in Vietnam, establish whether a work permit, exemption certificate or notification procedure applies. Prepare the relevant evidence and complete the required steps before commencing work. 

Step 4 — Apply for the Appropriate Residence Status 

Assess the appropriate visa or TRC route. Vietnamese law permits visa-purpose changes in specified circumstances, including qualifying investment and employment cases; approval is not automatic. 

Confirm the current filing requirements before assuming you must leave Vietnam or can complete everything domestically. 

Step 5 — Maintain Temporary Residence Registration and Track Expiry Dates 

Ensure temporary residence registration is completed and monitor passport, visa, work authorization and TRC dates. Reassess the documents when your employer, sponsor, passport, investment or working role changes. 

An investor route and an employee route do not necessarily follow an identical application sequence. 

Plan Your Visa, Work Permit and TRC With Vina TPT 

Vina TPT helps foreign investors assess visa, work permit, exemption and TRC requirements alongside their business establishment and HR compliance needs. 

Our team can review your investment structure, contribution, proposed role and intended stay, then discuss the relevant procedures and supporting documents. Share your nationality, ownership details, current immigration status and relocation plans to identify practical next steps. 

Discuss Your Vietnam Visa and Residence Requirements 

BOOK A FREE CONSULTATION


[Newsletter] September 2026 Tax Update: VAT Refund, PIT withholding, CIT & Invoice issuance 

Vietnam tax update september 2026

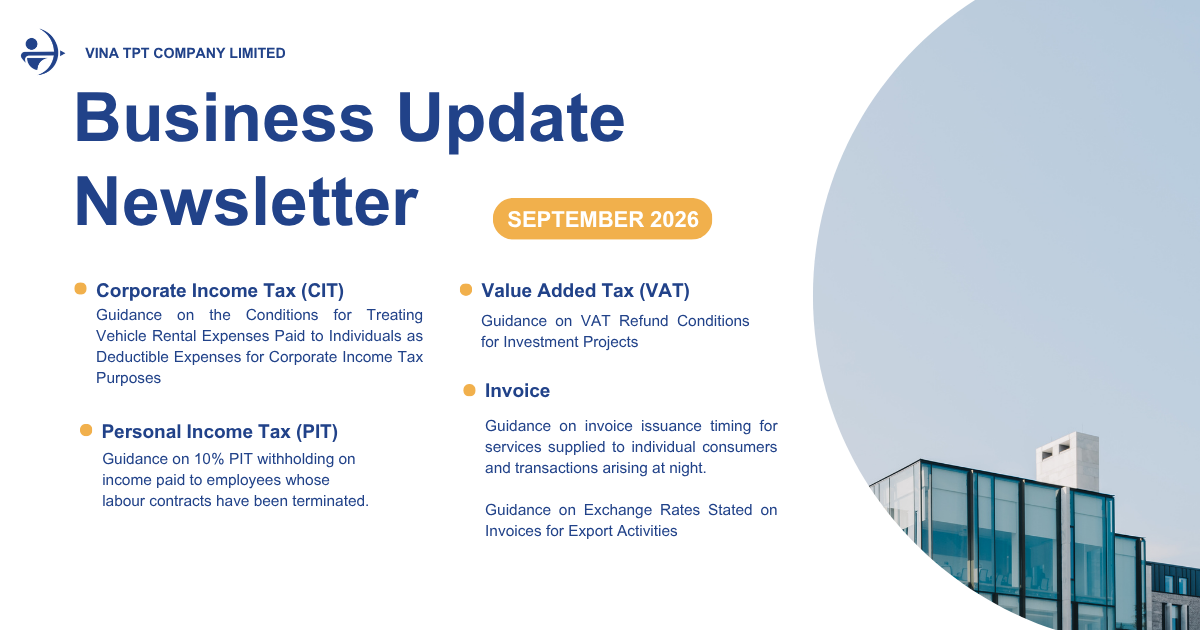
This September 2026 Vietnam tax update summarises recent guidance on VAT refunds for investment projects, deductible vehicle rental expenses, PIT withholding after employment termination, invoice issuance timing and exchange rates on export invoices. Each section highlights the relevant conditions and practical considerations to help businesses review their tax procedures and supporting documents. 

1. INVOICE

Guidance on invoice issuance timing for services supplied to individual consumers and transactions arising at night. 

Pursuant to Official Letter No. 6325/CT-QLNT dated August 26, 2026 of the Tax Department, guiding Article 9 of Decree No. 254/2026/NĐ-CP (effective July 1, 2026). 

Services supplied to individual consumers

For enterprises providing services to individual consumers, including banking; payment intermediary services; credit information services; securities business; crypto-asset transactions; support services for transactions on carbon exchanges; insurance business; money transfers via e-wallets; suspension and resumption of electricity supply; e-commerce; postal and transportation services supporting e-commerce; public passenger transport by metro and bus; passenger transport by taxi, contract vehicle, and two-wheeled motorcycle; parking services; cinema services; and other services, where such enterprises satisfy the conditions of having a software system capable of managing each transaction in detail and maintaining payment collection data in the system on a transaction-by-transaction basis: 

–  The seller shall prepare a Summary of E-Invoice Data for Sales of Goods and Provision of Services and a Detailed Statement of Transactions Arising During the Month or Quarter (covering the period from the first day to the last day of the relevant month or quarter), using the forms prescribed by the Minister of Finance, and submit them to the tax authority no later than the statutory deadline for submission of the Value Added Tax (“VAT”) return in accordance with the laws on tax administration. 

– Where a large volume of invoices is generated, the Summary of E-Invoice Data and the Detailed Statement of Transactions shall be divided into separate data files in accordance with the standard data format prescribed by the tax authority to ensure compliance with the technical requirements for data transmission and receipt. 

The seller is responsible for the accuracy of transaction information, must retain full detailed data for each transaction, and must ensure the data can be retrieved, reconciled and provided, together with related documents, on request of the tax authority or competent state agency. 

Transactions arising during night working hours

Where the seller has no automatic invoicing software and sells goods or supplies services during night working hours as defined by the Labor Code, the invoice must be issued no later than the next working day.ogether with the Appendix on VAT Refund Claim Information (Form No. 01-8/GTGT) as the basis for the tax authority to review and process the refund request. 

Guidance on Exchange Rates Stated on Invoices for Export Activities 

Pursuant to Official Letter No. 6810/CT-QLNT dated 14 September 2026 

In cases where economic or financial transactions are denominated in foreign currencies in accordance with foreign exchange regulations, the seller shall indicate on the invoice the exchange rate between the foreign currency and the Vietnamese Dong as prescribed in Point c.1, Clause 8 of the Appendix attached to Decree No. 254/2026/NĐ-CP. 

Pursuant to Clauses 1 and 5, Article 26 of the Law on Tax Administration No. 108/2025/QH15 and the accounting regulations, the exchange rate shown on the invoice shall be the actual transaction exchange rate determined in accordance with accounting laws and regulations.

2. PERSONAL INCOME TAX 

Guidance on 10% PIT withholding on income paid to employees whose labour contracts have been terminated. 

Pursuant to Official Letter No. 10049/NBI-QLDN1 dated August 3, 2026 of the Ninh Binh Provincial Tax Office, guiding Clauses 1 and 3, Article 26 and Clause 2, Article 50 of Decree No. 253/2026/NĐ-CP dated June 30, 2026 

– Where an employee is a resident individual whose labor contract was terminated on 30 June 2026, and the Company pays the employee’s salary for June 2026 on 10 July 2026, such payment shall be treated as a salary payment made to an individual whose labor contract has already been terminated. If the payment to each individual on each occasion is VND 5 million or more, the Company shall withhold personal income tax (“PIT”) at the rate of 10% before making the payment. If the payment is less than VND 5 million per payment, the Company shall withhold PIT at the rate of 10% only at the individual’s request. 

– The Company shall withhold PIT at the rate of 10% on taxable income from salaries and wages before making payment to the individual. Tax-exempt income prescribed by law, including remuneration for night work and overtime work, and salaries and wages paid for unused annual leave within the conditions, duration and limits prescribed by labor laws, shall not be included in the income subject to withholding. Any amount exceeding the statutory limits shall be included in taxable income. 

Compulsory insurance contributions, personal and dependent deductions, and other allowable deductions are taken into account in determining taxable income when applying the partially progressive tax tariff or upon annual PIT finalization, and shall not be deducted when applying the provisional 10% withholding rate prescribed in Clause 2, Article 50 of Decree No. 253/2026/ND-CP. 

3. VALUE ADDED TAX

Guidance on VAT Refund Conditions for Investment Projects 

Pursuant to Official Letter No. 7019/CT-QLNT dated 22 September 2026 issued by the Tax Department: 

Where, at the time of submitting the VAT refund application, a business establishment falls within the scope of cases eligible for a VAT refund in respect of an investment project, has input VAT that fully satisfies the conditions for VAT credit and refund in accordance with the VAT regulations, and has submitted a VAT refund application dossier in compliance with the tax administration regulations, the business establishment shall be considered for a VAT refund in respect of the investment project. 

Pursuant to Clause 4, Article 3 of Law on Investment No. 61/2020/QH14, Clause 2, Article 15 of Law on Value Added Tax No. 48/2024/QH15, and Article 30 of Decree No. 181/2025/ND-CP, there is no provision stipulating that the date of issuance of the Investment Registration Certificate (“IRC”) shall serve as the basis for determining the input VAT attributable to an investment project 

Where the Company has VAT invoices for purchased goods and services arising prior to the issuance of the IRC, if the Company is able to provide sufficient supporting documents and evidence demonstrating that such goods and services were actually purchased for the preparation and implementation of the investment project in accordance with the laws on investment, and the related input VAT satisfies the conditions for VAT credit and refund under the VAT regulations, such input VAT may be considered for credit and refund in respect of the investment project in accordance with the applicable regulations. 

4. CORPORATE INCOME TAX

Guidance on the Conditions for Treating Vehicle Rental Expenses Paid to Individuals as Deductible Expenses for Corporate Income Tax Purposes 

Pursuant to Official Letter No. 15944/DON-QLDN3 dated 18 August 2026 issued by the Dong Nai Tax Authority: 

  • Where an enterprise rents assets from an individual, the supporting documents required to substantiate the deductible expense include the asset lease agreement and documents evidencing payment of the rental fee. 
  • Where an enterprise rents assets from an individual and the lease agreement stipulates that the rental fee is exclusive of taxes (including value added tax and personal income tax), and the enterprise is required to declare and pay such taxes on behalf of the individual in accordance with the laws on tax administration, the taxes paid on behalf of the individual may also be treated as deductible expenses for corporate income tax purposes, provided that valid tax payment documents are available. 

5. Review Your Business’s Tax Compliance 

Vina TPT provides integrated accounting, tax, HR and payroll, legal and business advisory services for domestic and foreign-invested enterprises in Vietnam. From company establishment and post-licensing procedures to bookkeeping, financial reporting and ongoing compliance, we help businesses manage their obligations at each stage of their operations. 

Our tax services include tax filing and annual finalization, VAT refund assistance, tax health checks, transfer pricing and global minimum tax compliance. We also review supporting records, identify potential compliance gaps, and assist with documentation and explanations requested by tax authorities during tax reviews and inspections. 

If these updates affect your business, our team can help assess the implications, review your current procedures and recommend practical actions suited to your operations. 

Contact Vina TPT to Review Your Tax Compliance 

BOOK A FREE CONSULTATION

what-is-included-in-business-accounting-services-in-vietnam

Annual Tax Finalization in Vietnam 2026: Key Rules, Deadlines & Compliance Guide

annual-tax-finalization-in-vietnam-2026

annual-tax-finalization-in-vietnam-2026

Annual tax finalization is not simply a roll-up of the monthly or quarterly VAT and PIT returns. For the 2026 accounting period (ending on 31 December 2026 for companies that use a calendar financial year), the company must close its VAS books, prepare the annual financial statements, and finalize Corporate Income Tax (CIT) and Personal Income Tax (PIT). The usual statutory deadline is 31 March 2027.

In practice, foreign-invested (FDI) companies face a real risk of reassessment and late-payment interest in the annual tax-finalization period. The pressure points are usually the gap between provisional CIT paid over the four quarters and the tax due on finalization, errors in employee PIT finalization authorizations, and missing related-party transaction appendices.

This article sets out the full tax finalization Vietnam obligations for 2026 and the file the company should start preparing now.

1. What “Tax Finalization” Means in Vietnam

In Vietnam’s tax-administration system, annual tax finalization has a different legal character and a different scope of review from monthly or quarterly returns. Periodic filing only records provisional figures for the period. Tax finalization is the process of consolidating and reconciling all revenue, expenses, taxable income, and tax already paid across the full 12 months of the financial year, so that the tax the company and its employees actually owe, or are entitled to have refunded or offset, is fixed exactly.

The company’s annual tax-finalization file rests on two core obligations:

  • Corporate Income Tax (CIT) finalization: Determine total revenue, deductible expenses, upward and downward adjustments to taxable income, loss carry-forward, and the company’s official CIT for the year.
  • Personal Income Tax (PIT) finalization: Determine total salary and wage income the company paid during the year to all employees (local staff and foreign specialists), declare tax already withheld, and finalize on behalf of individuals who have authorized the company to do so.
  • Mandatory supporting documents: Annual financial statements prepared under VAS (independently audited for FDI companies) and the related-party transaction return set, if related-party relationships arose.

Under Article 44 of the Law on Tax Administration 2019, the annual tax-finalization file must be filed no later than the last day of the third month after the financial year ends.

2. Corporate Income Tax Finalization for 2026

CIT finalization for the 2026 tax year requires an exact match between the financial statements and the CIT finalization return (Form 03/TNDN), together with the loss-carry-forward and tax-incentive appendices, if any.

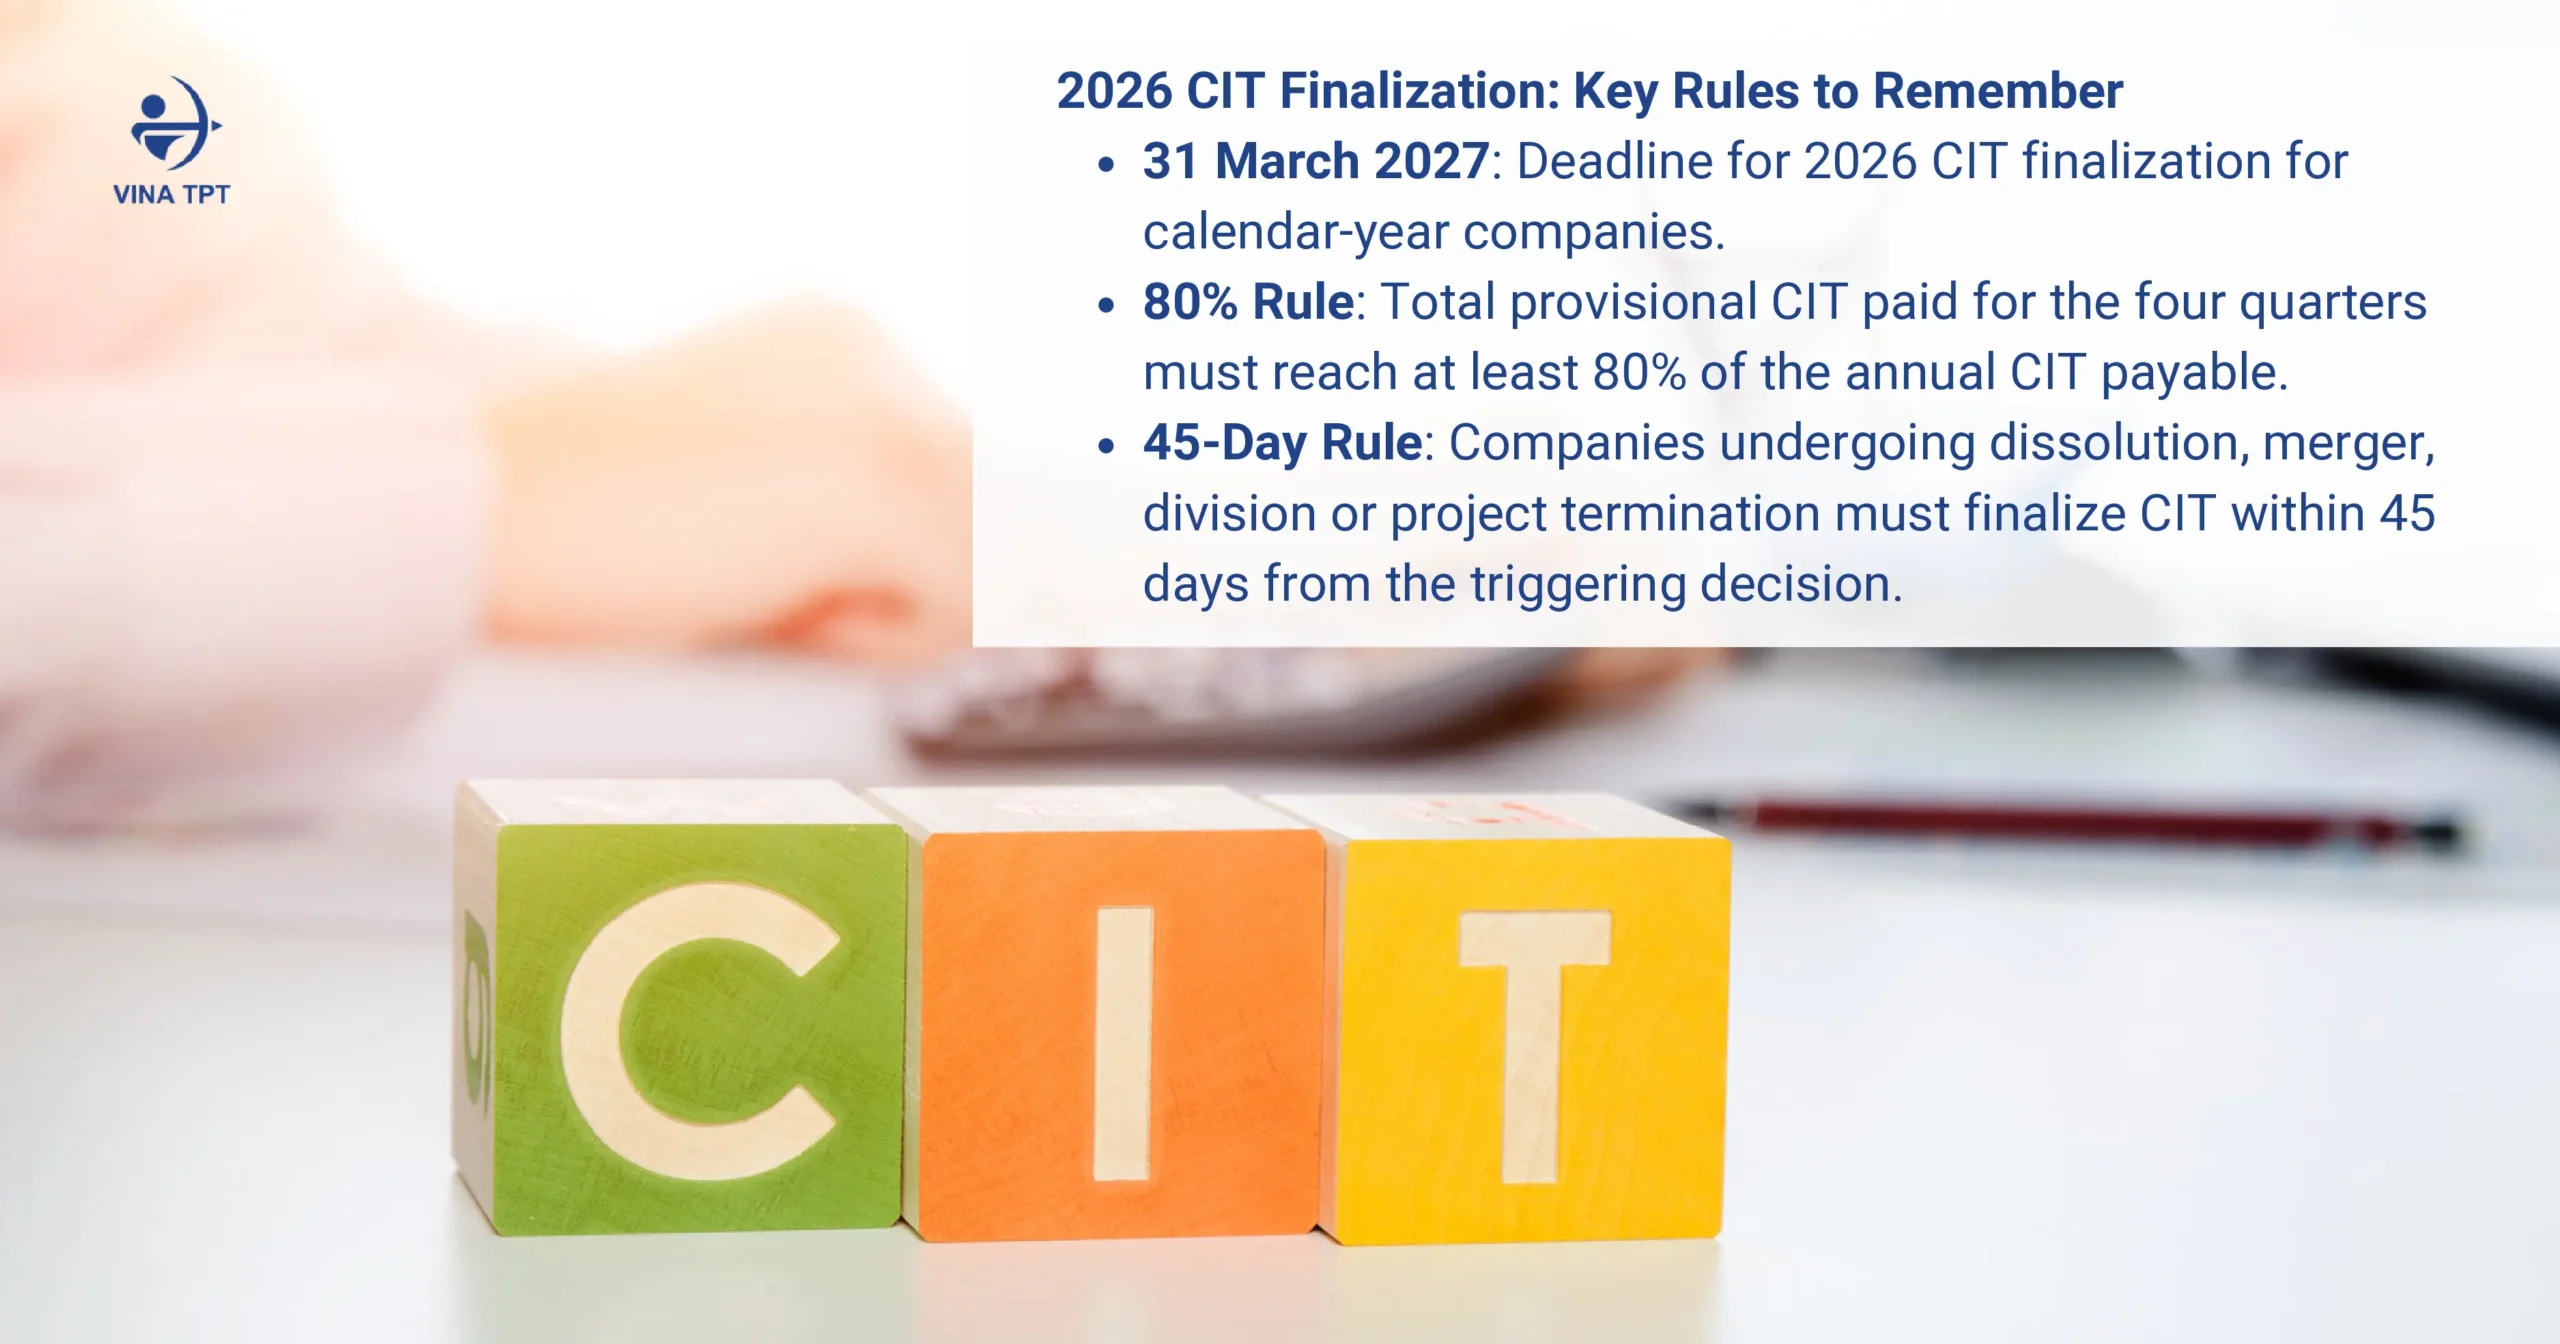
  • Filing deadline: For companies whose financial year matches the calendar year (1 January 2026 to 31 December 2026), the deadline for the 2026 CIT finalization return and the annual financial statements is 31 March 2027. For companies whose financial year does not follow the calendar year, the deadline is 90 days from the end of that financial year.
  • The 80% provisional-CIT rule: Under current rules, total provisional CIT paid over the four quarters of the tax year must not be less than 80% of the CIT due on the annual finalization return. If the four quarterly payments fall short of that 80% threshold, late-payment interest (0.03% per day) is charged on the shortfall from the day after the Quarter 4 payment deadline until the date the tax is actually paid.
  • 2026 support-policy update: If provisional CIT is deferred under a 2026 Government support measure (such as Decree 245/2026/ND-CP), the deferral changes only the payment date of the quarterly provisional tax. It does not change the filing deadline for the 2026 CIT finalization return, which must still be filed by 31 March 2027.
  • Event-based finalization: If a company is dissolved, bankrupt, divided, merged, converted in ownership, or ends a project in 2026, the CIT finalization file must be filed no later than the 45th day from the date of the decision that triggers the event. The company does not wait until the end of the financial year.

Explore Tax Advisory Services

annual-tax-finalization-in-vietnam-2026

3. PIT Finalization the Company Must File

When carrying out CIT and PIT finalization for 2026, the company acts as the income-paying organization. It must prepare the PIT finalization return (Form 05/QTT-TNCN) for all salary and wage income paid in 2026.

Key deadlines and legal points:

  • Deadline for the company (income-paying organization): The deadline to file the 2026 PIT finalization return for individuals who have authorized the company to finalize on their behalf is 31 March 2027.
  • Deadline for individuals who finalize directly: Individuals who must finalize directly with the tax office, those with income from more than one source, or foreign specialists whose contracts have ended, must file by the last day of the fourth month after the calendar year ends, which is 30 April 2027.
  • PIT rules updated from 2026: The 2026 finalization period applies the amended Personal Income Tax Law 2025 and Decree 253/2026/ND-CP (effective from 1 July 2026). The company must split income, family deductions, and tax-exempt items arising before and after 1 July 2026 exactly as the General Department of Taxation’s transitional guidance requires, so that tax withheld from staff is calculated correctly. The company finalizes only for individuals who have signed a labor contract of three months or more and who have submitted a valid tax-finalization authorization in the prescribed form.

4. Related-Party Forms Filed with CIT Finalization

For FDI companies, and for domestic companies that had related-party transactions in 2026, the related-party transaction return set is a mandatory part of the file and must be filed together with the CIT finalization return.

The related-party file submitted with finalization includes:

  • Appendix I: Information on related-party relationships and related-party transactions.
  • Appendices II and III: The list of information and documents to be provided in the Local File and the Master File.
  • Appendix IV: The Country-by-Country Report of the ultimate parent company (CbCR), if the company is in scope.

A company that bought or sold goods or services, borrowed, transferred technology, or paid a management fee to its parent or to other group companies must prepare and keep Transfer Pricing Documentation at its head office before finalization, ready to produce if the tax office inspects or audits.

5. Documents to Prepare Before the Deadline

For the tax finalization Vietnam period to run smoothly and avoid last-minute blocks, the accounting team must lock the full legal file before 31 March 2027. Do not wait until the filing week to start the reconciliation. The most common risk at this stage is not a missing return form. There is a shortage of original vouchers to explain and defend the figures already recorded in the books.

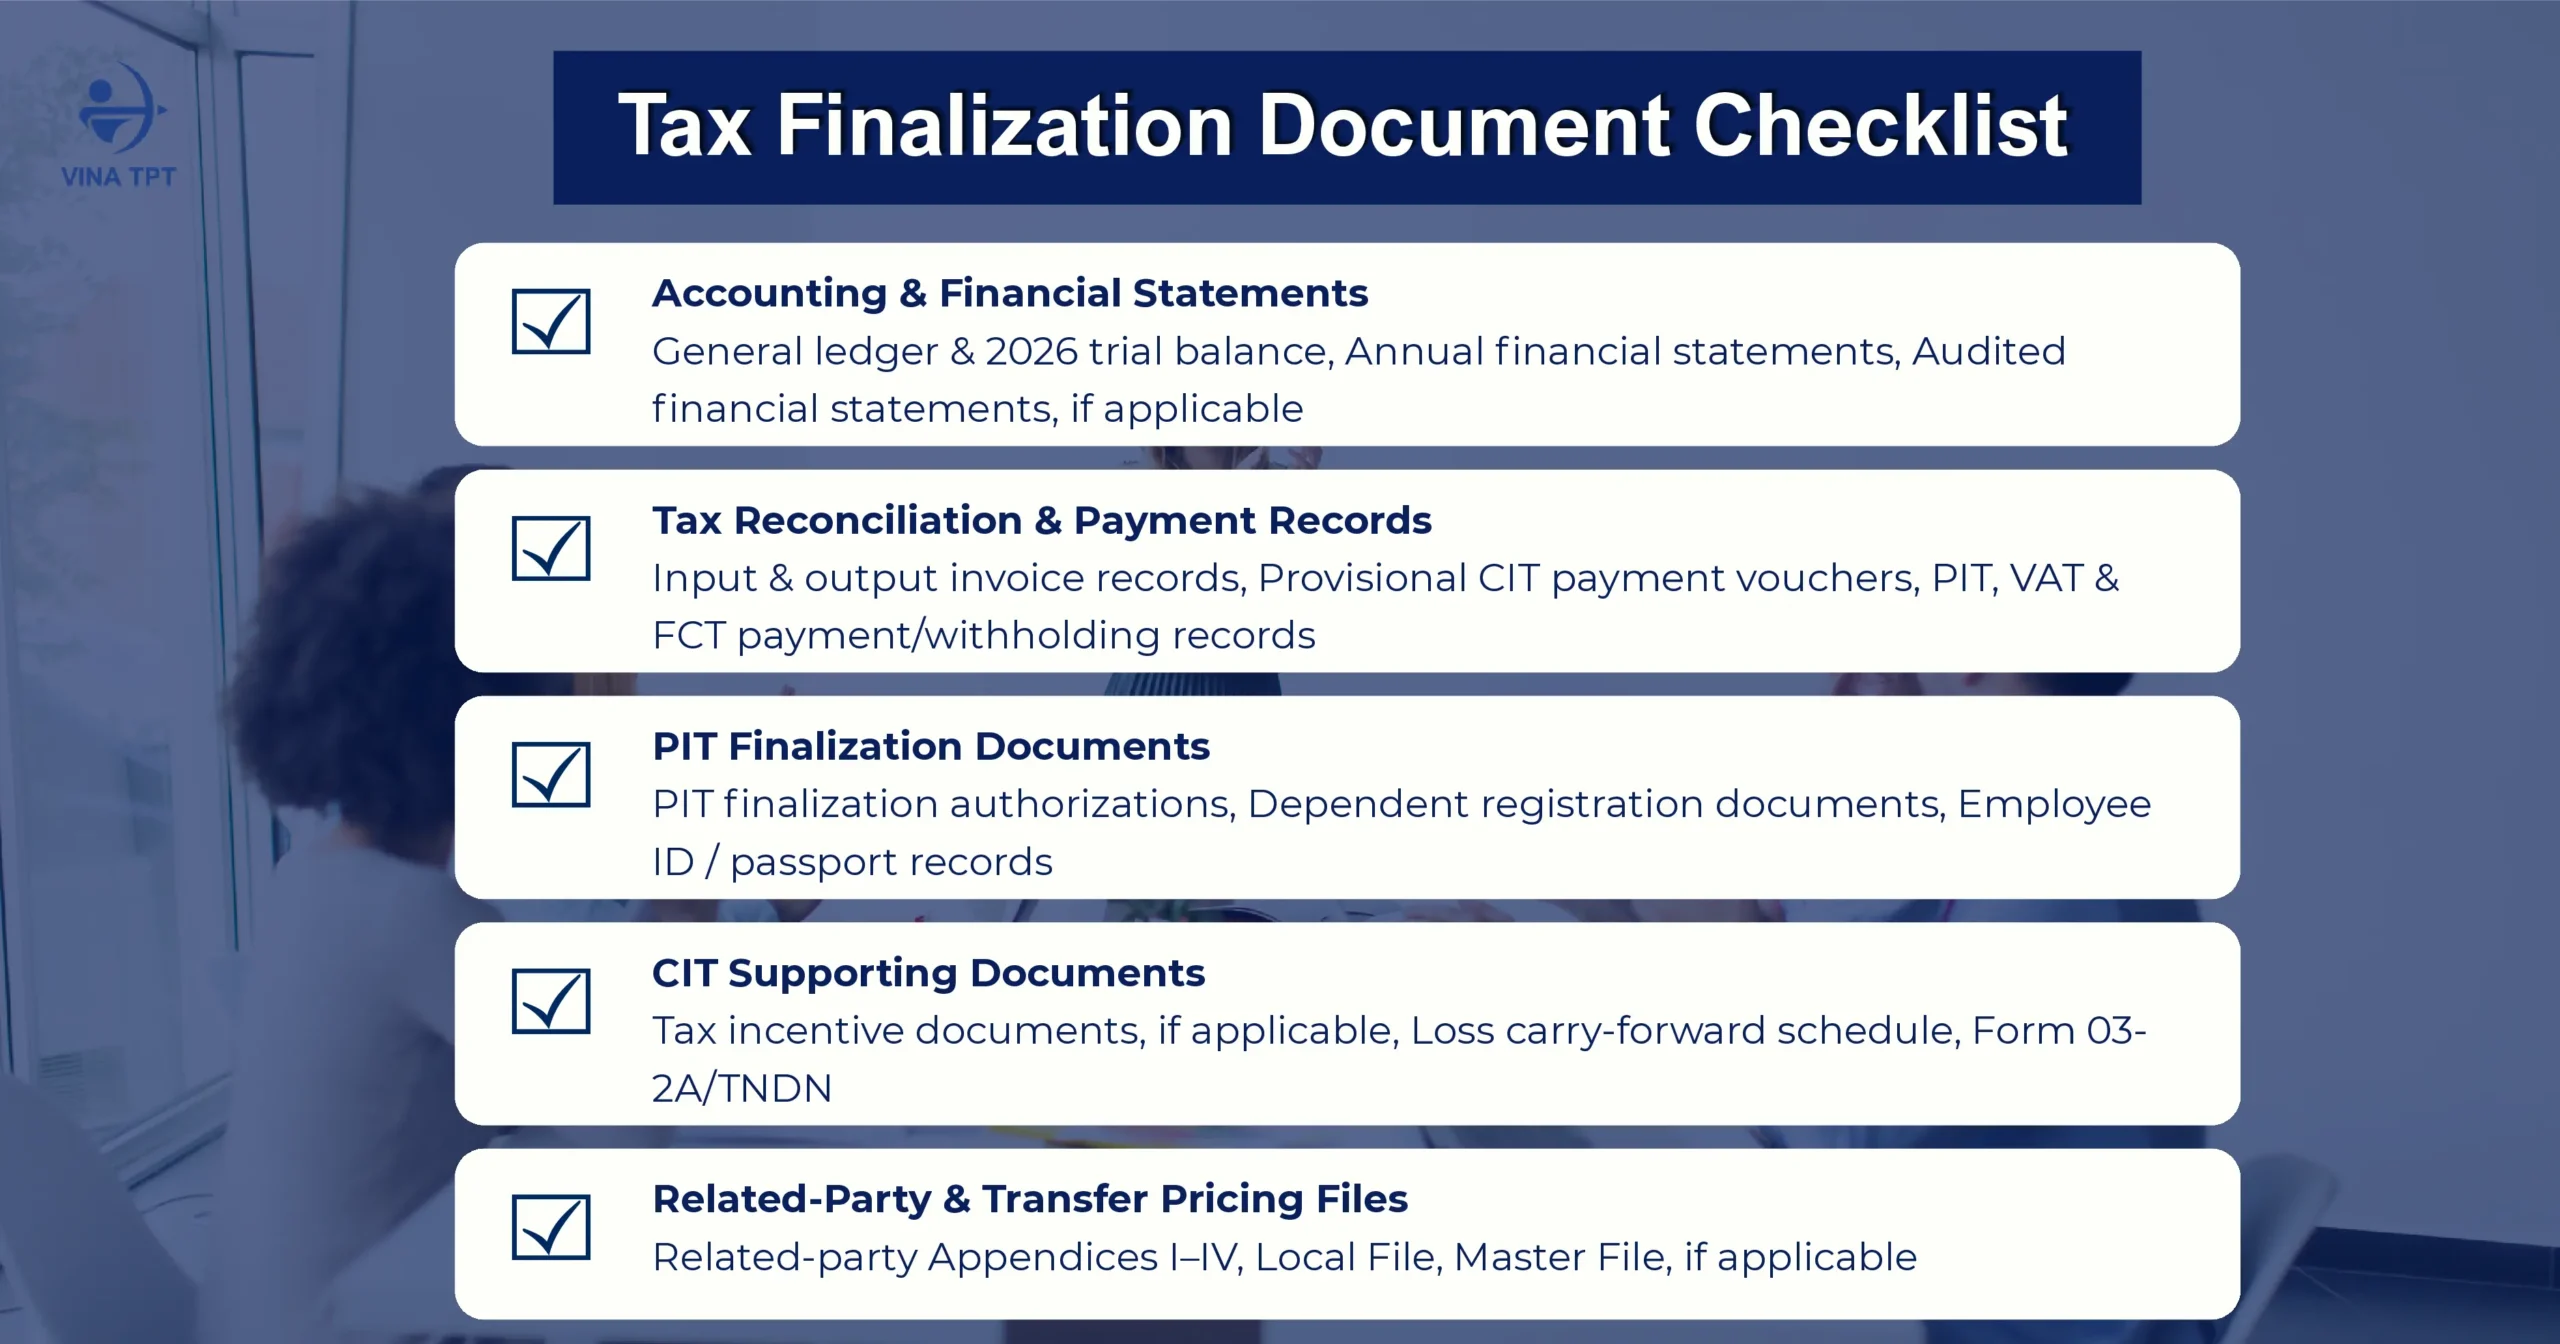
A legally complete annual tax-finalization file must cover these five core document groups:

  • VAS books and financial statements: This is the foundation of the file. Accounting must close the general ledger for all revenue, expense, tax, and capital accounts, together with the 2026 trial balance. For FDI companies that must be audited, the independently audited annual financial statements are the only legal basis for reconciling the CIT finalization return. Any gap between the finalization figures and the audit report will be the first point the tax office questions in an inspection.
  • Tax reconciliation and credit vouchers: This group covers the input and output invoice listings, VAT payment vouchers, the four quarterly provisional CIT payment vouchers, PIT withholding vouchers, and Foreign Contractor Tax (FCT) payment vouchers where payments were made abroad. A 100% match between the listings, the general ledger, and the periodic returns already filed during the year avoids complex supplementary filings before the year is closed.
  • PIT finalization authorization and deduction file: This applies only when the company finalizes on behalf of employees. The file includes the dependent-registration form, the PIT finalization authorization, and copies of personal identification (citizen ID or passport). A missing authorization, or a dependent registration filed after the deadline, will cause the family deduction to be excluded from the annual finalization – even if the income was actually withheld.
  • Tax-incentive file and loss-carry-forward schedule: This covers the legal documents confirming eligibility for CIT incentives, if any, and the schedule tracking losses carried from prior years into 2026 (Form 03-2A/TNDN). Without a valid loss-carry-forward schedule, prior-year losses will be disallowed as a deduction when CIT for this period is calculated.
  • Related-party transaction file (transfer pricing): This covers Appendices I–IV filed with the CIT finalization return, plus the transfer-pricing documentation (Local File and Master File). Every figure in the appendices must match the books exactly for intercompany loans, management fees, royalties, and internal purchases and sales. Leaving this work until March often produces large errors, because data collection and price benchmarking take time.

Reviewing and standardizing all five groups before the deadline turns tax finalization from a high-pressure risk review into a fast, safe, and fully controlled periodic filing.

annual-tax-finalization-in-vietnam-2026

6. Common Finalization Mistakes in 2026

The 2026 finalization period often produces reassessments and late-payment interest not because the company forgot to file, but because of these four data gaps.

  • Missing the 80% provisional CIT threshold: The company underestimates Quarter 4 revenue and expenses, so total provisional payments over the four quarters fall short of 80% of the CIT due on finalization. The tax system charges late-payment interest on the shortfall even if the annual return is filed on time. The way to limit this is to review Quarter 4 figures before locking the provisional payment, rather than scaling Quarter 3 revenue by an estimate.
  • PIT finalization for the wrong authorized persons: The company accepts an authorization to finalize for an individual with income from two or more sources, or for a person who does not meet the conditions to authorize. When the tax office reconciles the file, that portion of the company finalization is rejected. The employee must still finalize personally, and the company must explain the authorizations it accepted.
  • Missing related-party appendices: The company has loans, management fees, royalties, or purchases and sales with related parties, but does not file Appendices I–IV with the CIT finalization return. A missing appendix is a basis for the tax office to review interest expense and payments to related parties. Interest expense can be capped at 30% of EBITDA if the deduction conditions are not proven.
  • A gap between the financial statements and the CIT return: Accounting profit before tax on the financial statements differs from taxable income on the finalization return, and the company has no reconciliation of the adjustments: non-deductible expenses, temporary differences, tax incentives, or loss carry-forward. This is the first point an inspection asks about, because the two sets of figures must lead to the same taxable result.

All four errors can be handled if provisional payments, PIT authorization eligibility, related-party appendices, and the profit-adjustment schedule are reconciled before 31 March 2027.

7. How Vina TPT Supports Annual Tax Finalization

Preparing the 2026 CIT and PIT finalization file requires deep knowledge of VAS accounting and Vietnam’s Law on Tax Administration. Vina TPT provides a full-package annual tax-finalization service so FDI companies can close the year with confidence:

  • Data review and health check: Review the full 2026 books, flag non-deductible expense risks, and reconcile the 80% provisional CIT threshold before the filing deadline.
  • CIT and PIT finalization file: VAS financial statements, the CIT finalization return, the PIT finalization return, and filing on the company’s behalf through the e-tax system.
  • Related-party reporting (transfer pricing): Prepare Appendices I-IV and build a legally compliant transfer-pricing file (Local File and Master File).
  • Representation before the tax office: Explain figure differences directly and defend reasonable expenses during tax inspections.

Are you ready for the 2026 tax finalization period? Contact Vina TPT so our CPAs and tax specialists with more than 10 years of experience can review and lock an accurate file before the deadline.

BOOK A FREE CONSULTATION

Checklist Tax Registration Requirements After Your Business Setup Vietnam

checklist-tax-registration-requirements-after-your-business-setup-vietnam

checklist-tax-registration-requirements-after-your-business-setup-vietnam

You already hold the Enterprise Registration Certificate (ERC), so why can you still not issue invoices, open a bank account, or record the first transaction? The legal entity exists, but the tax and payment systems have not been switched on. Without a Chief Accountant, a registered digital signature, a configured e-tax account, or valid e-invoices, the company is not yet legally ready to operate in practice.

Once the business setup Vietnam process is complete, foreign investors must address a series of post-establishment obligations to prepare their companies for operations. This article from Vina TPT walks through the next execution steps in priority order: appointing key positions, completing initial tax registration Vietnam, opening bank accounts and contributing capital, filing the first periodic tax returns, registering e-invoice Vietnam before the first invoice is issued, and registering a social-insurance unit code if you are about to hire staff.

1. Appoint Key Positions, Seal and Digital Signature

One of the first compliance priorities after business setup Vietnam is configuring the company’s tax registration and accounting systems correctly. This establishes the foundation for subsequent tax filings and financial reporting.

The Enterprise Registration Certificate (ERC) already records the Legal Representative. Immediately after that milestone, the investor’s first urgent task is to appoint a Chief Accountant (or the person in charge of accounting) – either an in-house hire or a professional outsourced accounting service. Under Vietnam’s Law on Accounting, this title is mandatory for every FDI company.

In practice, commercial banks require the Chief Accountant appointment decision when the company opens its capital account. Opening that account is the step that lets the investor transfer charter capital within the 90-day deadline after the ERC, or within the longer schedule stated on the IRC. Without the account, the contribution cannot be recorded on time.

The next step is to engrave the company seal so the initial accounting and tax registration dossiers can be completed and legally valid. The company then purchases a digital signature (CA Token). The token is the electronic identity used to log in to the General Department of Taxation portal, register e-invoices and sign periodic tax returns. These tools support the company’s initial tax registration Vietnam procedures and enable electronic submissions through the relevant government portals.

2. Initial Tax Registration

Although the company’s tax code is issued automatically with the ERC, completing the initial tax registration Vietnam requirements remains an important step before the business begins regular tax reporting. The core configuration items include:

  • Accounting regime and financial year: Register the enterprise accounting regime (Circular 200/2014/TT-BTC or Circular 133/2016/TT-BTC) and confirm the financial year (usually the calendar year from 1 January to 31 December).
  • Fixed-asset depreciation method: Declare the depreciation method applied under Ministry of Finance rules.
  • E-tax account and VAT method: Declare the Value-Added Tax calculation method (credit method or direct method) as the basis for setting up VAS books.
  • Digital identity and corporate VNeID: Activate the company’s electronic identity account and link the Legal Representative’s VNeID for two-factor authentication on the National Public Service Portal and the Tax Portal.

Declaring the wrong VAT method or choosing the wrong filing period at this step leads to complex amendment procedures and interrupts the company’s input and output invoice flow.

3. Open the Bank Account and Contribute Capital

After completing business setup Vietnam, foreign investors should arrange the appropriate corporate bank accounts, including a Direct Investment Capital Account (DICA) where required, to facilitate timely capital contributions. The statutory deadline is 90 days from the date the ERC is issued (unless the Investment Registration Certificate (IRC) records a longer, staged contribution schedule).

The bank file for an FDI company typically requires the following documents:

  • Notarized copies of the ERC, IRC, and company charter.
  • A valid visa, Temporary Residence Card (TRC), or passport of the Legal Representative.
  • The decision appointing the Chief Accountant or the person in charge of accounting, plus personal identification.
  • Specimen-signature and seal registration for the account holder and the Chief Accountant.

Besides the DICA, the company also needs a VND current account for day-to-day commercial receipts and payments.

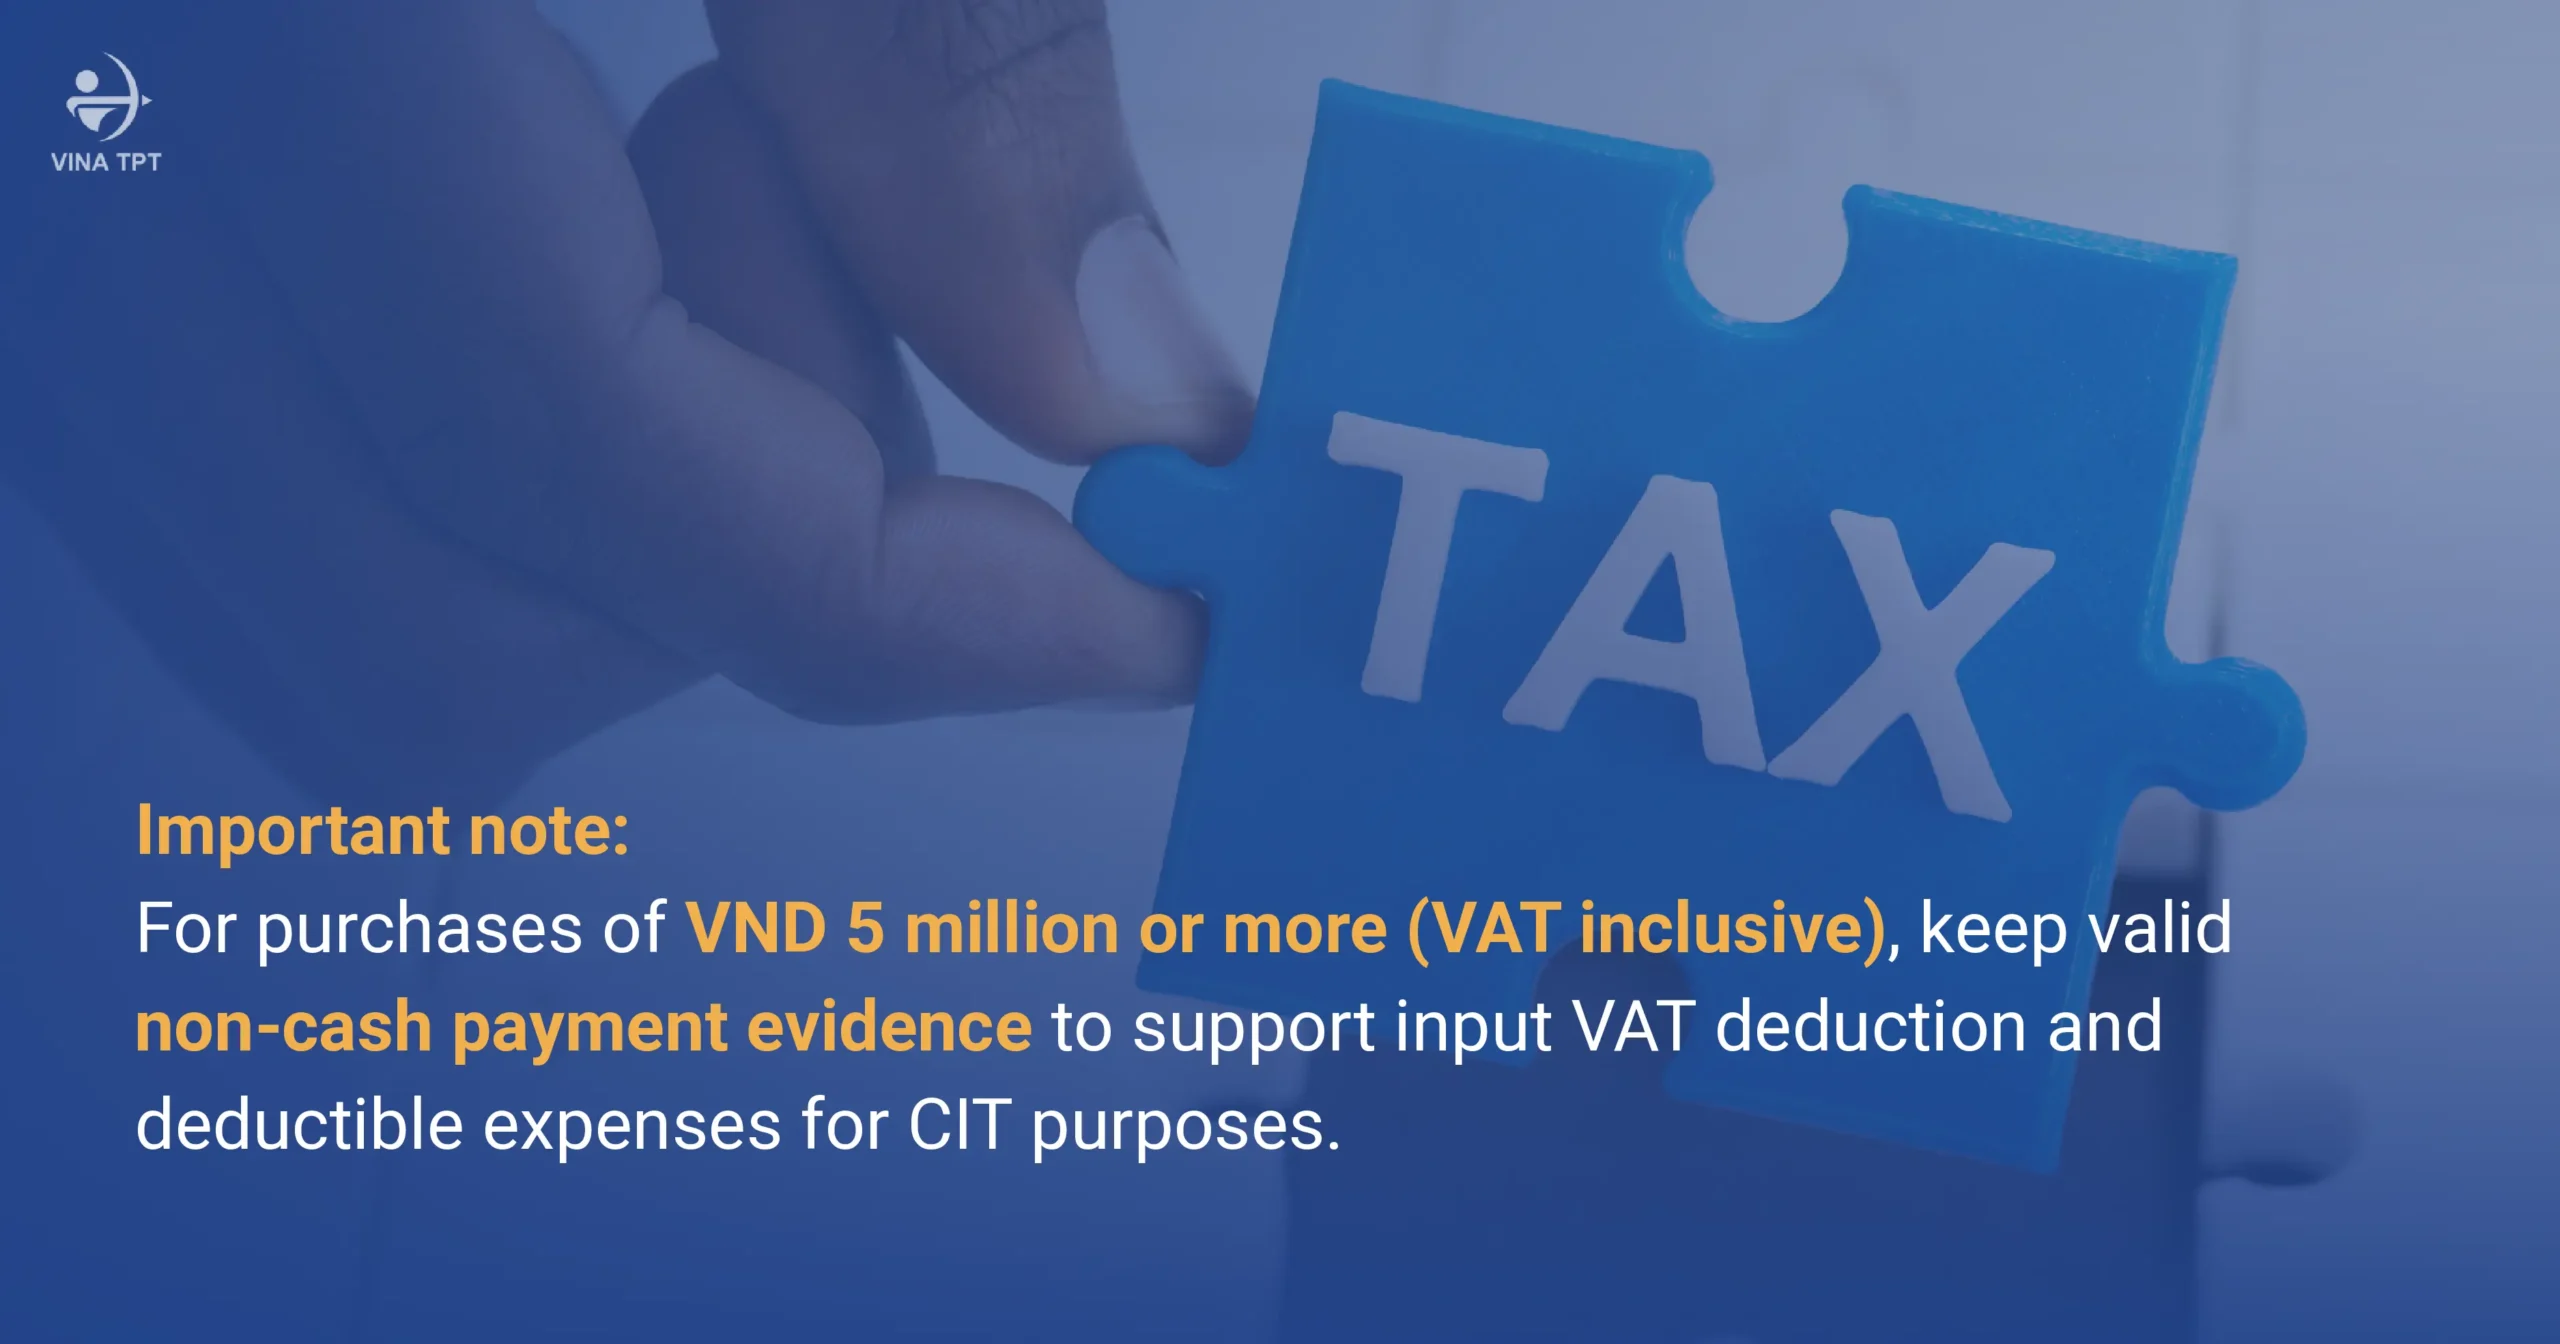
Important note on deductible costs: Under tax-administration rules, every purchase of goods or services of VND 5 million or more (VAT inclusive) must have a non-cash payment voucher (a transfer from the company’s bank account) to qualify for input VAT credit and for a reasonable expense when Corporate Income Tax is determined. Late charter-capital contribution through the DICA triggers administrative fines and can lock the company’s international banking functions.

checklist-tax-registration-requirements-after-your-business-setup-vietnam

Explore Vina TPT’s Company Formation Services

4. File the First Periodic Tax Returns

As soon as the ERC is issued and the tax code is activated, the company has periodic tax-compliance duties under the law — even if it is newly formed and has no revenue, no costs, and no staff.

Initial periodic filing obligations include:

  • VAT return: File monthly or quarterly (newly formed companies are usually quarterly VAT filers). If there are no transactions, the company must still file a nil return (select the “no arising” indicator).
  • PIT return: File quarterly if income was paid to employees in the period.
  • Self-assessed provisional CIT: The company determines quarterly provisional Corporate Income Tax if it has profit. No quarterly CIT return is filed; only the annual finalization is required.
  • Foreign Contractor Tax (FCT): File and pay on each arising payment if the company pays costs to overseas counterparties or service providers (Google, Meta, international software services, and similar).

>>> You may also be interested in: Tax Tips for Small Businesses in Vietnam to Avoid Mistakes

Updated legal note: From 1 January 2026, the business license fee is abolished under the new Government rules. Companies completing business setup Vietnam from 2026 no longer file a business-license-fee return or pay the annual fee.

5. Register E-Invoices Before You Issue the First Invoice

Registering e-invoice Vietnam (tax-authority-coded electronic invoices under Circular 78/2021/TT-BTC) is mandatory before the company records any sale of goods or supply of services. Until e-invoice registration is complete, the company must not issue commercial invoices. Issuing unofficial invoices or recording revenue outside the e-invoice system is a tax-law violation.

The e-invoice registration steps are:

  1. Choose a certified e-invoice solution provider.
  2. File the e-invoice registration form (Form 01/ĐKTĐ-HĐĐT) with the managing tax office, signed with the digital signature.
  3. Wait for the tax office’s approval (usually within one working day).

Every detail on the e-invoice template, company name, tax code, and head-office address, must match the ERC 100%. Even a small character or administrative-place-name discrepancy can lead the tax office to reject the invoice or the buyer to refuse the VAT credit. The company may issue invoices only after the digital signature and the e-invoice template have been confirmed as active on the General Department of Taxation portal.

6. Register Social Insurance If You Will Hire Staff

If the company plans to hire local or foreign staff to work formally right after incorporation, registering a social-insurance unit code is mandatory. Even if the company has only one or two employees on labor contracts, first-time registration for social insurance, health insurance, and unemployment insurance must be completed before the first official payday.

The social-insurance unit code is linked directly to the company’s quarterly Personal Income Tax (PIT) finalization data.

Note for expatriates: If a founder or foreign specialist works in Vietnam, the company must at the same time obtain a Work Permit or a confirmation that the person is exempt from a Work Permit, then register compulsory social insurance under the rules for foreign workers. Without a valid Work Permit, the foreign employee’s salary can be disallowed as a reasonable expense when Corporate Income Tax is calculated.

7. 30-Day Sequence After Business Setup in Vietnam

To help investors see the exact execution path, here is the mandatory 30-day sequence to follow as soon as the Enterprise Registration Certificate (ERC) is in hand:

7.1. Days 1-7 (initial legal setup)

  • Issue the decision appointing the Chief Accountant or the person in charge of accounting.
  • Engrave the company seal (if used) and purchase a company digital signature (CA Token).
  • File initial tax registration with the managing tax office.
  • Activate the Legal Representative’s VNeID digital identity so it connects to the public-service system.

7.2. Days 7-15 (finance and banking)

  • Open the Direct Investment Capital Account (DICA) and the VND current account at a commercial bank.
  • Notify the tax office of the bank accounts (via the digital signature).
  • Prepare funds and transfer charter capital from abroad into the DICA (complete within the 90-day deadline).

7.3. Days 15-30 (activation and periodic compliance)

  • Select an electronic invoicing provider and complete the e-invoice Vietnam registration process before issuing the company’s first invoice.

  • Set up the accounting books under VAS.

  • Register the social-insurance unit code if hiring has started.

  • Get ready for the first VAT and PIT filing period.

Reminder for FDI companies: Besides tax duties, foreign-invested companies must also meet the quarterly project-implementation reporting deadline on the National Foreign Investment Information System – even while the project is still in preparation and has no revenue.

8. How Vina TPT Handles Post-Setup Tax Registration

Handling the full tax registration Vietnam chain after incorporation often takes time and creates legal errors for foreign investors who are not yet familiar with Vietnam’s administrative system. Vina TPT provides an end-to-end advisory and implementation package that standardizes the entire post-establishment tax-compliance system:

  • Chief Accountant appointment and initial tax filing: Supplying a practicing-qualified Chief Accountant, registering the digital signature, activating corporate VNeID, and completing the initial tax-registration file accurately.
  • E-invoice configuration and VAS books: Supporting template registration and activation of e-invoice Vietnam, and setting up VAS books that match the industry.
  • Tax and social-insurance filing on the company’s behalf: Full handling of periodic returns (VAT, CIT, PIT, FCT), registration of the social-insurance unit code, and payroll for staff.
  • FDI legal support: Tracking the 90-day charter-capital deadline, filing periodic FDI investment reports, and supporting Work Permit and TRC applications for foreign staff.

Have you just completed business setup Vietnam and are preparing for the first invoice? Contact Vina TPT so our specialists and CPAs with 10-20 years of experience can review and activate the full initial tax checklist for your company.

checklist-tax-registration-requirements-after-your-business-setup-vietnam

BOOK A FREE CONSULTATION

VNeID for Foreigners: How to Register in Vietnam 2026

How to register VNeID for foreigners

From 28 September 2026, electronic identification accounts for foreigners are no longer classified as Level 1 or Level 2. Under Decree 320/2026/ND-CP, which amends Decree 69/2024/ND-CP, foreign nationals follow a single registration procedure.

The updated rules also broaden eligibility. Foreign nationals who have lawfully entered Vietnam can apply when needed, extending eligibility beyond those legally residing in the country.

This guide to VNeID for foreigners explains the benefits, eligibility requirements, documents to prepare, application steps and processing times.

1. Why Should Register VNeID for Foreigners?

VNeID is Vietnam’s national electronic identification application. It allows foreign nationals to manage their digital identity, access integrated information and documents, and use services connected to the electronic identification and authentication system.

The practical value of VNeID for foreigners lies in supporting everyday needs, including banking verification, online administrative procedures and access to electronic documents.

Identity Verification for Banking Services

At participating banks, VNeID supports identity verification and biometric matching. Completing these checks helps foreign customers meet the requirements for digital banking functions, including online transfers and payments.

Applicants must still satisfy the bank’s account opening requirements and provide the necessary documents. Having VNeID does not automatically allow a foreign customer to open an account entirely online at every bank.

Access to Online Public Services

Foreign nationals can use their electronic identification accounts to sign in, verify their identity and access procedures through public service systems that support VNeID.

This makes it easier to submit applications and receive notifications online, reducing the need to visit an authority for every stage of a procedure. Steps requiring physical attendance must still be completed as instructed.

Management of Electronic Documents

VNeID enables users to access information and documents integrated into their accounts, such as residence card information where integration and use are supported.

When handling procedures or transactions, receiving authorities and organisations use integrated information according to the applicable regulations. This helps reduce repeated declarations and requests to present original documents or copies already available through the application.

Registration of a Company’s Electronic Identification Account

For foreign investors who have established a company in Vietnam and also serve as its legal representative, a personal VNeID account supports registration of the company’s electronic identification account.

This helps the business verify its identity and access online public services available to organisations.

These benefits depend on the information integrated into the account and the systems supported by each bank, authority or service provider. Check the receiving organisation’s requirements before using VNeID for a particular transaction.

2. Who Can Apply for VNeID in Vietnam?

Foreign nationals can apply for an electronic identification account when needed if they:

  • Have lawfully entered Vietnam; or
  • Are legally residing in Vietnam.

Eligibility for VNeID for foreigners is not limited to employees or investors. Employment in Vietnam is therefore not stated as a prerequisite under this provision.

Foreign children under 14 and individuals under guardianship or representation can also register. They must follow the procedure involving their representative or guardian.

Do Foreigners Still Need a Level 2 Account?

From 28 September 2026, electronic identification accounts for foreign nationals are issued without a level classification.

Older guides may describe separate Level 1 and Level 2 procedures. Applicants should follow the updated registration requirements rather than rely on those earlier instructions.

non resident can apply VNeID for foreigners

3. What Should You Prepare Before Registration?

Preparing your documents and contact information before visiting the immigration authority can make the process easier. The following checklist covers the main requirements and practical preparations for VNeID for foreigners.

Passport or International Travel Document

  • Applicants must present their passport or another document valid for international travel.
  • Check your personal details before the visit so that the information you provide is consistent, particularly your full name, date of birth, nationality and document number.

Mobile Phone Number Registered in Your Name

  • Foreign applicants must provide a mobile phone number registered in their own name.
  • Check your subscription details with your mobile service provider. Using a number does not necessarily mean that the subscription is registered under your identity.
  • For children under 14 and applicants under guardianship or representation, the representative or guardian uses a number registered in their own name.

Email Address, if Available

  • Provide an email address if you have one. Email is one of the channels through which the registration result may be communicated.
  • Choose an address you check regularly and confirm that it is entered correctly.

Information Required by Form TK01

  • Applicants must provide complete and accurate information using Form TK01, the prescribed electronic identification account application form.
  • This includes the registered mobile phone number, email address if available, and any additional information requested for integration into the national identification application.

Smartphone for Using the Application

  • The receiving officer guides applicants in downloading, installing and entering information in the application.
  • Bringing a compatible smartphone with internet access is therefore useful. Make sure you can install the application and access the contact channels provided during registration.
What to prepare What to check
Passport or international travel document Bring it to present to the receiving officer
Mobile phone number Confirm that it is registered in the required person’s name
Email address Prepare an accessible address, if available
Application information Ensure your details match your travel document
Smartphone Check that it can install and run the application

Where Do Foreigners Register?

Applications for VNeID for foreigners are made in person at the immigration authority of the provincial-level police.

Before travelling, confirm the office address, opening hours and any local instructions concerning appointments or application reception.

This is particularly helpful if you need time away from work, must travel to the office, or will attend with a child or represented applicant.

4. How to Register for VNeID in Vietnam

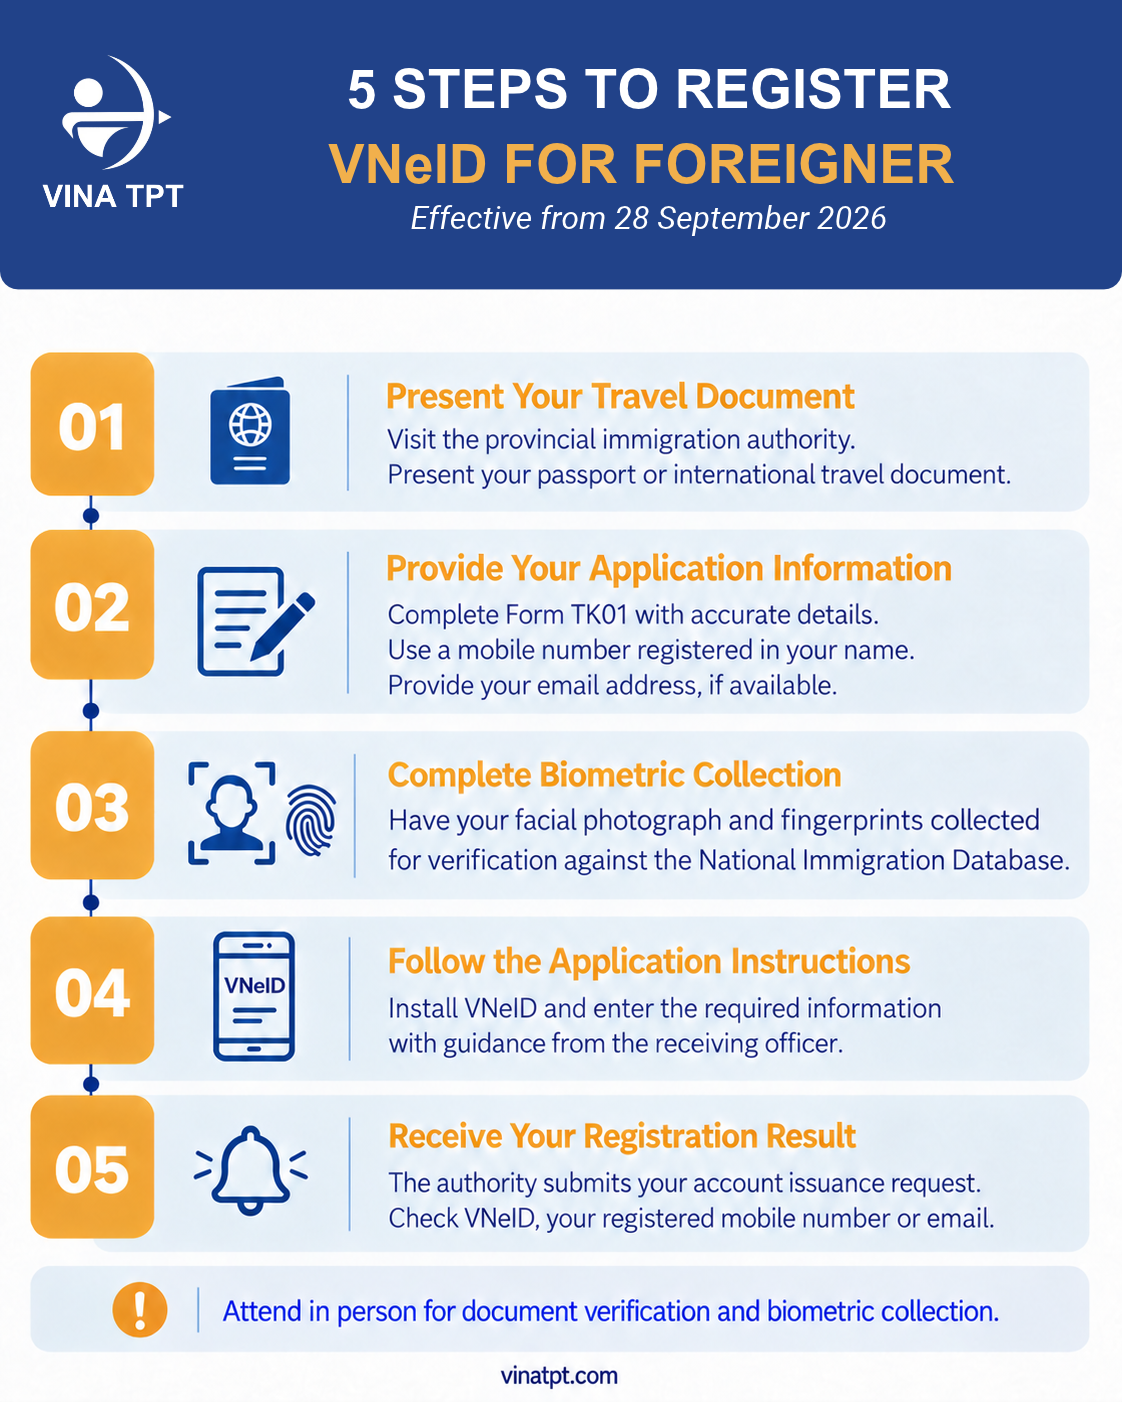
The registration process involves presenting your identity document, providing application information and completing biometric collection.

Step 1: Present Your Travel Document

Visit the immigration authority, request an electronic identification account and present your passport or international travel document.

An in-person visit forms part of the registration procedure for VNeID for foreigners. Downloading the application alone does not complete the process.

Step 2: Provide Your Application Information

Provide complete and accurate information using Form TK01.

Give the receiving officer your registered mobile phone number, email address if available, and any additional information you wish to integrate into the application.

Review your details carefully. If you notice an incorrect name, passport number or contact detail, inform the officer before submission.

Step 3: Complete Biometric Collection

The receiving officer enters your information into the electronic identification and authentication system.

The officer also captures your facial photograph and collects your fingerprints to authenticate your information against the National Immigration Database.

Applicants must attend in person for these biometric steps.

Step 4: Follow the Application Instructions

The officer guides you in downloading and installing the national identification application and entering the required information.

If your device encounters a technical problem, explain it to the officer so that you can receive appropriate guidance.

Step 5: Receive Your Registration Result

After completing the necessary steps, the immigration authority sends the account issuance request to the authority managing and operating the electronic identification and authentication system.

The result is communicated through one of these channels:

  • The national identification application;
  • Your registered mobile phone number; or
  • Your email address.

Keep these channels accessible and follow the instructions accompanying the notification.

5 steps to register VNeID for foreigners

5. How Long Does Registration Take?

The processing time for VNeID for foreigners depends on whether the applicant’s facial photograph and fingerprints are already available in the National Immigration Database.

Database status Statutory processing period
Facial photograph and fingerprints are already available No more than 2 working days
Facial photograph and fingerprints are not yet available No more than 5 working days

These periods are measured in working days. Allow for weekends and public holidays when estimating when you may receive the result.

If no notification arrives after the applicable period, contact the receiving authority for guidance. First, check the application, phone messages and email.

6. Registration for Foreign Children Under 14

Foreign children under 14 must visit the immigration authority together with their representative or guardian.

The representative or guardian uses a mobile phone number registered in their own name to provide the information and register the child’s electronic identification account.

The same arrangements apply to foreign nationals under guardianship or representation.

Families should arrange for both the applicant and the representative or guardian to attend, rather than assume that the representative can complete the procedure alone.

7. Vina TPT’s Support with VNeID for Foreigners

Vina TPT helps foreign nationals understand the registration requirements and prepare the necessary documents and information. We guide clients through the process so they can plan their visit and reduce difficulties caused by incomplete or inconsistent details.

For foreign investors who also serve as the legal representative of a Vietnamese company, we provide guidance on registering the company’s electronic identification account after personal registration has been completed.

Applicants must still attend the relevant authority for verification and biometric collection as required.

Contact Vina TPT for support with VNeID for foreigners and guidance on the registration procedure applicable to your circumstances.

Legal basis: Decree 69/2024/ND-CP, as amended by Decree 320/2026/ND-CP. This article covers the registration procedure for foreign nationals effective from 28 September 2026.

BOOK A FREE CONSULTATION

Vietnam Labor Compliance: 7 Areas Employers Should Review

Vietnam Labor Compliance

Vietnam Labor Compliance_ 7 Areas Employers Should Review

Vietnam labor compliance: Employment contracts, payroll records and work permits are part of a company’s day-to-day operations. Errors in these areas can also lead to administrative fines and obligations to pay employees amounts owed. Based on the information provided on Decree 283/2026/ND-CP, effective from September 10, 2026, sets out administrative penalties for violations in the fields of labor and social insurance.

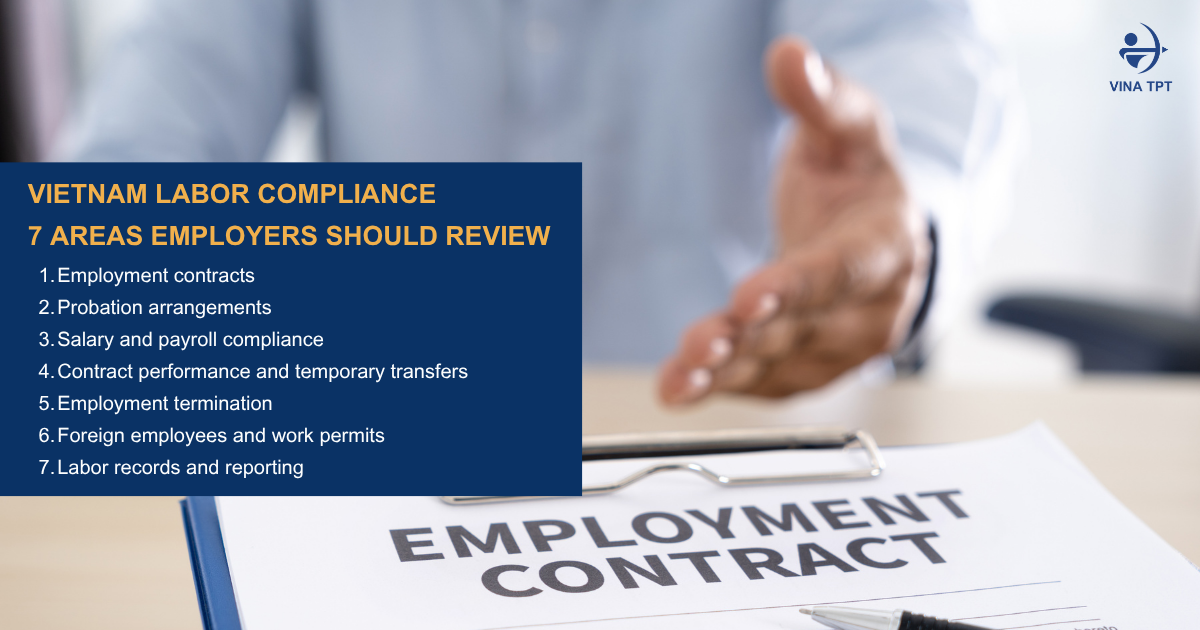
For businesses in Vietnam, this makes it important to review everyday HR practices, from employment contracts and payroll to work permits and labor records. Below are seven areas employers should pay particular attention to.

1. Employment contracts

Employers may face penalties for failing to sign a written employment contract when required, using the wrong type of contract, or omitting essential terms. Retaining an employee’s original identity documents, diplomas or certificates, and requiring a deposit or other asset as security for the contract, are also identified as violations.

The supplied material states that fines for violations concerning the form, type or contents of an employment contract range from VND 2 million to VND 25 million, depending on the number of affected employees. Retaining original documents or requiring a deposit may result in a fine of VND 20 million to VND 25 million.

Legal reference: Article 15 of Decree 283/2026/ND-CP.

2. Probation arrangements

A business should check how often it applies probation to a position, how long probation lasts and what salary the employee receives. The material specifies that probation should not be applied more than once for the same job, should not exceed the statutory period, and should be paid at no less than 85% of the salary for that job.

Employers must also communicate the probation result and enter into an employment contract when the employee meets the requirements in cases prescribed by law. Some violations carry fines of VND 500,000 to VND 1 million. Applying probation more than once, exceeding the permitted period or paying probation salary incorrectly may result in fines of VND 2 million to VND 5 million. An employer may also be required to pay the outstanding salary or enter into an employment contract.

Legal reference: Article 16 of Decree 283/2026/ND-CP.

3. Salary and payroll compliance

Payroll compliance extends beyond calculating monthly salaries. According to the supplied material, businesses may be fined VND 5 million to VND 10 million for certain failures involving salary scales, payroll tables, labor norms or bonus policies. These include failing to establish or disclose them, failing to consult the workplace employee representative organization when required, providing a noncompliant payslip, or failing to ensure equal pay for work of equal value.

Other salary violations include late or insufficient payment of contractual wages, overtime pay, night-work pay or work-stoppage pay. Improper deductions, failure to pay for unused annual leave when employment ends, and failures concerning salary during a temporary transfer or work suspension are also listed. The stated fine ranges depend on the number of affected employees:

Affected employees  Fine range 
1–10  VND 5–10 million 
11–50  VND 10–20 million 
51–100  VND 20–30 million 
101–300  VND 30–40 million 
301 or more  VND 40–50 million 

Paying below the government-prescribed minimum wage carries separate stated ranges: VND 20–30 million for 1–10 affected employees, VND 30–50 million for 11–50, and VND 50–75 million for 51 or more.

The material also addresses employees who are not subject to compulsory social, health and unemployment insurance. Their employer must pay an additional amount alongside salary equivalent to the employer’s contribution obligations. Failure to pay all or part of this amount may result in fines ranging from VND 3 million to VND 20 million, depending on the number of affected employees.

Depending on the violation, the business may be required to pay outstanding or late salary plus interest, or the unpaid insurance-equivalent amount plus interest.

Legal reference: Article 23 of Decree 283/2026/ND-CP.

4. Contract performance and temporary transfers

When assigning an employee to different work, businesses should review the notice given, the reason and duration of the transfer, and whether the employee’s consent is required. The supplied material also identifies risks in assigning a workplace different from that stated in the contract or failing to take an employee back after a period of contract suspension.

Fines for certain violations may range from VND 1 million to VND 7 million. The material lists higher ranges for workplace sexual harassment that does not reach the level of a criminal offence (VND 15–30 million) and coercion or mistreatment of employees (VND 50–75 million).

Legal reference: Article 17 of Decree 283/2026/ND-CP.

5. Employment termination

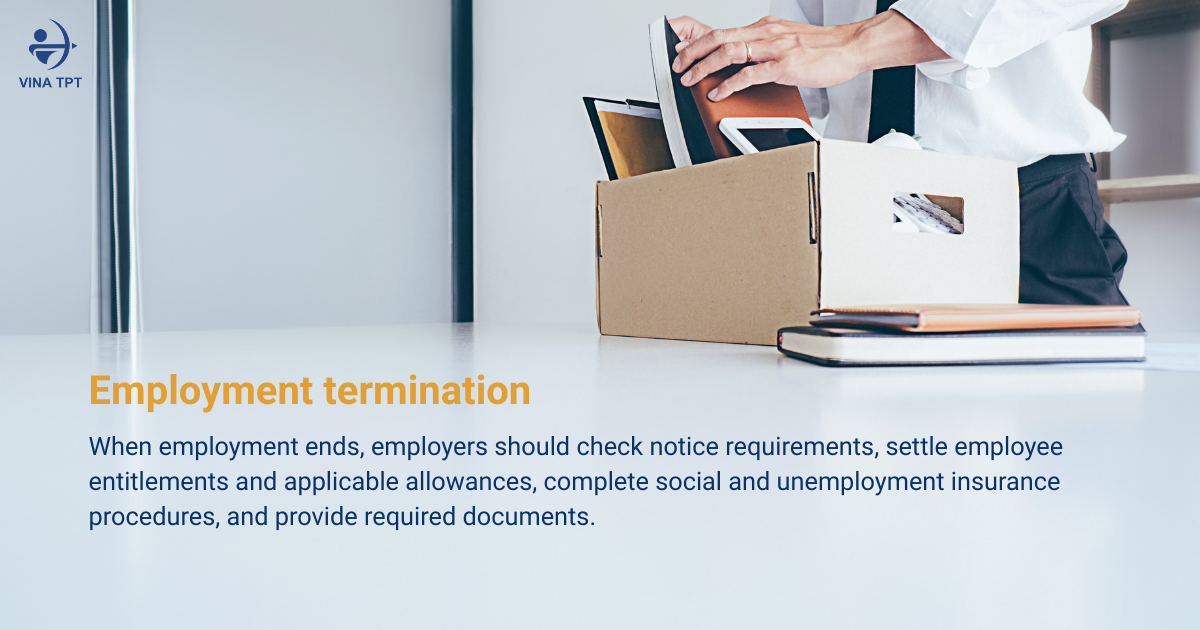
At the end of an employment relationship, employers should check whether written notice is required and whether all payments and documents have been completed. This includes employee entitlements, applicable severance or job-loss allowances, social and unemployment insurance procedures, and the return of documents or provision of relevant records when requested.

The stated fine for failing to give required written notice is VND 1 million to VND 3 million. Violations involving payments, allowances or post-termination documents may carry fines of VND 1 million to VND 20 million, depending on the number of affected employees.

Legal reference: Article 18 of Decree 283/2026/ND-CP.

Employment termination

6. Foreign employees and work permits

Businesses employing foreign nationals should review whether each employee holds a valid work permit or confirmation of exemption, and whether their actual work matches the permit. They should also check notification obligations when an employee works in multiple provinces or cities, as well as procedures for returning a permit or exemption confirmation when required.

According to the supplied material, a foreign employee working without a valid work permit or exemption confirmation may face a fine of VND 15 million to VND 25 million. For an employer using foreign employees without valid permits, the stated fines are VND 30–45 million for 1–10 employees, VND 45–60 million for 11–20, and VND 60–75 million for 21 or more. In some cases, a foreign employee may also be expelled from Vietnam.

Legal reference: Article 13 of Decree 283/2026/ND-CP.

7. Labor records and reporting

Workforce administration includes declarations of labor use, a labor management register, reports on changes in employment, and registration or updates to labor registration information.

The supplied material indicates fines of approximately VND 1 million to VND 10 million for violations involving declarations or the labor management register. Failure to register or update labor registration information may result in fines of VND 5–10 million for 1–50 employees, VND 10–15 million for 51–100, and VND 15–20 million for 101 or more.

Legal references: Articles 11 and 12 of Decree 283/2026/ND-CP.

Download Vina TPT’s checklist to review your company’s compliance with the seven employment areas covered in this article.

Download the Compliance Checklist for Labor & SHUI

Vina TPT – Review HR & Payroll Records Regularly

Administrative fines are only one possivinable consequence of a compliance gap. Depending on the violation, a business may also need to pay outstanding wages or benefits, pay interest, complete missing documents or fulfil other outstanding obligations. Regular reviews of employment contracts, payroll records, social insurance documents, work permits and labor reports can help businesses identify issues that need attention.

Vina TPT provides businesses in Vietnam with support across company incorporation, accounting, tax, HR and payroll, and business compliance. For the matters covered in this article, our HR and payroll services support salary calculation, social insurance record management, personal income tax calculation and filing, and related workforce administration.

Contact Vina TPT to discuss your company’s HR and payroll needs and the wider support required to manage your operations in Vietnam.

BOOK A FREE CONSULTATION

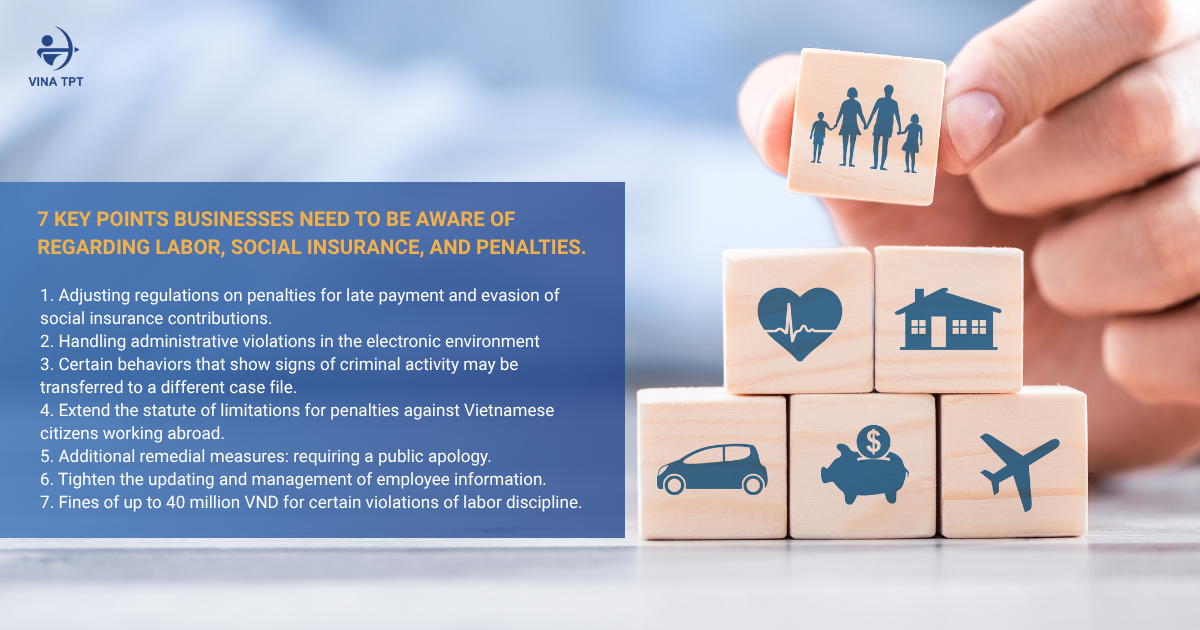
Decree 283/2026: 7 Labor and Social Insurance Compliance Points for Businesses from September 10, 2026

Decree 283/2026 7 Labor and Social Insurance Compliance Points for Businesses from September 10, 2026

Decree 283/2026/NĐ-CP governs administrative penalties in the fields of labor, social insurance, and Vietnamese workers working abroad under contracts. Issued on July 15, 2026, it took effect on September 10, 2026, replacing Decree No. 12/2022/NĐ-CP.

Compared with the previous regulations, Decree 283/2026/NĐ-CP introduces several notable provisions concerning late payment and evasion of compulsory social insurance and unemployment insurance contributions, employee data management, handling violations electronically, and labor discipline.

Below are seven points businesses should review to comply with the new regulations.

1. Revised penalties for late payment and evasion of social insurance and unemployment insurance contributions

Businesses should pay particular attention to the new rules on late payment and evasion of compulsory social insurance and unemployment insurance contributions.

Late payment of compulsory social insurance contributions

Under Article 43 of Decree No. 283/2026/NĐ-CP, late payment of compulsory social insurance contributions may be penalized based on a percentage of the total overdue amount.

Specifically:

  • A warning may be issued if the amount involved is less than VND 400,000 at the time the violation is officially recorded.
  • A fine of 12% to 15% of the total overdue compulsory social insurance contributions may be imposed, subject to the prescribed maximum of VND 75 million.
  • The business must also pay the outstanding contributions in full and an additional amount equal to 0.03% per day, calculated on the overdue amount and period in accordance with the regulations.

Evasion of compulsory social insurance contributions

Evasion of compulsory social insurance contributions is subject to a fine of 18% to 20% of the total amount evaded, subject to the prescribed maximum.

The Decree also sets out separate provisions for employers that fail to register, or fail to register all individuals required to participate in compulsory social insurance, after a period of 60 days.

The penalty is determined based on the number of affected employees.

Late payment and evasion of unemployment insurance contributions

Similarly, Articles 45 and 46 of Decree 283/2026/NĐ-CP separately address late payment and evasion of unemployment insurance contributions.

Late payment may be subject to a fine of 12% to 15% of the total overdue amount, up to the prescribed maximum of VND 75 million.

Evasion may be subject to a fine of 18% to 20% of the total amount evaded, up to the prescribed maximum of VND 75 million.

In addition to fines, businesses must implement the applicable remedial measures.

Businesses should note: When determining the fine applicable to an organization, they need to consult the provisions on fines for organizations in Decree No. 283/2026/NĐ-CP, rather than directly applying only the amount stated for each violation.


2. Handling administrative violations electronically

Decree No. 283/2026/NĐ-CP adds provisions for handling administrative violations electronically when the relevant infrastructure, technical, and information requirements are met.

Violation records, decisions, and related documents may be sent through prescribed electronic channels, including:

  • The email address that the individual in violation or the representative of the organization in violation has provided to the competent authority;
  • The national digital identification application or an electronic identification account that meets authentication requirements;
  • Applications specified in sector-specific legal documents;
  • SMS messages sent to a previously provided phone number; and
  • The email addresses of the fine collection agency and other relevant agencies for enforcement purposes.

Businesses should therefore keep the contact details, email addresses, and electronic accounts used in dealings with state authorities up to date to avoid missing notices or documents relating to violations.


3. Cases showing signs of criminal activity may be referred to competent authorities

Under Decree 283/2026/NĐ-CP, if an act shows signs of a crime during the review or handling of a violation, the official handling the case must refer the relevant file to the competent criminal proceedings authority.

Notable acts include:

  • Using forged papers or documents;
  • Illegally accessing, sharing, using, buying, selling, or exchanging information or data in the employee database that has not been made public by a competent authority;
  • Infringing an employee’s honor, reputation, or dignity during disciplinary proceedings;
  • Exploiting activities involving Vietnamese workers working abroad to organize illegal departures, exploitation, or forced labor; and
  • Repeatedly violating the rules by assigning workers aged 15 to under 18 to prohibited jobs or workplaces.

These provisions highlight the need for businesses to pay close attention to the accuracy of personnel records, data security, and procedures for handling employee matters.


4. Longer limitation period for violations involving Vietnamese workers working abroad

Decree No. 283/2026/NĐ-CP sets the following limitation periods for imposing administrative penalties:

  • One year for administrative violations relating to labor and social insurance; and
  • Two years for administrative violations involving Vietnamese workers working abroad under contracts.

The limitation period for violations in the field of sending Vietnamese workers abroad under contracts has therefore increased from one year to two years.

Businesses operating in this field should take the new period into account when reviewing records, contracts, and related compliance obligations.


5. Additional remedial measure: mandatory public apology

Alongside fines, Decree 283/2026/NĐ-CP adds or further specifies remedial measures, including a mandatory public apology in certain cases.

This measure may apply to specified acts, such as:

  • Workplace sexual harassment that does not warrant criminal prosecution;
  • Forced labor or mistreatment of employees that does not warrant criminal prosecution;
  • Requiring an employee to perform a labor contract to repay a debt owed to the employer; and
  • Certain violations relating to the organization and operation of trade unions.

Depending on the violation, a business may also be required to reinstate an employee, pay wages, or refund amounts it collected.

When reviewing compliance, businesses should therefore consider all applicable remedial measures as well as the potential fine.


6. Stricter requirements for updating and managing employee information

Decree No. 283/2026/NĐ-CP also addresses the provision, updating, and management of employee information.

For employees subject to compulsory social insurance, failure to provide information, or provision of incomplete or inaccurate information for labor registration, may be subject to penalties under the regulations.

Employment service businesses are required to:

  • Create and update employee data;
  • Manage employer data;
  • Protect the safety and confidentiality of personal data; and
  • Protect the safety and confidentiality of labor data and employment transaction data.

The Decree also prescribes penalties for illegally accessing, sharing, using, buying, selling, or appropriating employee data that has not been made public. In particular:

  • Illegal access, sharing, or use of data may be subject to the prescribed fines; and
  • Illegal buying, selling, exchanging, or appropriation of data may be subject to a fine of up to VND 70 million if the conduct does not warrant criminal prosecution.

Businesses should use these provisions to review how they manage personnel records, personal information, social insurance data, and internal data access rights.


7. Fines of up to VND 40 million for certain labor discipline violations

Article 25 of Decree 283/2026/NĐ-CP prescribes penalties for certain violations concerning labor discipline and material liability.

Businesses may be penalized for:

  • Failing to inform employees of the internal labor regulations;
  • Failing to display the main provisions of the internal labor regulations at the workplace;
  • Failing to establish written internal labor regulations when required;
  • Failing to register the internal labor regulations as required;
  • Applying internal labor regulations that are not yet effective or are no longer effective;
  • Taking disciplinary action without following the required procedures or limitation period; or
  • Suspending an employee from work contrary to the regulations.

Notably, certain serious violations may be subject to fines of VND 20–40 million, including:

  • Imposing a monetary fine or deducting wages instead of taking disciplinary action;
  • Taking disciplinary action for conduct that is not specified in the applicable regulations;
  • Imposing multiple forms of disciplinary action for a single violation; or
  • Taking disciplinary action against an employee during a period when the law prohibits it.

Depending on the circumstances, a business may also be required to reinstate the employee, pay wages, refund amounts collected, or issue a public apology.

Conclusion

Decree 283/2026/NĐ-CP introduces several notable changes to administrative penalties relating to labor, social insurance, unemployment insurance, and Vietnamese workers working abroad under contracts.

For businesses, compliance extends beyond paying social insurance contributions on time. It also involves managing employment records, updating data, establishing and registering internal labor regulations, following proper disciplinary procedures, and protecting employee information.

Reviewing and updating internal procedures can help businesses reduce the risk of violations and manage their workforce in accordance with current regulations.

Need to review your employment records and social insurance compliance?

Vina TPT provides HR & Payroll services and labor compliance advice, supporting businesses with personnel management and their social insurance obligations under current regulations.

BOOK

payroll-service-in-vietnam-a-practical-handbook-for-foreign-companies-and-hr-departments-2026

Doing Business in Vietnam: Essential Guide 2026-2027

doing-business-in-vietnam-essential-guide

doing-business-in-vietnam-essential-guide

The picture of doing business in Vietnam in 2026-2027 is shifting in a strategic way. The investment environment is no longer built only on low labor cost or early-stage land incentives. For foreign investors, small and medium-sized enterprises (SMEs), and FDI groups preparing to enter or expand, the business case now turns on the ability to use the new-generation Free Trade Agreement (FTA) network, adapt to the Law on Investment 2025, and stay inside a Tax-Accounting-Labor framework that is tightening discipline year by year.

Many international investors who start researching the market struggle to shape an overall compliance path. Focusing only on the initial incorporation license, and overlooking new legal updates, market-access conditions, or post-licensing FDI reporting, easily leads to project delays, administrative penalties, or a blocked profit-repatriation flow.

To give companies a complete and accurate view, this Vietnam business guide from Vina TPT examines doing business in Vietnam through six structured layers: assessing market attractiveness, covering the core legal changes of 2025-2026, choosing the form of presence, controlling operating obligations, and setting an optimized launch path for 2026-2027.

1. Why Vietnam Still Matters for Foreign Investors in 2026-2027

Vietnam continues to hold its place as one of the most dynamic and attractive investment destinations in Southeast Asia for 2026–2027. That appeal is shaped by a domestic market of nearly 100 million people, a golden-age population structure, a rapidly growing middle class, and a geo-economic position that connects directly with China, ASEAN, and the world’s main export shipping lanes.

Vietnam’s position is also reinforced by a deep network of new-generation Free Trade Agreements (FTAs), including the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP), the EU–Vietnam Free Trade Agreement (EVFTA), and the Regional Comprehensive Economic Partnership (RCEP). This treaty framework gives products made in Vietnam a clear tariff advantage when they are exported to major markets – provided the company meets the rules of origin and the relevant industry standards exactly.

FDI inflows into Vietnam are also going through a quality restructuring. The state now prioritizes high-tech projects, higher-value manufacturing, professional services, renewable energy, and the green economy over labor-intensive raw processing. For investors entering the market in 2026–2027, reading the sector direction and the incentive policy that applies to each field – from export manufacturing and retail trade to F&B and digital services – is the first step toward an efficient investment.

2. Legal Barriers and Key Regulatory Updates in 2025-2026

The 2025-2026 period marks a turning point in Vietnam’s business law, with a cluster of key statutes coming into force. Mastering these changes lets investors adjust their legal strategy early and cut compliance risk when doing business in Vietnam.

2.1. Updates under the Law on Investment 2025 (No. 143/2025/QH15) and Decree 96/2026/ND-CP

The Law on Investment 2025 (effective 1 March 2026; the list of conditional business lines applies from 1 July 2026) and guiding Decree 96/2026/ND-CP change the state’s management approach at the root:

  • A more flexible licensing sequence (ERC before IRC in some cases): Where the investor fully meets market-access conditions, the law allows the company to obtain the Enterprise Registration Certificate (ERC) first to establish legal personality, and complete the Investment Registration Certificate (IRC) afterward. This is more flexible than the IRC-before-ERC path required under the 2020 Law.
  • From ex-ante to ex-post control: The state has cut the list of conditional business lines and expanded the “green lane” (special investment procedures) in industrial parks, export-processing zones, high-tech parks, and digital technology parks.
  • Deeper decentralization: More project approvals sit with local authorities, and fewer small changes trigger a mandatory investment-project amendment.

2.2.Updates to the tax and financial-management framework (2025-2026)

  • Corporate Income Tax (Law No. 67/2025/QH15 and Decree 320/2025/ND-CP): The standard rate remains 20%. Preferential rates of 15% or 17% still exist for SMEs based on a revenue threshold, but the new rules tighten the eligibility tests so that subsidiaries of large groups cannot use those incentives.
  • Personal Income Tax (Law No. 109/2025/QH15 and Decree 253/2026/ND-CP): Applies from 1 July 2026 (with some salary-tax-bracket rules covering the full 2026 tax year) and revises the tax brackets and key family-circumstance deductions.
  • Tax administration and e-invoices (Law No. 108/2025/QH15): Effective 1 July 2026, this strengthens automated data matching and tightens control of e-invoices and cross-border transactions.
  • Abolition of the business license fee: From 1 January 2026, the business license fee is abolished. Companies no longer need to include this item in the operating budget.

Practical barriers that still matter: Even with simpler procedures, investors still face technical barriers: foreign-ownership limits, industry-specific sub-licenses, a lawful head-office address, digital identity requirements for the Legal Representative, the 90-day charter-capital contribution deadline, and periodic investment-monitoring reports.

doing-business-in-vietnam-essential-guide

3. How Foreign Investors Can Enter the Market: Forms and Entry Paths

To start doing business in Vietnam, a foreign investor needs a legal form of presence and an entry path that matches the project’s scale and commercial goal.

Common legal forms of presence

  • Limited liability company (LLC – one member or two or more members): The most practical and widely used model for small and mid-sized investors. Liability is limited to the committed capital, and the governance structure is lean and easier to run.
  • Joint-stock company (JSC): Suited to larger projects that involve at least three shareholders or that aim to raise capital and list on the stock market.

Two market-entry sequences under the new rules

Under the new legal framework, the investor has two procedural options:

  1. Traditional path (IRC → ERC): The investor files for the IRC so the project is appraised first, then incorporates the company to obtain the ERC. This path is safer for projects with complex conditions.
  2. Flexible path (ERC → IRC): Available where the project fully meets the published market-access conditions. The company obtains legal personality (ERC) first so it can prepare the operating setup, but actual project activity may start only after the IRC is completed within the committed deadline.

Vina TPT’s professional advice: Review the business-line conditions you intend to register in Vietnam. When setting up a company, you can look up the business-line codes and corresponding scope of activity on the official business-line lookup page to reduce the risk of having to amend or add lines during appraisal. Furthermore, registered capital must also match the actual project scale and must be paid in full into the Direct Investment Capital Account (DICA) within 90 days from the date the ERC is issued.

4. Tax, Accounting and Labor Rules After You Start Operations

Once licensing is complete, operating obligations begin in earnest. To keep the company safe and avoid administrative fines, the investor needs tight control of four core groups.

Tax and accounting (VAS)

  • Taxes that arise: Value-Added Tax (VAT), Corporate Income Tax (CIT), Personal Income Tax (PIT) for employees, and Foreign Contractor Tax (FCT) if the company pays for services or royalties to counterparties outside Vietnam.
  • Accounting standards: FDI companies must apply Vietnamese Accounting Standards (VAS), keep a proper set of books, appoint a legally qualified Chief Accountant, and prepare annual financial statements that are audited by an independent audit firm in Vietnam.

Labor and personnel

  • The company must sign labor contracts, register personal tax codes, and contribute compulsory social insurance, health insurance, and unemployment insurance for Vietnamese and foreign staff.
  • For foreign employees, the company must obtain a Work Permit or a Work Permit exemption, together with a Temporary Residence Card (TRC), so that residence is lawful.
  • It must also file periodic reports on labor use with the Department of Labor, Invalids and Social Affairs (DOLISA) or the industrial-park management board.

FDI investment reporting: Foreign-invested companies have a separate duty to update project-implementation reports and periodic investment monitoring and evaluation reports on the National Investment Information System (fdi.gov.vn). Missing these FDI reports will later block license amendments, capital increases, or lawful profit repatriation.

5. A Simple Roadmap to Start Doing Business in Vietnam

To help investors see the full execution path without being overwhelmed by technical detail, Vina TPT summarizes the standardized launch process in six decision points:

No. Decision point

What to complete

1

Review the industry and conditions Identify the business-line codes, check the foreign-ownership ratio, and confirm any sub-license requirements

2

Choose the structure and head office Select the company type (LLC/JSC) and sign a lease for a lawful registered address (Shared Office or a traditional office)

3

Prepare the dossier and legalize documents Collect investor documents, complete consular legalization, and obtain notarized Vietnamese translations

4

License and contribute capital Complete the IRC/ERC procedures on the path that fits the project, open the DICA, and contribute 100% of charter capital within 90 days

5

Activate initial compliance Register for tax, obtain a CA Token, set up e-invoices, establish the filing system, and complete the initial labor file

6

Operate on a sustainable basis Run VAS accounting, file periodic tax returns, submit FDI investment reports, and keep sub-license conditions in force

6. How Vina TPT Supports Foreign Investors

Entering and operating successfully in a fast-growing market like Vietnam requires a consulting partner that thinks clearly and understands how the system works in practice. Vina TPT provides end-to-end support through lawyers, legal specialists, CPAs, and Chief Accountants with 10-20 years of experience. We deliver a full service package and peace of mind for clients doing business in Vietnam:

  • Investment and industry strategy: Assessing market-access conditions under the Law on Investment 2025, advising on the capital structure, and designing an efficient company model.
  • Full-package company setup: Representing the investor to standardize the dossier, complete IRC and ERC procedures, engrave the seal, and finish post-licensing formalities.
  • Head-office solution (Shared Office): A lawful business-registration address in central Ho Chi Minh City that meets the tax authority’s inspection standards.
  • Post-establishment operating ecosystem: Full management of VAS tax accountant, bookkeeping service, payroll, social insurance, periodic FDI investment reporting, and industry-specific sub-licenses.
  • Continues to support in-depth services: VAT refunds, preparation and accompaniment during tax inspections, transfer pricing documentation, and advisory on mergers and acquisitions.

If you are preparing to start doing business in Vietnam in 2026-2027 and need a safe, accurate execution path, contact Vina TPT for in-depth advice from our specialist team.

BOOK A FREE CONSULTATION

doing-business-in-vietnam-essential-guide

What Is Included in Business Accounting Services in Vietnam?

what-is-included-in-business-accounting-services-in-vietnam

what-is-included-in-business-accounting-services-in-vietnam

You have just entered the Vietnamese market and are looking for a business accounting services provider that can optimize cost while still covering your basic compliance obligations. At this stage, many investors still do not have a clear picture of what they actually need: bookkeeping and tax filing only, or also payroll, labor reports, financial statements, and investment reports.

This article from Vina TPT breaks the work down by scope so you can choose an accounting services Vietnam package that matches real operating needs – complete on mandatory obligations, with nothing missing and nothing surplus relative to your current scale.

1. Bookkeeping and Daily Financial Records

The core foundation of any professional outsourcing accounting Vietnam solution is a daily bookkeeping system that is recorded accurately and in strict compliance with the Vietnamese Accounting Standards (VAS).

This workstream includes:

  • Document receipt and review: Checking the legality, validity, and reasonableness of all incoming and outgoing e-invoices, bank documents, commercial contracts, and customs declarations (if the company has import-export activities).
  • VAS bookkeeping: Recording in detail the transactions arising in revenue, expenses, fixed assets, prepaid expenses, inventory, and provisions under the correct VAS accounts.
  • Receivables, payables, and bank reconciliation: Reconciling bank statements (VND and foreign-currency accounts) and maintaining detailed records of customer receivables and supplier payables.

Vina TPT’s management view: Accounting data is not merely for internal storage. It must be of a standard that reconciles 100% with VAT returns, the annual audited financial statements, and FDI investment reports. If there is a discrepancy among these three data sources, the company faces a high risk of tax reassessment and significant penalties at finalization.

what-is-included-in-business-accounting-services-in-vietnam

2. Tax Compliance and Statutory Filings

Tax filing is the highest-risk workstream if the company does not keep up with changes in legal regulations. A provider of business accounting services is responsible for fulfilling all of the following obligations:

  • Value-Added Tax (VAT): Preparing and filing VAT returns on a monthly or quarterly basis; strictly reviewing input VAT deduction conditions (especially the mandatory bank-transfer requirement for invoices of VND 5 million or more).
  • Corporate Income Tax (CIT): Calculating quarterly provisional CIT (ensuring that the total provisional payments over four quarters are not lower than 80% of the amount payable on the annual finalization) and preparing the annual CIT finalization return.
  • Personal Income Tax (PIT): Filing withholding PIT returns monthly or quarterly and preparing the annual PIT finalization return for all employees.
  • Foreign Contractor Tax (FCT): Declaring and paying FCT arising from service contracts, royalties, international freight charges, or loan interest paid to foreign counterparties.
  • Business license fee and other taxes: Declaring and paying the business license fee at the beginning of the year, as well as natural resource tax and special consumption tax (if applicable).

The advisory firm must proactively track the tax calendar and alert the company to statutory deadlines in order to fully prevent late-payment penalties or a locked Tax Identification.

3. Payroll, PIT, Social Insurance and Labor Reports

Payroll cannot be separated from the accounting system. Errors in salary calculation and insurance will distort cash flow, affect deductible expenses for CIT purposes, and constitute labor-law violations.

A complete service package should include:

  • Payroll and insurance obligations: Preparing the payroll, issuing confidential payslips, calculating PIT withholdings, making social insurance, health insurance, and unemployment insurance contributions, and registering tax identification numbers and dependents for employees. For expatriates, the specialist must carefully check the Work Permit and Temporary Residence Card (TRC) conditions and correctly determine tax residency status (resident or non-resident) in order to calculate PIT accurately.
  • Five mandatory labor reports: In addition to tax returns, FDI companies are required to submit five periodic labor reports according to the standard schedule below:

Labor Report

Receiving Authority Filing Deadline

Prescribed Form

1. Report on labor utilization Department of Labor, Invalids and Social Affairs / Industrial Park or Economic Zone Management Board Twice a year: before 5 June and 5 December Form No. 01/PLI (Decree 145/2020/ND-CP)
2. Report on unemployment insurance participation Department of Labor, Invalids and Social Affairs Once a year: before 15 January of the following year Form No. 33 (Circular 28/2015/TT-BLDTBXH)
3. Occupational accident report Department of Labor, Invalids and Social Affairs Twice a year: before 5 July and 10 January of the following year Appendix XII (Decree 39/2016/ND-CP)
4. Occupational safety and hygiene report Department of Labor, Invalids and Social Affairs and Department of Health Once a year: before 10 January of the following year Appendix II (Circular 07/2016/TT-BLDTBXH)
5. Occupational health report District/City Medical Center Twice a year: before 5 July and 10 January of the following year Appendix 8 (Circular 19/2016/TT-BYT)

4. Financial Reporting and Management Reports

At the end of the financial year, the accounting services Vietnam provider prepares a complete set of financial statements under VAS, including the balance sheet, income statement, cash flow statement, and notes to the financial statements. This set of reports is the legal basis for the Tax Authority, the independent auditor, and submission to the statistics authority.

In addition to the statutory financial statements, the management of an FDI company also needs periodic monthly or quarterly Management Reports:

  • Profit and Loss (P&L) management report analyzing revenue and expenses
  • Cash flow management report
  • Aging report for accounts receivable and accounts payable

These management reports are presented in bilingual format (English – Vietnamese) so that Headquarters can monitor the financial health of the Vietnam entity without a language barrier.

Explore Vina TPT’s Accounting Services

5. Mandatory FDI Investment Reports

This is the obligation that many FDI companies miss when they use low-cost accounting packages. Missing investment reports not only leads to substantial administrative penalties but also creates serious bottlenecks when the company later adjusts its Investment Registration Certificate (IRC), increases capital, extends the project, or remits profits abroad.

Every foreign-invested enterprise (from 1% to 100% foreign capital) or project that has been granted an IRC is required to file investment reports. Even if the project has not yet generated revenue, is still in the construction phase, or has temporarily suspended operations, the company must still report (by declaring zero figures).

Investment reporting obligations consist of two main groups:

  1. Report on the Implementation of the Investment Project (filed online on the fdi.gov.vn system under Decree 96/2026/ND-CP)
  • Quarterly report: Filed before the 10th day of the first month of the following quarter. Content includes implemented investment capital, revenue, import-export value, headcount, amounts paid to the state budget, and land/water-surface use.
  • Annual report: Filed before 31 March of the following year. Content includes a comprehensive assessment of investment results, product sales, average employee income, operating costs, R&D activities, environmental impact, and the origin of the technology used.
  1. Investment Monitoring and Evaluation Report (under Decree 19/2026, Decree 96/2026, and Circular 44/2026/TT-BTC – Form 13)
  • Quarterly report: Filed before the 10th day of the first month of the following quarter.
  • Six-month report: Filed before 10 July of the current year.
  • Annual report: Filed before 10 February of the following year.

Vina TPT’s management view: Figures on the Investment Activity Report (IAR) must match the VAS accounting books and the tax returns. A discrepancy between the investment report and the audited financial statements is the first signal that the investment management authority and the tax authority will place the company on a specialized inspection list.

6. How to Choose the Right Business Accounting Services Package

To choose a suitable accounting compliance package, the Board of Directors of an FDI company should follow these steps:

  • Correctly determine scale and transaction profile: Assess the monthly volume of source documents, whether the company has import-export activities or Foreign Contractor Tax (FCT), the size of the workforce, and whether expatriates are employed.
  • Lock in the exact Scope of Work: Require the provider to state clearly in the contract whether the package covers only bookkeeping and tax filing, or a full package that includes payroll, labor reports, and periodic FDI investment reports.
  • Provider evaluation criteria: Prioritize a partner with hands-on FDI experience, a bilingual advisory team, a multi-level quality control (QC) process before filing, and the ability to represent the company directly before the Tax Authority and the investment management authority.
  • Clarify management reporting and the advisory layer: Ask whether the provider issues monthly management reports (P&L, cash flow, receivables and payables) and whether those reports are figures only or include commentary. At the same time, lock in the advisory scope in advance: filing only, or also support when a tax issue arises, an inspection is launched, or Headquarters needs an explanation of the figures.

7. How Vina TPT Delivers Business Accounting Services

Vina TPT provides a comprehensive business accounting services solution that gives FDI companies full legal peace of mind in Vietnam:

  • VAS bookkeeping and full-package tax filing: Recording the books under VAS and filing VAT, CIT, PIT, and FCT accurately and on time. The package also includes Chief Accountant services – a mandatory requirement for every FDI company, needed from company setup through the opening of the bank account.
  • Payroll administration and labor reports: Calculating salaries, optimizing insurance costs, completing expatriate PIT finalization, and filing all five mandatory labor reports.
  • Financial statements and FDI investment reports: Preparing the annual financial statements, supporting work with the independent auditor, and handling the full package of periodic investment monitoring reports.
  • Flexible operating model: Advising and delivering bilingual management reports (English – Vietnamese – Japanese), with remote or hybrid working arrangements depending on the company’s stage of development.
  • Continues to support in-depth services: VAT refunds, preparation and accompaniment during tax inspections, transfer pricing documentation, and advisory on mergers and acquisitions.

If your company wants to review its current compliance scope, contact Vina TPT today for an expert consultation on the most suitable solution.

BOOK A FREE CONSULTATION

what-is-included-in-business-accounting-services-in-vietnam