Vietnam Foreign Contractor Tax: Ultimate Guide for 2025 

vietnam foreign contractor tax

vietnam foreign contractor tax

Vietnam Foreign Contractor Tax (FCT), also known as Foreign Contractor Withholding Tax (FCWT), is a crucial withholding tax regime in Vietnam that applies to non-resident entities earning income from goods, services, or other activities sourced in the country. Governed primarily by Circular 103/2014/TT-BTC and updated through recent decrees like Decree 181/2025/ND-CP and Circular 69/2025/TT-BTC, FCT combines Value-Added Tax (VAT) and Corporate Income Tax (CIT) or Personal Income Tax (PIT) components to ensure foreign businesses comply with local tax obligations. This tax is particularly important for foreign contractors, suppliers, and digital service providers operating in Vietnam without a permanent establishment (PE), as non-compliance can lead to penalties, audits, and barriers to market entry. 

For quick assessment: Is FCT applicable to your business? 

1/ Checklist for Vietnam Foreign Contractor Tax Applicability: 

  • Are you a non-resident entity providing goods/services in Vietnam? (Yes/No) 
  • Does the transaction involve Vietnam-sourced income? (Yes/No) 
  • No permanent establishment in Vietnam? (Yes/No) 
  • If mostly “Yes,” FCT likely applies—consult a tax expert. 
Component  Description  Basic Rates (2025) 
VAT  Tax on added value in transactions  2-5% (with 2% reduction extended to Dec 2025) 
CIT  Income tax on profits  0.1-10% depending on activity 
PIT  For individuals  Up to 10% on gross income 

This overview sets the context: We’ll dive deeper into who pays, how to calculate, and tips for 2025 compliance, ensuring a logical flow from basics to advanced scenarios. 

2/ What is Vietnam Foreign Contractor Tax (FCT)? 

Foreign Contractor Tax (FCT) is a withholding tax imposed on payments made to foreign entities (non-residents) for income derived from Vietnam, regardless of where the contract is signed or services performed. It’s not a separate tax but a hybrid mechanism combining VAT and CIT (or PIT for individuals), withheld by the Vietnamese payer to simplify collection from non-residents. Introduced under Circular 103/2014/TT-BTC, FCT ensures foreign contractors contribute to Vietnam’s tax base without needing full residency. 

In 2025, updates via Circular 69/2025/TT-BTC emphasize stricter enforcement on e-commerce, aligning with global digital tax trends. Unlike standard withholding taxes (e.g., on dividends), FCT applies broadly to service-inclusive transactions, preventing tax evasion in cross-border deals. 

  • Key Components of FCT: 
  • VAT Portion: Covers value added, creditable for Vietnamese parties. 
  • CIT/PIT Portion: Taxes deemed profits. 
  • Hybrid Nature: Allows flexibility in calculation methods. 

For example, a foreign software firm licensing tech to a Vietnamese company pays FCT on royalties, contrasting with pure export taxes which might be exempt. This definition builds a foundation, leading to who it affects next. 

3/ Who is Subject to FCT? 

FCT targets non-resident foreign entities and individuals earning Vietnam-sourced income without a PE. This includes overseas contractors, subcontractors, suppliers, and digital platforms, as per updates in Official Letter 2200/CT-CS and 2025 regulations. 

Main Subjects: 

  • Foreign organizations providing services/goods in Vietnam. 
  • Non-resident individuals (e.g., consultants) without 183-day presence. 
  • E-suppliers like online marketplaces under new 2025 rules. 
Type of Subject  Conditions for Applicability  Examples 
Organizations  No PE; Vietnam-sourced income  Foreign engineering firms, SaaS providers 
Individuals  Non-residents earning fees  Expat freelancers, licensors 
E-Suppliers  Digital services to VN users  Streaming platforms, ad networks 

Checklist to Determine Liability: 

  • Income from VN contract? (Yes → Likely liable) 
  • Services performed in VN or goods with installation? (Yes → Liable) 
  • Treaty relief available? (Check DTAs) 
  • If unsure, register for clarification to avoid penalties. 

This section flows from definition to identification, highlighting 2025 e-supplier expansions for comprehensive coverage. 

Get to tax expert

Transactions Subject to FCT 

FCT applies to a wide range of cross-border transactions generating Vietnam-sourced income, including those with service elements. In 2025, this extends to digital distributions and royalties under tightened rules. 

Categories of Transactions: 

  • Goods sales bundled with services (e.g., equipment + installation). 
  • Pure services (e.g., consulting, training). 
  • Other income (e.g., interest, royalties, asset transfers). 
Transaction Type  Description  Examples  B2B vs. B2C Comparison 
Goods + Services  Sales with VN-linked support  Machinery import with setup  B2B: Higher scrutiny; B2C: Rare but taxable if services involved 
Services  Performed for VN entities  IT consulting  B2B: Standard FCT; B2C: E-commerce focus in 2025 
Other Income  Royalties, leases  Software licensing  Similar rates, but B2C digital often via platforms 

Risks include misclassifying pure goods as taxable—contextual examples like SaaS vs. physical sales add depth, transitioning to exemptions. 

Exemptions from FCT 

Certain transactions escape FCT if they meet strict criteria, reducing burdens for pure trade.  

  • Key Exemptions: 
  • Pure goods supply without VN services. 
  • Services wholly performed outside Vietnam. 
  • Reinsurance, international transport (partial). 
Exempt Scenario  Taxable Scenario  Reason 
Goods delivered at border  Goods + VN installation  No service element 
Offshore consulting  On-site training  Location of performance 
DTA-covered royalties  Non-treaty interest  Treaty provisions 

Always verify via DTAs; this hierarchy from common to specific ensures logical progression to calculations. 

Get expert support today

4/ Vietnam Foreign Contractor Tax Calculation Methods 

Foreign contractors can choose from three methods for FCT computation, each suiting different operational setups. Selection depends on eligibility and records, with 2025 updates favoring deduction for compliant firms. 

Method  Conditions  Pros/Cons 
Direct (Withholding)  No PE; simple records  Pros: Easy; Cons: Higher effective tax 
Deduction (VAS)  PE or 183+ days; full accounting  Pros: Lower on net; Cons: Audit-heavy 
Hybrid  Similar to Deduction; partial records  Pros: Flexible; Cons: Complex application 
  • Overview: Start with eligibility check, then apply rates—detailed sub-sections follow for hierarchy. 

4.1/ Direct Method (Withholding Method) 

The simplest approach: Tax is withheld on gross revenue using deemed rates. 

  • Steps: 
  • Identify gross turnover. 
  • Apply VAT (2-5%) + CIT (0.1-10%). 
  • Vietnamese party withholds within 10 days post-payment. 

Example: $100,000 service contract → VAT 5% ($5,000) + CIT 5% ($5,000) = $10,000 FCT. 

Revenue Gross  Rate  Tax Due 
$100,000  VAT 5% + CIT 5%  $10,000 

Flow: From formula to deadlines, ensuring practical application. 

4.2/ Deduction Method

Applicable Subjects:

Foreign contractors and foreign subcontractors are subject to tax when they meet all of the following conditions:

  • They have a permanent establishment in Vietnam or are identified as residents in Vietnam;
  • The duration of business operations in Vietnam under the contractor or subcontractor contract is 183 days or more, calculated from the effective date of the contract;
  • They comply with Vietnamese accounting regulations, register for tax, and are issued a tax identification number by the tax authority.
Methods of calculating VAT and Corporate Income Tax:
The declaration and determination of VAT and Corporate Income Tax are carried out according to the provisions of the VAT Law, the Corporate Income Tax Law, and related guiding documents.

4.3/ Hybrid Method 

Applicable Subjects:
Foreign contractors and foreign subcontractors, upon meeting the conditions for applying the declaration method or the direct method, and simultaneously implementing accounting procedures as prescribed by law on accounting and guidance from the Ministry of Finance, must register with the tax authorities to declare and pay taxes. Accordingly, VAT is applied using the deduction method and corporate income tax is calculated as a percentage of taxable revenue.
VAT for foreign contractors:
The determination and calculation of VAT are carried out according to the VAT Law and related guiding documents.
CIT for foreign contractors:
CIT is calculated using the direct method as prescribed by current regulations.

5/ FCT Rates 

Tax rates vary depending on the activity, with VAT at 2-5% (note that the 2% VAT reduction policy has been extended until the end of 2025 for certain industry groups) and corporate income tax from 1 -10%. Personal income tax (PIT) is governed by the law on PIT.

Activity  VAT Rate  CIT Rate  Examples 
Construction  3%  2%  Building projects 
Royalties  5%  10%  IP licensing 
Services  5%  5%  Consulting 


Get Free Consultation on Foreign Contractor Tax

6/ Declaration and Payment Procedures 

Steps: 

  • Register tax code (5 days before first transaction). 
  • Declare quarterly via GDT portal. 
  • Pay online within deadlines. 

Text Flowchart: Registration → Declaration (quarterly) → Payment (10 days post) → Audit if needed. 

7/ Frequently Asked Questions (FAQs) 

  1. What is the difference between FCT and standard withholding tax? FCT is broader, combining VAT/CIT for contractors, while standard applies to dividends/interest. 
  2. Is FCT applicable to e-commerce in 2025? Yes, with platforms withholding from July 1. 
  3. What if I have a PE? Switch to standard CIT; FCT may not apply. 
  4. Can I get a refund for overpaid FCT? Yes, via audit and claim within 5 years. 
  5. How to calculate FCT for hybrids? VAT on net, CIT on gross—consult for specifics. 
  6. Are there penalties for non-compliance? Up to 20% fines plus interest. 

If you need expert assistance with Foreign Contractor Tax (FCT) in Vietnam.

VINA TPT Tax Consultancy specializes in providing optimal solutions for Foreign Contractor Tax (FCT) for foreign businesses and partners in Vietnam. We help you understand and comply with the latest 2025 regulations, ensuring:

With a team of experts boasting over 20 years of experience and deep expertise in international taxation, VINA TPT is committed to supporting your business, from registration and declaration to crafting tax strategies tailored to your business model.

Book a Free Consultation with Our Expert
vina tpt accounting & tax firm

Accounting Services in Vietnam for FDI Compliance. 

What service do FDI company need to stay compliant in vietnam

Accounting services in Vietnam

As Vietnam’s economy thrives with a surge in foreign direct investment (FDI), the demand for accounting services in Vietnam has become critical for businesses to comply with local regulations and optimize operations. This comprehensive guide explores accounting solutions, from compliance to outsourcing, empowering you to make informed decisions. Discover how VINA TPT Company Limited, a leading provider, can support your business needs. 

What Are Accounting Services in Vietnam? 

Accounting services in Vietnam encompass professional solutions that help businesses manage finances, adhere to legal requirements, and produce accurate reports. Distinguished by local standards like Vietnamese Accounting Standards (VAS) and the transition to International Financial Reporting Standards (IFRS), these services are vital in an open economic landscape. 

  • Daily bookkeeping, including bank transactions and asset management. 
  • Preparation of financial statements compliant with VAS/IFRS, tailored for FDI companies. 
  • Tax advisory and lawful cost optimization. 
  • Audit support and financial due diligence. 

The growth of the accounting sector in Vietnam is closely tied to the rise of foreign enterprises, necessitating specialized solutions. For instance, a Japanese company in Ho Chi Minh City might require bilingual accounting services to meet internal and legal demands. 

Benefits of Outsourcing Accounting Services in Vietnam 

Outsourcing accounting services in Vietnam offers tangible benefits, especially for small and medium enterprises (SMEs) and FDI companies. Compared to in-house management, this approach saves costs, time, and reduces legal risks. 

  • Cost savings: Avoid investing in expensive staff and software, paying only for service packages as needed. 
  • Access to local expertise: Teams with deep knowledge of Vietnamese tax laws minimize penalty risks. 
  • Focus on core business: Free up resources to focus on strategic growth rather than bookkeeping. 
  • Rapid regulatory updates: Providers like VINA TPT stay updated with the latest regulations. 

For example, a U.S. company in Da Nang cut administrative costs by 30% by outsourcing to VINA TPT while ensuring timely VAT compliance. This highlights the practical value of outsourcing amid Vietnam’s growing international investment climate. 

Key Types of Accounting Services Available in Vietnam

1/ Bookkeeping and Financial Reporting 

Bookkeeping and financial reporting form the backbone of accounting services in Vietnam, ensuring transparent business operations. 

  • Record daily transactions, reconcile bank accounts, and manage assets. 
  • Prepare financial statements per VAS, with IFRS conversion support when required. 
  • Utilize accounting software like MISA or Fast for enhanced efficiency. 

A small business in Ho Chi Minh City improved report accuracy to 95% by adopting this process with expert assistance. 

2/ Tax Compliance and Advisory 

Tax compliance is mandatory, and accounting services in Vietnam help businesses optimize financial obligations. 

Tax Type  Rate (%)  Filing Period 
VAT  0, 5, 8, 10  Monthly/Quarterly 
CIT  15-17-20  Annually 
PIT  5-35  Quarterly 
  • File and submit VAT, CIT, and PIT taxes on time. 
  • Offer tax optimization, VAT refund assistance, and dispute resolution. 
  • Provide expertise in transfer pricing and Global Minimum Tax (Pillar Two). 

Download Vietnam Tax Handbook For Investor

3/ Payroll and HR Services 

Payroll and human resource management are crucial, particularly for foreign workers in Vietnam. 

  • Calculate salaries, contribute to social and health insurance. 
  • Assist with work permits and visas for foreign employees. 
  • Draft labor contracts and manage personnel records. 

Outsourcing saves 20% of administrative time compared to in-house management, especially in Ho Chi Minh City and Da Nang. 

4/ Chief Accountant Appointment 

Under Vietnamese law, companies must appoint a chief accountant, a need this service addresses. 

  • Register a chief accountant with tax authorities. 
  • Ensure compliance with related legal requirements. 
  • Reduce internal management burdens for small businesses. 

Outsourcing this role with VINA TPT helps new companies avoid violations. 

5/ Audit Assistance and Due Diligence 

Audit support and financial due diligence are essential for large enterprises. 

  • Prepare documents for annual audits. 
  • Conduct financial due diligence for M&A, adhering to Vietnamese standards. 
  • Assist in explanations to regulatory bodies. 

How to Choose the Right Accounting Service Provider in Vietnam 

How do you select the ideal accounting services in Vietnam provider? Consider these key factors. 

  • Experience: Teams with over 10 years in the field. 
  • Certifications: Chief accountant and tax advisory credentials from the Ministry of Finance. 
  • Bilingual support: Essential for FDI companies. 
Factor  In-house  Outsourced 
Cost  High (salaries, software)  Low (package-based) 
Expertise  Limited  High (specialists) 

VINA TPT offers bilingual (Vietnamese/English/Japanese) services and international certifications, surpassing many competitors. 

Top Accounting Firms and Providers in Vietnam 

Leading accounting services in Vietnam providers include: 

Company  Strength  Contact 
Acclime  Comprehensive FDI support  www.acclime.com 
TMF Group  Global services  www.tmf-group.com 
VINA TPT  Holistic solutions, expert team  www.vinatpt.com 

VINA TPT stands out with over 20 years of experience, offices in Ho Chi Minh City and Da Nang, and a team led by Mr. Lê Quốc Duy—a renowned consultant for Japanese and international firms, contributing to Mizuho Asia Report and Japanese journals.

Top accounting services in vietnam

Frequently Asked Questions (FAQs) 

  • What are the main taxes for foreign companies in Vietnam? VAT, CIT, and PIT with specific rates per regulation. 
  • How much do accounting services cost in Vietnam? Ranges from $85-800/month depending on the package; contact VINA TPT for a quote. 
  • Is outsourcing compliant with Vietnamese law? Yes, when using reputable providers like VINA TPT. 
  • What documents are needed for tax filings? Invoices, financial statements, and labor contracts. 
  • How to process a VAT refund? Reach out to VINA TPT for step-by-step assistance. 


EXPLORE OUR ACCOUNTING SERVICE

Personal income tax: Comprehensive Guide for Residents and Expats

what is personal income tax in vietnam

PERSONAL INCOME TAX IN VIETNAM FOR EXPATS


Personal Income Tax in Vietnam, governed by the Law on Personal Income Tax No. 04/2007/QH12 and its amendments (latest in 2025), is a critical obligation for individuals earning income in Vietnam. Whether you’re a local resident, an expat, or a digital nomad, understanding PIT ensures compliance and optimizes your financial planning. This guide covers tax rates, deductions, filing procedures, and more to address your needs—whether you’re seeking rates (informational), filing steps (transactional), or official resources (navigational).  

Why does PIT matter? With Vietnam’s economy growing and stricter tax enforcement in 2025, knowing your obligations prevents penalties and maximizes deductions. Ready to navigate Vietnam’s tax system? 

1/ Determining Your Tax Residency Status 

Your tax obligations hinge on your residency status. Under Vietnam’s tax law, you’re a tax resident if you meet one of these criteria: 

  • Stay in Vietnam for 183 days or more in a calendar year or 12 consecutive months. 
  • Hold a permanent residence card or have a leased property in Vietnam for 183+ days. 
  • Otherwise, you’re a non-resident, taxed only on Vietnam-sourced income. 

Special cases: Digital nomads or expats in Vietnam may unintentionally become tax residents if they overstay the 183-day threshold. To avoid this, maintain proof of residency elsewhere (e.g., tax certificates from another country).  

Tax residency status

Comparison: Tax Residents vs. Non-Residents 

Criteria  Tax Resident  Non-Resident 
Taxable Income Scope  Global income  Vietnam-sourced income only 
Tax Rates  Progressive (5%-35%)  Flat 20% (employment); 0.1%-20% (others) 
Filing Obligations  Annual finalization, monthly/quarterly  Pay-at-source or annual declaration 

This table highlights why residency status is critical for tax planning. 

2/ Types of Taxable Income 

Personal income tax applies to various income types, including: 

  • Employment income: Salaries, wages, bonuses, allowances, and fringe benefits. 
  • Non-employment income: Business profits, dividends, capital gains, real estate transfers, royalties, inheritances, gifts, and prizes (e.g., lottery winnings). 
  • Foreign currency income: Converted to VND using the State Bank of Vietnam exchange rate at the transaction date. 
  • Emerging categories: Income from digital services (e.g., content creation, online consulting) and remote work is increasingly scrutinized in 2025. 

income streams

3/ Personal Income Tax Rates 2025 

Vietnam uses progressive tax rates for residents and flat rates for non-residents: 

  • Residents: Taxed from 5% (up to 5 million VND/month) to 35% (over 80 million VND/month). 
  • Non-residents: 20% on employment income; other incomes (e.g., real estate, capital gains) range from 0.1%-20%. 

Personal Income Tax Rate Tables 

Monthly Taxable Income (VND)  Tax Rate  Tax Amount (VND)  Approx. USD 
Up to 5 million  5%  0-250,000  $0-10 
5-10 million  10%  250,000-750,000  $10-30 
10-18 million  15%  750,000-1,650,000  $30-65 
18-32 million  20%  1,650,000-3,650,000  $65-144 
32-52 million  25%  3,650,000-6,650,000  $144-262 
52-80 million  30%  6,650,000-11,250,000  $262-444 
Over 80 million  35%  11,250,000+  $444+ 

Note: Non-residents pay a flat 20% on employment income, converted to ~$800/month for a $4,000 salary. 

4/ Deductions and Allowances 

Reduce your taxable income with these deductions: 

  • Personal deduction: 11 million VND/month (~$434 USD). 
  • Dependent deduction: 4.4 million VND/month per dependent (e.g., children under 18, disabled spouses, low-income parents). Register with a Tax Identification Number (TIN) and documents (birth certificates, income proofs). 
  • Other deductions: Compulsory insurances (social, health, unemployment), charitable donations, voluntary pension contributions. 

Checklist for claiming deductions: 

  • Register dependents with tax authorities. 
  • Submit proof of income for dependents earning below the threshold. 
  • Keep records of charitable donations (receipts, bank transfers). 

See Our Full Range of Tax Solutions

5/ Tax-Exempt Income and Benefits 

Certain incomes and benefits are exempt from PIT: 

  • Exempt incomes: Bank interest, insurance compensations, retirement pensions, family property transfers, scholarships, certain agricultural incomes. 

Non-taxable benefits:  

  • One annual round-trip airfare for expats. 
  • School fees for expat children (direct employer payments). 
  • Mid-shift meals (capped at regional minimum wage). 
  • Housing (up to 15% of total income), uniforms (up to 5 million VND/year if cash). 

Example: An expat’s employer pays $2,000 for their child’s school fees directly—fully exempt from PIT. 

6/ How to Calculate Your Personal Income Tax in Vietnam 

Follow these steps to calculate your PIT: 

  1. Determine residency status: Resident or non-resident. 
  1. Calculate taxable income: Gross income minus exemptions. 
  1. Apply deductions: Personal, dependent, and insurance deductions. 
  1. Apply tax rates: Use progressive rates (residents) or flat rates (non-residents). 

Example: A resident expat earns 50 million VND/month with two dependents: 

  • Taxable income: 50.000.000 – 11.000.000 (personal) – 8.800.000 (dependents) = 30.200.000 VND. 
  • Tax: (10.000.000 × 5%) + (8.000.000× 10%) + (12.200.000 × 15%) = 500.000 + 800.000+ 1.830.000 = 3.130.000 VND (~$123 USD). 

Tool: Use the e-portal calculator https://luatvietnam.vn/tinh-thue-thu-nhap-ca-nhan.html  for accuracy. 

7/ Filing and Payment Procedures 

Vietnam’s tax year runs from January 1 to December 31. Key procedures: 

  • Withholding: Employers deduct PIT monthly/quarterly. Self-declare for multiple income sources. 

Deadlines: 

  • Monthly: 20th of the next month. 
  • Quarterly: End of the first month post-quarter. 
  • Annual finalization: March 31 (employers), April 30 (individuals). 

Methods: File via GDT e-portal https://canhan.gdt.gov.vn/ICanhan, local tax offices, or authorized agents. Payments via bank transfer or State Treasury. 

Leaving Vietnam: Finalize taxes 45 days before departure to avoid immigration issues. 

Checklist for filing: 

  • Obtain a Tax Identification Number (TIN). 
  • Prepare income statements, deduction proofs. 
  • Verify filing status on the GDT portal. 

8/ Double Taxation Agreements (DTAs) 

Vietnam has DTAs with over 80 countries (e.g., US, UK, Singapore) to prevent double taxation. Benefits include exemptions or credits for taxes paid abroad. 

How to claim relief: 

  • Notify tax authorities 15 days before payment. 
  • Submit foreign tax payment proofs (e.g., tax certificates). 
  • Example: A US expat pays 10% tax in Vietnam on dividends, then claims a credit in the US. 

Are you leveraging DTAs to avoid double taxation? 

9/ Special Considerations for Expats and Foreigners 

Expats face unique PIT challenges: 

  • US expats: Report global income to the IRS (via FBAR, FEIE, FTC) while complying with Vietnam’s residency rules. 
  • Short-term assignments: “Economic employer” rules may apply, requiring payroll withholding. 
  • Digital nomads: Risk being taxed as residents if staying 183+ days; global income becomes taxable. 
  • 2025 updates: The General Department of Taxation (GDT) uses AI to monitor digital transactions, enforcing taxes on crypto gains and online services. 

Example: A digital nomad staying 200 days in Vietnam may owe PIT on worldwide income unless proving non-residency.

10/ Common Mistakes, Penalties, and Tips for Compliance

Common mistakes:

  • Underreporting benefits: Expats often overlook taxable benefits like housing allowances or cash-based uniform payments, leading to incorrect tax filings.

  • Missing dependent registration deadlines: Failing to register dependents (e.g., children, spouses) by the deadline (typically March 31) forfeits deductions of 4.4 million VND/month per dependent.

  • Ignoring Double Taxation Agreements (DTAs): Not claiming DTA benefits with over 80 countries (e.g., US, UK) results in unnecessary double taxation.

Penalties:

  • Late filing: A 0.05% daily interest penalty applies to overdue tax submissions, accumulating quickly.

  • Underpayment: Fines range from 10%-20% of the underpaid amount, with potential legal action for significant violations.

Tips for expats in Vietnam compliance:

  • Engage professional tax agents: Complex cases, such as multi-source incomes or DTA applications, benefit from expert guidance. Vina TPT, with over a decade of experience, offers tailored PIT solutions, including tax filing, deduction optimization, and multilingual reporting for expats and FDI businesses.

  • Track days in Vietnam: Monitor your stay to confirm tax residency status (183+ days triggers global income taxation). Use calendar apps or consult professionals to avoid unintended residency.

  • Reconcile income records annually: Cross-check payslips, contracts, and bank statements to ensure accurate declarations.

  • Leverage expert support: As an expat, I’ve relied on Vina TPT to navigate Vietnam’s PIT complexities. Their expertise in tax compliance, work permits, and payroll management saved me time and ensured no penalties, allowing me to focus on my work

Comparison: Vietnam’s PIT rates (5%-35%) are competitive with Thailand’s (0%-35%) but higher than Singapore’s flat 0%-22% for residents. Partnering with a service like Vina TPT ensures you optimize deductions and comply with local laws, avoiding costly errors.

10/ Simplifying Tax Procedures with Vina TPT’s PIT Services for Foreigners

Navigating Vietnam’s Personal Income Tax system can be complex, especially for foreigners unfamiliar with local regulations, language barriers, and intricate filing requirements. Vina TPT PIT Services offers a comprehensive PIT service tailored for expatriates and non-residents, streamlining every aspect of tax compliance. With over a decade of experience, Vina TPT provides:

  • End-to-end tax filing: From obtaining a Tax Identification Number (TIN) to submitting accurate declarations via the GDT e-portal, ensuring timely compliance with monthly, quarterly, and annual deadlines.

  • Deduction optimization: Expert guidance to maximize personal and dependent deductions, as well as leveraging Double Taxation Agreements (DTAs) with over 80 countries to minimize tax liabilities.

  • Multilingual support: Clear communication in English and other languages to assist expats with residency status determination, income reporting, and penalty avoidance.

  • Payroll and compliance solutions: For expats on short-term assignments or digital nomads, Vina TPT handles payroll withholding, work permits, and monitors the 183-day residency threshold to prevent unintended tax obligations.

  • AI-driven accuracy: Using advanced tools to track digital transactions (e.g., crypto gains, online services), ensuring compliance with 2025’s stricter tax enforcement.

Let’s Find the Best Tax Solution for You

11/ FAQ on Personal Income Tax in Vietnam 

  • What is the threshold for PIT filing in Vietnam? 

Residents with taxable income above 11 million VND/month or non-residents with any Vietnam-sourced income must file. 

  • How do I register for a Tax Identification Number (TIN)? 

Apply via the GDT e-portal or local tax offices with ID/passport and proof of residency. 

  • Are overseas remittances taxable? 

No, unless used for taxable activities (e.g., investments). 

  • What happens if I overpay PIT? 

Request a refund via the GDT portal with proof of overpayment. 

  • Can I deduct home office expenses as a remote worker? 

No, unless registered as a business expense with proper invoices. 

Why choose Vina TPT?

Their expertise eliminates the stress of navigating Vietnam’s tax system, saving you time and preventing costly errors. Whether you’re a digital nomad, a corporate expat, or managing multiple income sources, Vina TPT ensures seamless compliance and financial peace of mind.

Book a Consultation with Our Expert
Payroll-HR-Manager-Vietnam-VinaTPT

Work Permit in Vietnam 2025 | Step-by-Step Guide & Requirements

work permit step by step guidance

Work permit in vietnam 1

Work permit in Vietnam is a mandatory requirement for foreigners to legally work in the country. This article provides detailed information on the latest requirements, documents, and procedures for obtaining a work permit, while also covering exemption cases and relevant penalties. 

1/ What is a Work Permit in Vietnam?  

The work permit is an official legal document issued by a competent Vietnamese authority, allowing foreign nationals to work legally in Vietnam. It is a compulsory requirement for most foreigners employed in the country. 

The work permit in Vietnam is issued by the Ministry of Home Affairs (MOHA) or Department of Home Affairs at the provincial or municipal level. The permit contains key details such as the employee’s full name, nationality, job position, and the validity period. 

2/ Why do foreigners need a work permit in Vietnam?  

Holding a work permit offers several benefits and is a legal requirement:  

  • Compliance with Vietnamese law: This is a legal regulation. Working without a work permit is considered a violation of labor laws.  
  • Avoiding legal risks: Both the employee and the employer can avoid legal risks, including administrative penalties or deportation.  
  • Protection of legal rights: A work permit helps protect the foreign worker’s legal rights, including those related to salary, insurance, and other benefits.  

The current legal documents governing work permits in Vietnam include:  

3/ Eligible individuals and conditions for being granted a work permit in Vietnam  

To be granted a work permit, foreigners must meet specific conditions.  

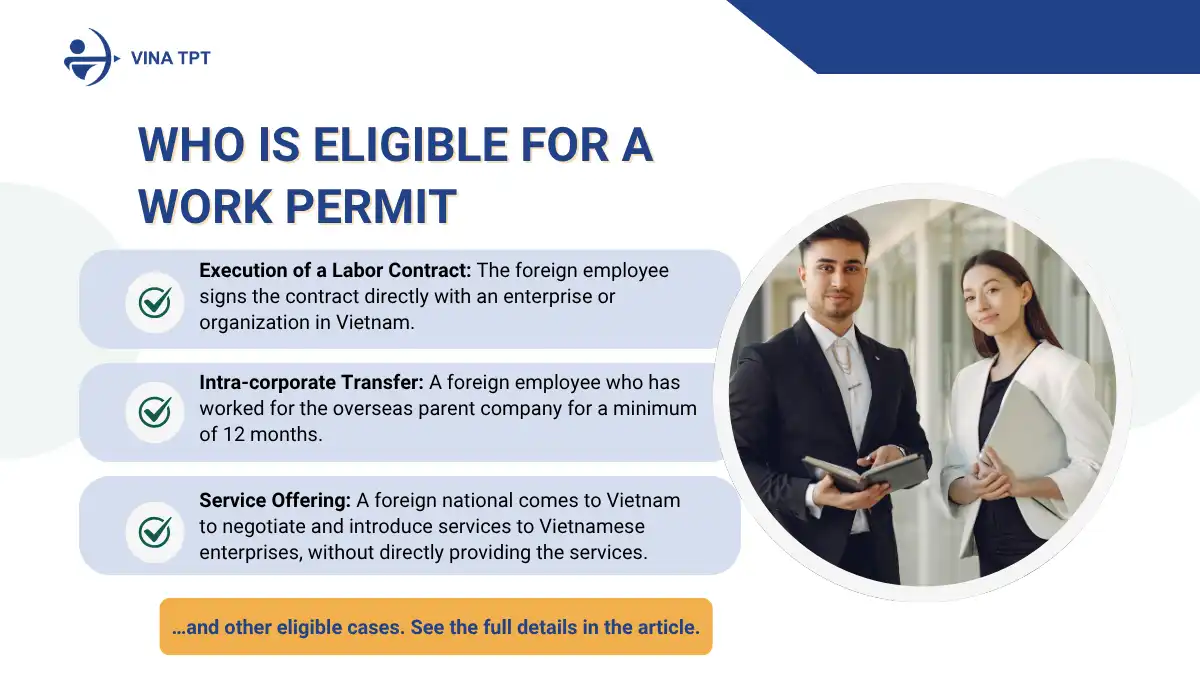
Eligible for a work permit

Eligible individuals for a work permit: 

The individuals eligible for a work permit in Vietnam are clearly defined in Article 2 of Decree No. 152/2020/ND-CP (as amended by Decree No. 70/2023/ND-CP). Specifically, these are foreigners entering Vietnam to work under the following forms: 

Performing a labor contract: 

  • The foreign national signs a direct labor contract with a company or organization in Vietnam. 
  • They hold positions such as expert, technician, manager, or executive director.  

Intra-corporate transferee 

  • The foreign worker has been employed by the overseas parent company for at least 12 months.  
  • They are transferred to work at a branch or representative office of the same group/company in Vietnam.  

Executing contracts or agreements between Vietnamese enterprises and foreign organizations 

These may involve fields such as economics, trade, finance, banking, insurance, science and technology, culture, sports, education, healthcare, etc.  

Contract-based service provider 

The foreigner comes to Vietnam to fulfill obligations under a service contract signed between a foreign entity and a Vietnamese one. They do not have a commercial presence in Vietnam.  

Service sales representative 

The foreigner visits Vietnam to negotiate or introduce services to Vietnamese businesses but does not directly deliver the services.  

Foreign volunteer 

They must have an assignment letter from a licensed non-governmental or international organization operating in Vietnam.  

Person responsible for establishing a commercial presence 

They represent a foreign organization in setting up a representative office in Vietnam.  

Other cases 

As defined by regulations or international agreements to which Vietnam is a signatory (e.g., WTO, CPTPP commitments).  

General conditions for work permit Viet Nam:  

Foreign workers must meet the following general conditions to be have work permit in Vietnam: 

  • Possess full civil act capacity.  
  • Be in good health suitable for the job. A valid health certificate is required.  
  • Be a manager, executive director, expert, or technical worker.  
  • Not have a criminal record or be under criminal prosecution.  
  • Obtain a written approval for the job position using a foreign worker. This document must be issued by a competent authority.  

Specific requirements for each category  

Each category has specific requirements in terms of qualifications and experience:  

  • Expert: Must hold a university degree or equivalent, and have at least 3 years of relevant work experience.  
  • Technical worker: Must have received at least 1 year of specialized training and have at least 3 years of experience in the trained field.  
  • Manager or executive director: Must have managerial experience. Supporting documents such as appointment decisions are required.  
  • Intra-corporate transferees: Must be assigned by the foreign enterprise. An appointment decision and proof of experience with the parent company are required.  

View more about service for Expats in Vietnam

4/ Application dossier for a new work permit in Vietnam  

Preparing a complete and accurate dossier is crucial. Required documents include: 

  • Health certificate valid for 12 months.   
  • Criminal record certificate issued within the last 6 months.   
  • Certificates, diplomas, or professional qualification documents.   
  • Document confirming work experience or a previous work permit.   
  • Two 4×6 cm photos with white background, taken within the last 6 months.   
  • Approval letter for the need to employ foreign workers.   
  • Certified copy of a valid passport.   
  • Additional documents depending on the specific case (e.g., contract, assignment letter, etc.).   
  • Foreign documents must be consular legalized and notarized translated.  

5/ VIETNAM WORK PERMIT PROCESS 

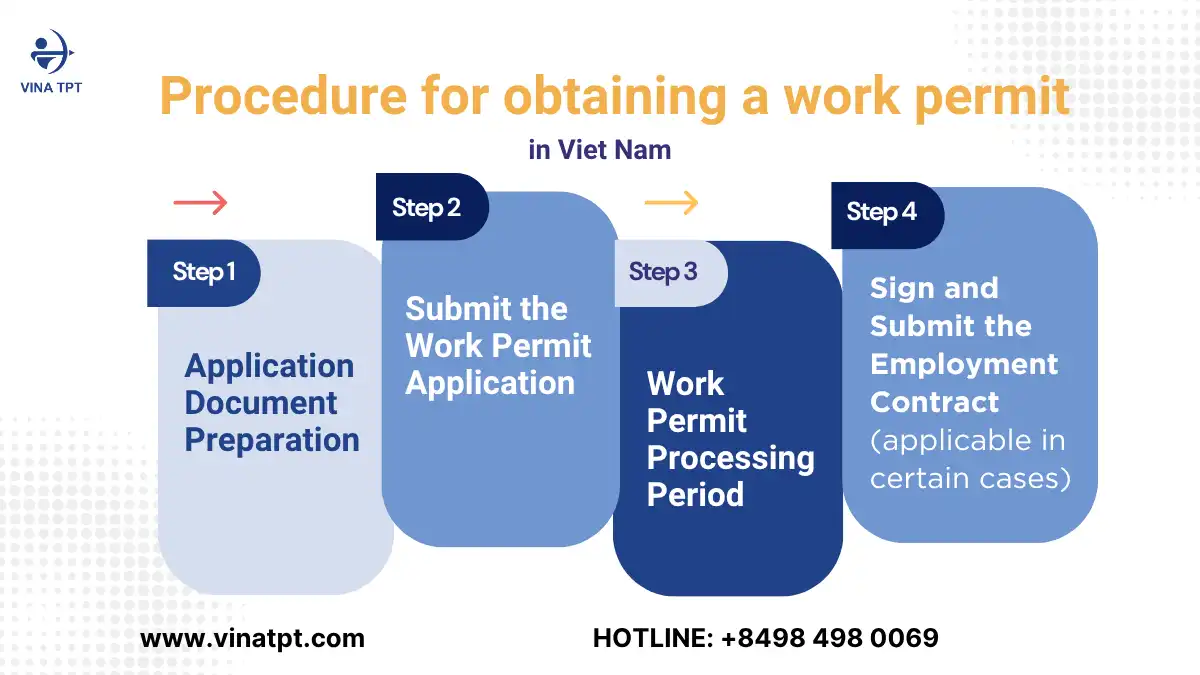
The process for obtaining a work permit includes the following steps:  

Step 1: Submit the application for a work permit in Vietnam 

Submission deadline: At least 15 days before the foreign worker is expected to start working in Vietnam. 

Receiving authority:   

  • Ministry of Home Affairs (for cases under its jurisdiction), 
  • Or Department of Home Affairs, where the foreigner is expected to work. 

Applicants:   

  • Employer: Applies to foreign workers working under labor contracts, intra-corporate transfers, execution of agreements, service providers, service sellers, or other applicable cases.  
  • Vietnamese or foreign entities operating in Vietnam: Applies when foreign workers are working under specific contracts or agreements.  
  • Foreign worker: Applies to those entering Vietnam to offer services or to establish a commercial presence.  

Step 2: Wait for the work permit issuance   

  1. Processing time: Within 5 working days from the date of receiving a complete and valid application. 
  1. Issuing authority: Ministry/ Department of Home Affairs where the foreigner will work.  
  1. Result:  If the application is valid and eligible, the foreign worker will be granted a work permit using Form No. 12/PLI – Appendix I of the Decree. của Nghị định.  

If not granted: The competent authority will issue a written response stating the reason for rejection.  

Step 3: Sign and submit the labor contract (applies to certain cases)   

Applicable to: Foreign workers working under labor contracts.  

Requirement: After the foreign worker is issued a work permit, the employer and the worker must sign a written labor contract in accordance with Vietnamese labor law. This must be done before the worker’s official start date. 

Employer’s obligation: The signed labor contract (original or certified copy) must be submitted to the authority that issued the work permit. 

Produre for abtaining a work permit in vietnam
Procedure for abtaining a work permit in viet nam

6/ Work Permit Fee in Vietnam 

The fee for obtaining a work permit is generally regulated by the Ministry of Finance. According to Circular No. 250/2016/TT-BTC, the fee for a new work permit is 400,000 VND per permit. However, this amount may vary slightly across provinces depending on local People’s Council regulations. 

Work Permit Validity: : The maximum validity period of a work permit is 2 years. 

7/ Exemptions from Work Permit Requirement  

In certain cases, foreigners working in Vietnam are not required to obtain a work permit:  

  • Being the owner or capital-contributing member of a company with contributed capital of at least VND 3 billion.  
  • Being a member of the Board of Directors of a joint-stock company with contributed capital of at least VND 3 billion.  
  • Entering Vietnam for work for less than 30 days and no more than 3 times per year.  
  • Performing duties under international agreements to which Vietnam is a signatory.  
  • Other cases as specified in Article 7 of Decree No. 152/2020/ND-CP (as amended by Decree No. 70/2023/ND-CP).  

You can find more detailed information on exemption work permit on the official Government Portal or in this article.  

8/ Penalty for without work permit in Viet Nam:  

Violations of work permit regulations are strictly penalized.  

In case of working without a permit (penalty for without work permit in Viet Nam)   

  • Foreign worker: May be fined from VND 15,000,000 to VND 25,000,000 and may be subject to deportation.  
  • Employing enterprise: May be fined from VND 30,000,000 to VND 75,000,000 depending on the number of violating workers.  
  • Administrative penalties: Detailed in Decree No. 12/2022/ND-CP on administrative sanctions in labor and social insurance. More information can be found at the Ministry of Home Affairs website: https://moha.gov.vn/ 
  • Other sanctions: : In addition to fines, workers may be deported and employers may face suspension of business activities.  

9/ Conclusion 

Applying for a work permit in Vietnam is a crucial legal procedure. It requires careful preparation and strict compliance with the regulations. To ensure a smooth process, you should: 

  • Prepare your application documents thoroughly and completely.  
  • Seek professional assistance if you are not familiar with the procedures. 
  • Comply with the law to avoid unnecessary legal risks.  

Vina TPT proudly offers full-package consulting and support services for obtaining work permits in Vietnam for foreigners. We assist clients with document preparation, application submission, and process follow-up. 

Our service saves you time and effort, ensuring the process is completed quickly and accurately.   

Contact us for detailed consultation.  

Book a free consultation

Vina TPT Accounting services