Cases Eligible for VAT Tax Refund in Vietnam in 2026 

cases-eligible-for-vat-tax-refund-in-vietnam-in-2026

In practice, the amount of VAT tax refund that a business may receive is often significant, especially when the deductible input VAT eligible for refund reaches VND 300 million or more. For this reason, tax refund procedures are always a matter of concern for domestic enterprises, foreign-invested enterprises (FDIs), and accounting departments.

The article below summarizes the cases eligible for VAT tax refund under the Law on Value Added Tax 2024, while clarifying the applicable conditions and important notes that businesses should understand when carrying out refund procedures.

cases-eligible-for-vat-tax-refund-in-vietnam-in-2026

1. What is a VAT tax refund?

A VAT tax refund is the return by the tax authority of VAT amounts that an enterprise or individual has paid or is entitled to deduct, provided that the legal conditions are satisfied. This typically applies when input VAT exceeds output VAT or when special tax incentive policies are available.

Carrying out a VAT tax refund helps reduce financial pressure on businesses, improve working capital, and encourage investment, exports, and other incentivized economic activities. It also helps ensure fairness in tax collection and avoids situations of overpayment.

Example: Company H exports fashion products (T-shirts) and is not required to pay output VAT because the applicable VAT rate is 0%. During the period, the company incurred VND 70 million in input VAT for raw materials. Under the regulations, Company H may receive a VAT tax refund of VND 70 million from the tax authority to offset the tax already paid.

2. Cases eligible for VAT tax refund

Under Article 15 of the Law on Value Added Tax 2024 and the related guiding documents, businesses and organizations may be entitled to a VAT tax refund in certain situations.

Below are 9 common cases eligible for VAT tax refund under the current regulations.

Case 1: VAT tax refund for exported goods and services

Case Condition Tax treatment
Business establishments with exported goods or services during the tax declaration period Input VAT not yet fully deducted exceeds VND 300 million Eligible for VAT tax refund on a monthly or quarterly basis
Input VAT not yet fully deducted is below VND 300 million Carried forward to the next tax declaration period for continued deduction

Pursuant to Clause 1, Article 15 of the Law on Value Added Tax 2024 and Article 29 of Decree 181/2025/ND-CP, businesses engaged in export activities may be entitled to a VAT tax refund in the following cases:If a business has both exported goods and domestic sales, it must separately account for the input VAT relating to export activities.

If separate accounting is not possible, the input VAT for exported goods is determined based on the ratio of export revenue to total taxable revenue.

After offsetting against the VAT payable for domestic sales, if the remaining input VAT is VND 300 million or more, the business may be granted a VAT tax refund. However, the refund amount must not exceed 10% of export revenue.

Some export-related cases eligible for refund include:

Case Eligible subject
Export under entrusted export arrangement The business that entrusts goods for export
Export processing The business entering into a processing contract with a foreign party
Export for overseas construction projects The business exporting materials or goods for overseas projects
On-the-spot export The business exporting goods on the spot

Note: A VAT tax refund is not available for imported goods that are subsequently exported to another country without processing or manufacturing in Vietnam.

Case 2: VAT tax refund for investment projects

Under Clause 2, Article 15 of the Law on Value Added Tax 2024 and Article 30 of Decree 181/2025/ND-CP, a business with an investment project may receive a VAT tax refund if the following conditions are met:

Case Tax treatment
A business applying the deduction method has a new or expanded investment project Input VAT arising during the investment phase is offset against VAT payable from current business activities
After offsetting, the remaining input VAT is VND 300 million or more Eligible for VAT tax refund

If the investment project has been completed but the business did not apply for refund during the investment phase, it may still submit a VAT tax refund dossier within one year from the project completion date.

Note: A VAT tax refund is not available in the following cases:

  • The enterprise has not fully contributed its charter capital as registered
  • The project belongs to a conditional business sector but the required conditions have not yet been met
  • The business fails to maintain the required business conditions during operation
  • The project involves exploitation of natural resources or minerals (except oil and gas exploration and field development projects), or production projects using extracted minerals that have been processed into other products as prescribed by law

Case 3: VAT tax refund for goods and services subject to the 5% VAT rate

Under Clause 3, Article 15 of the Law on Value Added Tax 2024 and Article 31 of Decree 181/2025/ND-CP, businesses that only produce or supply goods and services subject to the 5% VAT rate may receive a VAT tax refund if:

Case Condition Tax treatment
Business establishments supplying only goods and services subject to the 5% VAT rate Input VAT not yet deducted reaches VND 300 million or more after 12 consecutive months or 4 consecutive quarters Eligible for VAT tax refund

If the business produces or supplies multiple categories of goods or services subject to different VAT rates, it must separately account for the input VAT of the activities subject to the 5% rate.

If separate accounting is not possible, the input VAT for such activities is determined based on the ratio of revenue from goods and services subject to the 5% VAT rate to total taxable revenue during the refund period.

After offsetting against VAT payable from other business activities, if the remaining input VAT is VND 300 million or more, the business may be considered for a VAT tax refund.

Case 4: VAT tax refund upon dissolution or bankruptcy

Under Clause 4, Article 15 of the Law on Value Added Tax 2024 and Article 32 of Decree 181/2025/ND-CP:

A business applying the deduction method, upon dissolution or bankruptcy, may be entitled to a VAT tax refund if:

  • It has overpaid VAT, or
  • It still has input VAT not yet fully deducted

In cases where a cooperative group is converted into a cooperative, or a branch is dissolved, the enterprise or cooperative inheriting the business may continue to deduct or request a VAT tax refund for the uncredited VAT amount in accordance with the regulations.

EXPLORE OUR SERVICES

Case 5: VAT tax refund for goods carried upon exit from Vietnam

Under Clause 5, Article 15 of the Law on Value Added Tax 2024 and Article 33 of Decree 181/2025/ND-CP:

Case Tax treatment
Foreigners or overseas Vietnamese purchasing goods in Vietnam and carrying them abroad upon exit Eligible for VAT tax refund corresponding to the value of the goods carried

Case 6: VAT tax refund for ODA-funded programs and projects

Under Clause 6, Article 15 of the Law on Value Added Tax 2024:

Case Tax treatment
Program owners, project owners, main contractors, or organizations designated by foreign donors to manage ODA-funded programs/projects purchasing goods and services in Vietnam for project implementation Eligible for VAT tax refund for VAT paid on goods and services purchased in Vietnam
Organizations in Vietnam using non-refundable aid or humanitarian aid from foreign organizations or individuals to purchase goods and services for the program or project Eligible for VAT tax refund for VAT paid on goods and services used for the project

Case 7: VAT tax refund for subjects entitled to diplomatic privileges and immunities

Under Clause 7, Article 15 of the Law on Value Added Tax 2024:

Case Tax treatment
Subjects entitled to diplomatic privileges and immunities purchasing goods and services in Vietnam Eligible for VAT tax refund for the VAT amount shown on the invoice

Case 8: VAT tax refund under international treaties

Under Clause 8, Article 15 of the Law on Value Added Tax 2024:

Organizations or business establishments may receive a VAT tax refund if such refund is granted under a decision of the competent authority or under an international treaty to which Vietnam is a party.

Case 9: VAT tax refund under a decision of a competent authority

In addition to the cases above, a business establishment may also receive a VAT tax refund when a competent state authority issues a refund decision in accordance with the law.

3. Frequently asked questions about VAT tax refund

Question 1: How long does a VAT tax refund take?

After receiving the VAT tax refund dossier, the tax authority will classify it into two categories:

Case 1: Refund first, inspection later

Within 6 working days from the date the tax authority issues a notice of dossier acceptance, the tax authority will take one of the following actions:

  • Issue a refund decision if the dossier is eligible
  • Transfer the dossier to the “inspection before refund” category if inspection is required
  • Issue a notice of non-refund if the dossier does not meet the conditions

If the tax authority finds that the dossier contains unclear information or discrepancies compared with its data, it may request the taxpayer to provide explanations or supplement the dossier.

Note: The time taken by the taxpayer to provide explanations or supplement the dossier is not included in the refund processing time.

Case 2: Inspection first, refund later

For dossiers subject to prior inspection, the tax authority will carry out an inspection or audit at the taxpayer’s premises to determine the refundable VAT amount.

The processing time in this case must not exceed 40 days from the date the tax authority issues the notice of dossier acceptance.

After the inspection is completed, the tax authority will issue either a refund decision or a notice of non-refund if the dossier is not eligible.

Question 2: After receiving the refund decision, how long does it take to receive the money?

After issuing the refund decision, the tax authority will transfer the refund amount to the taxpayer within 3 working days if the refund is made via bank account.

In some cases where further verification is required, the payment period may be extended but must not exceed 6 working days from the date of the refund decision.

Question 3: What is the difference between VAT tax refund and VAT deduction?

A VAT tax refund means the tax authority returns the remaining input VAT not yet fully deducted to the business in certain cases prescribed by law, such as export activities, investment projects, or subjects enjoying special incentives.

By contrast, VAT deduction means the business offsets input VAT against output VAT payable. If, after offsetting, some input VAT remains unused, that amount is carried forward to the next tax declaration period for continued deduction.

This is also a common issue businesses look into when they want to understand how to get VAT refund in Vietnam in each specific situation.

Question 4: What is the minimum amount required to be eligible for VAT tax refund?

Under the current regulations, a business is only considered for a VAT tax refund if the input VAT not yet deducted is VND 300 million or more.

If the remaining undeducted input VAT is below VND 300 million, the business will not receive a refund and must continue carrying it forward to the next declaration period for deduction.

Although the rules on VAT tax refund are clearly provided in the law, in practice the process of preparing the dossier and working with the tax authority is often quite complicated, especially for businesses with limited experience in handling refund dossiers.

Even a minor error in the dossier, invoice, or supporting document may cause the tax authority to request additional documents or prolong the processing time. For this reason, many businesses choose to cooperate with a professional tax consulting firm to ensure that the dossier is properly prepared and the refund process is optimized.

4. VAT tax refund service process at Vina TPT

Typically, the VAT tax refund support process is implemented through the following steps:

Step 1: Consultation and refund eligibility assessment
Vina TPT discusses with the enterprise to understand its tax status, business model, and the specific refund case. Based on this information, our specialists will evaluate the eligibility for a VAT tax refund and propose an appropriate implementation approach.

Step 2: Review and preparation of the refund dossier
Vina TPT’s specialists assist the enterprise in reviewing invoices, supporting documents, tax declarations, and other relevant materials to ensure the dossier is complete and compliant before submission to the tax authority.

Step 3: Submission of the dossier and working with the tax authority
The dossier is submitted to the tax authority (directly, by post, or electronically). Vina TPT supports communication and explanations if additional information is required.

Step 4: Monitoring and receiving the refund amount
After the dossier is approved, the tax authority issues the refund decision and transfers the refund amount to the enterprise’s bank account. 

The processing time for a VAT tax refund dossier is typically:

  • Approximately 6 working days for cases of refund first – inspection later.
  • Up to 40 working days for cases of inspection first – refund later.

cases-eligible-for-vat-tax-refund-in-vietnam-in-2026

If your business needs detailed advice on VAT tax refund conditions or support in preparing a refund dossier, the specialists at Vina TPT are ready to assist so that your business can complete the procedure quickly and in compliance with the regulations.
BOOK A FREE CONSULTATION

Overview of Vietnam public holidays for Employees in 2026

Vietnam public holidays in 2026: updated holiday schedule, paid leave rules, and key labor law considerations for employers and employees

Starting from 2026, employees in Vietnam may be entitled to 12 Vietnam public holidays with paid leave each year, an increase of one day compared to previous regulations. These changes in Vietnam public holidays not only affect employees’ holiday plans but also directly impact human resource management and operational costs for businesses, particularly foreign-invested enterprises (FDIs).

The article below provides a comprehensive overview of Vietnam public holidays in 2026 and highlights important regulations that companies should consider when managing their workforce.

overview-of-vietnam-public-holidays-for-employees-in-2026

1. Latest regulations and updates on Vietnam public holidays

Under the Labor Code 2019, employees in Vietnam are entitled to days off with full salary during Vietnam public holidays as prescribed by the State. This is a mandatory benefit applicable to all employees working under labor contracts.

If a Vietnam public holiday coincides with a weekly day off, employees are entitled to a substitute day off on the following working day.

Previously, the system of Vietnam public holidays included 11 paid days off per year, including:

  • New Year’s Day: 1 day (January 1)
  • Lunar New Year (Tet): 5 days
  • Hung Kings’ Commemoration Day: 1 day (10th day of the 3rd lunar month)
  • Reunification Day: 1 day (April 30)
  • International Labor Day: 1 day (May 1)
  • National Day: 2 days (September 2 and one adjacent day)

However, on March 3, 2026, the Politburo approved Resolution No. 80-NQ/TW on the development of Vietnamese culture, officially designating November 24 each year as “Vietnam Culture Day.” This day is expected to become an official holiday to encourage cultural activities and improve the spiritual life of citizens.

For foreign employees working in Vietnam, in addition to the above Vietnam public holidays, they are entitled to two additional days off:

  • 1 traditional holiday of their home country
  • 1 national day of their home country

Both days are granted as paid leave under their labor contracts.

overview-of-vietnam-public-holidays-for-employees-in-2026

2. List of Vietnam public holidays in 2026

Based on the Labor Code and the tentative holiday schedule announced by the government, Vietnam public holidays in 2026 may include the following periods:

Holiday Date Total Days Off Notes
New Year Holiday From Jan 1 to Jan 4, 2026 4 days Including weekend days
Lunar New Year (Tet) From Feb 14 to Feb 22, 2026 9 days Including weekends
Hung Kings’ Commemoration Day Apr 26, 2026 1 day Substitute holiday on Apr 27, 2026
Reunification Day & Labor Day From Apr 30 to May 3, 2026 4 days Including weekend days
Vietnam National Day From Aug 29 to Sep 2, 2026 5 days Including weekend days
Vietnam Culture Day (new) Nov 24, 2026 1 day Official paid holiday

3. Other paid leave regimes besides Vietnam public holidays

In addition to Vietnam public holidays, employees are also entitled to other paid leave regimes under the Labor Code. These include annual leave, maternity leave, and several other special leave cases.

3.1 Annual paid leave in Vietnam

Under the Labor Code, employees who work for the same employer for 12 months are entitled to annual paid leave as follows:

  • 12 days for employees working under normal conditions
  • 14 days for minors, employees with disabilities, or those working in hazardous conditions
  • 16 days for employees performing extremely hazardous or dangerous work

Other important provisions include:

  • Employees who have not completed 12 months of service receive leave calculated proportionally based on months worked
  • Employees working for the same company for over 5 years receive one additional leave day per year
  • When terminating a labor contract, employers must compensate employees for unused annual leave days

3.2 Maternity leave and adoption leave

Under Vietnamese labor and social insurance regulations:

  • Female employees are entitled to 6 months of maternity leave
  • In the case of multiple births, an additional 30 days of leave is granted for each additional child starting from the second child
  • Female employees with children under 12 months old are entitled to 60 minutes of paid break per working day for childcare

3.3 Paternity leave

Male employees participating in social insurance are entitled to paternity leave within 30 days after childbirth, including:

  • 5 days for natural birth
  • 7 days for cesarean delivery
  • 10-14 days in cases of multiple births

EXPLORE OUR SERVICES

4. Recommendations for FDI enterprises regarding Vietnam Public Holidays

For foreign-invested enterprises, managing Vietnam public holidays is not merely about scheduling time off. It also directly affects payroll obligations, overtime costs, and compliance with Vietnamese labor regulations. Mistakes in calculating holiday pay or arranging substitute leave may lead to labor disputes or compliance risks during inspections.
Therefore, companies should standardize HR processes from the early stage of building their HR system, including:

  • Establishing mechanisms to calculate holiday pay and other paid leave in compliance with regulations
  • Controlling overtime costs during major holidays such as Tet
  • Managing additional holiday entitlements for foreign employees
  • Regularly updating regulatory changes related to Vietnam public holidays

For FDI enterprises operating in Vietnam, working with a knowledgeable HR consultant who understands local labor laws can help build a transparent payroll system, reduce compliance risks, and optimize long-term operational costs.

At Vina TPT, our team of HR and legal experts supports businesses in establishing structured systems for holiday management, payroll processing, and labor law compliance. Vina TPT currently provides HR and legal consulting services for many FDI companies operating in Vietnam. Standardizing HR processes from the beginning helps businesses minimize legal risks and focus on sustainable growth strategies in the Vietnamese market.

overview-of-vietnam-public-holidays-for-employees-in-2026

BOOK A FREE CONSULTATION

Personal Income Tax 2026: Key Changes Directly Affecting Employees

personal-income-tax-2026-key-changes-directly-affecting-employees

On December 10, 2025, following the National Assembly’s approval of the Personal Income Tax 2026 Law, several significant changes were introduced regarding the progressive tax schedule, personal and dependent deductions, and the scope of taxable income. These revisions may directly affect the personal income tax obligations of employees and foreign experts working in Vietnam.

The article below highlights the key updates and provides guidance on how to calculate personal income tax in accordance with the regulations applicable from 2026.

personal-income-tax-2026-key-changes-directly-affecting-employees

1. When does the Personal Income Tax Law 2026 take effect?

The amended Personal Income Tax Law 2025 (Law No. 109/2025/QH15), passed by the National Assembly, will officially take effect from July 1, 2026, replacing the 2007 Personal Income Tax Law.

However, for income derived from salaries and wages, important provisions such as the progressive tax schedule and personal deduction levels will apply to the 2026 tax year (from January 1, 2026). This means they will apply to the entire income generated during the year when conducting tax filing and finalization.

2. Key changes under Personal Income Tax 2026

2.1. Reduction of the progressive tax brackets from 7 to 5 levels

The reduction of tax brackets simplifies the calculation of personal income tax and makes it more transparent and easier to apply. This is one of the most notable reforms under Personal Income Tax 2026, aiming to streamline the tax system.

New progressive tax schedule (applicable from the 2026 tax year – from January 1, 2026):

Tax Bracket

Monthly Taxable Income (VND million) Tax Rate (%)

1

Up to 10

5%

2

Over 10 – 30

10%

3

Over 30 – 60

20%

4

Over 60 – 100

30%

5 Over 100

35%

The highest tax rate remains 35%, applied to the portion of taxable income exceeding VND 100 million per month. This adjustment maintains the progressive nature of personal income tax without placing excessive pressure on middle-income earners.

2.2. Significant increase in personal and dependent deductions

Another major change under Personal Income Tax 2026 is the increase in deduction levels for taxpayers and their dependents. According to Article 29(2) of the 2025 amended law, the new deduction levels apply from the 2026 tax year (January 1, 2026):

  • Personal deduction: increased to VND 15.5 million/month (VND 186 million/year), compared to the previous VND 11 million/month.
  • Dependent deduction: increased to VND 6.2 million/month per dependent.

The increase significantly reduces the payable personal income tax for employees with families. When conducting tax filing (kê khai thuế), taxpayers must register their dependents within the prescribed timeline to benefit from these deductions.

2.3. Updated scope of taxable income in the digital economy

The amended law clarifies the scope of taxable and non-taxable income, particularly in the context of the digital economy, freelance work, and multiple income streams. Income generated from digital platforms and online business activities remains subject to personal income tax under general principles.

Taxable income includes:

  • Salaries and wages and wage-related income
  • Remuneration, bonuses, and benefits in cash or in kind
  • Allowances, subsidies, and other income, except for those exempted under regulations

Non-taxable income includes:

  • Allowances for war veterans and national defense/security
  • Hazardous and remote-area allowances
  • Social insurance benefits, occupational accident and disease allowances
  • Severance pay, maternity benefits, adoption allowances
  • Social protection allowances and other government-regulated exemptions

personal-income-tax-2026-key-changes-directly-affecting-employees

3. Increased revenue threshold for household and individual businesses to 500.000.000 VND per year

Under Article 7(1) of the 2025 amended law, resident individuals engaged in business activities with annual revenue of 500.000.000 VND or less are not subject to personal income tax.

Accordingly, from the 2026 tax year, the revenue threshold for personal income tax applicable to household and individual businesses increases to 500.000.000 VND per year, five times higher than the previous VND 100 million threshold applied in 2025.

This adjustment reduces the tax burden on small businesses, increases disposable income, and encourages transparent business operations. It also reflects a broader tax reform trend aimed at supporting sustainable development of the household business sector.

EXPLORE OUR SERVICES

4. How to calculate Personal Income Tax 2026 under the new tax schedule

4.1. Formula for calculating personal income tax in 2026

Personal income tax payable = Taxable income × Applicable progressive tax rate

Where:

Taxable income = Total taxable income − Deductions − Mandatory insurance contributions

Deductions include:

  • Personal deduction: VND 15.500.000 VND/month
  • Dependent deduction: VND 6.200.000 VND/month per dependent
  • Mandatory insurance contributions (social insurance, health insurance, unemployment insurance) and other allowable deductions

The remaining taxable income is then subject to the 5-tier progressive tax schedule. Each portion of income falling within a bracket is taxed at the corresponding rate rather than applying a single rate to the entire income.

4.2. Example of personal income tax calculation

Example: Mr. B earns VND 60.000.000 VND per month and contributes mandatory insurance as follows:

  • Social insurance: 8%
  • Health insurance: 1.5%
  • Unemployment insurance: 1%

He has two dependents and no charitable contributions or additional deductions.

Step 1: Total taxable income
= 60.000.000 VND

Step 2: Total deductions

  • Personal deduction: 15.500.000 VND
  • Dependent deduction: 6.200.000 × 2 = 12.400.000 VND
  • Mandatory insurance: 60.000.000 × (8% + 1.5% + 1%) = 5.757.000 VND

→ Total deductions = 15.500.000 + 12.400.000 + 5.757.000 = 33.657.000 VND

Step 3: Taxable income
= 60.000.000 − 33.657.000 = 26.343.000 VND

Step 4: Apply progressive tax rates

  • First 10.000.000 × 5% = 500.000 VND
  • Remaining 16.343.000 × 10% = 1.634.000 VND

→ Total monthly personal income tax payable: approximately 2.134.000 VND

To understand the calculation method and see a practical example, you can read our detailed guide on How to Calculate Personal Income Tax 2026 in Vietnam.

5. Important notes when applying personal income tax 2026

Employees must accurately determine the timing of income generation to apply the correct tax period and deduction levels. Income arising from 2026 onward will fully apply the revised provisions of Personal Income Tax 2026, including cases where salary payments are made late.

In addition, registering dependents in a timely and complete manner remains a mandatory condition to benefit from deduction policies. Failure to register on time may result in higher temporary withholding during the year, with adjustments or refunds processed during annual tax finalization and tax filing procedures.

To stay updated on the latest developments regarding personal income tax, tax policies, and HR-related regulations, please follow the Events & Insights section of Vina TPT.

BOOK A FREE CONSULTATION

How to Start a Business in Vietnam: Consulting Sector Guide

how-to-start-a-business-in-vietnam-consulting-sector-guide

Vietnam’s business landscape has been expanding rapidly as the government places increasing emphasis on developing the private sector. Today, private enterprises account for around 50% of the country’s GDP and employ more than 80% of the national workforce, with over 940,000 registered businesses currently operating nationwide. 

As this entrepreneurial ecosystem continues to grow, many companies face challenges in areas such as management, marketing strategy, business development, and digital transformation. As a result, professional consulting services are becoming increasingly important for businesses seeking to improve competitiveness and navigate Vietnam’s evolving market environment.

If you are considering establishing a consulting company in Vietnam, understanding the legal framework and business registration process is an essential first step

how-to-start-a-business-in-vietnam-consulting-sector-guide 

1. Is consulting a conditional business line?

Under the Investment Law 2025 (effective from January 3, 2026), most common consulting services, such as management consulting, business consulting, marketing consulting, human resources consulting, and strategy consulting are not classified as conditional business lines.

This allows foreign investors to establish a 100% foreign-owned enterprise without requiring a Vietnamese partner and without applying for additional sub-licenses after obtaining the IRC and ERC. This is a significant advantage compared to sectors included in the restricted market access list.

However, for certain specialized consulting sectors, how to start a business will be more complex because additional industry-specific conditions must be satisfied. In such cases, the enterprise must comply with requirements relating to professional practicing certificates, capacity conditions, or separate licenses in accordance with regulations of the relevant ministries.

Therefore, before initiating procedures, investors should review Decree 31/2021/ND-CP and Decree 239/2025/ND-CP to determine whether the intended business line falls under the conditional category, thereby ensuring that they start a consulting business in Vietnam in the right direction and minimize the risk of dossier amendments.

2. Key consulting services currently in demand in Vietnam

In Vietnam, several consulting sectors are attracting the attention of foreign investors who are determining how to start a business at an early stage, including:

  • Management consulting: Including strategic planning, corporate restructuring, operational optimization, and performance management.
  • Technology and software consulting: Associated with digital transformation, IT system advisory, software solutions, automation, and data management.
  • Marketing consulting: Including brand building, market research, communications, and digital advertising. This group of business support services has been committed to market opening by Vietnam under WTO agreements and does not require a separate sub-license.
  • Tourism and service development consulting: Consulting on product development strategies, destination management, and tourism service operations. For each service group, how to start a business may differ in terms of operational scope and personnel requirements.
  • Healthcare management consulting: Primarily focusing on hospital management, service development strategies, and optimization of healthcare systems. If the enterprise provides medical examination and treatment services or specialized medical practice, it will be subject to conditions under the Law on Medical Examination and Treatment.

In general, strategic and business-support consulting services enjoy a high level of openness to foreign investors, while services directly related to technical expertise or specialized professional practice are subject to stricter conditions.

Explore Our Services

3. Conditions for establishing a consulting company in Vietnam for foreign investors

When establishing a foreign-invested consulting company in Vietnam, investors must meet several basic conditions relating to capital, office location, and management structure. 

3.1 Capital and financial capacity requirements

Although the Enterprise Law 2025 does not set a minimum charter capital for consulting companies, the Department of Finance will review the registered capital to ensure it is appropriate for the company’s operational scale, business plan, and proposed services.

In practice:

  • Charter capital of approximately USD 20,000-50,000 is generally considered appropriate for a professional consulting model with stable personnel and office operations.
  • For smaller-scale models with a limited service scope, charter capital in the range of USD 10,000 may still be accepted if the business plan clearly demonstrates reasonable and low initial investment costs.

Determining an appropriate capital level not only serves dossier appraisal requirements but also creates a financial foundation for operations in the early stage, especially when the enterprise is exploring how to start a business and has not yet generated stable revenue.

3.2 Office location requirements

When a foreign enterprise determines how to start a business in Vietnam, the head office location is a mandatory and important requirement. The location must:

  • Be permitted for use as an office or commercial premises;
  • Not be a residential apartment used solely for housing or a property without business function;
  • Have legal documentation proving the lawful right of use by the lessor.

Choosing an appropriate office location directly affects the validity of the dossier in the process of how to start a business.

If the enterprise has not yet secured a suitable location, Vina TPT provides consultation on virtual office solutions that satisfy enterprise registration conditions in accordance with legal regulations.

The use of a virtual office is a flexible solution in the early stage of how to start a business and is fully acceptable provided that:

  • The address is not located in a residential apartment building or a prohibited business registration area;
  • It is capable of receiving correspondence and official documents from state authorities;
  • The lessor has sufficient documentation proving lawful leasing rights;
  • The building is designated for “office” or “commercial – service” functions.

This solution helps enterprises optimize initial costs while still ensuring legal conditions for obtaining the Investment Registration Certificate (IRC) and the Enterprise Registration Certificate (ERC).

3.3 Legal representative requirements

Another important aspect in how to start a business is the appointment of a legal representative.

A foreign-invested consulting company must have at least one legal representative residing in Vietnam. The legal representative may be a foreign investor lawfully residing in Vietnam, or another individual (a Vietnamese citizen or a foreigner with valid residence documents) appointed by the enterprise.

This person is responsible for:

  • Organizing and managing company operations;
  • Fulfilling tax and financial reporting obligations;
  • Registering labor and social insurance;
  • Working with state authorities in administrative procedures.

Appointing a legal representative residing in Vietnam is a mandatory requirement and plays an important role in ensuring continuity in corporate governance and legal compliance. Lack of appropriate personnel preparation may cause difficulties in how to start a business, particularly when planning to start a consulting business in Vietnam with a foreign management team.

how-to-start-a-business-in-vietnam-consulting-sector-guide

4. How to start a business in Vietnam for a consulting company – detailed step-by-step procedures

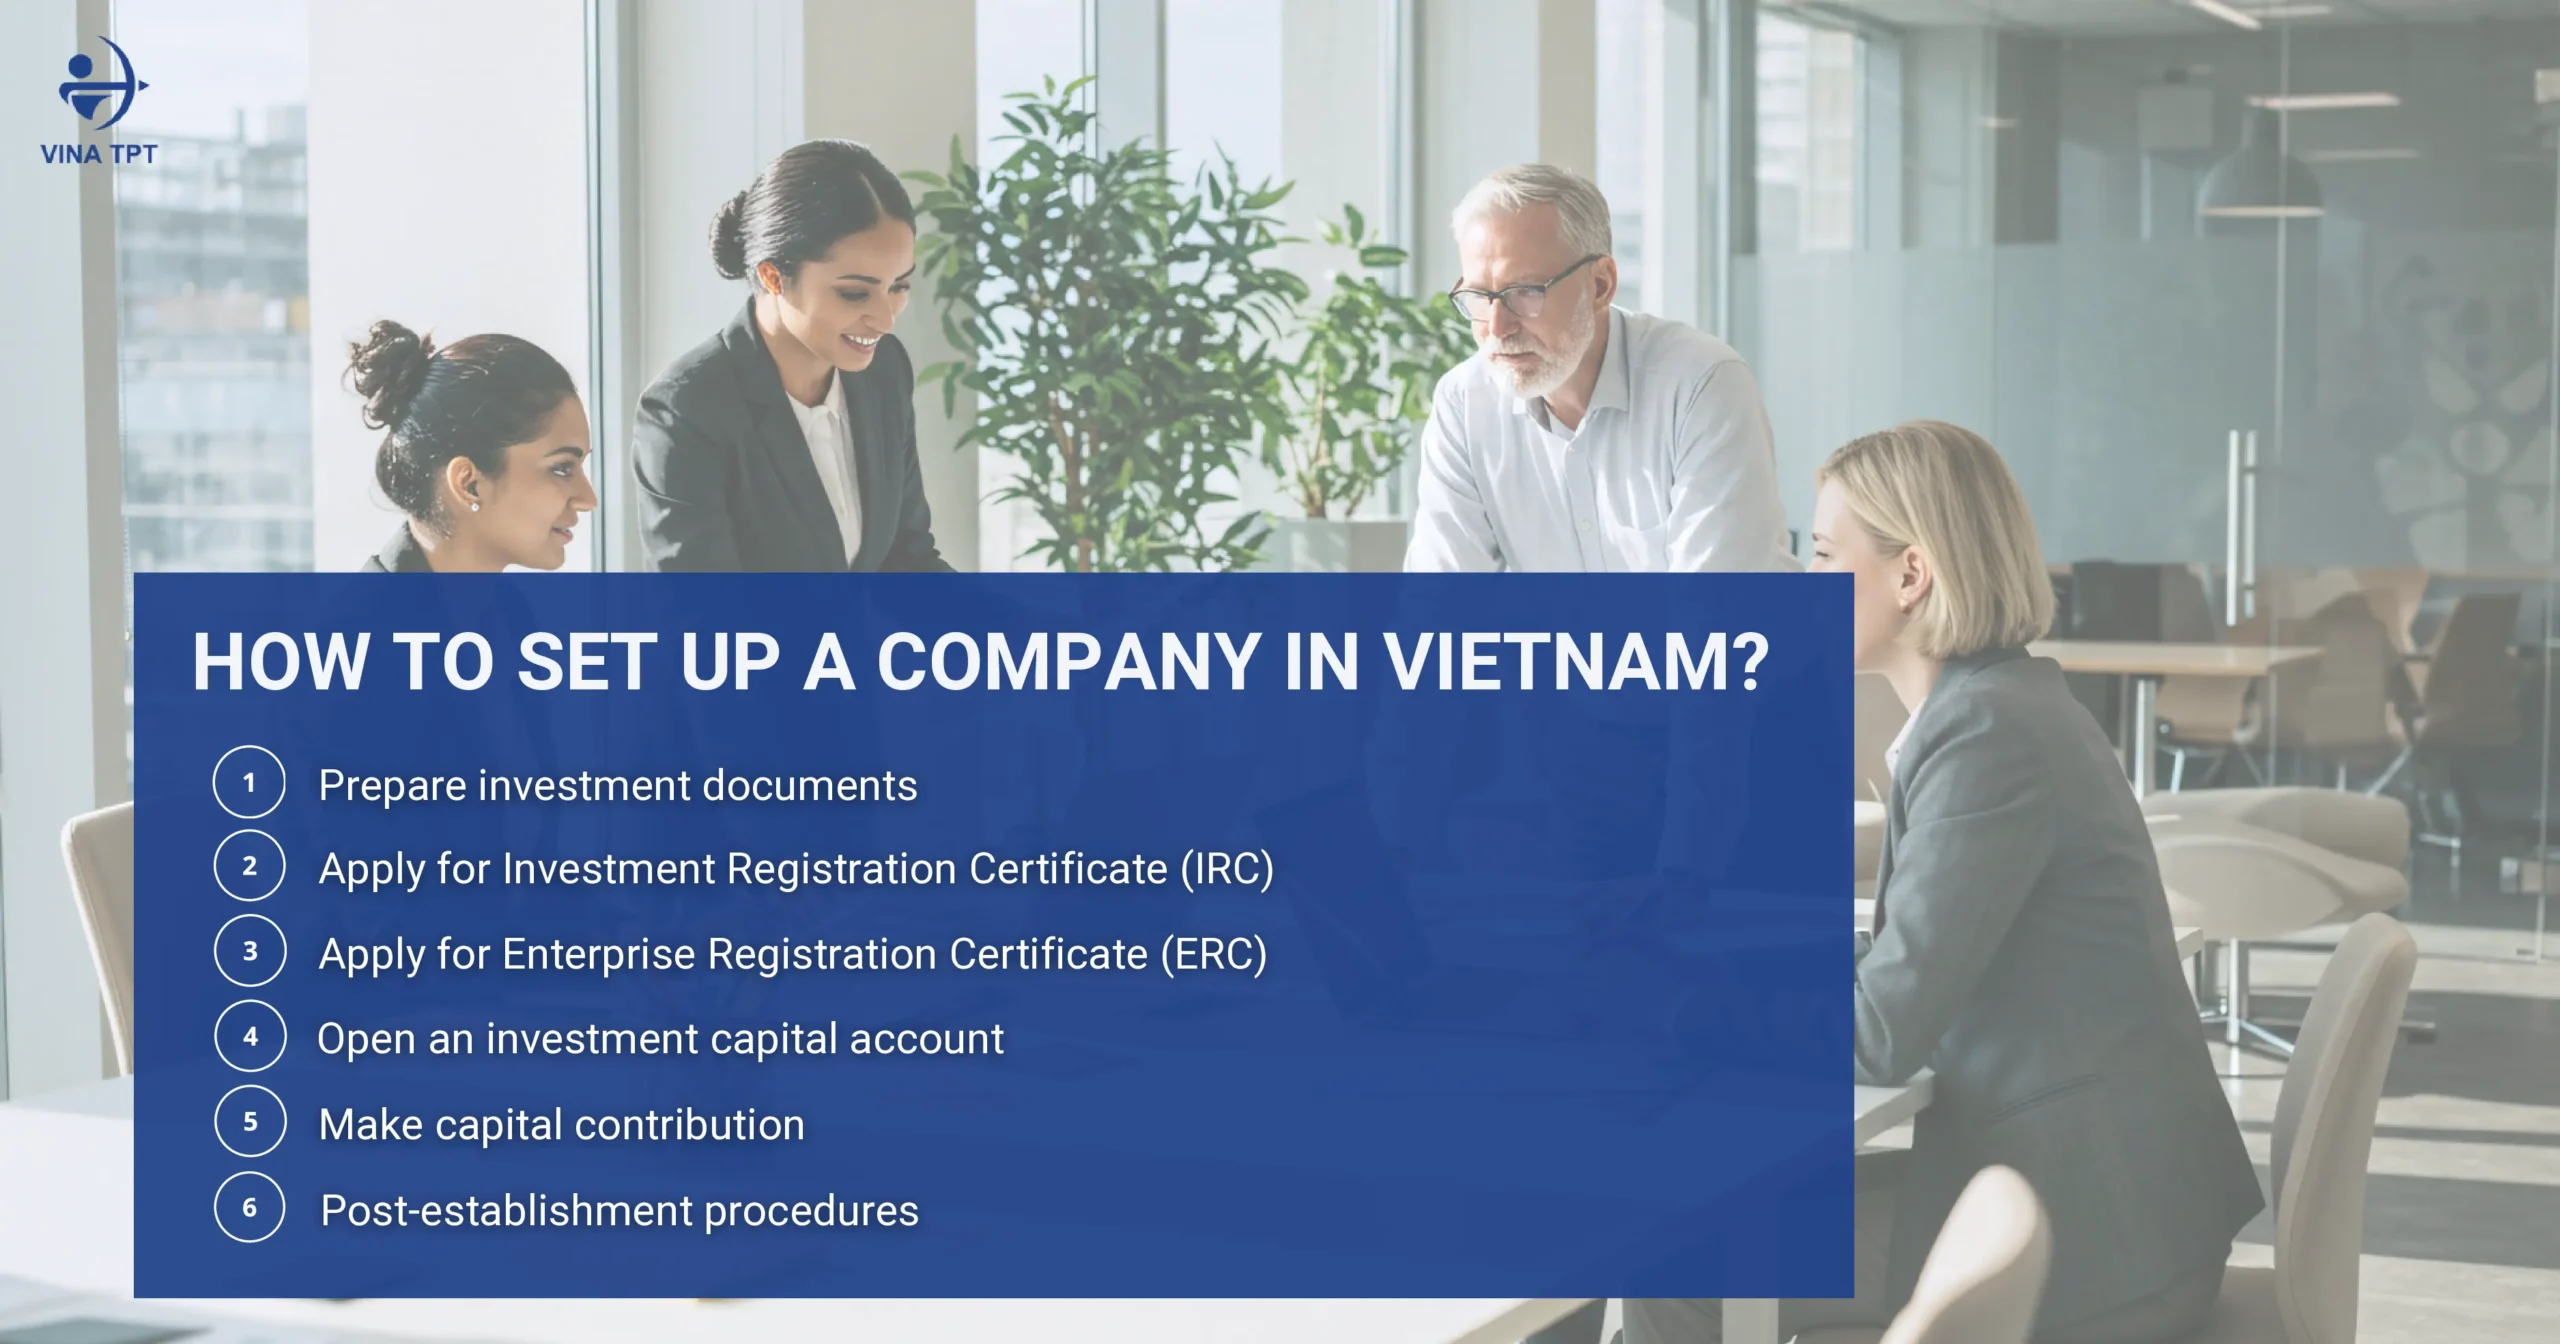
For the consulting sector, how to start a business generally includes the following steps:

Step 1: Prepare the application dossier for the Investment Registration Certificate (IRC)

Under the Investment Law 2025, investors are required to prepare:

  • A written request for implementation of the investment project;
  • Legal documents of the investor (passport for individuals; business registration certificate for organizations);
  • Investment project proposal (objectives of providing consulting services, scale, capital, location, duration of operation);
  • Documents proving financial capacity;
  • Office lease agreement or documents proving the lawful right to use the project location;
  • Technology explanation (if the project involves technology subject to appraisal).

The dossier is submitted to the competent investment registration authority in the province/city where the head office is located.

Note: Foreign documents must undergo consular legalization and be translated into Vietnamese.

Step 2: Obtain the Investment Registration Certificate (IRC)

The IRC records basic information of the consulting project, including:

  • The investor;
  • The registered consulting service business lines;
  • Investment capital and charter capital;
  • Location and duration of operation.

For standard consulting services (not classified as conditional business lines), this procedure mainly focuses on the validity of the dossier and financial capacity.

Step 3: Register the enterprise and obtain the Enterprise Registration Certificate (ERC)

After obtaining the IRC, the enterprise proceeds with company registration under the Enterprise Law 2025 to receive the Enterprise Registration Certificate (ERC).

The ERC establishes the company’s legal entity status and records:

  • The name of the consulting company;
  • Head office address;
  • Legal representative;
  • Charter capital;
  • Business lines (corresponding consulting service codes).

Step 4: Open an investment capital account and contribute capital

Immediately after obtaining the ERC, the enterprise must open a dedicated investment capital account at a bank licensed to operate in Vietnam.

The full charter capital must be contributed within 90 days from the ERC issuance date to avoid administrative penalties and ensure compliance of the enterprise.

Step 5: Complete post-establishment procedures

Before commencing operations, the consulting company must:

  • Complete initial tax registration and register for electronic invoices;
  • Purchase a digital signature;
  • Register labor and social insurance (if employees are hired).

After licensing, tax procedures and capital contribution complete the overall picture of how to start a business in Vietnam; from a practical perspective, this is the “final sprint” of the business registration process in Vietnam that many enterprises tend to underestimate.

Step 6: Obtain sector-specific licenses (if operating in conditional consulting sectors)

If the company provides consulting services in specialized sectors such as construction consulting, legal consulting, securities investment consulting, etc., the enterprise must satisfy additional requirements relating to practicing certificates or professional licenses under the corresponding specialized laws.

Complying with the correct sequence helps ensure that how to start a business proceeds smoothly and minimizes dossier amendments, especially when planning to start a consulting business in Vietnam in sectors requiring specialized expertise.

how-to-start-a-business-in-vietnam-consulting-sector-guide

5. Common mistakes when opening a consulting company in Vietnam

Many investors fail not because the market is difficult, but because they do not properly understand how to start a business. Below are common mistakes foreign investors often make when establishing a consulting company in Vietnam:

Mistake 1: Choosing an inappropriate enterprise structure

Many investors choose an enterprise structure based on habits in their home country without evaluating governance needs and capital mobilization capacity in Vietnam. An unsuitable choice (single-member LLC, multi-member LLC, joint stock company) may misalign with how to start a business, creating limitations in ownership structure, capital transfer, or future fundraising, and may even require conversion procedures later.

To avoid costly adjustments, investors should clearly determine growth objectives, number of shareholders/members, and fundraising plans before submitting the dossier.

Mistake 2: Failing to carefully review business line conditions

Registering business lines that fall under restricted market access or conditional sectors without reviewing relevant regulations often results in IRC dossiers being requested for clarification, amendment, or extended processing time.

Failure to thoroughly review business lines poses legal risks in how to start a business with foreign investment.

Investors should review the list of restricted market access sectors, specialized licensing conditions, and operational scope before finalizing project objectives.

Mistake 3: Selecting the wrong CPC code when registering business lines

For foreign-invested enterprises determining how to start a business correctly, in addition to registering Vietnam Standard Industrial Classification (VSIC) codes, investors must also refer to Vietnam’s WTO service commitments schedule, where services are classified under CPC (Central Product Classification) codes.

Common CPC codes in consulting and business services include:

  • Management consulting services – CPC 865
  • Marketing consulting services (marketing management) – CPC 86503
  • HR consulting services – CPC 86504 (management consulting); labor supply services – CPC 872
  • Software consulting services – CPC 842

Incorrect identification of CPC codes may result in:

  • Misapplication of market access conditions;
  • Misunderstanding of foreign ownership limits;
  • Unnecessary requirements for specialized licenses;
  • IRC dossier amendments.

Therefore, properly reviewing CPC codes before submitting the investment dossier is crucial to ensure accurate appraisal and minimize future amendment risks.

Mistake 4: Confusing the IRC and ERC procedures

Foreign-invested enterprises must generally follow the sequence: obtain the IRC (project approval) first, then register the ERC (legal entity establishment).

Confusing these procedures or preparing dossiers in the wrong order may delay implementation plans and lead to amendments.

Investors should build a legal roadmap in stages and prepare documentation corresponding to each certificate type.

Mistake 5: Lack of post-establishment financial and tax planning

Many enterprises focus on licensing but fail to anticipate tax obligations, operating costs, and periodic filing schedules, leading to penalties and operational disruption.

Immediately after establishment, enterprises should set up an accounting system, register e-invoices and digital signatures, and establish monthly/quarterly compliance plans to ensure stable operations.

Mistake 6: Failure to prepare labor and work permit plans

For foreign managers or experts, work permits and lawful residence status are required for long-term employment in Vietnam.

Without prior planning, enterprises may face management time limitations or urgent administrative procedures affecting operations.

Labor planning, work permits, and temporary residence cards should be integrated immediately after completing establishment procedures.

Mistake 7: Lack of understanding of the local business environment and culture

Differences in working styles, administrative procedures, and communication standards may affect negotiations, HR management, and coordination with partners or authorities.

Understanding the local context and establishing appropriate internal processes helps reduce operational friction and improve implementation efficiency from the early stage.

In cases where investors wish to optimize how to start a business and minimize potential risks, engaging professional consulting services can help standardize the entire process.

With over 20 years of experience supporting FDI enterprises in company formation, tax – accounting, and HR services in Vietnam, Vina TPT provides comprehensive consulting and implementation solutions, ensuring compliance with regulations and alignment with long-term investment objectives.

Contact Vina TPT for detailed consultation on how to start a business in line with your business model and investment goals.

how-to-start-a-business-in-vietnam-consulting-sector-guide

BOOK A FREE CONSULTATION

Outsourced Bookkeeping Services in Vietnam: Why It Helps Businesses Grow Faster

compare-in-house-outsourced-bookkeeping-services-vina-tpt-2

Managing in-house financial records often drains vital time and capital that should be spent on business expansion. Instead of struggling with complex tax compliance and reporting, savvy businesses are turning to outsourced bookkeeping to reduce overhead costs and guarantee professional accuracy. 

This article explores how outsourced bookkeeping services as a strategic growth engine, highlighting the specific challenges it solves, the seamless workflow provided by Vina TPT, and the ideal timing to transition for maximum operational freedom.

1. What is Outsourced Bookkeeping?

Outsourced bookkeeping means delegating your daily financial tasks: transaction recording, bank reconciliations, invoice management, financial statements, VAT/CIT reporting, and compliance to a professional external team. Unlike hiring a full-time accountant (with high salary, benefits, and training needs), you pay a fixed monthly fee for expert, scalable support.

This model is perfect for SMEs and foreign-invested companies in Vietnam that want to avoid local accounting complexities while staying compliant with VAS, IFRS, and tax regulations.

Learn more about Vietnamese accounting standards (VAS)

2. Key Challenges of In-House Bookkeeping That Slow Growth

In-house bookkeeping often creates hidden barriers:

  • High salary costs for qualified accountants (VND 15 – 30 million/month + insurance and bonuses).
  • Constant training to keep up with frequent law changes (VAT adjustments, e-invoice mandates, CIT updates in 2026).
  • Risk of penalties from errors in reporting or late filings (fines can reach tens of millions VND).
  • Management time wasted on admin instead of sales, product development, or market expansion.
  • Difficulty scaling during rapid growth or seasonal peaks without adding headcount.

These issues can consume 20–30% of operational budget and delay business momentum.

compare-in-house-outsourced-bookkeeping-services-vina-tpt

3. How Outsourced Bookkeeping Accelerates Business Growth

Partnering with Vina TPT for outsourced bookkeeping drives faster growth by:

  • Offering predictable low costs, typically 30% cheaper than in-house, freeing capital for marketing, hiring, or R&D.
  • Ensuring expert compliance, our team is always updated on 2026 regulations, eliminating penalty risks and audit stress.
  • Providing scalable support, handle increased transactions or headcount seamlessly without hiring extra staff.
  • Delivering faster, accurate reporting and real-time financial insights for better strategic decisions.
  • Allowing focus on core business, leaders concentrate on sales, innovation, and expansion instead of paperwork.

Explore Outsourced Bookkeeping Services

4. How Vina TPT’s Outsourced Bookkeeping Service Works

Vina TPT’s service is designed to be simple, secure, and efficient for foreign and local businesses.

Process overview:

  1. Free consultation & needs assessment: We discuss your business size, transaction volume, current setup, and goals.
  2. Secure data handover: Transfer existing records (bank statements, invoices, contracts) via encrypted portal.
  3. Daily/weekly bookkeeping: Our certified accountants record transactions, reconcile accounts, manage payables/receivables, and prepare trial balances.
  4. Monthly compliance & reporting: Deliver accurate financial statements, VAT/CIT returns, e-invoice filings, and tax declarations on time.
  5. Ongoing advisory & support: Unlimited queries, year-end audit preparation, and strategic financial guidance.

All work is 100% compliant with Vietnamese laws, using secure cloud tools. Pricing is transparent and flexible, starting from VND 3 million/month based on volume (no hidden fees).

5. When to Choose Outsourced Bookkeeping

This serivce is the strategic choice for newly established startups, SMEs with 1 to 50 employees, and high-growth firms looking to scale without administrative friction. It is particularly essential for businesses navigating complex compliance requirements, such as VAT, CIT, and e-invoicing allowing leadership to mitigate regulatory risks while focusing entirely on expansion. By transitioning to this service, companies can ensure professional financial management while maintaining the agility needed to thrive in a competitive market.

6. Conclusion

Outsourced bookkeeping eliminates major growth barriers: high costs, compliance headaches, and time lost on admin. With Vina TPT, you get reliable, expert support at a fraction of the cost—freeing your team to focus on what drives success: expansion and innovation.

Ready to accelerate your growth? Contact Vina TPT today for a free consultation and personalized cost-saving assessment. Let our experts handle your bookkeeping so you can build your future in Vietnam.

BOOK A FREE CONSULTATION

Vietnam Representative Office Compliance Obligations Guide

Vietnam-Representative-Office-Compliance-Obligations-Guide-vina-tpt-2

Vietnam-Representative-Office-Compliance-Obligations-Guide-Vina-tpt

Are you a foreign investor eyeing Vietnam’s dynamic market but wary of full-scale commitments? Establishing a Representative Office (RO) offers a low-risk entry point for market research, networking, and promotion without generating revenue. However, navigating compliance is crucial to avoid fines, license revocation, or unintended tax liabilities like Permanent Establishment (PE) risks. This comprehensive guide, updated for 2026 regulations, draws from key laws such as the Commercial Law 2005, Enterprise Law 2020, and Decree 07/2016/ND-CP (with procedural tweaks noted in recent updates).  

Key benefits of staying compliant include: 

  • Protecting your parent company’s reputation and avoiding penalties  
  • Leveraging Vietnam’s FDI incentives while minimizing bureaucratic hurdles. 
  • Ensuring seamless extensions or closures without disruptions. 

By the end, you’ll have actionable insights, checklists, and expert tips to thrive. Let’s dive in, starting with the basics. 

1. What is a Representative Office in Vietnam? 

A Representative Office (RO) in Vietnam serves as a non-commercial extension of a foreign company, ideal for exploring opportunities without direct business activities. Governed by evolving regulations, it’s a popular choice for FDI firms in 2026, with over 2,000 active ROs contributing to Vietnam’s economic growth. This section builds a foundational understanding, comparing it to other structures for informed decisions. 

Permitted and Prohibited Activities 

ROs are strictly limited to non-revenue-generating roles to prevent PE triggers. Permitted activities include: 

  • Market surveys and research. 
  • Promoting parent company products/services. 
  • Liaison with local partners. 
  • Attending trade fairs and seminars. 

Prohibited activities encompass: 

  • Direct sales or contract signing. 
  • Revenue generation or invoicing. 
  • Manufacturing or service provision for profit. 
  • Sub-leasing office space. 

For example, an RO can host promotional events but cannot close deals—violations could lead to audits or shutdowns. 

Comparison with Branches and Subsidiaries 

Structure  Legal Status  Activities  Taxation  Liability 
Representative Office  Dependent unit, no legal personality  Non-commercial (research, promotion)  No CIT/VAT; PIT on staff  Limited to parent company 
Branch  Dependent, but operational  Commercial trading possible  CIT (20%), VAT applicable  Parent liable 
Subsidiary (LLC/JSC)  Independent entity  Full business operations  CIT (20%), VAT, audits  Limited to invested capital 

ROs offer simpler compliance for initial market entry, unlike branches which require more reporting or subsidiaries needing capital injection (minimum varies by sector). Choose RO if your goal is testing waters without financial exposure. 

2. Key Conditions for Establishing a Representative Office 

Setting up an RO in Vietnam is straightforward but requires meeting eligibility thresholds to ensure alignment with national interests. This process, handled by the Department of Industry and Trade (DOIT), emphasizes transparency and typically completes in 4-6 weeks. Here’s a logical breakdown from requirements to execution. 

Eligibility Requirements for Foreign Companies 

Foreign entities must fulfill these criteria: 

  • Parent company operational for at least 1 year in home country. 
  • Activities compliant with Vietnam’s WTO and international treaties (e.g., no restricted sectors without ministerial approval). 
  • Proof of good standing and financial stability via audited statements. 
  • No prior violations in Vietnam. 

These ensure only reputable firms enter, reducing risks for local markets. 

Required Documents and Application Process 

Follow these numbered steps: 

  1. Prepare legalized documents: Certificate of incorporation, audited financials (last year), and parent company charter. 
  2. Draft application form (Form I-1 from Decree 07/2016/ND-CP). 
  3. Secure office lease agreement in Vietnam. 
  4. Notarize and translate all docs into Vietnamese. 
  5. Submit to provincial DOIT or relevant ministry. 

Include a letter of appointment for the Chief Representative. Digital submissions are encouraged in 2026 for faster processing. 

3. Post-Registration Compliance Procedures 

Once licensed, immediate actions are vital to operationalize your RO legally. This phase focuses on administrative setups within 30-45 days, preventing delays in hiring or banking. Overlooking these can trigger inspections—follow this timeline-driven guide. 

Initial Setup Steps (Stamp, Tax Code, Bank Account) 

  1. Register official seal (stamp) with Public Security within 15 days. 
  2. Obtain tax identification number (TIN) from local tax authority. 
  3. Open a foreign currency bank account for operational expenses (e.g., salaries, rent). 
  4. Register with social insurance if hiring staff. 

These steps enable daily functions; use banks like HSBC for RO-specific accounts. 

Notifying Authorities and Publishing Announcements 

  • Notify DOIT of operations start within 7 days. 
  • Publish establishment announcement in three consecutive newspaper issues (print or online). 
  • Inform tax and labor departments of Chief Representative details. 

This publicizes your presence, ensuring transparency per Decree 07. 

Common Pitfalls to Avoid 

  • Delaying seal registration: Leads to invalid contracts. 
  • Ignoring TIN: Blocks payroll processing. 
  • Incomplete publications: Fines up to 10 million VND. 
  • Tip: Engage local consultants for seamless compliance.

Establishment Representative Office with Vina TPT

4. Tax Compliance Obligations for Representative Offices

ROs enjoy tax exemptions but must handle employee-related duties diligently. No CIT or VAT applies since no revenue is generated, but PIT withholding is mandatory. This section outlines exemptions and filings with practical examples. 

Personal Income Tax (PIT) Withholding and Reporting 

  • Withhold PIT on salaries (progressive rates: 5-35%). 
  • File monthly/quarterly declarations; annual finalization by March 31. 
  • Example: For a 20 million VND salary, withhold ~10% PIT plus insurances. 

Report via e-tax portal for efficiency. 

Other Taxes and Filings 

  • Business license tax: Pay if operations exceed thresholds. 
  • Monthly filings: PIT and insurances. 
  • Deadlines: Quarterly by end of month following quarter. 

Vietnam-Representative-Office-Compliance-Obligations-Guide-vina-tpt-3

5. Labor and Payroll Compliance Requirements 

Hiring staff for your Representative Office (RO) in Vietnam must align with the Labor Code 2019 (amended) and Social Insurance Law 2024 to ensure fair treatment and avoid penalties. This includes drafting compliant contracts, managing payroll deductions, and handling insurances. With employer contributions totaling approximately 21.5% of the salary base (as per 2026 rates), budgeting is essential. Below, we clarify employee contributions to social insurance (SHUI) and expand on requirements for foreign workers, including the Temporary Residence Card (TRC). 

Hiring Employees and Labor Contracts 

  • Draft bilingual (English-Vietnamese) contracts detailing job terms, salary, benefits, working hours (up to 48 hours/week), and probation periods (up to 60 days for skilled roles). 
  • Register contracts with the local Department of Labor, Invalids, and Social Affairs (DOLISA) within 30 days of signing. 
  • Limit staffing to roles essential for RO functions like market research or liaison; there’s no strict cap, but justify headcount in annual reports to authorities. 

Consider including non-compete clauses for sensitive positions, but ensure they comply with Vietnamese law limits (e.g., no more than 1 year post-employment). For all employees, emphasize transparency to build trust and reduce disputes. 

Social, Health, and Unemployment Insurance Contributions 

All employees, including locals and foreigners (with some exemptions), must participate in mandatory insurances under the Social Insurance Law 2024. Contributions are calculated on the salary base (minimum regional wage or actual salary, capped at 20 times the base salary—approximately 36 million VND/month in 2026 for most cases). Here’s the breakdown for 2026 rates, clarifying both employer and employee shares: 

Insurance Type  Employer Share (%)  Employee Share (%)  Base  Notes 
Social Insurance (BHXH) – Pension and Death  14  8  Salary  Covers retirement and survivor benefits. 
Social Insurance (BHXH) – Sickness and Maternity  3  0  Salary  Employer-funded for sick leave and maternity (up to 6 months paid). 
Social Insurance (BHXH) – Occupational Accident and Disease  0.5  0  Salary  Covers work-related injuries; optional for low-risk ROs but mandatory in practice. 
Health Insurance (BHYT)  3  1.5  Salary  Provides medical coverage; integrated with national health system. 
Unemployment Insurance (BHTN)  1  1  Salary  Supports job loss benefits (up to 60% salary for 3-12 months). 
Total  21.5  10.5  Salary  Overall cap: 32% combined. 

Explore Payroll & Insurance Services

Work Permits and Visas for Foreign Staff 

Foreign staff (expats) add expertise but require extra steps for legal work and residency. Process these early to avoid operational delays. 

  1. Apply for a work permit via DOLISA (exemptions available for intra-company transfers, managers, or short-term experts under 30 days). 
  2. Secure a visa (e.g., LĐ1/LĐ2 for labor) upon entry or conversion. 
  3. Requirements: Health certificate (issued in Vietnam or legalized abroad), clean criminal record (from home country), and professional qualifications (e.g., degree + 3 years experience for skilled roles). 

The process typically takes 15-30 days; renew permits annually (up to 2 years max). For long-term stays, obtain a Temporary Residence Card (TRC) to replace frequent visa runs—it’s mandatory for expats residing over 1 year and simplifies travel in/out of Vietnam. 

6. Annual Reporting and Record-Keeping Duties 

Sustained compliance hinges on timely reports and audits. ROs must document activities for potential inspections every 3-5 years. Use templates for efficiency. 

Representative office annual performance report 

  • Submit to DOIT by January 30: Detail operations, staff, expenses. 
  • Include financial summaries (no audits required). 
  • Template: Cover achievements, challenges, future plans. 

Statistical and Labor Reports 

Report Type  Frequency  Deadline 
Annual performance report  Annual  Jan 30 
Labor Changes  Monthly  End of month 
Statistical  Semi-annual  Jul/Jan 

7. Ready to Ensure Full Compliance for Your Representative Office in Vietnam? 

Navigating the compliance landscape for a Representative Office (RO) in Vietnam can be complex, with evolving regulations, strict deadlines, and potential risks like fines, license revocation, or Permanent Establishment (PE) issues. By following the detailed guidance in this article you can operate confidently and focus on market growth. 

At Vina TPT, we specialize in supporting foreign investors and FDI enterprises with comprehensive, reliable solutions tailored to Vietnam’s business environment. With over 20 years of experience and a team of certified experts in Vietnamese Accounting Standards (VAS), IFRS, international tax law, and FDI regulations, we have successfully assisted more than 200 international clients in establishing and maintaining compliant operations. 

Our Key Services for Representative Offices and FDI Businesses 

  • Tax advisory and compliance — including PIT withholding/finalization, business license tax handling, and PE risk assessments. 
  • Labor and HR support — contract drafting, social/health/unemployment insurance registration (BHXH/BHYT/BHTN), work permit/TRC applications for foreign staff, and monthly labor reports. 
  • RO setup, extension, and closure consulting — handling all paperwork, DOIT submissions, seal/tax code/bank account setups, and termination clearances. 
  • Annual reporting and audit preparation — ensuring timely activity/statistical reports and readiness for government inspections. 

We prioritize 100% data protection, transparent pricing, and personalized service to help your RO thrive without unnecessary stress. Whether you’re just starting market research or managing an established office in Ho Chi Minh City or beyond, our one-stop approach saves time and minimizes risks. 

Let Vina TPT be your trusted partner in Vietnam – ensuring seamless compliance so you can focus on business growth in one of Asia’s most promising markets. Reach out now, we’re here to help! 

BOOK A FREE CONSULTATION

[Newsletter] Vietnam Tax Policy Updates December 2025 – VAT, FCT, PIT and Labor Regulations

Vina TPT Tax Expert analyzing Vietnam Tax Policy Updates 2026

Vina TPT Tax Expert analyzing Vietnam Tax Policy Updates 2026

Based on the latest Vietnam Tax Policy Updates, Vina TPT is pleased to provide a summary of critical tax and labor regulations that will directly impact business operations starting from late 2025 and into 2026. In the context of a rapidly changing legal environment, staying compliant is not just a legal requirement but a strategic advantage for enterprises operating in Vietnam.

1. Vietnam Tax Policy Updates: Value Added Tax (VAT)

Regarding VAT refunds for investment projects implemented before 01 July 2025 under the new regulations.

Official Letter No. 5938/CT-CS dated 12/12/2025 of the Department of Taxation refers to the value-added tax (VAT) policy related to tax refund for investment projects. Accordingly, in case business establishments have investment projects that have been invested before July 1, 2025 and are still in the investment stage from the effective date of Decree 181/2025/ND-CP (July 1, 2025), tax refund regulations for investment ( according to Clause 2, Article 15 of the VAT Law No. 48/2024/QH15 and Article 30 of Decree No. 181/2025/ND-CP ).

This means that business establishments need to clearly determine the time of starting the investment project and the implementation period to determine the benefits of VAT refund according to the new regulations. At the same time, operating business establishments with investment projects eligible for VAT refund must make a separate VAT declaration dossier for the investment project (on the declaration form 02/GTGT) in accordance with the law on tax administration (Point d, Clause 2, Article 7 of Decree No. 126/2020/ND-CP).
2. Vietnam Tax Policy Updates: Foreign Contractor Tax (FCT)

2.1. Regarding the contractor tax policy in cases where the company generates income from subscription service contracts in Vietnam.

Official Letter No. 4998/HYE-QLDN2 dated 02 December 2025 issued by Hung Yen Provincial Tax Department, the tax payment obligations are noted as follows:

a. Determination of Service Type:

  • Important: First, it is necessary to clearly determine whether the services provided under the contract are software products or software services as prescribed in Decree No. 71/2007/ND-CPstatus2 . To determine, it is necessary to contact the state management agency for information and communication.
  • If it is a software product/service: Exempt from VAT.
  • If not a software product/service: Subject to VAT and CIT according to the provisions of contractor tax.

b. Value Added Tax (VAT):

  • If not a software product/service:
  • Tax calculation method: Calculated directly on revenue.
  • VAT rate: 5% of revenue.

c. Corporate Income Tax (CIT):

  • Tax calculation method:
  • Direct method (percentage to revenue): Applicable if the foreign contractor does not meet the conditions for paying tax according to the declaration method (revenue – expenses).
  • Turnover for CIT calculation: All turnover received by the foreign contractor, exclusive of VAT, including expenses paid by the Vietnamese party on behalf of the Vietnamese party (if any).
  • Rate (%) of CIT calculated on taxable turnover:
  • If income from royalties (according to Clause 3, Article 7 of Circular 103/2014/TT-BTCstatus2 ): 10%
  • If not royalty income: 5%

d. Important Note:

  • New guiding documents: When the competent authority issues a document guiding the implementation of the Law on CIT No. 67/2025/QH15, it is necessary to comply with these new regulations.
  • Accurate determination of the type of service: Determining the exact type of service (software or not) is a key factor in determining the right tax obligation

2.2. Regarding Foreign Contractor Tax (FCT) on the use of foreign brands.

Based on the guidance provided by the Quang Ngai Provincial Tax Department in Official Letter No. 3601/QNG-QLDN1 dated 12 December 2025, if a Vietnamese company enters into a contract with a foreign company for the use of instructions and content associated with the foreign company’s brand in Vietnam, the Vietnamese party shall bear the responsibility for declaring and paying Foreign Contractor Tax (FCT) as follows:

a. Responsibility for tax deduction and payment:

Vietnamese companies must be obliged to declare, deduct and pay tax on behalf of foreign contractors for the copyright fee for using foreign brands in Vietnam, because this is a payment to foreign organizations that do not have permanent establishments in Vietnam.

b. Legal grounds:

The declaration, deduction and payment of tax must comply with the provisions of current law, including:

  • Circular No. 103/2014/TT-BTC dated 06/8/2014 of the Ministry of Finance (especially Article 4).
  • VAT Law No. 48/2024/QH15 dated 26/11/2024, Decree No. 181/2025/ND-CP dated 01/7/2025, Circular No. 69/2025/TT-BTC dated 01/7/2025 (related to VAT).
  • Decree No. 126/2020/ND-CP dated 19/10/2020 of the Government (especially Point n, Clause 4 and Point e, Clause 6, Article 8).

c. Form of Payment:

This liability arises regardless of the form of payment, including payment directly or through payment.

d. Tax Declaration:

  • VAT and CIT of foreign contractors applied by the direct method or CIT under the mixed method must be declared for each time of payment incurred. If you pay multiple times a month, you can declare it monthly.
  • VAT and CIT by the direct method or CIT by the mixed method of foreign contractors must be finalized at the end of the contract. CIT according to the declaration method of foreign contractors is settled annually.

3. Vietnam Tax Policy Updates: Personal Income Tax (PIT)

3.1. Regarding the registration of a new tax identification number (TIN) and the tax identification number for dependents.

Official Letter No. 6030/CT-NVT dated 16 December 2025 issued by the Tax Department regarding notes on the registration of new tax identification numbers and tax identification numbers for dependents. Specifically, pursuant to Clause 2 Article 38 and Clause 2 Article 39 of Circular No. 86/2024/TT-BTC, from 1 July 2025, the personal identification number shall be used in replacement of the individual tax identification number (TIN).

Taxpayers may use their personal identification number when their tax registration information has been successfully matched with the individual’s information stored in the National Population Database. At that time, the taxpayer shall record the personal identification number in the “Tax Identification Number” field on tax returns, tax payment documents, invoices, personal income tax (PIT) withholding dossiers, and other dossiers, documents, and materials that require declaration of the TIN.

From July 1, 2025, enterprises will register new tax returns for employees when they first go to work or register new employees for new employees/dependents who do not have tax returns according to the provisions of Point b, Clause 1, Article 22 of Circular 86/2024/TT-BTC. After successful tax registration (i.e. the taxpayer’s tax registration data matches the personal information stored in the national population database), the enterprise uses the personal identification number for tax deduction, declaration and payment as prescribed.

Regarding the self-registration of dependents when changing workplaces, taxpayers can register dependents for family circumstance deduction through web portals such as: National Public Service Portal (https://dichvucong.gov.vn); Information system for settlement of administrative procedures (https://dichvucong.gdt.gov.vn); Electronic Tax Portal (https://thuedientu.gdt.gov.vn “personal” module or register directly with the tax authority.

Taxpayers are only required to register and submit documents proving that each dependent is eligible for family circumstance deduction (according to the provisions of Point i, Clause 1, Article 9 of Circular No. 111/2013/TT-BTC). However, when changing the place of work, there is no connection to share information between the income-paying agencies (the new working unit has no basis to calculate the deduction of dependents), so the taxpayer must re-register the dependents at the new workplace.

Currently, the Ministry of Finance is developing a draft of a new PIT Law and a new Law on Tax Administration. Accordingly, the tax authority will build and operate a centralized electronic data system, allowing the storage and lookup of information on family circumstance deduction of dependents through tax identification numbers/personal identification numbers

4. Invoice Policy Updates

4.1. VAT policy and invoicing regulations regarding the time of invoice issuance and the VAT policy applicable to digital products and services.

According to Official Letter No. 5706/CT-CS dated 3 December 2025 issued by the Tax Department, the related contents are responded as follows: Regarding value added tax (VAT) policy, the Company should note that from July 1, 2025, regulations on 0% tax rate, conditions for applying 0% tax rate and conditions for deduction and refund of tax for exported goods and services have been specifically regulated in new legal documents ( Article 9 of Law on Value Added Tax No. 48/2024/QH15, Decree No. 181/2025/ND-CP and Circular No. 69/2025/TT-BTC ). This includes digital information content products.

For the period before July 1, 2025, it is necessary to base on the legal documents in effect at that time ( Clause 6, Article 1 of Law No. 31/2013/QH13, Decree No. 209/2013/ND-CP and Circular No. 219/2013/TT-BTC ), and at the same time refer to previous guidance documents of the Tax Department to ensure compliance with regulations at each period.

Regarding invoice issuance time, (Clause 1 and Clause 4, Article 9 of Decree No. 123/2020/ND-CP ), it is necessary to clearly define the time of transferring ownership/right to use the card to the customer according to the company’s terms of service. Accordingly, when the customer has paid, the money has been transferred to the company’s account and the customer has received the code, the transaction is considered complete . This determination needs to be based on comparison with actual records, the nature of the operation and the provisions of e-commerce law to ensure compliance with regulations on invoice issuance time.

4.2. Regarding the issuance of invoices for on-the-spot export goods.

Accordingly, Official Letter No. 3258/TNI-QLDN2 dated 1 December 2025 issued by the Tay Ninh Provincial Tax Department provides guidance on the issuance of invoices for on-the-spot export goods as follows:

The Company is responsible for issuing VAT invoices when selling goods (Article 4, Decree 123/2020/ND-CP, amended by Article 1, Decree 70/2025/ND-CP) , including cases of goods and services used for promotion, advertising, samples; goods and services used for giving, donating, exchanging, paying in lieu of salary for employees and internal consumption (except for goods circulated internally to continue the production process); exporting goods in the form of lending, borrowing or returning goods. Invoices must be issued and delivered to the buyer.

Regarding invoice content, the Company must comply with (Article 10, Decree 123/2020/ND-CP, amended by Article 1, Decree 70/2025/ND-CP) and (Clause 6, Article 28, Decree 181/2025/ND-CP) . This includes providing complete and accurate information of the buyer on the VAT invoice, especially in the case of on-the-spot export.

Regarding the conditions for deducting input VAT on goods processed for export, the company needs to ensure that it has all the required documents (Clause 6, Article 28, Decree 181/2025/ND-CP) , including: export processing contract, VAT invoice clearly stating the processing price and quantity of processed goods returned to foreign countries, transfer slip of processed products with confirmation from the parties, and must make non-cash payments according to the provisions of law. Customs declarations also need to be made according to customs laws.

5. Tax administration: Key Updates on Tax and Invoice Penalties Applicable from 16 January 2026

Official Letter No. 6175/CT-PC dated 22 December 2025 issued by the Tax Department regarding the introduction of new provisions under Decree No. 310/2025/NĐ-CP, which amends and supplements a number of articles of Decree No. 125/2020/NĐ-CP, effective from 16 January 2026, with the following important amendments and additions on tax and invoice penalties:

5.1. Supplementing the scope of adjustment and some administrative violations on taxes and invoices:

  • Supplementing revenues in accordance with the law on management and investment of state capital in enterprises assigned to tax administration agencies to manage revenues within the scope of adjustment.
  • Supplementing the sanctioned subjects being the constituent units responsible for declaration and violations related to the notification of this constituent unit.
  • Amending and supplementing regulations on sanctions for e-invoice service providers that provide solutions that do not comply with the principles of the law on invoices.

5.2. Amending and supplementing the principles of sanctioning administrative violations related to taxes and invoices:

Amendments to regulations on sanctions in case taxpayers incorrectly declare many indicators on tax dossiers on the same day. Abolish the aggravating circumstance of “repeated administrative violations” in some cases.

Supplementing regulations on sanctions in case taxpayers falsely declare many indicators on one tax dossier.

Supplementing regulations on sanctions for acts of invoicing at the wrong time or failing to issue invoices.

5.3. Amending and supplementing regulations on determination of aggravating circumstances of “large-scale administrative violations”:

Clearly stipulate 02 cases of application of the aggravating circumstance of “large-scale administrative violations” related to the number of violating invoices and the amount of evaded tax.

5.4. Amendments and supplements to regulations on administrative violations committed by relevant organizations and individuals:

Amending and supplementing regulations on sanctioning administrative violations against individuals and organizations (including foreign bank branches) when providing information and documents related to tax obligations and accounts of taxpayers in contravention of regulations.

5.5. Amendment of the fine bracket for acts of invoicing at the wrong time and acts of not invoicing:

Revise the fine bracket corresponding to the number of violation invoices in a case for these two acts.

5.6. To amend, supplement and abolish the competence to sanction administrative violations of titles:

  • Supplementing the authority to impose penalties in the form of fines for tax officials.
  • Amendment of names and sanctioning competence of heads of tax authorities at all levels.
  • Abolishing the title of chairman of the district-level People’s Committee and a number of other titles from the list of persons with sanctioning competence.

5.7. Amendments to regulations on the order and procedures for sanctioning administrative violations:

  • Amending regulations on the right to accountability of taxpayers, in accordance with the new provisions of the Law on Handling of Administrative Violations.

5.8. Abolition of a number of administrative violations on invoices:

Abolish acts of violating regulations on invoices ordered to be printed, invoices printed on order, sale of invoices ordered to be printed, issuance of invoices and cancellation of invoices.

6. Others: Officially Designating 24 November as “Vietnam Cultural Day”

Resolution No. 80-NQ/TW, issued on 7 January 2026, affirms that cultural and human development is a fundamental pillar of sustainable development. Accordingly, 24 November each year is officially designated as “Vietnam Cultural Day,” on which employees are entitled to a paid day off. This regulation aims to enhance cultural participation, encourage creativity, and promote a civilized and healthy lifestyle across society.

Conclusion

The Vietnam Tax Policy Updates for late 2025 and 2026 reflect a significant shift towards digitalization and more stringent compliance standards. From the transition of using personal identification numbers for PIT to the new administrative penalty framework effective January 16, 2026, it is clear that proactive preparation is essential for every enterprise.

At Vina TPT, we understand that navigating these complex changes can be challenging for businesses. Whether you need assistance with VAT refund dossiers for investment projects or clarifying Foreign Contractor Tax (FCT) obligations for digital services, our team of experts is ready to provide tailored solutions. Stay ahead of the regulatory curve and ensure your business operations remain seamless and compliant in the new year.

Contact Vina TPT today for a comprehensive tax health check and professional advisory services!

Get Expert Tax Advice

Vina TPT Tax Expert analyzing Vietnam Tax Policy Updates 2026

How Foreign Companies Reduce HR Costs in Vietnam with HR Outsourcing in 2026

As Vietnam’s economy continues to surge in 2026, driven by a robust influx of foreign direct investment (FDI), international businesses are increasingly eyeing this dynamic Southeast Asian market. With steady GDP growth and a young, highly skilled workforce, Vietnam offers outstanding opportunities across manufacturing, technology, and service industries

However, for foreign companies new to the scene, navigating the complexities of human resources and payroll management can be a daunting and costly endeavor. From stringent labor laws to evolving tax regulations, the administrative overhead often diverts focus from core operations and inflates expenses.

HR outsourcing is a strategic solution to reduce HR costs and effectively answer how to reduce HR cost. Also known as payroll outsourcing or Employer of Record (EOR) services, it allows foreign companies to outsource non-core HR tasks to local experts in Vietnam, ensuring full legal compliance while significantly cutting expenses. With over 20 years of experience supporting more than 200 foreign clients, Vina TPT provides specialized HR outsourcing tailored for FDI businesses. This guide explains how HR outsourcing optimizes operating costs in Vietnam with the latest 2026 updates, real-world examples, and practical tips on how to reduce HR cost for sustainable growth.

the-rising-challenge-of-HR-management-in-Vietnam

1. The Rising Challenges of HR Management for Foreign Companies in Vietnam

Foreign investors entering Vietnam in 2026 face a unique set of HR hurdles that can significantly impact the bottom line. The country’s labor market is competitive, with a talent shortage in specialized sectors like IT and engineering pushing up salaries. According to recent data, the average monthly salary for a mid-level employee ranges from VND 10-15 million (approximately USD 400-600), but for expats or skilled locals, it can climb to VND 30-50 million or more.

Key challenges include:

  • Compliance with Evolving Labor Laws: Vietnam’s labor regulations continue to evolve, requiring strict compliance with minimum wage adjustments, overtime rules, and electronic employment contracts. Non-compliance can lead to financial penalties and reputational risks.
  • Payroll and Tax Complexities: Ongoing personal income tax reforms increase the complexity of payroll management, particularly for expatriate employees. Employers must accurately manage tax withholding, annual tax finalization, and mandatory social insurance contributions.
  • Administrative Overload: Building an in-house HR function demands significant investment in specialized staff, payroll systems, and recurring regulatory reporting, driving up operating costs for growing businesses.
  • Cultural and Language Barriers: Foreign firms often struggle with local recruitment nuances, leading to high turnover rates and additional onboarding expenses.

Without proper management, these issues can erode up to 20-30% of operational budgets, delaying profitability in a market where quick scalability is key.

2. How HR Outsourcing Drives Cost Optimization in 2026

HR outsourcing transfers these burdens to specialized providers, allowing companies to pay a fixed, predictable fee while gaining access to expert systems and local knowledge. In Vietnam, EOR services start from as low as USD 298 per employee per month (all-inclusive), covering everything from payroll to compliance.

Here’s a detailed breakdown of cost savings:

Cost Category

In-House HR (Estimated Annual Cost for 50 Employees)

HR Outsourcing (e.g., with Vina TPT)

Potential Savings (Percentage)

HR & Payroll Staff Salaries VND 200-350 million (2-3 full-time specialists) Included in fee 100% (Outsourced expertise)
Payroll Software & Tools VND 10 – 50 million (Systems + Maintenance) Included 100%
Compliance & Legal Fees VND 30-100 million (Audits, Fines, Consultants) Managed with zero penalties Up to 80-90%
Social Insurance & Benefits VND 100 – 200 million (Contributions + Admin) Automated and optimized 20-30% (Efficient calculations)
Total Estimated VND 340 -700 million VND 120 – 400 million Up to 40% Overall

These figures are based on 2026 market averages, where outsourcing can reduce total HR costs by up to around two-thirds for FDI firms. Beyond direct savings, it also minimizes risks – for example, helping companies avoid personal income tax compliance issues such as incorrect deductions, which could otherwise result in back taxes and interest penalties.

core-benefits-of-hr-outsourcing

3. Core Benefits of HR Outsourcing for New Market Entrants

Enhanced Compliance in a Changing Landscape
In 2026, several important regulatory updates come into effect. Minimum wage increases impact social insurance contribution caps, while personal income tax reforms introduce additional deductions for high-income expatriates, such as housing allowances. HR outsourcing enables companies to adapt in real time through automated systems, including electronic labor contracts and periodic regulatory reporting.

Scalability and Flexibility
Companies can start with a small team and scale up smoothly as operations grow. Cloud-based platforms using SaaS models integrate easily with global systems, supporting hybrid workforces that combine local employees and expatriates.

Access to Local Talent and Market Insights
Providers such as Vina TPT leverage strong local networks to accelerate recruitment and shorten time-to-hire. They also provide guidance on cultural integration, helping improve employee engagement and retention.

Data Security and Transparency
With strict data protection requirements under Vietnam’s data privacy regulations, outsourcing providers rely on secure, centralized payroll systems to ensure data integrity, transparency, and reduced error risk.

Stronger Strategic Focus
By offloading administrative and compliance tasks, executives can focus on strategic priorities, such as expanding into high-tech industries that qualify for corporate income tax incentives.

4. Vina TPT’s HR Outsourcing Services: A Tailored Approach

At Vina TPT, our HR outsourcing encompasses:

  • Payroll Processing: Gross-to-net calculations, payslips, and multi-currency support for expats.
  • Insurance and Tax Management: SHUI registrations, PIT withholding, and annual finalizations compliant with 2026 reforms.
  • Labor Contract Services: Drafting electronic contracts per Decree 337, managing terminations, and handling disputes.
  • HR Advisory: Guidance on work permits, salary scales, and employee development under the new emphasis on workforce training.
  • Custom Reporting: Real-time dashboards for cost tracking and compliance audits.

Our fees are transparent, starting at competitive rates aligned with market standards, ensuring no hidden costs.

5. Ready to Streamline Your HR and Cut Costs in Vietnam?

In 2026, smart FDI companies are leveraging HR outsourcing to thrive amid regulatory changes. Vina TPT’s HR Outsourcing stands ready as your trusted partner, offering expert, compliant solutions that let you focus on what matters – growing your business.

We offer truly flexible pricing policies tailored to newly established FDI enterprises, even those with just 1–2 employees, while larger companies with hundreds of staff also receive customized, mutually agreeable fee structures that best suit their scale and needs.

Schedule a free consultation today for a personalized cost-saving assessment.

BOOK A FREE CONSULTATION

start a business in vietnam with vina tpt

Setting Up a Representative Office in Vietnam: Step-by-Step Guide for Foreigners 2026

As Vietnam continues to attract foreign direct investment (FDI) with robust economic growth in 2025-2026, many international businesses choose to establish a Representative Office (RO) as their initial market entry strategy. An RO allows foreign companies to build a legal presence, conduct market research, and liaise with local partners without engaging in direct profit-generating activities.

With over 20 years of experience supporting more than 200 foreign clients, Vina TPT specializes in guiding investors through this process efficiently and compliantly. This ultimate guide provides a step-by-step overview for setting up a representative office in Vietnam in 2025, based on the latest regulations under Commercial Law 2005 and Decree 07/2016/ND-CP (with minor procedural updates).

1. What is a Representative Office in Vietnam?

A representative office is a dependent unit of an enterprise that is established in a different province or country for the purpose of supporting the operations of its parent company. ts main activities typically include:

  • Promoting and marketing products or services
  • Collecting and analyzing market information
  • Identifying customer demands and industry trends
  • Providing customer consultation and support
  • Developing and maintaining relationships with partners
  • Assisting with administrative and procedural matters

Key limitations: Representative Offices cannot generate revenue, issue invoices, or conduct direct trading. If your goal involves commercial operations, consider a full foreign-invested enterprise instead.

Representative Office

Foreign-Invested Company

Legal Status Dependent unit; extension of the parent company Independent legal entity; registered in Vietnam.
Business Activities Non-profit; no direct revenue-generating activities. Full operations; allowed to trade, manufacture, and earn profits.
Primary Purpose Market research, brand promotion, and liaison activities. Executing full business operations and commercial contracts.
Suitability Ideal for testing the market and building local relationships. Best for long-term investment and generating local revenue.


2. Eligibility Requirements for Foreign Companies

To qualify for an RO in Vietnam:

  • The parent company must operate legally in its home country for at least 1 year.
  • Business activities must align with Vietnam’s WTO commitments.
  • No minimum capital is required, making it a low-risk option for SMEs and startups.

3. Setting Up a Representative Office: Step-by-Step Process

The process typically takes 4 – 6 weeks months in 2026, handled by the Department of Industry and Trade (DOIT).

Step 1: Prepare Documents

In order to facilitate a seamless and efficient licensing process for a Vietnam-based representative office, foreign entities should assemble the following essential documentation:

  • Application form for RO establishment
  • Parent company’s Business Registration Certificate (legalized)
  • Audited financial statements (latest year)
  • Appointment letter for Chief Representative
  • Lease agreement for office premises (physical address required)
  • Passport/ID of Chief Representative

Note: All foreign documents need consular legalization and Vietnamese translation.

Step 2: Submit Application

After finalizing the necessary paperwork, the investor submits it to the Business Registration Office under the Department of Planning and Investment where the representative office will be located.

Under normal circumstances, the licensing authority will review and issue a result within a timeframe of 10 to 15 business days.

Step 3: Obtain RO License

Upon the successful evaluation of the application, the competent authority will formally issue the Representative Office Establishment License.

To ensure full regulatory compliance, the entity must immediately proceed with post-licensing compliance tasks, such as: 

  • Engrave seal and register specimen
  • Open bank account (for expenses only)
  • Registering for tax if any expenses are incurred
  • Apply for work permits/TRC for foreign staff (if needed)

At VINA TPT, we support clients throughout every step—tracking the progress, handling all paperwork, and collecting the license as soon as the application is approved.

setting-up-a-representative-office-in-vietnam

4. Common Challenges and Tips

To ensure your 2026 application is processed without delays, please consider these essential points:

  • Legalization: Start document legalization early to avoid common administrative bottlenecks.
  • Office Lease: Ensure a valid lease agreement is signed before submitting your dossier.

Work Permits: Foreign Chief Representatives may require a work permit to stay compliant.

5. Ready to Establish Your Representative Office in Vietnam?

Establishing a representative office is a strategic move for foreign companies to expand and engage with the Vietnamese market. However, success requires deep legal insight and meticulous preparation. To overcome language barriers and administrative complexities, partnering with a professional service is the most effective solution.

With over 20 years of expertise, VINA TPT is proud to be the trusted partner for international businesses entering Vietnam. With Vina TPT’s one-stop support, foreign investors can navigate this process seamlessly, ensuring 100% data protection and transparent costs. Contact us today for expert consultation and a seamless start to your investment journey.

BOOK A FREE CONSULTATION

start a business in vietnam with vina tpt

How to Calculate Personal Income Tax 2026 in Vietnam

how-to-calculate-personal-income-tax-2026-vinatpt

Vietnam’s Personal Income Tax 2026 law was amended Law No. 109/2025/QH15 and officially takes effect from July 1, 2026. Key rules for salary, wages, and business income, however, apply right from January 1, 2026. These updates significantly reduce the tax burden for employees and business owners amid rising living costs. 

This guide explains exactly how to calculate PIT in 2026, highlights the major changes (increased family deductions, simplified progressive rates, expanded exemptions), and provides clear, real-world examples so you can compute your tax accurately and stay fully compliant. 

1. Major Changes to Personal Income Tax from 2026 

2026 introduces the biggest PIT reforms since 2012, driven by the amended PIT Law 2025 and Resolution 110/2025/UBTVQH15. The goal is to ease pressure on middle-income earners, support digital businesses, and attract high-tech investment while keeping pace with economic growth and inflation. 

Change  Main Benefit 
Increased family deductions  Lower tax for individuals and families 
Simplified progressive brackets  Easier calculation, reduced tax for average incomes 
Expanded exemptions  Support for high-tech, agriculture, and green sectors 

These reforms make the tax system more modern, transparent, and easier to comply with. 

1.1 Increased Family Deductions Effective January 1, 2026 

From January 1, 2026, family circumstance deductions are raised to better match higher living costs, helping millions of taxpayers pay less personal income tax The personal deduction increases from VND 11 million to VND 15.5 million per month (VND 186 million per year), and the deduction per dependent rises from VND 4.4 million to VND 6.2 million per month. 

Type of Deduction  2025 Amount  2026 Amount 
Personal deduction  11 million/month  15.5 million/month 
Per dependent  4.4 million/month  6.2 million/month 

Who qualifies as a dependent? 

  • Children: Under 18; over 18 if disabled and unable to work; full-time students (university, college, vocational) under 22 with low or no income. 
  • Spouse: Unable to work or with very low/no income. 
  • Parents, grandparents, siblings: Elderly or disabled individuals with insufficient income, directly supported by the taxpayer. 

Key conditions 

  • Each dependent can be claimed by only one taxpayer. 
  • Proof is required (birth certificate, household registration, disability certificate, school enrollment, support commitment letter). 
  • Register with your employer or tax office (usually via Form 20-ĐK-TNCN) before tax is calculated. 

1.2 New Progressive Personal Income Tax 2026 Rates – Reduced from 7 to 5 Brackets 

Effective January 1, 2026, the progressive tax scale is simplified from 7 brackets to 5, with wider income ranges to reduce the effective tax rate for middle earners. The top rate remains 35%, now applying only to monthly taxable income over VND 100 million (previously VND 80 million). 

Bracket  Monthly Taxable Income (VND million)  Annual Taxable Income (VND million)  Tax Rate (%) 
1  Up to 10  Up to 120  5 
2  Over 10 to 30  Over 120 to 360  10 
3  Over 30 to 50  Over 360 to 600  20 
4  Over 50 to 100  Over 600 to 1,200  30 
5  Over 100  Over 1,200  35 

Old vs. new comparison The old 7-bracket system had narrower bands, pushing many middle-income earners into higher rates. The new structure is simpler and saves 5–15% in tax for most employees, while encouraging extra work without jumping brackets quickly. 

1.3 Expanded Exemptions, Reductions & Special Incentives 

The updated law adds 21 new exempt income categories starting in 2026, focusing on education, healthcare, green projects, and high-tech sectors. Additional benefits include a 50% reduction on certain investment income and a 5-year exemption for high-tech professionals. 

  • New exempt items: Certain overtime pay, scholarships, income from green bonds, organic agriculture, gifts under VND 10 million, disaster relief support. 
  • Special incentives: 5-year PIT exemption for experts in AI, semiconductors, and R&D; 50% reduction on income from investments in tech startups. 
Incentive Type  Condition  Duration 
Scholarship exemption  Full-time formal education  Indefinite 
5-year high-tech exemption  Experts in AI, semiconductors, R&D  5 years from 2026 
50% investment reduction  Green/technology startups  Applies to 2026+ income 

Proof (contracts, certificates) is required, often from the Ministry of Science and Technology. 

personal-incom-tax-2026-vina-tpt

2. How to Calculate Personal Income Tax in 2026 – Step-by-Step Guide 

Core formula Tax payable = Taxable income × Progressive tax rate Taxable income = Total income – Exempt items – Deductions (family + mandatory insurance + charity + eligible medical/education expenses) 

This applies to tax residents. Non-residents pay a flat 20% on Vietnam-sourced income. 

Step 1: Determine Your Tax Residency Status 

Start by confirming whether you are a tax resident or non-resident, as this determines what income is taxable. 

Under Vietnam’s PIT law: 

  • Tax resident: Present in Vietnam ≥183 days in the calendar year, or maintaining a permanent residence (owned home or long-term rental with registered address). 
  • Non-resident: Taxed only on income sourced from Vietnam. 

Tax implications 

  • Residents: Taxed on worldwide income using the 5-bracket progressive scale (5%–35%). 
  • Non-residents: Flat 20% on Vietnam-sourced salary and wages (other rates apply to specific types). 

Step 2: Calculate Taxable Income 

Basic formula: Taxable income = Total income – Exempt items – Deductions 

  1. Total income includes salary, bonuses, taxable allowances, business profits, investment returns, etc. 
  2. Exempt items include scholarships, certain overtime pay, small gifts, etc. 
  3. Deductions include: 
  • Family deduction (VND 15.5 million/month personal + VND 6.2 million/month per dependent) 
  • Mandatory social, health, unemployment insurance (BHXH, BHYT, BHTN) 
  • Charitable donations (with receipts) 
  • Medical & education expenses (new in 2026, up to VND 10 million/year – detailed guidance pending) 

Example In January 2026, Mr. A receives: 

  • Salary: VND 70,000,000 
  • Meal allowance (per company policy): VND 1,000,000 
  • Sales commission: VND 2,000,000 

No charitable contributions. Mr. A has one registered dependent (child under 18). 

Calculation: 

  • Total income: 70,000,000 + 1,000,000 + 2,000,000 = VND 73,000,000
  • Exempt: VND 1,000,000 (meal allowance) 
  • Deductions: 15,500,000 (personal) + 6,200,000 (dependent) + 4,200,000 (mandatory insurance) = VND 24,850,000
  • Taxable income = 73,000,000  – 1,000,000 – 24,850,000 = VND 47,150,000 per month 

Step 3: Apply the 2026 Progressive Rates

new-progressive-personal-income-tax-rates-vina-tpt

Apply the 5-bracket scale to taxable income, calculating tax portion by portion and adding them up. 

Continuing Mr. A’s example (monthly taxable income: VND 47,150,000): 

  • Bracket 1: VND 10,000,000 × 5% = VND 500,000 
  • Bracket 2: (30,000,000 – 10,000,000) × 10% = VND 2,000,000 
  • Bracket 3: (47,150,000 – 30,000,000) × 20% = VND 3,430,000 

Total PIT payable: 500,000 + 2,000,000 + 3,430,000 = VND 5,930,000 

Net take-home pay: 73M – 4.2M (insurance) – 5.93M (PIT) = VND 62,870,000 

3. Special Rules for Foreigners and Expatriates in Vietnam 

Foreign nationals (expats) and overseas workers follow specific PIT rules in 2026. 

  • Non-residents: Flat 20% on Vietnam-sourced income, withheld at source. 
  • Residents: Subject to the same progressive rates as Vietnamese citizens. 

Double Taxation Agreements (DTAs) Vietnam has over 80 DTAs (with the US, EU countries, Japan, Singapore, etc.). To claim relief: 

  • Submit Form NT5/TNCN 
  • Provide proof of tax residency in your home country 
  • Claim credit for taxes already paid abroad 

Example: A non-resident expat earning VND 50 million/month pays VND 10 million (20%) PIT. With a DTA, the rate may drop to 10–15%. 

These rules, plus the 5-year exemption for high-tech experts, make Vietnam attractive for skilled international professionals. 

4. Filing and Finalizing Personal Income Tax in Vietnam 

PIT filing and finalization are fully online via the General Department of Taxation portal (thuedientu.gdt.gov.vn) or eTax Mobile app. 

General deadlines (apply every year): 

  • Employer finalization (for authorized employees): By the last day of the 3rd month after year-end (usually March 31). 
  • Individual self-finalization: By the last day of the 4th month after year-end (usually April 30). → If the deadline falls on a holiday or weekend, it shifts to the next working day. 

Who must self-file? Individuals with income from two or more sources who do not meet authorization conditions, or those seeking refunds or adjustments. 

5. Vina TPT – Your 2026 PIT Solution for Expats & Businesses in Vietnam 

Vina TPT is a leading tax advisory firm in Vietnam specializing in Personal Income Tax services for expatriates and foreign-invested companies. Our experienced team provides full support, from 2026 PIT forecasting and calculation to DTA claims and maximum deduction optimization. 

Why choose Vina TPT? 

  • Free initial consultation with clear guidance 
  • Fast, accurate filing and deadline reminders 
  • Full compliance with 2026 regulations to minimize risks 

Key services 

  • PIT finalization for expats with multi-source income 
  • Assistance with high-tech and investment incentives 
  • HR training on payroll updates and withholding 

Need help with your 2026 Personal Income Tax in Vietnam? Contact Vina TPT today for expert, hassle-free support.

BOOK A FREE CONSULTATION